
 Paget Disease Treatment Market | 2026-2036
Paget Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Paget Disease Treatment Market Intelligence
The distribution channel for intravenous bisphosphonates is tilting toward specialized infusion centers and away from general hospital settings. Novartis leverages its extensive portfolio in bone health to maintain a strong position in established therapies. Pfizer competes through its focus on pain management analgesics, which are often used adjunctively. Takeda Pharmaceutical Company Limited differentiates with its research into novel osteoclast regulation mechanisms.
Paget disease treatment involves pharmacological interventions that normalize the accelerated and disorganized bone remodeling process. These therapies primarily function by inhibiting excessive osteoclast activity, reducing bone resorption and alleviating symptoms. Among drug classes, Bisphosphonates represent the standard of care due to proven efficacy. The Oral administration route maintains a dominant share, valued for its convenience and patient adherence benefits.
Regulatory oversight from bodies like the U.S. FDA and the European Medicines Agency (EMA) dictates clinical trial requirements and marketing authorization for new antiresorptive drugs. Guidelines from Health Canada and Japan's PMDA further influence global development strategies and labeling. Future competitive advantage will hinge on developing treatments with superior long-term safety profiles and more convenient dosing regimens.
Market Dynamics
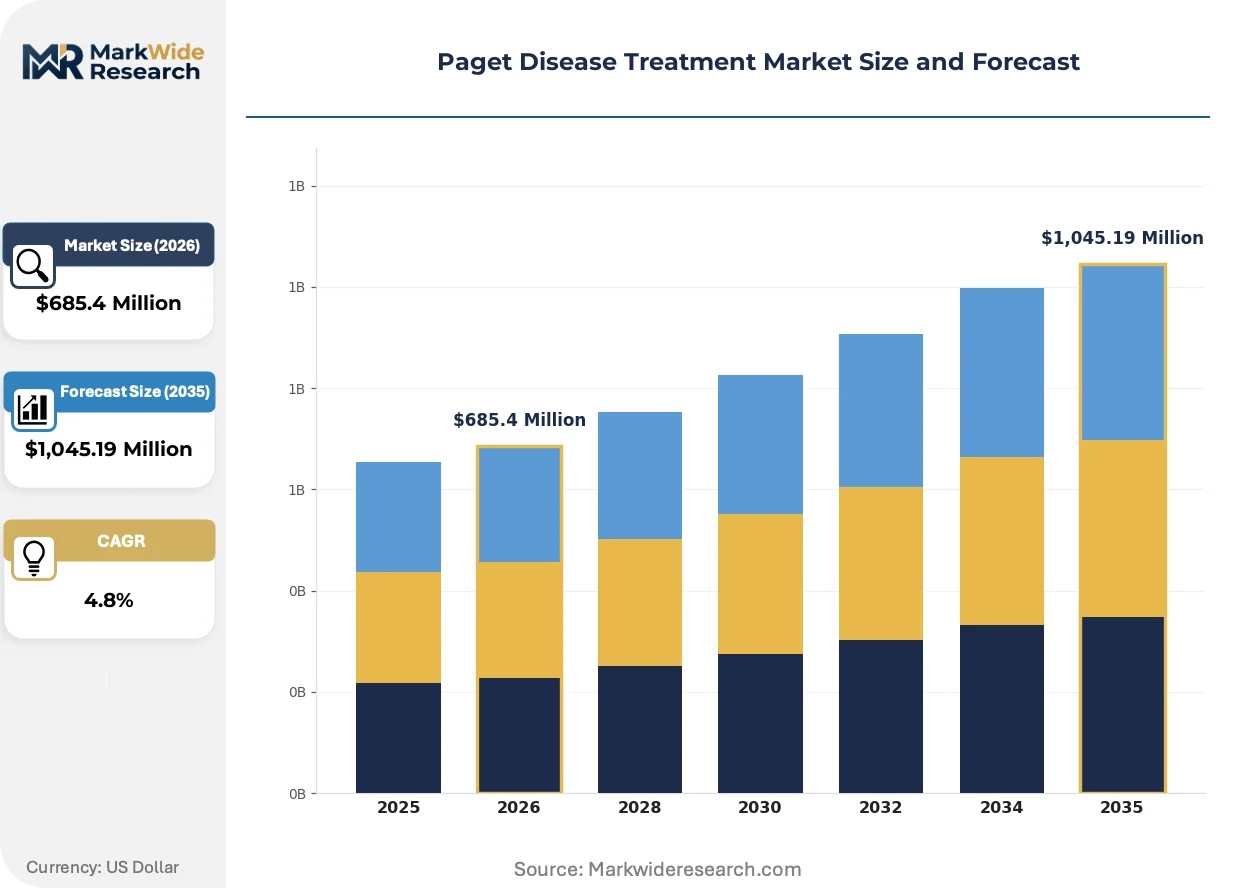
The market's structure is defined by the clinical need to balance potent osteoclast inhibition with long-term safety. This dynamic is intensified by an aging global population, which increases disease prevalence and demand for treatments with more convenient, less frequent dosing schedules.
Growth Catalysts
- Favorable Reimbursement Policies:Healthcare systems in countries like Germany and France provide extensive coverage for bisphosphonate therapies, encouraging their use as a first-line treatment for symptomatic Paget disease and supporting market volume.
- Rising Geriatric Population:Increasing life expectancy and a growing elderly demographic, particularly in Japan and the United States, expand the patient pool susceptible to age-related bone disorders, including Paget disease.
- Advancements in Drug Delivery:The development of long-acting injectable formulations improves patient adherence and convenience compared to daily or weekly oral medications, driving adoption within orthopedic centers and specialized clinics.
Market Restraints
- Stringent Regulatory Hurdles:The U.S. FDA and EMA impose rigorous requirements for demonstrating long-term safety, particularly concerning rare adverse events like atypical femoral fractures, which complicates and extends the drug approval process.
- Generic Erosion:The expiration of patents for foundational bisphosphonates has led to widespread generic competition, creating significant price pressure and reducing R&D investment incentives for follow-on products in the same class.
- High Rate of Asymptomatic Cases:A substantial portion of individuals with Paget disease exhibit no symptoms, leading to underdiagnosis and a smaller-than-expected treated population, which limits overall market potential.
Strategic Opportunities
- Novel Therapeutic Pathways:Research into alternative mechanisms for osteoclast regulation, such as targeting the RANKL pathway, presents an opportunity to develop treatments for patients who are unresponsive or intolerant to bisphosphonates.
- Expansion in Emerging Markets:Increasing healthcare expenditure and growing awareness of bone health in large markets like Brazil and China offer significant growth potential for established therapies as diagnostic capabilities improve.
- Specialized Infusion Center Channel:The shift toward administering intravenous therapies in dedicated infusion centers provides an opportunity for manufacturers to create targeted distribution and support programs outside of traditional hospital settings.
Industry Challenges
- Patient Adherence Issues:Gastrointestinal side effects associated with oral bisphosphonates pose a significant challenge to long-term patient compliance, potentially leading to suboptimal treatment outcomes and disease progression.
- Complex Diagnostics:Differentiating Paget disease from other metabolic bone disorders requires specific biochemical markers and imaging, creating a diagnostic challenge in primary care settings and delaying specialist referrals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paget Disease Treatment Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Bone Resorption Inhibition, Pain Management, Osteoclast Regulation, Bone Formation Stimulation Drug Class: Bisphosphonates, Calcitonin, NSAIDs, Analgesics, Antiresorptives Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular End User: Specialty Clinics, Orthopedic Centers, Rheumatology Units, Rehabilitation Facilities |
| Companies Covered | Eli Lilly and Company, Fresenius Kabi AG, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Takeda Pharmaceutical Company Limited, Merck & Co. Inc., AbbVie Inc., Zimmer Biomet Holdings Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paget Disease Treatment Market Strategic Shifts & Innovations
The therapeutic landscape is evolving from generalized bone resorption inhibition toward more precise and patient-centric interventions. This evolution is guided by a deeper understanding of osteoclast biology and a regulatory push for treatments with superior long-term safety profiles and dosing convenience.
Long-acting injectable bisphosphonates provide a powerful method for inhibiting excessive bone resorption with a single annual dose. Orthopedic centers and specialized rheumatology clinics are rapidly adopting these formulations for their proven efficacy and ability to improve patient management. This technology is collapsing the treatment cycle from hundreds of potential doses per year with oral tablets to a single yearly event, fundamentally changing patient compliance dynamics.
Regulatory guidelines from bodies like Health Canada and Japan's PMDA are increasingly harmonizing with standards set by the FDA and EMA. This global alignment emphasizes the need for comprehensive post-marketing safety data for all antiresorptive agents. Consequently, pharmaceutical developers are embedding long-term observational studies into their lifecycle management plans, particularly for next-generation therapies targeting Paget disease.
A distinct behavioral shift is occurring in the channel for intravenous therapies. The administration of IV bisphosphonates is migrating from general hospital outpatient departments to specialized, physician-owned infusion centers. This change offers greater convenience for patients and creates a more focused point of service. This trend is most visible in the United States, where reimbursement structures and physician practice models favor such specialized care delivery.
Paget Disease Treatment Market Segmentation
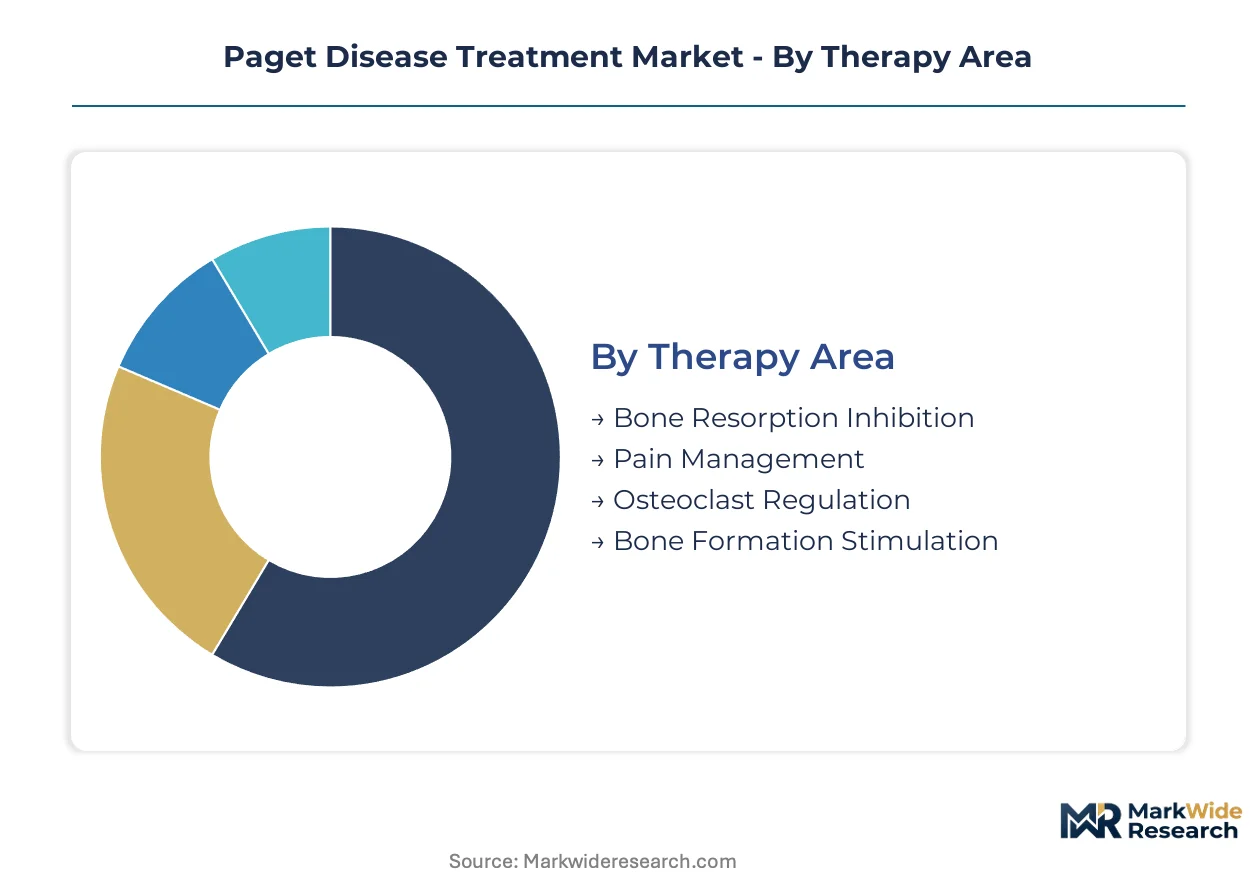
The Paget disease treatment market categorizes therapies and delivery mechanisms, reflecting diverse patient needs and clinical management approaches. Understanding these segments helps pharmaceutical companies tailor product development and market entry strategies. This detailed segmentation highlights areas of established care alongside emerging therapeutic avenues.
Therapy Area:
The intensity of after-sales service and patient education often varies significantly across different therapy areas, influencing resource allocation for pharmaceutical companies. Each area addresses a specific aspect of Paget disease pathology or symptom management.
- Bone Resorption Inhibition:This category includes treatments designed to slow down or prevent the breakdown of bone tissue, a primary mechanism in Paget disease. Demand for these therapies is concentrated in orthopedic centers and rheumatology clinics across the United States, driven by the need for long-term disease control.
- Pain Management:Therapies in this segment focus on alleviating the chronic bone pain associated with Paget disease, often used as an adjunct to disease-modifying agents. Patient demand for effective pain relief is high in Germany, where a significant aging population experiences symptomatic Paget disease.
- Osteoclast Regulation:This area encompasses novel treatments that specifically target the activity of osteoclasts, the cells responsible for bone resorption. Research efforts are increasing for these targeted interventions.
- Bone Formation Stimulation:These therapies aim to encourage the growth of new, healthy bone tissue, though their application in Paget disease is more limited compared to other bone disorders. This approach is less common for primary Paget disease treatment.
By volume, Bone Resorption Inhibition leads. By growth pace, Osteoclast Regulation is ahead.
Drug Class:
The cost tier of drug classes significantly impacts treatment accessibility and reimbursement policies across different healthcare systems. Generic availability particularly influences the pricing dynamics within established drug classes.
- Bisphosphonates:These drugs are the first-line treatment for Paget disease, known for their potent inhibition of osteoclast activity and widespread clinical use. Their established efficacy drives high prescription volumes in countries with advanced healthcare infrastructure, such as the United States.
- Antiresorptives:This broader category includes all drugs that reduce bone resorption, encompassing bisphosphonates and other agents with similar mechanisms. Demand for these agents is consistently high in European markets, supported by comprehensive health insurance coverage.
- Calcitonin:An older therapeutic option, calcitonin is a hormone that inhibits osteoclast activity, though it is now less commonly used than bisphosphonates due to lower efficacy. This drug class sees limited use.
- NSAIDs:Non-steroidal anti-inflammatory drugs provide symptomatic relief from pain and inflammation associated with Paget disease. These are frequently prescribed for pain management.
- Analgesics:This class of drugs is used to relieve pain, often prescribed to manage the discomfort caused by Paget disease. Analgesics address symptomatic needs.
Bisphosphonates dominate the market in terms of prescribed volume. Antiresorptives are gaining share fastest due to ongoing research and development.
Administration Route:
The application of different administration routes directly influences patient adherence, convenience, and the setting of care delivery. Patient preference for less frequent dosing drives innovation in this segment.
- Oral:This route involves medications taken by mouth, offering convenience and ease of access for many patients. Oral bisphosphonates maintain a dominant share in the market, particularly in primary care settings.
- Intravenous:Intravenous administration delivers medication directly into the bloodstream, often used for long-acting formulations or in cases of poor oral tolerance. This route is increasingly favored in specialized infusion centers for its improved adherence.
- Subcutaneous:Subcutaneous injections involve administering medication under the skin, providing a less invasive option than intravenous routes. This route offers potential for patient self-administration.
- Intramuscular:Intramuscular injections deliver medication into muscle tissue, a less common route for Paget disease treatments. This method is used for specific drug formulations.
Oral administration commands the largest share of patient volume. Intravenous formulations are exhibiting the steepest expansion trajectory.
End User:
The type of customer, or end user, dictates the specialized infrastructure and expertise required for effective Paget disease management. Each end-user segment plays a distinct role in diagnosis, treatment, and follow-up care.
- Specialty Clinics:These facilities provide focused care for specific conditions, including metabolic bone disorders, offering comprehensive diagnostic and treatment services. Such clinics are crucial referral centers.
- Orthopedic Centers:Orthopedic centers specialize in musculoskeletal conditions, often managing Paget disease patients who develop bone deformities or fractures. These centers show increasing utilization of advanced therapies.
- Rheumatology Units:These units focus on inflammatory and autoimmune conditions affecting joints, bones, and muscles, regularly treating Paget disease patients. Rheumatology units provide expert diagnosis and long-term management.
- Rehabilitation Facilities:Rehabilitation facilities assist patients in recovering from the physical impacts of Paget disease, such as mobility issues or post-fracture care. These facilities support functional recovery.
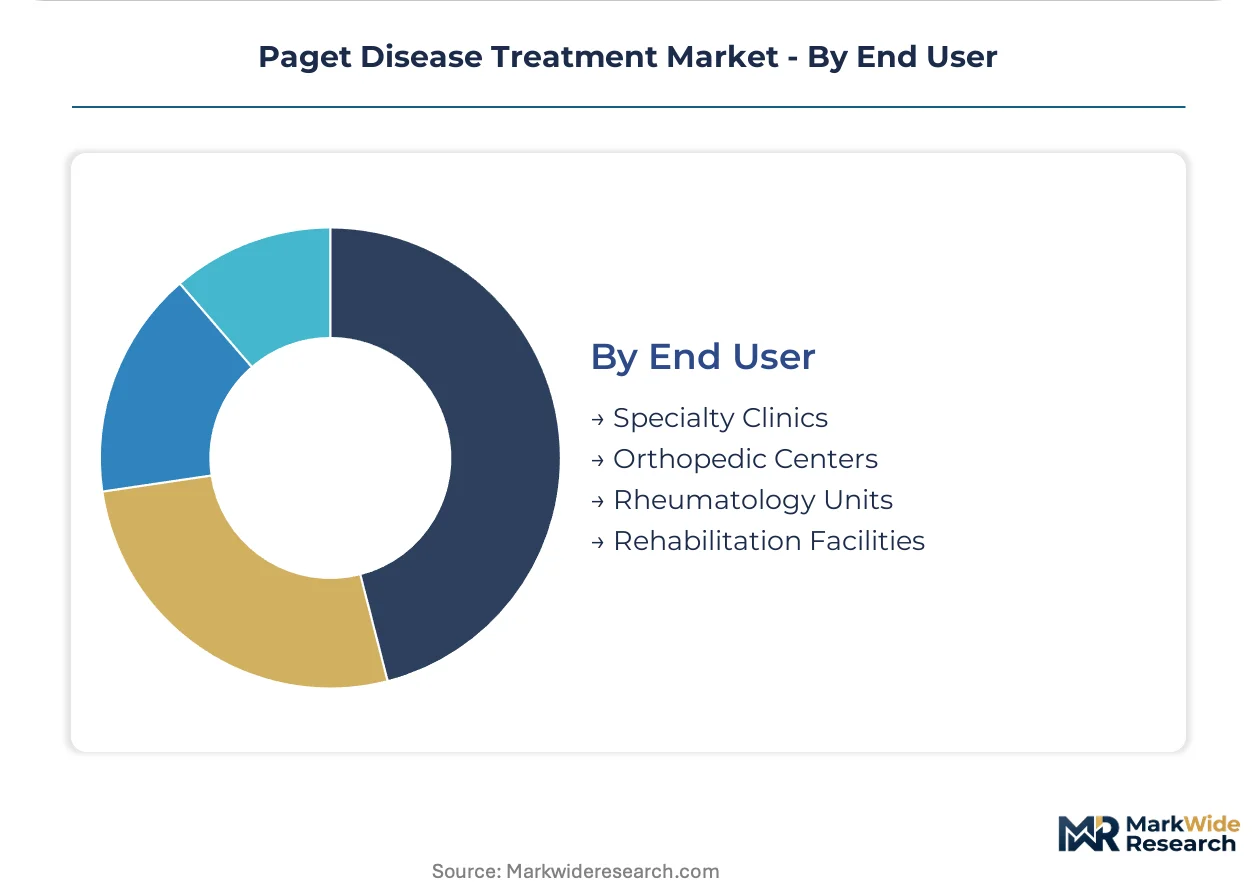
Orthopedic Centers account for the greatest volume of treated patients. Specialty Clinics are demonstrating the highest growth in patient admissions for Paget disease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for Paget disease treatments exhibits asymmetry, with the United States often commanding higher prices compared to European markets. This divergence reflects varied healthcare reimbursement models and regulatory landscapes across different geographies. Demand for advanced therapies is particularly robust in countries with strong healthcare infrastructure and aging populations.
United States
Demand for advanced bisphosphonate therapies in the United States stems from a significant aging population and high prevalence rates of Paget disease. The U.S. FDA imposes rigorous requirements for novel antiresorptive drugs, influencing product development cycles. Orthopedic centers in major metropolitan areas like New York and Los Angeles drive the utilization of specialized infusion services for intravenous treatments.
Germany
German healthcare systems provide extensive coverage for bisphosphonate therapies, encouraging their use as a first-line treatment for symptomatic Paget disease. The European Medicines Agency (EMA) sets stringent guidelines for drug approval, affecting market entry for new treatments. Specialized rheumatology clinics in cities such as Berlin and Munich are central to the diagnosis and management of Paget disease patients.
Japan
Japan's rapidly increasing life expectancy contributes to an expanding patient pool susceptible to age-related bone disorders, including Paget disease. Japan's PMDA influences global development strategies with its specific labeling requirements for antiresorptive agents. Research institutions in Tokyo and Osaka focus on novel osteoclast regulation mechanisms, attracting significant investment.
France
French healthcare policies ensure broad reimbursement for Paget disease treatments, supporting market volume and patient access to established therapies. The ANSM collaborates with the EMA on regulatory oversight, shaping the availability of new drugs. Specialized bone health clinics in Paris and Lyon are integral to delivering comprehensive care and supporting patient adherence programs.
Canada
Canadian demand for Paget disease treatments is sustained by a growing elderly demographic and favorable provincial reimbursement policies for bisphosphonates. Health Canada mandates comprehensive safety data for all antiresorptive agents, impacting post-marketing surveillance. Orthopedic and rheumatology units in Toronto and Vancouver are key centers for diagnosis and long-term management.
Paget Disease Treatment Market Key Industry Players
Established therapy providers and innovative drug developers split the market for Paget disease treatments, reflecting a diverse strategic landscape. The industry sees a mix of large pharmaceutical companies with broad portfolios and specialized firms focusing on niche therapeutic areas. Companies pursue competitive moves through R&D investment in novel mechanisms and strategic partnerships to expand distribution channels.
Among companies focusing on specific therapeutic approaches, Novartis AG exemplifies a strong position in established bone health therapies, leveraging its extensive portfolio. Pfizer Inc. represents a significant player in pain management analgesics, often used as adjunctive treatments to alleviate symptoms. Takeda Pharmaceutical Company Limited anchors the innovative segment, differentiating through its research into novel osteoclast regulation mechanisms and potential next-generation therapies.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Fresenius Kabi AG |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Takeda Pharmaceutical Company Limited |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Zimmer Biomet Holdings Inc. |
| Novartis AG |
Cost & Logistics Intelligence
Regulatory chokepoints from bodies like the U.S. FDA and European Medicines Agency (EMA) determine both pricing tier spreads for novel Paget disease treatments and the supply chain shape for advanced bisphosphonates. These stringent approval processes introduce significant development costs that translate into premium pricing for innovative therapies, while also dictating where and how these specialized drugs can be manufactured and distributed globally.
Pricing Analysis
Configured-to-order pricing for specialized infusion services, bundled with premium drug formulations, contrasts sharply with standard per-unit transactional pricing for generic oral bisphosphonates. The dominant pricing structure is a hybrid model, balancing contract-based long-term offtake for established therapies with value-based pricing for novel antiresorptive agents. Brand premium and after-sales service, including patient support programs, are key price differentiation drivers. Pricing pressure stems from generic erosion in the oral bisphosphonate segment, intensifying competition. Patients requiring long-acting injectable formulations are generally less price-sensitive due to convenience and adherence benefits, while those on generic oral medications are highly price-sensitive.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the complex distribution of specialized Paget disease treatments, particularly for high-value intravenous formulations. Geographic supply concentration for active pharmaceutical ingredients (APIs) primarily resides in India and China, with final drug manufacturing often occurring in the United States, Germany, and Switzerland. Raw material dependencies include specific chemical precursors for bisphosphonates and specialized excipients for injectable formulations. Regulatory restrictions on manufacturing sites present a structural supply chain risk. Distribution runs through a dual model: direct-to-hospital systems for established injectables and specialized pharmaceutical distributors serving a growing network of dedicated infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is reshaping the Paget disease treatment market, driven by the increasing interoperability between specialized clinics, diagnostic labs, and pharmaceutical companies in patient management ecosystems.
For Market Incumbents: Insulate core market share by investing in next-generation bisphosphonates with superior long-term safety profiles, countering emerging entrant archetypes focused on novel osteoclast regulation. Expand manufacturing capacity in key geographies like the United States and Germany to mitigate regulatory and logistics risks. Deepen channel control within specialized infusion centers through exclusive distribution agreements and patient adherence programs, addressing the margin pressure from generic erosion.
For New Entrants and Emerging Players: Establish a beachhead in novel therapeutic pathways, such as targeting the RANKL pathway, for patients unresponsive to bisphosphonates. The most penetrable segment lies within orphan drug designations or niche patient populations with specific genetic markers. A go-to-market angle focused on superior dosing convenience, like annual subcutaneous injections, can attract early adopters and differentiate from established oral therapies.
For Investors and Strategic Acquirers: Regulatory harmonization across the FDA and EMA reshapes the acquisition landscape, favoring companies with robust clinical pipelines and comprehensive post-marketing safety data. Acquisition targets should be innovative biotech firms specializing in osteoclast regulation or advanced drug delivery systems. The signal to watch is the successful completion of Phase III trials for non-bisphosphonate therapies, indicating a potential paradigm shift in treatment. Long-term viability hinges on treatments offering both efficacy and improved safety over a 5-10 year window.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel antiresorptive drugs, securing competitive advantage against established therapies. |
| Manufacturing Scale-Up | Ensures reliable supply of high-demand bisphosphonates, reducing dependency on single-source suppliers. |
| Licensing Agreement | Expands product portfolios with innovative treatments, addressing unmet needs in Paget disease management. |
| Distribution Channel Expansion | Reaches a broader patient base through specialized infusion centers, improving accessibility for intravenous therapies. |
| Pipeline Diversification | Mitigates risk by developing treatments for various bone disorders, reducing reliance on a single indication. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, medical journals, and healthcare expenditure reports. Primary interviews involved drug development executives, rheumatologists, and hospital procurement managers to gather qualitative insights. This approach triangulated bottom-up market sizing from patient populations with top-down validation from pharmaceutical sales data, ensuring robust data integrity.
The forecast framework considers patient demographics, disease prevalence rates, and evolving treatment guidelines across the analysis window. Segmentation dimensions modeled include therapy area, drug class, administration route, and end-user, alongside regional regulatory clusters. Compound annual growth rates were derived from historical market trends, anticipated drug approvals, and shifts in healthcare policy. Key industry-specific forecast inputs include the uptake rate of long-acting injectable bisphosphonates and the impact of generic erosion.
Stress conditions across patient adherence rates, regulatory approval timelines, and healthcare reimbursement policies were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding clinical trial success rates and market acceptance of new therapies. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Hypopigmentation Disorder Treatment Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Cubital Tunnel Syndrome Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Autism Spectrum Disorder Management Market