
 New Zealand Healthcare Surface Disinfectant Wipes Market | 2026-2036
New Zealand Healthcare Surface Disinfectant Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Healthcare Surface Disinfectant Wipes Market Foresight
Aged-care facilities and primary care clinics is bifurcating demand away from traditional hospital-centric purchasing in the New Zealand healthcare surface disinfectant wipes landscape. Ecolab leverages its institutional hygiene portfolio to sustain contract relationships with district health boards across the North Island. Reckitt Benckiser Group plc differentiates through consumer-recognised brand equity that extends into clinical procurement channels. CAPES MEDICAL SUPPLIES LIMITED anchors its position in the South Island through specialised distribution to regional laboratories and nursing homes.
Healthcare surface disinfectant wipes are non-woven substrates impregnated with antimicrobial chemistries—quaternary ammonium compounds, sodium hypochlorite, or isopropyl alcohol at concentrations typically between 70% and 90%—engineered for single-use decontamination of medical devices, patient contact surfaces, and high-touch environmental areas in clinical settings. Alcohol-based wipes dominate acute care procurement due to rapid evaporation and broad-spectrum efficacy against enveloped viruses, while multi-surface wipes capture expanding volume in outpatient clinics where material compatibility constraints limit bleach formulations. Soft pack packaging leads in nursing home and home-health applications where space efficiency and resealability reduce cross-contamination risk, though canister formats retain preference in hospital central supply departments.
New Zealand's Health and Disability Services Standards, administered by HealthCERT within the Ministry of Health, mandate documented environmental cleaning protocols that directly specify wipe-based disinfection frequencies in accredited facilities. The country's national pharmaceutical regulator evaluates antimicrobial claims through a Medsafe registration pathway that shapes product labelling and clinical marketing permissions. Stakeholders must monitor evolving sustainability mandates under the Waste Minimisation Act and potential biosecurity-driven procurement localisation as supply chain resilience becomes a decisive criterion in district health board tender evaluations.
Market Dynamics
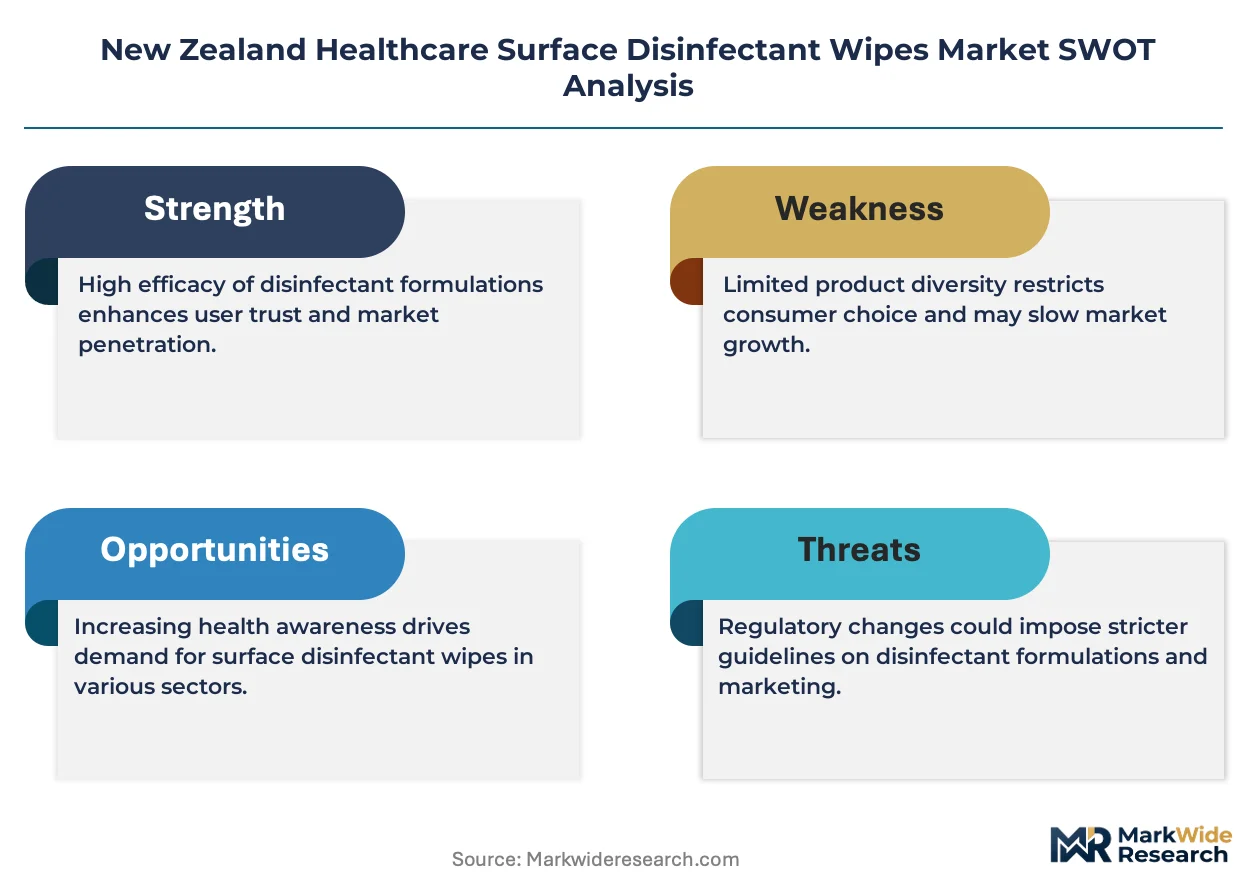
HealthCERT's tightening infection control audits under the Health and Disability Services Standards are forcing aged-care operators to replace reusable cleaning cloths with single-use hospital-grade wipes, compressing procurement cycles and elevating compliance documentation as a primary vendor selection criterion.
Growth Catalysts
- HealthCERT Audit Intensification:Unannounced facility inspections now mandate documented wipe-based disinfection logs, accelerating replacement demand across Canterbury's nursing home networks.
- Quaternary Ammonium Formulation Advances:Extended surface residual activity against Clostridioides difficile spores is opening acute care applications previously reserved for sodium hypochlorite.
- Auckland Metropolitan Hospital Expansion:District health board capital programs in Waitematā and Auckland regions are consolidating purchasing power toward bulk wipe contracts.
Market Restraints
- Isopropyl Alcohol Feedstock Volatility:Refinery output fluctuations in Taranaki's petrochemical corridor transmit directly to wipe manufacturing cost structures.
- Import Concentration Risk:Seventy percent of non-woven substrate supply originates from Australian converters, exposing distributors to trans-Tasman shipping disruptions.
- Biodegradable Certification Delays:Eco-labelling verification under the Waste Minimisation Act extends product launch timelines by eight to fourteen months.
Strategic Opportunities
- Waikato Regional Laboratory Network:Diagnostic facility construction in Hamilton creates untapped demand for DNA/RNA decontamination protocols.
- Home Health Channel Expansion:Post-acute discharge programs are routing wipe procurement through pharmacy retail rather than institutional distributors.
- Te Whatu Ora Consolidation:The national health service merger is centralizing infection control product tendering, favoring suppliers with multi-region fulfillment capability.
Industry Challenges
- Environmental Services Workforce Shortages:Aged-care facilities struggle to recruit technicians trained in HealthCERT-compliant documentation protocols.
- Legacy Inventory Integration:District health boards must reconcile incompatible wipe dispensing systems across merged hospital estates.
Report Scope
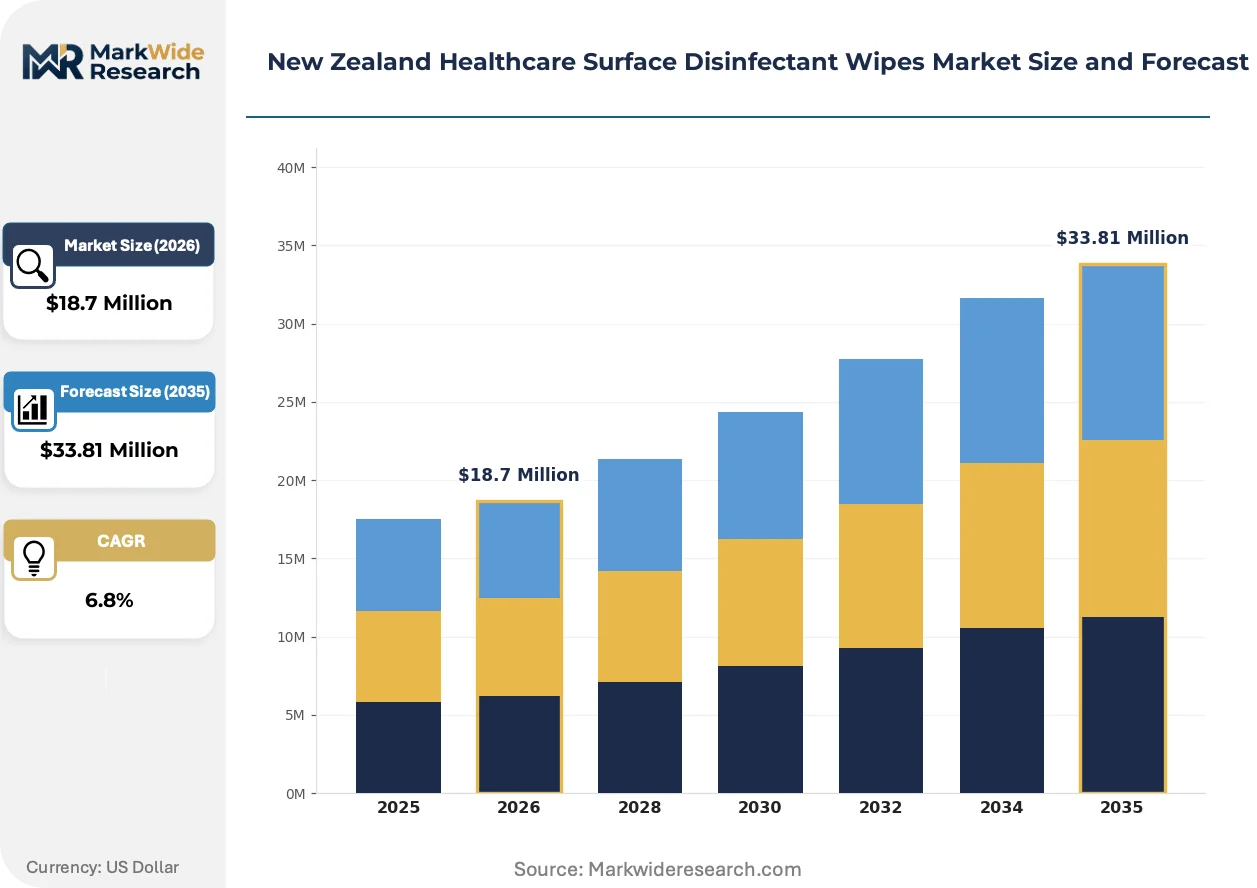
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Healthcare Surface Disinfectant Wipes Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $33.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohol-Based Wipes, Bleach Wipes, Antiseptic Wipes, Multi-Surface Wipes End User: Hospitals, Clinics, Nursing Homes, Laboratories Packaging Type: Soft Packs, Buckets, Canisters, Dispensing Boxes Distribution Channel: Online Retail, Supermarkets, Pharmacies, B2B Supply |
| Companies Covered | Henry Schein Regional Limited, MicroAnalytix NZ, Hygiene Systems Australasia Ltd., CAPES MEDICAL SUPPLIES LIMITED, OfficeMax New Zealand, Nano Care NZ Ltd, Ecolab, The Clorox Company, Reckitt Benckiser Group plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Healthcare Surface Disinfectant Wipes Market Shifts & Advancements
Substrate chemistry and packaging formats are converging around sustainability mandates and space-constrained care environments, with manufacturers racing to balance biodegradability claims against sporicidal performance requirements.
Cellulose-based biodegradable substrates impregnated with benzalkonium chloride formulations are displacing traditional polyester spunlace materials in aged-care procurement. Facility managers in Otago's retirement villages are specifying these products to preempt Waste Minimisation Act compliance deadlines. The shift is compressing margins for converters lacking certified compostable supply chains.
HealthCERT's 2024 technical advisory on environmental cleaning frequency is mandating quarterly protocol reviews in accredited facilities. The regulation is elevating wipe consumption metrics as a measurable audit criterion. District health boards in Wellington and Hawke's Bay are responding by standardizing on pre-saturated formats with validated contact times.
Direct-to-facility e-procurement platforms are fragmenting traditional distributor relationships in primary care. General practices in provincial North Island regions are bypassing medical supply wholesalers to source wipes through pharmacy cooperative buying groups. This channel shift is most pronounced in Tauranga and Palmerston North clinic networks.
New Zealand Healthcare Surface Disinfectant Wipes Market Segmentation
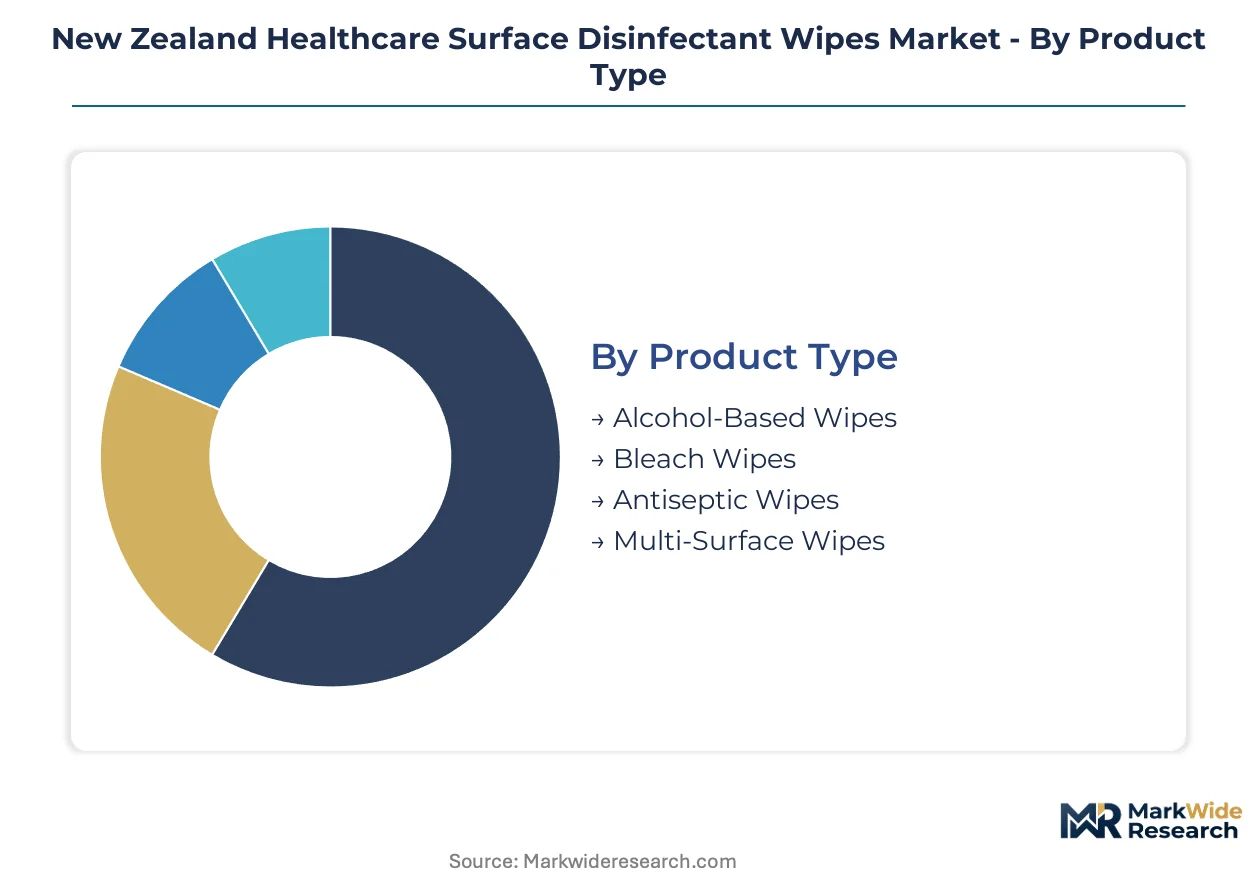
Healthcare surface disinfectant wipes in New Zealand flow through distinct procurement pathways shaped by HealthCERT compliance requirements, facility scale, and supply chain reliability. Segment boundaries determine margin structures, with hospital-grade formulations commanding premium positioning through institutional tenders while retail channels absorb volume in post-acute and home-health settings.
Product Type:
Channel dynamics bifurcate sharply: acute care procurement funnels through district health board tenders favoring validated sporicidal performance, while primary care and aged-care channels prioritize material compatibility and storage efficiency.
- Alcohol-Based Wipes:Isopropyl alcohol formulations at 70-90% concentration deliver rapid evaporation and broad-spectrum efficacy against enveloped viruses. Waitematā and Auckland district health boards specify these for high-touch medical device decontamination in metropolitan hospital networks.
- Multi-Surface Wipes:Quaternary ammonium compound formulations balance antimicrobial action against material compatibility constraints. Canterbury's expanding outpatient clinic infrastructure is absorbing volume as facilities replace bleach protocols to protect ultrasound equipment and polymer surfaces.
- Bleach Wipes:Sodium hypochlorite-impregnated substrates retain dominance in C. difficile outbreak protocols and terminal cleaning applications.
- Antiseptic Wipes:Benzalkonium chloride and chlorhexidine gluconate formulations serve pre-injection skin preparation and minor wound care in primary care settings.
Alcohol-based wipes dominate installed base. Multi-surface wipes are where expansion concentrates.
End User:
Procurement authority and compliance burden vary dramatically across end-user categories, with Te Whatu Ora consolidation centralizing hospital purchasing while aged-care operators face direct HealthCERT audit exposure.
- Hospitals:District health boards in Auckland, Canterbury, and Wellington regions execute bulk tender contracts specifying validated contact times and batch traceability. Capital expansion programs in Waitematā are consolidating purchasing power toward fewer, larger suppliers.
- Nursing Homes:Aged-care facilities across Otago and Canterbury face unannounced HealthCERT inspections mandating documented wipe-based disinfection logs. Operators are replacing reusable cloths with single-use hospital-grade formats to compress compliance risk.
- Clinics:General practices in provincial North Island regions route procurement through pharmacy cooperatives, fragmenting traditional distributor relationships.
- Laboratories:Diagnostic facilities require DNA/RNA decontamination protocols with validated nucleic acid degradation claims.
Hospitals anchor volume concentration. Nursing homes are climbing the fastest.
Packaging Type:
Format selection tracks storage constraints, cross-contamination protocols, and dispensing system compatibility across merged hospital estates.
- Soft Packs:Resealable flexible packaging reduces storage footprint and enables point-of-care accessibility. Otago retirement villages and home-health programs specify these for space efficiency and reduced contamination risk.
- Canisters:Rigid cylindrical containers with pop-up dispensing retain preference in hospital central supply departments requiring high-capacity, one-handed access.
- Buckets:Large-format refillable systems serve high-throughput environmental services operations in metropolitan hospitals.
- Dispensing Boxes:Wall-mounted or countertop units support standardized placement protocols in clinic examination rooms.
Canisters dominate installed base. Soft packs are gaining share fastest.
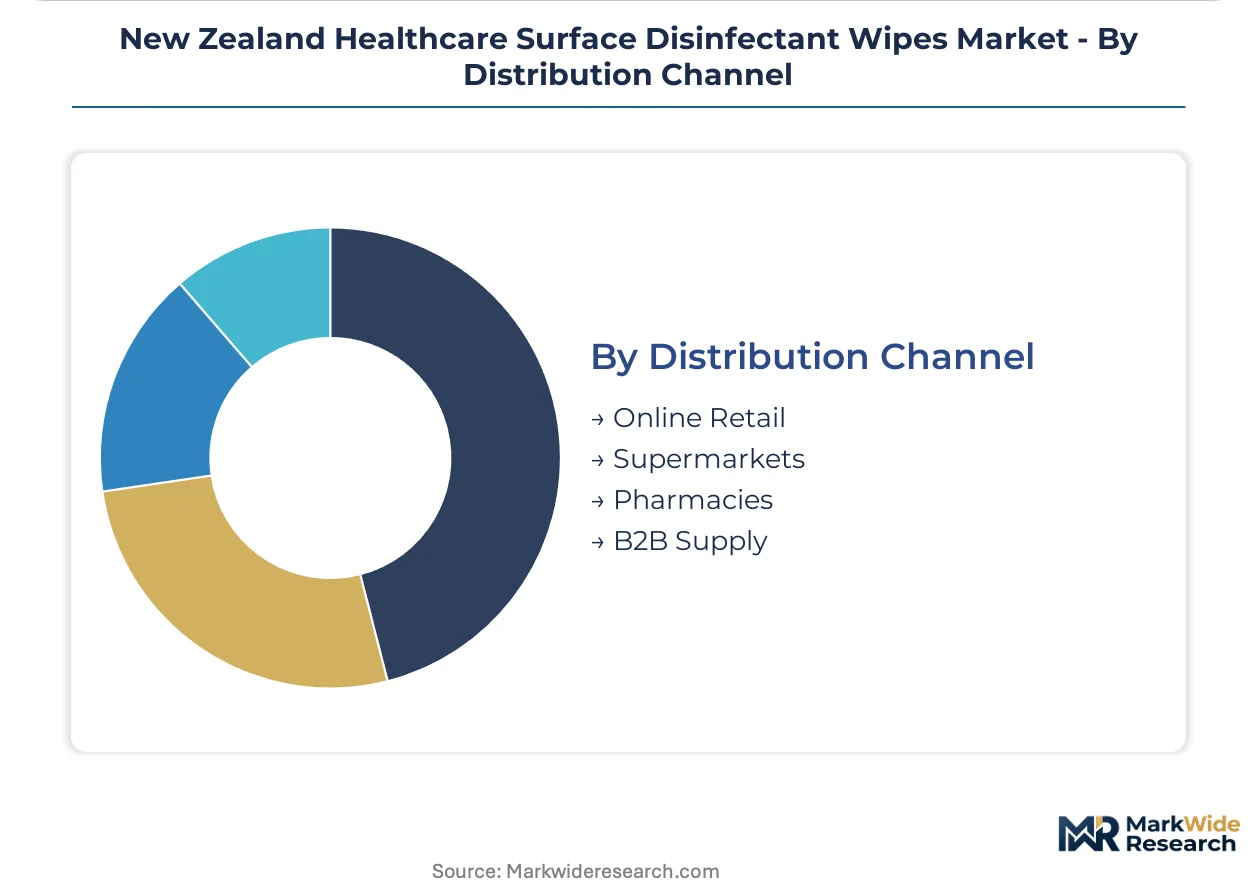
Distribution Channel:
Channel structure is concentrating around Te Whatu Ora centralization and e-procurement fragmentation in primary care.
- B2B Supply:Institutional distributors contract directly with district health boards and aged-care chains, embedding compliance documentation and training support. Ecolab and CAPES MEDICAL SUPPLIES LIMITED anchor relationships through multi-region fulfillment capability.
- Pharmacies:Cooperative buying groups in Tauranga and Palmerston North clinic networks are capturing primary care volume previously routed through medical supply wholesalers.
- Online Retail:Direct-to-facility platforms enable smaller practices to bypass traditional distribution tiers.
- Supermarkets:Limited healthcare-grade penetration; primarily consumer-oriented disinfectant products.
B2B supply dominates installed base. Pharmacies are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seventy percent of non-woven substrate supply flows from Australian converters, exposing distributors to trans-Tasman shipping disruptions while Auckland's metropolitan hospital networks concentrate procurement power.
Auckland Region
Waitematā and Auckland district health boards execute bulk tender contracts for validated sporicidal wipes. HealthCERT audits mandate documented disinfection logs across acute care facilities. Capital expansion programs in Auckland City are consolidating purchasing toward fewer, larger suppliers with multi-region fulfillment capability.
Canterbury
Outpatient clinic infrastructure expansion drives multi-surface wipe absorption as facilities replace bleach protocols. The Canterbury District Health Board standardizes on pre-saturated formats with validated contact times. Christchurch's clinical construction pipeline is absorbing volume previously routed through Auckland distributors.
Wellington
District health boards here respond to HealthCERT's 2024 technical advisory by mandating quarterly protocol reviews. Wellington Hospital's central supply departments retain preference for canister formats with pop-up dispensing. The region's laboratory networks require DNA/RNA decontamination protocols with validated nucleic acid degradation claims.
Otago
Retirement villages across Otago specify cellulose-based biodegradable substrates to preempt Waste Minimisation Act compliance deadlines. Aged-care operators face unannounced HealthCERT inspections mandating single-use hospital-grade formats. Dunedin's nursing home networks are compressing procurement cycles to elevate compliance documentation.
Waikato
Diagnostic facility construction in Hamilton creates untapped demand for specialized decontamination protocols. The regional laboratory network expansion routes procurement through institutional distributors embedding training support. Hamilton's clinical infrastructure growth is outpacing traditional supply chain configurations.
New Zealand Healthcare Surface Disinfectant Wipes Market Competitive Landscape
Concentration sits with institutional hygiene specialists anchoring district health board relationships through compliance documentation and multi-region fulfillment. The vendor base spans three strategic archetypes: multinational chemical hygiene conglomerates with institutional portfolios, regional medical supply distributors with specialized South Island coverage, and consumer-recognized brands extending into clinical procurement channels. Competitive positioning hardens around Te Whatu Ora tender consolidation and e-procurement fragmentation in primary care.
Among multinational hygiene conglomerates, Ecolab exemplifies the institutional-contract archetype through district health board relationships across the North Island. Reckitt Benckiser Group plc occupies a position bridging consumer brand equity into clinical procurement channels. CAPES MEDICAL SUPPLIES LIMITED anchors the regional-distributor archetype through specialized South Island coverage to regional laboratories and nursing homes.
| Leading Market Players |
|---|
| Henry Schein Regional Limited |
| MicroAnalytix NZ |
| Hygiene Systems Australasia Ltd. |
| CAPES MEDICAL SUPPLIES LIMITED |
| OfficeMax New Zealand |
| Nano Care NZ Ltd |
| Ecolab |
| The Clorox Company |
| Reckitt Benckiser Group plc |
| Others |
Supply & Pricing Matrix
Long-term bulk tender contracts with district health boards lock in supply access and price visibility for institutional distributors, anchoring cost predictability while compressing margins for converters lacking multi-region fulfillment capability across New Zealand's fragmented procurement landscape.
Pricing Analysis
HealthCERT compliance mandates dictate the pricing tier structure across the New Zealand healthcare surface disinfectant wipes market. Three-tier pricing stratifies across hospital-grade sporicidal formulations, multi-surface quaternary ammonium products, and economy antiseptic wipes for primary care. Price differentiation hinges on validated contact time documentation and biodegradable substrate certification under the Waste Minimisation Act. Cost compression in aged-care channels is intensifying as operators replace reusable cloths with single-use formats. Nursing homes exhibit highest price sensitivity due to thin operational margins, while metropolitan hospital networks prioritize performance validation over unit cost.
Supply Chain Analysis
Inventory buffers and extended lead times characterize distributor relationships with Australian non-woven substrate converters across the Tasman Sea. Supply concentrates in Australia for cellulose-based biodegradable materials, China for polyester spunlace substrates, and domestic blending facilities in Auckland for final impregnation. Raw material dependencies span isopropyl alcohol from Taranaki petrochemical output, benzalkonium chloride active ingredients, and compostable packaging films. Single-source vulnerability from trans-Tasman shipping disruptions poses structural risk during biosecurity-driven procurement localisation. Distribution runs through institutional B2B supply contracting with district health boards, bypassed increasingly by pharmacy cooperative buying groups in provincial primary care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Te Whatu Ora's national health service merger, centralizing infection control product tendering and elevating multi-region fulfillment capability as a decisive vendor selection criterion across New Zealand's healthcare procurement landscape.
For Market Incumbents: Fortify district health board relationships by embedding compliance documentation and training support within contract structures. Deepen backward integration into certified compostable substrate supply chains to preempt Waste Minimisation Act margin compression. Expand capacity reservation agreements with Taranaki refinery operators to hedge isopropyl alcohol feedstock volatility threatening cost structures. For New Entrants and Emerging Players: Medsafe registration fast-track pathways through parallel submission with Australian TGA approvals accelerate market entry timelines. Target Waikato's diagnostic facility construction pipeline for DNA/RNA decontamination protocol specialization. Penetrate pharmacy cooperative buying groups in Tauranga and Palmerston North through direct-to-facility e-procurement platform partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward regional distributors with specialized South Island coverage and established aged-care facility relationships. Long-term viability over the projection horizon rests on biodegradable certification capabilities and HealthCERT audit documentation infrastructure. Watch for Te Whatu Ora tender consolidation announcements as inflection indicators for sector-wide margin restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Medsafe Registration Fast-Track | Parallel TGA submissions compress product launch timelines by eight to fourteen months under current biodegradable certification delays. |
| Backward Integration into Substrates | In-house production of cellulose-based biodegradable materials preempts Waste Minimisation Act compliance deadlines squeezing converter margins. |
| Multi-Region Fulfillment Expansion | Distribution networks spanning Auckland, Canterbury, and Otago satisfy Te Whatu Ora centralized tender consolidation requirements. |
| Pharmacy Cooperative Partnership | Channel alignment with Tauranga and Palmerston North buying groups captures primary care volume fragmenting away from institutional distributors. |
| HealthCERT Documentation Platform | Digital compliance logging systems embed vendor stickiness through audit-ready disinfection protocol traceability for aged-care operators. |
Research Methodology
A spread of perspectives from infection control officers, district health board procurement managers, aged-care facility operators, and non-woven substrate converters converged on the working assumptions shaping this analysis. Primary field engagement combined structured interviews with institutional distributors and environmental services technicians alongside secondary validation through HealthCERT technical advisories, Medsafe registration databases, and district health board tender documentation. Customs records tracking isopropyl alcohol and quaternary ammonium compound import flows supplemented trade flow analysis. Bottom-up facility-level consumption estimates triangulated against top-down pharmaceutical regulatory filings.
Segmentation dimensions modeled span product type chemistry, end-user facility category, packaging format specifications, and distribution channel structure across the projection horizon. CAGRs derive from facility expansion pipelines, HealthCERT audit frequency intensification schedules, and substrate innovation adoption curves. Forecast inputs incorporate Te Whatu Ora consolidation timelines, Waste Minimisation Act compliance phase-in assumptions, and trans-Tasman shipping reliability scenarios affecting Australian substrate supply.
Decision-makers should treat outputs as directional under assumptions of continued HealthCERT audit intensification and stable trans-Tasman trade flows; material deviation through biosecurity disruption or regulatory acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Ear Infection Treatment Market
Infection Control
Yeast Infection Market
Infection Control
Hand Hygiene Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Virus Filtration Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Sterilization Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Infection Control Supplies Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Hospital Acquired Infections Therapeutic Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Point of Care Infection Control Market