
 United Kingdom Respiratory Devices Market | 2026-2036
United Kingdom Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Respiratory Devices Market Analytics
Germany's precision manufacturing base for ventilator components is narrowing the UK's historical reliance on imported critical care modules. Fisher & Paykel Healthcare Ltd anchors its European humidification systems supply from manufacturing footprints in Germany and New Zealand, leveraging dual-source resilience. ResMed Inc. competes through cloud-connected CPAP platforms that sustain recurring revenue from sleep apnea patients across NHS England commissioning groups. Philips Respironics differentiates via integrated diagnostic-to-therapy workflows that dominate hospital procurement frameworks in the UK.
United Kingdom respiratory devices encompass mechanical apparatus, drug delivery systems, and monitoring instruments engineered to diagnose, treat, or manage pulmonary conditions, typically incorporating flow sensors, pressure regulators, and filtration media rated for biocompatibility under ISO 18562. These systems serve acute hospital ventilation, chronic disease management, and ambulatory oxygen therapy across clinical and domestic settings. Inhalers and nebulizers constitute the mature volume core where generic competition compresses margins, while CPAP devices capture premium pricing through software subscription attach rates. Homecare represents the fastest-growing end user channel as NHS England pushes hospital-at-home models that shift ventilator and oxygen concentrator deployment into domestic environments.
MHRA enforces UKCA marking requirements that diverged from CE marking post-Brexit, forcing manufacturers to maintain parallel conformity assessment procedures for the British market. NICE technology appraisals determine reimbursement eligibility for novel respiratory interventions, directly shaping manufacturer commercialization sequencing and evidence generation investments. The Care Quality Commission's oversight of domiciliary care providers influences procurement standards for home-deployed oxygen and ventilation equipment. Stakeholders must monitor whether MHRA's anticipated alignment with EU MDR timelines stabilizes or extends regulatory duplication costs for device sponsors operating across both jurisdictions.
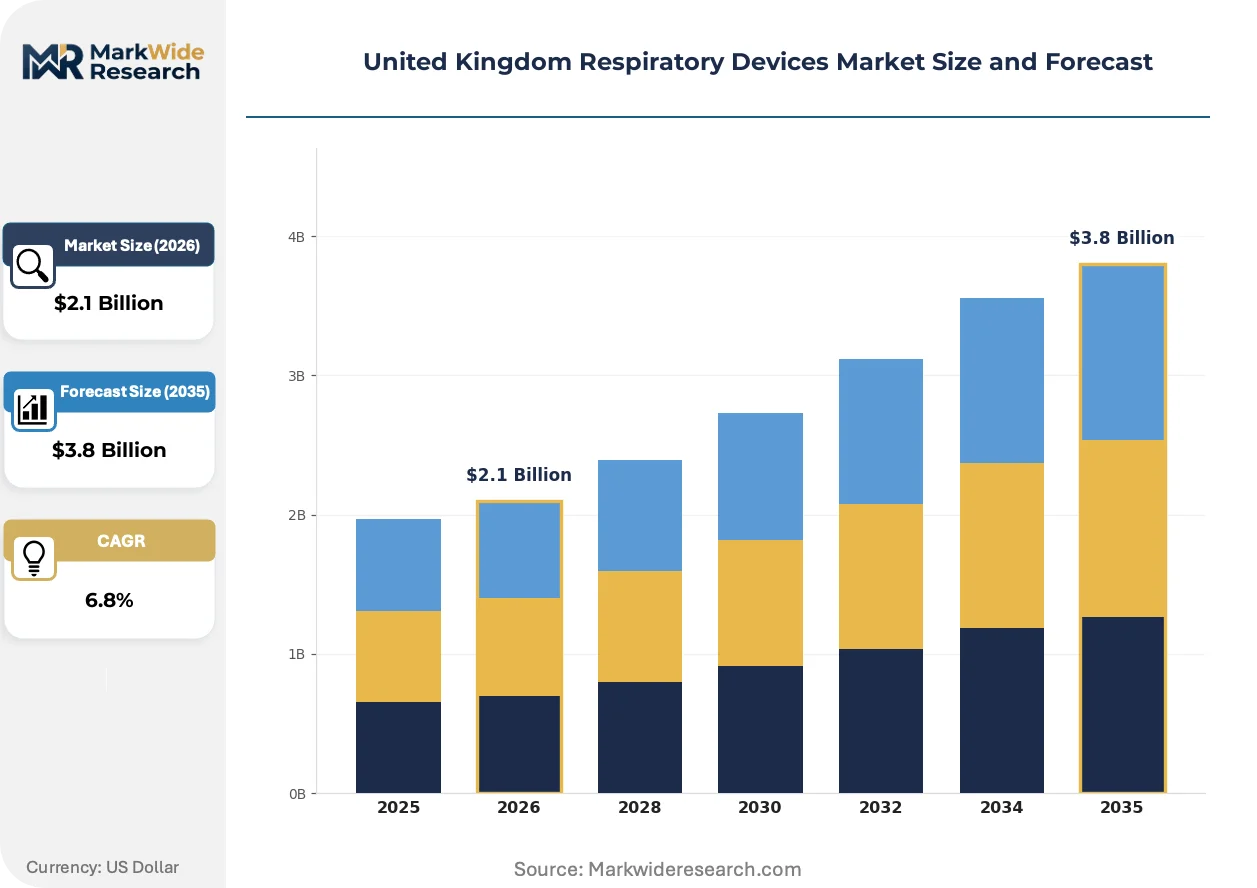
Market Dynamics
NHS England's hospital-at-home expansion is collapsing traditional site-of-care boundaries for ventilation and oxygen therapy, forcing manufacturers to reengineer devices for domestic environments while maintaining clinical-grade reliability standards.
Growth Catalysts
- MHRA Software-as-Medical-Device Guidance:Updated pathways for digital inhalers and remote monitoring platforms are accelerating product registration timelines for connected respiratory technologies.
- Homecare Provider Networks:Domiciliary care operators across England and Scotland are scaling connected respiratory monitor deployments to support chronic disease management outside hospital walls.
- Greater London NHS Trust Clusters:Concentrated procurement volumes from commissioning groups in the capital are creating demand anchors that pull supply chain investment toward the southeast.
Market Restraints
- Dual Conformity Assessment Burden:UKCA marking divergence from CE marking post-Brexit forces manufacturers to maintain parallel certification procedures, inflating regulatory compliance costs for the British market.
- German Component Dependency:Precision-manufactured ventilator modules sourced from German suppliers create concentration risk in critical care supply chains serving UK hospitals.
- Generic Inhaler Margin Compression:Patent-expired drug delivery devices face pricing pressure from commoditized alternatives, squeezing returns in the highest-volume product segment.
Strategic Opportunities
- Manchester-Leeds Hospital Corridor:Procurement frameworks across northern England's integrated care systems present underpenetrated demand for integrated diagnostic-to-therapy workflows.
- Cloud-Connected CPAP Subscriptions:Recurring revenue models from sleep apnea patient monitoring platforms offer margin expansion beyond device hardware sales.
- NICE Technology Appraisal Alignment:Evidence generation investments targeting NICE reimbursement eligibility can unlock preferential positioning within NHS commissioning decisions.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 18562 filtration media certification timelines delay product launches for devices incorporating novel materials or modified flow paths.
- Legacy Hospital IT Integration:Remote patient monitoring platforms face interoperability friction with NHS England's fragmented electronic health record infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Respiratory Devices Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, CPAP Devices, Oxygen Concentrators Application: Asthma, COPD, Sleep Apnea, Lung Diseases End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Technology: Electronic, Manual, Portable, Stationary |
| Companies Covered | Fisher & Paykel Healthcare Ltd, Philips Respironics, ResMed Inc., Drägerwerk AG & Co. KGaA, GE Healthcare, GSK plc, Drive DeVilbiss Healthcare, Medtronic plc, Invacare Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Respiratory Devices Market Evolving Landscape
Connected respiratory technologies are collapsing the distinction between acute and ambulatory care settings, forcing simultaneous innovation in hardware miniaturization, cloud architecture, and regulatory evidence frameworks.
Digital inhalers with embedded dose-counters and Bluetooth connectivity are collapsing the historical separation between medication adherence tracking and clinical decision support. NHS England's integrated care systems are piloting these devices for asthma and COPD cohorts at scale. The technology is collapsing pharmaceutical reimbursement models toward outcomes-based frameworks that tie payment to demonstrated adherence improvements.
MHRA's anticipated alignment with EU MDR timelines is creating regulatory uncertainty for device sponsors operating across both jurisdictions. Manufacturers face parallel conformity assessment procedures until divergence stabilizes. The UKCA marking transition most affects digital inhaler and remote monitoring platform developers with limited compliance infrastructure.
Hospital-at-home procurement is fragmenting traditional tender structures that bundled ventilator and oxygen concentrator purchases within acute care capital budgets. Integrated care systems in Greater London and the Manchester-Leeds corridor are unbundling these acquisitions into separate homecare service contracts. Scotland's NHS boards are advancing fastest in this disintermediation, rewriting supplier qualification requirements around domestic installation and patient training capabilities.
United Kingdom Respiratory Devices Market Segmentation
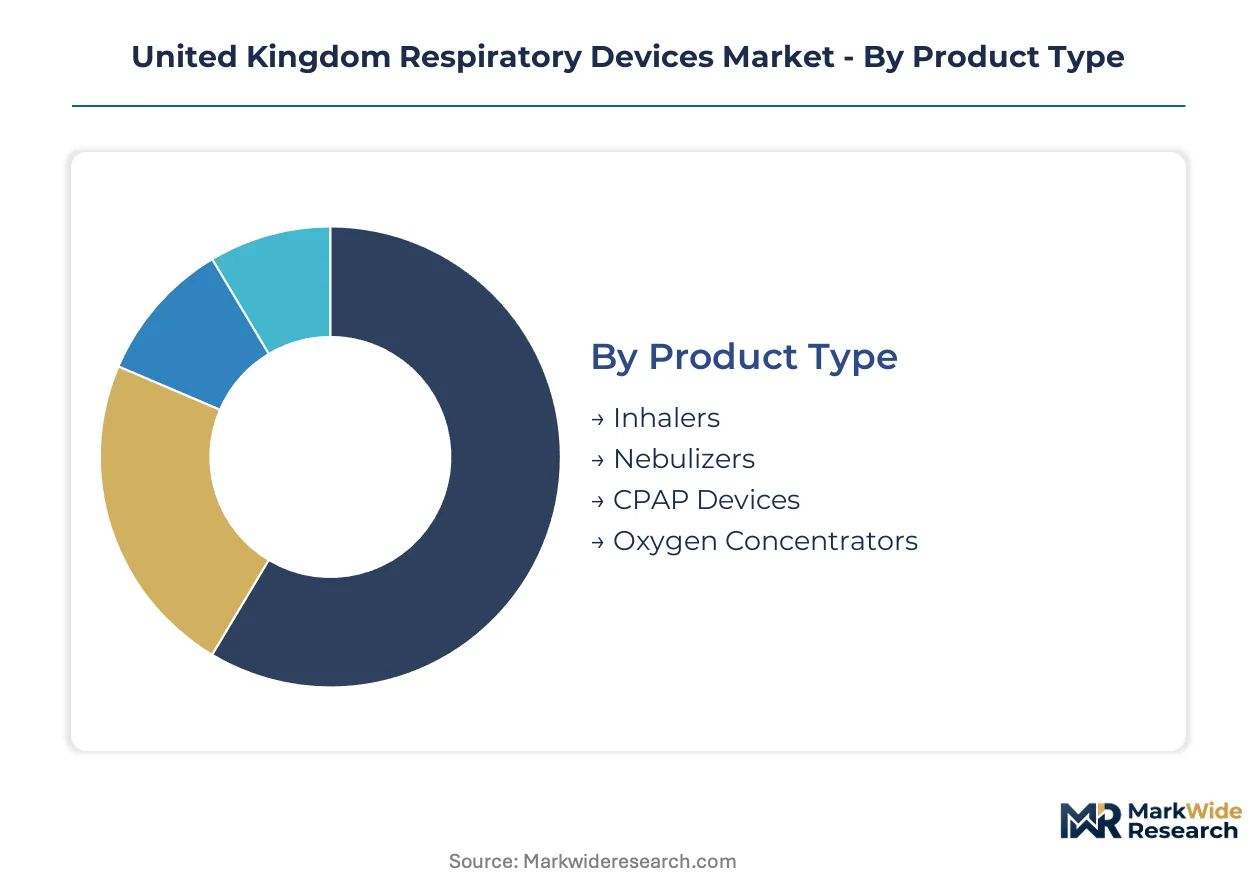
Respiratory device segmentation in the United Kingdom reveals divergent service intensity profiles across product categories. After-sales requirements vary dramatically between disposable inhaler refills and complex CPAP maintenance contracts, reshaping manufacturer margin structures and channel economics.
Product Type:
After-sales service intensity separates these segments into two distinct commercial models: hardware-plus-consumables versus subscription-enabled platforms.
- Inhalers:Metered-dose and dry-powder devices dominate prescription volumes across NHS England formularies. Generic competition compresses unit margins, forcing manufacturers to capture value through high-volume pharmaceutical partnerships rather than device premiums.
- CPAP Devices:Cloud-connected sleep apnea platforms generate recurring revenue through software subscriptions and remote monitoring services. NHS England commissioning groups increasingly specify these capabilities in procurement frameworks, elevating total cost of ownership over upfront hardware pricing.
- Nebulizers:Compressor and mesh technologies serve acute exacerbation management in hospital and home settings.
- Oxygen Concentrators:Stationary and portable units support long-term oxygen therapy for COPD cohorts across domiciliary care networks.
By volume, Inhalers leads. By growth pace, CPAP Devices is ahead.
Application:
Clinical pathway reimbursement status determines device selection criteria and evidence requirements for each indication.
- Asthma:Digital inhalers with adherence tracking are penetrating NHS England integrated care system pilots. NICE technology appraisals for connected devices are reshaping procurement toward outcomes-based contracts that tie payment to demonstrated reduction in acute exacerbations.
- Sleep Apnea:Diagnostic-to-therapy workflows dominate hospital procurement, with cloud-connected platforms capturing premium positioning through remote patient monitoring capabilities that reduce clinic visit burdens.
- COPD:Long-term oxygen therapy and nebulization support chronic management across homecare provider networks.
- Lung Diseases:Interstitial lung disease and pulmonary fibrosis applications require specialized ventilation support in tertiary referral centers.
Asthma commands the largest patient population. Sleep Apnea shows the steepest expansion trajectory.
End User:
Site-of-care migration from acute settings to domestic environments is fragmenting traditional procurement structures.
- Homecare:Domiciliary care operators across England and Scotland are scaling connected respiratory monitor deployments. NHS England's hospital-at-home expansion is collapsing site-of-care boundaries, forcing manufacturers to reengineer devices for domestic reliability standards.
- Hospitals:Acute care trusts in Greater London procurement clusters concentrate demand for critical care ventilators and high-flow oxygen systems. The Manchester-Leeds hospital corridor presents underpenetrated demand for integrated diagnostic-to-therapy workflows.
- Clinics:Community respiratory services handle diagnostic workup and therapy initiation.
- Rehabilitation Centers:Post-acute weaning and respiratory muscle training support recovery trajectories.
Hospitals retain the highest equipment value per site. Homecare is expanding most quickly.
Technology:
Power source and mobility configuration determine regulatory pathways and patient training requirements.
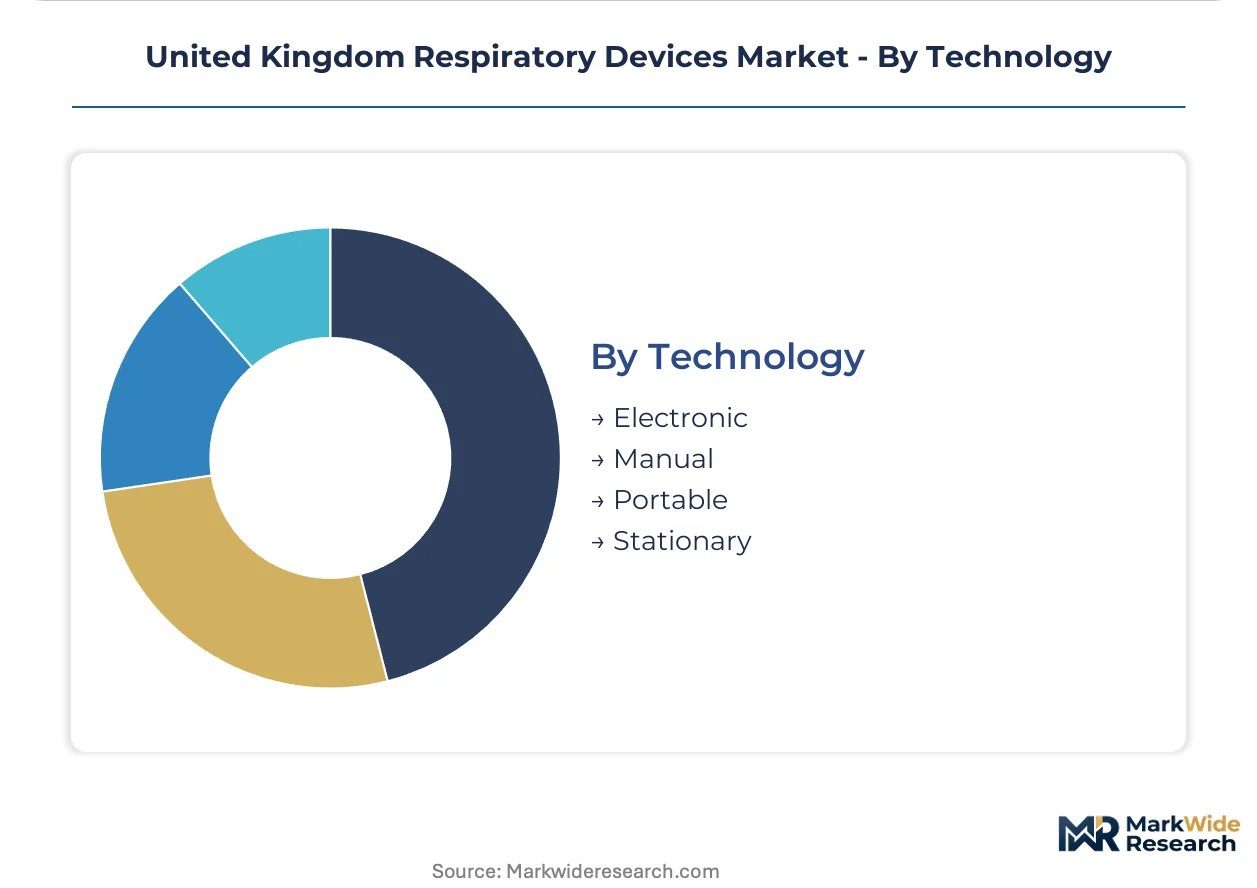
- Electronic:Sensor-embedded devices with Bluetooth connectivity and cloud integration require MHRA software-as-a-medical-device registration. Updated guidance is accelerating timelines for digital inhaler and remote monitoring platform developers.
- Portable:Battery-powered oxygen concentrators and travel CPAP units support patient mobility. Scotland's NHS boards are advancing fastest in rewriting supplier qualification requirements around domestic installation capabilities.
- Manual:Mechanical devices without electronic components face simpler conformity assessment procedures.
- Stationary:Fixed-installation ventilators and concentrators serve bedbound patients.
Electronic systems capture the premium tier. Portable configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision-manufactured ventilator components from Germany concentrate critical supply risk for UK hospitals. MHRA's UKCA marking divergence from CE standards forces parallel conformity assessments across all British market entry pathways.
Greater London
NHS commissioning clusters in the capital concentrate procurement volumes for digital inhalers and connected CPAP platforms. NICE technology appraisals determine reimbursement eligibility for novel respiratory interventions across integrated care systems. The London-Southeast corridor anchors demand for hospital-at-home ventilator deployments.
Manchester-Leeds Corridor
Integrated care systems across northern England present underpenetrated demand for diagnostic-to-therapy workflows. Scotland's NHS boards advance faster in rewriting supplier qualification requirements for domestic oxygen concentrator installations. The corridor's hospital procurement frameworks favor cloud-connected monitoring capabilities.
Scotland
NHS boards lead UK-wide disintermediation of traditional acute care tender structures into separate homecare service contracts. The Care Quality Commission's domiciliary care oversight influences procurement standards for portable oxygen equipment. Edinburgh and Glasgow clusters concentrate chronic disease management device deployments.
Wales
Community respiratory services handle diagnostic workup and therapy initiation across dispersed rural populations. Welsh health boards prioritize portable electronic devices with Bluetooth connectivity for remote patient monitoring. Cardiff-Newport corridor concentrates supplier qualification for mesh nebulizer technologies.
Midlands
Rehabilitation centers across Birmingham and Nottingham support post-acute weaning and respiratory muscle training. MHRA software-as-a-medical-device registration timelines affect digital inhaler developers with limited compliance infrastructure. The region's manufacturing footprint supplies filtration media components to ventilator assemblers.
United Kingdom Respiratory Devices Market Competitive Landscape
Multi-divisional healthcare conglomerates and specialized respiratory technology firms split the market between integrated portfolio breadth and focused innovation depth. The vendor base concentrates around three strategic archetypes: diversified medtech majors leveraging cross-category procurement relationships, pure-play respiratory specialists monetizing software subscription attach rates, and pharmaceutical-device hybrids capturing value through drug delivery partnerships. Dominant competitive moves include backward integration into precision component manufacturing and geographic expansion through NHS trust framework positioning.
Among diversified medtech majors, GE Healthcare and Medtronic plc occupy positions spanning diagnostic imaging through therapeutic intervention. Fisher & Paykel Healthcare Ltd exemplifies the pure-play respiratory specialist archetype, anchoring European humidification systems supply from dual-source manufacturing footprints. Philips Respironics sits within the integrated diagnostic-to-therapy tier, representing workflow consolidation strategies that dominate hospital procurement frameworks.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare Ltd |
| Philips Respironics |
| ResMed Inc. |
| Drägerwerk AG & Co. KGaA |
| GE Healthcare |
| GSK plc |
| Drive DeVilbiss Healthcare |
| Medtronic plc |
| Invacare Corporation |
| Others |
Value Network & Pricing Analysis
Undercapacity in precision-machined ventilator component fabrication across German supplier networks is amplifying pricing power for critical care module producers while forcing UK hospital procurement teams toward longer-term offtake commitments. This utilization squeeze propagates through device assembly tiers, elevating working capital requirements for manufacturers and compressing margins on standardized oxygen concentrators.
Pricing Analysis
MHRA's UKCA marking requirements dictate the pricing tier structure across the British respiratory devices market. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected CPAP platforms with software subscriptions from basic nebulizers and generic inhalers. Certification grade and after-sales service bundling drive price differentiation between MHRA-registered electronic devices and manual alternatives. Cost compression in the inhaler segment is intensifying because pharmaceutical generic competition erodes device premiums. NHS England commissioning groups exhibit highest price sensitivity on upfront hardware, while domiciliary care operators show lowest sensitivity for subscription-enabled monitoring platforms.
Supply Chain Analysis
Contract manufacturing concentration for ventilator humidification systems rests with Fisher & Paykel's dual-source footprints in Germany and New Zealand. Geographic supply concentration draws from Germany for precision-machined components, China for electronic sensors and batteries, and domestic UK assemblers for final device integration. Raw material dependencies hinge on biocompatible filtration media, medical-grade silicones, and lithium-ion power cells. Single-source vulnerability concentrates in German precision component suppliers serving critical care ventilation modules. Distribution runs through NHS trust procurement frameworks and domiciliary care service contracts rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected CPAP subscription layers and remote patient monitoring service contracts are expanding faster than hardware sales, transforming respiratory devices into recurring-revenue platforms where software attach rates determine enterprise value.
For Market Incumbents: Entrench dominance in Greater London NHS trust procurement clusters by deepening backward integration into filtration media component production, insulating against ISO 18562 certification bottlenecks. Secure exclusive supplier qualification status with Scotland's NHS boards for hospital-at-home oxygen concentrator deployments before competitive frameworks solidify. Capacity addition in Midlands manufacturing corridors anchors domestic supply resilience against German component concentration risk. For New Entrants and Emerging Players: The Manchester-Leeds hospital corridor's integrated care systems represent the most penetrable entry point for diagnostic-to-therapy workflow platforms, with procurement frameworks favoring cloud-connected capabilities that incumbent diversified medtech majors underweight. Mid-market domiciliary care operators in Wales and northern England seek portable electronic devices with Bluetooth connectivity for dispersed rural populations. A software-first go-to-market angle—lead with MHRA software-as-a-medical-device registration for remote monitoring platforms before hardware certification—accelerates revenue recognition while compliance infrastructure scales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pure-play respiratory specialists monetizing CPAP subscription attach rates and humidification system service contracts. Long-term viability across the analysis window favors acquisition targets with established NHS England framework positioning and demonstrated NICE technology appraisal navigation. The signal to watch is MHRA alignment with EU MDR timelines—regulatory divergence stabilization would compress compliance costs for dual-market operators and unlock margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Software-as-Medical-Device Registration | Accelerates market entry timelines for digital inhaler developers targeting NHS England integrated care pilots. |
| Hospital System Partnership | Locks in preferred supplier status within Greater London commissioning clusters for ventilator and oxygen therapy platforms. |
| Backward Integration into Filtration Media | Captures ISO 18562 certification timelines and reduces dependency on Midlands component suppliers. |
| Reimbursement Strategy | Aligns evidence generation investments with NICE technology appraisals to unlock NHS commissioning decisions. |
| Software Companion Development | Enables recurring revenue models through remote patient monitoring subscriptions attached to CPAP hardware sales. |
Research Methodology
Initial hypotheses were tested against primary input from NHS England commissioning managers, biomedical engineers at acute care trusts, domiciliary care procurement leads, and MHRA regulatory affairs specialists and refined through secondary validation. Primary interviews combined with hospital procurement databases, GPO contracts, MHRA device registration filings, and NICE technology appraisal documentation established demand-side ground truth. Bottom-up patient cohort modeling and top-down NHS England budget allocation analysis triangulated market sizing.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology configuration alongside regional procurement cluster intensity. CAGRs were derived from patient population growth trajectories, NHS hospital-at-home expansion targets, and device replacement cycles. Forecast inputs incorporated MHRA registration timeline assumptions and NICE reimbursement eligibility probabilities.
Macroeconomic conditions sit as an overlay; deviation in NHS England capital expenditure allocations or sterling-euro exchange rate volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory divergence stabilization and integrated care system procurement consolidation. Quarterly review of MHRA guidance updates and NHS trust framework award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Implantable Collamer Lens Market
Medical Devices
Steerable Needles Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Cryoablation Devices Market
Medical Devices
Medical Machine Battery Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Global Radiofrequency Ablation Devices Market