
 Global Hospital Acquired Infection Control Market | 2026-2036
Global Hospital Acquired Infection Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hospital Acquired Infection Control Market Analysis
A capital-intensity divergence between automated sterilization platforms and manual chemical disinfection workflows is reorganizing competitive tiers in hospital infection control. STERIS plc leverages integrated sterilization systems to dominate capital equipment placements in North American academic medical centers. 3M Company sustains adhesive-based antimicrobial portfolio strength across outpatient surgical settings. Getinge AB anchors its position through washer-disinfector automation lines that reduce reprocessing labor in high-throughput hospitals.
Hospital acquired infection control encompasses engineered systems, chemical formulations, and procedural protocols designed to prevent pathogen transmission in clinical environments, with sterilization equipment typically achieving SAL 10^-6 microbial kill assurance and UV-C systems delivering 254 nm wavelength dosage for surface decontamination. The primary purpose spans breaking chain of infection across surgical instruments, environmental surfaces, and healthcare worker contact points. Disinfectants occupy the largest product volume pool given recurring consumption in daily terminal cleaning protocols, while sterilization equipment captures disproportionate margin concentration due to capital replacement cycles and proprietary consumable lock-in. Personal protective equipment competes on regulatory certification tiering, with FDA-cleared surgical N95 respirators commanding premium positioning over standard isolation gowns.
The FDA enforces 510(k) premarket notification for sterilization devices under 21 CFR Part 880, while the EMA's MDR framework reclassifies reusable surgical instrument reprocessors to Class IIa with heightened clinical evidence requirements. EPA registration under FIFRA governs hospital disinfectant label claims, creating a three-year regulatory barrier for novel active ingredient entry. WHO infection prevention guidelines additionally shape procurement specifications in low-resource settings through essential device lists. Stakeholders must monitor evolving EU Green Deal restrictions on ethylene oxide emissions, as this sterilization modality faces phase-down pressure that would force capital conversion toward hydrogen peroxide vapor and ozone-based alternatives.
Market Dynamics
Ethylene oxide phase-down mandates under the EU Green Deal are forcing sterilization infrastructure conversion toward hydrogen peroxide vapor and ozone-based alternatives, compressing capital replacement cycles and reordering equipment supplier hierarchies.
Growth Catalysts
- Surgical site infection prevention mandates:Joint Commission accreditation standards now require documented terminal cleaning validation in ambulatory surgical centers, expanding automated disinfection system procurement.
- Reprocessing evidence requirements:EMA's MDR Class IIa reclassification for reusable surgical instrument reprocessors demands enhanced clinical data packages, favoring established manufacturers with regulatory infrastructure.
- Japan's hospital infrastructure renewal:METI-funded facility modernization programs accelerate UV-C surface decontamination system deployment in tertiary care institutions.
Market Restraints
- Ethylene oxide supply concentration:Sterilant gas production clusters in Gulf Coast petrochemical corridors expose reprocessing facilities to hurricane-related supply disruptions and price volatility.
- Copper and silver ion input costs:Antimicrobial coating formulations face raw material price pressure from mining supply constraints and energy-intensive refining processes.
- Autoclave throughput limitations:Steam sterilization's temperature and moisture sensitivity excludes heat-labile polymer instruments, restricting application scope in advanced laparoscopic surgery.
Strategic Opportunities
- India's tier-2 hospital expansion:CDSCO streamlined medical device registration pathways and PLI scheme incentives attract sterilization equipment manufacturers to establish local assembly operations.
- Point-of-use sterilization convergence:Integration of hydrogen peroxide vapor chambers with robotic surgical suites enables immediate instrument turnaround, reducing central sterile supply department dependency.
- EPA Safer Choice program alignment:Hospital systems pursuing sustainability certifications create preference pull for quaternary ammonium formulations with improved occupational exposure profiles.
Industry Challenges
- Sterile processing technician certification bottlenecks:IAHCSMM and CBSPD credentialing program capacity constraints limit workforce expansion needed for automated reprocessing line operation.
- Legacy steam infrastructure integration:Washer-disinfector automation retrofits require structural floor reinforcement and utility capacity upgrades in aging hospital plants built before 1990.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hospital Acquired Infection Control Market |
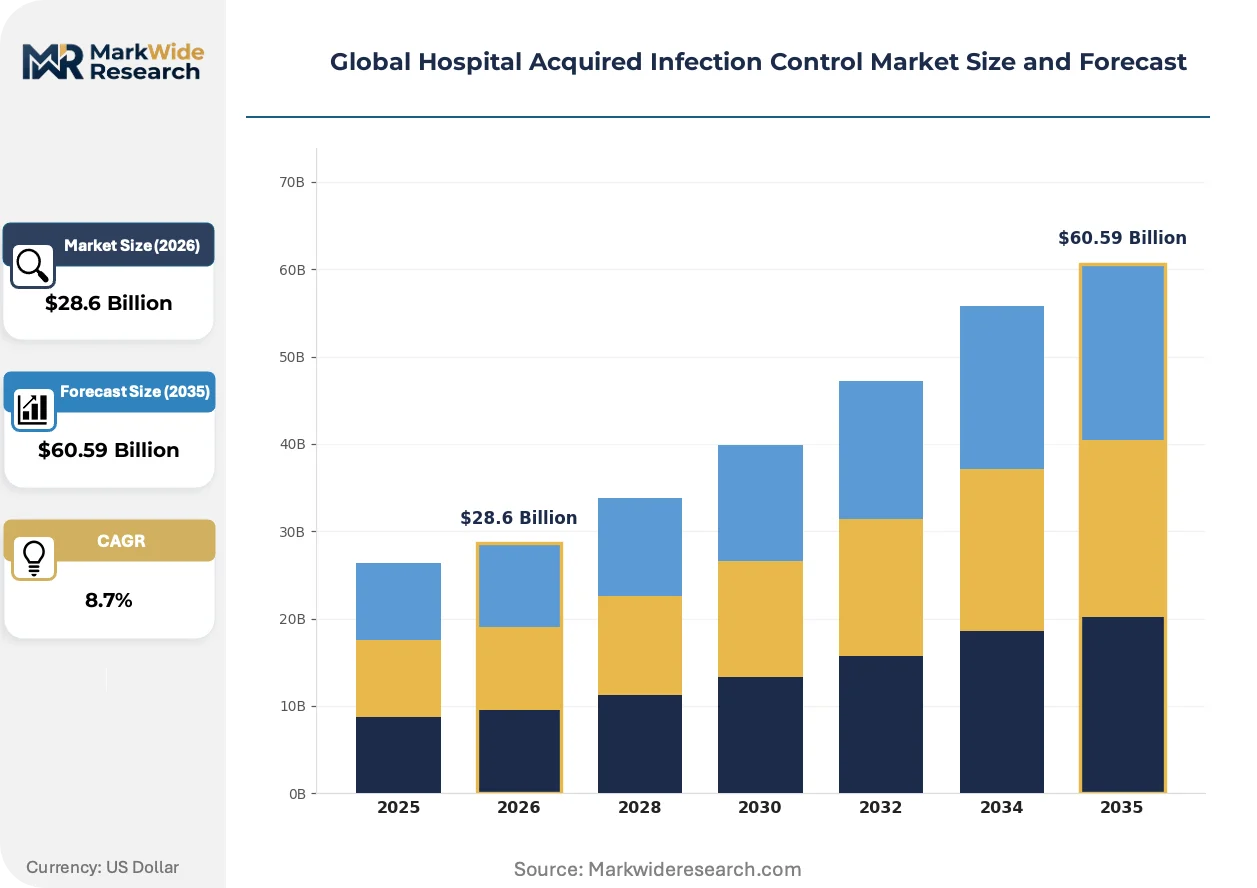
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectants, Antibiotics, Sterilization Equipment, Personal Protective Equipment Technology: UV Light, Chemical Solutions, Thermal Methods, Electromagnetic Radiation End User: Hospitals, Long-Term Care Facilities, Outpatient Clinics, Surgical Centers Service Type: Consulting Services, Installation Services, Maintenance Services, Training Services |
| Companies Covered | STERIS plc, 3M Company, Getinge AB, Ecolab Inc., Becton, Dickinson and Company, Advanced Sterilization Products, Belimed Inc., Cantel Medical, Sotera Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hospital Acquired Infection Control Market Emerging Trajectories
Novel surface decontamination modalities are compressing dwell-time requirements and challenging chemical disinfectant volume economics across high-touch clinical environments.
UV-C LED arrays operating at 265-280 nm wavelengths are fragmenting mercury vapor lamp dominance in surface disinfection applications. Outpatient surgical centers and long-term care facilities adopt these solid-state systems for their instant-on capability and reduced mercury disposal liability. The technology is fragmenting capital equipment supplier margins by enabling modular, scalable deployments that bypass traditional central engineering procurement channels.
REACH restrictions on peracetic acid concentrations are compelling reformulation of automated endoscope reprocessing chemistries. German and French health technology assessment bodies now require environmental fate documentation in disinfectant procurement tenders. High-throughput endoscopy centers in Bavaria and Rhône-Alpes regions accelerate adoption of alternative high-level disinfectants with improved biodegradability profiles.
Consolidated purchasing organizations are unbundling sterilization equipment service contracts from capital sale agreements. IDN procurement teams in Texas and California now separately negotiate preventive maintenance, consumable supply, and remote monitoring subscriptions. This purchasing behavior shift concentrates vendor selection authority within supply chain functions rather than clinical engineering departments.
Global Hospital Acquired Infection Control Market Segmentation
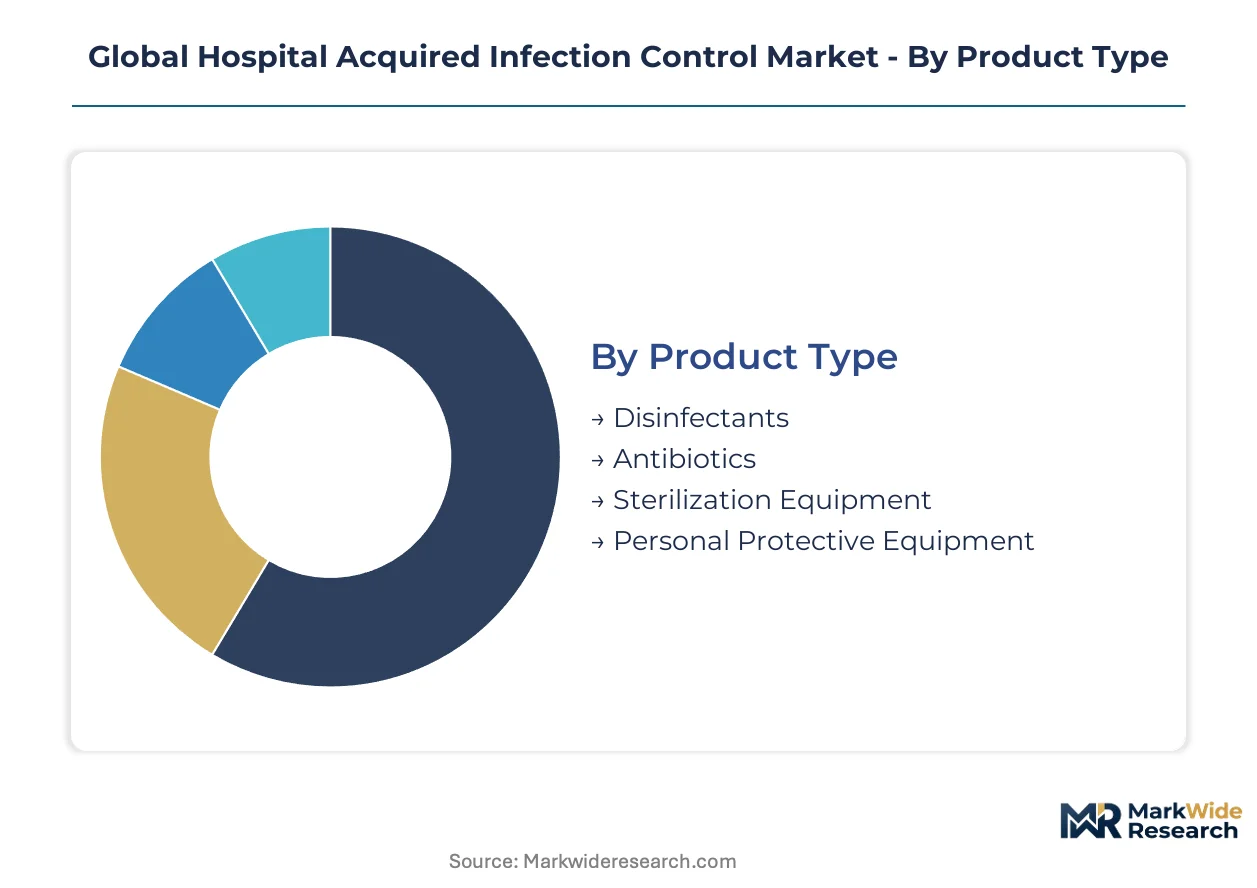
Hospital infection control procurement channels diverge sharply between capital-intensive sterilization platforms and recurring consumable streams. Understanding segment-channel alignment reveals where vendor margin capture concentrates versus where price commoditization pressures dominate.
Product Type:
Capital equipment flows through clinical engineering and central sterile supply departments, while chemical consumables route through group purchasing organizations and distributor networks.
- Disinfectants:Quaternary ammonium compounds, chlorine-based formulations, and hydrogen peroxide blends constitute the highest-volume procurement category. Daily terminal cleaning protocols in United States hospitals and German surgical centers drive recurring purchase cycles, with EPA Safer Choice and REACH biodegradability credentials now gating contract eligibility.
- Sterilization Equipment:Autoclaves, ethylene oxide chambers, and hydrogen peroxide vapor systems achieve SAL 10^-6 microbial kill assurance. Japanese tertiary care institutions and North American academic medical centers dominate capital placement demand, accelerated by METI-funded infrastructure renewal and Joint Commission accreditation mandates.
- Antibiotics:Systemic prophylaxis for surgical site infection prevention in cardiac and orthopedic procedures.
- Personal Protective Equipment:FDA-cleared surgical N95 respirators and isolation gowns differentiated by regulatory certification tiering.
By volume, Disinfectants leads. By growth pace, Sterilization Equipment is ahead.
Technology:
Technology selection maps directly to instrument material compatibility constraints and throughput requirements, with thermal methods dominating legacy metal instruments while newer modalities address heat-labile polymers.
- Chemical Solutions:Peracetic acid, glutaraldehyde, and ortho-phthalaldehyde formulations achieve high-level disinfection for flexible endoscopes. Bavarian and Rhône-Alpes endoscopy centers in Germany and France accelerate adoption as REACH concentration restrictions force reformulation toward improved biodegradability profiles.
- UV Light:Mercury vapor lamps and solid-state LED arrays at 254-280 nm wavelengths deliver surface decontamination without moisture or residue. Outpatient surgical centers in Texas and California prefer modular LED deployments for instant-on capability and reduced mercury disposal liability.
- Thermal Methods:Steam autoclaving remains the workhorse for heat-stable surgical instruments.
- Electromagnetic Radiation:Gamma and electron beam sterilization for single-use device manufacturing.
Chemical Solutions commands the largest installed base. UV Light is climbing the fastest.
End User:
End-user scale determines procurement sophistication, with integrated delivery networks extracting price concessions unavailable to standalone facilities.
- Hospitals:Tertiary and quaternary institutions with central sterile supply departments and dedicated infection prevention committees. United States academic medical centers and Japanese metropolitan hospitals anchor demand for automated washer-disinfector lines and UV-C surface decontamination systems.
- Surgical Centers:Ambulatory facilities facing Joint Commission terminal cleaning validation requirements. German and United States outpatient surgical settings drive compact sterilization equipment procurement for immediate instrument turnaround.
- Long-Term Care Facilities:Skilled nursing and assisted living environments with elevated environmental cleaning frequency needs.
- Outpatient Clinics:Physician offices and diagnostic centers with limited reprocessing infrastructure.
Hospitals absorb the majority of capital expenditure. Surgical Centers is gaining share fastest.
Service Type:
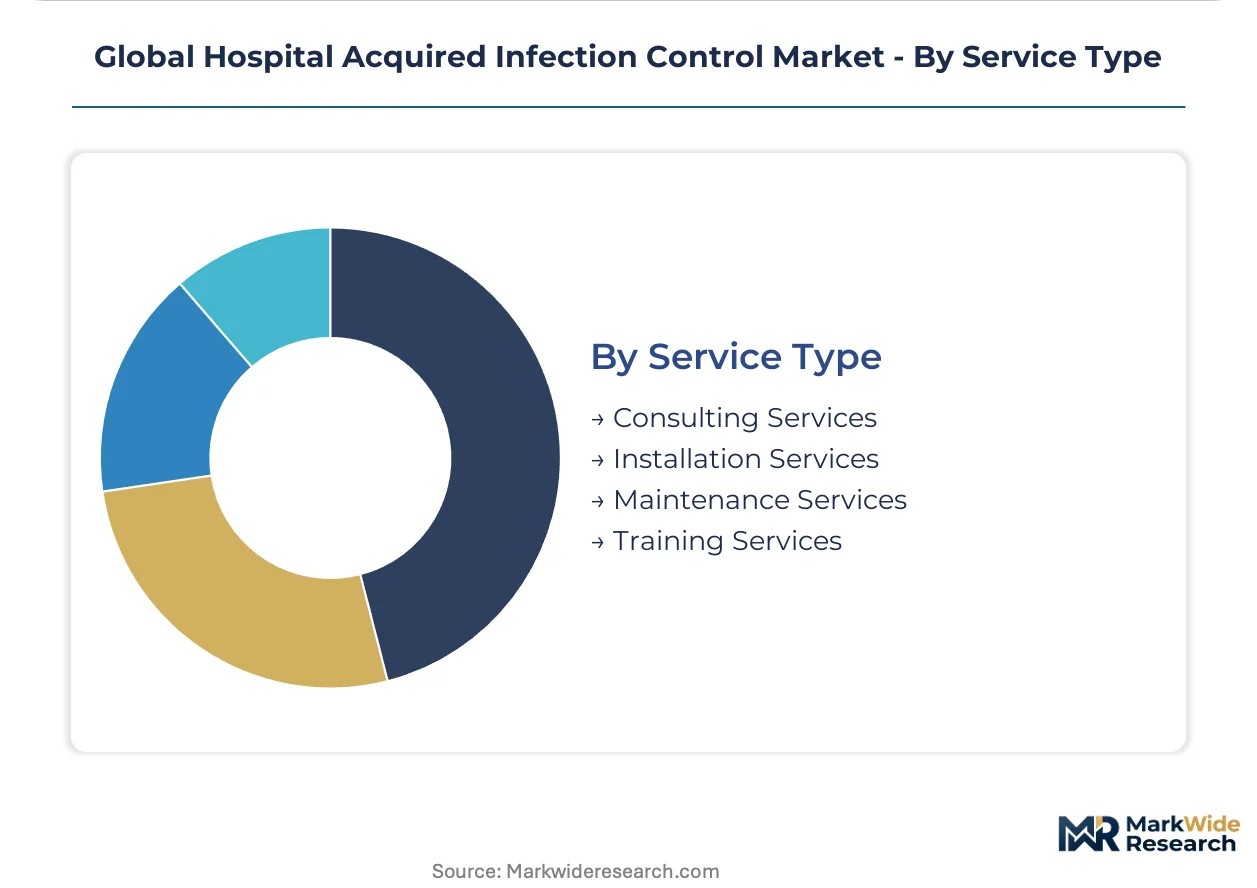
Service revenue attachment rates vary inversely with customer technical sophistication, with training and consulting commanding premium pricing in emerging markets.
- Maintenance Services:Preventive maintenance contracts and emergency repair coverage for sterilization equipment. United States IDN procurement teams in Texas and California increasingly unbundle these from capital sales, negotiating remote monitoring subscriptions separately.
- Training Services:IAHCSMM and CBSPD certification preparation for sterile processing technicians. India's tier-2 hospital expansion creates demand as CDSCO streamlined registration and PLI scheme incentives attract equipment manufacturers requiring technician workforce development.
- Consulting Services:Infection prevention program assessment and accreditation preparation.
- Installation Services:Structural reinforcement and utility upgrades for washer-disinfector automation retrofits.
Maintenance Services generates the steadiest recurring revenue. Training Services shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between capital-intensive sterilization equipment in Japanese tertiary hospitals and consumable disinfectant volume in United States outpatient settings. Germany anchors European demand through automated washer-disinfector retrofits, while India's tier-2 expansion favors modular point-of-use systems. These geographic differences reshape vendor go-to-market priorities.
United States
Academic medical centers in Texas and California drive automated sterilization platform procurement as IDN procurement teams unbundle service contracts from capital sales. FDA 510(k) premarket notification requirements under 21 CFR Part 880 create regulatory barriers favoring established manufacturers with clinical data infrastructure. The Joint Commission's surgical site infection prevention mandates expand terminal cleaning validation requirements across ambulatory surgical centers in the Dallas-Fort Worth and Los Angeles metropolitan clusters.
Germany
Bavarian and Rhône-Alpes endoscopy centers accelerate adoption of alternative high-level disinfectants as REACH concentration restrictions force peracetic acid reformulation. The EMA's MDR Class IIa reclassification for reusable surgical instrument reprocessors demands enhanced clinical evidence packages. Stuttgart and Munich anchor washer-disinfector automation demand as METI-funded infrastructure renewal programs accelerate capital replacement cycles in high-throughput hospitals.
Japan
Tokyo and Osaka metropolitan hospitals anchor UV-C surface decontamination system deployment through METI-funded facility modernization programs. PMDA medical device registration requirements shape procurement specifications for hydrogen peroxide vapor alternatives to ethylene oxide sterilization. The Kansai region's tertiary care institutions concentrate demand for SAL 10^-6 microbial kill assurance systems in robotic surgical suites.
India
Tier-2 hospital expansion in Maharashtra and Gujarat creates demand for compact sterilization equipment as CDSCO streamlined registration pathways reduce market entry barriers. The PLI scheme attracts equipment manufacturers to establish local assembly operations requiring technician workforce development. Delhi-NCR and Bangalore clusters concentrate procurement of point-of-use hydrogen peroxide vapor chambers for immediate instrument turnaround in high-volume surgical settings.
France
Paris and Lyon health technology assessment bodies now require environmental fate documentation in disinfectant procurement tenders. ANSM enforcement of MDR clinical evidence requirements favors established reprocessor manufacturers with regulatory infrastructure. The Île-de-France region's hospital consolidation drives centralized sterile supply department investments in automated washer-disinfector lines with remote monitoring subscriptions.
Global Hospital Acquired Infection Control Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in hospital infection control equipment supply. Capital equipment manufacturers with proprietary consumable lock-in dominate placement decisions in North American academic medical centers, while chemical formulation specialists compete on EPA registration speed and REACH biodegradability credentials. Two strategic archetypes define competitive positioning: integrated sterilization system providers bundling equipment with long-term service contracts, and modular point-of-use specialists enabling decentralized reprocessing workflows. M&A activity concentrates among sterilization equipment manufacturers acquiring regional service networks, while technology licensing partnerships proliferate between UV-C LED array developers and outpatient surgical center distributors.
Among integrated sterilization system providers, STERIS plc and Getinge AB exemplify the capital equipment archetype with established regulatory infrastructure and clinical engineering relationships. 3M Company occupies a distinct position within adhesive-based antimicrobial and personal protective equipment segments, leveraging FDA-cleared certification tiering to command premium positioning. These three entities represent the competitive spectrum from automated platform dominance to consumable volume leadership, with each archetype responding differently to ethylene oxide phase-down mandates and unbundled procurement trends.
| Leading Market Players |
|---|
| STERIS plc |
| 3M Company |
| Getinge AB |
| Ecolab Inc. |
| Becton, Dickinson and Company |
| Advanced Sterilization Products |
| Belimed Inc. |
| Cantel Medical |
| Sotera Health |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for ethylene oxide sterilization chambers concentrate pricing power among Gulf Coast petrochemical suppliers, while inventory buffers at German washer-disinfector manufacturers insulate against raw material volatility. This temporal asymmetry between consumable chemical flows and capital equipment cycles shapes margin capture across the hospital infection control value chain.
Pricing Analysis
Long-term service contracts dominate sterilization equipment procurement, with United States IDNs negotiating unbundled preventive maintenance subscriptions separate from capital sales. Price differentiation hinges on FDA 510(k) clearance tier and EPA Safer Choice certification status, with premium positioning reserved for systems validated to SAL 10^-6 microbial kill assurance. Cost compression in standard-tier chemical disinfectants intensifies as REACH biodegradability requirements force reformulation investments. Ambulatory surgical centers exhibit highest price sensitivity, while Japanese tertiary hospitals prioritize performance specifications over procurement cost.
Supply Chain Analysis
Gulf Coast ethylene oxide production clusters represent a critical chokepoint, with hurricane exposure and EU Green Deal phase-down mandates threatening sterilization modality continuity. Raw material flows draw from United States petrochemical corridors, German precision engineering centers, and Chinese UV-C LED component manufacturers. Single-source vulnerability concentrates in ethylene oxide sterilant gas supply, where three Gulf Coast facilities anchor global production. Distribution runs through group purchasing organizations for chemical consumables and direct clinical engineering channels for capital equipment placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat, where FDA 510(k) clinical data infrastructure and EPA registration timelines create switching costs that protect incumbent positioning across replacement cycles.
For Market Incumbents: Fortify proprietary consumable lock-in through hydrogen peroxide vapor chemistry patents as ethylene oxide phase-down accelerates. Expand technician certification program capacity to address IAHCSMM and CBSPD bottlenecks threatening automated line deployment. Vertical integration into UV-C LED array manufacturing secures component supply against Chinese export restrictions. For New Entrants and Emerging Players: Remote monitoring service gaps in legacy sterilization equipment create entry points for software-native competitors. Target India's tier-2 hospital expansion with compact point-of-use systems leveraging CDSCO streamlined registration. Pursue hospital system partnerships in Maharashtra and Gujarat requiring immediate instrument turnaround capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized sterilization divisions lacking healthcare-specific regulatory infrastructure. Long-term viability centers on modality transition exposure, with hydrogen peroxide vapor and ozone-based alternatives displacing ethylene oxide-dependent revenue streams. Monitor EU Green Deal enforcement velocity as inflection indicator for capital conversion timing.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Safer Choice Certification | Unlocks contract eligibility with sustainability-focused United States hospital systems pursuing green building credentials. |
| CE Marking Pathway under MDR | Enables European market access for reusable surgical instrument reprocessors facing Class IIa clinical evidence requirements. |
| Hospital System Partnership | Secures multi-year sterilization equipment placements through integrated delivery network procurement consolidation. |
| Software Companion Development | Captures recurring revenue via remote monitoring subscriptions unbundled from capital sale agreements. |
| Reimbursement Strategy | Aligns infection prevention program investments with Joint Commission accreditation standards and surgical site infection quality metrics. |
Methodological Framework
Initial hypotheses were tested against primary input from sterile processing technicians, hospital infection prevention officers, biomedical engineers, and group purchasing organization contract managers and refined through secondary validation. Sources included FDA 510(k) premarket notification databases, EPA FIFRA registration filings, EMA MDR submission records, hospital procurement contract repositories, and trade flow data from sterilization equipment customs declarations. Bottom-up demand modeling triangulated against top-down market sizing across product type, technology modality, and end-user facility categories.
Variance decomposition separated volume drivers from price evolution across the projection horizon. Segmentation dimensions modeled encompassed disinfectant chemistry class, sterilization equipment technology, thermal versus non-thermal modality, and facility scale tier. CAGRs were synthesized from replacement cycle analysis, regulatory mandate implementation schedules, and infrastructure renewal program funding trajectories. Forecast inputs incorporated METI-funded hospital modernization timelines and EU Green Deal enforcement phase-in assumptions.
Forecasts assume regulatory continuity in FDA 510(k) notification requirements and EMA MDR classification frameworks; material policy shifts would require re-modeling capital replacement assumptions. Ethylene oxide supply disruption scenarios and REACH concentration restriction acceleration represent specific revision triggers. Practitioners should keep alternative scenarios live as EU Green Deal implementation velocity and Japanese infrastructure renewal funding allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Surgical Site Infections Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Antimicrobial Suture Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Sterilization Equipment and Disinfectant Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Disinfection Cupboard Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Hand Hygiene Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market