
 Patient Hygiene Aids Market | 2026-2036
Patient Hygiene Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Hygiene Aids Market Analytics
Hospital procurement consortiums is rewriting distribution economics for patient hygiene aids. Kimberly-Clark Corporation leverages its direct-contract relationships with integrated delivery networks to sustain volume commitments across North American health systems. B. Braun Melsungen anchors European hospital supply through specialized infection control portfolios that compete on clinical validation rather than commodity pricing.
Patient hygiene aids encompass single-use and limited-use products engineered for cleansing, disinfection, and comfort maintenance in clinical and home care settings, typically manufactured from nonwoven substrates, thermoformed plastics, or cellulose blends with specified fluid retention capacities and bioburden thresholds. Wet wipes formulated with quaternary ammonium compounds dominate infection control applications in hospitals, while bedpan liners fabricated from biodegradable polymers represent the fastest-growing material segment as long-term care facilities phase out conventional plastics. Soap dispensers with touchless sensor activation occupy mature, price-competitive territory where margin pools concentrate in refill cartridge contracts rather than hardware sales.
The FDA regulates antimicrobial hygiene claims under pesticide and medical device frameworks, while the EU MDR and REACH impose substance restriction and clinical evidence requirements on products marketed for infection prevention in European healthcare settings. In the United States, EPA registration requirements for surface disinfectants create compliance barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving green procurement mandates in Germany and California, where public health systems are embedding lifecycle assessment criteria into supplier qualification protocols.
Market Dynamics
Hospital procurement consortiums are consolidating purchasing power across integrated delivery networks, forcing manufacturers to abandon traditional distributor relationships in favor of direct-contract volume commitments with price transparency clauses.
Growth Catalysts
- EU Medical Device Regulation (MDR):Clinical evidence requirements for infection prevention claims are elevating product validation standards, advantaging manufacturers with dedicated regulatory infrastructure and accelerating hospital procurement of certified antimicrobial hygiene aids.
- Biodegradable polymer innovation:Long-term care facilities in Germany and Japan are expanding procurement of bedpan liners and disposable washcloths fabricated from compostable materials to meet phased plastic reduction mandates.
- Hospital-acquired infection protocols:Bulk purchasing of quaternary ammonium compound wet wipes is concentrating in United States health systems as CMS reimbursement penalties for preventable infections tighten compliance timelines.
Market Restraints
- Cellulose pulp input volatility:Fluctuating softwood pulp prices from Nordic and Brazilian suppliers compress margin pools for nonwoven substrate manufacturers serving the disposable washcloth segment.
- EPA registration barriers:Surface disinfectant compliance timelines extending 18-24 months create structural moats favoring established players with dedicated regulatory affairs teams over emerging entrants.
- Reusable textile substitution:Industrial laundry services for washable patient gowns and bath towels are reclaiming share in cost-constrained European long-term care facilities where capital budgets prioritize equipment over consumables.
Strategic Opportunities
- Home care channel expansion:Direct-to-consumer subscription models for antimicrobial wet wipe assortments are penetrating post-acute patient populations in the United States where insurance reimbursement for home health supplies creates predictable recurring revenue streams.
- California green procurement mandates:Senate Bill 54 implementation is embedding lifecycle assessment criteria into Medi-Cal supplier qualification protocols, creating first-mover advantage for biodegradable material innovators.
- Sensor-activated dispenser convergence:Integration of IoT-enabled soap and sanitizer dispensers with electronic health record systems is enabling usage analytics contracts that displace hardware sales with per-patient-day service fees.
Industry Challenges
- Microbiological validation talent scarcity:Clinical testing laboratories face capacity constraints for bioburden threshold certification required under EU MDR Annex I general safety and performance requirements.
- Legacy dispenser infrastructure retrofit costs:Long-term care facilities must reconcile capital expenditure for touchless sensor hardware against existing manual dispenser depreciation schedules.
- REACH substance restriction compliance:Ongoing ECHA evaluations of quaternary ammonium compound environmental toxicity are forcing reformulation investments ahead of confirmed regulatory action.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Hygiene Aids Market |
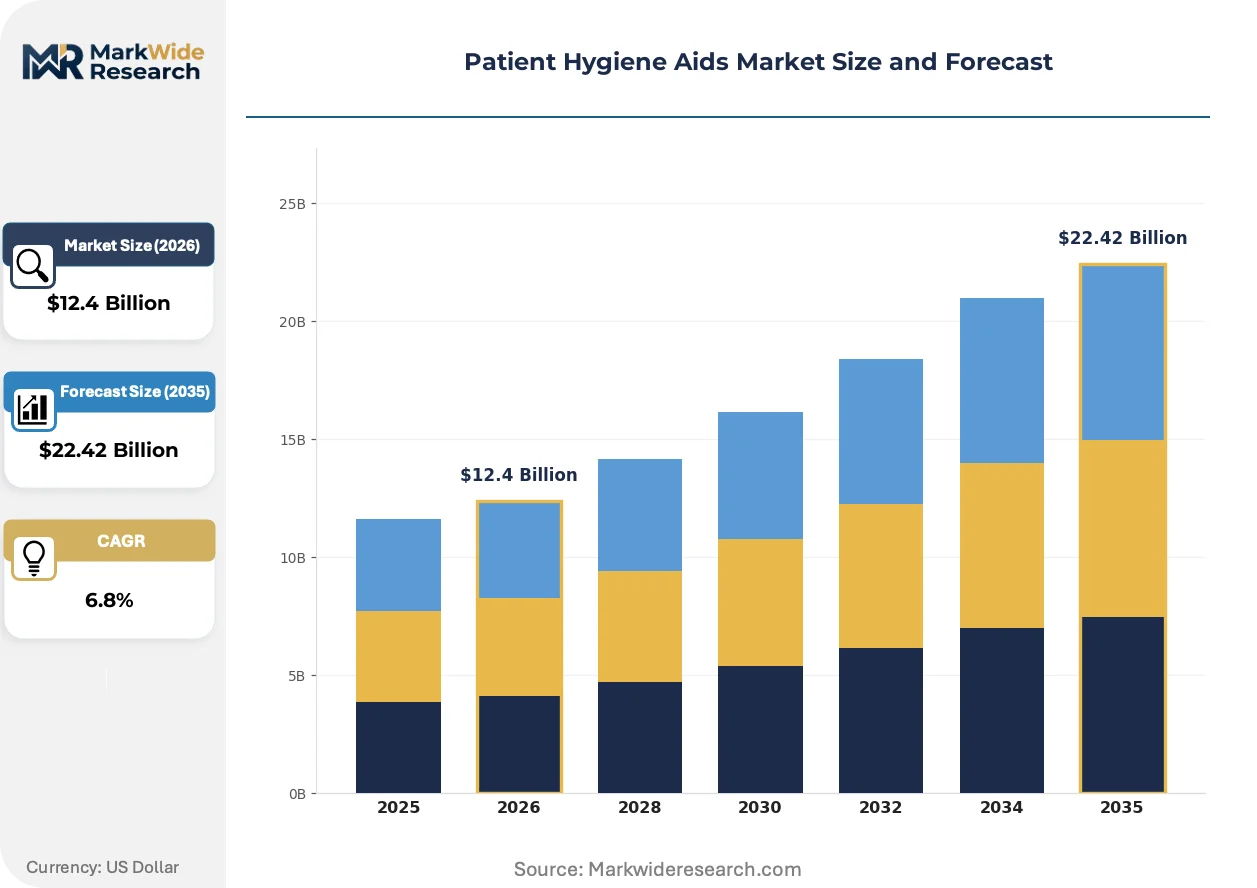
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Wipes, Antimicrobial Sprays, Soap Dispensers, Bedpan Liners End User: Hospitals, Long-Term Care Facilities, Home Care Providers, Rehabilitation Centers Material: Nonwoven Fabric, Plastic, Paper, Biodegradable Material Application: Personal Care, Infection Control, Patient Comfort, Mobility Assistance |
| Companies Covered | Unilever, Colgate-Palmolive Company, 3M, Kimberly-Clark Corporation, B. Braun Melsungen, Johnson & Johnson, P&G, Reckitt Benckiser Group, HARTMANN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Hygiene Aids Market Evolving Landscape
Digital inventory management and connected hygiene infrastructure are displacing manual replenishment cycles, while regulatory pressure on chemical formulations accelerates material science investment.
Antimicrobial coating deposition via atmospheric plasma treatment is virtualizing traditional dip-and-cure manufacturing for nonwoven patient washcloths. United States hospital systems with centralized sterile processing departments are piloting these substrates for surgical prep applications. The technology is virtualizing batch-based quality control into continuous in-line monitoring, compressing defect detection timelines from hours to seconds.
REACH substance restriction evaluations under ECHA's 2024-2026 rolling action plan are forcing reformulation of quaternary ammonium compound wet wipes ahead of confirmed hazard classification. Manufacturers with European manufacturing footprints are accelerating partnerships with bio-based surfactant suppliers to secure alternative active ingredient pipelines. Infection control product portfolios marketed for clinical validation rather than commodity pricing face the steepest compliance cost trajectories.
Consolidated procurement through integrated delivery network direct contracts is fragmenting traditional distributor relationships that historically captured 25-35 point margins on patient hygiene aids. Group purchasing organizations in the United States are unbundling infection control product categories from broadline medical-surgical contracts, enabling specialty manufacturers to compete on clinical evidence rather than rebate structures. This disintermediation is most visible in academic medical centers with dedicated value analysis committees.
Patient Hygiene Aids Market Segmentation
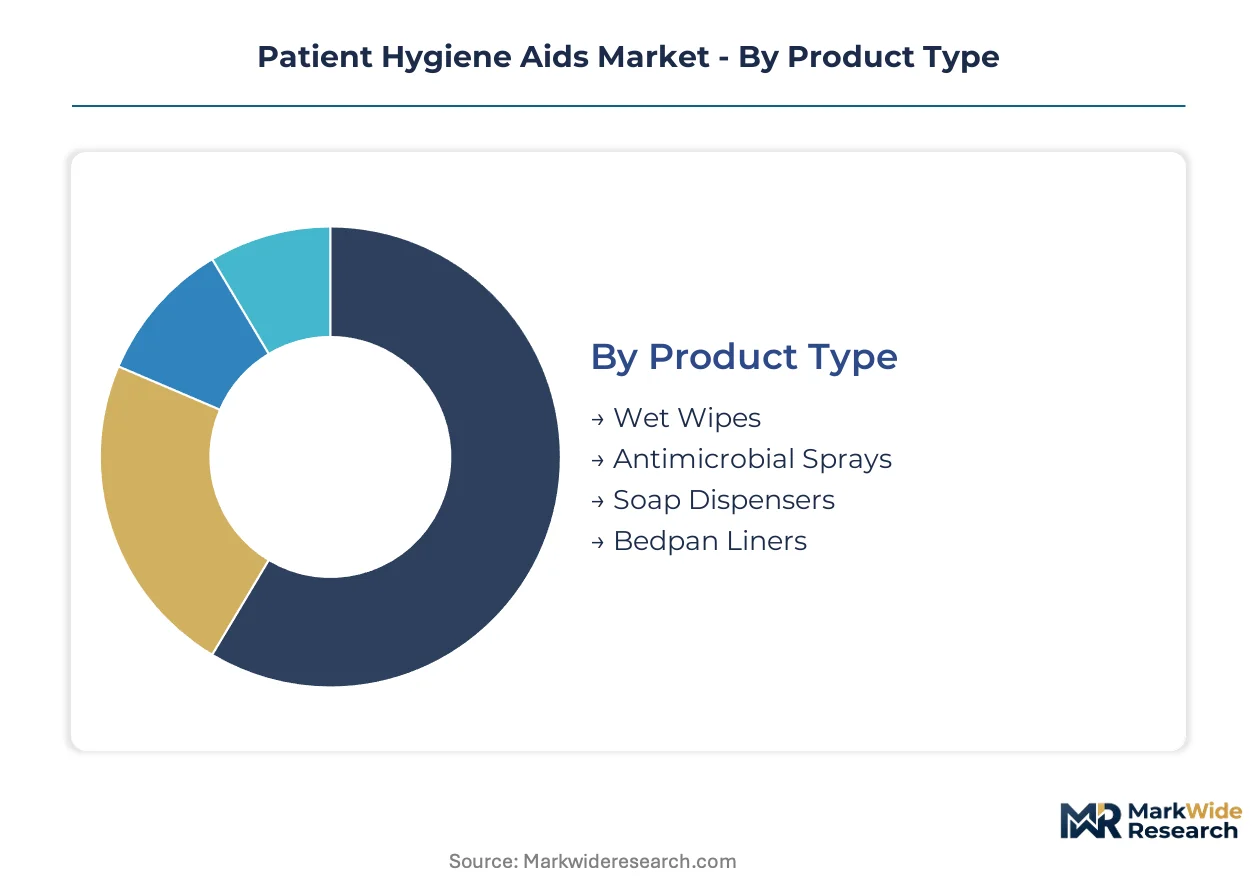
Patient hygiene aids span diverse clinical and non-clinical use cases where material composition, regulatory compliance, and end-user procurement power fragment competitive dynamics. Understanding segment boundaries reveals where formulation investments concentrate and which distribution channels command premium positioning.
Product Type:
Use-case spectrum spans acute infection prevention protocols through chronic care waste management, with each product category serving distinct clinical workflows and capital expenditure cycles.
- Wet Wipes:Nonwoven substrates saturated with quaternary ammonium compounds or alcohol solutions, engineered for bioburden reduction per EPA registration standards. Demand concentrates in United States hospital systems where CMS reimbursement penalties for preventable infections mandate bulk procurement of validated antimicrobial formats.
- Bedpan Liners:Thermoformed or film-based receptacle inserts fabricated from biodegradable polymers or conventional plastics, designed for single-use containment and odor sealing. Long-term care facilities in Germany and Japan are expanding procurement of compostable variants ahead of phased plastic reduction mandates.
- Antimicrobial Sprays:Aqueous or aerosolized formulations for surface disinfection between patient contact events.
- Soap Dispensers:Touchless sensor-activated or manual pump hardware with refill cartridge systems, occupying mature price-competitive territory where margin pools concentrate in consumable contracts rather than capital equipment sales.
The dominant share belongs to Wet Wipes, while Bedpan Liners is closing the gap fastest.
End User:
Procurement authority and reimbursement pathways diverge sharply across institutional settings, shaping volume commitment structures and clinical validation requirements.
- Hospitals:Integrated delivery networks with centralized sterile processing departments and value analysis committees. United States academic medical centers unbundle infection control categories from broadline contracts, enabling specialty manufacturers to compete on EPA-registered clinical evidence rather than rebate structures.
- Long-Term Care Facilities:Capital-constrained operators balancing equipment depreciation schedules against consumable recurring costs. Industrial laundry services for reusable textiles are reclaiming share in European facilities where budgets prioritize washer-extractor investments over disposable procurement.
- Home Care Providers:Post-acute and hospice agencies serving dispersed patient populations with insurance-reimbursed supply protocols.
- Rehabilitation Centers:Skilled nursing and physical therapy settings with intermediate acuity levels and mixed reusable-disposable hygiene workflows.
Hospitals command the largest procurement volumes, though Long-Term Care Facilities are expanding most quickly as aging demographics shift care settings.
Material:
Substrate selection determines regulatory pathway, end-of-life disposal cost, and fluid retention performance specifications across clinical applications.
- Nonwoven Fabric:Spunbond-meltblown-spunbond or airlaid cellulose structures with specified tensile strength and liquid absorption capacity. Atmospheric plasma treatment is virtualizing traditional dip-and-cure manufacturing, enabling continuous in-line quality monitoring that compresses defect detection timelines.
- Biodegradable Material:Polylactic acid, polyhydroxyalkanoate, or cellulose-derived films and fibers engineered for compostable disposal. California Senate Bill 54 implementation is embedding lifecycle assessment criteria into Medi-Cal supplier qualification protocols, creating first-mover positioning for material innovators.
- Plastic:Conventional polypropylene or polyethylene thermoformed components facing substitution pressure from green procurement mandates.
- Paper:Cellulose pulp-based substrates subject to Nordic and Brazilian softwood price volatility that compresses margin pools for disposable washcloth manufacturers.
Nonwoven Fabric retains the dominant position, while Biodegradable Material is gaining share fastest on regulatory tailwinds.
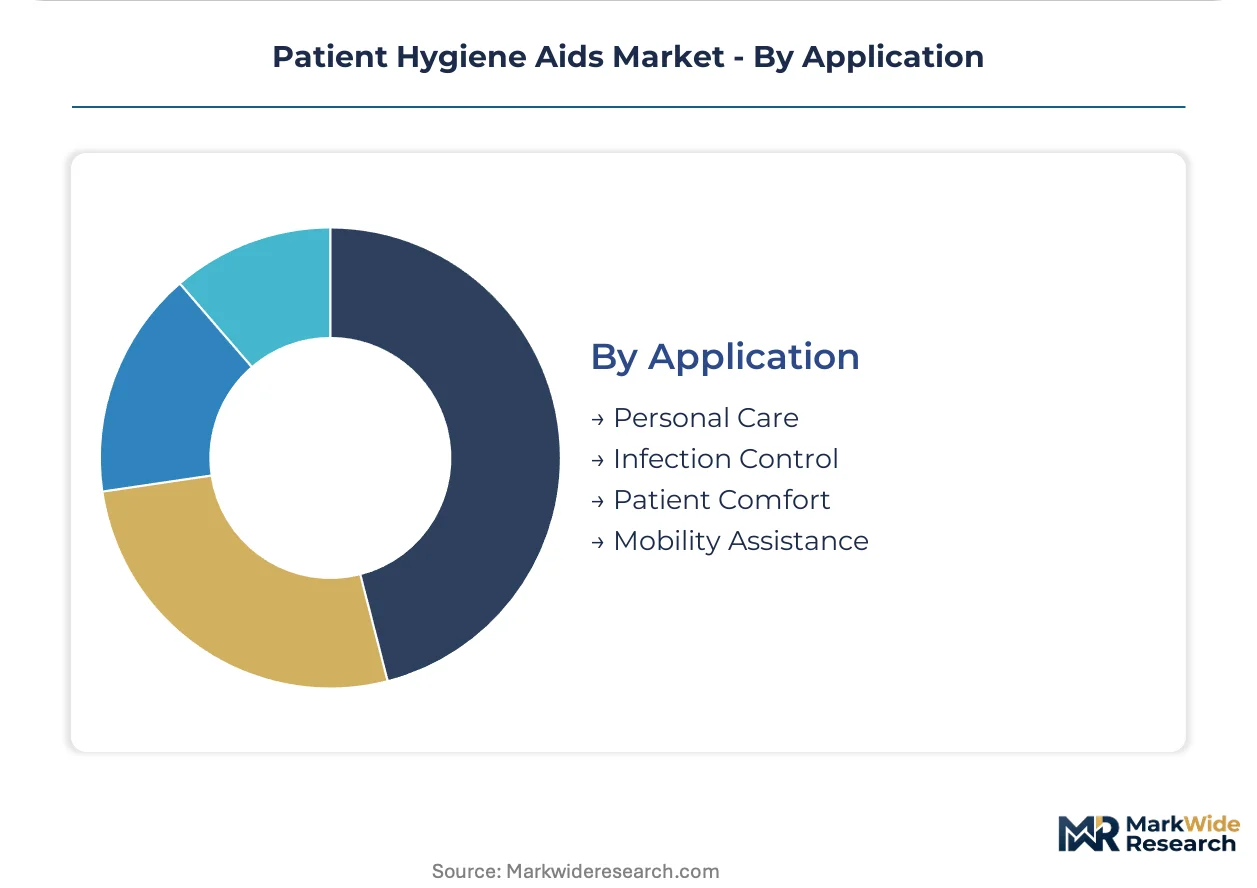
Application:
Functional purpose determines active ingredient selection, bioburden threshold requirements, and integration with electronic health record workflows.
- Infection Control:EPA-registered surface disinfectants and antimicrobial hand hygiene products subject to clinical evidence requirements under EU MDR Annex I general safety and performance specifications. REACH substance restriction evaluations are forcing reformulation investments ahead of confirmed quaternary ammonium compound hazard classification.
- Patient Comfort:Cleansing and moisture management products where skin integrity and dermatological safety drive formulation priorities.
- Personal Care:Routine bathing, oral hygiene, and grooming aids for dependent patients across institutional and home settings.
- Mobility Assistance:Products supporting patient transfer, positioning, and hygiene maintenance during movement.
Infection Control captures the dominant share, while Patient Comfort is climbing the fastest as pressure injury prevention protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA infection control mandates anchor procurement intensity in the United States, while EU MDR clinical evidence requirements and Japan's aged-care infrastructure investments reshape competitive positioning across developed markets. Demand concentrates in health systems with reimbursement penalties for preventable infections and long-term care facilities facing plastic reduction deadlines.
United States
CMS hospital-acquired condition reduction programs and EPA-registered disinfectant procurement protocols drive bulk purchasing of antimicrobial wet wipes across integrated delivery networks. The FDA regulates antimicrobial claims under overlapping pesticide and medical device frameworks. Academic medical centers in Boston and the Research Triangle unbundle infection control categories from broadline contracts, enabling specialty manufacturers to compete on clinical validation.
Germany
Long-term care operators in North Rhine-Westphalia and Bavaria expand procurement of biodegradable bedpan liners ahead of national plastic reduction mandates. The EU MDR elevates clinical evidence requirements for infection prevention claims, advantaging manufacturers with dedicated regulatory infrastructure. Industrial clusters around Hamburg and Frankfurt host sterile processing equipment manufacturers piloting atmospheric plasma treatment for nonwoven substrates.
Japan
METI-guided aged-care infrastructure investments accelerate procurement of sensor-activated hygiene dispensers in Tokyo and Osaka metropolitan facilities. The PMDA oversees medical device classification for products marketed with antimicrobial efficacy claims. Long-term care operators in Kansai phase out conventional plastics through compostable polymer adoption aligned with municipal waste reduction targets.
United Kingdom
NHS Supply Chain consolidation drives standardized procurement of patient hygiene aids across England's integrated care systems. The MHRA enforces EU MDR-aligned clinical evidence requirements post-Brexit transition. Manufacturing concentration in the Midlands and Yorkshire supports domestic nonwoven substrate production for disposable washcloth supply.
India
CDSCO medical device registration requirements and expanding private hospital networks in Maharashtra and Karnataka drive demand for imported infection control formats. Industrial clusters around Ahmedabad and Chennai develop domestic nonwoven manufacturing capacity for cost-competitive disposable hygiene products. State-level healthcare infrastructure programs in Gujarat and Tamil Nadu prioritize bulk procurement of single-use patient comfort items.
Patient Hygiene Aids Market Competitive Landscape
Diversified consumer health conglomerates and specialized medical device manufacturers split the market across institutional and retail channels. Consolidated procurement through integrated delivery networks favors players with direct-contract capabilities and dedicated regulatory affairs infrastructure. Three archetypes dominate: scale-driven hygiene conglomerates with broad infection control portfolios, mid-cap specialists in biodegradable material formats, and regional fabricators serving cost-constrained long-term care markets. Competitive moves concentrate on M&A for regulatory infrastructure and partnerships with bio-based surfactant suppliers.
Within the scale-driven tier, Unilever and Colgate-Palmolive exemplify consumer health conglomerates leveraging retail distribution infrastructure into institutional channels. Among specialized medical device manufacturers, B. Braun Melsungen occupies a position anchored in European hospital supply relationships, while Kimberly-Clark Corporation represents North American health system direct-contract capabilities. These three entities sit within distinct competitive vectors: retail-to-institutional crossover, clinical validation specialization, and integrated delivery network volume commitment respectively.
| Leading Market Players |
|---|
| Unilever |
| Colgate-Palmolive Company |
| 3M |
| Kimberly-Clark Corporation |
| B. Braun Melsungen |
| Johnson & Johnson |
| P&G |
| Reckitt Benckiser Group |
| HARTMANN |
| Others |
Value Network & Pricing Analysis
Nordic softwood pulp clusters around Gothenburg and Tampere feed nonwoven substrate capacity that compresses margin pools for disposable washcloth manufacturers when input costs spike. Hospital procurement consortiums exploit this concentration to extract price transparency clauses from suppliers, while biodegradable polymer innovators in Hamburg and Osaka command premiums ahead of phased plastic mandates.
Pricing Analysis
Price spreads between United States academic medical centers and European long-term care facilities exceed 40 percent for equivalent antimicrobial wet wipe formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by EPA registration tier and clinical validation depth, with infection control portfolios bearing the steepest compliance cost trajectories. Cost compression in the standard tier intensifies because industrial laundry services reclaim share in budget-constrained facilities. Long-term care operators in Germany and Japan exhibit highest price sensitivity, while United States integrated delivery networks prioritize clinical evidence over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days strain working capital for nonwoven substrate manufacturers serving distributor-dependent long-term care channels. Supply concentrates in Sweden, Finland, and Brazil for cellulose pulp; China and Germany for thermoformed plastics; and Japan for sensor-activated dispenser electronics. Raw material dependencies span Nordic softwood pulp, quaternary ammonium compound surfactants, and polylactic acid biopolymers. Single-source vulnerability concentrates in Brazilian pulp supply during harvest volatility periods. Distribution runs through integrated delivery network direct contracts that disintermediate traditional medical-surgical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
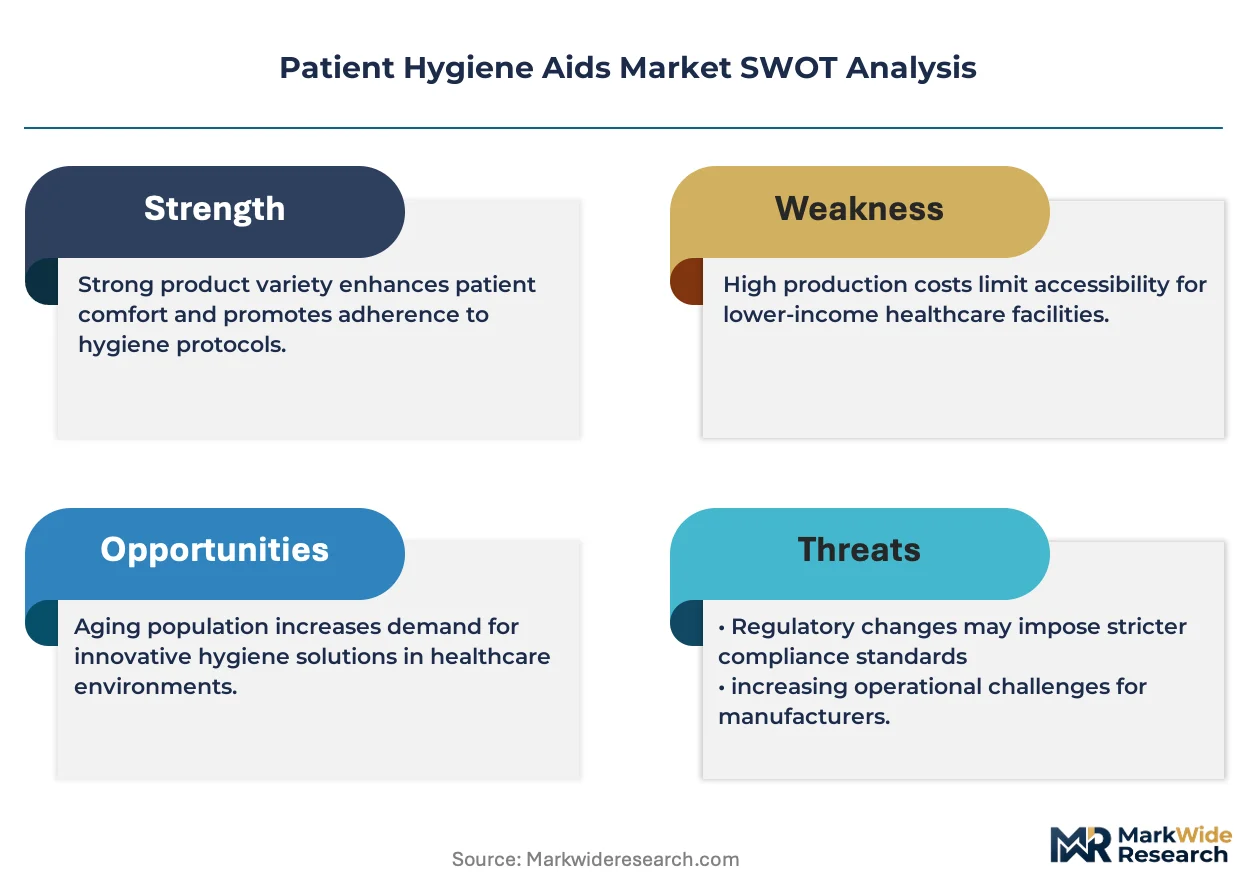
Reusable textile services and industrial laundry equipment represent a credible substitute threat that disposable hygiene incumbents must neutralize through clinical validation investments.
For Market Incumbents: Entrench infection control portfolios with EPA-registered clinical evidence that reusable alternatives cannot replicate. Secure backward integration into nonwoven substrate production to buffer Nordic pulp price volatility. Deepen direct-contract relationships with United States academic medical centers where value analysis committees unbundle categories from broadline rebates. For New Entrants and Emerging Players: Establish a beachhead in California's Medi-Cal supplier qualification protocols by embedding lifecycle assessment criteria into biodegradable bedpan liner formats. Target home care subscription channels where insurance reimbursement creates predictable recurring revenue streams. Lead with sensor-activated dispenser IoT integration contracts that displace hardware sales with per-patient-day service fees. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory infrastructure play because EU MDR clinical evidence requirements and EPA registration barriers create structural moats favoring established players with dedicated compliance teams. Acquisition targets should display microbiological validation laboratory partnerships and bio-based surfactant supplier relationships. Watch ECHA rolling action plan evaluations of quaternary ammonium compound toxicity as an inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Clinical evidence investments under EU MDR Annex I secure hospital procurement preference in Germany and France. |
| Biodegradable Material Scale-Up | Polylactic acid and polyhydroxyalkanoate capacity expansion captures California Senate Bill 54 procurement mandates. |
| Hospital System Direct Contract | Integrated delivery network volume commitments displace distributor margins and lock in multi-year supply agreements. |
| IoT Dispenser Integration | Electronic health record connectivity enables usage analytics contracts that transform hardware sales into recurring service revenue. |
| Regulatory Affairs Infrastructure | Dedicated EPA and ECHA compliance teams compress registration timelines and exclude capital-constrained entrants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA registration databases, EU MDR notified body guidance, and hospital procurement contract disclosures. Interviews with sterile processing directors, GPO contracts managers, biomedical engineers, and long-term care procurement officers informed demand-side validation. Customs trade data for cellulose pulp and nonwoven fabric imports, SEC filings from diversified hygiene conglomerates, and CMS Medicare cost report data supplied quantitative anchors. Bottom-up patient-day consumption modeling and top-down health system expenditure analysis triangulated market sizing.
Forecast inputs incorporate infection control protocol adoption curves, plastic reduction mandate implementation schedules, and reimbursement penalty expansion trajectories across the analysis window. Segmentation dimensions span product type, end-user procurement authority, material substrate, and application functional purpose. CAGRs derive from logarithmic trend fitting of historical consumption patterns adjusted for regulatory inflection points. Industry-specific inputs include CMS hospital-acquired condition penalty schedules and ECHA substance restriction evaluation timelines.
Sensitivities concentrate around pulp price volatility, REACH quaternary ammonium compound reclassification, and reusable textile service market reclamation rates. Forecasts embed assumptions regarding procurement consortium consolidation velocity and biodegradable material cost parity achievement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Antimicrobial Suture Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Preventable Vaccines Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Disinfection Equipment Market
Infection Control
Infection Control Supplies Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Medical Washer Disinfector Market
Infection Control
Sanitizers Market
Infection Control
North America Hand Sanitizer Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Sterilization Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Yeast Infection Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Global Viral Inactivation Market