
 Botulism Market | 2026-2036
Botulism Market Size, Share, and Industry Trends Forecast 2026-2036
Botulism Market Analysis
North American biomanufacturing capacity is reshaping supply security for botulinum antitoxin products. Emergent BioSolutions leverages its government contracting relationships to anchor domestic heptavalent antitoxin production. Allergan (AbbVie) sustains leadership in therapeutic botulinum toxin through specialized purification processes. Ipsen Pharma competes in neurological indications with differentiated formulation technology.
Botulism refers to a rare but life-threatening neuroparalytic condition caused by botulinum toxin, a zinc metalloprotease produced by Clostridium botulinum that blocks acetylcholine release at neuromuscular junctions, requiring prompt antitoxin administration to prevent respiratory failure. The condition serves both critical public health response functions and commercial therapeutic applications in movement disorders and aesthetics. Antitoxin Therapy dominates the Treatment Type segment due to its established efficacy in neutralizing circulating toxin before neuronal uptake. Infant Botulism leads the Therapy Area category, reflecting higher case recognition rates and dedicated pediatric hospital protocols. Distribution through Hospitals captures the majority of value, given the emergency nature of clinical presentation and cold-chain requirements for biological products.
FDA oversight through the Center for Biologics Evaluation and Research governs antitoxin licensing and lot release testing, while EMA's Committee for Medicinal Products for Human Use coordinates centralized marketing authorizations across EU member states. WHO prequalification pathways shape procurement decisions for national stockpiles in emerging economies. Stakeholders must monitor regulatory harmonization efforts between FDA and EMA for biosimilar antitoxin pathways, as divergence in immunogenicity standards could fragment market access.
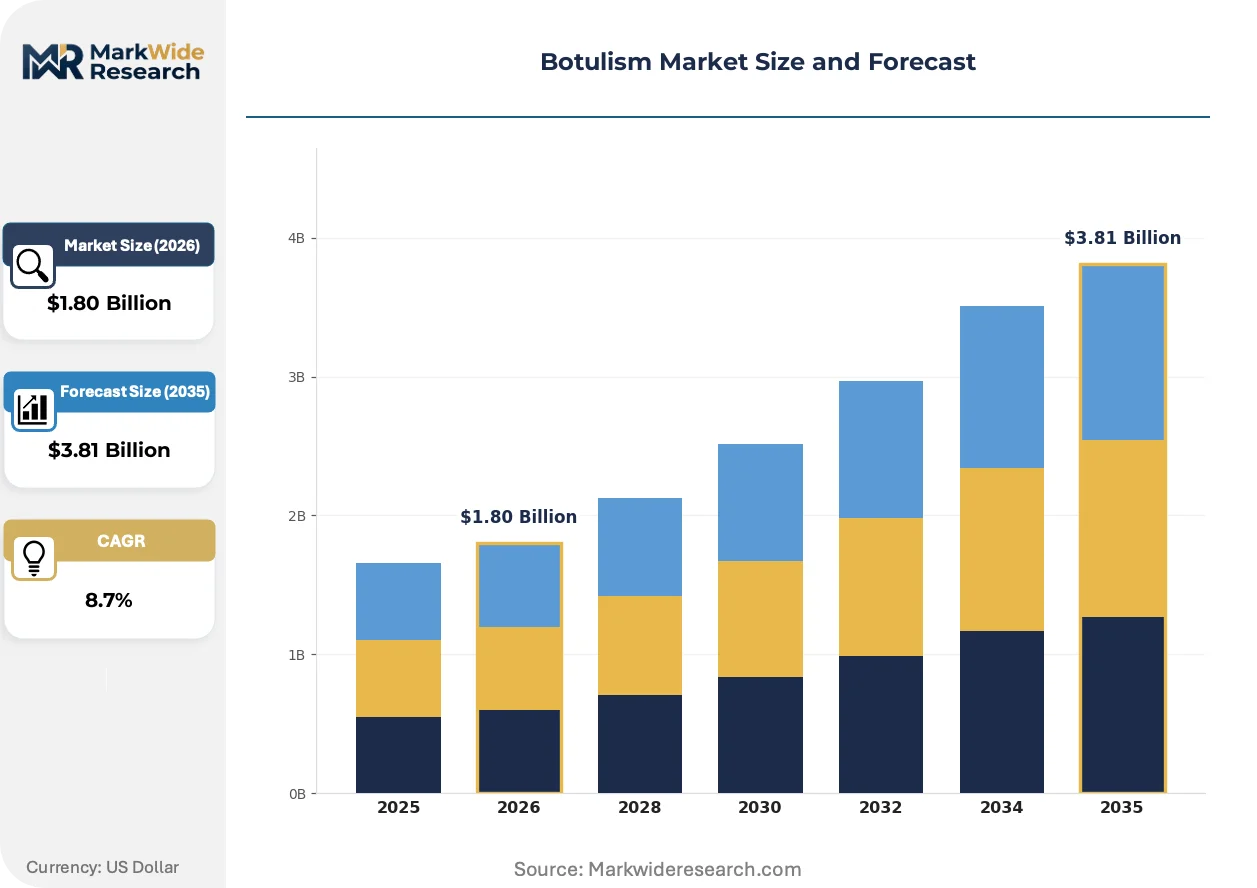
Market Dynamics
Domestic biomanufacturing concentration is reshaping procurement security for botulinum antitoxin products, with government stockpile mandates forcing geographic diversification of heptavalent production capacity.
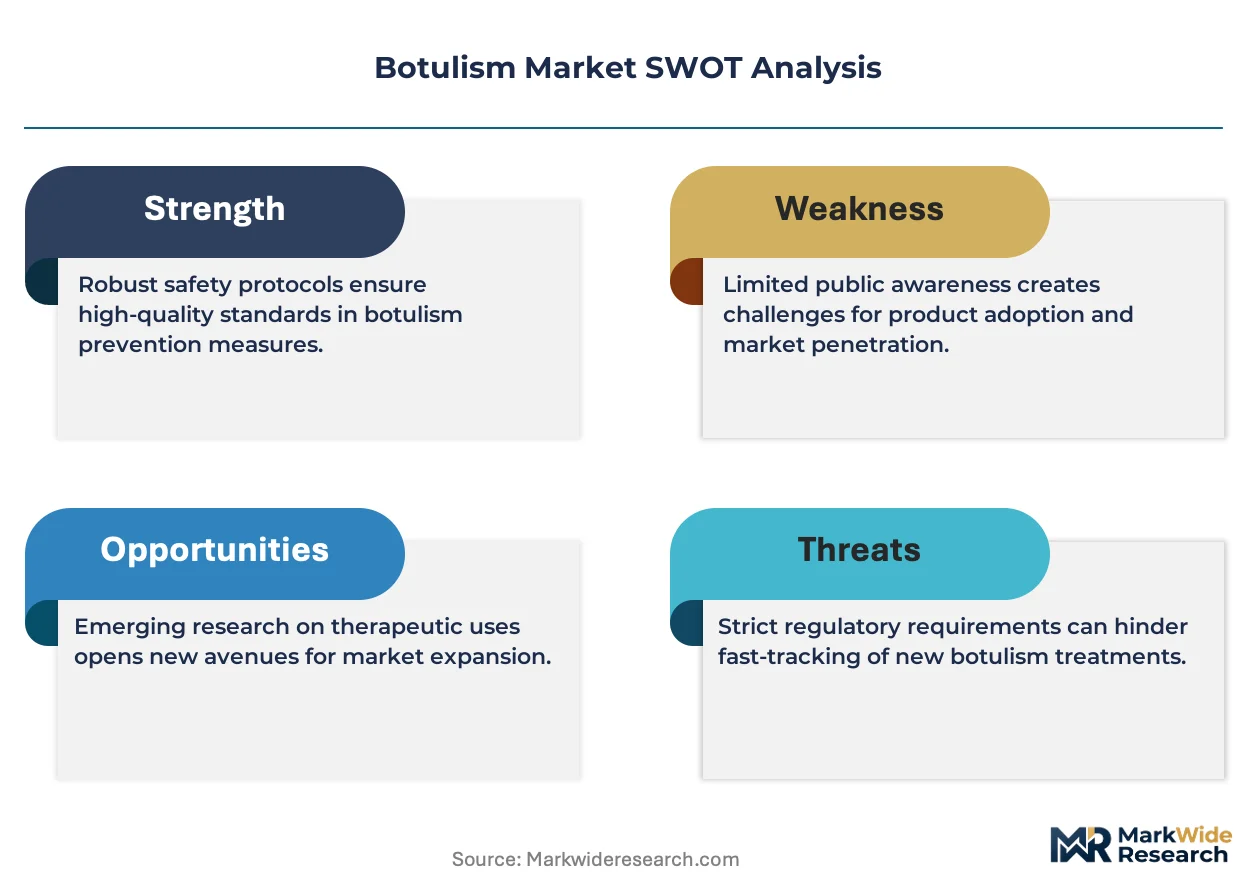
Growth Catalysts
- BARDA Strategic National Stockpile contracts:US federal procurement guarantees anchor demand for emergency antitoxin reserves, creating predictable offtake for domestic manufacturers.
- Pediatric hospital protocol standardization:Dedicated infant botulism treatment centers are expanding recognition and rapid diagnostic pathways across tertiary care networks.
- Cosmetic toxin formulation advances:Purification process improvements are opening therapeutic expansion into chronic migraine and spasticity indications.
Market Restraints
- Equine plasma supply concentration:Antitoxin production depends on specialized horse farm networks in limited geographic zones, exposing supply to animal health disruptions.
- Cold-chain biological handling costs:Temperature-controlled distribution from manufacturing through hospital pharmacy adds 15-25% to delivered product cost.
- Recombinant antibody platform substitution:Fully human monoclonal development programs threaten long-term equine-derived antitoxin market position.
Strategic Opportunities
- India national stockpile formation:CDSCO biologics pathway maturation enables WHO prequalification pursuit for emerging economy procurement.
- Pre-hospital antitoxin administration:Emergency medical services protocols are expanding point-of-care delivery before hospital transfer.
- Japan PMDA orphan drug incentives:Designation pathways for rare disease biologics reduce regulatory timeline and fee burdens for novel formulations.
Industry Challenges
- Specialized immunoglobulin manufacturing talent:Equine hyperimmunization and plasma fractionation expertise concentrates in aging workforce pools.
- Lot release testing timeline compression:FDA Center for Biologics Evaluation and Research potency assays create 6-12 month approval bottlenecks between production and distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botulism Market |
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Infant Botulism, Wound Botulism, Foodborne Botulism, Adult Intestinal Colonization Treatment Type: Antitoxin Therapy, Surgical Intervention, Supportive Care, Antibiotics Distribution Channel: Hospitals, Pharmacies, Online Platforms, Clinics End User: Healthcare Providers, Research Institutions, Pharmaceutical Companies, Emergency Services |
| Companies Covered | Emergent BioSolutions, XOMA Corporation, Allergan (AbbVie), Ipsen Pharma, Merz Pharma, Molecular Targeting Technologies, Microbiotix, AlphaVax, Morphotek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botulism Market Emerging Trajectories
Recombinant expression systems and point-of-care diagnostics are converging to compress traditional antitoxin development and deployment timelines. These shifts promise to reshape both therapeutic and emergency response applications.
Recombinant DNA platforms are collapsing the equine dependency that has dominated antitoxin production for decades. Fully human monoclonal antibody candidates from academic medical centers are advancing through Phase II trials. This transition is collapsing the 12-18 month production cycles required for hyperimmune plasma collection into 8-12 week bioreactor batch timelines.
EMA's Committee for Orphan Medicinal Products has streamlined pediatric indication extensions for existing antitoxin licenses. Reduced clinical data requirements for well-characterized biologics are accelerating supplemental approvals. European reference laboratory networks are responding with harmonized potency standards to support centralized procurement.
Hospital consortium purchasing is consolidating antitoxin procurement decisions into regionalized pharmacy and therapeutics committees. Group purchasing organizations are displacing individual hospital emergency department buying patterns. This concentration is most visible across US health system networks where formulary standardization reduces vendor fragmentation.
Botulism Market Segmentation
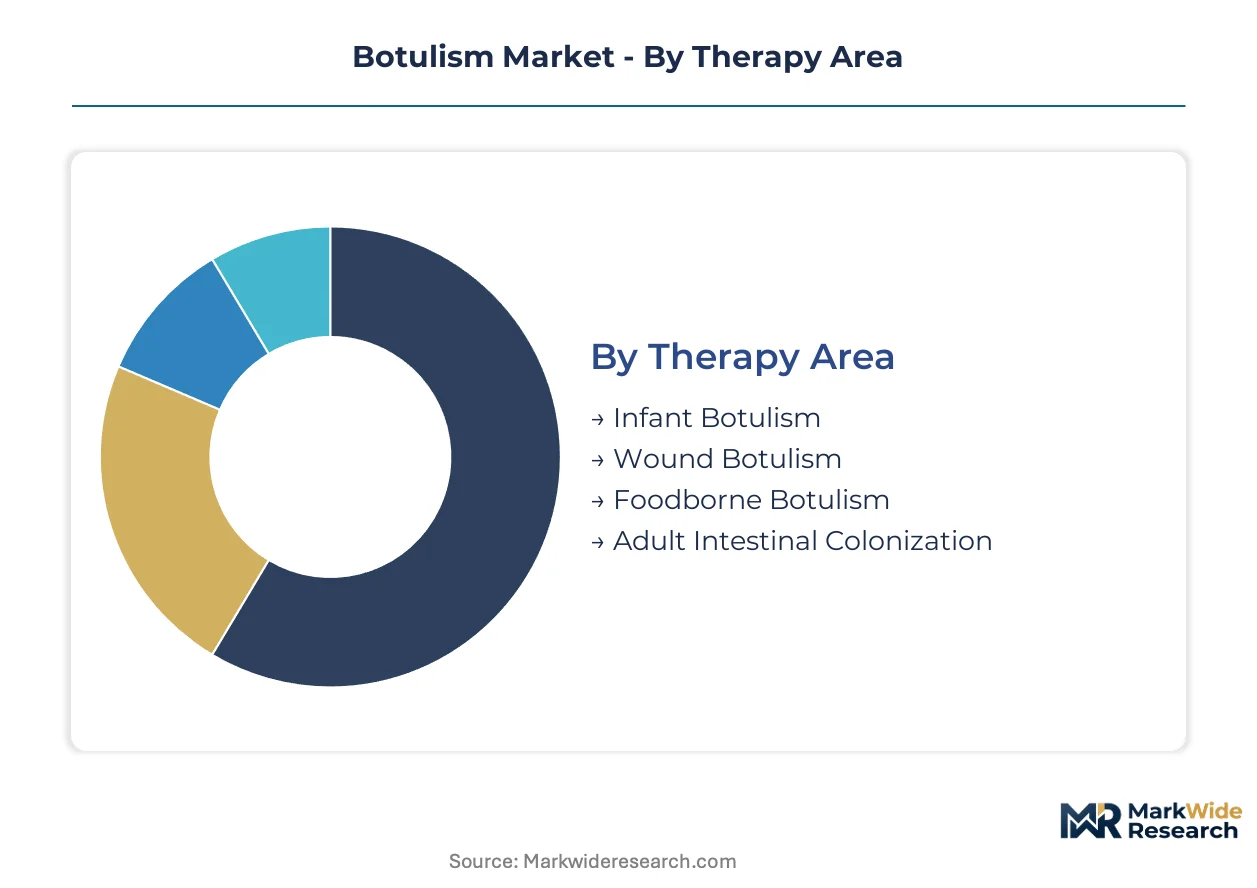
Botulism market segmentation reveals how clinical urgency, biological handling requirements, and procurement authority concentrate value across distinct channels. Each dimension exposes different margin structures and regulatory touchpoints that shape competitive positioning.
Therapy Area:
After-sales service intensity varies sharply across patient populations, with infant cases demanding dedicated pediatric ICU coordination and wound cases requiring surgical follow-through.
- Infant Botulism:Affects infants under 12 months through intestinal colonization by C. botulinum spores, producing toxin that causes floppy baby syndrome and respiratory compromise. Demand concentrates in tertiary pediatric centers across California, Texas, and Pennsylvania where dedicated treatment protocols and rapid diagnostic pathways have reduced time-to-antitoxin administration. Hospital networks with specialized neonatal intensive care units anchor procurement volume for this segment.
- Wound Botulism:Results from toxin production in contaminated traumatic or injection-related wounds, particularly among persons who inject drugs. Emergency departments in urban corridors with high opioid use disorder prevalence—Baltimore, Philadelphia, and Seattle clusters—drive recognition and antitoxin deployment. CDC surveillance networks track geographic hotspots to pre-position stockpiles.
- Foodborne Botulism:Classic intoxication from preformed toxin in improperly preserved foods, requiring immediate antitoxin plus public health investigation.
- Adult Intestinal Colonization:Rare form mimicking infant botulism in adults with altered gut flora, typically following antibiotic therapy or gastrointestinal surgery.
Infant Botulism holds the largest share; momentum sits with Wound Botulism as injection drug use patterns shift geographically.
Treatment Type:
Cost tier stratification separates biological antitoxins from procedural and pharmaceutical alternatives, with reimbursement complexity scaling inversely with therapeutic specificity.
- Antitoxin Therapy:Equine-derived heptavalent antitoxin and human-derived BabyBIG represent the only disease-specific interventions, neutralizing circulating toxin before neuronal uptake. BARDA stockpile contracts and pediatric hospital formulary standardization create predictable offtake for domestic manufacturers. Cold-chain requirements and lot release testing timelines constrain supply elasticity.
- Surgical Intervention:Wound debridement and source control for wound botulism, performed in operating suites with infectious disease consultation. Academic medical centers with trauma designation capture the procedural volume, particularly in regions with climbing injection drug use rates.
- Supportive Care:Mechanical ventilation and intensive monitoring constitute the backbone of management for all forms, consuming ICU bed-days and respiratory therapist capacity.
- Antibiotics:Adjunctive therapy for wound botulism to address polymicrobial infection, with metronidazole and penicillin G dominating empirical protocols.
Antitoxin Therapy commands premium pricing; Supportive Care represents the volume base across all clinical presentations.
Distribution Channel:
Geographic proximity to emergency response infrastructure determines channel viability, with biological product stability windows favoring direct hospital delivery over intermediated routes.
- Hospitals:Emergency departments and pharmacy departments manage antitoxin procurement through CDC release protocols and stockpile draw-down agreements. Group purchasing organizations consolidate buying power across health system networks, displacing individual hospital negotiations.
- Pharmacies:Retail and specialty pharmacy channels handle outpatient botulinum toxin preparations for therapeutic indications—chronic migraine, spasticity, cervical dystonia—where maintenance dosing creates recurring prescription volume.
- Online Platforms:Emerging channel for patient education and telemedicine triage, directing suspected cases to appropriate emergency facilities rather than direct product distribution.
- Clinics:Outpatient neurology and movement disorder clinics administer therapeutic toxin formulations, with cosmetic applications concentrating in dermatology and plastic surgery practices.
Hospitals dominate emergency antitoxin distribution; Clinics are climbing fastest on therapeutic toxin expansion.
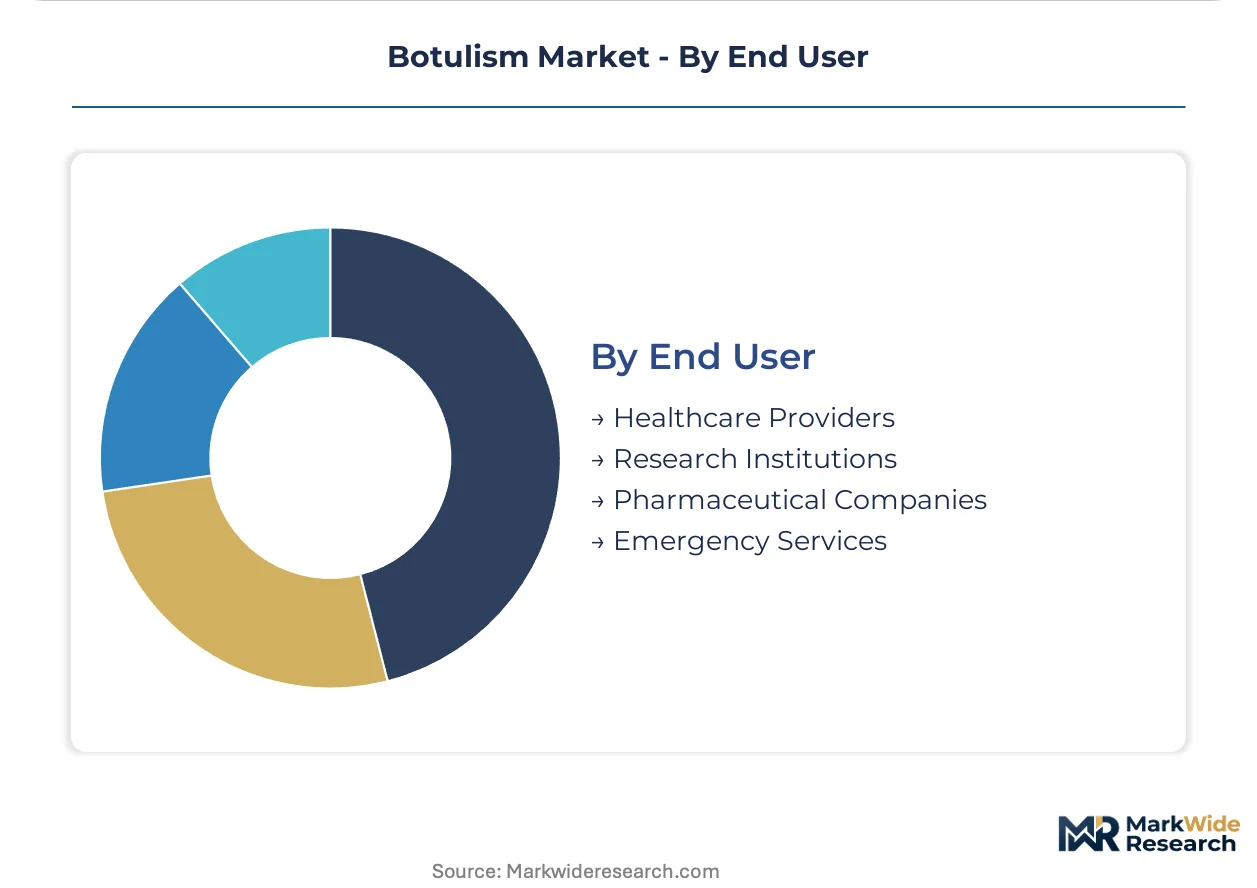
End User:
Customer type segmentation maps to fundamentally different procurement behaviors, from emergency stockpile management to research-driven development partnerships.
- Healthcare Providers:Hospital networks, emergency medical services, and individual practitioners execute antitoxin administration and therapeutic toxin injection. CDC and state health department coordination governs access to emergency reserves.
- Research Institutions:Academic medical centers and national laboratories advance recombinant antitoxin platforms and novel diagnostic assays. NIH funding mechanisms and BARDA advanced research contracts support translational programs.
- Pharmaceutical Companies:License holders and contract manufacturers manage heptavalent antitoxin production, purification, and lot release testing. Government contracting relationships anchor revenue predictability.
- Emergency Services:Regional emergency management agencies and metropolitan EMS systems coordinate pre-hospital antitoxin administration protocols, expanding point-of-care delivery before hospital transfer.
Healthcare Providers represent the installed base; Research Institutions are gaining share fastest on recombinant platform investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight through the Center for Biologics Evaluation and Research anchors the United States as the dominant geography, with BARDA stockpile contracts and pediatric hospital networks driving procurement concentration. Geographic demand patterns reflect emergency response infrastructure density and regulatory pathway maturity.
United States
BARDA Strategic National Stockpile contracts guarantee predictable offtake for heptavalent antitoxin manufacturers. CDC coordinates state health department release protocols for emergency deployment. California, Texas, and Pennsylvania host tertiary pediatric centers with dedicated infant botulism treatment protocols.
Germany
EMA centralized marketing authorizations enable streamlined EU-wide distribution from German manufacturing hubs. The Paul-Ehrlich-Institut governs lot release testing for biological products entering European markets. Frankfurt and Munich anchor pharmaceutical distribution networks serving central European hospital systems.
Japan
PMDA orphan drug incentives reduce regulatory timelines for rare disease biologics including novel antitoxin formulations. METI coordinates national stockpile planning for public health emergencies. Tokyo and Osaka metropolitan areas concentrate specialized ICU capacity for neuroparalytic emergency management.
India
CDSCO biologics pathway maturation enables WHO prequalification pursuit for national stockpile formation. Government procurement is expanding for emergency response infrastructure in tertiary care networks. Maharashtra and Karnataka host hospital systems developing pediatric ICU protocols for toxin-mediated paralysis.
Switzerland
Swissmedic maintains stringent biological product standards that influence reference pricing across European markets. The country's specialized immunoglobulin manufacturing heritage supports contract development for recombinant platforms. Basel and Zurich anchor pharmaceutical R&D clusters advancing monoclonal antibody alternatives.
Botulism Market Vendor Landscape
Government contractors and therapeutic specialists split the market into distinct procurement channels with limited overlap. Consolidation characterizes the emergency antitoxin segment where federal relationships create high barriers to entry. Three archetypes dominate: stockpile-anchored biomanufacturers, cosmetic-therapeutic toxin purifiers, and recombinant platform developers. Competitive moves center on geographic diversification of plasma supply networks and strategic partnerships for monoclonal antibody advancement.
Within the government-contracting tier, Emergent BioSolutions exemplifies stockpile-anchored positioning through its BARDA relationships. Allergan, now operating under AbbVie, occupies the therapeutic toxin purification space with specialized formulation capabilities. Ipsen Pharma represents European competition in neurological indications through differentiated delivery technologies. These three entities collectively illustrate how divergent capability requirements—equine hyperimmunization, precision purification, and formulation engineering—segment competitive terrain.
| Leading Market Players |
|---|
| Emergent BioSolutions |
| XOMA Corporation |
| Allergan (AbbVie) |
| Ipsen Pharma |
| Merz Pharma |
| Molecular Targeting Technologies |
| Microbiotix |
| AlphaVax |
| Morphotek |
| Others |
Supply Flow & Price Mechanics
Undercapacity in equine hyperimmunization facilities across the United States and Europe is compressing supplier margins while elevating antitoxin lot premiums for emergency purchasers. BARDA contract floors insulate domestic manufacturers from spot-price volatility, yet cold-chain biological handling costs add fifteen to twenty-five percent to delivered product cost, forcing geographic proximity trade-offs in procurement decisions.
Pricing Analysis
Geographic price spreads between North American and European hospital systems reflect divergent reimbursement frameworks and stockpile financing mechanisms. Contract-based long-term offtake dominates, with BARDA strategic reserves anchoring predictable revenue streams for domestic biomanufacturers while European tender processes introduce competitive bidding pressure. Price differentiation rests on FDA lot release tier versus EMA centralized authorization, with pediatric ICU networks showing lowest price sensitivity due to emergency protocol mandates and highest sensitivity among regional emergency services expanding pre-hospital administration programs. Cost compression in standard equine-derived antitoxin is intensifying as recombinant monoclonal platforms advance through Phase II trials.
Supply Chain Analysis
Tariff exposure between United States and European Union jurisdictions complicates cross-border antitoxin distribution despite regulatory harmonization efforts. Supply concentrates in United States, Germany, and Switzerland, with equine plasma sourcing anchored in specialized horse farm networks across Kentucky, Tennessee, and Bavaria. Production rests on hyperimmune plasma collection, fractionation capacity, and fill-finish biological suites. Single-source vulnerability in equine health management threatens batch continuity. Distribution runs through CDC-coordinated state health department release protocols for emergency reserves, with direct hospital pharmacy delivery for therapeutic indications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant antibody platform maturation is disrupting decades-old equine-dependent production economics, compressing development timelines from eighteen months to eight weeks and forcing incumbent repositioning.
For Market Incumbents: Harden equine plasma supply security through captive herd partnerships in geographically dispersed zones, mitigating animal health disruption exposure. Secure backward integration into specialized immunoglobulin manufacturing talent pools, addressing aging workforce concentration. Accelerate recombinant platform licensing to neutralize monoclonal substitution threat from academic medical center spinouts. For New Entrants and Emerging Players: Pursue WHO prequalification pathway for CDSCO-authorized biologics targeting Indian national stockpile formation, the most penetrable emerging economy procurement channel. Establish contract development relationships with Swissmedic-influenced European reference laboratories for harmonized potency standards. Position through emergency medical services pre-hospital administration protocols as differentiated point-of-care delivery angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among stockpile-anchored biomanufacturers with BARDA relationship depth and predictable offtake schedules. Five-to-ten year viability favors entities with parallel recombinant platform development alongside legacy equine infrastructure. Monitor Phase II monoclonal antibody readouts as inflection indicator for platform substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Platform Development | Collapses eighteen-month equine production cycles into eight-week bioreactor timelines, threatening incumbent positioning. |
| BARDA Contract Extension | Anchors predictable revenue streams for domestic heptavalent antitoxin manufacturers through strategic reserve mandates. |
| WHO Prequalification Pursuit | Enables emerging economy national stockpile access through CDSCO pathway maturation in India procurement. |
| Pre-Hospital Protocol Expansion | Extends antitoxin administration point-of-care delivery through emergency medical services coordination networks. |
| Pediatric ICU Network Partnership | Captures infant botulism volume concentration across California, Texas, and Pennsylvania tertiary centers. |
Methodological Framework
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors provided ongoing calibration against operating reality. Primary interviews with CDC emergency response coordinators and BARDA contracting officers combined with secondary validation from FDA Center for Biologics Evaluation and Research filings, EMA Committee for Medicinal Products for Human Use opinions, ClinicalTrials.gov recombinant antibody program records, and WHO prequalification assessment reports. Bottom-up patient volume modeling and top-down procurement budget analysis triangulated market size estimates.
Scenario-bracketing around recombinant platform substitution velocity and equine supply disruption probability framed projection uncertainty. Segmentation modeling across therapy area, treatment type, distribution channel, and end user dimensions generated discrete growth trajectories. CAGRs derived from historical procurement pattern analysis and forward policy commitment assessment. Forecast inputs incorporated BARDA contract renewal schedules, PMDA orphan drug designation timelines, and European reference laboratory harmonization progress.
Sensitivities concentrate around recombinant monoclonal Phase II trial outcomes, equine health event probability, and regulatory divergence between FDA and EMA immunogenicity standards. Forecasts reflect documented assumptions subject to revision from technological substitution, supply disruption, or pathway harmonization shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Hand Hygiene Products Market
Infection Control
Salivary Gland Infection Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Patient Hygiene Aids Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Intra Abdominal Infection Market