
 Blood Stream Infection Testing Market | 2026-2036
Blood Stream Infection Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Stream Infection Testing Market Analysis
Aftermarket service revenue for installed diagnostic platforms is rewriting profitability expectations across the blood stream infection testing landscape. bioMérieux SA leverages its global service infrastructure to sustain recurring revenue from its BacT/ALERT installed base. BD competes through vertically integrated blood culture media production that anchors its instrument placement strategy. Thermo Fisher Scientific Inc. dominates molecular consumables with a platform-agnostic reagent portfolio that extends across multiple instrument generations.
Blood stream infection testing encompasses laboratory and point-of-care methods designed to detect viable pathogens, microbial antigens, or nucleic acid signatures directly from blood specimens, typically requiring sample volumes of 10-30 mL collected in aerobic and anaerobic culture bottles or specialized lysis-centrifugation tubes, with turnaround targets compressing from 48-72 hours for conventional blood culture to under 2 hours for PCR-based panels. The technology dimension shows genotypic methods capturing margin expansion as hospitals replace phenotypic workflows with multiplex PCR and MALDI-TOF mass spectrometry for species-level identification. End user concentration tilts toward hospitals where antimicrobial stewardship committees mandate rapid diagnostic integration, while diagnostic laboratories occupy the volume-intensive reference testing tier with lower per-test margins.
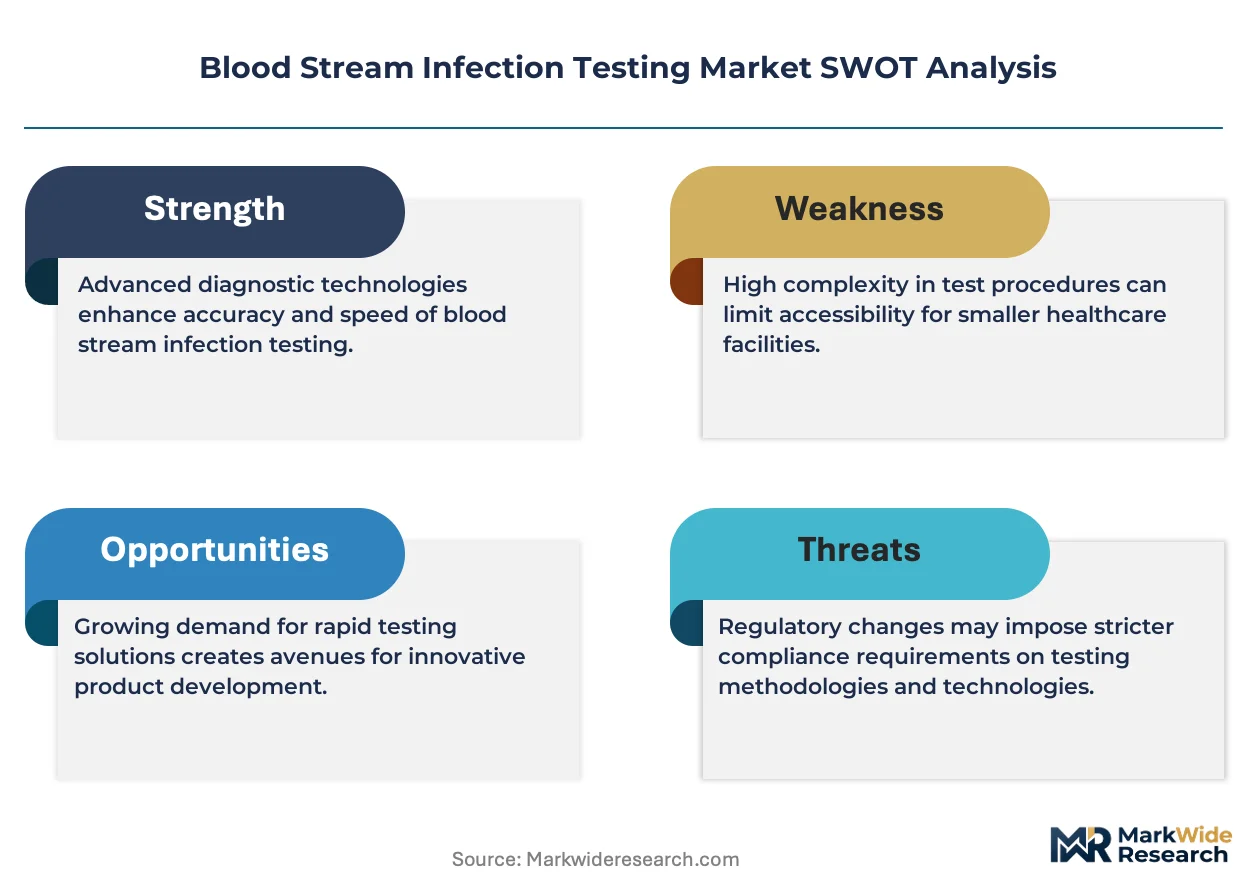
The FDA regulates blood stream infection diagnostics through premarket notification and premarket approval pathways with CLIA complexity classifications that determine site-of-care eligibility, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for notified body conformity assessments that reshape market access timelines. ISO 15189 accreditation standards for medical laboratories drive quality system investments that filter vendor selection toward integrated platform providers. Stakeholders must monitor evolving breakpoints from CLSI and EUCAST that redefine resistance thresholds and trigger panel content revisions across commercial assays.
Market Dynamics
Antimicrobial stewardship mandates are compressing diagnostic turnaround expectations from 48-hour blood culture cycles to under 2-hour molecular panels, forcing hospital laboratories to restructure capital allocation toward rapid pathogen identification platforms.
Growth Catalysts
- FDA CLIA waiver pathways:Accelerated regulatory clearances for point-of-care diagnostics expand testing eligibility beyond centralized laboratories into emergency departments and intensive care units.
- Hospital antimicrobial stewardship committees:Mandatory rapid diagnostic integration protocols in tertiary care facilities drive instrument procurement for species-level identification within therapeutic decision windows.
- MALDI-TOF mass spectrometry:Proteomic fingerprinting technology reduces time-to-identification from 24-48 hours to minutes, displacing biochemical phenotyping workflows in high-volume laboratories.
Market Restraints
- Reagent cost structure:Molecular consumables carry 3-5x per-test cost premiums versus conventional blood culture media, constraining adoption in budget-constrained community hospitals.
- Supply concentration in polymerase production:Thermostable DNA polymerase manufacturing clusters in specialized biochemical suppliers, exposing assay producers to input bottlenecks.
- Technical limitation in polymicrobial detection:Current PCR panels miss mixed infections and fastidious organisms, requiring parallel culture-based confirmation that extends total diagnostic pathway length.
Strategic Opportunities
- Underpenetrated outpatient oncology clinics:Febrile neutropenia protocols in ambulatory cancer centers lack rapid diagnostic infrastructure, creating greenfield placement potential for compact molecular platforms.
- EU In Vitro Diagnostic Regulation clinical evidence requirements:Stricter notified body conformity assessments favor established manufacturers with robust quality systems, consolidating market access for integrated platform providers.
- Digital microbiology convergence:Integration of automated blood culture with AI-augmented imaging and cloud-based resistance prediction compresses interpretation timelines beyond instrument-level automation.
Industry Challenges
- Clinical microbiology technologist shortage:Specialized training requirements for MALDI-TOF and molecular assay operation outpace educational pipeline output, constraining laboratory throughput expansion.
- Legacy laboratory information system integration:Disparate data formats between rapid diagnostic instruments and hospital electronic health records demand costly middleware development for seamless result reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Stream Infection Testing Market |
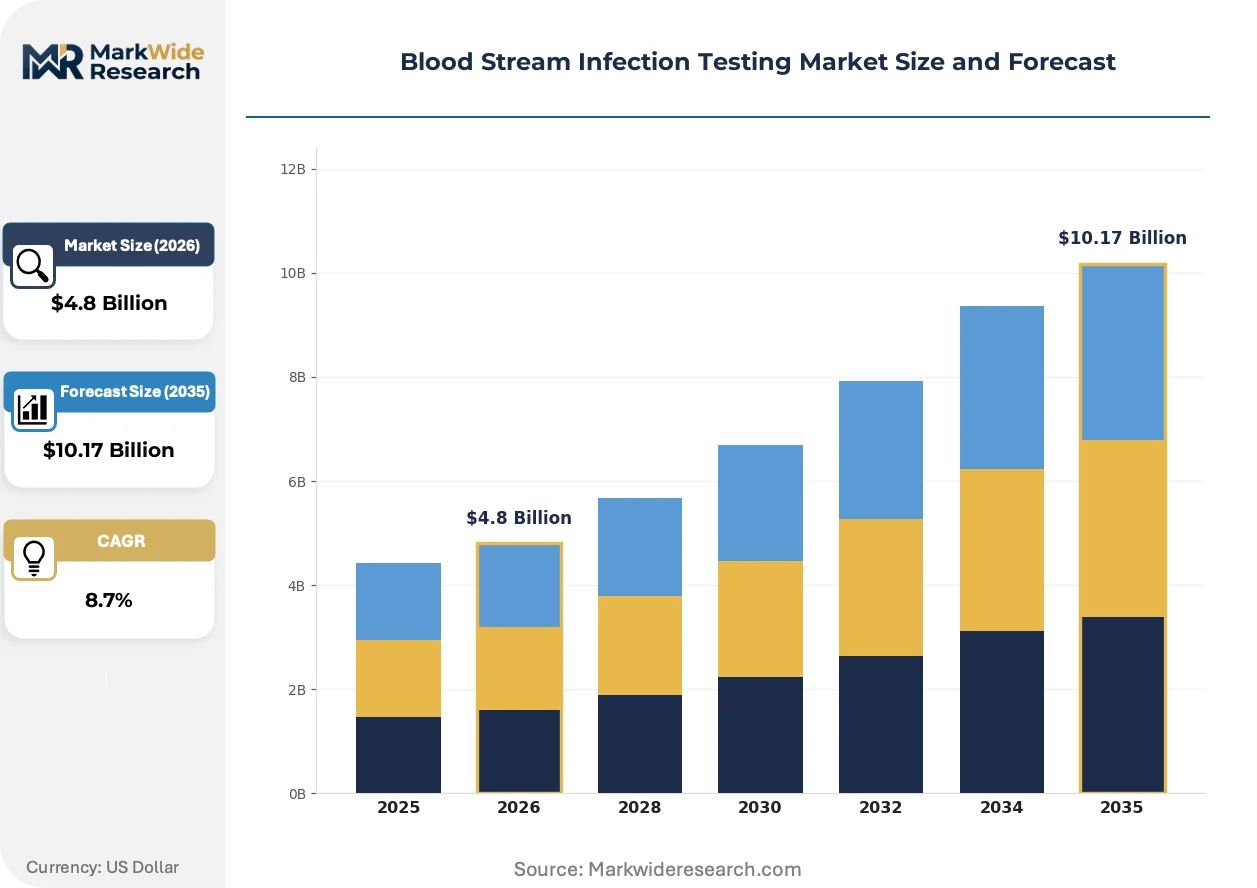
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Culture, PCR Test, Serological Test, Rapid Diagnostic Test Technology: Phenotypic, Genotypic, Immunoassay, Mass Spectrometry End User: Hospitals, Diagnostic Laboratories, Blood Banks, Research Institutes Application: Clinical Diagnosis, Infection Control, Drug Resistance Testing, Epidemiology Studies |
| Companies Covered | Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd, Abbott Laboratories, BD, bioMérieux SA, Cepheid, Beckman Coulter, Inc., Luminex Corporation, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Stream Infection Testing Market Emerging Trajectories
Digital pathology and artificial intelligence are penetrating microbiology workflows, while regulatory frameworks on both sides of the Atlantic reshape market access requirements for novel diagnostic modalities.
Next-generation sequencing is virtualizing species identification and resistance profiling by replacing culture-dependent methods with direct-from-blood metagenomic analysis. Academic medical centers in the United States and Germany are piloting nanopore-based platforms for same-day turnaround on complex polymicrobial infections. This technology is virtualizing the traditional distinction between identification and susceptibility testing into a unified molecular readout.
The EU In Vitro Diagnostic Regulation imposes stricter clinical performance studies and post-market surveillance obligations on blood stream infection assay manufacturers. Notified body capacity constraints extend conformity assessment timelines, delaying product launches. High-complexity molecular panels face proportionally greater documentation burdens than moderate-complexity alternatives, reshaping R&D prioritization toward streamlined assay architectures.
Hospital procurement committees are consolidating vendor relationships around integrated platform ecosystems that span blood culture, identification, and susceptibility testing. Single-source contracting reduces operational complexity but locks laboratories into captive consumable streams. This concentration is most pronounced in the United States, where health system consolidation has concentrated purchasing power among integrated delivery networks negotiating enterprise-wide diagnostic supply agreements.
Blood Stream Infection Testing Market Segmentation
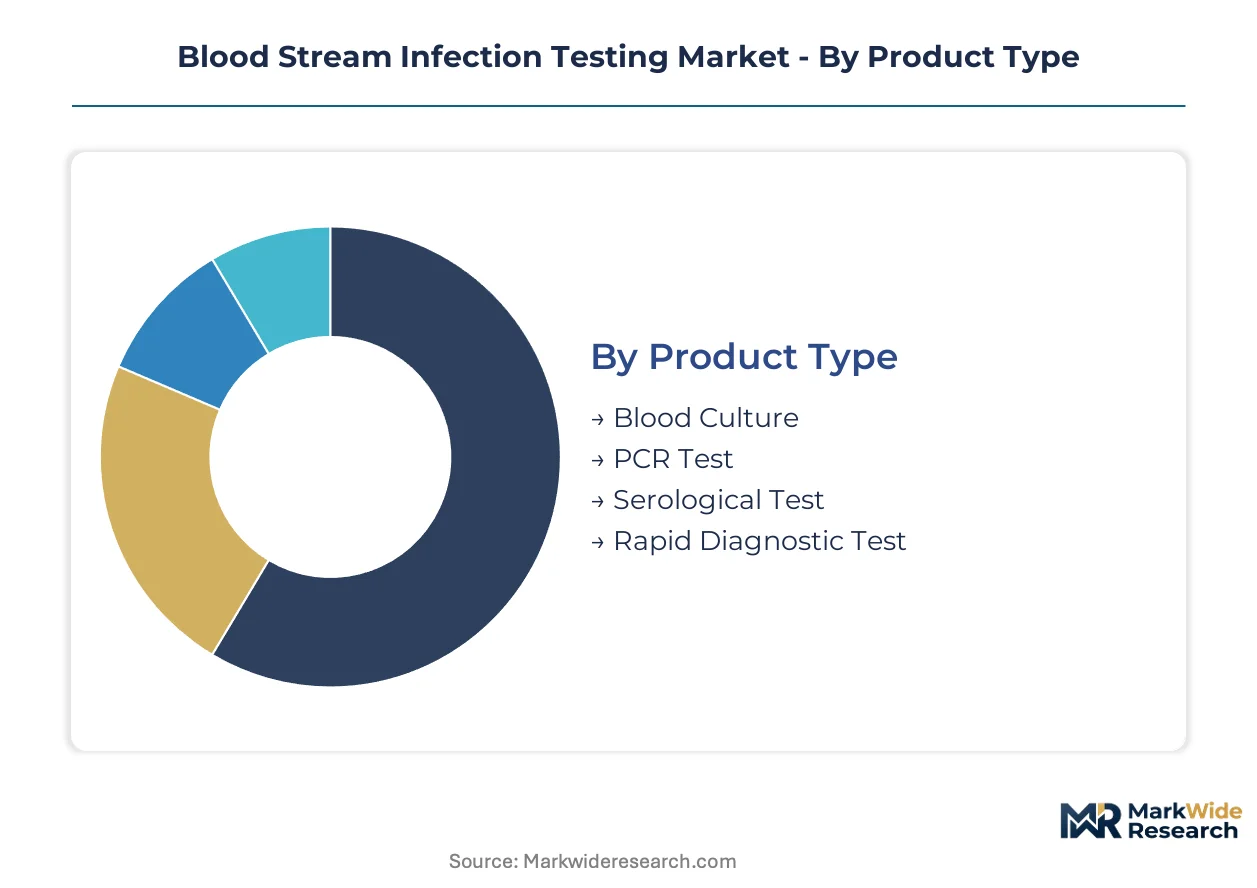
Segmentation in blood stream infection testing reveals how capital deployment, consumable economics, and service intensity vary across technology platforms. Hospital procurement committees weight installed base serviceability against per-test reagent costs when selecting vendor ecosystems.
Product Type:
After-sales-service intensity varies dramatically across product categories, with automated blood culture platforms demanding multi-year service contracts while rapid diagnostics shift margin to disposable cartridges.
- Blood Culture:Automated systems process 10-30 mL specimens in aerobic and anaerobic bottles, requiring continuous temperature monitoring and contamination protocols. United States hospital laboratories concentrate demand here as antimicrobial stewardship programs mandate 24-48 hour incubation cycles for comprehensive pathogen recovery. Service contracts typically span 5-7 years and anchor vendor lock-in.
- PCR Test:Multiplex nucleic acid amplification panels deliver species identification within 1-2 hours from direct blood specimens. German tertiary care centers drive adoption where rapid therapeutic decision windows override higher consumable costs. Thermal cycler maintenance and assay calibration generate recurring technical service visits.
- Serological Test:Antibody detection assays for retrospective infection confirmation.
- Rapid Diagnostic Test:Lateral flow and immunochromatographic devices for point-of-care screening.
Blood Culture holds the largest share; momentum sits with PCR Test.
Technology:
Cost tier stratification separates capital-intensive phenotypic platforms from genotypic methods commanding premium reagent pricing.
- Phenotypic:Conventional culture-based methods rely on biochemical reactions and colony morphology for species identification. Japanese hospital networks maintain substantial installed bases where workflow familiarity and lower per-test costs sustain utilization despite slower turnaround times.
- Genotypic:Molecular amplification and sequencing technologies detect pathogen DNA or RNA directly from clinical specimens. United States academic medical centers are expanding genotypic adoption as FDA-cleared panels proliferate and resistance gene detection becomes clinically essential.
- Immunoassay:Antigen and antibody detection platforms for rapid pathogen screening.
- Mass Spectrometry:MALDI-TOF systems generate proteomic fingerprints for species-level identification within minutes.
Phenotypic retains volume dominance; genotypic methods are climbing the fastest.
End User:
Customer type determines purchasing authority complexity, with integrated delivery networks consolidating hospital procurement while reference laboratories negotiate reagent contracts independently.
- Hospitals:Inpatient facilities operate blood culture instruments, molecular platforms, and mass spectrometry systems across clinical microbiology laboratories. Antimicrobial stewardship committees in United States tertiary care centers mandate rapid diagnostic integration, driving capital expenditure toward sub-2-hour identification platforms.
- Diagnostic Laboratories:Reference and commercial laboratories process high specimen volumes with automated blood culture and identification systems. Germany's centralized laboratory network concentrates regional testing volume, achieving economies of scale that community hospitals cannot replicate.
- Blood Banks:Transfusion services screen donor units for bacterial contamination.
- Research Institutes:Academic and government laboratories develop novel detection methodologies.
Hospitals command the largest share; diagnostic laboratories are gaining share fastest.
Application:
Maturity levels diverge across use cases, with clinical diagnosis representing established reimbursement pathways while epidemiology applications remain grant-dependent.
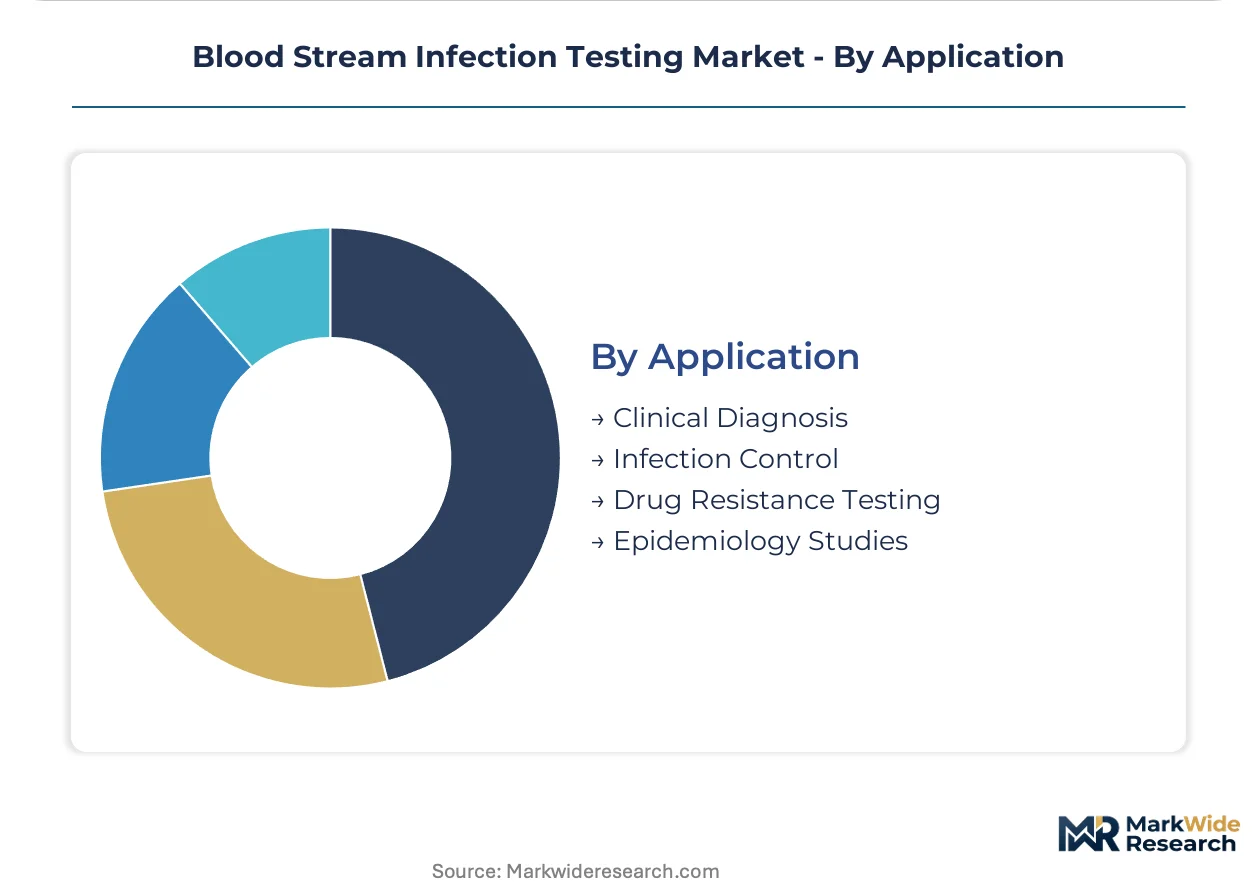
- Clinical Diagnosis:Patient-level pathogen detection guides antimicrobial therapy selection. Japan's aging population and high hospitalization rates concentrate demand for rapid bacteremia diagnosis in emergency and intensive care settings.
- Infection Control:Surveillance testing identifies nosocomial transmission chains. United States hospital epidemiologists deploy whole-genome sequencing for outbreak investigation as CLIA-certified laboratory capacity expands.
- Drug Resistance Testing:Phenotypic and genotypic susceptibility profiling.
- Epidemiology Studies:Population-level pathogen surveillance and resistance monitoring.
Clinical Diagnosis holds the largest share; infection control applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany tolerate 3-5x reagent premiums for molecular speed, while community hospitals in India and Brazil face hard budget constraints that sustain conventional blood culture dominance. This elasticity divide shapes vendor pricing power and product mix across national markets.
United States
Tertiary care antimicrobial stewardship mandates drive sub-2-hour identification procurement in the United States. FDA CLIA waiver pathways accelerate point-of-care clearances for emergency department deployment. The Boston-Cambridge corridor concentrates nanopore sequencing pilots at academic medical centers.
Germany
Centralized laboratory networks in Germany achieve blood culture economies of scale that community hospitals cannot replicate. EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for notified body conformity assessments. The Rhine-Ruhr metropolitan region anchors reference testing consolidation.
Japan
Aging demographics and high hospitalization rates concentrate rapid bacteremia diagnosis demand in Japanese emergency and intensive care settings. PMDA regulatory frameworks govern in vitro diagnostic approvals with quality system requirements. The Kanto region around Tokyo maintains substantial phenotypic platform installed bases.
India
Budget-constrained community hospitals in India sustain conventional blood culture workflows despite slower turnaround times. CDSCO regulates medical device imports and domestic manufacturing licensing. Diagnostic laboratory chains in Maharashtra and Karnataka expand reference testing capacity for outsourced molecular panels.
United Kingdom
NHS antimicrobial resistance strategies mandate rapid diagnostic integration in United Kingdom tertiary centers. MHRA post-Brexit regulatory autonomy reshapes conformity assessment timelines for EU-originating assays. London teaching hospitals pilot whole-genome sequencing for outbreak investigation networks.
Blood Stream Infection Testing Market Vendor Landscape
Capability concentration sits with integrated platform specialists; scale advantage sits with diversified life science conglomerates. The market structures around three tiers: blood culture automation incumbents with captive media production, molecular assay specialists with platform-agnostic reagent portfolios, and mass spectrometry entrants displacing biochemical phenotyping. Consolidation momentum runs through service contract anchoring and enterprise procurement consolidation, while technology licensing partnerships accelerate assay menu expansion.
Among diversified diagnostics conglomerates, Thermo Fisher Scientific Inc. and BD occupy positions that exemplify contrasting scale strategies. Thermo Fisher represents the platform-agnostic reagent archetype with molecular consumables extending across instrument generations. BD anchors the vertically integrated blood culture tier where captive media production locks in instrument placement. BioMérieux SA sits within the European specialist tier, sustaining recurring revenue through global service infrastructure for installed base retention.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| BD |
| bioMérieux SA |
| Cepheid |
| Beckman Coulter, Inc. |
| Luminex Corporation |
| Bruker Corporation |
| Others |
Supply Flow & Price Mechanics
Thermostable DNA polymerase manufacturing clusters in specialized biochemical suppliers in the United States and Germany, anchoring margin capture in the reagent tier while instrument vendors compete on service contract duration and geographic coverage of technical field teams.
Pricing Analysis
After-sales service contracts spanning 5-7 years drive lifetime value for automated blood culture platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with full menu molecular panels from community hospitals selecting targeted assays. Cost compression in the PCR reagent tier is intensifying because multiplex panel commoditization erodes per-test premiums. Community hospitals exhibit highest price sensitivity, deferring molecular adoption where blood culture workflows satisfy stewardship minimums.
Supply Chain Analysis
Supplier-financing facilities from specialty biochemical producers extend payment terms to assay manufacturers buffering working capital cycles. Polymerase production concentrates in the United States and Germany, while blood culture media manufacturing anchors in regional production hubs serving hospital networks. Critical inputs span thermostable enzymes, selective culture media formulations, and MALDI-TOF calibration matrices. Single-source vulnerability in polymerase supply exposes panel producers to input bottlenecks. Distribution runs through integrated delivery networks consolidating procurement across hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough as antimicrobial stewardship mandates force capital refresh cycles in hospital microbiology laboratories, compressing replacement timelines from 7-10 year instrument lifecycles toward 5-year upgrade cycles.
For Market Incumbents: Insulate installed base retention by extending service contract durations and embedding field engineers within hospital microbiology departments. Captive blood culture media production locks instrument placement against molecular displacement. Vertical integration into polymerase manufacturing reduces exposure to supplier concentration risk. For New Entrants and Emerging Players: Establish a beachhead in outpatient oncology clinics where febrile neutropenia protocols lack rapid diagnostic infrastructure. Point-of-care molecular platforms for emergency department deployment face lower competitive density than saturated central laboratory segments. Partner with antimicrobial stewardship software vendors for bundled workflow integration. For Investors and Strategic Acquirers: Capital is best deployed toward platform-agnostic reagent specialists with FDA-cleared panels spanning multiple instrument generations. Long-term viability hinges on regulatory navigation capability under EU In Vitro Diagnostic Regulation conformity assessment requirements. Watch FDA CLIA waiver volume acceleration as inflection indicator for point-of-care market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Pathway Acceleration | FDA clearance for point-of-care diagnostics expands testing eligibility beyond centralized laboratories into emergency departments. |
| Hospital System Partnership | Enterprise-wide diagnostic supply agreements with integrated delivery networks lock in multi-year consumable commitments. |
| Software Companion Development | AI-augmented imaging integration with automated blood culture systems compresses interpretation timelines beyond instrument automation. |
| Reimbursement Strategy | CPT code alignment for rapid molecular panels secures favorable coverage decisions from Medicare and commercial payers. |
| CE Marking Pathway | Notified body conformity assessment under EU In Vitro Diagnostic Regulation enables market access across German and United Kingdom hospital networks. |
Methodological Framework
Operator-level perspectives from clinical microbiology laboratory directors, hospital antimicrobial stewardship committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EU notified body conformity assessment databases, hospital procurement records, and CLSI breakpoint guideline revisions. Bottom-up instrument placement modeling and top-down market sizing triangulated volume estimates across the analysis window.
Scenario-bracketing framed the projection framework across conservative, base, and expansion cases. Segmentation dimensions spanned product type, technology platform, end-user facility tier, and regional regulatory cluster. CAGRs derived from logistic diffusion modeling of molecular platform adoption curves and replacement cycle compression in hospital capital planning. Industry-specific inputs incorporated antimicrobial stewardship mandate implementation timelines and CLIA waiver clearance velocity.
Sensitivities concentrate around FDA regulatory pathway timing, EU notified body capacity constraints, and hospital capital budget cyclicality. Forecasts reflect documented assumptions regarding technology substitution rates and reimbursement policy stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Surgical Site Infections Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Medical Washer Disinfector Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Dental Infection Treatment Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Alcohol Wipes Market
Infection Control
Hand Hygiene Products Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market