
 Antimicrobial Suture Market | 2026-2036
Antimicrobial Suture Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Suture Market Analysis
Hospital procurement consolidation is repositioning antimicrobial suture vendors toward long-term supply contracts and bundled pricing. Johnson & Johnson (Ethicon) leverages its surgical ecosystem to anchor premium suture lines within integrated delivery networks. Medtronic competes through its minimally invasive surgery platform, bundling sutures with stapling and energy devices. B. Braun sustains manufacturing scale across European and Asian production nodes, controlling cost positions in standard absorbable lines.
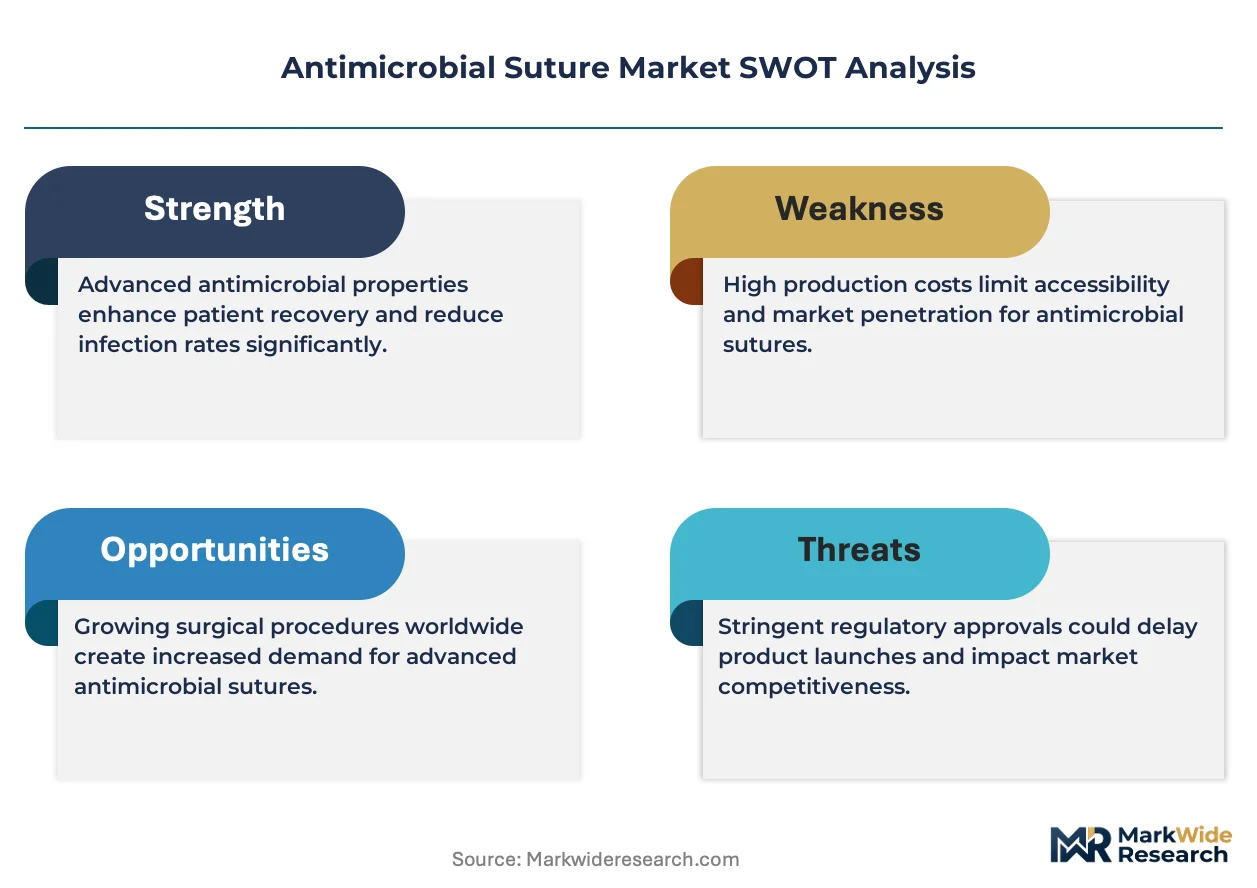
An antimicrobial suture is a surgical closure device impregnated with antiseptic agents such as triclosan or chlorhexidine to inhibit bacterial colonization at wound sites, typically manufactured through extrusion of synthetic polymers followed by coating or drug-eluting fiber integration. Its primary purpose is reducing surgical site infections in procedures where bacterial contamination risk exceeds baseline thresholds. Absorbable sutures dominate volume due to elimination of removal visits, while barbed sutures capture margin pools in laparoscopic closures by eliminating knot-tying steps and reducing operative time. Among applications, general surgery anchors baseline demand, whereas orthopedic surgery extends growth as joint reconstruction volumes rise and infection consequences carry catastrophic cost implications.
FDA biocompatibility standards under ISO 10993 govern cytotoxicity and sensitization testing for antimicrobial coatings, while EMA's Medical Device Regulation (MDR) imposes post-market surveillance obligations that lengthen approval timelines for novel suture formulations. The EU Green Deal's chemical restrictions are forcing reformulation away from legacy antiseptic compounds toward biodegradable alternatives. Stakeholders must monitor regulatory divergence between US and European testing paradigms when allocating R&D budgets across geographic pipelines.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing antimicrobial suture suppliers to restructure around integrated delivery networks rather than standalone product sales. This structural force privileges manufacturers with broad surgical portfolios capable of anchoring multi-year supply contracts.
Growth Catalysts
- Surgical Site Infection Mandates:CMS non-payment policies for hospital-acquired infections in the United States create institutional pressure to adopt infection-prevention devices. Facilities absorb premium suture costs to avoid reimbursement penalties.
- Orthopedic Procedure Volume:Joint reconstruction surgeries in Germany and Japan carry catastrophic infection cost implications, driving preference for antimicrobial closure devices in high-stakes musculoskeletal interventions.
- Triclosan-Coated Polymer Technology:Drug-eluting fiber integration enables sustained antimicrobial release without compromising tensile strength, expanding the addressable procedure set beyond traditional coated sutures.
Market Restraints
- Raw Material Concentration:Polyglycolic acid and polydioxanone supply clusters in Chinese and German chemical manufacturing create input cost volatility and single-source vulnerability for absorbable suture producers.
- EMA MDR Compliance Burden:Post-market surveillance obligations and clinical evidence requirements under the EU Medical Device Regulation extend approval timelines and inflate regulatory capital requirements for novel formulations.
- Non-Antimicrobial Substitution:Standard monofilament sutures with enhanced surface finishing compete on cost in price-sensitive ambulatory surgical centers, limiting antimicrobial penetration in outpatient settings.
Strategic Opportunities
- Indian Ambulatory Surgery Centers:Underpenetrated outpatient facilities in tier-2 Indian cities present volume expansion potential as surgical infrastructure scales under national health insurance expansion programs.
- Biodegradable Antiseptic Formulations:EU Green Deal chemical restrictions are forcing innovation away from legacy triclosan toward bioabsorbable antimicrobial compounds that satisfy environmental compliance.
- Barbed Suture-Laparoscopic Device Bundling:Knotless closure technology convergence with robotic surgery platforms enables premium positioning in minimally invasive procedures where operative time reduction commands price premiums.
Industry Challenges
- Polymer Extrusion Specialist Scarcity:Manufacturing antimicrobial sutures requires combined expertise in pharmaceutical coating and medical textile engineering, a skill intersection with limited trained workforce availability.
- ISO 10993 Cytotoxicity Certification Delays:Biocompatibility testing protocols for novel antimicrobial coatings extend development timelines, compressing effective patent windows before generic competition emerges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Suture Market |
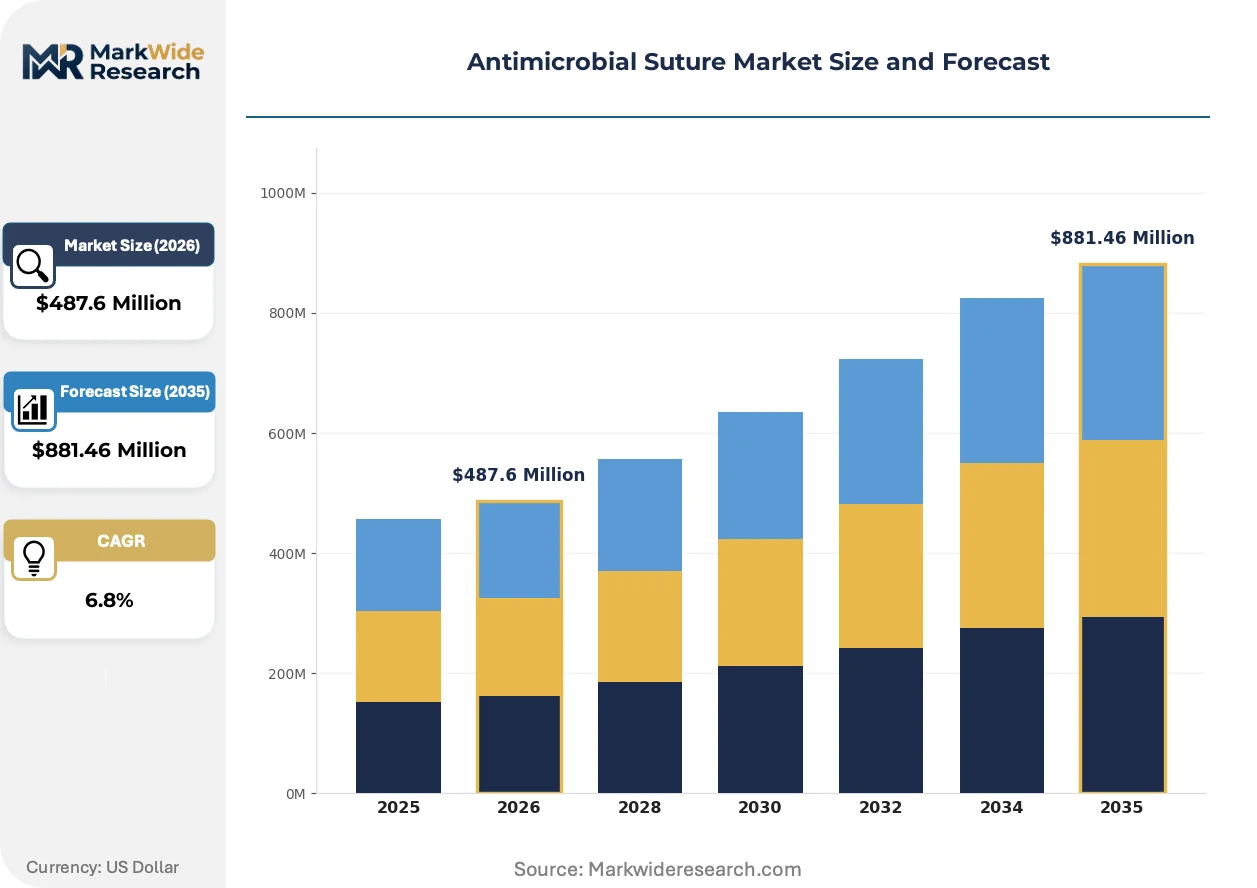
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable, Non-absorbable, Barbed Sutures, Monofilament End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Specialty Clinics Material: Polypropylene, Polyester, Silk, Nylon Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Dental Surgery |
| Companies Covered | Dolphin Sutures, The Healthium Group, Johnson & Johnson (Ethicon), Meril Life Sciences, Internacional Farmacéutica, Medtronic, Lotus Surgicals, Unilene, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Suture Market Emerging Trajectories
Active polymer science and regulatory chemistry are converging to reshape how antimicrobial efficacy is engineered into surgical closure devices. Three developments are restructuring competitive positioning and procurement criteria.
Chlorhexidine-impregnated monofilament sutures deliver broader-spectrum bacterial inhibition than legacy triclosan formulations, particularly against gram-positive pathogens common in orthopedic and cardiovascular procedures. Academic medical centers in the United States and Japan are adopting these devices as standard of care in joint replacement and sternal closure. Synthetic absorbable platforms with integrated antiseptic elution are overtaking surface-coated alternatives in premium surgical segments where infection consequences carry litigation and readmission cost exposure.
REACH chemical authorization requirements in the European Union are forcing reformulation of legacy antimicrobial compounds used in suture coatings. ECHA substance evaluation processes have flagged triclosan and related phenolic antiseptics for endocrine disruption concerns, compelling manufacturers to validate biodegradable alternatives through extended environmental fate studies. German and French surgical device distributors are now requiring chemical safety documentation that exceeds baseline CE marking, filtering supplier eligibility toward those with dedicated regulatory toxicology capabilities.
Integrated delivery networks in the United States are consolidating suture procurement through centralized committees that evaluate total cost of infection rather than unit price. These committees weight antimicrobial devices against standard sutures plus prophylactic antibiotic protocols, creating preference algorithms that favor coated products in high-risk procedure categories. The purchasing model compresses vendor fragmentation and rewards suppliers with outcome data from multi-site clinical registries.
Antimicrobial Suture Market Segmentation
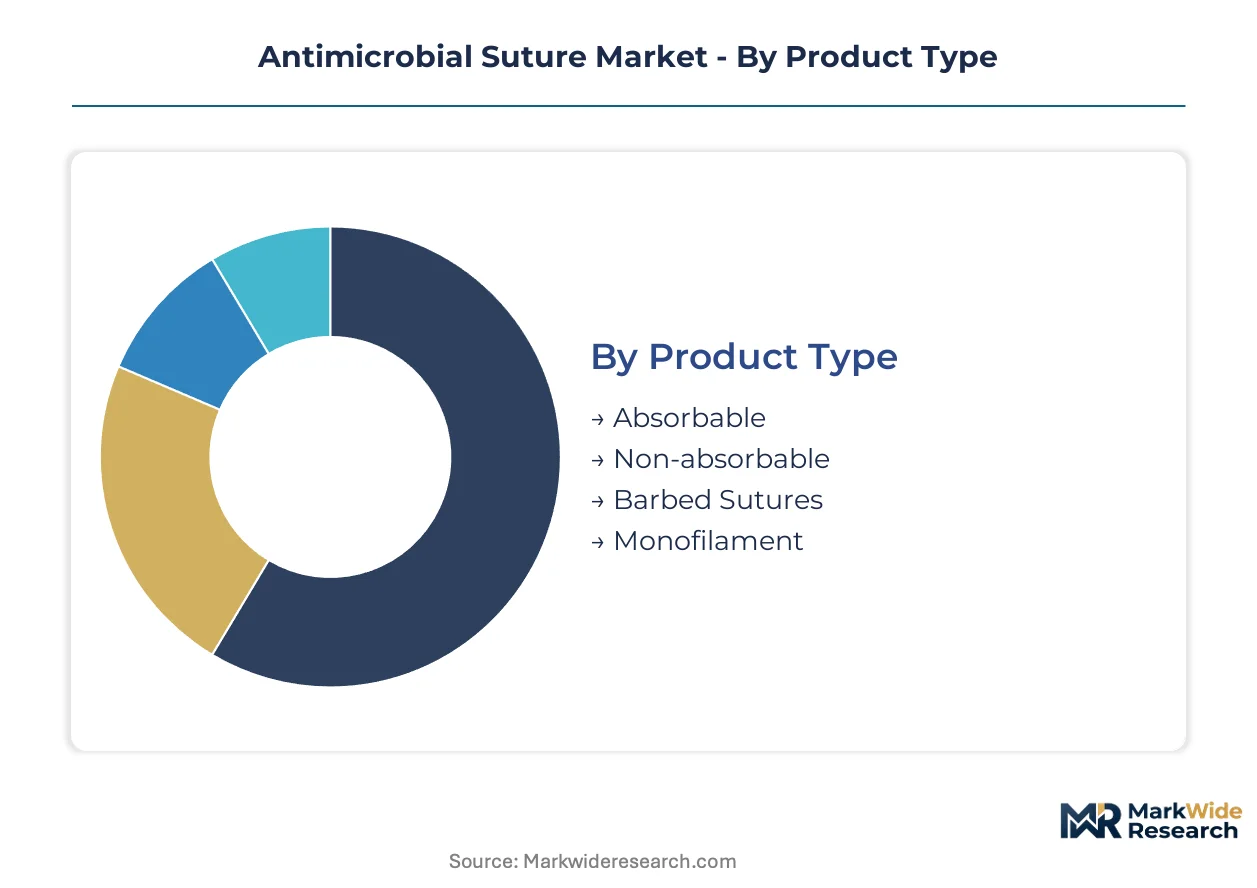
Antimicrobial suture procurement decisions hinge on procedure-specific infection risk profiles, material biocompatibility requirements, and institutional purchasing frameworks. Manufacturers must align product portfolios across absorbability profiles, end-user facility types, and surgical specialty demands to capture contract value.
Product Type:
Surgeons select suture architecture based on wound healing timeline, tissue interaction properties, and operative technique constraints.
- Absorbable:Polyglycolic acid and polylactide copolymers degrade through hydrolysis, eliminating removal visits and reducing patient compliance burdens. General surgery departments in United States academic medical centers specify these devices for abdominal wall closures where deep suture retrieval risks outweigh material costs.
- Barbed Sutures:Bidirectional anchor points distribute tension along the wound length without knot-tying, compressing operative time in laparoscopic environments. Orthopedic surgery units in German hospitals prioritize these devices for subcutaneous closures in joint replacement procedures where operating room throughput drives financial performance.
- Non-absorbable:Polypropylene and polyester filaments maintain tensile strength indefinitely, serving cardiovascular sternal closures and hernia mesh fixation where permanent mechanical support is mandatory.
- Monofilament:Single-strand construction minimizes bacterial wicking through capillary action, preferred in contaminated wound settings despite higher handling stiffness.
Volume sits with absorbable sutures; growth tilts toward barbed configurations.
End User:
Facility reimbursement structures and infection liability exposure determine antimicrobial suture penetration rates across care settings.
- Hospitals:Inpatient surgical departments absorb premium device costs to avoid CMS non-payment penalties for hospital-acquired infections. Integrated delivery networks in the United States negotiate multi-year supply contracts that bundle sutures with stapling and energy devices.
- Ambulatory Surgical Centers:Freestanding facilities face compressed margins and limited infection tracking infrastructure, creating price sensitivity that favors standard monofilament alternatives unless mandated by procedural protocols.
- Outpatient Clinics:Minor wound closure volumes in dermatology and primary care settings rarely justify antimicrobial premium pricing, limiting penetration to high-risk immunocompromised patient subsets.
- Specialty Clinics:Oral surgery and ophthalmology practices require ultra-fine diameter sutures with specialized needle configurations, commanding niche premium positioning.
Procurement concentration favors hospitals; ambulatory expansion offers the steepest volume trajectory.
Material:
Polymer selection governs tensile strength retention, inflammatory response, and antimicrobial coating compatibility.
- Polypropylene:Isotactic crystalline structure provides maximal chemical inertness and minimal tissue reactivity, anchoring cardiovascular and permanent soft tissue approximation procedures.
- Polyester:Braided multifilament construction delivers superior handling and knot security, standard in orthopedic tendon repairs where mechanical failure carries catastrophic functional consequences.
- Silk:Natural protein fiber with capillary action properties now restricted to ligature applications where absorbability is undesirable and antimicrobial coating is contraindicated.
- Nylon:Polyamide elasticity suits skin closure and microsurgical anastomosis, though hydrolytic degradation limits long-term implantation.
Polypropylene commands permanent implant share; polyester gains in high-tension orthopedic applications.
Application:
Surgical specialty infection risk profiles and litigation exposure determine antimicrobial device specification intensity.
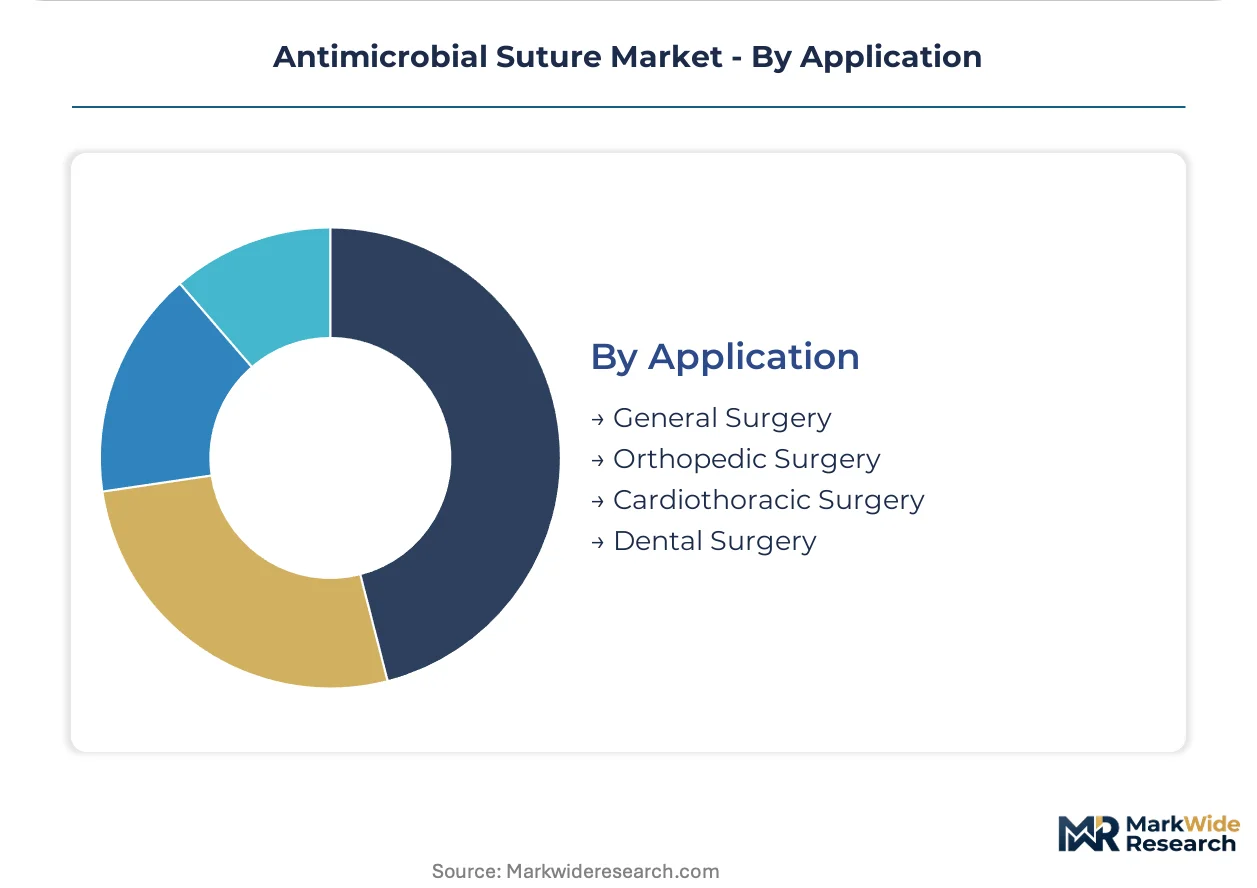
- General Surgery:Abdominal and gastrointestinal procedures generate baseline antimicrobial suture demand through institutional infection prevention protocols.
- Orthopedic Surgery:Prosthetic joint and spinal instrumentation implantations carry catastrophic infection cost implications, driving mandatory antimicrobial closure device adoption in German and Japanese reimbursement frameworks.
- Cardiothoracic Surgery:Sternal wound infections in cardiac bypass patients produce mortality and readmission penalties, compelling coated suture use in United States hospital systems.
- Dental Surgery:Oral flora contamination risk in implant and periodontal procedures supports niche antimicrobial suture utilization despite limited procedure value.
General surgery anchors baseline volume; orthopedic applications expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyglycolic acid and polydioxanone manufacturing clusters in Shanghai and Ludwigshafen anchor antimicrobial suture supply chains. Hospital procurement consolidation across four major surgical markets is restructuring vendor relationships toward integrated delivery networks.
United States
CMS non-payment policies for hospital-acquired infections drive institutional adoption of infection-prevention devices. FDA biocompatibility standards under ISO 10993 govern cytotoxicity testing for antimicrobial coatings. Academic medical centers in Boston and Cleveland specify coated sutures for cardiac sternal closures to avoid readmission penalties.
Germany
Joint reconstruction volumes and catastrophic infection cost implications fuel antimicrobial closure device demand. EMA's Medical Device Regulation imposes post-market surveillance obligations that extend approval timelines. Chemical manufacturing in Ludwigshafen supplies polyglycolic acid feedstock to European suture producers facing REACH authorization pressures.
Japan
Aging demographics and elevated surgical volume sustain preference for premium wound closure technologies. METI standards alignment with ISO frameworks streamlines domestic device registration. Osaka-based orthopedic surgery units mandate antimicrobial sutures for prosthetic joint implantations under national reimbursement protocols.
India
National health insurance expansion programs scale surgical infrastructure in tier-2 cities, creating ambulatory surgery center volume potential. CDSCO medical device rules govern import and local manufacturing licensing. Gujarat textile engineering clusters supply braided suture substrates to domestic and export markets.
China
Domestic joint replacement procedure growth and infection control standard elevation drive device specification intensity. NMPA medical device registration requirements differentiate imported from locally manufactured products. Shanghai polymer manufacturing facilities supply synthetic absorbable materials to regional suture fabricators.
Antimicrobial Suture Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable antiseptic formulations and ambulatory surgery center penetration. The vendor base structures around three archetypes: diversified surgical portfolio conglomerates, specialized suture manufacturers with regional manufacturing scale, and polymer-focused material suppliers extending into finished devices. Competitive moves concentrate on multi-year supply contract anchoring within integrated delivery networks and regulatory toxicology capability building for EU Green Deal compliance.
Among diversified surgical conglomerates, Johnson & Johnson (Ethicon) and Medtronic exemplify portfolio breadth that enables bundled procurement positioning. B. Braun represents the European manufacturing scale archetype with production node distribution across multiple geographies. Dolphin Sutures and Lotus Surgicals occupy positions within specialized regional fabricator tiers serving price-sensitive ambulatory markets.
| Leading Market Players |
|---|
| Johnson & Johnson (Ethicon) |
| Medtronic |
| B. Braun |
| The Healthium Group |
| Meril Life Sciences |
| Dolphin Sutures |
| Lotus Surgicals |
| Unilene |
| Internacional Farmacéutica |
| Others |
Supply Flow & Price Mechanics
Triclosan-to-chlorhexidine formulation divergence separates premium antimicrobial sutures from commodity-coated alternatives, with this bifurcation manifesting in both contract pricing structures and raw material sourcing configurations. Hospital procurement committees in the United States weight outcome data from clinical registries against unit costs, while EMA MDR compliance burdens in Germany inflate regulatory capital requirements that pass through to European price points.
Pricing Analysis
Warranty and clinical outcome guarantees bundled with multi-year supply contracts anchor premium positioning for integrated delivery networks, whereas unbundled transactional pricing dominates ambulatory surgical center procurement. Pricing stratifies across premium, standard, and economy tiers based on antimicrobial compound certification grade and volume scale commitments. Cost compression in standard absorbable lines intensifies because Chinese manufacturers expand polydioxanone extrusion capacity. Ambulatory surgical centers exhibit acute price sensitivity; academic medical centers with CMS infection penalty exposure show minimal elasticity.
Supply Chain Analysis
Freight cost volatility from Shanghai polymer manufacturing clusters to European conversion facilities compresses margins on absorbable suture imports. Polyglycolic acid feedstock concentrates in Chinese and German chemical manufacturing nodes; polydioxanone monomer production draws from Ludwigshafen and Shanghai facilities. Single-source vulnerability in triclosan active pharmaceutical ingredient supply creates exposure to REACH authorization disruptions. Distribution runs through hospital GPO contracts and specialized surgical device distributors serving outpatient settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antimicrobial suture market sits in active polymer transition, with chlorhexidine-impregnated monofilament platforms displacing legacy surface-coated triclosan formulations across orthopedic and cardiovascular procedure categories.
For Market Incumbents: Hedge against REACH chemical restrictions by accelerating biodegradable antiseptic R&D pipelines and securing dual-source polymer feedstock agreements with Shanghai and Ludwigshafen manufacturers. Backward integration into polyglycolic acid precursor production insulates margin positions from Chinese input cost volatility. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian tier-2 ambulatory surgery centers offers white-space penetration potential under national health insurance expansion programs. Target barbed suture-laparoscopic device bundling for robotic surgery platforms as the most penetrable premium segment. Pursue CDSCO manufacturing licensing partnerships with Gujarat textile engineering clusters to establish domestic production credibility. For Investors and Strategic Acquirers: Re-rating potential sits with specialized suture manufacturers possessing dedicated regulatory toxicology capabilities given ECHA substance evaluation pressures on legacy antiseptic compounds. Long-term viability favors firms with biodegradable formulation pipelines and multi-site clinical registry data. Watch EMA MDR approval timeline compression as the inflection signal for European market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Antiseptic Formulation | EU Green Deal compliance enables continued European market participation under REACH authorization constraints. |
| Hospital System Partnership | Integrated delivery network contracts anchor volume through bundled procurement with stapling and energy devices. |
| CE Marking Pathway | MDR post-market surveillance obligations extend timelines but filter competitor eligibility toward capable manufacturers. |
| Backward Integration | In-house polyglycolic acid production reduces exposure to Chinese chemical manufacturing input volatility. |
| Software Companion Development | Outcome tracking platforms support CMS infection penalty avoidance documentation for United States hospital clients. |
Methodological Framework
Document review covered FDA 510(k) filings, EMA MDR technical documentation, hospital GPO contract databases, and ISO 10993 biocompatibility test standards, complemented by interviews with surgical device procurement managers, biomedical engineers, regulatory affairs specialists, and polymer extrusion manufacturing directors. Secondary validation drew from customs trade data, CMS Medicare cost reports, and CDSCO medical device registration records. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Segment-level value outputs combined absorbability profiles, end-user facility types, and surgical specialty applications across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and reimbursement policy shift timelines. Modeled inputs included joint reconstruction procedure growth rates, REACH chemical authorization schedules, and ambulatory surgery center infrastructure expansion under national health insurance programs.
Underlying measurement precision varies by segment; hospital procurement data carries tighter precision than ambulatory surgical center estimates due to GPO contract transparency. Forecasts reflect assumptions about regulatory timeline stability and polymer feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Biological and Chemical Indicators Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Antiseptic Bathing Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Yeast Infection Market
Infection Control
Disinfection Cupboard Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
Disinfection Equipment Market
Infection Control
Alcohol Wipes Market
Infection Control
Hand Hygiene Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Virus Filtration Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market