

Medical Activated Carbon Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Activated Carbon Dressing Market Insights
The EU Medical Device Regulation is shifting demand toward biocompatible absorbent materials with verified carbon sourcing. Smith+Nephew leverages its wound management portfolio to sustain leadership in antimicrobial dressing categories. ConvaTec Group anchors its position through hydrophilic delivery systems that integrate activated carbon layers for odor control.
Medical activated carbon dressings are composite wound care materials incorporating activated charcoal derived from coconut shell or bamboo at surface areas exceeding 800 m²/g, designed to adsorb exudate, bacteria, and malodorous compounds from chronic and infected wounds. Sheet and pad formats dominate current volume as these configurations conform to standard wound bed geometries and support layered application protocols. Powder and granule segments are gaining traction in deep cavity wounds and tunneling ulcers where conformability requirements exceed flat dressing capabilities.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence standards for manufacturers seeking market access. Japan's PMDA and South Korea's MFDS impose additional biocompatibility testing protocols that filter entrants without established quality management systems. Stakeholders must monitor evolving reimbursement codes for bioactive dressings as payors recalibrate coverage criteria toward outcomes-based wound healing metrics.
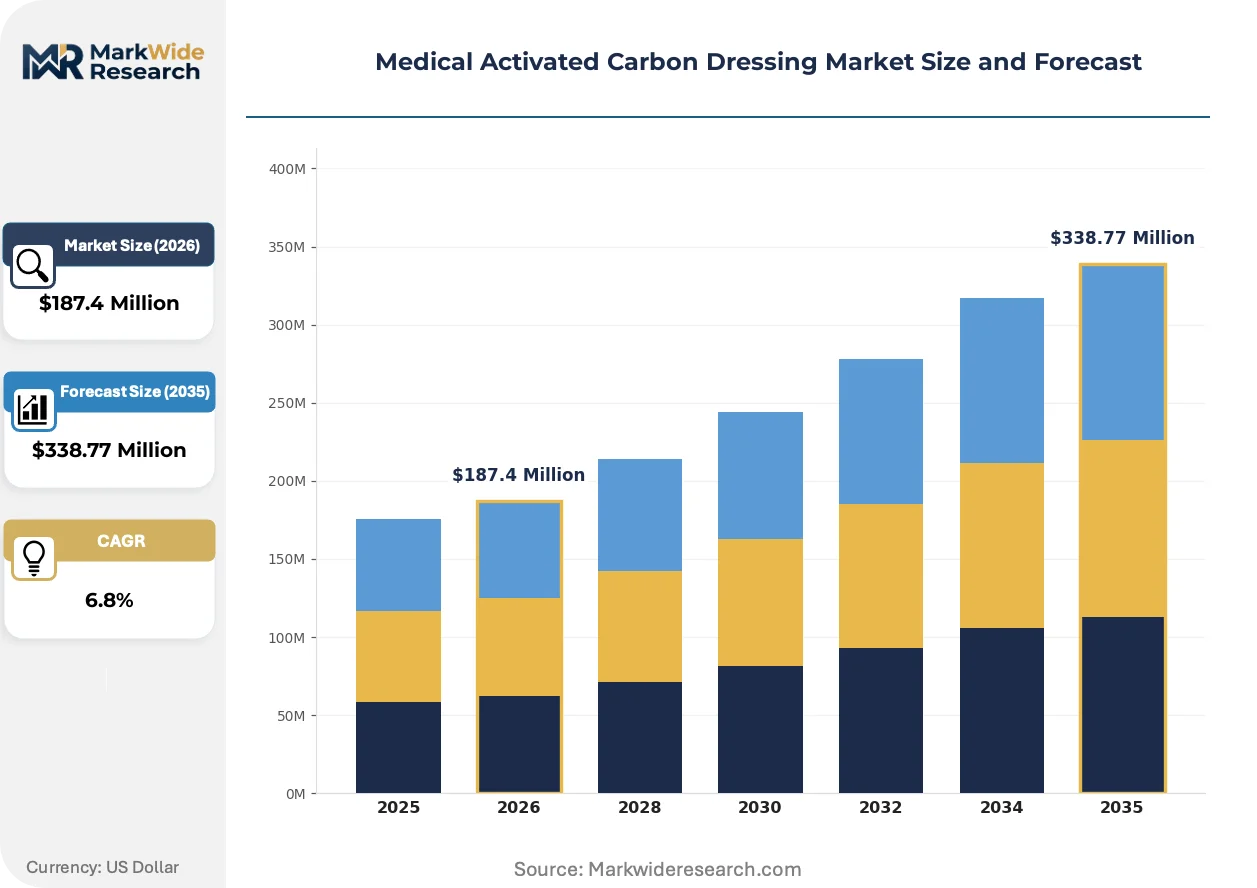
Market Dynamics
The EU Medical Device Regulation's biocompatibility documentation requirements are compressing product development timelines while simultaneously filtering out manufacturers lacking established quality management systems, creating a structural consolidation pressure across the activated carbon dressing supply base.
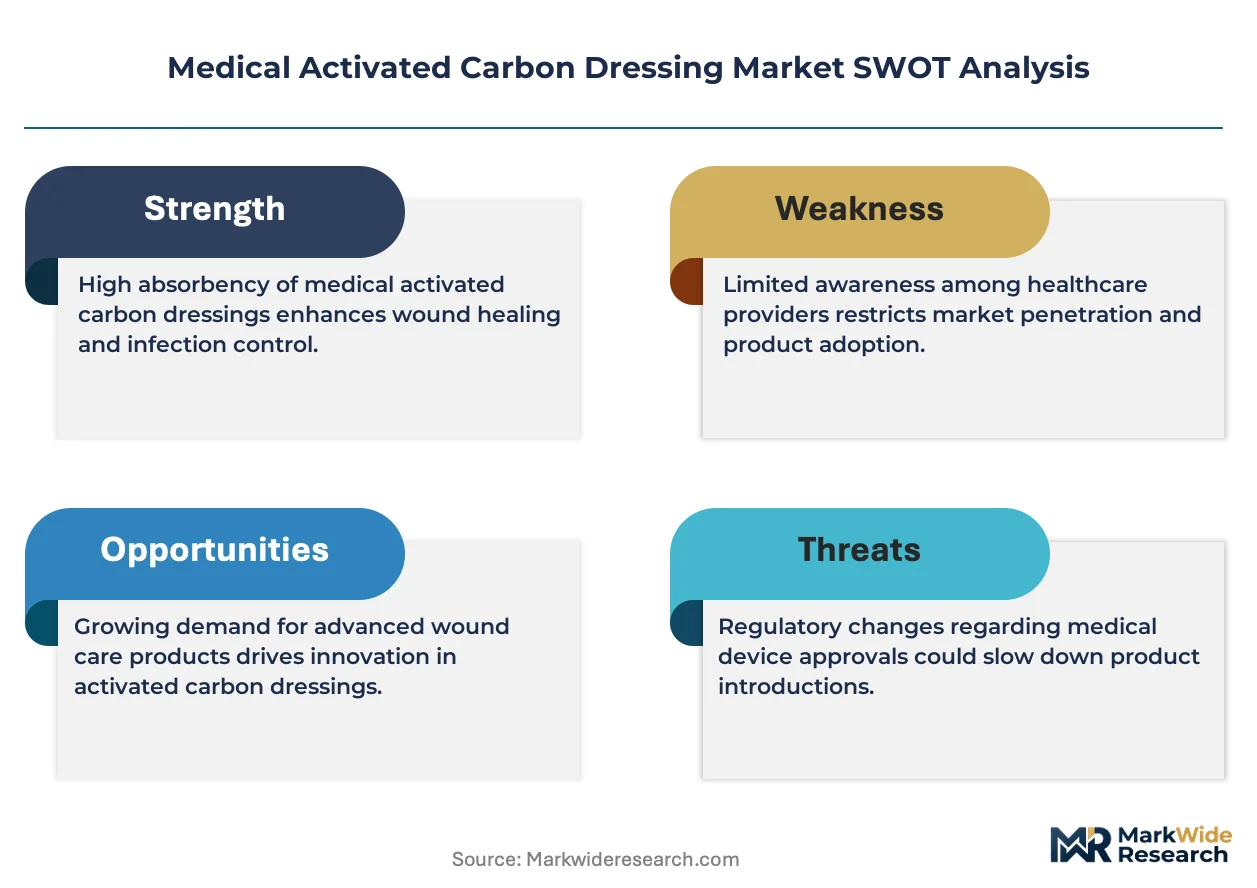
Growth Catalysts
- Chronic wound prevalence:Aging demographics in Germany, Japan, and the United States are expanding the addressable patient population requiring advanced wound management solutions with odor control capabilities.
- FDA 510(k) pathway clarity:Updated medical device classification for antimicrobial dressings provides predictable regulatory timelines that accelerate market access for compliant manufacturers.
- Coconut shell carbon sourcing:Sustainable biomass feedstock availability from Southeast Asian suppliers supports cost-competitive production of high-surface-area activated carbon exceeding 800 m²/g.
Market Restraints
- Input cost volatility:Coconut shell charcoal prices fluctuate with agricultural yield cycles and competing industrial demand from water purification and air filtration sectors.
- Supply concentration risk:Premium-grade activated carbon production clusters among Indonesian and Sri Lankan processors, exposing buyers to geographic disruption vulnerabilities.
- Technical limitation:Activated carbon's black coloration obscures wound bed visualization, complicating clinical assessment protocols and limiting adoption in settings requiring frequent exudate monitoring.
Strategic Opportunities
- Underpenetrated geography:India's expanding hospital infrastructure and CDSCO regulatory harmonization efforts create entry pathways for bioactive dressing manufacturers with established GMP compliance.
- Technology convergence:Integration of activated carbon layers with silver ion delivery systems and hydrophilic foam substrates enables multifunctional dressing platforms commanding premium positioning.
- Distribution innovation:Direct-to-clinic digital procurement platforms in South Korea bypass traditional distributor markups while accelerating product turnover in high-volume wound care centers.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies require 12-18 month completion cycles that delay EU MDR technical documentation submission.
- Legacy EHR integration:Wound documentation systems in United States long-term care facilities lack standardized fields for bioactive dressing performance tracking, complicating outcomes data collection for reimbursement justification.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Activated Carbon Dressing Market Trends and Innovations
Manufacturing automation and regulatory data digitization are compressing development cycles while reshaping competitive requirements for clinical evidence generation and supply chain traceability.
Electrospun nanofiber carrier matrices impregnated with activated carbon particles are automating the precision layering of adsorptive materials onto flexible backing substrates. Contract manufacturers in Germany and Japan are adopting these systems to reduce lot-to-lot variability in carbon distribution density. This automation is compressing the cost differential between manual assembly and continuous roll-to-roll production, enabling mid-scale entrants to achieve quality parity with established wound care suppliers.
REACH substance registration requirements for imported activated carbon are tightening documentation obligations on non-EU manufacturers seeking European market access. The regulation mandates full supply chain disclosure for coconut shell and bamboo feedstock origins, with ECHA enforcement actions targeting incomplete dossiers. Small Asian processors lacking in-house regulatory affairs capabilities are exiting the EU supplier pool, concentrating sourcing relationships among integrated chemical distributors with dedicated compliance infrastructure.
Hospital procurement committees in the United States are consolidating vendor relationships through standardized formulary contracts that bundle antimicrobial dressings with negative pressure wound therapy systems. This preference consolidation disadvantages standalone dressing suppliers lacking portfolio breadth, while favoring wound management platform providers with integrated logistics and clinical training support. The shift is most visible in integrated delivery networks across Texas and Florida, where supply chain rationalization initiatives prioritize single-source accountability for infection prevention product categories.
Medical Activated Carbon Dressing Market Segmentation
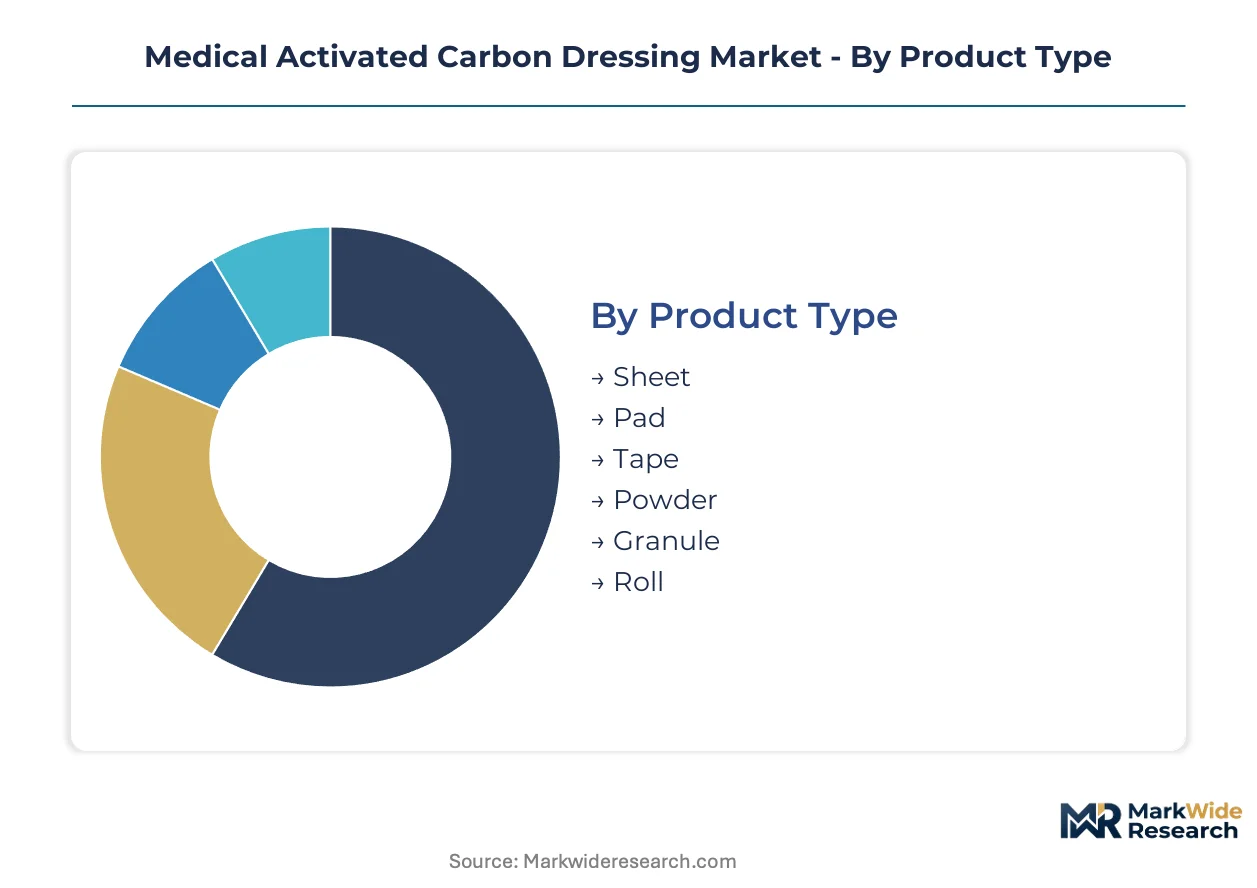
Segmentation in the Medical Activated Carbon Dressing Market reveals how wound geometry, clinical setting, and application protocol dictate material format selection. Manufacturers configure carbon distribution density and backing substrate properties to match specific exudate volumes, wound depths, and frequency of dressing changes.
Product Type:
Supply concentration in flat-format manufacturing favors sheet and pad production, while deep-cavity applications pull investment toward loose-fill alternatives with specialized filling equipment.
- Sheet:Thin, flexible laminates with activated carbon layers bonded to non-woven substrates conform to shallow wound beds and pressure injury sites. Hospital procurement in Germany and the United States favors sheet formats for standardized protocol compliance across nursing staff.
- Pad:Thicker absorbent cores with carbon-impregnated centers manage moderate-to-heavy exudate in diabetic foot ulcers. Demand concentrates in Japan's long-term care facilities where odor control requirements intersect with extended wear time protocols.
- Tape:Narrow carbon-impregnated strips secure secondary dressings and seal periwound margins.
- Powder:Micronized activated carbon blends fill tunneling wounds and undermining cavities where conformability exceeds flat dressing capabilities.
- Granule:Controlled particle size distributions enable precise cavity packing in deep pressure injuries.
- Roll:Continuous carbon-impregnated substrates allow custom cutting for irregular wound geometries in burn centers.
Today's leader: Pad. Tomorrow's challenger: Powder.
Application:
Cost tier differentiation separates high-frequency change protocols in acute burn units from extended-wear applications in chronic wound management.
- Wound Care:General-purpose carbon dressings address exudate and bacterial load in traumatic and surgical wounds. Volume concentrates in United States emergency departments and trauma centers where rapid odor control supports patient dignity and staff compliance.
- Burn Treatment:Specialized low-adherent carbon dressings minimize mechanical trauma during dressing changes on partial-thickness burns. Demand clusters in Germany's specialized burn centers where silver-carbon combination products command premium positioning.
- Ulcer Management:Chronic venous and arterial ulcers require sustained bacterial adsorption over multi-day wear periods.
- Post-Surgical Dressings:Incisional wound protection with carbon layers reduces surgical site infection risk in contaminated procedures.
- Skin Grafts:Carbon-impregnated contact layers manage exudate from donor sites and graft beds without disrupting vascularization.
Wound Care commands current volume. Burn Treatment offers the steepest expansion trajectory as combination antimicrobial-carbon platforms penetrate specialized centers.
End User:
Customer type determines packaging configuration, clinical training requirements, and reimbursement documentation complexity across the delivery chain.
- Hospitals:Integrated delivery networks in Texas and Florida consolidate antimicrobial dressing procurement through formulary contracts bundling carbon dressings with negative pressure wound therapy systems.
- Clinics:Outpatient wound centers prioritize cost-per-change metrics and storage efficiency for high-volume diabetic foot ulcer management.
- Ambulatory Care Centers:Same-day surgical facilities require compact packaging and rapid application protocols.
- Rehabilitation Facilities:Long-term care settings in Japan emphasize odor control and extended wear time to minimize resident disturbance.
- Specialty Care Units:Burn centers and palliative care units demand customized carbon loading densities for specific exudate profiles.
Hospitals dominate procurement volume. Specialty Care Units represent the fastest-climbing segment as palliative wound protocols formalize odor management standards.
Delivery Mode:
Margin structure varies sharply between commodity self-adhesive formats and composite platforms integrating multiple functional layers.
- Self-Adhesive:Pressure-sensitive carbon dressings enable single-operator application in home care and emergency settings. Demand spreads across United States long-term care facilities seeking to reduce skilled nursing time per dressing change.
- Non-Adhesive:Carbon-impregnated contact layers require secondary retention but minimize trauma on fragile periwound skin. Preference concentrates in Germany's dermatology clinics treating epidermolysis bullosa and other fragility disorders.
- Hydrophilic:Moisture-activated carbon release systems enhance exudate spreading and adsorption kinetics.
- Hydrophobic:Water-repellent carbon barriers protect surrounding skin in heavily exuding wounds.
- Composite Dressings:Multi-layer platforms combining carbon, foam, and silver elements command premium positioning in complex wound protocols.
Self-Adhesive holds installed base dominance. Composite Dressings gain share fastest as technology convergence justifies reimbursement premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale activated carbon production for medical applications during the 1980s, establishing quality benchmarks that shaped subsequent regulatory frameworks across wound care markets worldwide.
United States
Integrated delivery networks in Texas and Florida drive hospital procurement consolidation for antimicrobial dressings. FDA 510(k) pathway updates provide predictable regulatory timelines for manufacturers seeking market access. Greater Boston hosts specialized wound care research clusters advancing combination dressing platforms.
Germany
Specialized burn centers in Bavaria and North Rhine-Westphalia command premium positioning for silver-carbon combination products. EU MDR biocompatibility documentation requirements filter manufacturers lacking established quality management systems. The Eindhoven Region supply corridor feeds carbon sourcing relationships with dedicated compliance infrastructure.
Japan
Long-term care facilities prioritize odor control and extended wear time protocols for aging demographics. PMDA biocompatibility testing protocols impose additional quality filters on market entrants. Kanto region wound management specialists anchor demand for pad-format carbon dressings in institutional settings.
India
Expanding hospital infrastructure and CDSCO regulatory harmonization efforts create entry pathways for bioactive dressing manufacturers. Kerala and Maharashtra clusters demonstrate early adoption of advanced wound care protocols in private hospital chains. GMP compliance capabilities separate viable entrants from commodity suppliers.
South Korea
Direct-to-clinic digital procurement platforms bypass traditional distributor markups in high-volume wound care centers. MFDS biocompatibility testing requirements align with international standards while filtering quality-system deficiencies. Seoul Capital Area medical device distributors accelerate product turnover through consolidated logistics networks.
Medical Activated Carbon Dressing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance capabilities and clinical evidence portfolios. The vendor base stratifies into three tiers: multinational wound management platforms with integrated logistics, regional specialists with focused antimicrobial dressing portfolios, and contract manufacturers supplying private-label carbon layers. Two dominant competitive moves define current positioning: technology convergence through silver-carbon-foam combination platforms, and geographic expansion into underpenetrated Asian hospital networks.
Among UK-based multinationals, Smith+Nephew and ConvaTec Group exemplify platform-scale positioning through wound management portfolio breadth. Coloplast represents the specialized tier with focused expertise in chronic care segments. These three entities anchor competitive dynamics by demonstrating how regulatory compliance infrastructure and clinical training capabilities separate sustainable market presence from transactional supply relationships.
| Leading Market Players |
|---|
| Smith+Nephew |
| ConvaTec Group |
| Coloplast |
| Mölnlycke Health Care |
| 3M |
| Cardinal Health |
| Medline Industries |
| Hollister Incorporated |
| DermaRite Industries |
| Others |
Pricing and Supply Chain Analysis
Backward integration into coconut shell carbon sourcing anchors both supply security and margin protection for wound care manufacturers navigating volatile agricultural feedstock markets. This upstream control over activated carbon production clusters in Indonesia and Sri Lanka determines who captures value when raw material costs spike from competing industrial demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared combination dressings with silver ion delivery from basic carbon-impregnated pads and commodity private-label alternatives. Price differentiation hinges on ISO 10993 biocompatibility certification tier and clinical evidence depth supporting reimbursement claims. Cost compression in the economy tier intensifies as Indonesian processors lacking REACH compliance infrastructure exit the EU supplier pool. Outpatient wound centers exhibit highest price sensitivity, while Germany's specialized burn centers absorb premium positioning for odor-control performance.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Sri Lankan coconut shell carbon processors who feed 80% of medical-grade activated carbon exceeding 800 m²/g surface area specifications. Raw material dependencies encompass Southeast Asian agricultural yields, German electrospun nanofiber carrier matrices, and Japanese hydrophilic foam substrates. Supply chain risk centers on ECHA enforcement actions targeting incomplete REACH substance registration dossiers. Distribution runs through integrated delivery networks in Texas and Florida that bundle antimicrobial dressings with negative pressure wound therapy systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as aging demographics in Germany, Japan, and the United States expand the chronic wound patient pool requiring odor management solutions. Hospital procurement consolidation favors platform-scale suppliers with integrated logistics and clinical training infrastructure.
For Market Incumbents: Anchor market position through exclusive formulary contracts with integrated delivery networks in Texas and Florida that bundle carbon dressings with negative pressure wound therapy systems. Deepen backward integration into Indonesian coconut shell carbon processing to secure feedstock priority during agricultural yield cycles. Invest in ISO 10993 biocompatibility documentation infrastructure to accelerate EU MDR technical dossier submission timelines ahead of smaller competitors. For New Entrants and Emerging Players: Hospital procurement committees in India's Kerala and Maharashtra clusters represent the most penetrable entry point where CDSCO regulatory harmonization and expanding private hospital infrastructure create first-mover advantages. Target powder and granule formats for deep cavity wounds where conformability requirements exceed flat dressing capabilities and competition from established players remains sparse. Build direct relationships with contract manufacturers in Germany and Japan adopting electrospun nanofiber automation to achieve quality parity without capital-intensive production facilities. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR biocompatibility documentation requirements filter manufacturers lacking established quality management systems, compressing the viable supplier base to platform-scale players and specialized regionalists. Acquisition targets include mid-tier wound care specialists with FDA 510(k) clearances and established GMP compliance but limited geographic reach. Watch for CDSCO regulatory harmonization completion in India as the inflection signal triggering accelerated hospital procurement of advanced wound care products.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access through predictable regulatory timelines for antimicrobial dressing classifications. |
| CE Marking Pathway | EU MDR technical documentation compliance filters competitors lacking ISO 10993 biocompatibility portfolios. |
| Hospital System Partnership | Formulary bundling with negative pressure wound therapy systems locks out standalone dressing suppliers. |
| Backward Integration | Captive coconut shell carbon sourcing secures feedstock priority during Southeast Asian agricultural yield cycles. |
| Reimbursement Strategy | Outcomes-based wound healing metrics alignment secures favorable coverage codes for bioactive dressing categories. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and South Korea, with primary inputs from each market informing demand calibration and regulatory pathway mapping. The research combines interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and wound care clinicians with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CDSCO regulatory harmonization notices, and hospital procurement contract records. Bottom-up patient population modeling and top-down manufacturer revenue triangulation cross-verify segment-level estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models product type, application protocol, end-user facility type, and delivery mode dimensions alongside regional regulatory cluster differentiation. CAGRs derive from logistic diffusion curves fitted to chronic wound prevalence trajectories and hospital procurement adoption patterns. Industry-specific forecast inputs include PMDA biocompatibility testing completion timelines and REACH substance registration enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to coconut shell charcoal agricultural yield volatility and EU MDR documentation requirement evolution. Forecasts reflect underlying assumptions about reimbursement code stability and infection control protocol tightening without claiming certainty against macroeconomic or regulatory revision. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.