
 Home Appliances Glass Market | 2026-2036
Home Appliances Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Home Appliances Glass Market Intelligence
The supply of technicians skilled in advanced glass coating and tempering processes is collapsing the time-to-market for new appliance designs. Schott AG leverages its expertise in specialty borosilicate glass to serve premium oven and cooktop segments. Saint-Gobain differentiates through its global manufacturing footprint and extensive product portfolio for major appliance OEMs. Corning Incorporated competes with its chemically strengthened glass solutions, targeting high-impact applications like interactive refrigerator doors.
Home appliances glass refers to thermally or chemically treated safety glass, including tempered and laminated variants, designed for use in household devices. This material must withstand significant thermal shock, mechanical stress, and chemical exposure while providing aesthetic and functional surfaces. Tempered glass remains the dominant product type due to its safety profile and cost-effectiveness in ovens and washers. However, demand for coated glass, particularly with Low-E coatings for improved thermal insulation, is accelerating in high-end refrigerator and microwave applications.
Safety and material standards are governed by regulations like the EU's RoHS directive restricting hazardous substances and the US CPSC's safety standards for glass in specific applications. These frameworks, alongside China's GB standards for safety glass, directly influence material selection and testing protocols for manufacturers. Stakeholders must now decide whether to invest in recycling infrastructure for complex coated glass or focus on developing more sustainable, mono-material alternatives.
Market Dynamics
The central tension in the home appliances glass market is the collision between consumer demand for seamless, all-glass aesthetics in smart devices and the stringent energy efficiency mandates that require complex, often costly, multi-layer coatings on those same surfaces.
Growth Catalysts
- Energy Efficiency Mandates:The EU's Ecodesign Directive and similar global regulations are compelling the use of advanced Low-E coatings on refrigerator and oven glass to reduce energy consumption, directly stimulating demand for coated glass products.
- Premium Appliance Segment:Consumer appetite for high-performance cooking appliances drives the adoption of specialty materials like borosilicate glass in premium oven doors and cooktops, valued for its superior thermal shock resistance and durability.
- Manufacturing Consolidation:Demand for appliance glass is concentrating in industrial hubs within China and Germany, where large-scale, export-oriented appliance manufacturing creates a consistent and high-volume procurement base for glass suppliers.
Market Restraints
- High Energy Inputs:The glass tempering and coating processes are exceptionally energy-intensive, exposing manufacturers to significant margin pressure from volatile electricity and natural gas prices, particularly in regions like Europe.
- Substitution from Polymers:In non-critical or structural components of appliances, high-performance engineering polymers and metal composites present a substitution threat, offering lower weight and different form factors than traditional glass.
- Specialized Production Expertise:The production of advanced coated and chemically strengthened glass is concentrated among a few global specialists, creating potential supply bottlenecks and limiting the bargaining power of smaller appliance OEMs.
Strategic Opportunities
- Interactive Surfaces:The integration of touch controls, sensors, and transparent displays into refrigerator doors and oven panels creates a significant opportunity for glass with advanced electronic and optical coatings.
- Emerging Market Penetration:Rising disposable incomes in countries like India and Brazil, coupled with government incentives like India's PLI scheme for white goods, create new growth frontiers for appliance and component manufacturers.
- Antimicrobial Glass:Growing consumer focus on hygiene presents an opportunity for glass treated with antimicrobial coatings for use on high-touch surfaces like microwave doors, refrigerator handles, and control panels.
Industry Challenges
- Recycling Complexity:The multi-material composition of coated and laminated appliance glass makes it difficult and uneconomical to recycle, posing a significant challenge to manufacturers' circular economy and sustainability objectives.
- Skilled Labor Scarcity:A shortage of technicians with expertise in operating and maintaining sophisticated vacuum deposition coating lines and advanced tempering furnaces can constrain production expansion and quality control.
- Capital Expenditure Requirements:Establishing or upgrading production lines for specialty glass, particularly for large-format coated panes used in modern refrigerators, requires substantial capital investment in furnaces and cleanroom environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Appliances Glass Market |
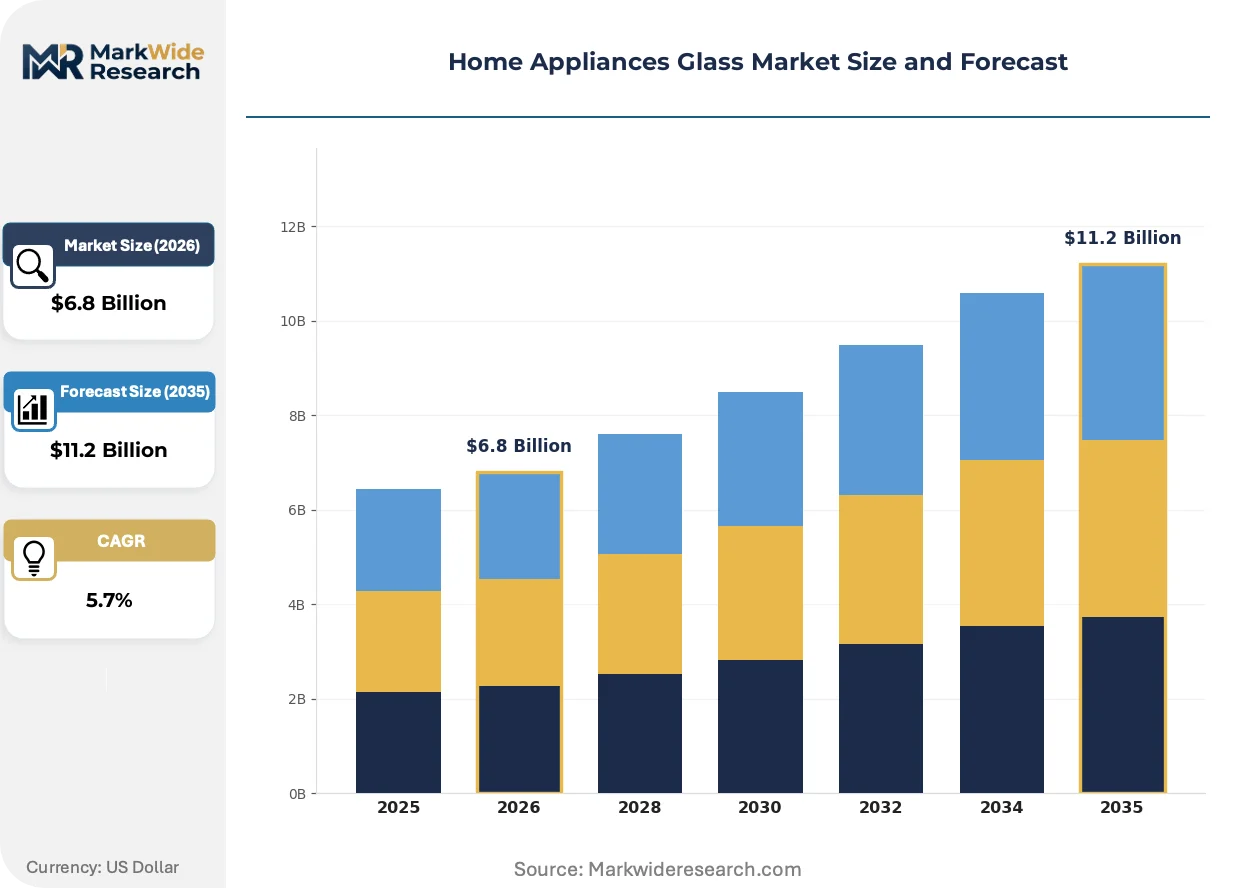
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Coated Glass, Double Glazed Glass Application: Refrigerators, Microwaves, Ovens, Washers Technology: Low-E Coating, Reflective Coating, Anti-Fog Coating, UV Protection End User: Manufacturers, Retailers, Distributors, Individuals |
| Companies Covered | Corning Incorporated, Guardian Industries Holdings, Schott AG, Glaston Corporation, Nippon Sheet Glass Co. Ltd., Saint-Gobain, Nippon Electric Glass Co. Ltd., NSG Group, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Appliances Glass Market Strategic Shifts & Innovations
Material science is being pushed by dual demands for enhanced functional performance and deeper digital integration. This forces glass to evolve from a simple passive barrier into an active, multi-functional substrate central to the appliance's user experience and energy efficiency.
Multi-functional coatings that combine low-emissivity, anti-reflection, and hydrophobic properties onto a single glass substrate are a key innovation. Premium appliance manufacturers are rapidly adopting these integrated solutions for high-end oven and refrigerator models to improve both performance and aesthetics. This development is decomposing the traditional bill of materials, where separate films or components previously delivered these distinct functions.
China's GB standards for safety glass in home appliances are directly influencing global supply chains. These regulations impose rigorous testing for thermal shock and mechanical impact, setting a high bar for quality. This particularly affects glass destined for oven doors and induction cooktops, forcing global manufacturers with production facilities in China to align their quality assurance protocols with these stringent domestic requirements.
Appliance OEMs are altering their sourcing patterns, showing a clear preference for complete, pre-assembled glass modules over raw glass panes. This shift disrupts the traditional component supplier model, favoring vertically integrated glass processors who can deliver a finished smart door with embedded electronics and displays. This pattern is most visible in the North American and European premium appliance segments.
Home Appliances Glass Market Segmentation
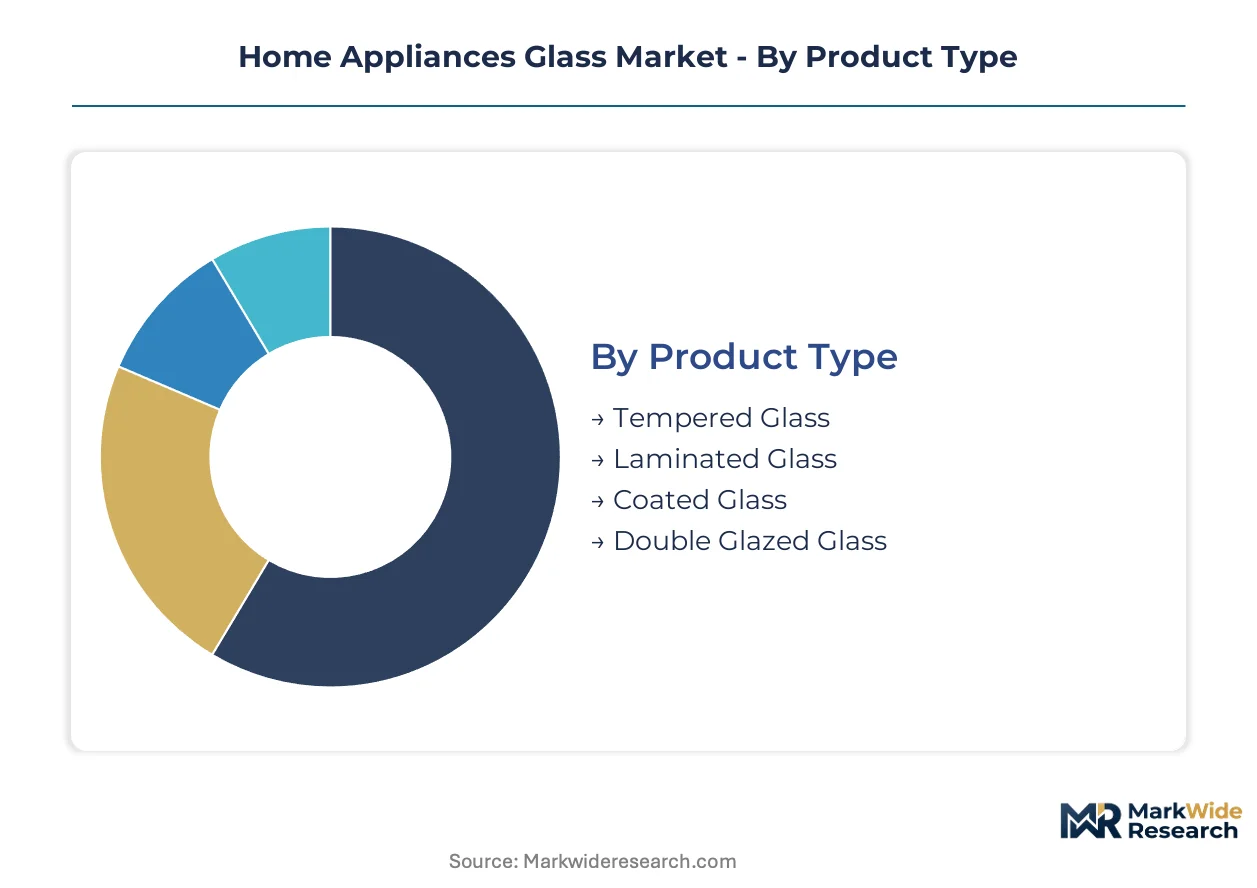
The Home Appliances Glass Market segmentation provides a granular view of material types, their end-use applications, and the specialized technologies driving product evolution. This detailed breakdown helps stakeholders understand where value accrues and how regulatory pressures influence material selection. The analysis highlights critical areas for innovation and market penetration.
Product Type:
Global demand for home appliances glass shows distinct geographic patterns, with certain product types dominating domestic markets while others are designed for export-oriented manufacturing hubs.
- Tempered Glass:This safety glass undergoes thermal treatment to enhance its strength and fracture resistance, breaking into small, blunt pieces upon impact. Demand is particularly strong in China and Germany for oven doors and cooktops, driven by stringent safety regulations and high-volume appliance production.
- Coated Glass:Coated glass incorporates thin-film layers to modify optical and thermal properties, such as low-emissivity for insulation or anti-reflection for aesthetic appeal. European appliance manufacturers increasingly demand coated glass for high-end refrigerators and smart ovens, compelled by the EU's Ecodesign Directive.
- Laminated Glass:Laminated glass layers multiple panes with an interlayer, offering enhanced safety and sound dampening for specialized appliance applications.
- Double Glazed Glass:Double glazed glass uses two panes separated by a gas or vacuum, providing thermal insulation for energy-efficient oven doors.
Tempered Glass commands the established base. The steepest expansion runs through Coated Glass.
Application:
The functional requirements of home appliances dictate specific glass properties, influencing material selection and design complexity across different end-use categories.
- Refrigerators:Glass in refrigerators includes shelves, interior panels, and increasingly, interactive smart doors with integrated displays. Demand for these advanced glass solutions is accelerating in North America and Europe, driven by consumer preference for seamless aesthetics and smart home integration.
- Ovens:Oven glass must withstand extreme thermal shock and high temperatures, typically employing tempered or borosilicate glass for doors and control panels. Safety standards in countries like China and the US mandate robust glass for these high-heat applications.
- Microwaves:Glass for microwaves primarily serves as transparent doors and interior plates, requiring durability and resistance to heat and chemical exposure.
- Washers:Washers utilize glass for transparent doors, needing high impact resistance and chemical durability against detergents.
Ovens represent a mature application segment. Refrigerators are gaining share fastest due to smart features.
Technology:
Advanced coating technologies provide specific functional enhancements to home appliances glass, transforming passive components into active elements.
- Low-E Coating:Low-emissivity coatings minimize heat transfer, crucial for energy-efficient appliances like refrigerators and ovens by reflecting infrared radiation. Regulatory mandates, such as the EU's Ecodesign Directive, significantly stimulate demand for Low-E glass in European manufacturing.
- Reflective Coating:Reflective coatings manage light and heat, often used for aesthetic purposes or to reduce glare on appliance displays and oven doors. Major appliance OEMs in Germany and Japan specify these coatings for premium product lines.
- Anti-Fog Coating:Anti-fog coatings prevent condensation build-up on glass surfaces, enhancing visibility in humid environments or during rapid temperature changes.
- UV Protection:UV protection coatings block harmful ultraviolet radiation, safeguarding internal components and food items from degradation.
Low-E Coating technology is experiencing the most rapid adoption. Reflective Coating maintains a consistent demand in premium segments.
End User:
The distribution of home appliances glass reflects diverse procurement strategies, from direct OEM supply to retail channels for replacement parts.
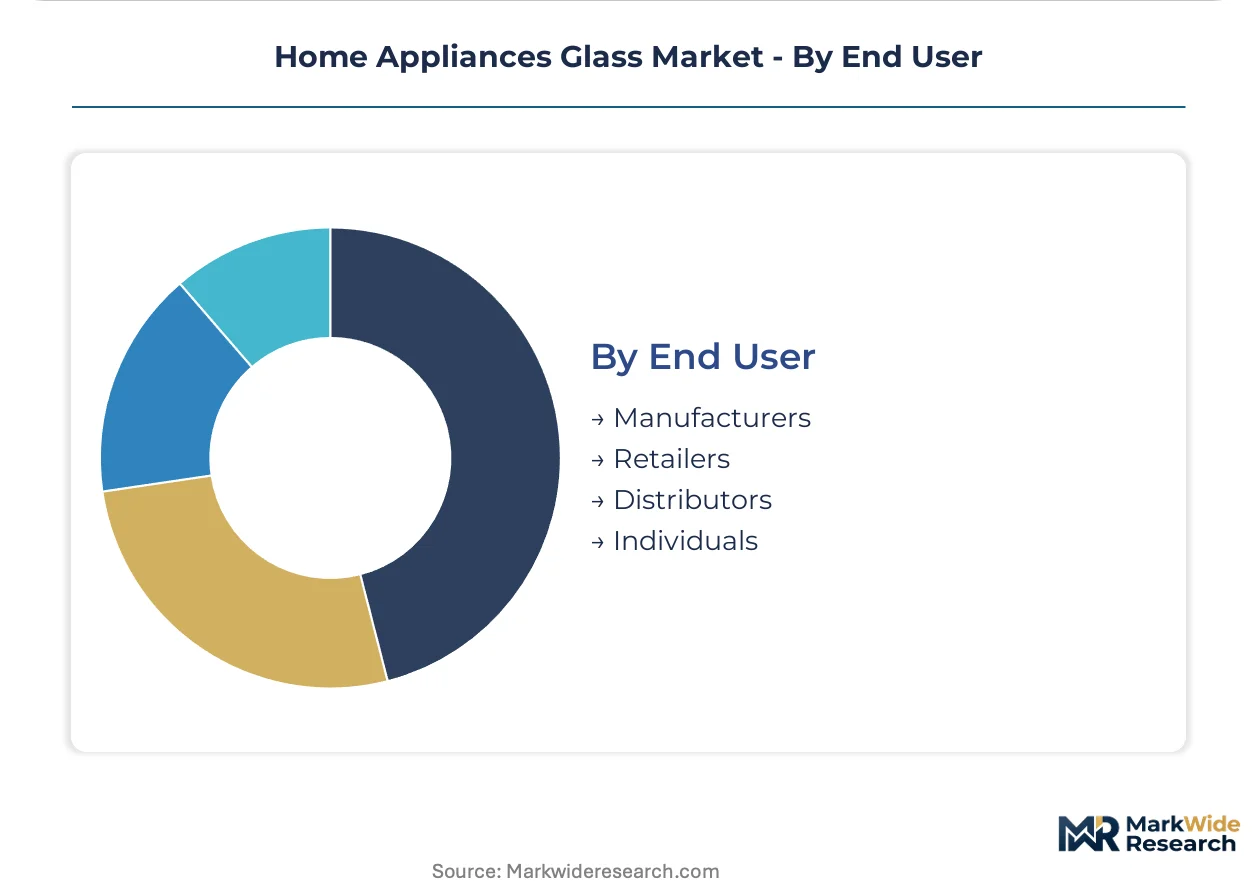
- Manufacturers:Appliance manufacturers represent the largest end-user segment, procuring glass components directly for integration into their production lines. This demand concentrates in major manufacturing hubs like China and Germany for both domestic and export models.
- Retailers:Retailers serve as a crucial channel for aftermarket glass components and replacement parts, catering to individual consumers and repair services. The North American market shows consistent demand for retail-supplied glass due to a large installed base.
- Distributors:Distributors facilitate the flow of glass components from producers to smaller manufacturers or specialized repair shops, often managing complex logistics.
- Individuals:Individual consumers purchase glass directly for DIY repairs or custom appliance projects, though this segment remains relatively small.
Manufacturers drive the bulk of volume. Retailers are seeing sustained growth in replacement markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global home appliances glass market exhibits varied consumption patterns, with some regions prioritizing energy efficiency while others focus on smart features. European manufacturers, for instance, emphasize advanced Low-E coatings due to stringent environmental policies. Asian markets, conversely, are driven by high-volume production and a rising middle class.
China
Demand for tempered glass in China is strong for oven doors and cooktops, driven by high-volume appliance production. China's GB standards for safety glass impose rigorous thermal shock and impact testing. Manufacturing hubs in the Yangtze River Delta concentrate glass processing facilities for export markets.
Germany
German appliance manufacturers increasingly demand coated glass for high-end refrigerators and smart ovens, compelled by the EU's Ecodesign Directive. Reflective coatings are specified for premium product lines by major OEMs. Production clusters in Bavaria integrate advanced glass solutions into export-oriented appliance designs.
United States
Consumer preference for seamless aesthetics and smart home integration drives demand for advanced glass solutions in refrigerators across the United States. The US CPSC's safety standards influence material selection. The Midwest region, particularly around Ohio, hosts significant appliance manufacturing and related glass supply chains.
Japan
Major appliance OEMs in Japan specify reflective coatings for premium product lines, enhancing aesthetic appeal and reducing glare. JIS standards for industrial products ensure high quality for glass components. The Kanto region, including Tokyo, serves as a hub for advanced appliance design, integrating sophisticated glass technologies.
India
Rising disposable incomes in India, coupled with government incentives like India's PLI scheme for white goods, create new growth frontiers. This stimulates demand for both basic tempered glass and increasingly, coated variants. Industrial zones in Maharashtra and Gujarat are expanding their capacity for appliance assembly.
Home Appliances Glass Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for home appliances glass. The market structure features a tiered hierarchy, with large-scale glass producers at the top. These companies often operate as full-service providers for major appliance OEMs. Strategic archetypes include global diversified glass manufacturers and specialized high-performance glass innovators. Dominant competitive moves involve capacity expansion in key manufacturing hubs and strategic partnerships to develop advanced coating technologies.
Within the global diversified glass manufacturers archetype, Saint-Gobain and AGC Inc. exemplify extensive product portfolios and global manufacturing footprints. These industry leaders serve major appliance OEMs across various geographies, including North America and Europe. Schott AG represents specialized high-performance glass innovators, leveraging expertise in borosilicate glass for premium oven and cooktop applications. These companies focus on delivering complete, pre-assembled glass modules, often with embedded electronics, to meet the increasing demand for interactive surfaces and energy-efficient designs in modern appliances.
| Leading Market Players |
|---|
| Corning Incorporated |
| Guardian Industries Holdings |
| Schott AG |
| Glaston Corporation |
| Nippon Sheet Glass Co. Ltd. |
| Saint-Gobain |
| Nippon Electric Glass Co. Ltd. |
| NSG Group |
| AGC Inc. |
| Others |
Cost & Logistics Intelligence
Appliance manufacturing lead times, particularly for premium models, directly influence glass component pricing and supply chain agility. This sensitivity to delivery schedules grants bargaining power to vertically integrated glass processors.
Pricing Analysis
Long-term offtake agreements characterize the dominant pricing model for specialty glass components supplied to major appliance OEMs. Price differentiation stems from the level of coating complexity and the volume scale of procurement. Cost compression in standard tempered glass is intensifying due to overcapacity in basic glass production from China. Smaller appliance manufacturers exhibit the highest price sensitivity, while premium segment brands prioritize performance and reliable supply over marginal cost savings.
Supply Chain Analysis
Just-in-time inventory strategies dominate for high-volume, standardized glass components, while strategic stockpiles are often maintained for specialized coated glass. Geographic supply concentration centers on China, Germany, and the United States for finished appliance glass modules. The industry sources key inputs like silica sand, soda ash, and specialized coating chemicals. Commodity price volatility in natural gas, essential for glass tempering, represents a significant structural risk. Direct supply from glass processors to appliance manufacturers forms the primary distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home appliances glass market faces a shortage of specialized talent, particularly technicians skilled in advanced vacuum deposition coating lines. This scarcity of expertise defines strategic opportunities and competitive dynamics.
For Market Incumbents:Fortify core positions by investing in next-generation coating technologies and expanding capacity in strategic manufacturing hubs like Germany. This counters the threat of substitution from polymers in non-critical applications and addresses margin pressure from energy inputs. Deepen backward integration into specialized raw material sourcing to secure supply. Enhance certification investment for Low-E coatings to maintain regulatory compliance leadership.
For New Entrants and Emerging Players:Differentiate on specialized coatings for interactive surfaces, targeting the premium refrigerator and oven segments. Focus on niche applications like antimicrobial glass for high-touch microwave doors, representing a white-space opportunity. The most penetrable segment lies within emerging markets like India, driven by rising disposable incomes. A direct-to-OEM sales model, emphasizing co-development, offers a strong go-to-market angle.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core glass manufacturing assets. The sector demonstrates long-term viability driven by continuous innovation in energy efficiency and smart home integration. Specialized high-performance glass innovators, particularly those with advanced coating IP, represent a prime acquisition archetype. A sustained increase in R&D spending by major appliance OEMs on smart glass features signals market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Coating Technology R&D | Developing multi-functional coatings enhances glass performance and meets EU Ecodesign Directive requirements for appliances. |
| Global Manufacturing Footprint Expansion | Establishing production in China and Germany serves major appliance manufacturing hubs and reduces logistics costs. |
| Strategic Partnerships with OEMs | Collaborating with appliance manufacturers on integrated glass modules secures long-term supply contracts and design influence. |
| Specialized Borosilicate Glass Capacity | Increasing output for borosilicate glass addresses growing demand in premium oven and cooktop segments. |
| Skilled Labor Development Programs | Addressing the scarcity of technicians for coating and tempering processes ensures production stability and quality control. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, and production managers at major glass manufacturers anchored the qualitative base. This primary data was validated through extensive secondary research, including appliance OEM annual reports, industry association publications, and trade statistics from China customs. A rigorous bottom-up and top-down triangulation process ensured data consistency. Publicly available technical specifications for appliance glass provided further validation.
Sensitivity analysis was applied to key market variables, assessing their impact on projected growth trajectories across the analysis window. The analytical framework modeled segmentation by product type, application, technology, and regional regulatory mandates. Compound annual growth rates were derived from historical trends and anticipated technological advancements. Appliance production volumes and energy efficiency targets served as crucial industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant shifts in global trade policies or raw material supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding technological adoption rates and regulatory enforcement. Revision becomes warranted when appliance manufacturing output in key regions crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
North America Major Home Appliances Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Sweden Home Appliances Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
China Home Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Canada Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Middle East and Africa Home Appliances Market