
 Sweden Home Appliances Market | 2026-2036
Sweden Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Home Appliances Market Analytics
CE marking under the EU Ecodesign Framework is unwinding competitive access for non-compliant manufacturers across Sweden. Electrolux AB leverages its domestic manufacturing footprint and deep R&D heritage to anchor premium positioning in built-in kitchen segments. Samsung Electronics competes through smart appliance ecosystems that integrate with Nordic energy management platforms. BSH Hausgeräte GmbH differentiates via specialized cooking technologies tailored to Scandinavian culinary preferences.
Sweden home appliances comprise electrically powered domestic equipment designed for food preservation, textile care, surface cleaning, and thermal food preparation, typically operating at 230V/50Hz with energy efficiency ratings scaled from A to G under EU harmonized standards. Refrigerators and washing machines occupy the largest product volumes, though smart appliances and IoT-enabled units capture expanding margin pools as Swedish consumers prioritize connected home energy optimization. Energy efficient technology leads unit shipments, while conventional appliances face structural decline in urban replacement cycles.
The Swedish Energy Agency enforces EU Ecodesign and Energy Labelling regulations, while the Swedish Chemicals Agency monitors REACH compliance for appliance materials, collectively raising baseline costs but filtering out low-efficiency imports. Boverket's building codes indirectly shape appliance demand by mandating energy performance in new residential construction. Stakeholders must monitor how EU F-Gas Regulation revisions affect refrigeration technology roadmaps and whether Sweden's national carbon reduction targets accelerate electrification subsidies for appliance replacements.
Market Dynamics
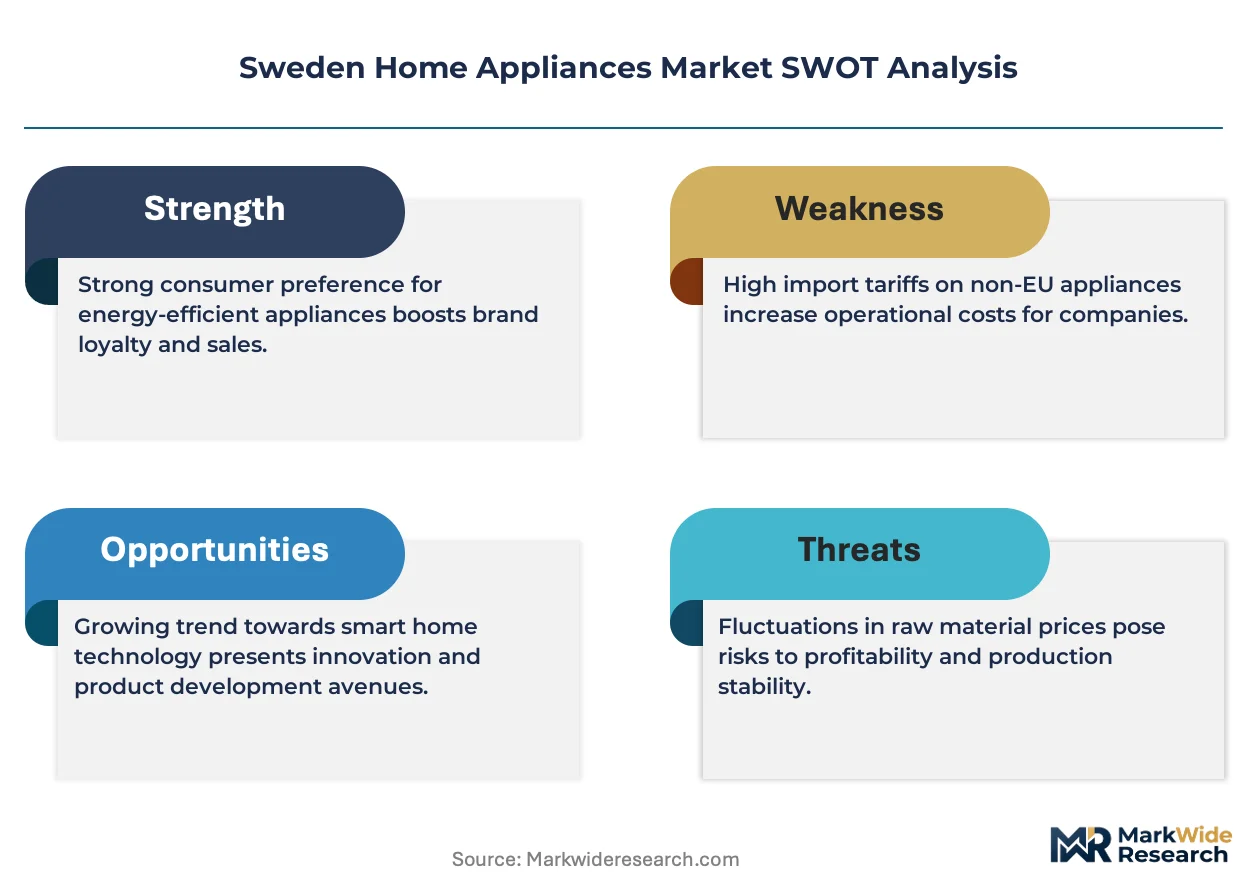
The Swedish home appliances sector is pivoting around the EU Ecodesign Directive's escalating efficiency mandates, which are systematically filtering out low-grade imports while forcing domestic manufacturers to accelerate modular platform redesigns.
Growth Catalysts
- Energy Labelling Revisions:The EU's A-to-G rating recalibration under Ecodesign is compelling Swedish households to replace legacy refrigeration units ahead of functional end-of-life, compressing replacement cycles in Stockholm's renovation corridors.
- Stockholm Metropolitan Density:Housing stock modernization in Sweden's capital region is outpacing national averages, concentrating premium built-in appliance demand within a 150-kilometer radius that rewards localized distribution networks.
- Heat Pump Integration:Swedish HVAC-electrification subsidies are creating bundled procurement opportunities where appliance vendors pair washing machines and dryers with residential heat pump installations.
Market Restraints
- Copper and Rare Earth Input Volatility:Motor and compressor manufacturing faces cost pressure from concentrated Chilean copper supply and Chinese rare earth processing dominance, squeezing margin on mid-tier Swedish appliance production.
- F-Gas Phase-Down Timeline:The EU F-Gas Regulation's hydrofluorocarbon quotas are forcing refrigeration OEMs to accelerate capital-intensive natural refrigerant transitions before cost curves flatten.
- Import Compliance Friction:Non-EU manufacturers lacking CE marking infrastructure are structurally excluded from Swedish retail channels, limiting price competition at the economy tier.
Strategic Opportunities
- Gothenburg Second-City Expansion:Western Sweden's industrial corridor shows underpenetrated smart appliance adoption relative to Stockholm, offering first-mover positioning in connected home energy management.
- Grid-Responsive Appliance Mandates:Sweden's national carbon reduction targets are expected to expand electrification subsidies toward demand-flexible washing machines and dishwashers that synchronize with Nordic spot electricity pricing.
- AI-Enabled Predictive Maintenance:Convergence of onboard appliance sensors with Nordic energy platform APIs is creating subscription revenue streams that decouple service monetization from hardware sales.
Industry Challenges
- Embedded Software Certification:Swedish appliance OEMs face extended validation timelines for cybersecurity compliance under the EU Cyber Resilience Act, delaying product launches by 8-14 months.
- Legacy System Integration:Smart appliance rollouts require backward compatibility with Sweden's heterogeneous residential building automation standards, fragmenting R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Home Appliances Market |
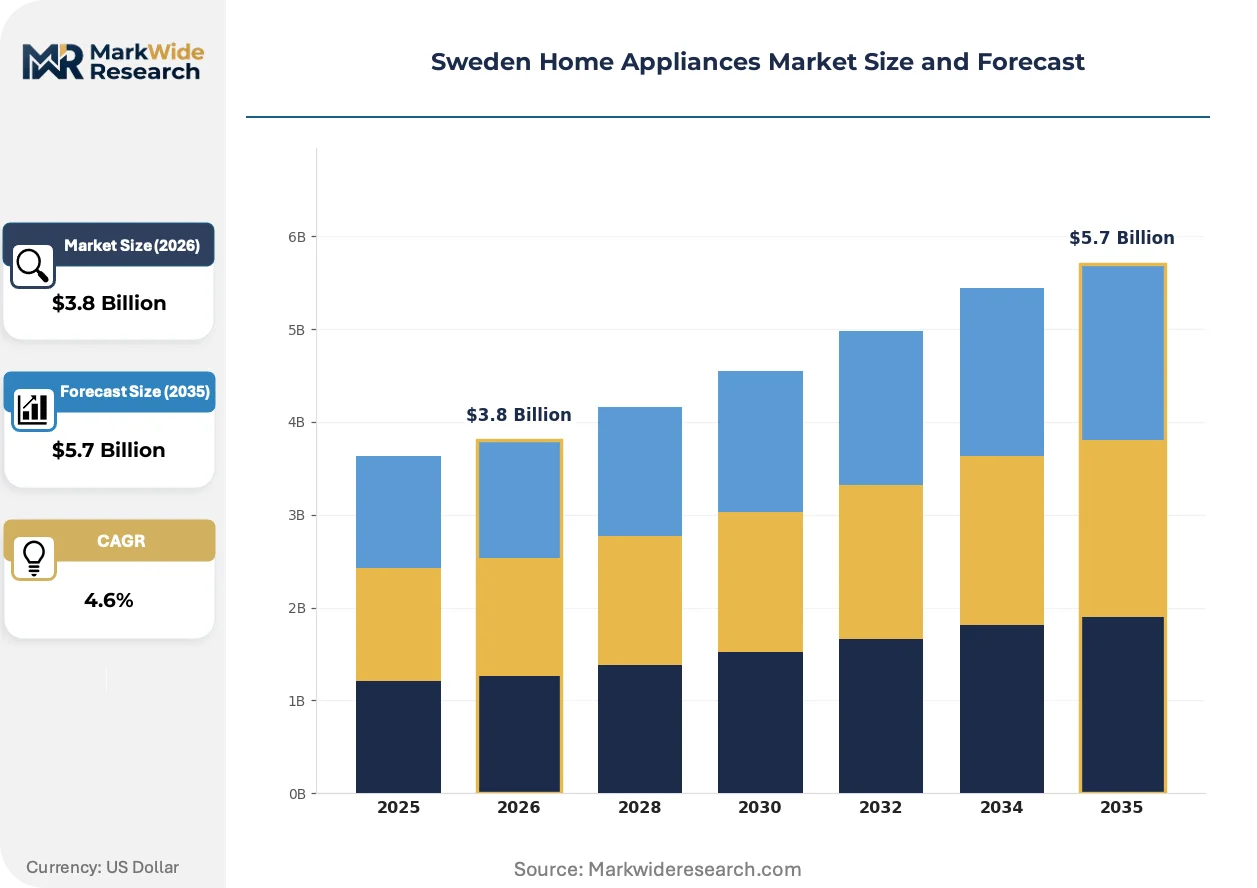
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Dishwashers, Ovens Technology: Smart Appliances, Energy Efficient, IoT Enabled, Conventional End User: Residential, Commercial, Retail, Hospitality Distribution Channel: Online, Offline, Wholesalers, Direct Sales |
| Companies Covered | Samsung Electronics, BSH Hausgeräte GmbH, Electrolux AB, Smeg Group SpA, Haier Electronics Group Co. Ltd, Whirlpool Corporation, Panasonic Corporation, Arcelik AS, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Home Appliances Market Evolving Landscape
Swedish appliance development is converging on platform-based modularity and energy-system interoperability, with manufacturers racing to embed grid-responsive intelligence ahead of regulatory deadlines.
Natural refrigerant technology is decomposing conventional vapor-compression architectures in Swedish refrigeration manufacturing. Electrolux and domestic competitors are adopting propane-isobutane blends for domestic units, eliminating synthetic F-gas dependencies. The shift is compressing supplier bases toward specialized compressor OEMs with hydrocarbon certification expertise.
REACH compliance enforcement by the Swedish Chemicals Agency is tightening material traceability requirements across appliance supply chains. Manufacturers must now document full substance inventories for polymers and coatings, raising baseline procurement costs. Small-component suppliers without ECHA-registered chemical databases are exiting the Swedish market, concentrating sourcing among Tier-1 material vendors.
Swedish household purchasing is rotating toward lifecycle-cost transparency over upfront price points. Retailers are displacing sticker-price dominance with ten-year operating cost calculators that factor Nordic electricity tariffs and carbon levies. This behavioral pivot is most pronounced in Malmö's housing cooperatives, where collective procurement favors A-rated appliances despite 30-40% capital premiums.
Sweden Home Appliances Market Segmentation
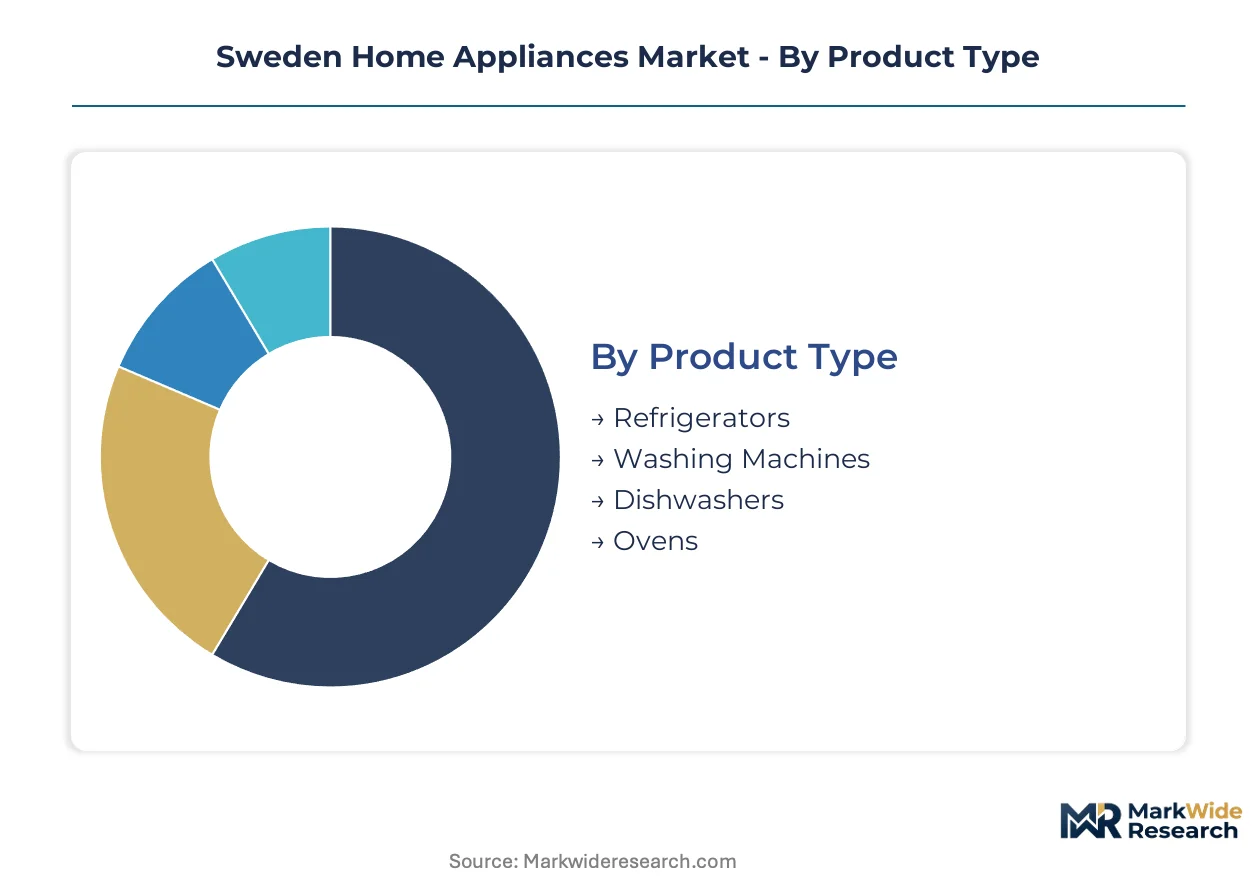
Swedish appliance procurement splits along regulatory compliance tiers and connectivity requirements, with EU Ecodesign thresholds filtering product availability across every channel. Segmentation reveals how Stockholm's renovation density concentrates demand for premium certified units while secondary cities lag in smart appliance penetration.
Product Type:
CE marking thresholds under the EU Ecodesign Directive create divergent competitive barriers across refrigeration and thermal preparation equipment, with natural refrigerant mandates restructuring supplier bases.
- Refrigerators:Hydrocarbon refrigerant architectures dominate Swedish manufacturing as F-Gas quotas eliminate synthetic alternatives. Demand clusters in Stockholm's housing cooperative sector, where collective procurement favors A-rated units despite capital premiums. Established volume favors refrigerators; emerging adoption favors ovens with specialized cooking technologies.
- Washing Machines:Heat pump integration creates bundled procurement with residential HVAC electrification subsidies. Western Sweden's industrial corridor shows underpenetrated smart adoption relative to Stockholm's metropolitan density. Motor and compressor manufacturing faces copper and rare earth input volatility.
- Dishwashers:Grid-responsive intelligence is embedding ahead of anticipated demand-flexibility mandates tied to Nordic spot electricity pricing.
- Ovens:Specialized cooking technologies tailored to Scandinavian culinary preferences differentiate premium positioning in built-in kitchen segments.
Refrigeration hardware captures the steepest replacement cycle compression from energy labelling recalibration; cooking equipment maintains longer functional lifecycles.
Technology:
Connectivity premiums stratify across Nordic energy platform interoperability, with API integration determining margin capture beyond hardware sales.
- Smart Appliances:Onboard sensors converging with energy management platforms enable subscription revenue streams decoupling service monetization from unit sales. Stockholm's metropolitan corridor rewards localized distribution networks for connected home optimization. Established volume favors smart appliances; emerging adoption favors energy efficient units in price-sensitive procurement.
- Energy Efficient:A-to-G rating recalibration compels replacement ahead of functional end-of-life, compressing cycles in renovation corridors. Malmö's housing cooperatives drive collective procurement despite 30-40% capital premiums over conventional alternatives.
- IoT Enabled:Cybersecurity validation timelines under the EU Cyber Resilience Act extend product launches by 8-14 months.
- Conventional:Structural decline accelerates in urban replacement cycles as lifecycle-cost transparency displaces sticker-price dominance.
Smart connectivity is expanding most quickly in Stockholm; energy efficiency certification dominates procurement in secondary municipalities.
End User:
Building automation heterogeneity fragments R&D allocation differently across residential and commercial deployment scales.
- Residential:Housing stock modernization outpacing national averages concentrates premium built-in demand within 150 kilometers of Stockholm. Boverket's building codes mandate energy performance in new construction, indirectly shaping appliance specifications. Established volume favors residential; emerging adoption favors hospitality for connected guest experience.
- Commercial:Procurement prioritizes lifecycle operating cost transparency over upfront capital expenditure.
- Retail:Ten-year operating cost calculators factor Nordic electricity tariffs and carbon levies into point-of-sale decisions.
- Hospitality:Underpenetrated smart appliance adoption in Western Sweden offers first-mover positioning.
Single-family renovation drives replacement velocity; multi-unit commercial procurement favors standardized specification bundles.
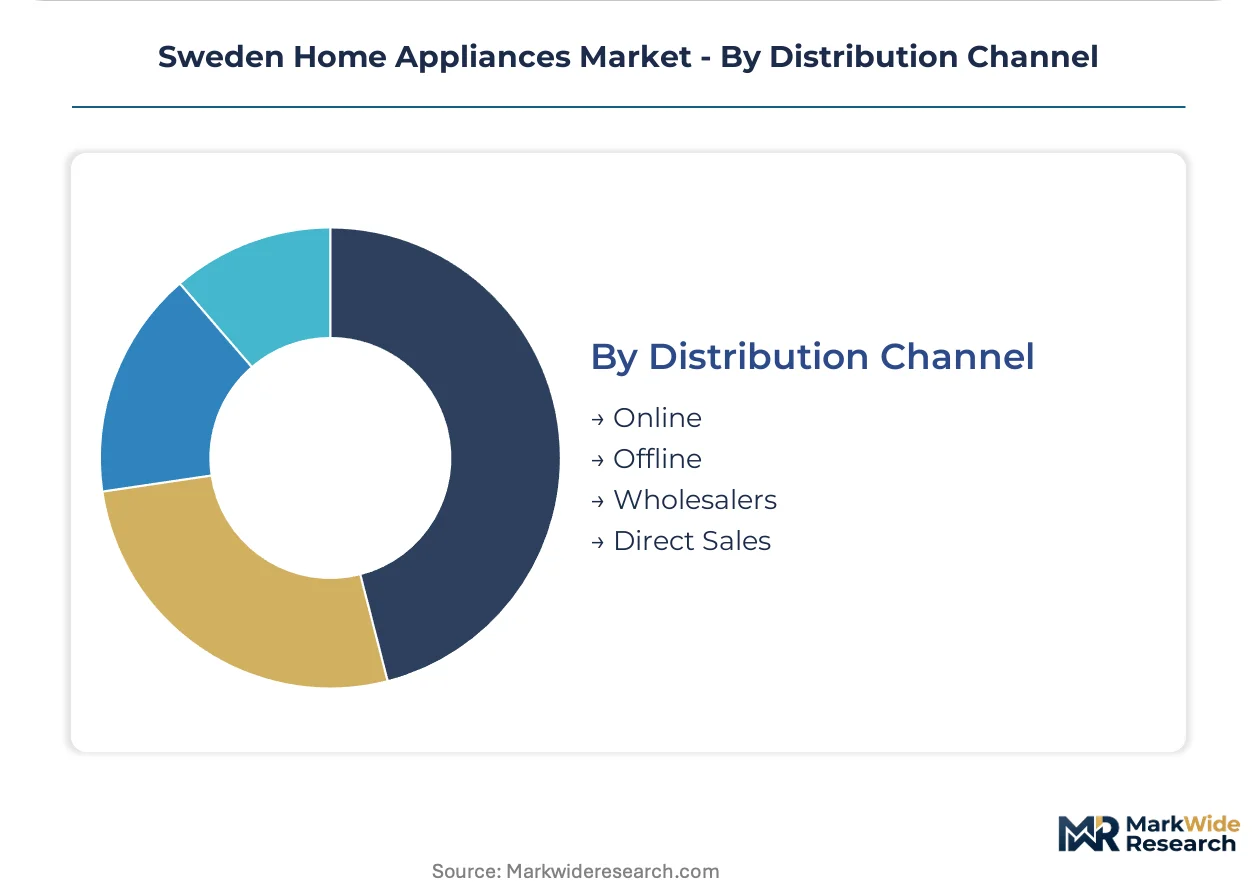
Distribution Channel:
Compliance infrastructure requirements concentrate channel power among distributors with CE marking and REACH documentation capabilities.
- Online:Retailers displace sticker-price dominance with operating cost calculators that factor carbon levies into purchase decisions. Stockholm's density enables efficient last-mile logistics for bulky refrigeration units. Established volume favors online; emerging adoption favors direct sales for grid-responsive bundled offerings.
- Offline:Localized networks within the capital region capture premium built-in kitchen demand.
- Wholesalers:Tier-1 material vendor concentration follows small-component supplier exits from REACH enforcement.
- Direct Sales:Heat pump integration creates paired procurement opportunities with residential electrification subsidies.
E-commerce captures urban replacement urgency; direct channels gain traction in HVAC-appliance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish appliance procurement concentrates in owner-occupied housing cooperatives and single-family renovation segments, with regional demand intensity tracking municipal energy retrofit subsidy availability and building stock age profiles.
Stockholm Metropolitan Area
Stockholm's housing cooperative sector drives premium built-in kitchen demand through collective procurement mechanisms that favor A-rated appliances despite capital premiums. Boverket's building codes mandate energy performance in new residential construction, indirectly accelerating appliance replacement in renovation corridors. The capital region concentrates smart appliance adoption within a 150-kilometer radius that rewards localized distribution networks.
Gothenburg and Western Sweden
Western Sweden's industrial corridor exhibits underpenetrated smart appliance adoption relative to Stockholm, creating first-mover positioning opportunities in connected home energy management. The Swedish Energy Agency enforces EU Ecodesign regulations regionally, filtering out non-compliant imports from retail channels. Gothenburg's port infrastructure handles hydrocarbon refrigerant compressor imports for domestic manufacturing.
Malmö and Southern Sweden
Malmö's housing cooperatives pioneered lifecycle-cost transparency in procurement, displacing sticker-price dominance with ten-year operating cost calculators. REACH compliance enforcement by the Swedish Chemicals Agency tightens material traceability for polymer suppliers serving southern manufacturing. The Øresund corridor benefits from cross-border logistics integration with Danish energy platform providers.
Uppsala and East Central Sweden
Uppsala's university-driven residential construction maintains above-average energy performance standards that shape appliance specifications. The Swedish Chemicals Agency monitors regional REACH compliance for appliance materials, raising baseline procurement costs. Eastern municipalities cluster heat pump installation activity that creates bundled procurement with washing machines and dryers.
Sweden Home Appliances Market Competitive Landscape
Player mix skews toward diversified multinational electronics conglomerates with domestic manufacturing heritage. The Swedish home appliances sector maintains moderate concentration, with CE marking infrastructure and REACH documentation capabilities serving as structural filters. Two strategic archetypes dominate: integrated domestic manufacturers with deep R&D heritage, and Asian electronics conglomerates competing through smart ecosystem platforms. Competitive moves center on modular platform redesigns for natural refrigerant transitions and API integration with Nordic energy management systems.
Within the domestic heritage tier, Electrolux AB anchors premium positioning through its manufacturing footprint and built-in kitchen specialization. Samsung Electronics and LG Electronics represent the smart ecosystem archetype, leveraging connected appliance platforms that integrate with regional energy management infrastructure. BSH Hausgeräte GmbH occupies a position between these vectors, drawing on specialized cooking technologies adapted to Scandinavian culinary preferences.
| Leading Market Players |
|---|
| Samsung Electronics |
| BSH Hausgeräte GmbH |
| Electrolux AB |
| Smeg Group SpA |
| Haier Electronics Group Co. Ltd |
| Whirlpool Corporation |
| Panasonic Corporation |
| Arcelik AS |
| LG Electronics |
| Others |
Value Network & Pricing Analysis
Natural refrigerant substitution for synthetic hydrofluorocarbons is compressing supplier bases toward specialized compressor OEMs with hydrocarbon certification expertise, simultaneously redrawing procurement geography around German and Italian component hubs and elevating capital premiums for A-rated appliance tiers.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper pricing dominate motor and compressor procurement, with Chilean supply concentration transmitting volatility directly into Swedish manufacturing cost bases. Three-tier pricing structure across premium, standard, and economy levels stratifies by energy efficiency certification grade and smart connectivity integration, with CE marking compliance adding fixed overhead that squeezes mid-tier margins most acutely. Price differentiation hinges on REACH documentation depth and Nordic energy platform API compatibility, with Stockholm housing cooperatives showing lowest price sensitivity due to collective procurement mechanisms while secondary city retail channels face acute sticker-price resistance. Pricing pressure stems from rare earth magnet cost escalation in Chinese processing facilities, compressing margins on conventional motor architectures faster than premium heat-pump-integrated alternatives.
Supply Chain Analysis
Strait of Malacca transit underwrites rare earth magnet flows from Chinese separation facilities to European motor manufacturers, exposing Swedish appliance OEMs to concentrated logistics risk. Manufacturing draws from German compressor engineering, Italian cooking component specialization, and Chinese electronics assembly for smart appliance control modules. Copper cathode sourcing rests on Chilean mine output and Zambian refining capacity, while hydrocarbon refrigerant blends require specialized handling infrastructure concentrated in German and Danish chemical processing. Single-source vulnerability sits with Chinese rare earth magnet supply, where export licensing shifts can disrupt motor production timelines without alternative qualified suppliers. Distribution runs through Stockholm-centric retail networks for premium built-in segments, with direct HVAC bundling channels expanding in eastern municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swedish appliance demand is recovering through housing cooperative renovation cycles, with Boverket energy performance mandates in new construction creating replacement pull ahead of functional end-of-life.
For Market Incumbents: Compound domestic manufacturing heritage into modular platform architectures that absorb natural refrigerant transitions without full retooling, anchoring premium positioning as F-Gas quotas eliminate synthetic alternatives. Deepen backward integration into hydrocarbon-certified compressor supply through captive partnerships with German engineering specialists, defending margin structure against rare earth input volatility. Prioritize cybersecurity certification investment under the EU Cyber Resilience Act to compress validation timelines that currently delay product launches by 8-14 months. For New Entrants and Emerging Players: Subscription-based predictive maintenance services represent an under-served layer where incumbents remain hardware-focused, offering recurring revenue decoupled from unit sales through Nordic energy platform API integration. Western Sweden's industrial corridor presents the most penetrable geography for smart appliance adoption, with Gothenburg's port infrastructure enabling efficient hydrocarbon refrigerant component import. Pursue direct sales channels paired with residential heat pump installations, leveraging Swedish HVAC-electrification subsidies for bundled procurement entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Nordic component suppliers holding ECHA-registered chemical databases and REACH documentation infrastructure that smaller competitors cannot replicate. Long-term viability centers on manufacturers with proven natural refrigerant platform transitions and embedded software capabilities spanning the 5-10 year regulatory compliance horizon. Monitor Swedish Energy Agency enforcement intensity around EU Ecodesign thresholds as the inflection indicator for competitive filtering velocity and margin expansion in certified tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Platform Transition | Eliminates F-Gas dependency ahead of quota phase-down, qualifying products for Swedish electrification subsidies. |
| Nordic Energy Platform API Integration | Enables grid-responsive appliance intelligence that synchronizes with spot electricity pricing in Stockholm metropolitan corridors. |
| Backward Integration into Compressor Supply | Captures hydrocarbon certification expertise concentrated among German engineering specialists, securing refrigerant transition timelines. |
| Direct Sales Channel Development | Facilitates bundled procurement with residential heat pump installations leveraging Swedish HVAC-electrification subsidies. |
| REACH Documentation Infrastructure Investment | Builds ECHA-registered chemical databases that filter competitors from Swedish retail channels under Chemicals Agency enforcement. |
Research Methodology
A spread of perspectives from appliance manufacturing executives, Nordic energy platform engineers, housing cooperative procurement managers, and retail category buyers converged on the working assumptions around replacement cycle compression and smart connectivity monetization. Primary fieldwork combined structured interviews with supply chain planners at compressor OEMs and regulatory affairs leads at domestic manufacturers. Secondary validation drew from Swedish Energy Agency enforcement disclosures, Boverket building code amendments, ECHA REACH registration databases, and EU Ecodesign implementing measure texts. Bottom-up unit shipment modeling triangulated against top-down household penetration rates across Stockholm, Gothenburg, Malmö, and Uppsala metropolitan clusters.
Segmentation dimensions modeled span product type, technology tier, end-user category, and distribution channel, with energy efficiency certification grade and smart connectivity integration treated as cross-cutting variables. CAGRs were derived from replacement cycle velocity analysis tied to housing stock age profiles and renovation subsidy availability, with natural refrigerant adoption curves and cybersecurity compliance timelines as appliance-specific forecast inputs across the projection horizon.
Forecasts assume regulatory continuity in EU Ecodesign and F-Gas Regulation implementation; material policy shifts around carbon border adjustments or accelerated electrification subsidies would require re-modeling. Practitioners should keep alternative scenarios live as Swedish national carbon reduction targets and Nordic spot electricity pricing volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Australia Washing Machine Market
Home Appliances
Residential Dishwashers Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
White Goods Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Mexico Major Home Appliance Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Residential Washing Machine Market
Home Appliances
Washing Machine Market