
 Qatar Major Home Appliances Market | 2026-2036
Qatar Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Major Home Appliances Market Analytics
Aftermarket service revenue is fragmenting across Qatar's appliance ecosystem as manufacturers compete for recurring income streams beyond unit sales. Haier Smart Home Co. Ltd. leverages its connected appliance platform to capture remote diagnostics and predictive maintenance contracts. Samsung Electronics Co. Ltd. anchors premium positioning through its Doha flagship network and exclusive retail partnerships. LG Electronics Inc. specializes in built-in kitchen suites targeting villa developments in Al Wakrah and Al Khor.
Qatar Major Home Appliances encompass electrically powered domestic equipment for food preservation, fabric care, cooking, and surface cleaning, typically operating at 240V/50Hz with cooling capacities ranging from 200L to 600L for refrigeration units and spin speeds exceeding 1,200 RPM for washing systems. These products serve residential and commercial end users requiring durable, climate-adapted performance in Gulf environmental conditions. Refrigerators dominate volume throughput given Qatar's import-dependent food supply chain and extended storage requirements. Smart Appliances and IoT-Enabled systems represent the fastest-expanding technology dimension as property developers integrate connected home infrastructure into new builds. Energy-Efficient models face accelerating pull from QS energy labeling mandates and rising electricity tariffs for commercial users.
The Qatar General Organization for Standardization enforces QS mark certification and energy performance standards that govern import eligibility and retail distribution. The Ministry of Commerce and Industry administers consumer protection regulations covering warranty terms and after-sales service obligations. The Ministry of Municipality and Environment coordinates building codes that specify appliance installation standards for residential and hospitality construction. Stakeholders must monitor evolving smart home interoperability requirements and refrigerant phase-down schedules under regional environmental commitments.
Market Dynamics
QS energy labeling mandates from the Qatar General Organization for Standardization are compressing import eligibility windows and forcing manufacturers to recertify entire product lines, creating a structural filter that favors established suppliers with dedicated compliance infrastructure.
Growth Catalysts
- Lusail and The Pearl luxury developments:Premium residential towers are specifying built-in kitchen suites and connected laundry systems as standard fit-outs, creating bundled procurement volumes for appliance vendors.
- QS mark certification pathways:The Qatar General Organization for Standardization's streamlined digital submission process is reducing time-to-market for compliant products, accelerating retail distribution access.
- Smart home infrastructure integration:Property developers are pre-wiring residential units for IoT-enabled appliance connectivity, embedding hardware demand into construction timelines.
Market Restraints
- Refrigerant phase-down schedules:Regional environmental commitments are forcing redesign cycles for cooling systems, raising R&D burdens for manufacturers serving Qatar's high ambient-temperature operating conditions.
- Import concentration through Jebel Ali:Overreliance on a single UAE logistics hub creates vulnerability to shipping disruptions and customs processing bottlenecks affecting Qatar-bound inventory.
- Electricity tariff structures:Commercial users face rising per-kWh costs that compress replacement cycles for energy-inefficient legacy equipment, but residential tariff subsidies dampen consumer urgency for efficiency upgrades.
Strategic Opportunities
- Al Wakrah and Al Khor villa corridors:Underpenetrated suburban developments outside Doha's core are expanding with mid-tier housing stock requiring full appliance packages.
- Predictive maintenance service contracts:Connected appliance platforms enable remote diagnostics revenue streams, shifting vendor economics from one-time sales to recurring service relationships.
- Hospitality corridor along West Bay:Hotel construction and refurbishment cycles are specifying commercial-grade laundry and refrigeration equipment with extended warranty requirements.
Industry Challenges
- Smart home interoperability standards:Fragmented communication protocols between property management systems and appliance control interfaces are forcing redundant engineering efforts.
- Technician certification pipelines:Shortages of QS-certified service personnel are extending repair timelines and eroding brand loyalty among time-sensitive consumers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Major Home Appliances Market |
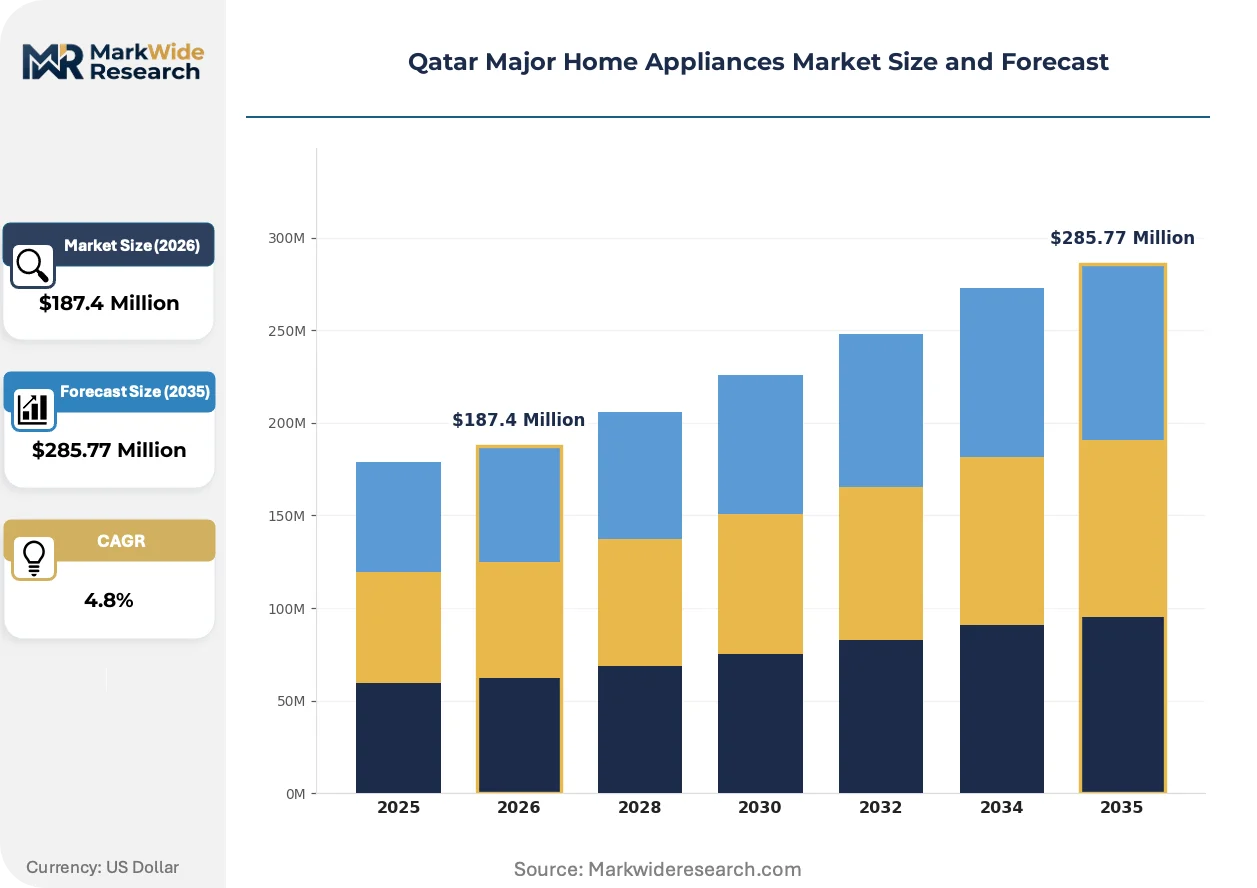
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers End User: Households, Hotels, Restaurants, Offices Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Conventional Distribution Channel: Online Retailers, Department Stores, Specialty Stores, Direct Sales |
| Companies Covered | Haier Smart Home Co. Ltd., Panasonic Corporation, Whirlpool Corporation, Hisense, TCL, LG Electronics Inc., BSH Home Appliances, Arçelik, Samsung Electronics Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Major Home Appliances Market Evolving Landscape
Connectivity architectures and energy performance thresholds are converging to redefine product specifications across Qatar's residential and hospitality segments, with compliance and convenience emerging as dual purchase determinants.
Inverter-driven compressor technology is replacing fixed-speed cooling systems in refrigeration and air-conditioning applications. Villa developers in Al Wakrah and Al Khor are specifying inverter models as baseline requirements in new construction tenders. Fixed-speed compressors are rendering obsolete across premium and mid-tier segments as electricity costs and noise regulations tighten.
QS energy labeling mandates from the Qatar General Organization for Standardization now require visible efficiency ratings on all retail-displayed appliances. Retailers are restructuring floor space to prioritize A-rated models and phasing out non-compliant inventory. Commercial laundry operators in West Bay hospitality properties are responding fastest, driven by operational cost scrutiny and corporate sustainability reporting obligations.
After-sales service unbundling is separating warranty fulfillment from brand ownership. Independent service aggregators are capturing maintenance contracts through multi-brand technician networks, displacing manufacturer-captive service operations. This pattern concentrates in Doha's high-density residential zones where repair response speed outweighs brand loyalty in purchase decisions.
Qatar Major Home Appliances Market Segmentation
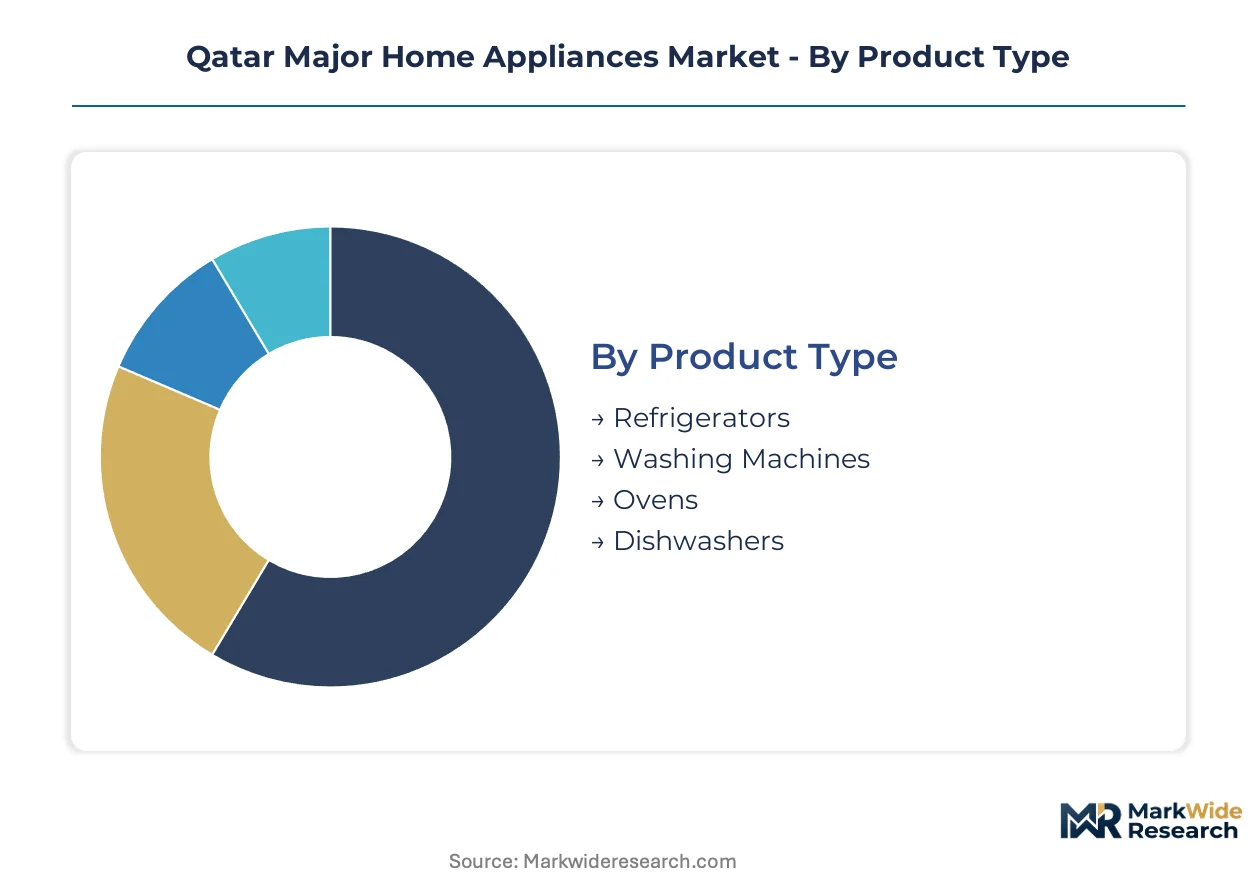
Segmentation in Qatar's appliance market reveals distinct service intensity patterns across product types and user profiles. The country's luxury residential concentration and QS certification requirements create divergent margin structures that reward targeted positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with cooling systems demanding specialized refrigerant handling and compressor diagnostics that constrain vendor choice.
- Refrigerators:Units span 200L to 600L cooling capacities with inverter-driven compressors replacing fixed-speed systems. Demand clusters in Doha's high-end households and West Bay hospitality properties where extended food storage requirements meet strict QS energy labeling mandates. Service contracts concentrate here due to compressor complexity and refrigerant phase-down compliance burdens.
- Washing Machines:Front-load systems exceed 1,200 RPM spin speeds with connected diagnostics capabilities. Lusail and The Pearl luxury towers specify these as standard fit-outs, bundling procurement volumes with predictive maintenance subscriptions that shift vendor economics toward recurring revenue.
- Ovens:Built-in kitchen suites integrate convection and steam technologies for villa developments.
- Dishwashers:Commercial-grade units serve West Bay hotel refurbishment cycles with extended warranty requirements.
By volume, Refrigerators leads. By growth pace, Washing Machines is ahead.
End User:
Cost tier differentiation separates premium specification buyers from price-sensitive procurement, with hospitality operators facing sharper operational cost scrutiny than subsidized residential users.
- Households:Doha's high-end segment drives built-in kitchen suite demand while Al Wakrah and Al Khor villa corridors expand mid-tier housing stock requiring full appliance packages. Electricity tariff subsidies dampen urgency for efficiency upgrades among residential users.
- Hotels:West Bay hospitality corridor specifications emphasize commercial-grade laundry and refrigeration equipment. Corporate sustainability reporting obligations accelerate QS energy label compliance faster than residential segments.
- Restaurants:Food service operators prioritize durable cooling systems given Qatar's import-dependent supply chain.
- Offices:Commercial users face rising per-kWh costs that compress replacement cycles for legacy equipment.
Households dominates absolute unit absorption. Hotels shows the steepest expansion trajectory for connected system specifications.
Technology:
Application focus separates infrastructure-dependent connected platforms from standalone efficiency upgrades, with new construction embedding hardware demand while retrofits lag.
- Smart Appliances:Connected platforms enable remote diagnostics and predictive maintenance contracts. Property developers pre-wire residential units for IoT-enabled connectivity, embedding hardware demand directly into construction timelines rather than replacement cycles.
- Energy-Efficient:QS energy labeling mandates from the Qatar General Organization for Standardization require visible efficiency ratings on all retail-displayed appliances. Retailers restructure floor space to prioritize A-rated models and phase out non-compliant inventory.
- IoT-Enabled:Interoperability with property management systems forces redundant engineering efforts amid fragmented communication protocols.
- Conventional:Fixed-speed compressors and non-connected controls retain presence in price-sensitive segments.
Energy-Efficient models command the largest installed base. Smart Appliances is climbing the fastest as Lusail and The Pearl developments specify connected infrastructure.
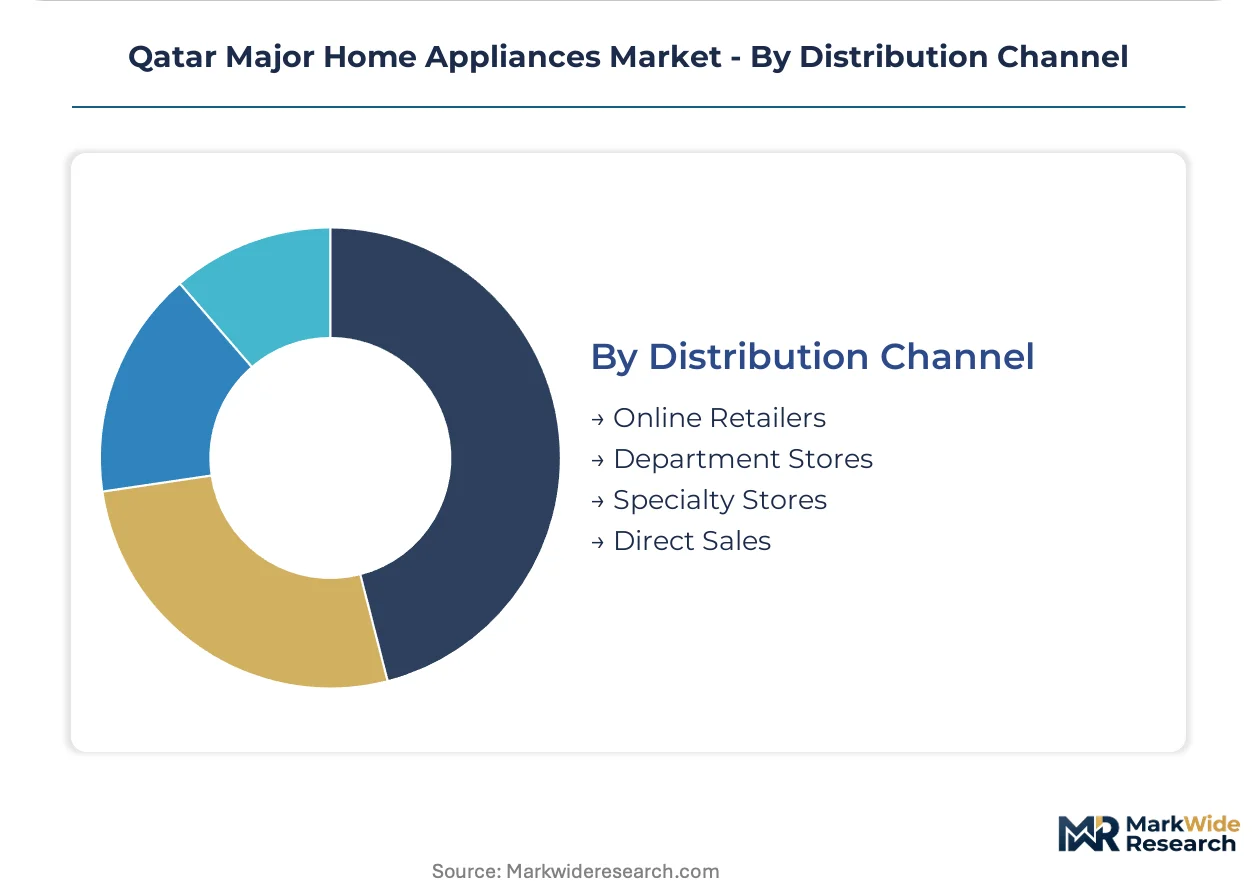
Distribution Channel:
Customer type segmentation separates bundled project procurement from individual replacement purchases, with developer relationships commanding volume discounts unavailable to retail buyers.
- Specialty Stores:Doha flagship networks anchor premium positioning through exclusive retail partnerships. QS-certified technician availability concentrates here, accelerating repair response times that outweigh brand loyalty in purchase decisions.
- Department Stores:Floor space restructuring prioritizes A-rated models under QS mandate compliance. Multi-brand display environments enable comparison shopping that fragments manufacturer-captive service operations.
- Online Retailers:Digital platforms capture remote diagnostics subscription attachments alongside hardware sales.
- Direct Sales:Developer relationships secure bundled procurement volumes for new construction projects.
Specialty Stores handles the greatest transaction value. Online Retailers is gaining share fastest through predictive maintenance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Qatar's sub-regions, with Doha's luxury household segment showing price insensitivity while Al Wakrah and Al Khor villa buyers respond more acutely to mid-tier pricing. This divergence shapes inventory allocation and service network placement for appliance vendors.
Doha
The capital's high-end households drive specification for built-in kitchen suites and connected laundry systems with predictive maintenance subscriptions. The Qatar General Organization for Standardization enforces QS mark certification and energy labeling mandates that filter retail inventory toward A-rated models. West Bay's hospitality corridor concentrates commercial-grade procurement for hotel refurbishment cycles.
Al Wakrah
Villa developments in this southern municipality are expanding mid-tier housing stock requiring full appliance packages rather than premium standalone units. Building codes from the Ministry of Municipality and Environment specify installation standards that favor inverter-driven compressor systems. The Al Wakrah South corridor is seeing bundled developer procurement that compresses margins but secures volume throughput.
Al Khor
This northern municipality's suburban expansion attracts price-sensitive household formation with demand for durable, climate-adapted cooling and fabric care systems. Electricity tariff subsidies for residential users dampen urgency for efficiency upgrades despite QS labeling requirements. The Al Khor Community and surrounding villa clusters concentrate retail distribution investments from mid-tier specialists.
Lusail
Qatar's newest city mandates smart home infrastructure pre-wiring in all residential towers, embedding IoT-enabled appliance demand directly into construction timelines. The Qatar General Organization for Standardization's streamlined digital certification process accelerates time-to-market for compliant products. Marina District and Fox Hills developments specify connected kitchen suites and laundry systems as standard fit-outs.
The Pearl
This artificial island's luxury residential towers command premium positioning for imported appliance brands with exclusive retail partnerships. The Ministry of Commerce and Industry administers consumer protection regulations covering extended warranty terms that elevate service contract values. Porto Arabia and Qanat Quartier clusters concentrate flagship showroom investments and QS-certified technician deployment.
Qatar Major Home Appliances Market Competitive Landscape
Capability concentration sits with full-line manufacturers possessing dedicated compliance infrastructure; scale advantage sits with diversified electronics conglomerates leveraging cross-category procurement relationships. The vendor base stratifies across three tiers: global appliance specialists with captive service networks, diversified technology groups with smart home ecosystems, and regional distributors with logistics flexibility. Consolidation pressure is mounting as QS recertification burdens favor established players with dedicated regulatory affairs capacity. Competitive moves center on predictive maintenance service unbundling and developer-direct procurement relationships.
Among the diversified technology groups, Samsung Electronics Co. Ltd. and LG Electronics Inc. occupy positions defined by connected platform integration and premium retail anchoring. Haier Smart Home Co. Ltd. exemplifies the full-line specialist archetype with emphasis on remote diagnostics infrastructure. These three companies represent distinct strategic postures: ecosystem-led connectivity, flagship retail positioning, and service-revenue transition respectively.
| Leading Market Players |
|---|
| Haier Smart Home Co. Ltd. |
| Panasonic Corporation |
| Whirlpool Corporation |
| Hisense |
| TCL |
| LG Electronics Inc. |
| BSH Home Appliances |
| Arçelik |
| Samsung Electronics Co. Ltd |
| Others |
Value Network & Pricing Analysis
Jebel Ali's logistics concentration in the UAE governs landed cost structures for Qatar-bound appliance inventory, compressing margin flexibility for distributors while amplifying procurement leverage for volume buyers in Doha's luxury residential segment. This single-hub dependency creates asymmetric pricing power that favors developer-direct relationships over fragmented retail channels.
Pricing Analysis
Long-term offtake agreements dominate procurement for Lusail and The Pearl luxury developments, locking in bundled appliance packages at volume-discounted rates unavailable to individual retail purchasers. Three-tier pricing structure across premium, standard, and economy levels separates flagship showroom positioning from mid-tier villa fit-outs and price-sensitive replacement demand. Cost compression in the mid-tier is intensifying because Al Wakrah and Al Khor developers are consolidating supplier rosters to secure full-package bids. Residential users in subsidized electricity tariff zones show lowest price sensitivity; commercial hospitality operators in West Bay face sharpest cost scrutiny.
Supply Chain Analysis
Contract manufacturing concentration rests with South Korean and Chinese production facilities serving Middle East export markets, with Samsung Electronics and LG Electronics anchoring premium capacity while Haier Smart Home scales volume throughput for connected platform lines. Compressor components and refrigerant systems draw from specialized suppliers in China and South Korea, with inverter-driven modules commanding allocation priority. Single-source vulnerability concentrates in Jebel Ali customs processing, where Qatar-bound shipments face bottleneck risk from documentation delays. Distribution runs through developer-direct channels for new construction, specialty retail flagships for replacement demand, and emerging digital platforms for predictive maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's appliance market is crossing a platform-economics inflection as smart home interoperability requirements force ecosystem consolidation around connected service revenue models rather than discrete hardware margins.
For Market Incumbents: Pre-empt independent service aggregator capture by embedding predictive maintenance subscriptions into developer-direct contracts before unbundling accelerates across Doha's high-density residential zones. Defensive certification investment in QS mark digital submission infrastructure will filter recertification burdens toward smaller competitors lacking dedicated regulatory affairs capacity. Backward integration into compressor technology partnerships secures supply continuity amid refrigerant phase-down redesign cycles. For New Entrants and Emerging Players: Pursue underpenetrated mid-tier villa corridors in Al Wakrah South and Al Khor Community where bundled procurement volumes exceed brand loyalty intensity and service response speed determines vendor selection. White-space exists in multi-brand technician networks capable of QS-certified coverage outside Doha's core. A direct-to-developer sales model bypassing established retail flagships offers fastest traction. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue transition play because predictive maintenance contracts are displacing one-time hardware economics as the dominant value capture mechanism. Acquisition targets should emphasize connected platform infrastructure and captive service network density rather than manufacturing scale alone. The signal to watch is smart home interoperability standard convergence, which will determine which ecosystem architectures achieve developer specification lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Haier Smart Home's remote diagnostics infrastructure shifts vendor economics from unit sales to recurring service contracts. |
| Developer-Direct Procurement Partnership | Lusail and The Pearl bundled fit-out specifications create volume anchoring unavailable through fragmented retail channels. |
| QS Certification Infrastructure Investment | Dedicated regulatory affairs capacity filters recertification burdens toward smaller competitors under energy labeling mandates. |
| Smart Home Interoperability Integration | Property management system connectivity determines specification priority amid fragmented communication protocol standards. |
| Multi-Brand Service Network Expansion | Independent technician aggregators capture maintenance contracts through faster response times than manufacturer-captive operations. |
Research Methodology
Desk research of customs import records, QS certification filings, and hospitality procurement databases preceded structured interviews with appliance category managers at Doha flagship retailers, developer procurement leads in Lusail and The Pearl, QS-certified service technicians, and Ministry of Commerce and Industry regulatory affairs officers. Primary fieldwork captured pricing structure dynamics, certification pathway timelines, and smart home infrastructure integration requirements. Secondary validation drew from Qatar General Organization for Standardization energy labeling disclosures, Ministry of Municipality and Environment building code specifications, and hospitality sector sustainability reporting. Bottom-up unit shipment estimates triangulated against top-down construction pipeline valuations.
Assumption sets held fixed Qatar's mandatory QS standards and refrigerant phase-down schedules while varying smart home interoperability adoption curves, electricity tariff subsidy levels, and Jebel Ali logistics capacity utilization. Segmentation modeling spanned product type, end user category, technology tier, and distribution channel across the projection horizon. CAGRs derived from construction completion timelines, replacement cycle compression patterns, and connected platform penetration slopes. Industry-specific forecast inputs included villa development permits in Al Wakrah and Al Khor, West Bay hotel refurbishment cycles, and QS digital certification processing velocity.
Macroeconomic conditions sit as an overlay; deviation in oil price trajectories affecting government infrastructure spending or construction labor availability would shift the trajectory. Forecasts reflect assumptions around regulatory continuity, supply chain hub stability, and technology standard convergence. Quarterly review of QS certification queue lengths, Jebel Ali customs processing times, and smart home protocol adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
China Small Home Appliances Market
Home Appliances
White Goods Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
France Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Canada Home Appliances Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Israel Home Needs Appliances Market