
 GCC Major Home Appliances Market | 2026-2036
GCC Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Major Home Appliances Market Foresight
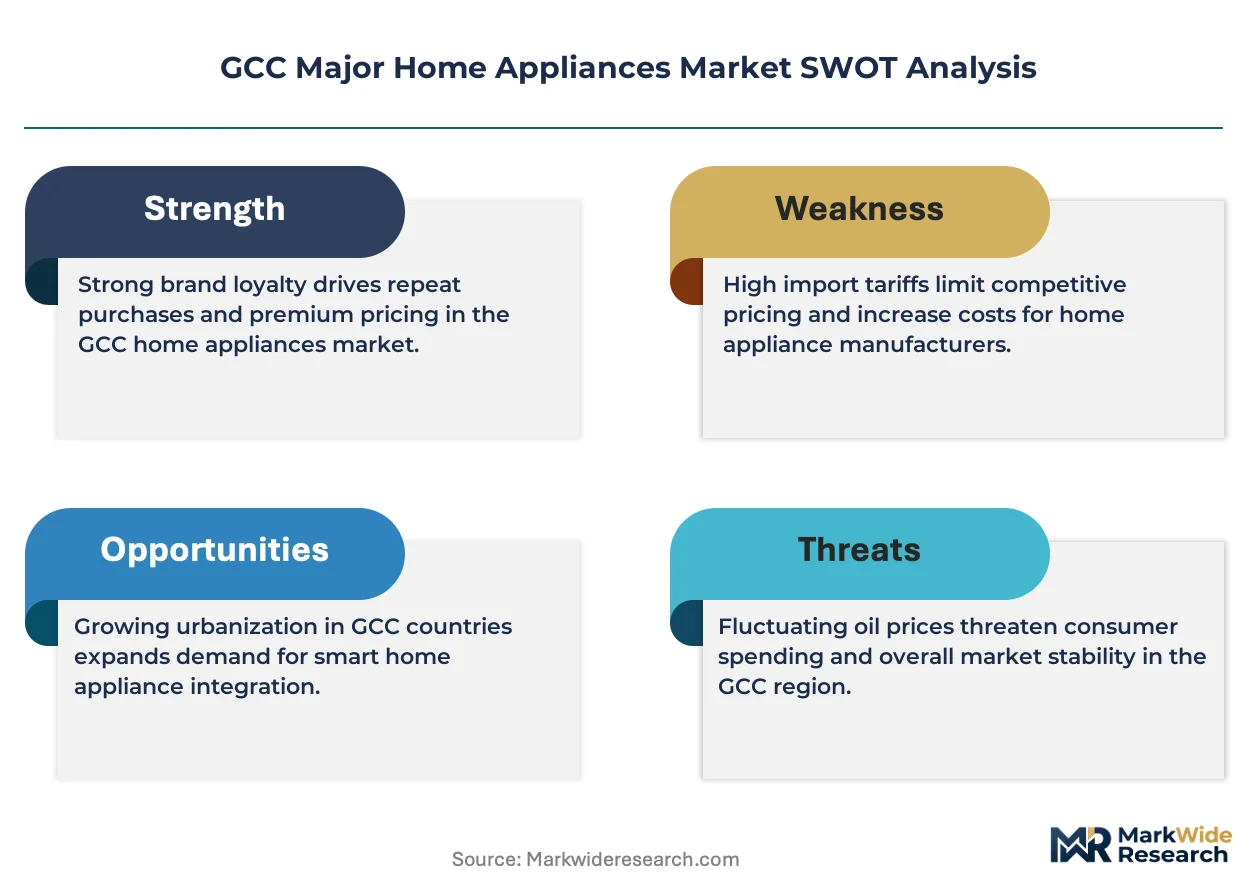
Expatriate technician availability in the GCC is collapsing as visa reform programs and nationalization quotas tighten labor inflows. Samsung Electronics Co. Ltd. leverages its regional manufacturing footprint in Egypt to sustain competitive lead times into Saudi and UAE distribution hubs. LG Electronics Inc. anchors its position through inverter compressor technology leadership that differentiates its air conditioner portfolio from standard fixed-speed alternatives. Whirlpool Corporation competes on brand equity among affluent homeowners while navigating higher import duty structures that elevate landed costs.
GCC major home appliances encompass electrically powered durable goods for domestic and commercial environments, typically operating on 220-240V at 50Hz with cooling capacities measured in British thermal units and energy efficiency ratios certifying thermal performance per watt consumed. Refrigerators and air conditioners dominate volume throughput given the region's ambient temperature extremes and extended cooling seasons, while smart and Wi-Fi enabled technology segments attract premium positioning as property developers embed connected home infrastructure into new residential towers. Inverter technology leads replacement cycles due to electricity tariff sensitivity among homeowners, whereas hospitality and healthcare facility applications sustain commercial-grade demand for heavy-duty washing machines and dishwashers with accelerated cycle specifications.
Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology enforce mandatory energy efficiency labeling that restricts market access for non-compliant imports, while Gulf Standardization Organization harmonization efforts reduce technical barriers across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and UAE. These frameworks elevate baseline product specifications and compress margins for manufacturers lacking certified test laboratories or regional conformity assessment partnerships. Stakeholders must monitor evolving minimum energy performance standards and local content requirements that could reshape supplier eligibility and procurement qualification criteria.
Market Dynamics
Heat intensity across Saudi Arabia's central corridor and UAE's coastal zones is accelerating replacement cycles toward inverter compressor systems, while Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology efficiency mandates compress the viable product set for importers.
Growth Catalysts
- SASO Energy Labeling Mandates:Saudi Arabia's tiered efficiency requirements redirect procurement toward inverter-driven cooling systems that exceed minimum performance thresholds.
- Smart-Connected Infrastructure:Property developers in Dubai's premium residential towers embed Wi-Fi enabled appliance frameworks that elevate specification requirements for new construction.
- Central Province Developments:Riyadh corridor residential expansion concentrates demand for heavy-duty washing machines and dishwashers with accelerated cycle specifications.
Market Restraints
- Import Duty Structures:Elevated landed costs for non-regional manufacturers compress margin flexibility and limit pricing maneuverability.
- Technician Labor Contraction:Visa reform programs and nationalization quotas across GCC states reduce expatriate service technician availability.
- Fixed-Speed Inventory Stranding:Existing distribution channel stock of conventional compressor systems faces accelerated obsolescence under tightening efficiency tiers.
Strategic Opportunities
- Regional Manufacturing Proximity:Egypt-based production facilities enable competitive lead times into Saudi and UAE distribution hubs.
- Hospitality Grade Commercial Demand:Healthcare and hotel facility applications sustain demand for heavy-duty cycle specifications with premium service contracts.
- Gulf Standardization Organization Harmonization:Cross-border technical barrier reduction opens consolidated procurement pathways across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and UAE.
Industry Challenges
- Conformity Assessment Bottlenecks:Certified test laboratory scarcity delays product eligibility for SASO and ESMA labeling requirements.
- Installation Workforce Gaps:Refrigerant handling certification requirements exceed available trained technician supply during peak replacement seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Major Home Appliances Market |
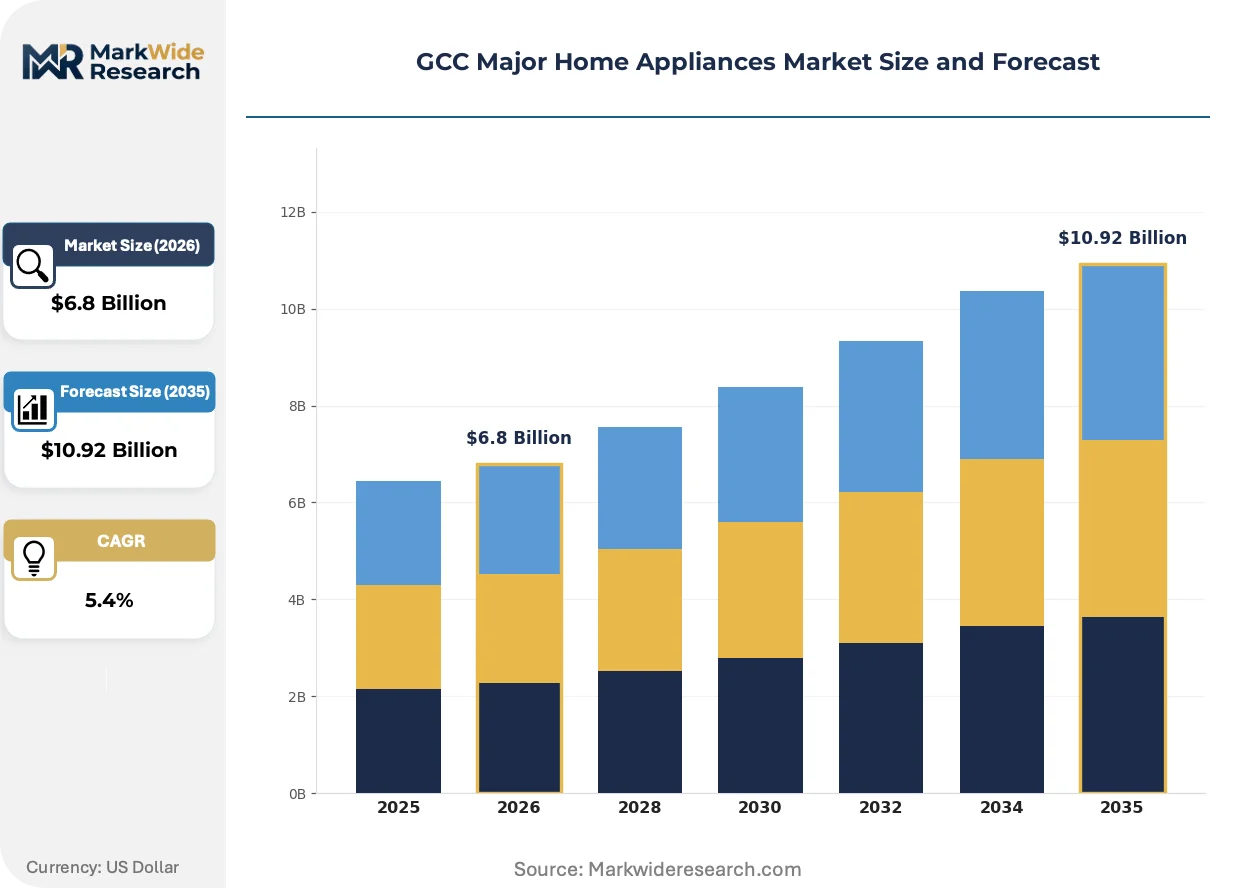
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Air Conditioners, Microwaves, Dishwashers Technology: Inverter, Smart, Energy Star, Wi-Fi Enabled, Touch Control Application: Residential, Commercial Offices, Hospitality, Educational Institutions, Healthcare Facilities End User: Homeowners, Property Developers, Facility Managers, Retailers, Leasing Companies |
| Companies Covered | BSH Hausgeräte GmbH, Electrolux AB, LG Electronics Inc., Midea Group Co. Ltd., Panasonic Corporation, Samsung Electronics Co. Ltd., Haier Group Corporation, Arçelik A.Ş., Whirlpool Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Major Home Appliances Market Shifts & Advancements
Inverter technology is compressing the viable competitive set while regulatory labeling frameworks accelerate product turnover. Smart connectivity protocols are embedding into new construction specifications, and procurement concentration among large-scale developers is reshaping distribution economics.
Inverter compressor systems optimize electricity consumption by modulating motor speed against cooling demand rather than cycling on-off. Residential homeowners across Riyadh and Jeddah corridors are upgrading amid intensifying summer heat patterns and tariff sensitivity. Variable-speed technology is displacing fixed-speed alternatives in replacement cycles, compressing margins for manufacturers lacking certified inverter platforms.
Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology enforce mandatory energy efficiency labeling that restricts market access for non-compliant imports. These frameworks elevate baseline product specifications and compress margins for manufacturers lacking regional conformity assessment partnerships. Air conditioner and refrigerator categories face the most immediate compliance pressure, with distributors accelerating clearance of pre-tier inventory.
Large-scale property developers in Dubai and Riyadh are consolidating appliance procurement into master specifications for entire residential towers. Traditional retail channel fragmentation is giving way to direct manufacturer relationships with developer procurement teams. This concentration is most visible in UAE premium residential construction and Saudi central province master-planned communities.
GCC Major Home Appliances Market Segmentation
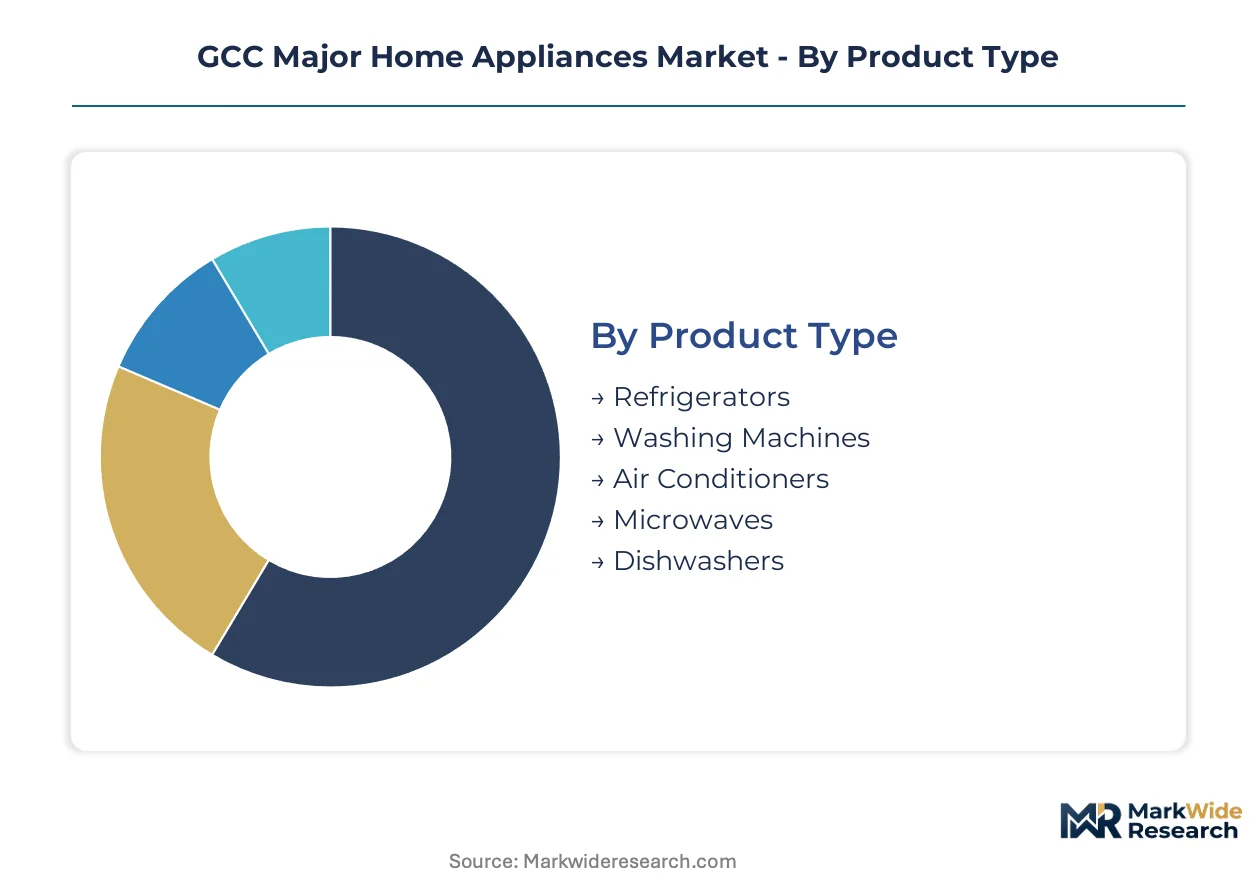
Segmentation in the GCC major home appliances market reveals how regulatory tiering and infrastructure specifications redirect procurement across product categories. SASO and ESMA efficiency mandates compress the viable competitive set differently across cooling systems, cleaning equipment, and food preservation technologies.
Product Type:
SASO energy labeling applies differentiated efficiency thresholds across cooling versus cleaning categories, with refrigerant-based systems facing the most stringent compliance timelines.
- Refrigerators:Compression-based cooling systems with insulated compartments for food preservation operate at 220-240V with energy efficiency ratio certifications. Demand concentrates in Riyadh corridor residential towers where SASO tier requirements accelerate replacement of pre-2019 inventory toward inverter compressor platforms.
- Air Conditioners:Split-system and central cooling units measured in British thermal units dominate procurement volumes given ambient temperature extremes. Dubai premium residential developments specify variable-speed inverter systems exclusively, displacing fixed-speed alternatives from new construction pipelines.
- Washing Machines:Drum-based cleaning systems with accelerated cycle specifications serve residential and commercial laundry applications.
- Microwaves:Magnetron-based heating appliances occupy compact kitchen footprints with standardized voltage requirements.
- Dishwashers:Rack-based cleaning systems with thermal drying cycles target hospitality and healthcare facility specifications.
Established volume favors Air Conditioners; emerging adoption favors Refrigerators as efficiency mandates tighten.
Technology:
Cost tier differentiation separates premium inverter platforms from baseline fixed-speed alternatives, with certification requirements elevating procurement thresholds.
- Inverter:Variable-speed compressor systems modulate motor output against thermal load rather than cycling on-off. Saudi central province developments specify inverter technology exclusively under SASO tier 1 requirements, compressing margins for manufacturers lacking certified platforms.
- Smart:Connected appliance protocols with embedded sensors and remote monitoring capabilities integrate with building management systems. Dubai's premium residential towers embed Wi-Fi enabled frameworks into master specifications, elevating procurement requirements for new construction.
- Energy Star:Efficiency certification systems benchmark consumption against standardized test protocols.
- Wi-Fi Enabled:Wireless connectivity modules enable smartphone-based control and energy monitoring.
- Touch Control:Capacitive interface panels replace mechanical switches in premium positioning tiers.
Procurement concentration favors Inverter; specification evolution favors Smart as developer master agreements expand.
Application:
Volume distribution across end-use environments reflects cooling season intensity and facility upgrade cycles.
- Residential:Single-family and multi-unit dwellings drive replacement cycles amid tariff sensitivity and heat intensity patterns. Riyadh and Jeddah corridors concentrate demand for inverter-driven cooling systems as homeowners upgrade amid intensifying summer temperatures.
- Hospitality:Hotel and resort facilities sustain commercial-grade demand for heavy-duty washing machines and dishwashers with accelerated cycle specifications. Healthcare and hotel applications in UAE coastal zones specify premium service contracts with rapid response commitments.
- Commercial Offices:Workplace environments with centralized cooling infrastructure.
- Educational Institutions:School and university facilities with seasonal usage patterns.
- Healthcare Facilities:Hospital and clinic environments with sterilization-grade requirements.
Replacement velocity favors Residential; contract value favors Hospitality.
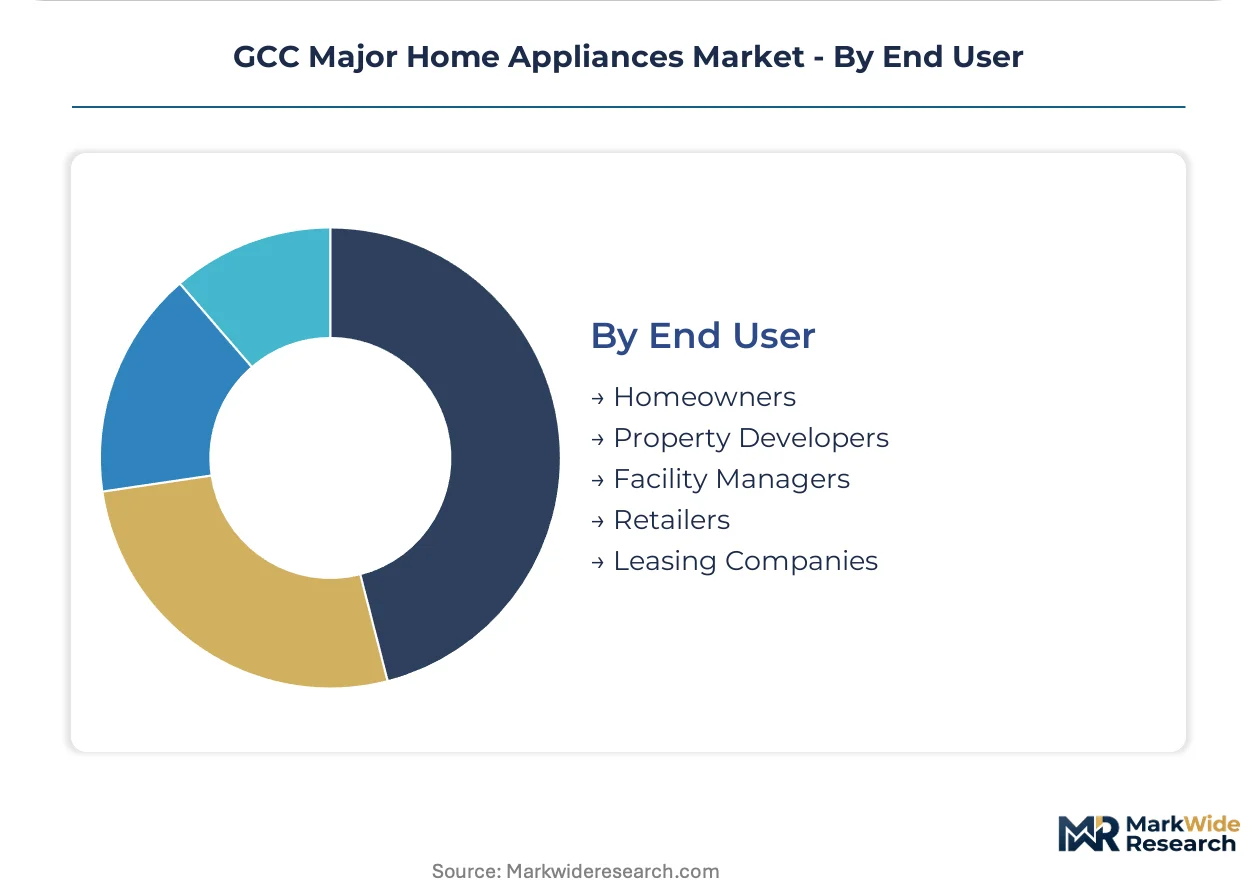
End User:
Customer type determines procurement channel structure and specification authority.
- Property Developers:Large-scale residential tower projects consolidate appliance procurement into master specifications. Dubai and Riyadh master-planned communities bypass traditional retail channels through direct manufacturer relationships.
- Homeowners:Individual purchasers drive replacement cycles through retail and e-commerce channels. Tariff sensitivity across Saudi Arabia's central corridor accelerates inverter adoption amid electricity cost pressures.
- Facility Managers:Commercial and institutional environments with maintenance contract responsibilities.
- Retailers:Distribution intermediaries with inventory and service obligations.
- Leasing Companies:Asset owners with standardization and durability requirements.
Channel concentration favors Property Developers; replacement frequency favors Homeowners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Standards, Metrology and Quality Organization anchors the region's regulatory architecture through tiered efficiency mandates that redirect procurement toward inverter-driven cooling systems. These frameworks compress the viable product set for importers while elevating baseline specifications across the six-member Gulf Cooperation Council.
Saudi Arabia
Riyadh corridor residential expansion and Jeddah coastal upgrades concentrate demand for heavy-duty washing machines and inverter air conditioners. SASO energy labeling mandates accelerate obsolescence of pre-2019 fixed-speed inventory. Central province master-planned communities specify variable-speed compressor systems exclusively under tier 1 requirements.
United Arab Emirates
Dubai premium residential towers embed Wi-Fi enabled appliance frameworks into master specifications that bypass traditional retail channels. Emirates Authority for Standardization and Metrology efficiency tiers restrict market access for non-compliant imports. UAE coastal zones sustain commercial-grade demand from hospitality and healthcare facilities with premium service contracts.
Qatar
Doha metropolitan construction and hospitality sector expansion drive procurement for heavy-duty cycle dishwashers and sterilization-grade equipment. The Ministry of Commerce and Industry enforces Gulf Standardization Organization harmonized standards that reduce technical barriers. Lusail City development concentrates demand for smart-connected building infrastructure.
Kuwait
Summer heat intensity and electricity tariff sensitivity accelerate residential replacement cycles toward inverter compressor platforms. The Public Authority for Industry administers conformity assessment requirements that elevate import thresholds. Hawalli and Salmiya residential corridors concentrate retail channel demand for energy-efficient cooling systems.
Oman
Muscat metropolitan expansion and tourism infrastructure investment sustain demand for commercial-grade laundry and kitchen equipment. The Ministry of Commerce, Industry and Investment Promotion aligns with Gulf Standardization Organization technical regulations. Duqm special economic zone development attracts supplier distribution hub establishment.
GCC Major Home Appliances Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the GCC major home appliances competitive structure. Korean and Chinese manufacturing conglomerates leverage regional production footprints to compress lead times into Saudi and UAE distribution hubs. Specialist fabricators from Turkey and Europe compete on brand equity and premium positioning among affluent homeowner segments. Dominant competitive moves include strategic partnerships with large-scale property developers and portfolio diversification into smart-connected platforms.
Within the integrated manufacturing tier, Samsung Electronics Co. Ltd. and LG Electronics Inc. exemplify scale-driven positioning through regional supply chain proximity. Midea Group Co. Ltd. occupies a position among Chinese industrial conglomerates with diversified appliance portfolios. These three anchors represent the competitive archetypes shaping procurement relationships with GCC developer consortiums and retail distribution networks.
| Leading Market Players |
|---|
| BSH Hausgeräte GmbH |
| Electrolux AB |
| LG Electronics Inc. |
| Midea Group Co. Ltd. |
| Panasonic Corporation |
| Samsung Electronics Co. Ltd. |
| Haier Group Corporation |
| Arçelik A.Ş. |
| Whirlpool Corporation |
| Others |
Supply & Pricing Matrix
Inverter compressor technology substitution for fixed-speed systems simultaneously relocates manufacturing gravity toward Egypt-based production platforms and compresses margin structures for distributors holding legacy inventory. This displacement dynamic concentrates pricing power among manufacturers with certified variable-speed platforms while stranding conventional compressor stock across Saudi and UAE wholesale channels.
Pricing Analysis
Price spreads between Dubai premium tower specifications and Kuwait retail channels exceed three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on SASO tier certification status and after-sales service bundling with installation warranties. Pricing pressure stems from Egyptian manufacturing proximity undercutting landed costs for Far East imports. Property developers exhibit lowest price sensitivity due to master-specification consolidation, while individual homeowners in Riyadh corridor retail channels drive hardest bargain negotiations.
Supply Chain Analysis
Strait of Hormuz transit underwrites container routing for Korean and Chinese manufacturing hubs serving UAE distribution centers. Raw material dependencies center on copper winding stock, refrigerant compounds, and semiconductor control modules. Supply chain risk concentrates in single-source vulnerability for inverter drive controllers sourced from South Korean fabs. Distribution runs through developer-direct procurement relationships that bypass traditional retail wholesale tiers in Dubai and Riyadh master-planned communities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across property developer master agreements, hospitality service contracts, and retail replacement cycles creates multiple entry vectors for specialized positioning. Developer specification authority consolidation fragments further as mid-tier Saudi construction consortia seek differentiated appliance sourcing.
For Market Incumbents: Fortify inverter technology certification portfolios against SASO tier escalation threats by deepening backward integration into compressor manufacturing. Anchor channel control through exclusive service partnerships with Riyadh and Dubai developer procurement teams. Expand Egypt production capacity to compress lead times against emerging Chinese regional entrants. For New Entrants and Emerging Players: ESMA fast-track certification for Wi-Fi enabled platforms opens white-space penetration in Dubai premium residential specifications underserved by legacy fixed-speed suppliers. Target Oman Duqm special economic zone distribution hub establishment as regional logistics anchor. Pursue hospitality-grade dishwasher and heavy-duty laundry equipment gaps in Qatar healthcare facility procurement. For Investors and Strategic Acquirers: Gulf Standardization Organization harmonization completion reshapes the acquisition landscape toward cross-border procurement platform consolidation. Five-to-ten year viability favors manufacturers with captive inverter compressor technology and regional conformity assessment laboratory partnerships. Monitor technician labor nationalization quota enforcement as inflection signal for service-network-dependent valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Platform Certification | SASO tier compliance secures access to Saudi central province master-planned community specifications. |
| Egypt Manufacturing Footprint | Regional production proximity compresses lead times into UAE and Saudi distribution hubs versus Far East sourcing. |
| Developer Direct Partnership | Master specification relationships bypass fragmented retail channels in Dubai premium tower construction. |
| Smart Connectivity Integration | Wi-Fi enabled frameworks align with ESMA efficiency tiers and building management system embedding requirements. |
| Hospitality Service Contract | Heavy-duty cycle specifications with rapid response commitments sustain premium pricing in UAE coastal zones. |
Research Methodology
Cross-validation between distributor inventory data and developer procurement documentation anchors the qualitative findings on specification evolution. Primary interviews with appliance category managers, HVAC contractor operations heads, and property developer procurement directors combined with secondary validation from SASO technical regulation filings, ESMA efficiency tier databases, and customs import manifests. Bottom-up channel volume estimates triangulate against top-down construction pipeline assessments across the analysis window.
Sensitivity analysis on heat intensity projections and electricity tariff trajectories shapes the analytical framework. Segmentation dimensions span product category, technology tier, application environment, and end-user procurement authority across the modeling period. CAGRs derive from replacement cycle velocity assumptions and new construction penetration rates, with inverter adoption curves and smart connectivity embedding rates as industry-specific forecast inputs.
Underlying assumptions cover regulatory tier enforcement consistency and expatriate labor availability stabilization, with deviation risk concentrated in technician certification bottleneck severity and refrigerant phase-down schedule acceleration. Practitioners should keep alternative scenarios live as Gulf Standardization Organization harmonization implementation timelines and nationalization quota enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
North America Electric Fireplace Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Argentina Home Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Italy Home Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Chile Home Appliances Market