
 Japan Small Home Appliances Market | 2026-2036
Japan Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Small Home Appliances Market Foresight
Single-person urban households is recalibrating demand toward compact, multi-functional appliances that maximize utility in limited kitchen spaces. Panasonic Corporation leverages its deep domestic manufacturing footprint to sustain price competitiveness across rice cooker and coffee maker lines. Zojirushi Corporation anchors premium positioning through precision temperature control technology in its thermal appliances. Tiger Corporation specializes in vacuum-insulation engineering that differentiates its product portfolio from mass-market alternatives.
Japan small home appliances encompass electrically powered compact equipment designed for domestic food preparation, beverage brewing, and thermal processing, typically operating at 100V with power draws between 300W and 1,500W and incorporating stainless steel heating elements or microprocessor-controlled induction systems. These devices serve residential and light commercial users requiring automated, space-efficient alternatives to manual cooking methods. Smart appliances incorporating IoT connectivity and voice-assistant integration represent the fastest-expanding technology segment as manufacturers respond to aging demographics seeking simplified operation interfaces. Rice cookers retain the most mature product type position with saturated household penetration, while blenders capture emerging interest from health-conscious younger consumers driving replacement cycles.
METI enforces stringent energy-efficiency labeling under its Top Runner Program, compelling manufacturers to redesign heating elements and standby power circuits to maintain market access. The Consumer Affairs Agency coordinates with JIS standards bodies to establish electrical safety and electromagnetic compatibility requirements that filter out non-compliant imports. PMDA oversight extends to appliances with health-related claims such as nutrient-preservation features. Stakeholders must monitor evolving interoperability standards between smart appliances and domestic IoT platforms as METI advances its Society 5.0 implementation roadmap.
Market Dynamics
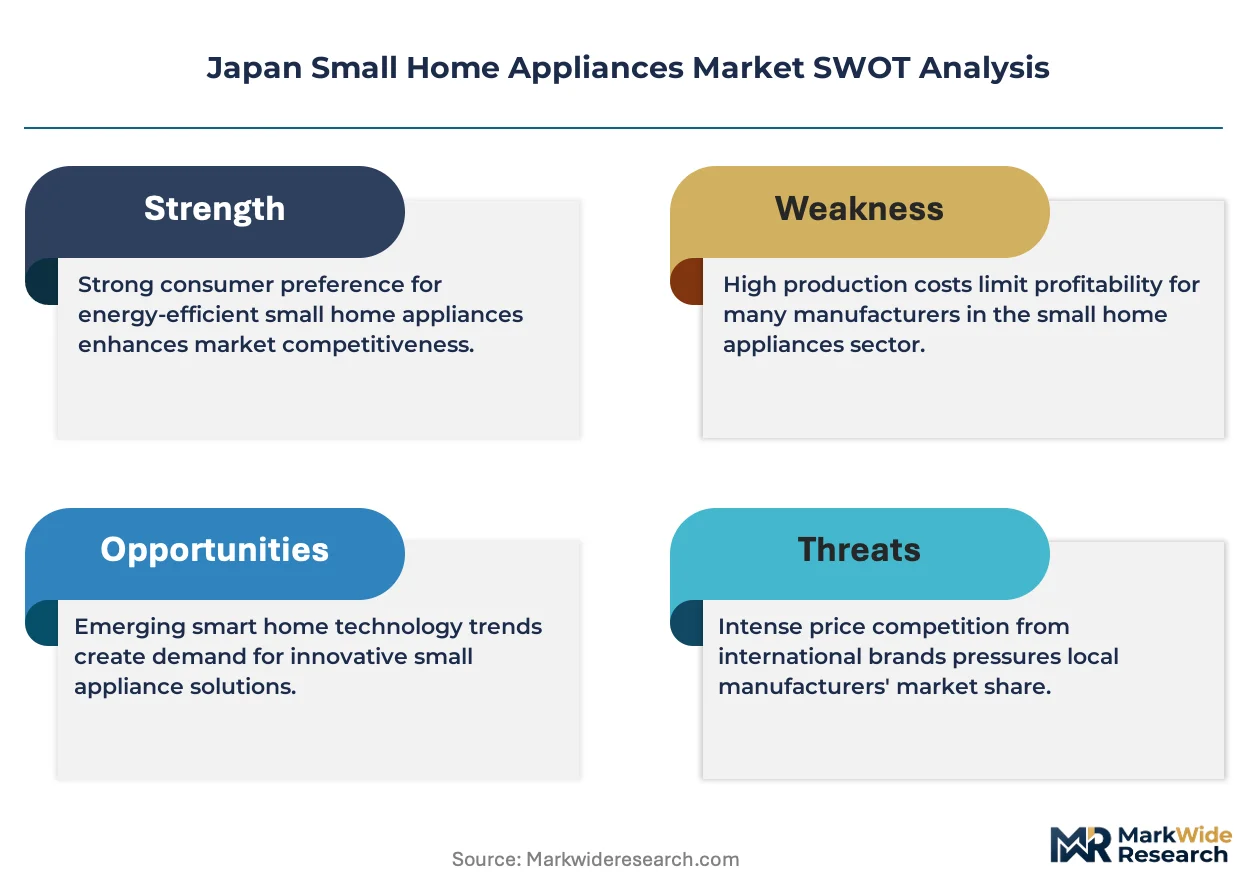
Japan's small home appliances sector faces structural recalibration from METI's Top Runner Program, which mandates continuous efficiency improvements in standby power and heating element design. This regulatory pressure compresses product development cycles while elevating compliance costs for domestic manufacturers.
Growth Catalysts
- Single-person household expansion:Urban Tokyo and Osaka corridors now host record concentrations of solo dwellers, generating sustained pull for compact multi-function kitchen equipment.
- METI Society 5.0 roadmap:Smart-home interoperability mandates accelerate IoT platform integration across appliance categories, creating upgrade incentives.
- Health-conscious consumption:Nutrient-preservation features in thermal appliances attract younger demographics seeking functional benefits beyond basic cooking.
Market Restraints
- Nickel and copper volatility:Stainless steel heating elements and induction coil materials face input cost pressure from commodity market swings.
- Saturated rice cooker penetration:Near-universal household ownership in Japan eliminates volume growth in the largest product category.
- Import competition from Southeast Asia:Lower-cost manufacturing bases erode price positioning in entry-level segments.
Strategic Opportunities
- Kyushu and Tohoku underpenetration:Secondary metropolitan zones outside Tokyo-Osaka corridor offer whitespace for smart appliance distribution expansion.
- Voice-assistant convergence:Integration with Amazon Alexa and Google Home platforms opens premium positioning for aging-user accessibility.
- PMDA health-claim pathway:Regulatory framework for nutrient-preservation certification enables differentiated marketing in thermal processing equipment.
Industry Challenges
- Firmware engineering talent scarcity:IoT connectivity requirements outpace domestic supply of embedded systems specialists.
- JIS certification timelines:Electromagnetic compatibility testing creates 4-6 month product launch delays.
- Legacy platform integration:Smart appliances must interoperate with fragmented domestic IoT standards without alienating non-connected users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Small Home Appliances Market |
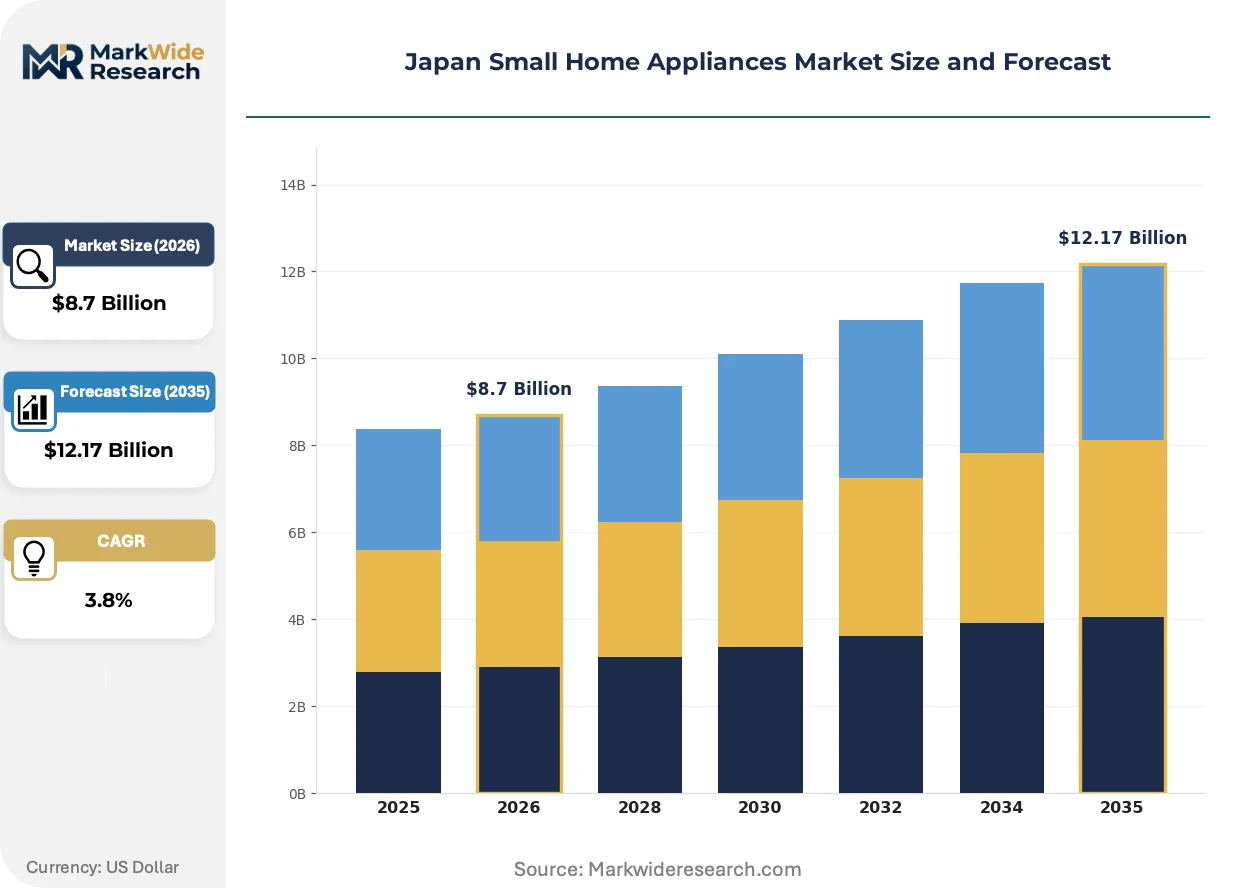
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Toasters, Coffee Makers, Rice Cookers Technology: Smart Appliances, Energy Efficient, Manual, Automatic End User: Residential, Commercial, Institutions, Hospitality Distribution Channel: Online Retail, Direct Sales, Supermarkets, Specialty Stores |
| Companies Covered | Mitsubishi Electric Corporation, LG Electronics, Panasonic Corporation, Zojirushi Corporation, Samsung, Sharp Corporation, Toshiba Corporation, Tiger Corporation, Hitachi, Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Small Home Appliances Market Shifts & Advancements
Three distinct vectors reshape Japan's small appliance landscape: connected functionality, efficiency mandates, and demographic-responsive design. Each trend carries specific implications for product architecture and go-to-market strategy.
Induction heating systems with microprocessor-controlled temperature curves are integrating precision thermal management into compact form factors. Single-person urban households adopt these systems fastest, replacing conventional resistive heating for rice and beverage preparation. This technology is integrating automated cooking programs that eliminate manual monitoring, compressing the skill barrier for complex preparations.
METI's 2024 revision to Top Runner standards tightens standby power limits below one watt for most appliance categories. Manufacturers must redesign power supply circuits and standby logic to maintain market access. Rice cookers and thermal carafes face the steepest redesign burden, with domestic producers accelerating solid-state relay adoption.
Subscription-based accessory replenishment is emerging as a preferred channel for consumable-dependent appliances. Coffee maker and water purifier segments lead this shift, with direct-to-consumer platforms displacing traditional retail for filter and cartridge replacement. Greater Tokyo Area consumers show highest uptake, driven by convenience prioritization among time-constrained professionals.
Japan Small Home Appliances Market Segmentation
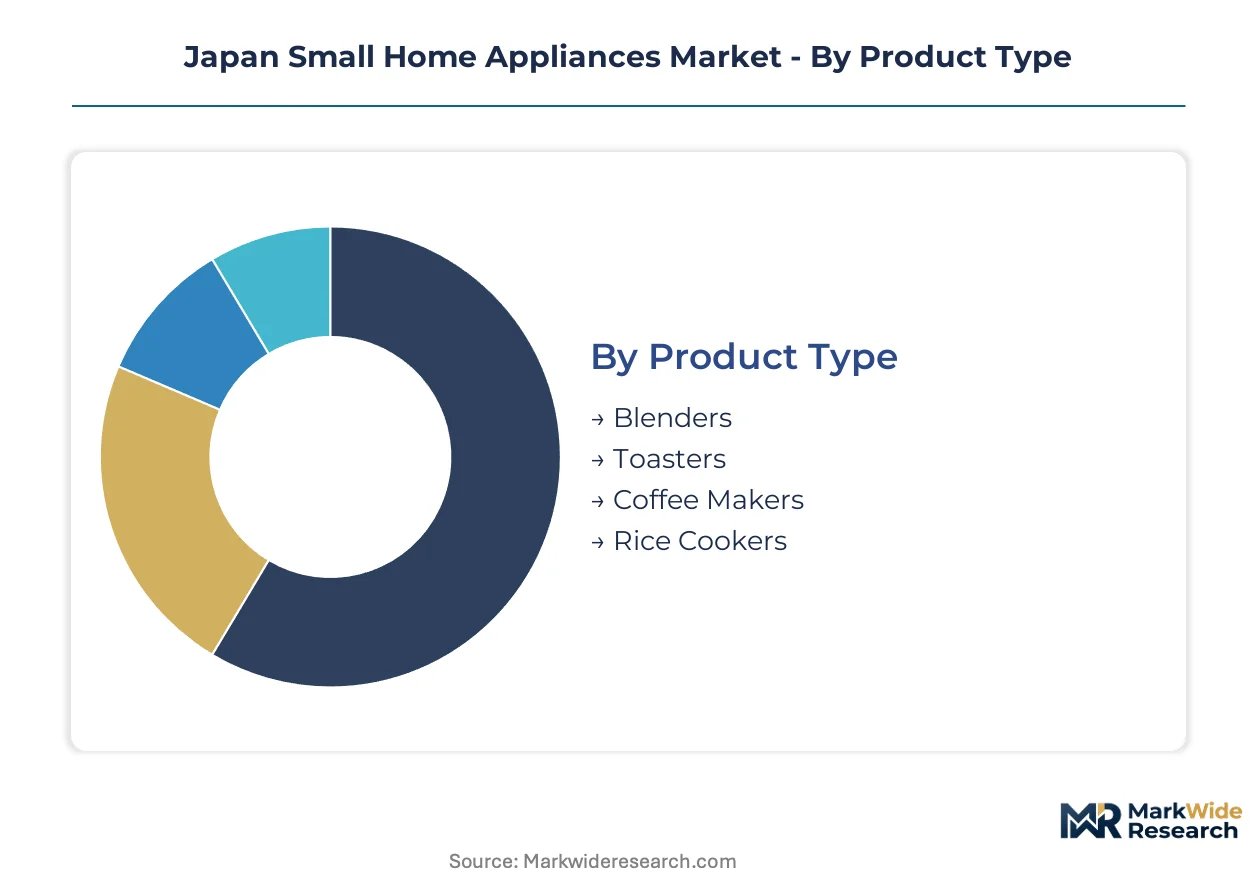
Segmentation in Japan's small home appliances market exposes divergent profit pools across technology tiers and channel structures. Manufacturers calibrate R&D allocation and pricing architecture differently for saturated categories versus emerging connectivity-enabled segments.
Product Type:
Rice cookers anchor volume shipments while blenders capture premium expansion from health-oriented urban consumers.
- Rice Cookers:Microprocessor-controlled induction heating systems with multi-stage temperature curves dominate Japanese households. Near-universal penetration in Greater Tokyo and Osaka-Kobe corridors eliminates volume growth, forcing manufacturers toward replacement-cycle acceleration through IoT-enabled models.
- Blenders:High-speed blade systems with nutrient-preservation programming attract younger demographics seeking smoothie preparation and ingredient processing. Health-conscious consumption in Tokyo's central wards drives fastest category expansion among all product types.
- Coffee Makers:Drip and espresso configurations with thermal carafe integration serve single-person households prioritizing convenience.
- Toasters:Compact infrared and convection variants address space constraints in urban apartments with limited counter area.
Today's leader: Rice Cookers. Tomorrow's challenger: Blenders.
Technology:
Cost tier stratification separates compliance-driven efficiency upgrades from discretionary smart-home investments.
- Smart Appliances:Wi-Fi-enabled devices with voice-assistant integration and remote monitoring capabilities. METI Society 5.0 interoperability mandates accelerate adoption in Greater Tokyo Area, though firmware engineering scarcity constrains domestic development timelines.
- Energy Efficient:Solid-state relay heating elements and sub-one-watt standby circuits meeting Top Runner Program thresholds. METI's 2024 revision forces redesign cycles across rice cooker and thermal appliance portfolios.
- Automatic:Microprocessor-controlled operation with preset cooking programs eliminating manual intervention.
- Manual:Basic electromechanical controls serving price-sensitive segments and secondary metropolitan zones.
Compliance requirements favor Energy Efficient. Consumer pull concentrates in Smart Appliances.
End User:
Application concentration tilts heavily toward residential installations, with commercial segments offering specialized margin structures.
- Residential:Single-person urban households in Tokyo and Osaka corridors drive compact multi-function demand. Space constraints and convenience prioritization shape purchasing decisions across all product categories.
- Commercial:Light food-service operations in convenience stores and small restaurants requiring durable thermal processing equipment.
- Hospitality:Hotel breakfast service and in-room amenity configurations with standardized aesthetic requirements.
- Institutions:Corporate cafeterias and educational facilities with high-throughput, low-complexity preparation needs.
Volume concentration: Residential. Margin opportunity: Commercial.
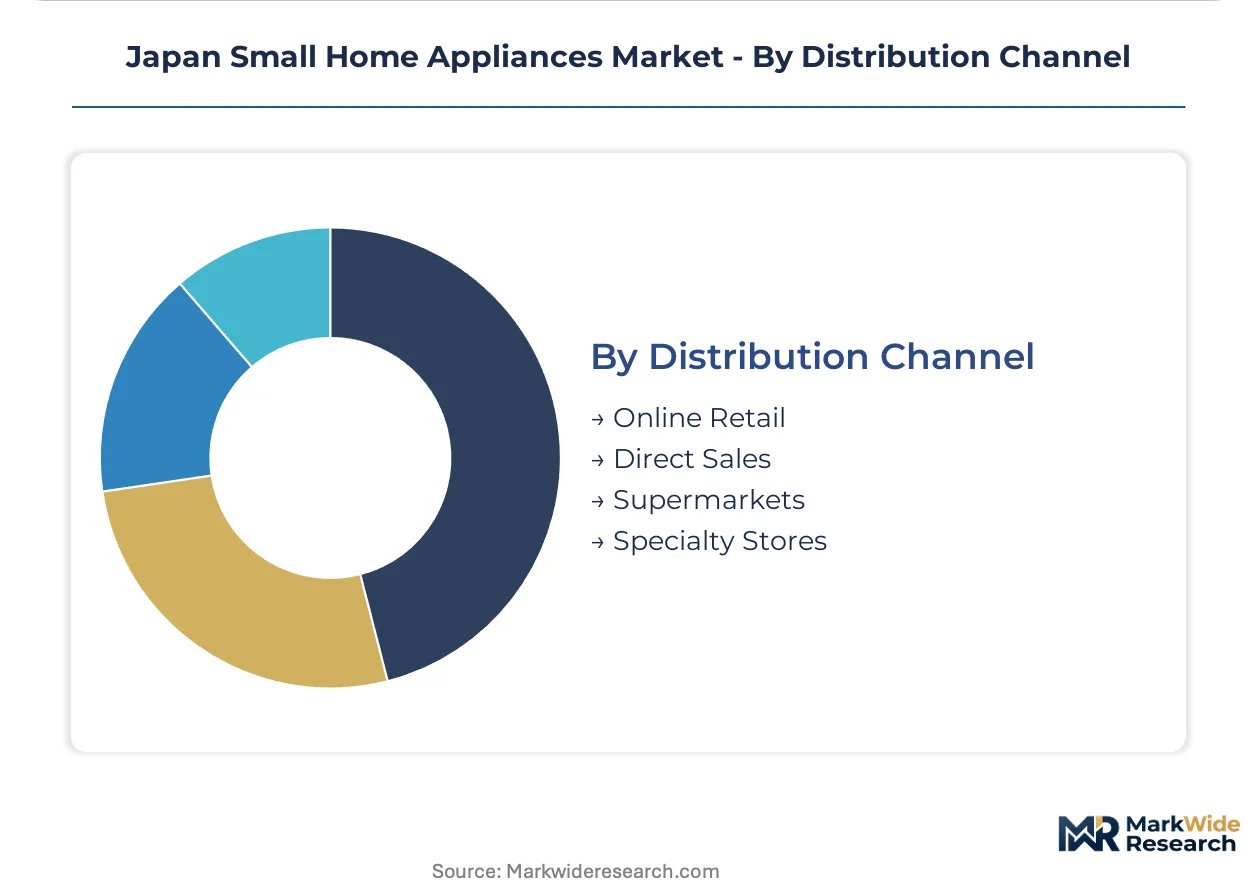
Distribution Channel:
Customer type fragmentation separates subscription-oriented professionals from tactile-preference traditionalists.
- Online Retail:Direct-to-consumer platforms with subscription-based accessory replenishment for coffee maker filters and water purifier cartridges. Greater Tokyo Area professionals show highest uptake driven by convenience prioritization.
- Specialty Stores:Hands-on demonstration environments where thermal performance and build quality validation drive premium appliance selection.
- Supermarkets:Mass-market penetration for entry-level rice cookers and basic toasters with impulse-purchase accessibility.
- Direct Sales:Manufacturer-controlled channels enabling bundled warranty and extended service offerings.
Channel momentum: Online Retail. Experience anchor: Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturers face a widening cost-of-compliance gap as METI efficiency mandates intensify, pushing production rationalization toward regions with lower regulatory overhead while preserving design and R&D functions within Japan.
Kanto/Tokyo
Greater Tokyo Area households drive premium smart-appliance adoption with space-constrained kitchens demanding multi-function equipment. METI's Society 5.0 interoperability standards accelerate IoT platform integration across Shibuya and Minato ward residences. Dense urban fabric in central Tokyo sustains highest per-capita spending on connected rice cookers and thermal appliances.
Kansai/Osaka
Osaka-Kobe metropolitan corridor hosts established manufacturing bases for precision thermal control systems serving both domestic and export markets. JIS certification requirements filter non-compliant imports through Kansai port customs processing. Sakai industrial zone maintains specialized production lines for vacuum-insulation components.
Chubu/Nagoya
Nagoya manufacturing cluster leverages automotive supplier ecosystem for precision electronics and microprocessor sourcing. METI Top Runner Program compliance costs concentrate engineering resources in this central Japan hub. Toyota City proximity enables cross-industry talent migration into appliance firmware development.
Kyushu
Fukuoka metropolitan zone shows underpenetrated smart-appliance distribution relative to income levels, creating whitespace for direct-to-consumer platform expansion. Regional energy-efficiency incentive programs supplement national METI standards. Kumamoto prefecture hosts emerging specialty retail networks targeting compact household equipment.
Tohoku
Sendai and surrounding prefectures exhibit slower replacement cycles for legacy appliances, extending product lifespans beyond national averages. Local government energy-subsidy programs accelerate adoption of Top Runner-certified equipment in post-disaster reconstruction housing. Morioka manufacturing zone supplies basic electromechanical components to national assembly networks.
Japan Small Home Appliances Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers hedge against saturated rice cooker penetration. The vendor base clusters around three distinct tiers: integrated electronics conglomerates with domestic manufacturing footprints, specialized thermal appliance houses with precision engineering heritage, and Korean diversified technology groups leveraging scale economies. Strategic archetypes separate efficiency-driven compliance specialists from premium-positioned innovation leaders and value-oriented import competitors. Technology licensing and backward integration into heating element supply represent the two most visible competitive moves.
Within the integrated conglomerate tier, Panasonic Corporation and Mitsubishi Electric Corporation exemplify domestic manufacturing anchoring strategies that sustain price competitiveness through captive production networks. Zojirushi Corporation and Tiger Corporation occupy the specialized precision-engineering segment, with their corporate nomenclature signaling thermal technology heritage. LG Electronics and Samsung represent the Korean technology-group archetype, importing scale-driven positioning from adjacent consumer electronics categories.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| LG Electronics |
| Panasonic Corporation |
| Zojirushi Corporation |
| Samsung |
| Sharp Corporation |
| Toshiba Corporation |
| Tiger Corporation |
| Hitachi, Ltd. |
| Others |
Supply & Pricing Matrix
Firmware engineering talent concentration in the Greater Tokyo Area and Osaka-Kobe corridor creates labor-cost differentials that widen pricing-tier spreads between smart-connected and basic electromechanical appliance segments. METI compliance burdens and JIS certification timelines compound these cost structures, forcing manufacturers to stratify portfolios across premium IoT-enabled, mid-tier automatic, and entry-level manual product lines.
Pricing Analysis
Retailer markup layers in specialty store channels absorb 25-35 points of gross margin before reaching residential end-users, while direct-to-consumer platforms compress this spread for subscription-dependent categories. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified smart appliances with voice-assistant integration from basic automatic models and import-competing manual alternatives. Pricing pressure stems from Southeast Asian manufacturing cost advantages in entry-level rice cooker and toaster segments. Commercial hospitality buyers exhibit lowest price sensitivity due to durability requirements and standardized aesthetic mandates.
Supply Chain Analysis
Single-source vulnerability sits with Chinese suppliers of solid-state relay components and South Korean providers of precision microprocessors for induction heating systems. Component sourcing draws from domestic Nagoya-area automotive electronics suppliers for firmware modules, Chinese foundries for heating element substrates, and Taiwanese fabs for Wi-Fi connectivity chipsets. Tariff exposure through Kansai port customs processing creates inventory holding cost pressure for non-JIS-certified imports. Distribution runs through captive direct-to-consumer platforms, specialty retail demonstration networks, and mass-market supermarket penetration for replacement-cycle acceleration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's small home appliances sector functions as a stable compounder anchored by irreversible single-person household expansion and mandatory METI efficiency upgrade cycles that sustain replacement demand regardless of macroeconomic volatility.
For Market Incumbents: To counter firmware engineering talent scarcity constraining IoT development timelines, Panasonic and Zojirushi should deepen backward integration into embedded systems training pipelines through Nagoya technical institute partnerships. Simultaneously, accelerate solid-state relay adoption to compress Top Runner compliance redesign cycles and defend margin position against Korean technology groups. For New Entrants and Emerging Players: Begin with Kyushu and Tohoku distribution whitespace where smart-appliance penetration lags income-adjusted expectations. Target Fukuoka metropolitan zone professionals through direct-to-consumer platforms with subscription-based filter replenishment for coffee maker categories, leveraging convenience prioritization absent from incumbent specialty store networks. For Investors and Strategic Acquirers: Korean diversified technology groups are the most active acquirer in this space, seeking thermal engineering heritage to complement scale-driven consumer electronics positioning. Acquisition targets should display precision temperature control IP and vacuum-insulation manufacturing capabilities. Monitor METI Society 5.0 interoperability standard finalization as inflection signal for smart-appliance upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home Platform Integration | Voice-assistant convergence with Amazon Alexa opens aging-user accessibility premium positioning. |
| Subscription Accessory Replenishment | Direct-to-consumer filter cartridge replacement displaces traditional retail in Greater Tokyo Area. |
| Energy Efficiency Redesign | Solid-state relay adoption meets METI 2024 Top Runner standby power thresholds. |
| PMDA Health-Claim Certification | Nutrient-preservation feature validation enables differentiated thermal appliance marketing. |
| Kyushu Distribution Expansion | Fukuoka metropolitan zone underpenetration offers whitespace for direct-to-consumer platforms. |
Research Methodology
Coverage spans Kanto, Kansai, Chubu, Kyushu, and Tohoku, with primary inputs from each region combined with secondary validation. Primary interviews engaged product development directors at Panasonic and Zojirushi, procurement managers at Tokyo and Osaka specialty retailers, firmware engineering leads in Nagoya automotive supplier ecosystems, and METI standards compliance officers. Secondary sources incorporated JIS certification databases, METI Top Runner Program filings, Consumer Affairs Agency safety reports, and customs records through Kansai port authorities. Bottom-up shipment data triangulated against top-down household penetration estimates across single-person urban dwelling segments.
Rate-of-change decomposition across the projection horizon modeled product type segmentation by rice cooker, blender, coffee maker, and toaster categories; technology tiers spanning smart, energy efficient, automatic, and manual; and distribution channel splits between online retail, specialty stores, supermarkets, and direct sales. CAGRs derived from replacement cycle acceleration patterns, demographic household formation trends, and regulatory mandate compliance deadlines. Industry-specific inputs included METI Society 5.0 interoperability roadmap milestones and PMDA health-claim certification pathway evolution.
Several conditions sit outside the modeled scope, including unforeseen commodity price spikes in nickel and copper heating element materials, sudden JIS certification timeline extensions, and geopolitical disruptions to Chinese solid-state relay supply. Forecasts reflect documented assumptions regarding single-person household formation persistence and METI regulatory enforcement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
India Laundry Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
Household Refrigerator Market
Home Appliances
Japan Home Appliances Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
European Built-In Refrigerator Market
Home Appliances
Residential Dishwashers Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
United States Laundry Appliances Market