
 Latin America Laundry Appliances Market | 2026-2036
Latin America Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Laundry Appliances Market Foresight
The capital-intensity gap between global OEMs and regional assemblers is collapsing as modular inverter-motor platforms slash tooling requirements for efficient washing-machine production. Whirlpool Corporation leverages its Monterrey manufacturing complex to sustain cost-competitive exports throughout Central America and the Caribbean. AB Electrolux anchors its regional position through specialized front-load lines targeting Brazil's middle-class condominium market.
Latin America laundry appliances encompass electrically powered equipment for washing, rinsing, spinning, and drying textile goods, with drum capacities typically spanning six to twenty kilograms and spin speeds reaching fourteen hundred revolutions per minute for residential units. The primary commercial purpose centers on automating fabric cleaning cycles for households, commercial laundromats, hospitality operators, and healthcare facilities seeking hygiene-compliant linen processing. Front-load washing machines command premium positioning due to superior water and energy efficiency, while top-load variants retain volume leadership across price-sensitive markets in Mexico and Colombia. Smart appliances represent the fastest-expanding technology tier as Wi-Fi-enabled diagnostic and remote-cycle management features penetrate upper-middle residential segments in São Paulo and Buenos Aires.
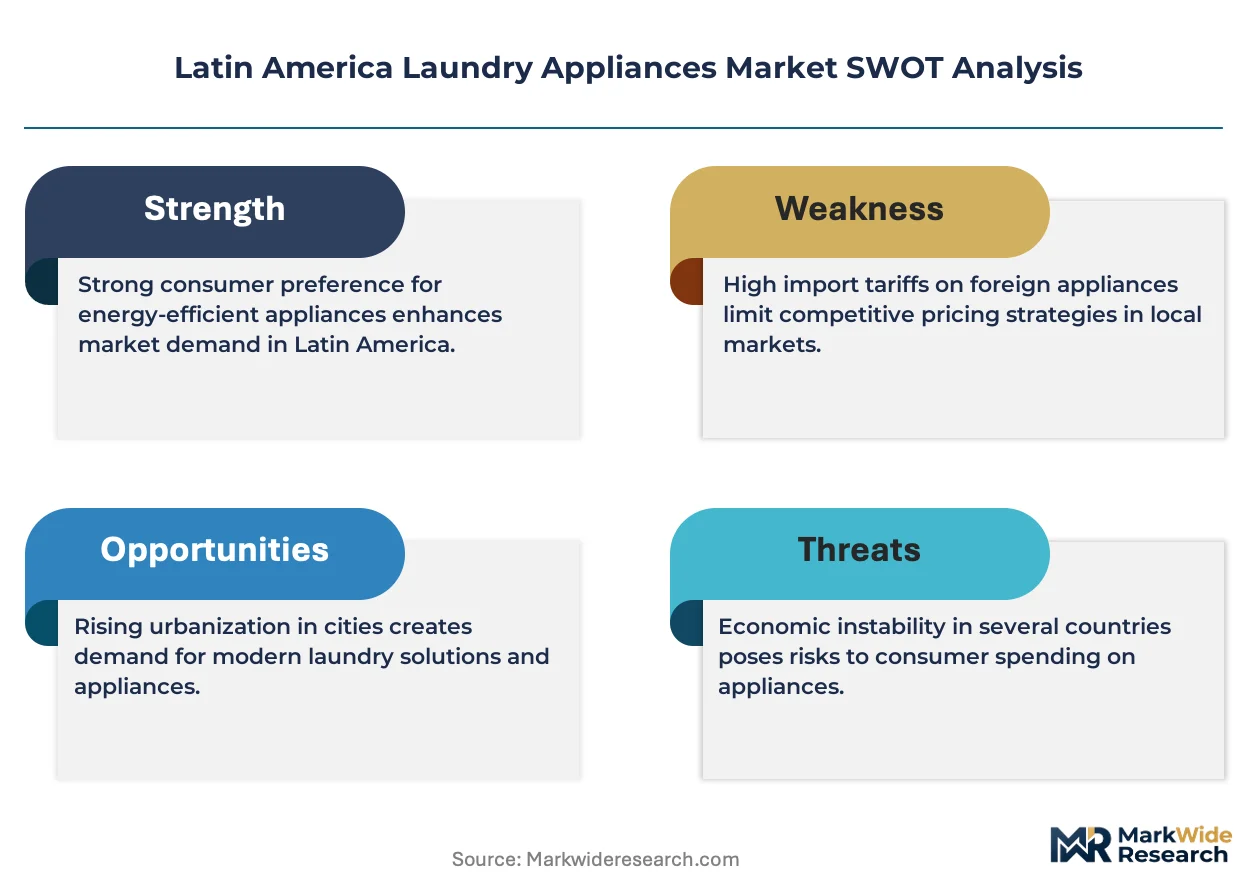
INMETRO certification requirements in Brazil and Argentina's IRAM safety standards shape mandatory efficiency thresholds and electrical safety protocols for all imported and domestically manufactured units. Mexico's PROFECO consumer-protection framework enforces truthful energy-labeling claims, creating compliance costs that filter smaller trading operations from formal retail channels. Stakeholders must monitor how pending water-usage restrictions in Chile and Peru's coastal cities redirect R&D investment toward ultra-low-consumption drum designs.
Market Dynamics
Modular inverter-motor platforms are collapsing capital barriers between global OEMs and regional assemblers, forcing a rapid recalibration of manufacturing scale economics across Brazil, Mexico, and Argentina. This technology diffusion is redistributing production capacity toward mid-tier players who previously lacked access to efficient drum-drive systems.
Growth Catalysts
- INMETRO energy-efficiency mandates:Brazil's labeling requirements compel manufacturers to redesign motor and heating systems, accelerating inverter adoption across the residential base.
- Urban condominium expansion:São Paulo and Rio de Janeiro's vertical residential construction creates concentrated demand for compact front-load units with stackable configurations.
- Heat-pump drying technology:Rising electricity tariffs in Argentina and Chile make ventless heat-pump dryers economically viable for middle-class households previously restricted to air-drying.
Market Restraints
- Steel and copper input volatility:Drum housings and motor windings depend on commodity prices that swing with Chinese construction cycles, compressing assembler margins unpredictably.
- Single-source inverter module concentration:Brazil and Mexico rely on a narrow supplier base in East Asia for variable-frequency drive components, exposing production schedules to shipping disruptions.
- Water-scarcity infrastructure mismatch:Ultra-low-consumption machines require household plumbing retrofits that lag appliance replacement cycles in Peru's coastal cities.
Strategic Opportunities
- Colombia's underpenetrated automated laundry base:Manual washing persists in 40% of Bogotá and Medellín households, creating a conversion market for basic top-load units with financing plans.
- IRAM safety standard harmonization:Argentina's alignment with IEC 60335-2-7 reduces certification duplication costs for manufacturers serving both Mercosur and Andean markets.
- Wi-Fi module + utility demand-response integration:Smart appliances that synchronize with grid peak pricing create value for Brazilian utilities seeking load-shifting partners.
Industry Challenges
- Inverter-motor calibration technician scarcity:Brazil's vocational training pipeline produces insufficient field service engineers capable of diagnosing variable-frequency drive faults in warranty periods.
- PROFECO compliance documentation burden:Mexico's consumer protection framework requires extensive energy-test verification that delays product launches by four to six months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Laundry Appliances Market |
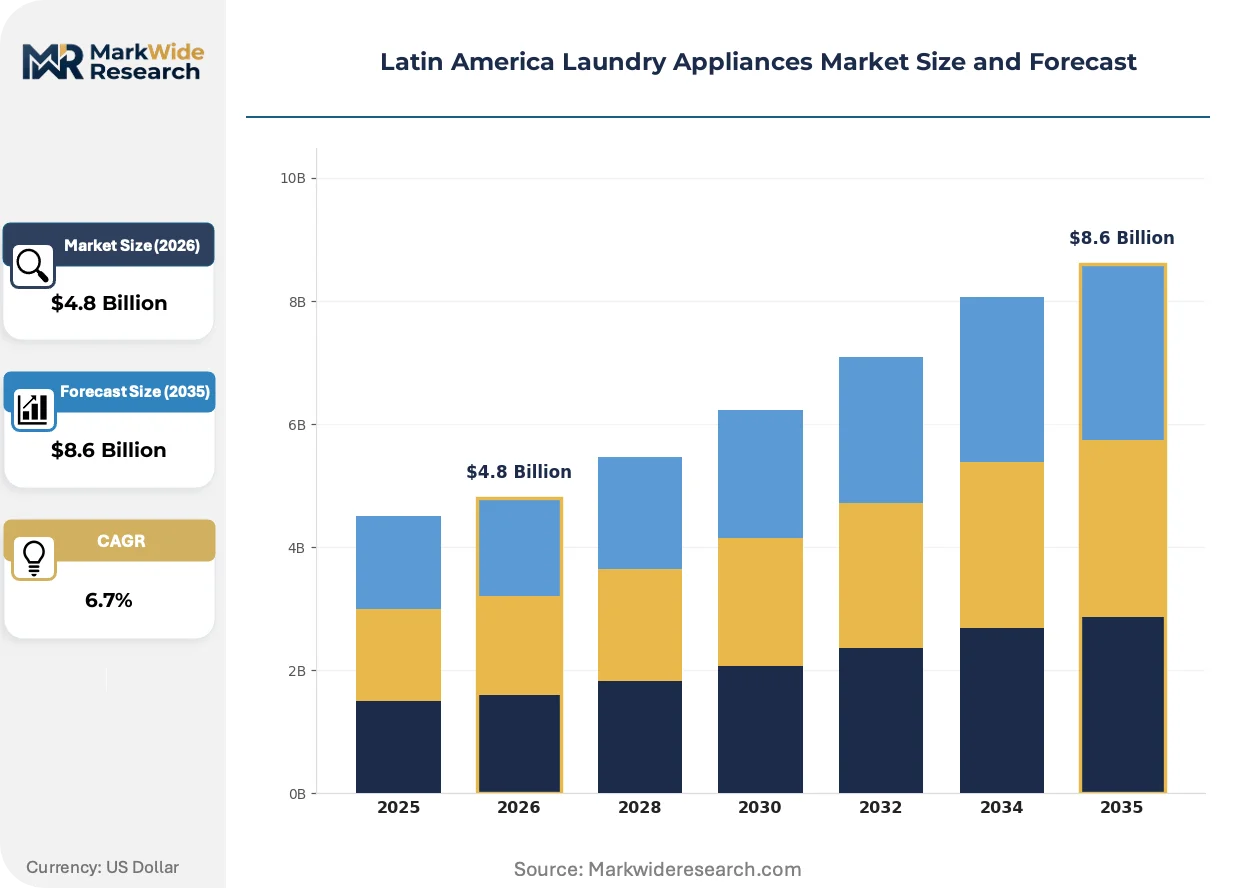
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Coin-Operated Machines End User: Residential, Commercial Laundries, Hospitality, Healthcare Facilities Technology: Front Load, Top Load, Hybrid, Smart Appliances Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Whirlpool Corporation, AB Electrolux, Samsung, LG Electronics, Panasonic Corporation, Miele, Haier Electronics Group Co Ltd, Bosch, Groupe SEB, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Laundry Appliances Market Shifts & Advancements
Active motor control algorithms and connected-appliance architectures are compressing the performance gap between premium and mid-tier laundry equipment. These shifts are rewriting how manufacturers segment their portfolios and how retailers merchandise replacement cycles.
Direct-drive inverter motors are eliminating belt-and-pulley transmission systems from mid-price washing machines. Brazilian and Mexican assemblers now source these platforms from Tier-2 motor suppliers, accelerating adoption in condominium-dense markets where noise reduction commands rent premiums. This mechanical simplification is displacing traditional induction-motor production lines and eroding the service-revenue base of independent repair networks.
Argentina's IRAM safety standards and Chile's pending water-usage restrictions are tightening compliance thresholds for drum-design efficiency. Manufacturers must now certify spray-pattern optimization and load-sensing accuracy under standardized test protocols. Front-load platforms targeting Buenos Aires and Santiago are absorbing the bulk of R&D redirection, with top-load variants losing shelf space in formal retail channels.
Appliance-as-service leasing models are penetrating São Paulo's property-management sector, unbundling capital expenditure from monthly operating costs. Multifamily operators now specify connected machines with usage-based billing, displacing traditional unit-purchase decisions by individual tenants. This procurement restructuring concentrates buyer power among large real-estate portfolios and compresses replacement cycles to match lease durations rather than product lifespans.
Latin America Laundry Appliances Market Segmentation
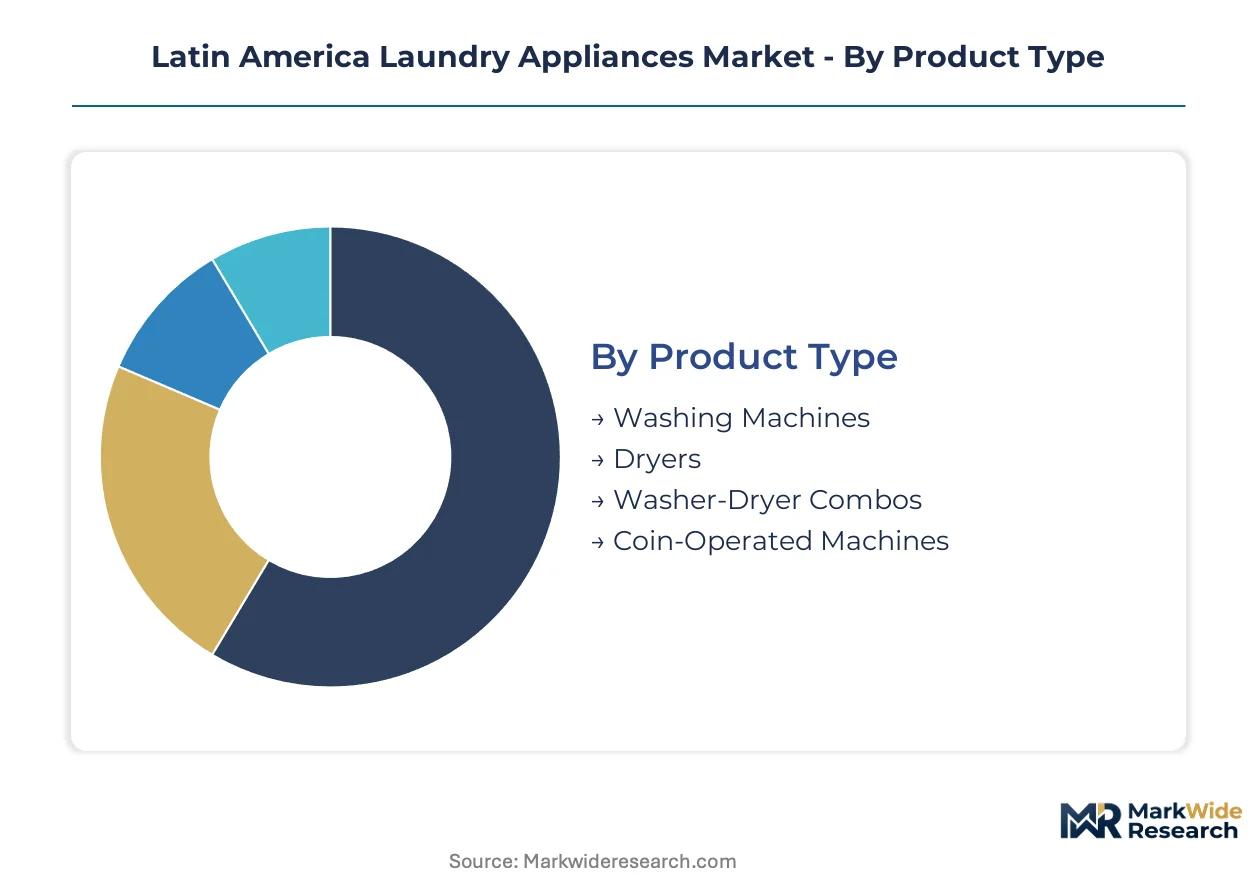
Segmentation in Latin America laundry appliances reveals how regulatory pressure and urban housing patterns split demand across technical specifications and procurement channels. Manufacturers must align inverter-motor platforms and connected features with distinct buyer economics in São Paulo condominiums versus Bogotá rental housing.
Product Type:
Margin pools concentrate in full-size washing machines and heat-pump dryers where INMETRO efficiency premiums justify price architecture, while coin-operated formats extract value through usage-based revenue models.
- Washing Machines:Drum capacities from six to twenty kilograms dominate residential procurement, with front-load variants capturing premium positioning in Brazil's vertical housing corridors due to stackable configurations and water-consumption compliance. São Paulo's condominium developers specify these units in bulk for new construction, driving specification lock-in that stretches replacement cycles.
- Dryers:Heat-pump technology is displacing vented electric models in Argentina and Chile as electricity tariffs reshape operating-cost calculations for middle-class households. Buenos Aires apartment dwellers increasingly accept ventless designs despite longer cycle times, trading speed for installation flexibility.
- Washer-Dryer Combos:Single-unit formats serve space-constrained urban households in Rio de Janeiro and Lima where dedicated laundry rooms are absent.
- Coin-Operated Machines:Commercial laundromat operators in Mexico City and Medellín deploy these for pay-per-use revenue, with connected payment modules reducing cash-handling overhead.
The dominant share belongs to washing machines, while dryers are closing the gap fastest.
End User:
Volume concentration sits with residential households, though commercial and institutional buyers concentrate procurement power through specification influence and fleet replacement schedules.
- Residential:Urban households in Brazil's southeastern corridor and Mexico City metropolitan area drive automated-laundry adoption, with financing plans converting manual-washing households in Colombia's secondary cities. INMETRO labeling shapes purchase decisions as energy costs claim growing shares of household budgets.
- Commercial Laundries:Independent operators and franchise networks in Santiago and Buenos Aires require industrial-capacity equipment with rapid cycle times and linen-throughput optimization.
- Hospitality:Hotel chains in Cancún and Rio de Janeiro specify hygiene-certified machines with thermal disinfection cycles for guest-linen processing.
- Healthcare Facilities:Hospitals in São Paulo and Mexico City demand infection-control compliance through high-temperature wash programs and barrier-separated clean-dirty workflows.
Residential buyers command volume leadership, with commercial laundries expanding most quickly.
Technology:
Cost tier stratification separates belt-drive induction systems from inverter-motor platforms, with smart connectivity adding a third price band that concentrates in upper-middle urban segments.
- Front Load:Horizontal-drum designs with tumble-action washing achieve superior water and energy efficiency through lower fill levels and faster spin extraction. Brazil's INMETRO labeling mandates accelerate adoption as manufacturers redesign motor systems to hit A-grade thresholds.
- Top Load:Vertical-axis machines with agitator or impeller mechanisms retain price-sensitive volume in Mexico and Colombia, where purchase-price sensitivity outweighs lifetime operating-cost considerations.
- Hybrid:Dual-function platforms combining washing and drying in single drums serve space-constrained markets in Lima and Caracas.
- Smart Appliances:Wi-Fi-enabled diagnostic and remote-cycle management features penetrate São Paulo and Buenos Aires upper-middle segments, with utility demand-response integration creating value for Brazilian grid operators seeking load-shifting partners.
Front-load configurations hold the dominant share, while smart appliances are gaining share fastest.
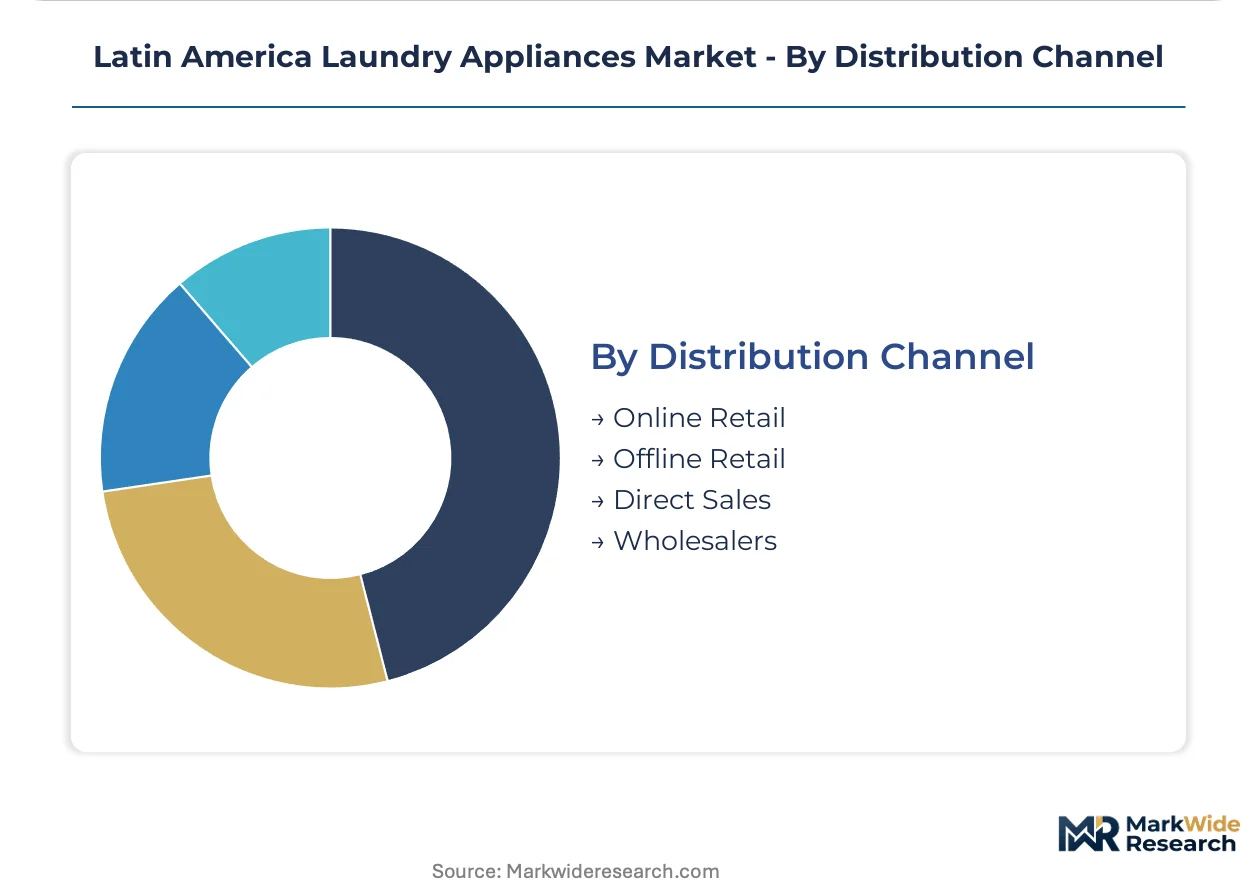
Distribution Channel:
Supply concentration favors offline retail for appliance categories requiring installation coordination, though online platforms capture growing share in replacement cycles and accessory sales.
- Online Retail:E-commerce platforms capture replacement-cycle purchases and compact-unit sales where delivery logistics are straightforward, with financing integration driving conversion in price-sensitive markets.
- Offline Retail:Brick-and-mortar chains dominate full-size washing machine and dryer sales through in-store demonstration and installation-service bundling, particularly in Brazil's formal retail corridors.
- Direct Sales:Property developers and hospitality procurement teams source through manufacturer-direct channels for bulk condominium and hotel-fit-out specifications.
- Wholesalers:Regional distributors serve independent retailers and commercial laundromat operators across Central America and Caribbean markets with inventory pooling and credit terms.
Offline retail maintains the dominant share, while online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in São Paulo's condominium corridor exceeds that of Mexico City's peripheral districts by a factor reflecting energy-label premiums and installation-service bundling. Brazil's southeastern manufacturing belt commands specification influence over Central American export flows. Argentina's import-substitution pressures compress margins for foreign OEMs serving Buenos Aires.
Brazil
Urban vertical housing in São Paulo state and Rio de Janeiro metropolitan area concentrates demand for stackable front-load configurations with INMETRO A-grade certification. The national energy-efficiency labeling mandate forces motor-system redesigns that favor inverter platforms over legacy induction drives. Whirlpool Corporation leverages its Monterrey manufacturing complex to sustain cost-competitive exports throughout the broader region.
Mexico
PROFECO consumer-protection frameworks enforce truthful energy-labeling claims that filter smaller trading operations from formal retail channels in Mexico City metropolitan area. The PROFECO compliance documentation burden delays product launches by four to six months for new entrants seeking shelf space. Nuevo León's industrial corridor hosts assembly operations serving both domestic demand and Central American re-export.
Argentina
IRAM safety standards alignment with IEC 60335-2-7 reduces certification duplication costs for manufacturers serving both Mercosur and Andean markets from Buenos Aires distribution hubs. Rising electricity tariffs reshape operating-cost calculations for middle-class households considering heat-pump dryer adoption. The import-substitution policy environment compresses foreign OEM margins while creating openings for regional assemblers.
Chile
Pending water-usage restrictions in Santiago and coastal cities redirect R&D investment toward ultra-low-consumption drum designs with spray-pattern optimization. Electricity tariff structures make ventless heat-pump dryers economically viable for apartment dwellers trading speed for installation flexibility. The national regulator tightens compliance thresholds that front-load platforms must satisfy for formal retail placement.
Colombia
Manual washing persists in forty percent of Bogotá and Medellín households, creating conversion markets for basic top-load units with financing plans penetrating price-sensitive segments. Water-scarcity infrastructure mismatches lag appliance replacement cycles in coastal cities. Regional distributors serve independent retailers with inventory pooling and credit terms that accelerate automated-laundry adoption.
Latin America Laundry Appliances Market Competitive Landscape
Concentration sits with multinational appliance OEMs possessing captive manufacturing infrastructure and brand equity in energy-label compliance. The vendor base stratifies across three tiers: global full-line manufacturers with regional assembly plants, mid-tier regional assemblers leveraging modular inverter platforms, and niche specialists in commercial or connected-appliance segments. Dominant competitive moves include capacity consolidation in Brazil and Mexico to capture Mercosur and USMCA trade advantages, plus technology licensing arrangements that transfer inverter-motor calibration capabilities to regional partners.
Among North American-based full-line manufacturers, Whirlpool Corporation anchors the premium-mid tier through its Monterrey manufacturing footprint and specification relationships with São Paulo property developers. AB Electrolux, a Swedish public limited company, occupies a position exemplifying European engineering-focused positioning through specialized front-load lines targeting Brazil's middle-class condominium market. Samsung and LG Electronics, both South Korean electronics conglomerates, represent the scale-driven end with integrated component supply chains and smart-appliance connectivity platforms penetrating upper-middle segments in São Paulo and Buenos Aires.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| AB Electrolux |
| Samsung |
| LG Electronics |
| Panasonic Corporation |
| Miele |
| Haier Electronics Group Co Ltd |
| Bosch |
| Groupe SEB |
| Others |
Supply & Pricing Matrix
Modular inverter-motor platforms replacing belt-drive induction systems simultaneously relocate component sourcing toward East Asian electronics corridors and compress the premium-to-standard pricing spread across Brazil and Mexico. This substitution dynamic collapses legacy cost barriers that previously protected regional assemblers from global OEM competition.
Pricing Analysis
The customization-premium spread narrows as INMETRO A-grade certification becomes table stakes rather than differentiator. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor efficiency tier and connected-feature bundling. Cost compression in the economy tier intensifies because Brazilian distributors demand volume rebates that erode assembler margins. Commercial laundromat operators exhibit lowest price sensitivity due to usage-based revenue models, while Colombian manual-washing conversion households resist financing premiums above bare-baseline top-load units.
Supply Chain Analysis
China and South Korea anchor variable-frequency drive module production, while Brazil and Mexico host final assembly for regional consumption. Drum housings draw from domestic steel rolling mills, but copper windings and electronic control boards rest on East Asian supplier concentration. Single-source vulnerability in inverter component sourcing exposes Brazilian production schedules to shipping disruptions through Panama Canal chokepoints. Distribution runs through Nuevo León manufacturing complexes serving Central American re-export corridors and São Paulo distribution hubs penetrating Mercosur markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against manual-washing persistence and shared-laundry service models that unbundle appliance ownership from household budgets.
For Market Incumbents: Secure captive inverter-motor supply agreements with Tier-2 suppliers to neutralize East Asian component bottlenecks. Consolidate specification relationships with São Paulo condominium developers before mid-tier assemblers achieve INMETRO certification parity. The shared-laundry service threat intensifies as property managers unbundle capital expenditure from tenant operating costs.
For New Entrants and Emerging Players: IRAM certification fast-track through Buenos Aires testing laboratories opens Mercosur access without Brazilian INMETRO duplication costs. Colombia's manual-washing conversion base offers the most penetrable geography, with financing-integrated distribution through Medellín independent retailers providing viable go-to-market angle. Target Bogotá rental housing clusters where appliance-as-service models remain underdeveloped.
For Investors and Strategic Acquirers: The market sits at a technology-diffusion phase that favors mid-tier assemblers with modular platform access over legacy induction-motor incumbents. Long-term viability centers on connected-appliance capability and utility demand-response integration. Acquisition target archetype: Brazilian or Mexican regional assemblers possessing INMETRO certification infrastructure and condominium specification relationships. Monitor heat-pump dryer adoption rates in Buenos Aires and Santiago as inflection indicator for premium-tier expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Inverter-Motor Platform Licensing | Transfers calibration capabilities to regional partners lacking R&D depth. |
| Condominium Specification Lock-In | São Paulo developers specify stackable front-load configurations in bulk procurement. |
| Heat-Pump Dryer Portfolio Expansion | Argentina's electricity tariffs make ventless designs economically viable for apartments. |
| Utility Demand-Response Partnership | Brazilian grid operators seek smart-appliance load-shifting partners for peak pricing. |
| Financing-Integrated Distribution | Credit terms accelerate conversion of Colombia's manual-washing households. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with appliance manufacturing executives, INMETRO certification engineers, São Paulo property development procurement directors, and Colombian independent retail distributors; alongside secondary validation through customs trade records, SEC filings of listed OEMs, INMETRO efficiency registry databases, and PROFECO consumer complaint archives. Bottom-up and top-down triangulation reconciled unit shipment estimates with reported revenue segmentation.
Across the analysis window, the forecasting framework modeled demand by product type, technology tier, end-user segment, and distribution channel, with geographic clustering around regulatory harmonization zones. CAGRs derived from regression analysis against urban household formation rates, electricity tariff trajectories, and water-scarcity infrastructure investment pipelines. Key inputs included INMETRO labeling adoption curves and heat-pump dryer payback period calculations for middle-class households.
Decision-makers should treat outputs as directional under assumptions of continued INMETRO enforcement and stable East Asian component supply; material deviation in trade policy or commodity volatility would warrant model refresh. Forecasts reflect these base conditions without contingency for regulatory suspension or shipping route disruption. Recalibration cycles align with material shifts in Brazilian energy-labeling thresholds and Argentine import-substitution policy intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Japan Home Appliances Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Range Hood Market
Home Appliances
Household Refrigerator Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Italy Home Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Brazil Home Appliances Market
Home Appliances
Brazil Laundry Appliances Market