
 Mobile Refrigerators Market | 2026-2036
Mobile Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Refrigerators Market Insights
Aftermarket service revenue is reshaping margin capture across the mobile refrigeration value chain. Samsung Electronics leverages its semiconductor supply chain to control inverter compressor module costs. Haier Group anchors production scale across multiple climate zones through distributed manufacturing footprints. Electrolux AB differentiates via energy-label optimization for European caravan and marine applications.
A mobile refrigerator is a self-contained, thermally insulated cooling unit engineered to maintain sub-ambient temperatures during transit, typically employing vapor-compression, absorption, or thermoelectric cycles with power draws ranging from 45W to 150W depending on capacity and insulation grade. These units serve commercial and consumer applications where grid-independent cold storage preserves perishables, vaccines, or temperature-sensitive cargo away from fixed infrastructure. Compressor-based systems command the dominant share of value owing to superior coefficient of performance and freezing capability, while thermoelectric variants capture niche volume in low-capacity camping and personal vehicle segments. Solar-hybrid power configurations represent the fastest-expanding configuration as panel efficiency gains and lithium phosphate battery cost curves enable off-grid multi-day autonomy.
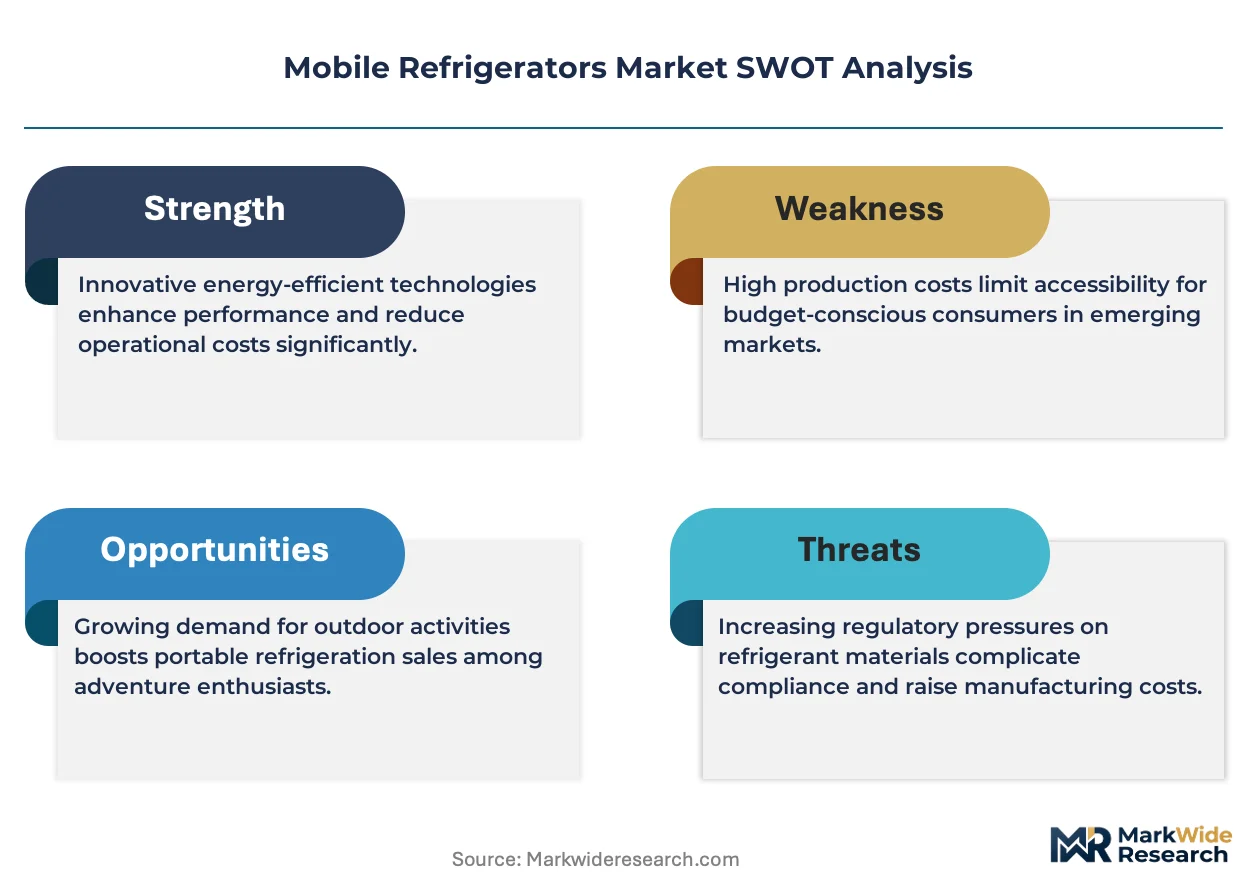
The EPA SNAP program and EU F-Gas Regulation constrain refrigerant selection, compelling OEMs to validate flammable hydrocarbon charge limits and redesign safety shut-off architectures. CE marking and UL 250 testing protocols govern electrical and thermal safety access for North American and European market entry. Stakeholders must monitor refrigerant phase-down schedules and energy-label recalibration timelines to align R&D pipelines with compliance deadlines.
Market Dynamics
The mobile refrigeration sector is restructuring around hydrocarbon refrigerant transitions as the EPA SNAP program and EU F-Gas Regulation force OEMs to abandon high-GWP chemistries, compressing R&D timelines and supplier qualification windows.
Growth Catalysts
- Last-mile pharmaceutical cold chain:Vaccine distribution networks now require portable units maintaining 2-8°C through variable ambient conditions, pulling compressor-based systems into medical logistics fleets.
- EU F-Gas Regulation phase-down:The 2024-2030 refrigerant quota system accelerates validation of propane and isobutane architectures, creating first-mover advantages for compliant OEMs.
- Outdoor recreation equipment pull:RV ownership in the United States and caravan registrations across Germany sustain replacement cycles for 12V and 24V DC-powered units.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and compressor housing materials face commodity price swings that compress gross margins on mid-range product lines.
- Compressor supplier concentration:Variable-speed inverter module production clusters in East Asian manufacturing hubs, exposing OEMs to single-source risk during logistics disruptions.
- Thermoelectric performance ceiling:Peltier systems cannot achieve sub-freezing temperatures, limiting their addressable market to beverage cooling and excluding frozen cargo applications.
Strategic Opportunities
- Solar-hybrid autonomy:Lithium iron phosphate battery cost curves and 22%+ efficient photovoltaic panels enable multi-day off-grid operation for remote medical camps and expedition vehicles.
- India cold-chain infrastructure gaps:The country's PLI scheme for food processing and dairy creates demand for grid-independent refrigeration in last-mile agricultural distribution.
- Marine and caravan energy-label optimization:Electrification of European leisure craft drives specification of A+++ rated units that reduce generator runtime and fuel consumption.
Industry Challenges
- Hydrocarbon safety system integration:Propane charge limits require redesigned shut-off valves, pressure relief architectures, and ignition source isolation that extend certification timelines by 8-14 months.
- Cross-regional testing protocol fragmentation:UL 250, CE marking, and CB scheme requirements differ on electrical safety and thermal runaway thresholds, forcing redundant validation for multi-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Refrigerators Market |
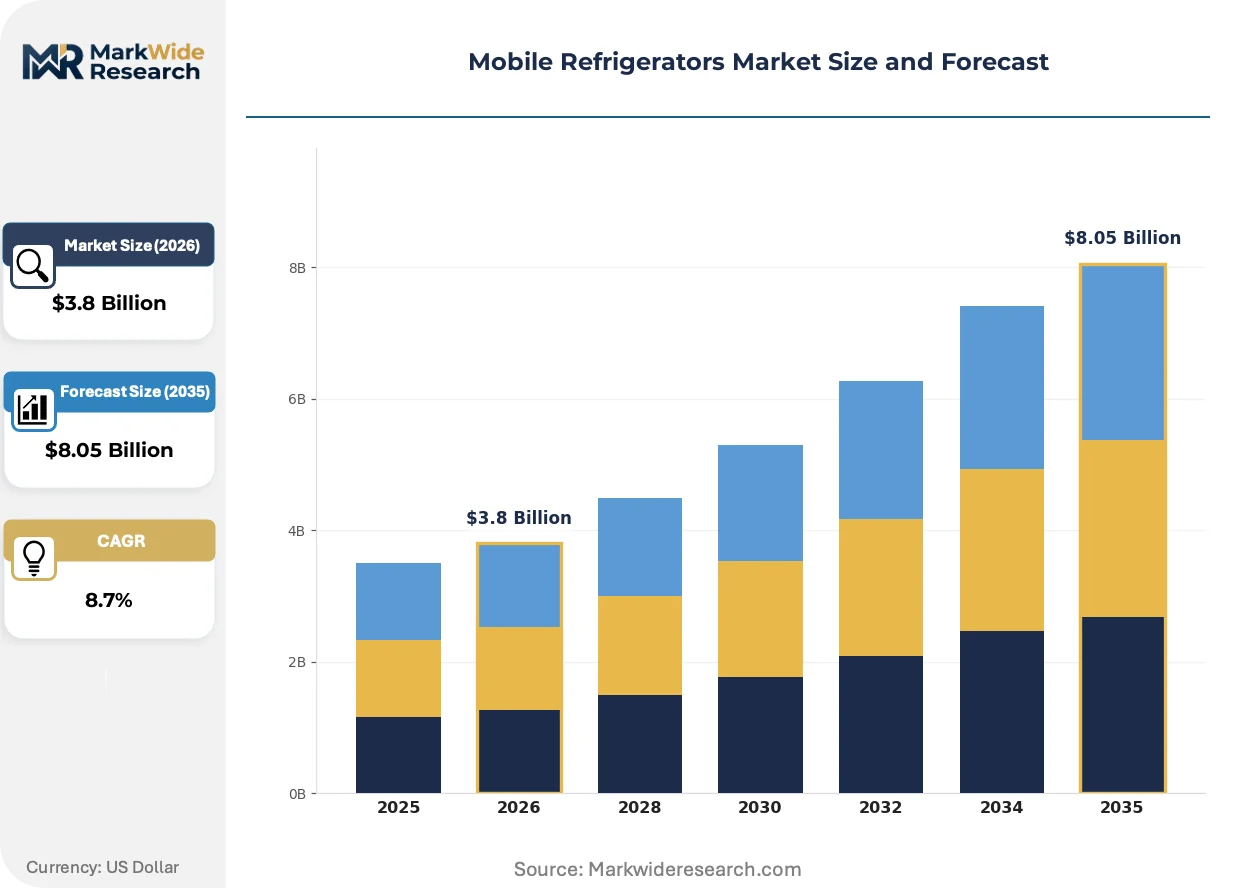
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorption, Compressor, Thermoelectric, Freezer Application: Camping, Food Delivery, Medical Transport, RV Use End User: Hospitality, Outdoor Enthusiasts, Logistics Companies, Emergency Services Power Source: Battery, AC/DC, Solar, Generator |
| Companies Covered | Samsung Electronics, LG Electronics, Whirlpool Corporation, Haier Group, Electrolux AB, Panasonic Corporation, GE Appliances, Midea Group, Hitachi Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Refrigerators Market Trends and Innovations
Refrigerant chemistry transitions and power system hybridization are compressing traditional product lifecycles while opening new application verticals previously unserved by mobile cooling equipment.
Variable-speed inverter compressors are collapsing energy consumption benchmarks for mid-capacity units. Cold-chain logistics operators in Germany and the Netherlands are specifying these modules for pharmaceutical fleet retrofits. The technology is collapsing the operating cost gap between mobile and fixed refrigeration infrastructure.
The EPA SNAP program's 2024 restrictions on R-404A and R-134a are forcing refrigerant architecture redesigns across North American production lines. OEMs must validate flammable hydrocarbon charge limits below 150g or pivot to CO2 transcritical systems with higher pressure vessel costs. Marine and RV segments face the steepest compliance curves due to confined-space installation requirements.
Subscription-based fleet refrigeration services are displacing unit ownership models among last-mile delivery contractors. Temperature monitoring and predictive maintenance bundles now accompany hardware leases in urban pharmaceutical distribution networks. The United Kingdom and Netherlands show the highest penetration of this service-contract structure, driven by NHS and EMA GDP compliance documentation requirements.
Mobile Refrigerators Market Segmentation
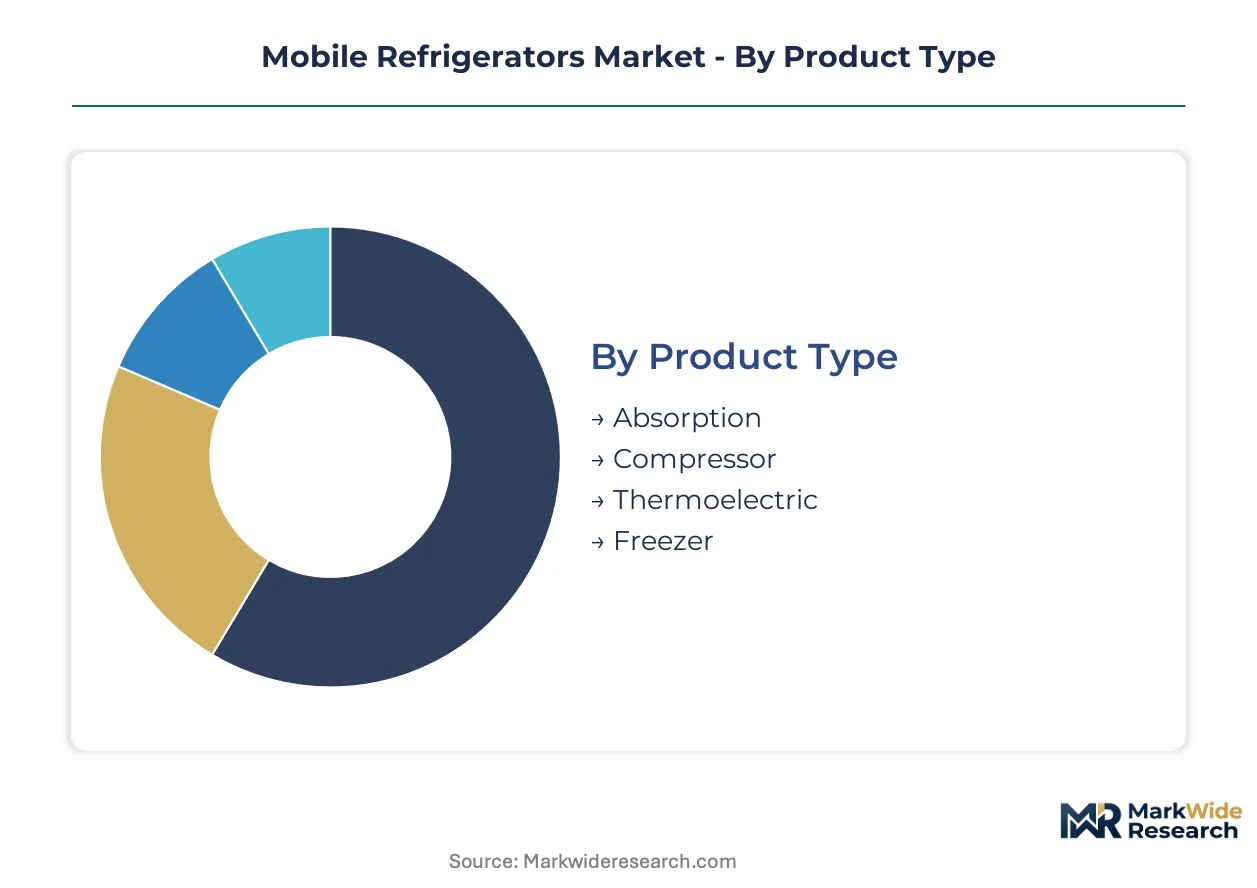
Mobile refrigerators serve divergent thermal loads across recreational, medical, and commercial logistics contexts. Product architecture and power configuration choices directly determine addressable use cases and margin profiles. Segmentation reveals where hydrocarbon refrigerant transitions and solar-hybrid autonomy reshape competitive positioning.
Product Type:
Cooling cycle selection governs coefficient of performance, freezing capability, and off-grid viability across the use-case spectrum.
- Compressor:Vapor-compression systems deploy variable-speed inverter modules achieving superior energy efficiency and sub-freezing temperatures. Demand concentrates in pharmaceutical last-mile fleets across Germany and the Netherlands where GDP compliance mandates precise temperature control. The EPA SNAP program accelerates propane and isobutane architecture validation for this dominant product class.
- Thermoelectric:Peltier-effect units operate silently with no moving parts but face hard thermodynamic limits near 20°C below ambient. Adoption clusters in personal vehicle beverage cooling and low-capacity camping segments where freezing capability is dispensable and cost minimization dominates.
- Absorption:Ammonia-hydrogen absorption cycles run on propane burner or electric heat, eliminating compressor noise for RV bedroom installations.
- Freezer:Dedicated sub-zero units address frozen cargo transport for specialty food logistics and expedition medical supply.
Established volume favors Compressor; emerging adoption favors Thermoelectric.
Application:
Deployment context determines insulation grade, power draw tolerance, and regulatory scrutiny intensity.
- Medical Transport:Cold-chain logistics for vaccines and biologics demands 2-8°C stability through variable ambient conditions. NHS and EMA GDP documentation requirements in the United Kingdom and Netherlands pull compressor-based units into fleet retrofits with integrated temperature logging.
- RV Use:Recreational vehicle installations prioritize 12V/24V DC efficiency and low noise signatures for overnight operation. United States RV ownership rates sustain replacement cycles across absorption and compressor product lines.
- Food Delivery:Last-mile restaurant and grocery logistics specify compact footprint units for scooter and compact van mounting.
- Camping:Portable units for tent and car-camping applications balance weight against cooling duration on battery power.
Medical Transport commands premium pricing; Food Delivery shows steepest volume expansion trajectory.
End User:
Procurement authority and total cost of ownership calculation methods vary sharply across customer categories.
- Logistics Companies:Fleet operators amortize capital cost against fuel savings and maintenance reduction. Subscription-based service contracts with predictive maintenance bundles displace unit ownership among pharmaceutical distribution contractors in urban European markets.
- Outdoor Enthusiasts:Individual consumers prioritize purchase price and brand reputation over lifecycle cost analysis. Solar-hybrid configurations gain traction in this segment as lithium iron phosphate battery costs decline.
- Emergency Services:Disaster response and field hospital deployments require ruggedized units with multi-source power flexibility.
- Hospitality:Catering and event operators specify mobile refrigeration for temporary outdoor service expansion.
Logistics Companies dominate commercial volume; Outdoor Enthusiasts drive solar-hybrid specification.
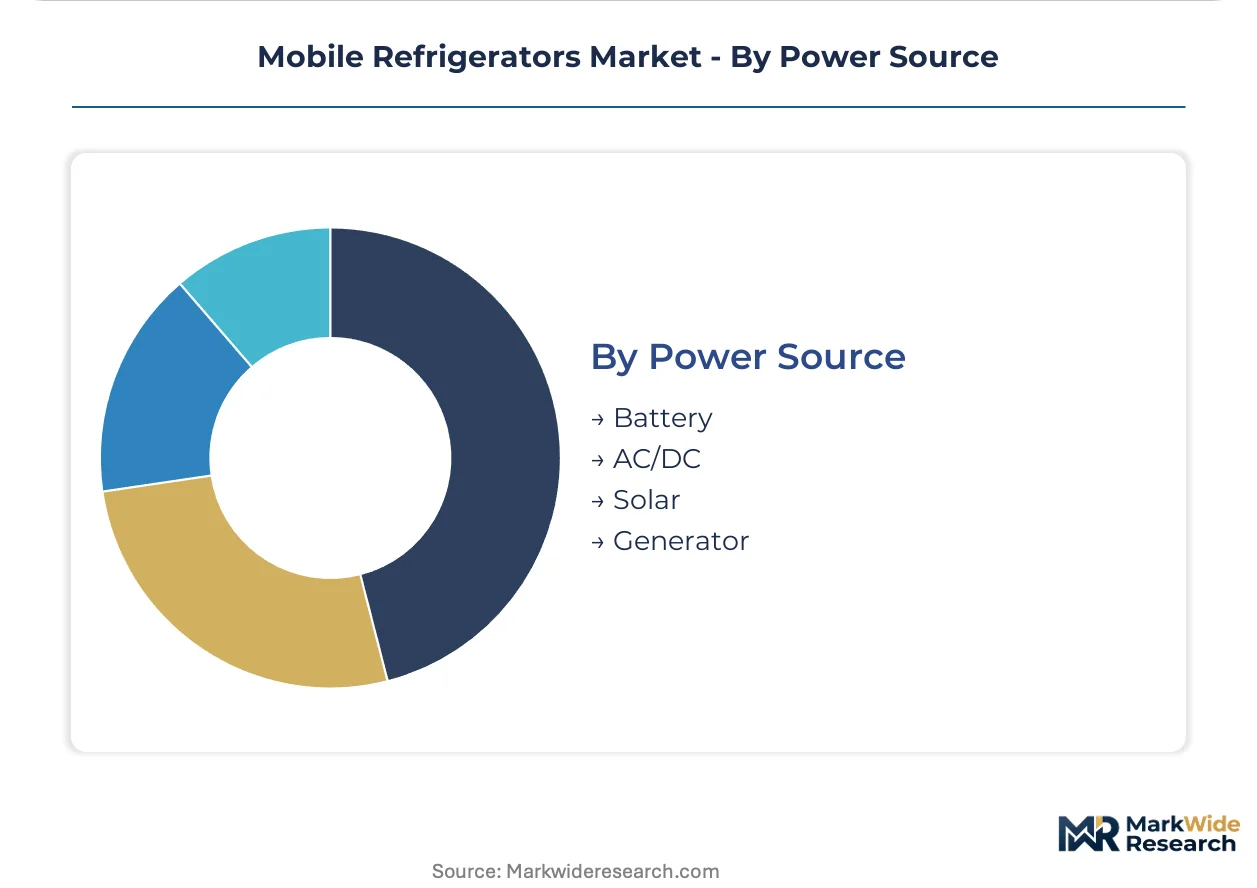
Power Source:
Electrical architecture determines operational autonomy and grid dependency elimination potential.
- Solar:Photovoltaic integration with lithium iron phosphate storage enables multi-day off-grid operation. Panel efficiency gains above 22% and battery cost curves expand addressable markets to remote medical camps and expedition vehicles previously unserved.
- Battery:Standalone lithium or lead-acid systems serve short-duration applications where solar exposure is unreliable. Energy density limitations constrain deployment to sub-48-hour autonomy requirements.
- AC/DC:Dual-voltage capability allows grid connection at base and vehicle battery operation during transit.
- Generator:Fossil-fuel generators provide backup power for high-capacity units in grid-absent environments.
Battery dominates installed base; Solar gains share fastest in premium outdoor and medical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States channels mobile refrigeration into RV recreation and outdoor leisure, while Germany and the Netherlands deploy identical hardware for pharmaceutical cold-chain compliance. India and China pursue agricultural last-mile applications with distinct power and cost constraints.
United States
RV ownership exceeds eleven million units nationwide, sustaining replacement demand for 12V DC compressor and absorption systems. The EPA SNAP program's 2024 refrigerant restrictions force domestic OEMs to validate propane architectures ahead of European counterparts. Manufacturing concentrates in Indiana's Elkhart County, where RV supplier parks enable rapid prototype-to-production cycles for camping and overlanding segments.
Germany
Caravan registrations and marine leisure craft electrification pull A+++ energy-rated units into specification. The EU F-Gas Regulation's 2024-2030 quota system accelerates hydrocarbon refrigerant transitions for OEMs serving Dutch and Belgian export markets. Production clusters in Baden-Württemberg leverage automotive supplier networks for inverter compressor module integration.
Netherlands
Pharmaceutical distribution density creates concentrated demand for GDP-compliant mobile units with integrated temperature logging. EMA documentation requirements for vaccine transport mandate precise 2-8°C stability validation. Cold-chain logistics operators in Rotterdam and Utrecht specify subscription-based fleet services with predictive maintenance bundles.
India
Dairy and fresh produce distribution gaps drive demand for grid-independent solar-hybrid configurations. The PLI scheme for food processing incentivizes domestic assembly of lithium phosphate battery systems. Manufacturing activity concentrates in Gujarat and Maharashtra, where component supplier ecosystems serve agricultural cooperative procurement channels.
China
Export manufacturing dominance pairs with emerging domestic demand for camping and vehicle-based recreation. MEE oversight of refrigerant phase-downs aligns production lines with EU and North American import requirements. Industrial capacity clusters in Guangdong and Zhejiang, where compressor module suppliers serve global OEM assembly networks.
Mobile Refrigerators Market Competitive Landscape
Capability concentration sits with inverter compressor and semiconductor-integrated specialists; scale advantage sits with diversified appliance conglomerates. The vendor base separates into three tiers: premium technology integrators, mid-range volume manufacturers, and regional assembly specialists. Competitive moves center on refrigerant architecture validation for hydrocarbon compliance and solar-hybrid power system integration for off-grid segments.
Within the diversified conglomerate tier, Samsung Electronics, Haier Group, and Electrolux AB exemplify distinct geographic anchoring strategies. Samsung Electronics represents East Asian semiconductor supply chain leverage for compressor module cost control. Haier Group occupies a position spanning multiple climate zones through distributed manufacturing footprints. Electrolux AB exemplifies European energy-label optimization for caravan and marine applications where A+++ ratings reduce generator runtime.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Whirlpool Corporation |
| Haier Group |
| Electrolux AB |
| Panasonic Corporation |
| GE Appliances |
| Midea Group |
| Hitachi Ltd |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum commodity volatility compresses gross margins across mid-range compressor product lines, forcing tier spreads that separate premium inverter-based units from standard thermoelectric alternatives while reshaping supplier qualification windows for hydrocarbon refrigerant architectures.
Pricing Analysis
Long-term offtake contracts dominate procurement between cold-chain logistics operators and OEMs, with subscription-based fleet services displacing unit ownership among pharmaceutical distribution contractors. Price differentiation hinges on energy-label certification tier and integrated temperature logging capability. Cost compression in standard-grade thermoelectric units intensifies as Chinese manufacturing scale floods camping and personal vehicle segments. Outdoor enthusiasts exhibit highest price sensitivity, while medical transport operators prioritize GDP compliance over capital cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates risk planning for inverter compressor module procurement. Manufacturing concentrates in Guangdong, Zhejiang, and Baden-Württemberg, with heat exchanger copper tubing and lithium iron phosphate battery cells anchoring cost structures. Single-source vulnerability clusters around East Asian variable-speed inverter production. Distribution runs through RV supplier parks in Indiana's Elkhart County and automotive-tier supplier networks serving European caravan OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inverter compressor module integration and hydrocarbon refrigerant safety system engineering constitute scarce capabilities that constrain competitive entry, with hydrocarbon charge limit validation expertise determining market access timelines.
For Market Incumbents: Entrench position through captive supply of semiconductor-integrated compressor modules and accelerated propane architecture certification ahead of EPA SNAP program deadlines. Secure long-term offtake agreements with pharmaceutical logistics operators to lock in replacement cycle demand. Defend against emerging solar-hybrid specialists by acquiring lithium phosphate battery integration capabilities. For New Entrants and Emerging Players: India's agricultural cooperative procurement channels offer underpenetrated entry points for grid-independent solar-hybrid configurations. Target dairy distribution gaps in Gujarat and Maharashtra with localized assembly partnerships. Bypass established OEM service networks by deploying predictive maintenance platforms bundled with hardware leases. For Investors and Strategic Acquirers: Inverter compressor specialists with validated hydrocarbon architectures represent the priority acquisition archetype for portfolio exposure to refrigerant transition tailwinds. Monitor EMA GDP documentation requirement enforcement intensity as inflection indicator for pharmaceutical fleet retrofit velocity. Long-term viability favors OEMs with multi-regional certification pipelines spanning UL 250, CE marking, and BIS compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Refrigerant Validation | EPA SNAP program compliance timelines determine North American market access for propane and isobutane architectures. |
| Solar-Hybrid Power Integration | Lithium iron phosphate battery cost curves enable multi-day off-grid autonomy for remote medical camps. |
| Subscription Fleet Services | NHS and EMA GDP documentation requirements pull temperature-monitoring bundles into pharmaceutical logistics contracts. |
| Inverter Compressor Module Sourcing | East Asian semiconductor supply chain leverage controls cost positioning for energy-efficient premium tiers. |
| Multi-Regional Certification Pipeline | CE marking, UL 250, and CB scheme redundancy accelerates launch velocity across European and North American markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cold-chain logistics procurement directors, RV OEM platform engineers, pharmaceutical fleet operators, and aftermarket service heads; and secondary validation against EPA SNAP program filings, EU F-Gas Regulation quota announcements, SEC 10-K disclosures from diversified appliance conglomerates, and customs records tracking compressor module trade flows. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Forecast inputs span cooling cycle type, application vertical, power source configuration, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level volume trajectory modeling incorporating refrigerant phase-down schedules and energy-label recalibration timelines. Industry-specific inputs include RV ownership replacement cycle patterns and pharmaceutical GDP compliance documentation adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese solar-hybrid specialists or accelerated hydrocarbon validation by European automotive-tier suppliers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Body Dryer Market
Appliances
Mini Refrigerator Market
Appliances
Microwave Oven Market
Appliances
Saudi Arabia Dishwasher Market
Appliances
Bathroom Heaters Market
Appliances
Water Dispenser Market
Appliances
AI Washing Machine Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Small Electric Kettles Market
Appliances
China Induction Hobs Market
Appliances
Refrigerator Repair Service Market
Appliances
Electric Hand Dryer Market
Appliances
Qatar Dishwashers Market
Appliances
US Portable Washing Machines Market
Appliances
Japan Massage Equipment Market
Appliances
Bahrain Microwave Ovens Market