
 China Home Appliances Market | 2026-2036
China Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
China Home Appliances Market Analysis
Smart appliance bundling is recalibrating buyer choice across China's home appliances sector, as developers and retailers package climate, refrigeration, and laundry systems into unified smart-home configurations. Haier Smart Home leverages its open-ended IoT ecosystem to anchor premium contracts with property developers in Shenzhen and Hangzhou. Midea Group sustains manufacturing scale through captive compressor production and dominates air conditioner exports from its Guangdong base. Hisense Group Co., Ltd. differentiates via laser-display integration into living-room appliance suites, competing for share in high-end residential projects.
China home appliances encompass electrically powered domestic equipment designed for cooking, food preservation, cleaning, and climate control, typically operating at 220V/50Hz with energy-efficiency grades mandated under GB standards. These products serve households, commercial developers, and retail channels by automating domestic labor and enabling connected property management. Smart appliances lead value creation through AI-driven energy optimization and remote diagnostics, while traditional appliances occupy volume positions in rural prefectures where price sensitivity persists. IoT-integrated appliances represent the fastest-expanding segment as property developers embed pre-installed connected infrastructure into new residential towers across Chengdu and Wuhan.
SAMR enforces product safety and energy-label accuracy under GB standards, while MIIT coordinates smart-home interoperability protocols that shape which connectivity platforms gain market access. China's dual carbon goals impose escalating efficiency thresholds on manufacturers, effectively filtering out non-compliant imports and subscale domestic producers. Stakeholders must monitor how NMPA-aligned material safety reviews and evolving GB efficiency tiers will reshape component sourcing and factory certification requirements.
Market Dynamics
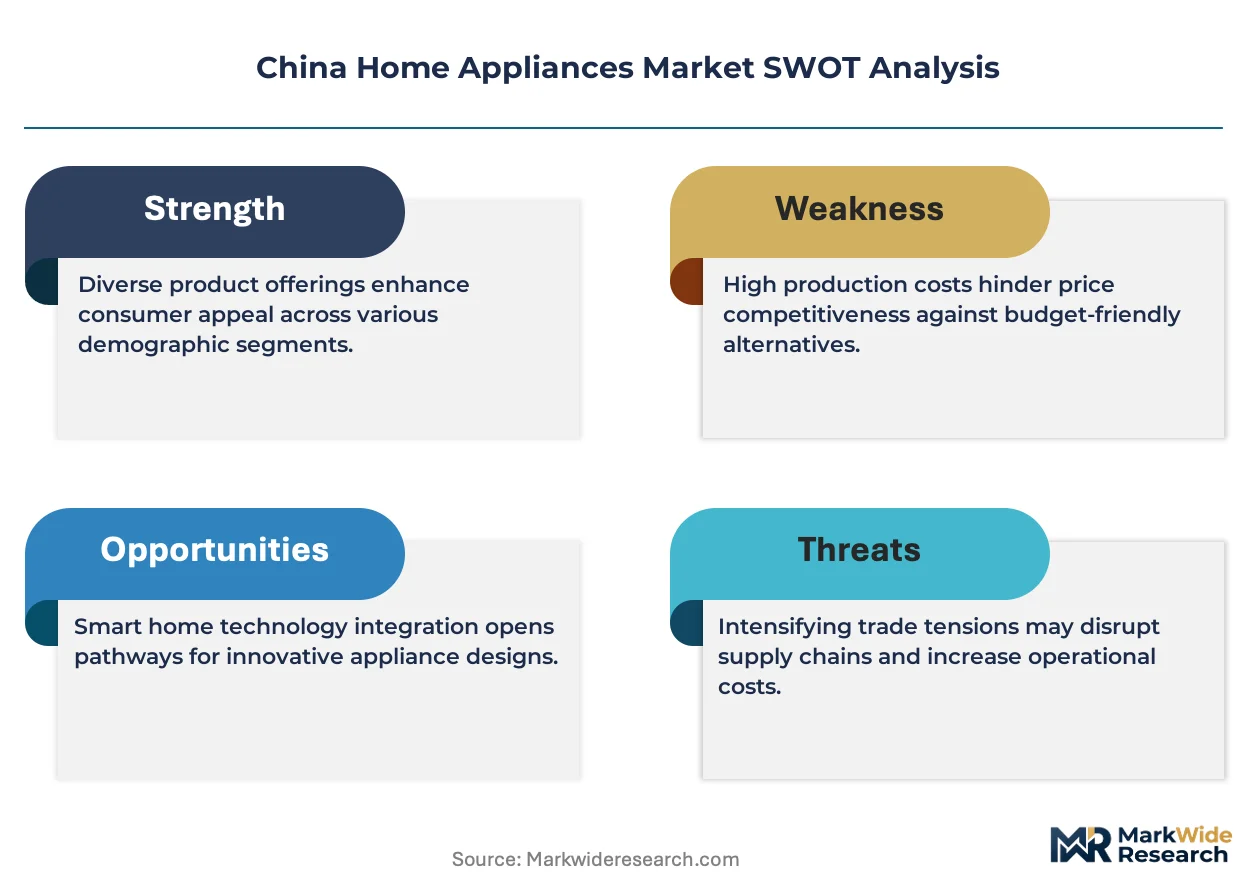
MIIT's escalating GB energy-efficiency tiers are compressing margins for conventional compressor architectures while forcing wholesale retooling of production lines across Guangdong and Shandong manufacturing clusters.
Growth Catalysts
- Dual carbon mandates:Beijing's 2030 emissions targets are accelerating factory conversion to heat-pump platforms and inverter-driven climate systems.
- Property developer bundling:Shenzhen and Hangzhou residential towers now specify pre-installed IoT infrastructure as standard, pulling through connected appliance suites.
- Rural electrification:Grid extension into western prefectures is opening first-time appliance ownership for refrigeration and laundry equipment.
Market Restraints
- Copper and rare-earth volatility:Compressor motor laminations and permanent-magnet materials face input cost swings that erode contract pricing stability.
- Import component concentration:Power semiconductor modules for inverter drives remain concentrated in Taiwanese and South Korean foundry supply.
- Technical limitation:Heat-pump performance degradation below minus 15°C restricts deployment in northern Heilongjiang and Inner Mongolia residential heating.
Strategic Opportunities
- Central and western provinces:Chengdu and Xi'an new-build residential volumes exceed connected-appliance penetration rates seen in coastal cities five years prior.
- Agricultural cold-chain extension:County-level food preservation networks are creating demand for commercial-scale refrigeration beyond household units.
- Smart-home interoperability:MIIT's unified connectivity protocols are enabling cross-brand appliance orchestration that reduces developer procurement friction.
Industry Challenges
- Firmware and systems integration talent:Shortage of embedded-software engineers with appliance-specific safety certification is delaying connected-product launches.
- GB standard recertification timelines:Six-to-nine month approval windows for revised efficiency grades are freezing product line transitions during peak construction seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Home Appliances Market |
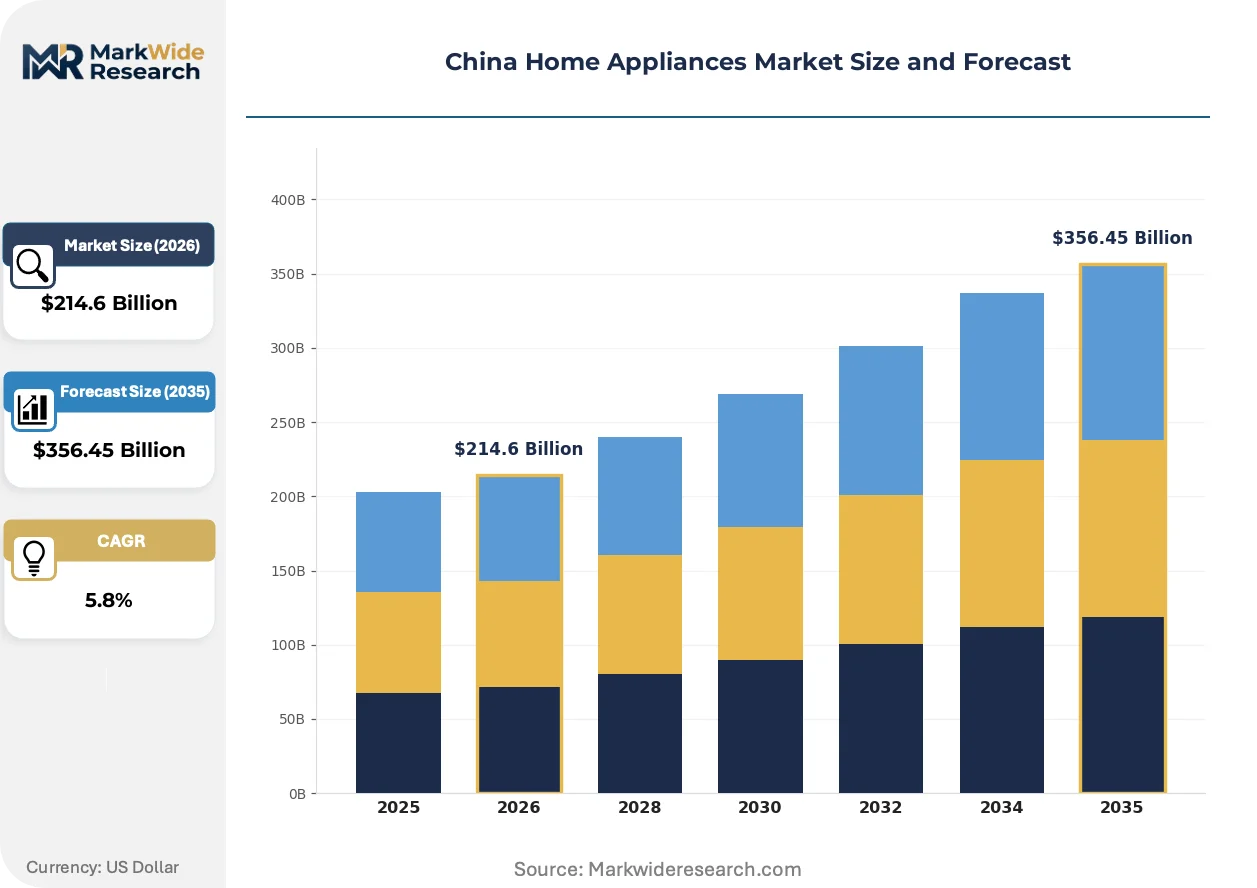
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $356.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Air Conditioners, Ovens Customer Type: Households, Property Developers, Retail Outlets, E-commerce Platforms Technology: Smart Appliances, Energy-efficient Appliances, Traditional Appliances, IoT-integrated Appliances Distribution Channel: Online Sales, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Hisense Group Co., Ltd., Haier Smart Home, Haier Group Corporation, Panasonic Corporation, BSH Home Appliances, Midea Group, TCL Corporation, Samsung, Gree Electric Appliances, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Home Appliances Market Emerging Trajectories
Electrification of domestic thermal systems is converging with connected-property infrastructure to redefine how climate and water-heating equipment is specified, sold, and serviced across Chinese residential development.
Heat-pump water heaters and space-conditioning units are electrifying residential thermal loads previously served by gas combustion. Tier-one property developers in Shanghai and Beijing are specifying all-electric mechanical systems in new luxury towers to meet prescriptive carbon-intensity targets. This shift is electrifying traditional boiler and furnace supply chains while expanding addressable market for high-COP compressor platforms.
MIIT's smart-home interoperability mandates are standardizing connectivity protocols across previously siloed appliance categories. Manufacturers must now certify to unified data-exchange frameworks to access developer procurement channels. Air-conditioning and refrigeration OEMs are most affected, reconfiguring control boards and cloud architectures to satisfy pre-installation requirements in Wuhan and Nanjing residential projects.
Builder-direct procurement is consolidating buyer power and compressing traditional retail channel margins. Property developers in Shenzhen and Hangzhou now negotiate three-year appliance supply agreements covering entire tower portfolios, displacing individual household purchasing decisions. This concentration is most visible in premium residential verticals where smart-system bundling determines project marketability.
China Home Appliances Market Segmentation
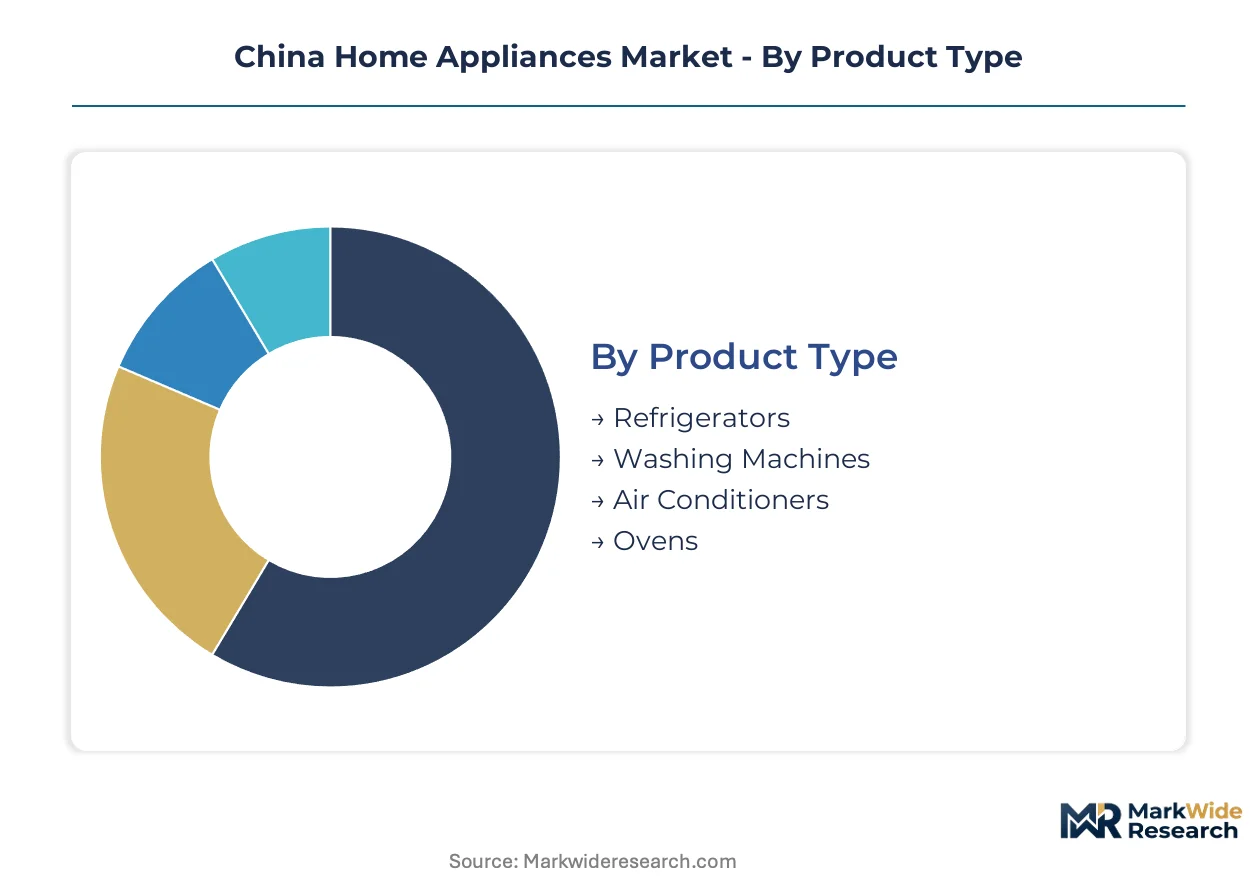
Segmentation in China's home appliances sector reveals how MIIT efficiency mandates and property developer procurement are reshaping demand composition. Buyers sort sharply between connected infrastructure for new residential towers and replacement cycles in existing housing stock.
Product Type:
Product differentiation tracks cooling load requirements and installation constraints across China's climatic zones.
- Air Conditioners:Inverter-driven units with variable-speed compressors dominate specifications for southern provinces where cooling degree-days exceed 3,000 annually. Guangdong and Fujian developers now mandate heat-pump capable systems to satisfy dual carbon compliance in new construction.
- Refrigerators:Multi-door frost-free platforms with linear inverter compressors anchor premium kitchen fit-outs in Shanghai and Beijing high-rises. Rural prefectures sustain demand for direct-cool top-mount units where grid stability and purchase budgets constrain specification.
- Washing Machines:Front-load drum platforms with direct-drive motors capture share in tier-one cities where water efficiency ratings influence purchase decisions.
- Ovens:Built-in electric convection units concentrate in coastal urban markets with established Western cooking habits.
Volume sits with air conditioners; growth tilts toward refrigerators as cold-chain extension penetrates county-level markets.
Customer Type:
Procurement authority is concentrating with entities controlling installation timing and connectivity infrastructure.
- Property Developers:Shenzhen and Hangzhou tower projects now specify three-year appliance supply agreements covering entire portfolios, consolidating buyer power and displacing individual household decision-making. Pre-installed IoT infrastructure requirements pull through connected climate and refrigeration suites as standard.
- E-commerce Platforms:JD.com and Tmall channel inventory to replacement demand in tier-two and tier-three cities where physical retail presence thins. Flash sales and bundling algorithms compress margin structures for standard-efficiency inventory.
- Households:Individual purchasers retain influence in rural western prefectures where first-time ownership drives refrigeration and laundry equipment sales.
- Retail Outlets:Suning and Gome storefronts concentrate on high-consideration purchases requiring tactile evaluation and installation coordination.
Developer contracts capture premium positioning; e-commerce platforms are expanding most quickly into underpenetrated prefectures.
Technology:
Technology tiers map directly to GB efficiency grade certification and MIIT interoperability mandates.
- IoT-integrated Appliances:Control boards with unified data-exchange frameworks enable cross-brand orchestration required for Wuhan and Nanjing residential tower certifications. Cloud architectures supporting remote diagnostics and AI-driven energy optimization command developer procurement preference.
- Smart Appliances:WiFi-enabled platforms with proprietary app ecosystems differentiate Haier and M offerings in premium retail channels, though fragmentation in connectivity protocols creates procurement friction.
- Energy-efficient Appliances:GB Grade 1 and 2 certified units qualify for subsidy programs in Beijing and Shanghai municipal incentive schemes.
- Traditional Appliances:Non-connected, fixed-speed platforms occupy volume positions in price-sensitive rural markets where electrification grids are newly extended.
Traditional platforms retain volume leadership in western provinces; IoT-integrated systems claim the steepest expansion trajectory as connected residential construction accelerates.
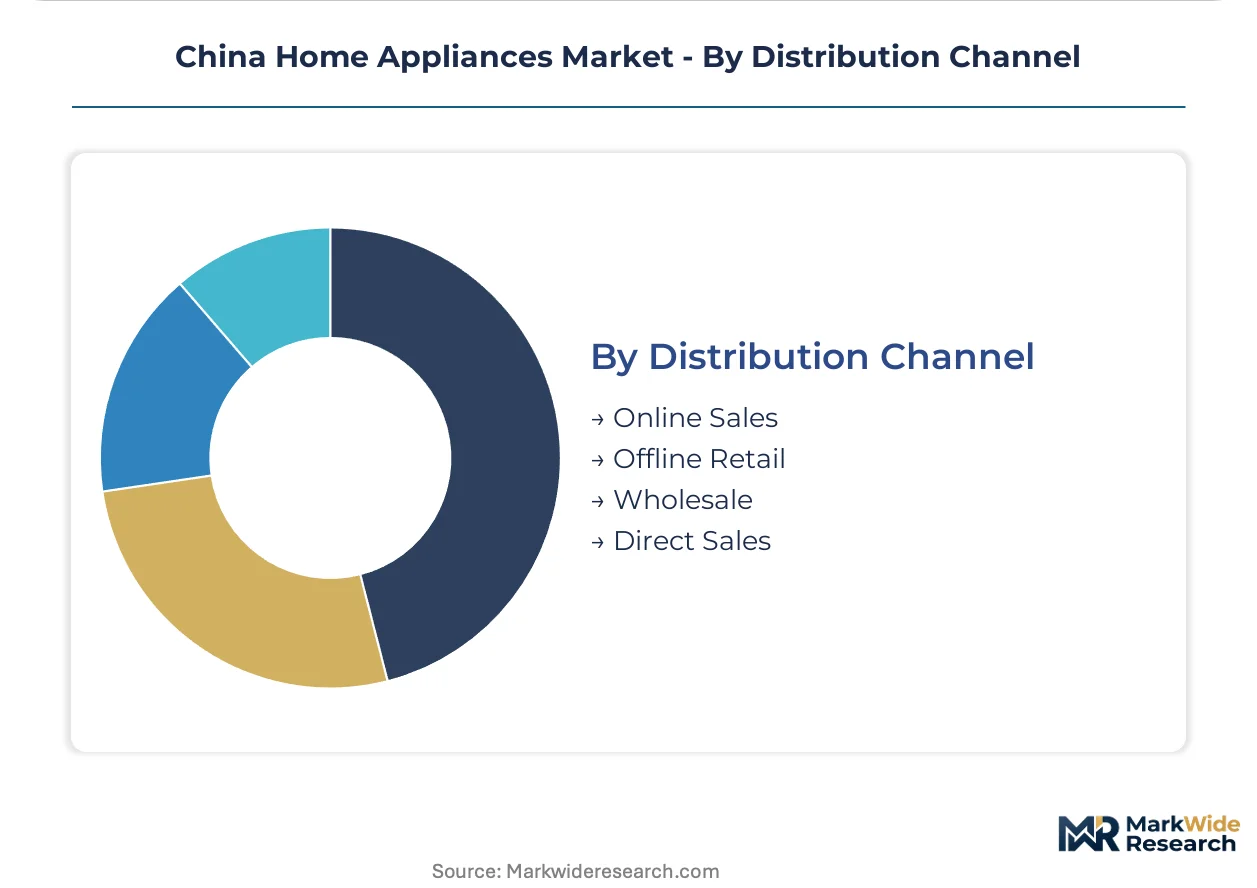
Distribution Channel:
Channel selection follows buyer type concentration and installation service requirements.
- Direct Sales:Manufacturer-to-developer relationships in Shenzhen and Chengdu bypass retail markups and enable customized firmware configurations for tower-specific building management systems.
- Online Sales:Platform logistics networks deliver to county-level addresses where physical retail infrastructure remains sparse, particularly for replacement refrigeration and laundry equipment.
- Offline Retail:Flagship stores in Shanghai and Beijing commercial districts support high-consideration purchases with same-day installation and extended warranty programs.
- Wholesale:County-level distributors aggregate demand for commercial-scale refrigeration serving agricultural cold-chain extension beyond household units.
Wholesale channels anchor rural volume; direct sales are gaining share fastest as developer procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's home appliances production clusters concentrate in coastal provinces while consumption spreads inland through government electrification programs and property development waves. Guangdong and Shandong factories supply inverter compressors and connected climate systems to developers across western expansion zones.
Guangdong Province
Shenzhen and Guangzhou property developers specify pre-installed IoT infrastructure as standard in new residential towers, pulling through connected air-conditioning suites. MIIT smart-home interoperability mandates require unified data-exchange certification for market access. The Pearl River Delta manufacturing belt sustains captive compressor production and dominates export volumes to Southeast Asian markets.
Shandong Province
Qingdao anchors refrigerator and washing machine manufacturing for both domestic distribution and overseas shipment. GB energy-efficiency grade recertification timelines of six-to-nine months freeze product transitions during peak construction seasons. The province's industrial cluster supplies frost-free multi-door platforms to Beijing and Shanghai premium residential fit-outs.
Jiangsu Province
Nanjing and Suzhou developers integrate cross-brand appliance orchestration into building management systems under MIIT protocol harmonization. SAMR enforces product safety and energy-label accuracy that filters non-compliant component imports. The Yangtze River Delta corridor concentrates smart-appliance firmware engineering talent for connected-property infrastructure.
Sichuan-Chongqing Region
Chengdu new-build residential volumes exceed connected-appliance penetration rates seen in coastal cities five years prior. Rural electrification grid extension opens first-time ownership for refrigeration and laundry equipment in western prefectures. County-level distributors aggregate demand through wholesale channels serving agricultural cold-chain extension beyond household units.
Beijing-Tianjin-Hebei Corridor
Capital region luxury towers specify all-electric mechanical systems to meet prescriptive carbon-intensity targets under dual carbon mandates. Heat-pump performance degradation below minus 15°C restricts deployment in northern Heilongjiang and Inner Mongolia residential heating. Municipal subsidy programs in Beijing and Shanghai incentivize GB Grade 1 and 2 certified equipment procurement.
China Home Appliances Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across China's home appliances sector, creating a tiered structure where scale advantages clash with agility in smart-home integration. The vendor base organizes around manufacturing depth, connectivity platform control, and developer relationship intensity. Three archetypes dominate: integrated ecosystem builders with captive component supply, export-oriented volume manufacturers with backward integration into compressor production, and display-technology specialists extending into living-room appliance suites. Competitive moves concentrate on strategic partnerships with property developers for three-year supply agreements and technology licensing for unified interoperability certification.
Among the integrated ecosystem builders, Haier Smart Home and Haier Group Corporation represent the diversified conglomerate archetype with open-ended IoT platform strategies. Midea Group exemplifies the export-oriented volume manufacturer with scale-driven positioning. Hisense Group Co., Ltd. occupies a position within the display-technology extension archetype, leveraging laser-display integration for premium residential project competition.
| Leading Market Players |
|---|
| Hisense Group Co., Ltd. |
| Haier Smart Home |
| Haier Group Corporation |
| Panasonic Corporation |
| BSH Home Appliances |
| Midea Group |
| TCL Corporation |
| Samsung |
| Gree Electric Appliances, Inc. |
| Others |
Supply Flow & Price Mechanics
Embedded-software engineering talent concentration in the Yangtze River Delta and Pearl River Delta creates labor-cost differentials that widen pricing spreads between IoT-integrated premium tiers and fixed-speed economy units. GB energy-efficiency recertification timelines compress margin structures as manufacturers absorb six-to-nine month approval delays during peak construction seasons.
Pricing Analysis
Price erosion across economy-tier fixed-speed platforms traces to rural electrification programs pulling first-time buyers toward entry-level refrigeration and laundry equipment. Three-tier pricing structure across premium, standard, and economy levels separates GB Grade 1 certified heat-pump systems from Grade 2 inverter units and fixed-speed alternatives. Pricing pressure stems from copper and rare-earth volatility in compressor motor laminations. Rural western prefectures exhibit highest price sensitivity; Shenzhen property developers demonstrate lowest sensitivity given three-year bundled procurement contracts.
Supply Chain Analysis
Workforce availability for firmware engineering constrains control-board production in Jiangsu and Guangdong manufacturing clusters. Supply concentrates in China for compressor assembly, Taiwan and South Korea for power semiconductor modules, and Japan for permanent-magnet materials. Raw material dependencies span copper motor laminations, rare-earth permanent magnets, and refrigerant-grade steel. Single-source vulnerability in inverter-drive semiconductors creates procurement risk. Distribution runs through direct manufacturer-to-developer relationships in tier-one cities and wholesale county-level networks in western provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's home appliances sector functions as a vertical-integration race where captive compressor production and in-house IoT platform control determine margin sustainability. Players pursuing upstream component supply or downstream developer channel lock-in gain structural pricing power.
For Market Incumbents: Deepen backward integration into refrigerant-grade steel and permanent-magnet materials to offset copper volatility exposure. Expand captive compressor capacity in Shandong and Guangdong clusters to defend against emerging heat-pump specialists. Lock three-year developer procurement contracts in Chengdu and Xi'an before MIIT interoperability mandates standardize cross-brand orchestration.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium IoT-integrated suites and economy fixed-speed units offers white-space entry for GB Grade 2 certified inverter platforms with modular connectivity upgrades. Target county-level agricultural cold-chain refrigeration where wholesale distributors aggregate fragmented demand. Pursue white-label manufacturing partnerships with western provincial distributors lacking direct OEM relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier inverter specialists achieving MIIT interoperability certification given developer procurement consolidation. Long-term viability favors manufacturers with captive component supply and firmware engineering depth. Watch GB efficiency tier advancement timelines as inflection signal for product-line transition capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Compressor Production Expansion | Shandong and Guangdong capacity additions insulate margin structures from copper and rare-earth volatility. |
| MIIT Interoperability Certification Investment | Unified data-exchange framework compliance unlocks Shenzhen and Hangzhou developer procurement channels. |
| Heat-Pump Platform Conversion | Dual carbon mandate alignment positions suppliers for Beijing-Tianjin-Hebei luxury tower electrification specifications. |
| County-Level Wholesale Channel Partnerships | Agricultural cold-chain extension in Sichuan-Chongqing creates commercial refrigeration demand aggregation. |
| Firmware Engineering Talent Acquisition | Jiangsu embedded-software capabilities accelerate connected-product launch timelines amid certification delays. |
Methodological Framework
MIIT policy circulars, SAMR certification databases, and provincial grid extension records formed the secondary backbone for market sizing and regulatory trajectory assessment. Primary interviews with appliance OEM procurement directors, property developer facilities managers, and compressor manufacturing plant engineers validated production capacity and procurement specification trends. Bottom-up unit shipment estimates by province and product category triangulated against top-down manufacturer revenue disclosures.
Top-down macroeconomic drivers and bottom-up segment penetration rates converged in the analytical framework across the analysis window. Segmentation dimensions modeled include product type, customer archetype, technology tier, and distribution channel. CAGRs derived from province-level construction permit data, rural electrification grid extension schedules, and MIIT efficiency mandate phase-in timelines. Heat-pump performance degradation thresholds and inverter adoption curves informed climate-system demand projections.
Inputs from MIIT policy releases and provincial statistical yearbooks were available through the study window; gaps in real-time developer contract terms introduce uncertainty bands around premium-tier penetration assumptions. Forecasts reflect documented assumptions regarding dual carbon mandate enforcement intensity and GB standard recertification timeline consistency. Material deviation in SAMR material safety review stringency or NMPA-aligned component sourcing requirements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Egypt Small Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
Electric Household Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Europe White Goods Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Germany Major Home Appliance Market