
 Household Refrigerator Market | 2026-2036
Household Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Household Refrigerator Market Outlook
Leasing and pay-per-use appliance subscription models is rewriting capital deployment across the household refrigerator industry. Samsung Electronics leverages its semiconductor supply chain to integrate connected cooling platforms. Haier Smart Home anchors its position through backward integration into compressor manufacturing. Whirlpool sustains brand loyalty via proprietary water-filtration ecosystems tied to replacement revenue.
A household refrigerator is a thermally insulated cabinet employing vapor-compression refrigeration to maintain food storage temperatures between 0°C and 5°C in fresh compartments and below −18°C in freezer sections, utilizing polyurethane foam insulation and hermetic rotary or linear compressors driven by refrigerants such as R-600a or R-134a. French Door configurations command premium positioning in North American kitchens where width and capacity requirements dominate. Inverter technology leads efficiency-driven replacement cycles across Asian households where electricity tariffs structure total-cost-of-ownership calculations. Smart connectivity represents the fastest-expanding technology segment as Wi-Fi-enabled diagnostics shift service models from reactive to predictive.
The US Department of Energy sets minimum energy conservation standards under 10 CFR 430, while the EPA's SNAP program governs refrigerant transitions away from high-GWP compounds. The EU F-Gas Regulation and Ecodesign requirements mandate phasedown of hydrofluorocarbons and enforce repairability indexing. China's GB standards and MIIT circular economy directives enforce recycling quotas for retired units. Stakeholders must monitor refrigerant chemistry transitions and modular design mandates as these regulatory vectors increasingly determine product architecture and geographic market access feasibility.
Market Dynamics
The US Department of Energy's revised compressor efficiency standards under 10 CFR 430 are forcing fundamental redesigns of refrigeration architectures, while India's urban household formation accelerates replacement cycles and China's tier-one cities drive smart-home integration at compressed refresh intervals.
Growth Catalysts
- Appliance Efficiency Mandates:The US Department of Energy's 10 CFR 430 standards compel inverter compressor adoption, creating pull-through demand for replacement units that meet stricter coefficient-of-performance thresholds.
- Urban Household Formation:India's metropolitan expansion generates first-time buyer volumes alongside replacement waves as nuclear family structures proliferate in Mumbai, Delhi, and Bangalore.
- Smart-Home Ecosystem Convergence:Wi-Fi-enabled diagnostics and predictive maintenance protocols are restructuring service revenue models from reactive repair to subscription-based monitoring platforms.
Market Restraints
- Refrigerant Chemistry Volatility:The EPA's SNAP program and EU F-Gas Regulation mandate phasedown of hydrofluorocarbons, forcing costly retooling for R-600a and R-1234yf compatibility across production lines.
- Steel and Copper Input Concentration:Compressor manufacturing depends on concentrated Southeast Asian metal suppliers, exposing margin structures to commodity price swings and logistics bottlenecks.
- Polyurethane Foam Insulation Limitations:Thermal performance ceilings in conventional cabinet construction constrain efficiency gains without dimensional trade-offs that conflict with North American width preferences.
Strategic Opportunities
- Leasing and Subscription Models:Pay-per-use appliance financing is penetrating European markets where capital-light consumption preferences align with circular economy mandates under EU Ecodesign requirements.
- Repairability Index Optimization:France's mandatory repairability scoring creates competitive differentiation for modular designs with standardized component interfaces and extended spare-part availability.
- Predictive Maintenance Integration:IoT sensor convergence with cloud analytics enables remote compressor diagnostics, reducing field service dispatch costs and extending asset lifecycles for fleet operators.
Industry Challenges
- Hermetic Compressor Engineering Talent Scarcity:The specialized knowledge base for rotary and linear compressor design is concentrating among aging technical workforces in Japan and Germany.
- Multi-Regulatory Certification Overlap:Simultaneous compliance with US DOE efficiency testing, EU F-Gas phasedown schedules, and China's GB recycling quotas extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Refrigerator Market |
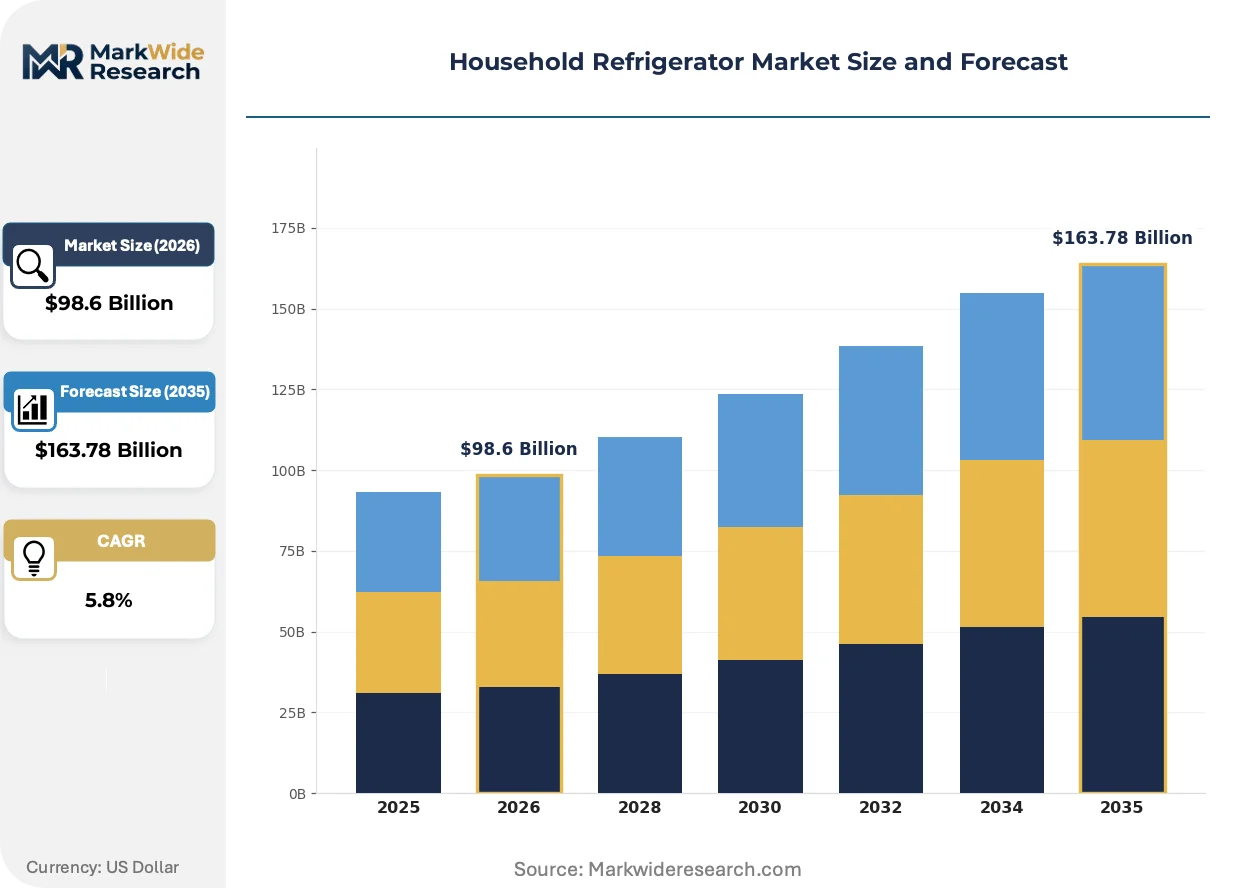
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $163.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Side-by-Side, French Door, Top Freezer, Bottom Freezer Technology: Inverter, Non-Inverter, Smart, Conventional End User: Households, Apartments, Dormitories, Restaurants Size: Compact, Standard, Large, Extra Large |
| Companies Covered | Haier Smart Home Co., Ltd., Samsung Electronics Co., Ltd., LG Electronics Inc., Whirlpool Corporation, Electrolux AB, GE Appliances, Panasonic Holdings Corporation, Robert Bosch GmbH, Hitachi, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Refrigerator Market Strategic Shifts
Refrigeration technology is undergoing platform-level transformation as compressor architectures, refrigerant chemistries, and connectivity protocols converge to meet efficiency mandates while enabling new service monetization models.
Variable-speed inverter compressors are replacing fixed-speed rotary units in mid-tier and premium segments, modulating cooling output to match thermal load rather than cycling on-off. Asian households facing electricity tariff structures that penalize peak consumption are adopting these systems at accelerated rates. This hardware transition is digitizing energy management interfaces and enabling utility-controlled demand-response participation.
The EU F-Gas Regulation mandates an 80% phasedown of hydrofluorocarbon consumption by 2030, prohibiting new equipment using refrigerants above specified global-warming-potential thresholds. Manufacturers are requalifying production lines for hydrocarbon and hydrofluoroolefin alternatives with flammability-handling protocols. French and German markets are experiencing the most acute compliance pressure as national implementations enforce earlier phaseout dates than the baseline directive.
Direct-to-consumer channels and appliance-as-a-service contracts are displacing traditional retail financing in urban markets where credit access and space constraints favor flexible ownership models. European consumers are leading this behavioral shift, with subscription providers bundling maintenance, efficiency upgrades, and end-of-life recycling into monthly fees. This restructuring compresses manufacturer-brand relationships and elevates platform operators as the primary customer interface.
Household Refrigerator Market Segmentation
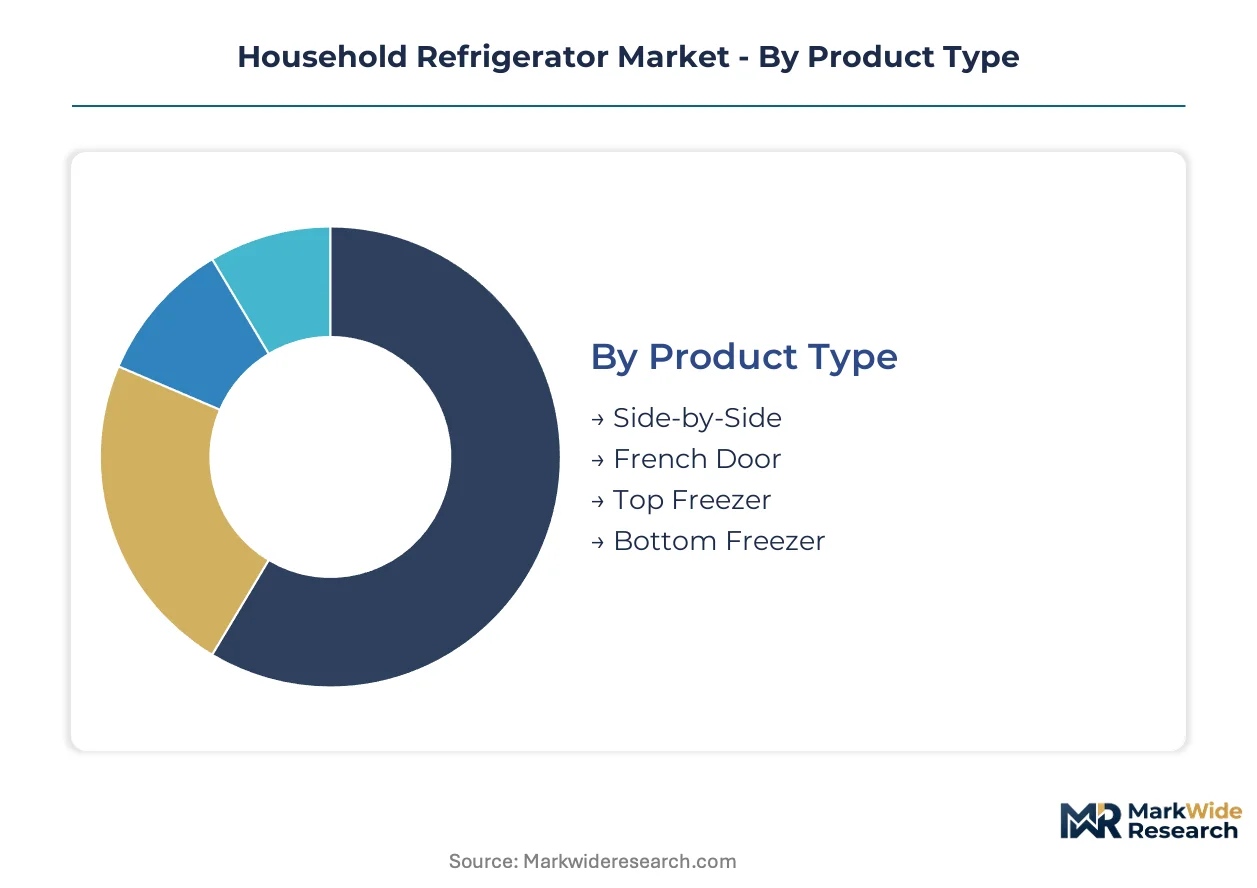
Refrigerator segmentation maps divergent engineering requirements against distinct ownership economics. Configuration choices dictate compressor sizing, insulation depth, and control system complexity, while technology tiers separate capital expenditure from lifecycle operating costs.
Product Type:
Cost tier stratification across refrigerator configurations reflects kitchen spatial constraints and storage volume trade-offs.
- French Door:Dual-door fresh compartments above pull-out freezer drawers maximize usable width for sheet-pan storage. North American suburban kitchens with island layouts absorb premium pricing for this configuration as household size and entertainment frequency drive cubic-foot requirements.
- Side-by-Side:Vertical split between fresh and frozen compartments delivers narrow door swing arcs suited to galley kitchens. Urban apartments in Mumbai and São Paulo favor this format where doorway widths and corridor clearances constrain appliance dimensions.
- Top Freezer:Traditional stacked design maintains lowest manufacturing cost through single compressor serving both zones. First-time buyers and rental property owners prioritize this segment for acquisition affordability.
- Bottom Freezer:Eye-level fresh food access reduces bending frequency for aging demographics. European markets with older household profiles show disproportionate preference for this ergonomic arrangement.
Top Freezer commands the established base. The steepest expansion runs through French Door.
Technology:
Application-specific efficiency mandates and connectivity premiums are restructuring technology adoption curves across regulatory jurisdictions.
- Inverter:Variable-speed compressors modulate refrigerant flow to thermal load rather than cycling on-off, cutting energy consumption by 20-30% versus fixed-speed equivalents. Japanese and South Korean households facing tiered electricity tariffs recover premium pricing through operating cost savings within 3-4 years.
- Smart:Wi-Fi-enabled diagnostics, inventory cameras, and utility demand-response interfaces transform appliances into data nodes. China's tier-one cities lead deployment as Mijia and similar platforms integrate refrigeration into whole-home automation ecosystems.
- Non-Inverter:Fixed-speed rotary compressors remain standard in price-sensitive markets where capital constraints override efficiency calculations. Southeast Asian rural electrification programs and African urbanization waves sustain this segment's volume.
- Conventional:Mechanical thermostats and absence of electronic controls minimize failure modes and repair costs. Institutional purchasers in hospitality and education sectors specify this reliability-focused configuration.
Non-Inverter retains volume leadership in emerging markets. Smart connectivity gains share fastest among premium urban replacements.
End User:
Customer type determines durability specifications, warranty terms, and service network density requirements.
- Households:Nuclear family units drive replacement cycles tied to kitchen renovation timelines and efficiency upgrade incentives. India's urban household formation concentrates demand here as first-time buyers establish independent residences.
- Apartments:Space-constrained multi-unit dwellings demand compact dimensions, reduced noise signatures, and neutral aesthetics for open-plan integration. European city centers and East Asian megacities structure procurement around these constraints.
- Dormitories:Institutional volume purchasers prioritize theft-resistant designs, minimal maintenance requirements, and standardized dimensions for fleet replacement. University housing authorities and military barracks represent concentrated contracting channels.
- Restaurants:Commercial-grade durability expectations, rapid temperature recovery after door openings, and health code compliance documentation distinguish this segment. Food service operators accept premium pricing for reliability guarantees.
Households anchor aggregate demand. Restaurants generate the highest per-unit margin contribution.
Size:
Volume segmentation aligns cabinet dimensions with household composition, storage habits, and real estate economics.
- Standard:18-22 cubic foot capacities match median household refrigeration requirements across developed economies. This segment captures the efficiency sweet spot where insulation thickness and compressor sizing optimize energy performance per stored liter.
- Large:23-28 cubic foot configurations accommodate bulk purchasing and extended fresh storage for suburban households with vehicle access to warehouse retailers. North American market penetration exceeds other geographies due to dwelling size and shopping pattern differences.
- Compact:Under-counter and mini-refrigerator formats serve secondary cooling needs in bedrooms, offices, and hospitality settings. European studio apartments and Japanese single-person households sustain this segment despite limited primary kitchen adoption.
- Extra Large:29+ cubic foot capacities target multi-generational households and dedicated frozen storage applications. Energy efficiency regulations in California and EU member states constrain this segment's growth through maximum annual consumption limits.
Standard size holds the volume center. Compact formats expand most quickly through hospitality and remote work applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Energy's 10 CFR 430 efficiency standards and India's urban household formation incentives are reshaping procurement patterns across distinct national markets. Regulatory pressure on compressor redesigns intersects with smart-home integration in China's tier-one cities.
United States
Suburban kitchen renovations and island-layout preferences drive French Door configuration demand. The US Department of Energy enforces minimum energy conservation standards under 10 CFR 430. California's Title 20 appliance regulations constrain maximum annual consumption for extra-large capacity units.
China
Tier-one city smart-home ecosystems accelerate replacement cycles through Mijia platform integration. MIIT circular economy directives enforce recycling quotas for retired refrigerator units. Shanghai and Beijing concentrate demand for Wi-Fi-enabled diagnostics and predictive maintenance protocols.
India
Urban household formation in Mumbai, Delhi, and Bangalore generates first-time buyer volumes alongside nuclear family replacement waves. BIS energy labeling standards structure efficiency tiering for consumer comparison. Gujarat and Maharashtra industrial corridors host compressor component manufacturing clusters.
Germany
Aging demographics favor bottom freezer ergonomic arrangements with reduced bending frequency. The EU F-Gas Regulation mandates phasedown of hydrofluorocarbons with stricter national implementation timelines. Bavaria and Baden-Württemberg anchor refrigeration engineering talent concentration.
Japan
Tiered electricity tariffs accelerate inverter compressor adoption for operating cost recovery within 3-4 years. METI efficiency standards and JIS certification requirements structure product architecture. The Kanto region around Tokyo concentrates connected cooling platform development.
Household Refrigerator Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The household refrigerator industry exhibits consolidated leadership among diversified appliance conglomerates with captive semiconductor or compressor supply chains. Three archetypes dominate: integrated platform operators leveraging backward integration into component manufacturing, brand-loyalty builders anchoring replacement revenue through proprietary accessory ecosystems, and connectivity-first players converging refrigeration with whole-home automation. Competitive moves center on M&A for regional distribution access and strategic partnerships for smart-home protocol integration.
Among Asia-Pacific-based conglomerates, Haier Smart Home Co., Ltd. exemplifies the integrated platform archetype through captive compressor manufacturing, while Samsung Electronics Co., Ltd. occupies a position representing semiconductor-supply-chain convergence with connected cooling. LG Electronics Inc. anchors the tier specializing in variable-speed inverter technology deployment.
| Leading Market Players |
|---|
| Haier Smart Home Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Whirlpool Corporation |
| Electrolux AB |
| GE Appliances |
| Panasonic Holdings Corporation |
| Robert Bosch GmbH |
| Hitachi, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Steel and copper input concentration among Southeast Asian metal suppliers determines both tiered pricing spreads across compressor-dependent product lines and the geographic clustering of manufacturing footprints. This commodity dependency forces manufacturers to absorb margin volatility or pass through cost swings, compressing mid-tier positioning while premium and economy segments maintain structural separation.
Pricing Analysis
Energy efficiency certification tiering under DOE 10 CFR 430 and EU Ecodesign creates the primary spread between premium inverter systems and baseline fixed-speed units. Three-tier pricing structure across premium smart-connected, standard inverter, and economy non-inverter levels reflects differential compliance costs and after-sales service bundling. Pricing pressure stems from refrigerant chemistry transitions forcing costly retooling for R-600a and R-1234yf compatibility. First-time buyers in India's urban expansion zones exhibit highest price sensitivity, while North American replacement purchasers prioritize total-cost-of-ownership calculations over acquisition cost.
Supply Chain Analysis
Polyurethane foam feedstock and hermetic compressor castings draw from concentrated supply bases in China, Thailand, and Vietnam. Rotary compressor manufacturing rests on steel sheet and copper winding imports, while cabinet insulation depends on MDI and polyol chemical streams. Single-source vulnerability runs through Japanese and German hermetic compressor engineering talent pools as aging workforces concentrate specialized knowledge. Distribution runs through big-box retail chains in North America, platform-integrated e-commerce in China, and traditional trade channels sustaining volume in India's secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-home ecosystem penetration in China's tier-one cities signals early-cycle expansion, with Wi-Fi-enabled diagnostics restructuring service revenue models before mass-market saturation.
For Market Incumbents: Entrench platform control through captive compressor manufacturing and proprietary connectivity protocols that lock in replacement part revenue. Haier Smart Home's backward integration into compressor production offers a defensive template against margin erosion from refrigerant transition costs. Incumbents must secure hermetic compressor engineering talent in Japan and Germany before demographic concentration accelerates capability scarcity. For New Entrants and Emerging Players: Rural electrification corridors in Southeast Asia and African urbanization waves present white-space targets where capital constraints sustain non-inverter volume. India's nuclear family household formation generates first-time buyer demand underserved by premium-focused incumbents. A direct-to-consumer subscription model bundling maintenance and end-of-life recycling bypasses traditional retail gatekeepers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors component-integrated specialists over brand-loyalty builders. Long-term viability hinges on regulatory compliance capabilities across multiple jurisdictions rather than geographic scale alone. Acquisition targets should demonstrate modular design competence for EU repairability mandates and established refrigerant chemistry transition pipelines. The signal to watch is utility demand-response partnership announcements as predictive maintenance platforms mature.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply of hermetic rotary units insulates margins from Southeast Asian metal price volatility. |
| Smart-Home Platform Integration | Mijia and similar ecosystems in Shanghai and Beijing accelerate replacement cycles through diagnostics bundling. |
| Subscription Service Launch | Pay-per-use contracts align with EU Ecodesign circular economy mandates and reduce customer acquisition friction. |
| Refrigerant Chemistry Retooling | R-600a and R-1234yf compatibility investments secure market access under EPA SNAP and EU F-Gas phasedown schedules. |
| Repairability Index Optimization | France's mandatory scoring creates competitive differentiation for modular designs with standardized component interfaces. |
Study Parameters
Initial hypotheses were tested against primary input from compressor engineering directors, appliance procurement managers at multi-unit housing developers, and aftermarket service network operators, then refined through secondary validation. Compressor engineering directors, retail category buyers, circular economy compliance officers, and utility demand-response program managers provided field perspectives. Secondary sources included DOE 10 CFR 430 filings, EU Ecodesign repairability databases, MIIT recycling quota disclosures, and customs trade records for steel and copper inputs. Bottom-up unit shipment modeling and top-down value reconciliation ensured cross-verification across the analysis window.
Demand-supply balance framing anchored the forecast framework, with replacement cycle timing and smart-home penetration curves driving volume projections. Segmentation dimensions spanned configuration type, compressor technology tier, end-user category, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and efficiency mandate compliance deadlines. Refrigerant chemistry transition timelines and electricity tariff structures in Japan and South Korea provided industry-specific demand elasticity inputs.
Practitioners should monitor refrigerant phasedown acceleration, utility demand-response program expansion, and hermetic compressor engineering talent migration for early signals of forecast revision. Quarterly review of DOE efficiency standard update schedules, EU F-Gas implementation timelines, and MIIT recycling quota enforcement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Latin America Washing Machine Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
China Small Home Appliances Market
Home Appliances
Major Home Appliances Market
Home Appliances
South Korea Small Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Residential Washing Machine Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Saudi Arabia Major Home Appliances Market