
 Asia-Pacific Major Home Appliance Market | 2026-2036
Asia-Pacific Major Home Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Major Home Appliance Market Outlook
Aftermarket service revenue is reshaping margin architecture across the Asia-Pacific major home appliance landscape. Haier Smart Home leverages its connected-ecosystem infrastructure to capture recurring software and maintenance income streams. Samsung Electronics anchors its regional position through captive semiconductor supply chains for inverter modules. Midea Group competes on manufacturing scale, operating some of the world's largest compressor and motor production complexes in Guangdong province.
Asia-Pacific major home appliances encompass electrically powered domestic equipment including refrigerators, washing machines, air conditioners, and ovens, typically rated above 1 kW input power and designed for continuous or frequent residential use with operational lifespans of 10-15 years. Refrigerators constitute the largest installed base across the region, though inverter-technology air conditioners claim the fastest replacement-cycle velocity due to tropical climate stress and efficiency-upgrade incentives. Smart appliances and IoT-enabled platforms concentrate margin pools in software-layer subscriptions and predictive-maintenance contracts rather than hardware sales alone.
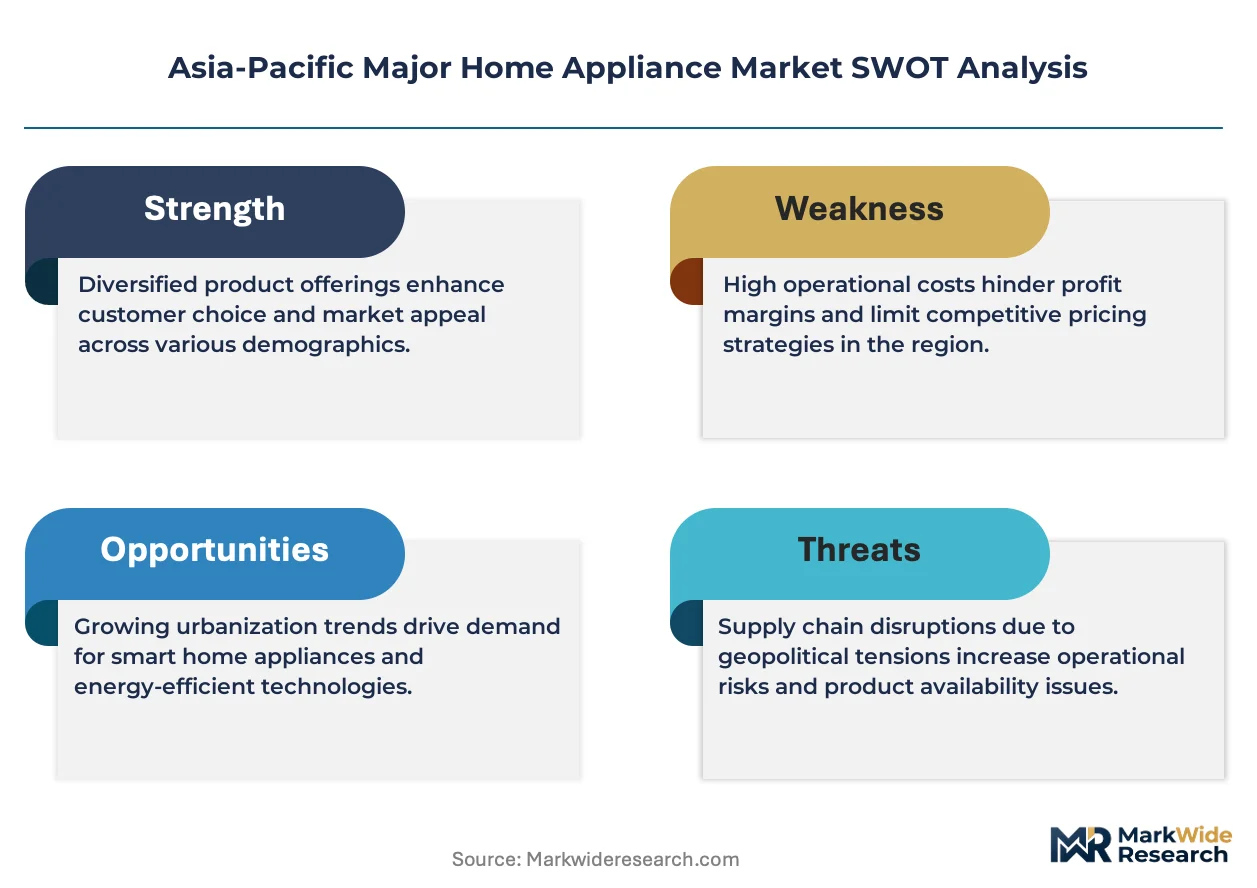
China's SAMR enforces GB standards for energy consumption and refrigerant phase-down schedules, while India's BIS mandates star-labeling thresholds that effectively bar non-compliant imports from Bangladesh and Southeast Asian assembly hubs. Japan's METI directs Top Runner standards that cascade into regional supply-chain specifications through component-sourcing dependencies. Stakeholders must monitor how carbon-border adjustments and refrigerant-transition timelines will restructure sourcing geography and certification burdens across the forecast horizon.
Market Dynamics
Refrigerant phase-down mandates under China's GB standards and India's BIS energy-labeling thresholds are compressing product lifecycles and forcing component-level redesigns across compressor and heat-exchanger supply chains.
Growth Catalysts
- Inverter-motor adoption:Southeast Asian urban households are replacing fixed-speed air conditioners with variable-frequency units to meet tropical cooling loads and utility rebate thresholds.
- India's PLI scheme for white goods:Component manufacturing incentives are attracting compressor and motor assembly capacity to Gujarat and Tamil Nadu industrial corridors.
- Japan's Top Runner standards:METI efficiency benchmarks cascade through regional OEM sourcing specifications, accelerating premium product penetration.
Market Restraints
- Copper and rare-earth input volatility:Permanent-magnet motor costs fluctuate with dysprosium and neodymium concentrate pricing from Chinese separation facilities.
- Refrigerant supply concentration:HFC-32 and R-290 production clusters in Shandong province create single-source dependency for Indian and ASEAN assembly plants.
- Technical limitation in heat-pump performance:Sub-5°C ambient efficiency degradation constrains air-source adoption in northern Chinese and Himalayan markets.
Strategic Opportunities
- Underpenetrated rural Vietnam:Grid electrification in Mekong Delta provinces is unlocking first-time refrigerator and washing-machine ownership.
- IoT predictive maintenance:Connected compressor diagnostics enable subscription revenue streams from software-layer service contracts.
- Regulatory tailwind from Australia's GEMS:Minimum energy performance standards create import barriers that favor regional OEMs with established testing infrastructure.
Industry Challenges
- Refrigerant-handling certification gaps:R-290 flammability protocols require technician retraining that outpaces vocational pipeline capacity in Indonesia and Philippines.
- Legacy inverter control integration:Smart-grid communication standards vary across Japanese, Korean, and Chinese protocols, complicating unified firmware architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Major Home Appliance Market |
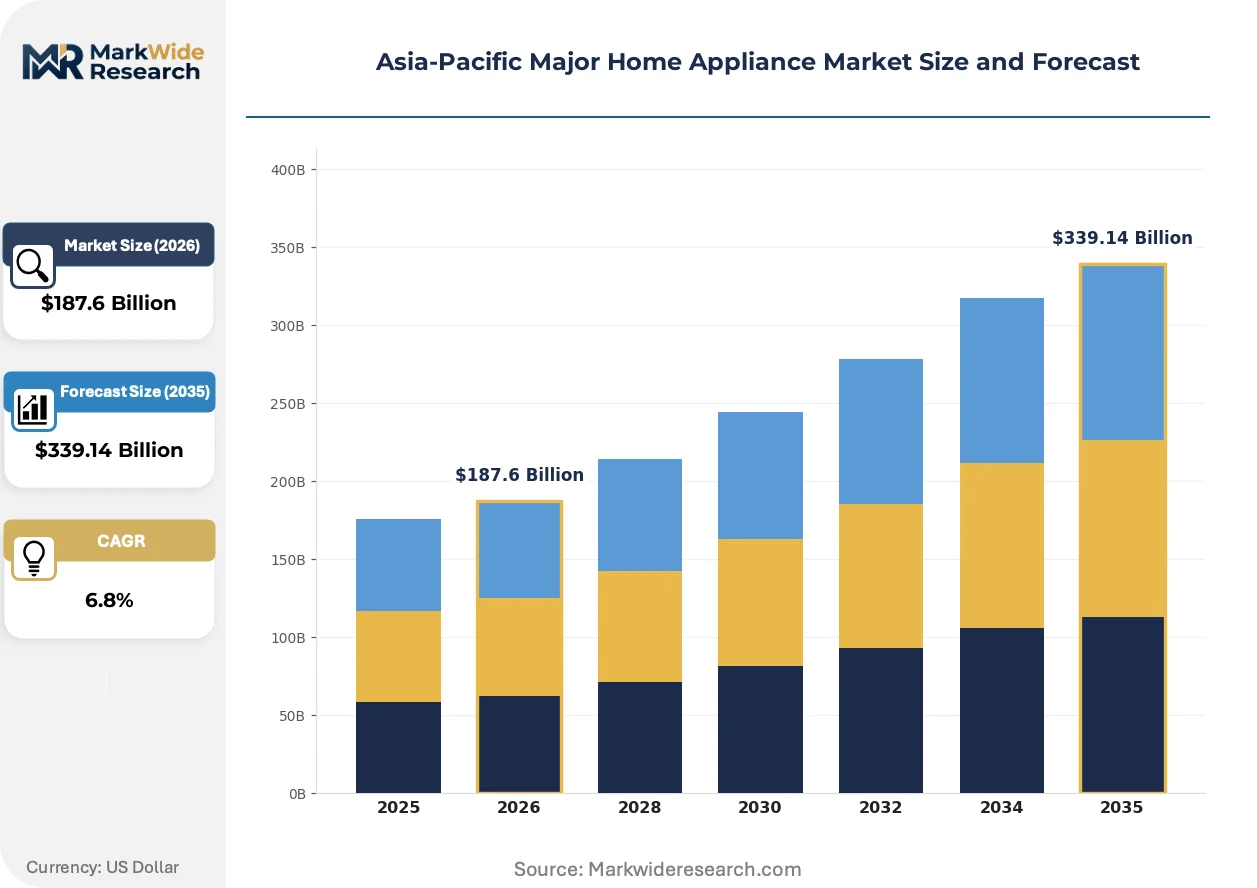
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Air Conditioners, Ovens Technology: Smart Appliances, Energy Efficient, Inverter Technology, IoT-Enabled End User: Households, Residential Buildings, Commercial Spaces, Retail Outlets Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Haier Smart Home, Midea Group, LG Electronics, Samsung Electronics, Panasonic Corporation, Hisense Group, Whirlpool Corporation, BSH Hausgeräte, Sharp Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Major Home Appliance Market Strategic Shifts
Hardware-software decoupling is redistributing margin pools from unit sales toward recurring service revenue, while refrigerant chemistry and motor topology shifts are rewriting component sourcing maps.
Variable-speed linear compressors eliminate crankcase mechanical losses through direct electromagnetic piston drive. Korean and Japanese OEMs are embedding these units in premium side-by-side refrigerators for Seoul and Tokyo apartment segments. Fixed-frequency reciprocating compressor architectures are rendering obsolete for capacity classes above 300 liters.
China's SAMR is accelerating GB 21455-2019 revisions that tighten seasonal performance factor thresholds for room air conditioners. Component suppliers must recalibrate expansion valve maps and coil surface geometries to maintain compliance. India's western state clusters face the steepest retrofit burden due to above-average inverter penetration rates.
Appliance-as-a-service contracting is displacing outright purchase in Australian and New Korean rental housing markets. Property management platforms bundle energy-monitoring subscriptions with maintenance coverage. Sydney and Melbourne multi-unit residential developments represent the densest adoption geography for this procurement model.
Asia-Pacific Major Home Appliance Market Segmentation
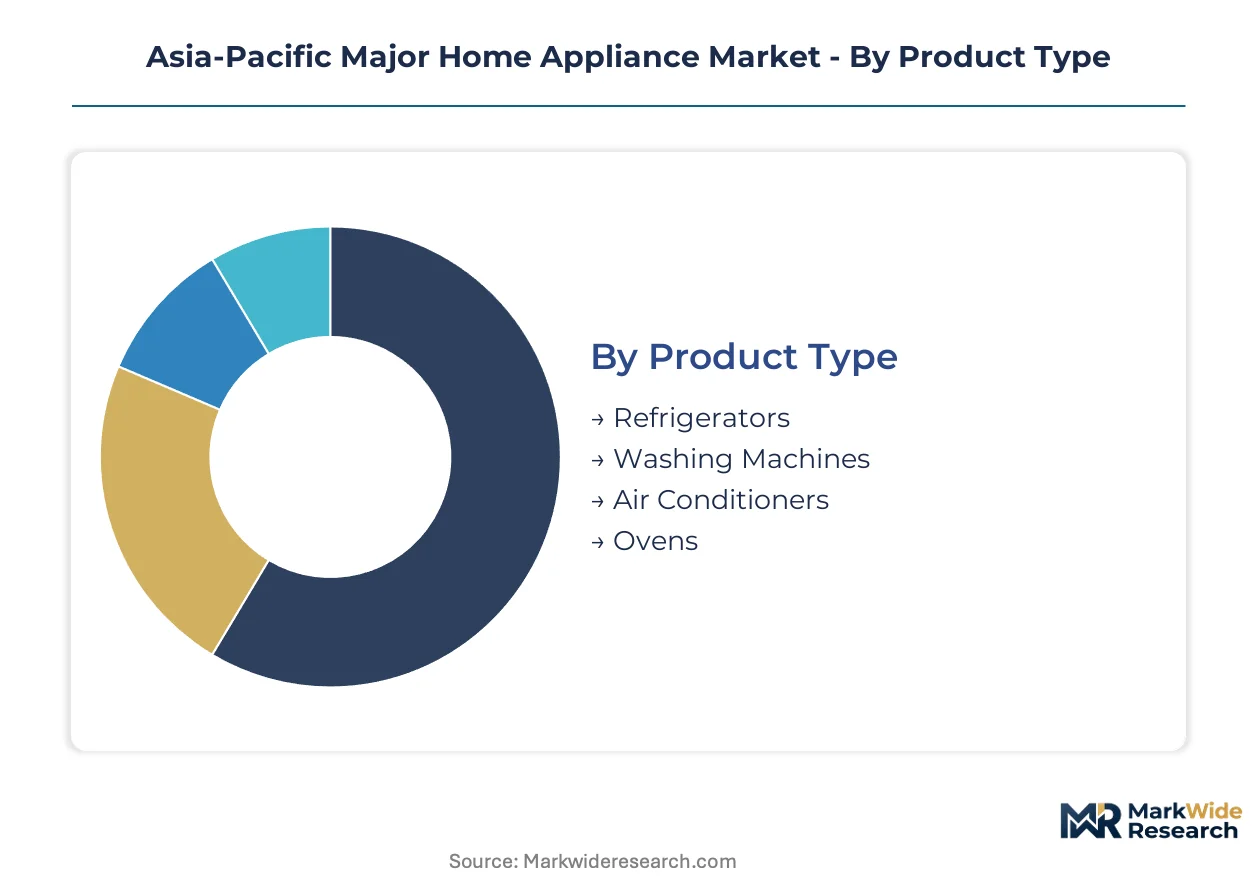
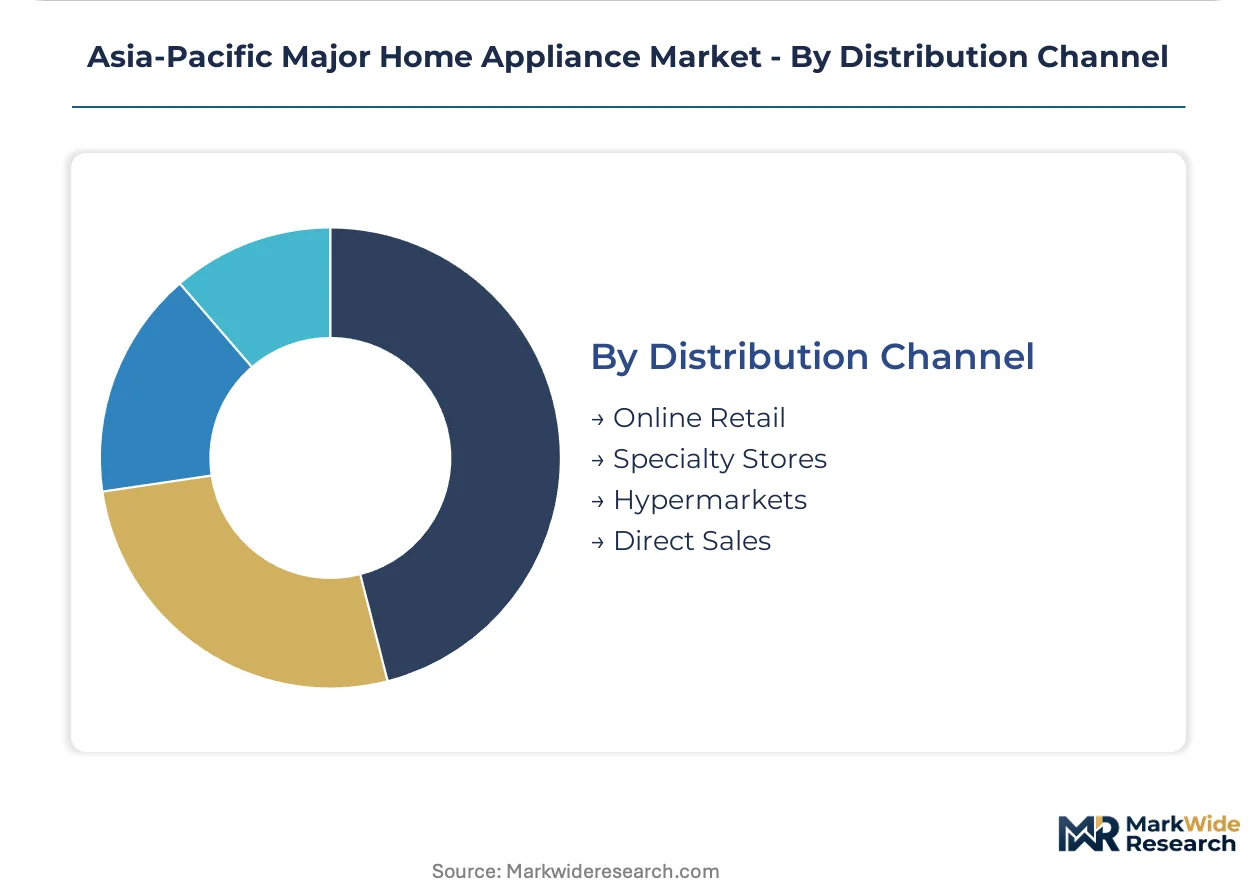
Segmentation in the Asia-Pacific major home appliance market exposes how margin pools concentrate across technology tiers and channel structures. Product type and technology segmentation reveal where inverter-motor upgrades and refrigerant transitions are forcing replacement cycles. Distribution channel splits track the shift from traditional retail toward connected-platform procurement in Southeast Asian megacities.
Product Type:
Cost tier stratification across refrigeration, climate control, and cooking equipment segments the installed base by replacement velocity and energy-labeling exposure.
- Refrigerators:Side-by-side and multi-door configurations dominate premium urban households in Seoul and Tokyo, where linear compressor adoption eliminates mechanical crankcase losses. India's western state clusters drive volume demand for direct-cool units as electrification penetrates tier-2 cities.
- Washing Machines:Front-loading drum machines with inverter direct-drive motors capture share in Australian and Korean markets where water-efficiency labeling mandates steep thresholds. Top-loading agitator designs retain dominance in Vietnamese and Indonesian rural first-time ownership segments.
- Air Conditioners:Split-system inverter units replace fixed-speed window units across Southeast Asian megacities responding to BIS and GB efficiency thresholds.
- Ovens:Built-in convection models concentrate in Japanese and Australian renovation cycles; freestanding gas ranges dominate Indian and Southeast Asian cooking cultures.
Refrigerators command the established base. The steepest expansion runs through air conditioners.
Technology:
Application sophistication separates hardware-only sales from recurring software-layer revenue streams across the regional installed base.
- Smart Appliances:Wi-Fi-enabled refrigerators and washing machines in Seoul and Sydney apartment developments bundle predictive maintenance subscriptions with hardware procurement.
- Energy Efficient:Five-star BIS-labeled and GB 21455-2019 compliant units face mandatory phase-in timelines that compress product lifecycles in India and China.
- Inverter Technology:Variable-frequency compressor and motor drives eliminate start-stop cycling losses. Demand concentrates in Thailand and Vietnam where utility rebate programs accelerate fixed-speed replacement.
- IoT-Enabled:Connected climate-control systems with smart-grid communication capabilities face protocol fragmentation between Japanese, Korean, and Chinese standards.
Inverter technology commands the established base. The steepest expansion runs through IoT-enabled platforms.
End User:
Customer type determines procurement scale, specification complexity, and service-contract attachment rates across residential and commercial deployment.
- Households:Individual family units in Southeast Asian megacities drive replacement demand for connected refrigeration and climate-control systems with 10-15 year operational horizons.
- Residential Buildings:Multi-unit developers in Sydney and Melbourne bundle appliance-as-a-service contracts with property management platforms, displacing outright purchase.
- Commercial Spaces:Office and hospitality installations in Singapore and Hong Kong specify centralized climate control with building-management system integration.
- Retail Outlets:Appliance showroom and service-center footprints concentrate in India's Gujarat and Tamil Nadu industrial corridors near component assembly hubs.
Households command the established base. The steepest expansion runs through residential buildings.
Distribution Channel:
Volume concentration and margin capture diverge sharply between physical retail infrastructure and digital platform penetration across national markets.
- Online Retail:E-commerce platforms capture growing share in Australian and Korean markets where subscription bundling and predictive maintenance contracts attach to connected-product sales.
- Specialty Stores:Dedicated appliance retailers in Japan and South Korea provide installation and refrigerant-handling certification services that online channels cannot replicate.
- Hypermarkets:Big-box retail in Thailand and Indonesia moves volume for standard-efficiency refrigerators and washing machines in electrifying rural provinces.
- Direct Sales:OEM-owned service networks in China and India handle inverter-technology upgrades and extended-warranty attachments for premium product tiers.
Hypermarkets command the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific region. Japanese and Korean households prioritize premium smart-enabled units with predictive maintenance subscriptions. Indian and Southeast Asian markets concentrate demand in entry-to-mid-tier efficiency tiers driven by electrification and first-time ownership waves.
China
Urban households in Shanghai and Beijing drive replacement demand for connected refrigeration systems with 10-15 year operational horizons. SAMR enforces GB 21455-2019 revisions that tighten seasonal performance factor thresholds for room air conditioners. Component suppliers in Shandong province recalibrate expansion valve maps and coil surface geometries to maintain compliance with accelerating efficiency mandates.
India
Western and southern state clusters in Gujarat and Tamil Nadu outpace national residential construction velocity, concentrating demand for direct-cool refrigerators and inverter air conditioners. BIS star-labeling thresholds effectively bar non-compliant imports from Bangladesh and Southeast Asian assembly hubs. The PLI scheme for white goods attracts compressor and motor assembly capacity to industrial corridors near Ahmedabad and Chennai.
Japan
Tokyo and Osaka apartment segments specify linear compressor-equipped side-by-side refrigerators that eliminate mechanical crankcase losses. METI Top Runner standards cascade through regional OEM sourcing specifications, accelerating premium product penetration. Nagoya-based component fabricators supply variable-speed motor drives to Korean and Chinese assembly plants under technology licensing arrangements.
South Korea
Seoul metropolitan developers bundle appliance-as-a-service contracts with property management platforms, displacing outright purchase in multi-unit residential developments. Korean OEMs embed variable-speed linear compressors in premium refrigeration units through captive semiconductor supply chains for inverter modules. Busan-Ulsan industrial corridors host motor and compressor testing facilities serving regional export markets.
Australia
Sydney and Melbourne multi-unit residential developments represent the densest adoption geography for subscription-based procurement models. GEMS minimum energy performance standards create import barriers that favor regional OEMs with established testing infrastructure. Queensland and Western Australia grid electrification programs unlock replacement cycles for aging fixed-speed air conditioning stock.
Asia-Pacific Major Home Appliance Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three distinct competitive archetypes: diversified electronics conglomerates with captive semiconductor supply chains, pure-play appliance specialists with manufacturing scale advantages, and emerging ecosystem players monetizing software-layer service contracts. Consolidation pressure operates through backward integration into compressor and motor production, alongside strategic partnerships for smart-grid protocol standardization.
Within the diversified conglomerate tier, Samsung Electronics and LG Electronics exemplify players anchoring regional position through upstream control over inverter module supply. Haier Smart Home occupies a position representing the ecosystem archetype, capturing recurring software and maintenance income streams through connected-platform infrastructure. Midea Group sits within the manufacturing-scale tier, operating production complexes in Guangdong province that supply regional assembly plants.
| Leading Market Players |
|---|
| Haier Smart Home |
| Midea Group |
| LG Electronics |
| Samsung Electronics |
| Panasonic Corporation |
| Hisense Group |
| Whirlpool Corporation |
| BSH Hausgeräte |
| Sharp Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Guangdong province compressor manufacturing clusters compresses supplier margins and intensifies pricing competition across China's domestic market. Utilization rates below 80 percent force component suppliers to absorb rare-earth magnet cost volatility rather than pass through to OEMs, while Indian PLI scheme beneficiaries in Gujarat and Tamil Nadu gain pricing latitude through production-linked incentives.
Pricing Analysis
Long-term offtake contracts dominate procurement between Shandong province refrigerant producers and Indian assembly plants, insulating buyers from spot-market HFC-32 volatility. Price differentiation separates BIS five-star certified units from non-compliant imports barred by India's energy-labeling thresholds. Cost compression in mid-tier inverter air conditioners intensifies as Thai and Vietnamese utility rebate programs accelerate fixed-speed replacement cycles. Rural Indonesian first-time buyers exhibit highest price sensitivity; Seoul and Tokyo apartment developers show lowest sensitivity due to appliance-as-a-service bundling.
Supply Chain Analysis
Export-control regimes on permanent-magnet motor technology limit Korean and Japanese variable-speed drive exports to Chinese assembly partners. Supply concentration centers on China for compressor castings and motor laminations, South Korea for inverter module semiconductors, and Thailand for coil heat-exchanger fabrication. Raw material dependencies draw from Shandong province HFC-32 production, Jiangxi rare-earth separation facilities, and Chilean copper concentrate. Single-source vulnerability runs through Shandong refrigerant clusters serving ASEAN assembly plants. Distribution runs through OEM-owned service networks in China and India for premium-tier installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as China's dual carbon goals and India's BIS mandates force replacement cycles across the region's installed base.
For Market Incumbents: Build captive semiconductor moats for inverter module supply to defend against Korean electronics conglomerates with upstream control. Secure backward integration into compressor casting and rare-earth magnet sourcing to neutralize dysprosium price volatility from Jiangxi separation facilities. Invest in R-290 flammability-handling certification infrastructure ahead of vocational pipeline gaps in Indonesia and Philippines. For New Entrants and Emerging Players: Build out IoT predictive maintenance platforms targeting Australian and Korean multi-unit residential developers with subscription bundling. Underpenetrated rural Vietnam offers the most penetrable geography as Mekong Delta grid electrification unlocks first-time refrigerator ownership. Partner with property management platforms in Sydney and Melbourne for appliance-as-a-service channel access. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because efficiency-mandate tightening across China SAMR and India BIS creates sustained component-upgrade demand. Target mid-tier inverter technology specialists with established testing infrastructure for Australia's GEMS barriers. Watch refrigerant-transition timeline acceleration as the inflection signal forcing supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive production in Guangdong and Tamil Nadu insulates margins from Shandong supply concentration. |
| IoT Platform Integration | Predictive maintenance subscriptions in Seoul and Sydney shift revenue from hardware to recurring software. |
| R-290 Refrigerant Transition | Flammability protocol compliance ahead of India's BIS phase-down timelines creates first-mover certification advantage. |
| Smart-Grid Protocol Standardization Partnership | Unified firmware architectures resolve fragmentation between Japanese, Korean, and Chinese communication standards. |
| Appliance-as-a-Service Launch | Property management bundling in Australian multi-unit developments displaces transactional purchase models. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with compressor manufacturing executives, BIS certification specialists, utility rebate program administrators, and property management platform operators; and secondary validation through China SAMR GB standard filings, India PLI scheme disclosure documents, Australia GEMS registry data, and ASEAN customs trade records. Bottom-up unit shipment modeling triangulated against top-down consumer expenditure surveys.
Forecast inputs considered product type segmentation across refrigeration, climate control, washing, and cooking equipment; technology tiers spanning inverter, smart-enabled, and IoT-connected platforms; and distribution channel splits between online retail, specialty stores, hypermarkets, and direct OEM service networks. CAGRs were derived from installed base replacement velocity analysis and regulatory mandate phase-in schedules. Industry-specific inputs included seasonal performance factor threshold trajectories under China GB 21455-2019 revisions and India's BIS star-labeling adoption curves.
Stress conditions across copper and rare-earth concentrate pricing, refrigerant supply disruption scenarios, and grid electrification pace in rural Vietnam were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory compliance timelines and technology substitution elasticity. Material shifts in China dual carbon goal acceleration or India PLI scheme expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
United States Home Appliances Market
Home Appliances
Japan Home Appliances Market
Home Appliances
India Major Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Small Home Appliances Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Sweden Home Appliances Market
Home Appliances
Undercounter Refrigerators Market
Home Appliances
UAE Laundry Appliances Market