
 Canada Home Appliances Market | 2026-2036
Canada Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Home Appliances Market Outlook
Connected appliance architecture is fragmenting as manufacturers embed disparate IoT protocols, cloud platforms, and voice-assistant integrations into once-standard product lines. Samsung Electronics leverages its proprietary SmartThings ecosystem to control device interoperability across kitchens and laundry rooms. LG Electronics anchors its position through in-house production of core compressor and motor technologies. Whirlpool Corporation sustains brand strength in conventional segments while selectively adding Wi-Fi modules to premium SKUs.
Canada home appliances comprise electrically powered machines designed for domestic tasks, typically operating at 120V/60Hz with cold-climate insulation ratings and bilingual safety labeling. Refrigerators dominate product type revenue due to replacement cycles and size upgrades in suburban renovations. Energy-efficient technology captures growing share as provincial rebate programs from BC Hydro and Hydro-Quebec subsidize ENERGY STAR-certified models. Smart appliances and IoT-enabled categories attract early adopters in high-income postal codes, though conventional units still occupy volume leadership in price-sensitive markets.
Health Canada sets electromagnetic emissions and material safety standards through the Radiation Emitting Devices Act, while Natural Resources Canada administers ENERGY STAR certification that gates retail placement. CSA Group standards govern electrical safety and fire risk, creating compliance costs that favor scaled manufacturers over import-only distributors. Stakeholders must weigh whether to prioritize connected-product R&D against the persistent profitability of replacement-driven conventional sales in secondary Canadian markets.
Market Dynamics
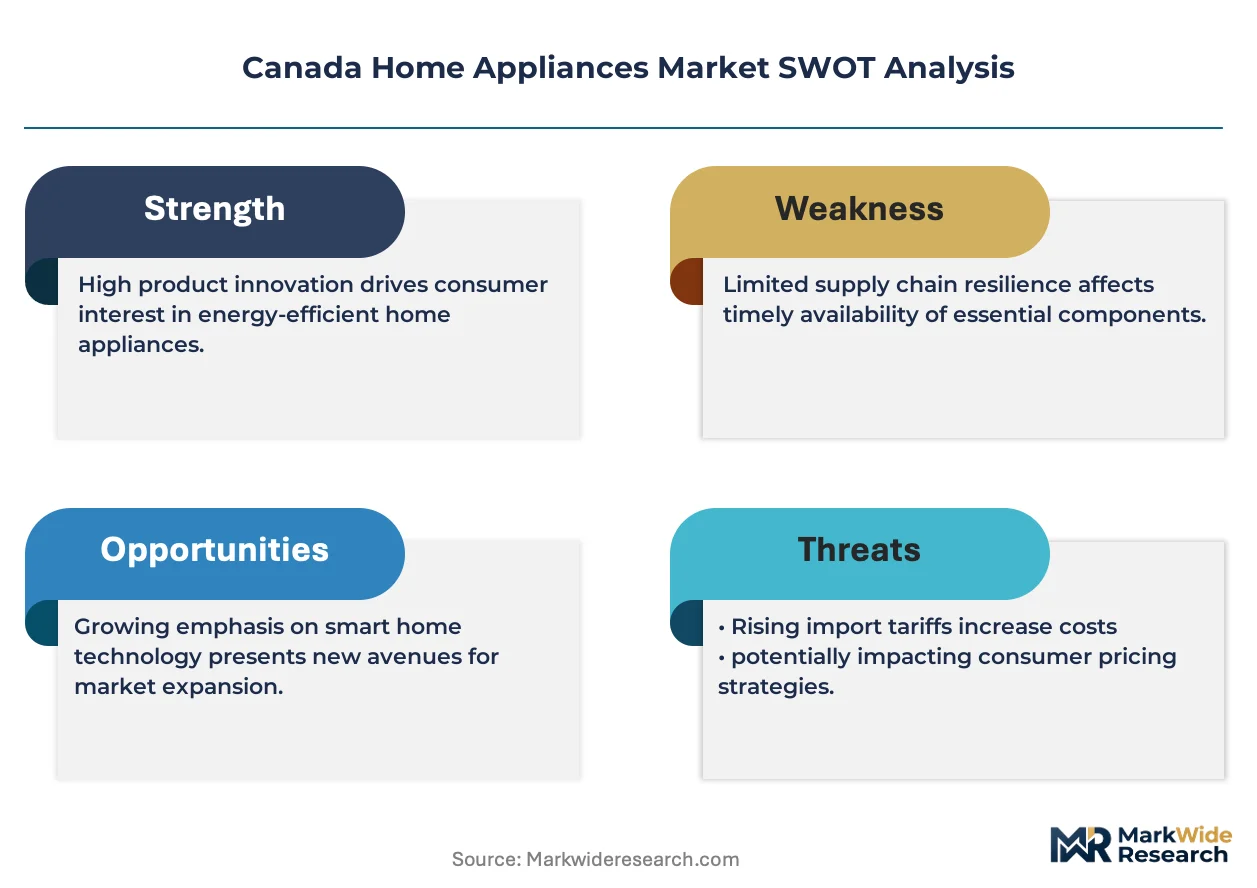
Natural Resources Canada's ENERGY STAR certification gates retail placement while provincial rebate programs from BC Hydro and Hydro-Quebec subsidize certified models, compressing margins for non-compliant inventory and forcing manufacturers to reconfigure product portfolios around efficiency benchmarks.
Growth Catalysts
- BC Hydro CleanBC Appliance Rebates:British Columbia's efficiency incentive program accelerates replacement cycles for refrigerators and heat pumps in single-family suburban renovations.
- Heat pump technology:Cold-climate rated air-source heat pumps displace fossil fuel heating in Atlantic Canada and rural Quebec, driving bundled appliance purchases.
- Toronto-Vancouver condominium pipeline:Urban densification creates demand for compact, stackable laundry and slim-profile refrigeration formats.
Market Restraints
- CSA Group certification timelines:Electrical safety testing and bilingual labeling requirements add 4-8 months to product launch schedules for import-only distributors.
- Steel and copper price volatility:Compressor housings and motor windings face input cost swings that manufacturers struggle to pass through in price-sensitive segments.
- Smart appliance protocol fragmentation:Incompatible IoT standards between proprietary ecosystems create buyer hesitation and elevate support costs for retailers.
Strategic Opportunities
- Atlantic Canada heat pump penetration:Nova Scotia and New Brunswick show underpenetrated electrification rates relative to national targets, creating white space for cold-climate rated systems.
- Hydro-Quebec dual-fuel incentives:The provincial utility's subsidy framework for hybrid heating systems opens bundled sales channels for HVAC-appliance combinations.
- Voice-assistant convergence with energy management:Integration of Alexa and Google Home with smart thermostats and appliances enables utility-controlled demand response programs.
Industry Challenges
- Refrigerant technician certification:Health Canada's PMRA requirements for handling hydrofluorocarbon alternatives create skilled labor bottlenecks in service networks.
- Legacy inventory obsolescence:Stranded conventional appliances face markdown pressure as efficiency standards tighten, compressing working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Home Appliances Market |
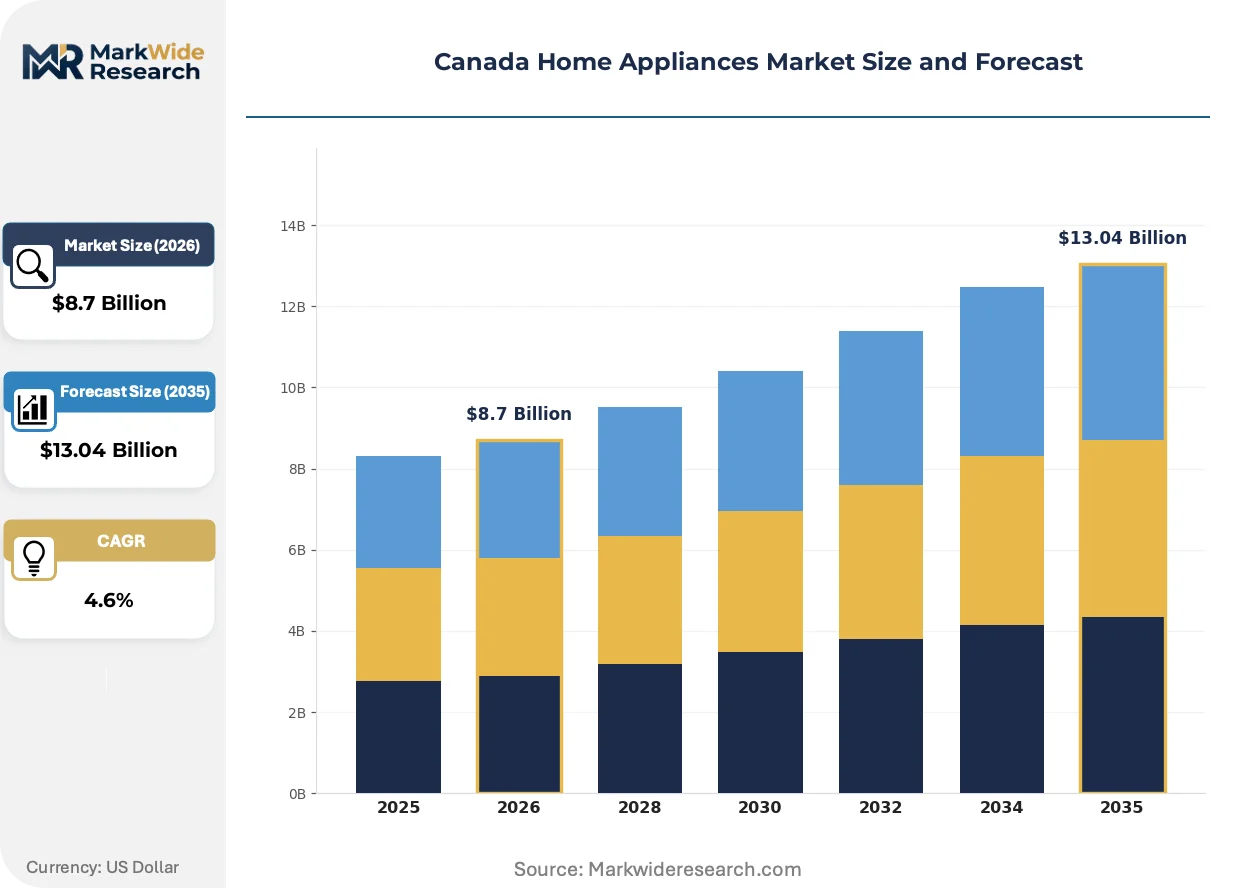
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers End User: Households, Restaurants, Hotels, Retail Stores Technology: Smart Appliances, Energy-Efficient, Conventional, IoT-Enabled Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Whirlpool Corporation, Samsung Electronics, LG Electronics, Electrolux Group, Haier Group, Panasonic Holdings Corporation, Robert Bosch GmbH, Midea Group, AO Smith Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Home Appliances Market Strategic Shifts
Digital control systems are virtualizing mechanical functions across refrigeration and laundry equipment, while provincial efficiency mandates and shifting urban housing formats reshape product specifications and distribution priorities.
Variable-speed compressor technology is virtualizing traditional on-off cooling cycles in residential refrigerators. Calgary and Edmonton households with solar installations adopt inverter-driven models at elevated rates. This virtualization enables granular energy consumption tracking and utility-integrated demand response participation.
Natural Resources Canada's ENERGY STAR Most Efficient designation tightens eligibility thresholds annually. Retailers face delisting risk for SKUs failing updated benchmarks. Premium refrigeration and dishwasher segments respond fastest, with manufacturers accelerating inverter motor and heat pump dryer introductions.
Appliance-as-a-service models emerge in Toronto's rental condominium market. Property management firms bundle washer-dryer subscriptions with tenant leases, displacing traditional retail ownership. This procurement pattern concentrates most visibly in purpose-built rental towers developed by institutional landlords.
Canada Home Appliances Market Segmentation
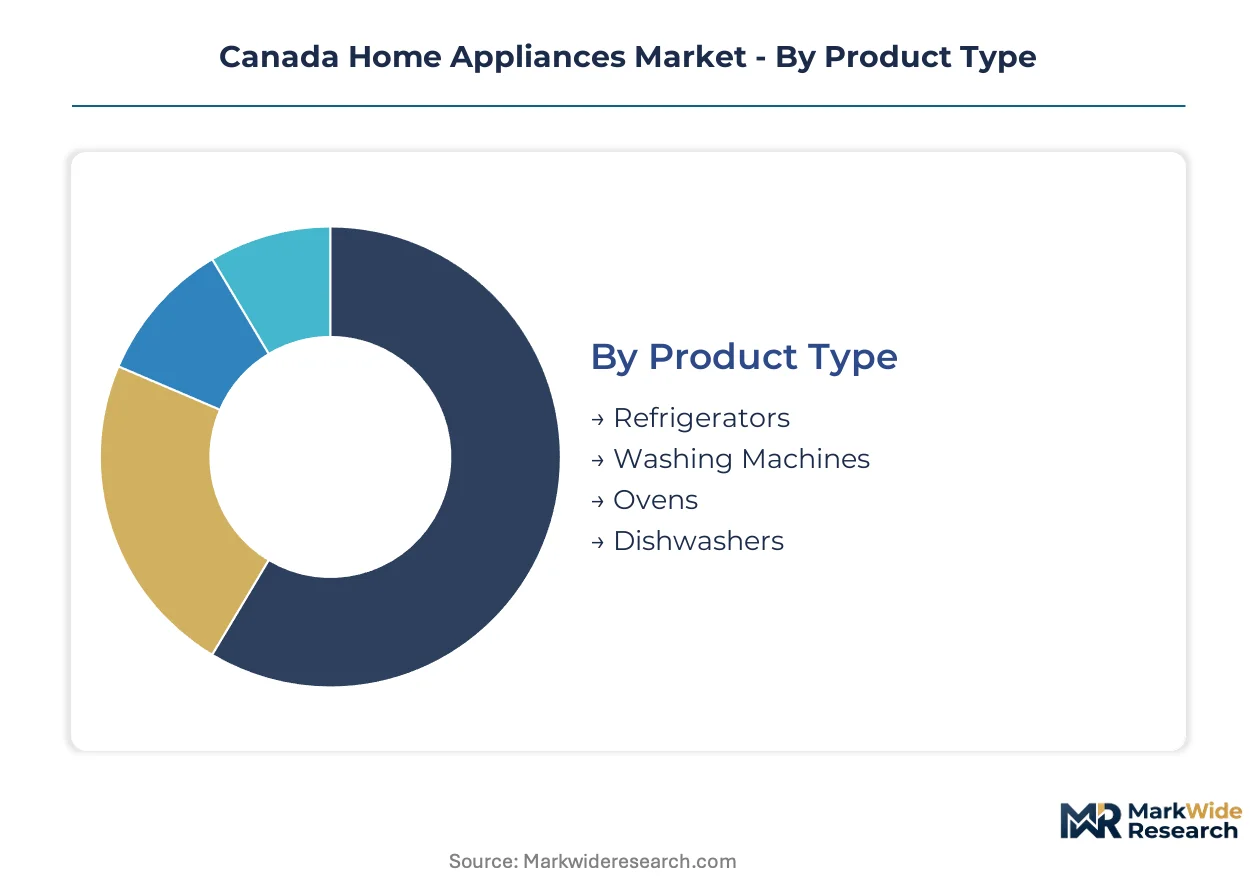
Segmentation in the Canada Home Appliances Market reveals how regulatory pressure, housing formats, and procurement patterns split demand across incompatible product specifications. Manufacturers must configure portfolios around ENERGY STAR tiers, smart connectivity levels, and channel-specific margin structures.
Product Type:
The use-case spectrum spans food preservation, fabric care, cooking, and automated cleaning — each carrying distinct replacement cycles and efficiency upgrade potential.
- Refrigerators:Cold-climate insulation ratings and variable-speed compressor technology define premium tiers. Demand concentrates in suburban renovation markets across Ontario and British Columbia, where size upgrades and ENERGY STAR rebates accelerate replacement cycles.
- Washing Machines:Front-load configurations with heat pump drying dominate condominium installations in Toronto and Vancouver. Stackable formats address space constraints in high-density rental towers.
- Ovens:Electric and induction models gain share in Quebec and British Columbia as provinces restrict new natural gas hookups.
- Dishwashers:Quiet-operation ratings and water-efficiency certifications drive differentiation in open-concept kitchen renovations.
The dominant share belongs to Refrigerators, while Washing Machines are closing the gap fastest.
End User:
Cost tier stratification separates volume-driven residential replacement from commercial installations demanding durability certifications and service network coverage.
- Households:Owner-occupied single-family homes in Calgary, Edmonton, and Ottawa suburbs drive premium appliance bundles during kitchen renovations. Rental condominium markets in Toronto increasingly favor appliance-as-a-service procurement.
- Restaurants:Commercial-grade refrigeration and cooking equipment require NSF/ANSI sanitation certifications and 240V three-phase power configurations.
- Hotels:Procurement concentrates through hospitality supply contractors, with noise ratings and energy monitoring capabilities as key selection criteria.
- Retail Stores:Display refrigeration and food service equipment for grocery and convenience channels prioritize reliability over efficiency premiums.
Households command the volume base, though Hotels are expanding procurement fastest as Atlantic Canada tourism infrastructure upgrades.
Technology:
Application maturity separates established efficiency platforms from emerging connectivity architectures still seeking interoperability standards.
- Smart Appliances:Wi-Fi-enabled refrigeration and laundry equipment with voice-assistant integration concentrate in Alberta's tech-forward households with solar installations.
- Energy-Efficient:Inverter motors and heat pump dryers qualify for provincial rebate programs from BC Hydro and Hydro-Quebec, gating retail placement.
- Conventional:Mechanical control systems without connectivity modules retain volume leadership in price-sensitive secondary markets and rural postal codes.
- IoT-Enabled:Utility-integrated demand response participation requires smart meter compatibility currently limited to Ontario and British Columbia pilot programs.
Energy-Efficient technology holds the installed base advantage, yet Smart Appliances are gaining share fastest among new construction and renovation projects.
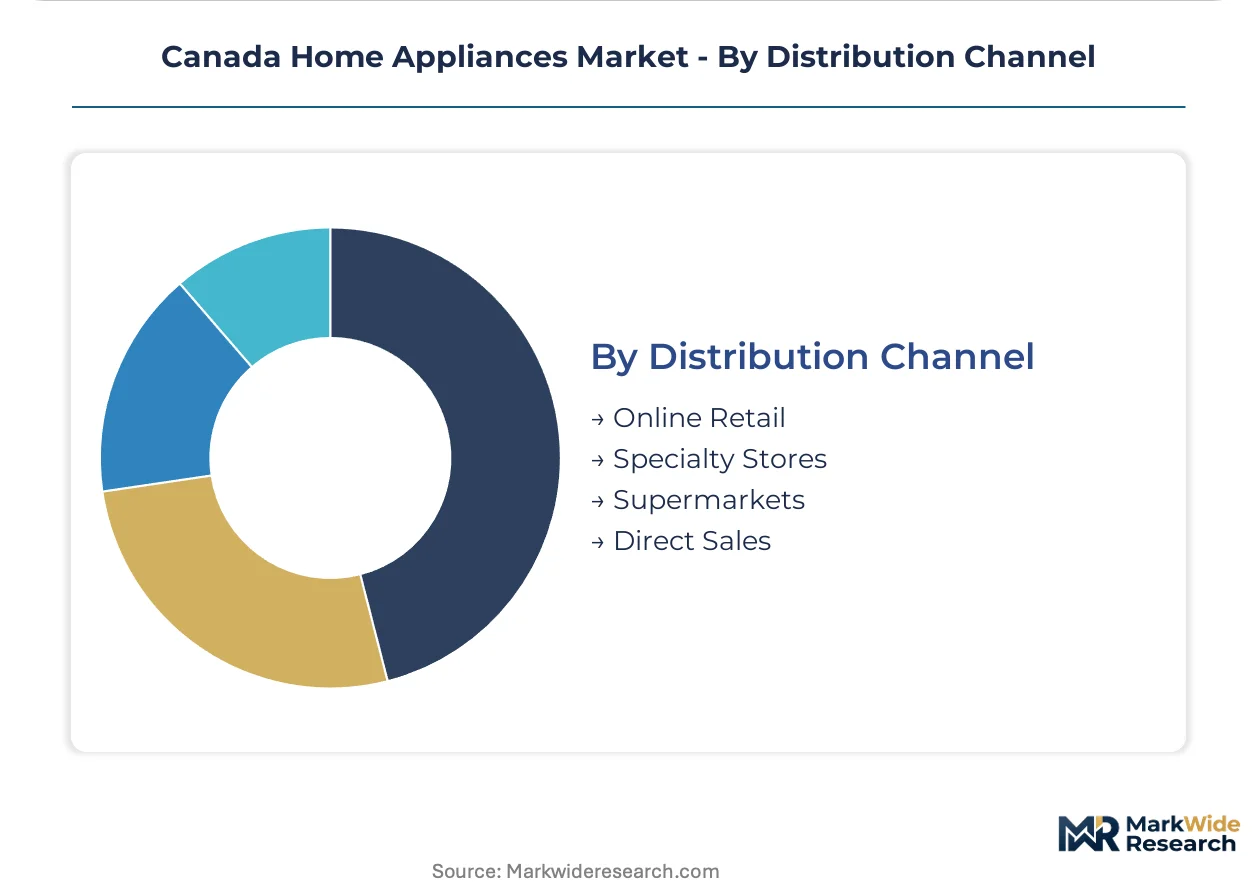
Distribution Channel:
Customer type and purchase urgency dictate channel selection, with big-ticket items favoring tactile evaluation while replacement cycles enable digital procurement.
- Online Retail:Major appliances through e-commerce platforms grow in secondary markets where specialty store coverage is sparse. Delivery logistics and installation coordination remain friction points.
- Specialty Stores:Independent dealers and national chains like Home Hardware provide in-person consultation for kitchen renovation projects. Staff technical knowledge influences premium-tier conversion rates.
- Supermarkets:Mass merchandisers stock compact refrigeration and countertop appliances, with seasonal promotions driving impulse purchases.
- Direct Sales:Builder programs and property management contracts bypass retail markup for multi-unit residential developments in Vancouver and Toronto.
Specialty Stores retain the revenue concentration, while Direct Sales are expanding most quickly through institutional landlord procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Owner-occupied suburban households in Ontario and Quebec drive replacement cycles for premium refrigeration and laundry bundles. Rental condominium markets in Toronto and Vancouver shift procurement toward appliance-as-a-service models. Atlantic Canada's electrification mandates accelerate heat pump penetration in provinces lagging national efficiency targets.
Ontario
Toronto's condominium pipeline and Ottawa's suburban renovation market sustain demand for compact, stackable laundry formats. The Independent Electricity System Operator's demand response programs incentivize smart appliance adoption in households with smart meter installations. Kitchener-Waterloo tech workers anchor early adoption of Wi-Fi-enabled refrigeration with voice-assistant integration.
Quebec
Hydro-Québec's dual-fuel subsidy framework accelerates bundled HVAC-appliance purchases in Montreal's single-family suburbs. The province's natural gas hookup restrictions for new construction shift cooking appliance demand toward induction models. Quebec City's historic district renovations prioritize quiet-operation dishwashers for open-concept kitchen conversions.
British Columbia
BC Hydro's CleanBC appliance rebates compress replacement cycles for ENERGY STAR-certified refrigerators in Vancouver and Victoria. The province's cold-climate heat pump incentives displace fossil fuel heating in Kelowna's suburban developments. Richmond's high-density rental towers concentrate demand for slim-profile refrigeration and compact laundry systems.
Alberta
Calgary and Edmonton households with solar installations adopt inverter-driven appliances at elevated rates. The province's tech-forward demographic concentrates smart appliance purchases in suburban neighborhoods with fiber broadband penetration. Natural Resources Canada's ENERGY STAR Most Efficient designation gates retail placement for premium SKUs in Edmonton appliance showrooms.
Atlantic Canada
Nova Scotia and New Brunswick show underpenetrated heat pump adoption relative to federal electrification targets, creating white space for cold-climate rated systems. Efficiency Nova Scotia's rebate programs accelerate replacement of conventional electric resistance heating in Halifax's aging housing stock. Saint John's commercial tourism upgrades drive hospitality procurement of energy-monitoring refrigeration.
Canada Home Appliances Market Competitive Environment
Channel-controlling players compete with product-specialist players across Canada's fragmented appliance retail environment. The vendor base splits between diversified conglomerates with captive distribution networks and focused manufacturers reliant on third-party retail partnerships. Two strategic archetypes dominate: ecosystem-integrated technology firms leveraging proprietary IoT platforms, and efficiency-focused incumbents optimizing around ENERGY STAR certification thresholds. Competitive moves center on provincial rebate program alignment and builder-direct procurement channel capture.
Among North American-headquartered conglomerates, Whirlpool Corporation occupies a position representing conventional segment strength with selective smart connectivity additions. Samsung Electronics and LG Electronics anchor the ecosystem-integrated tier, exemplifying proprietary platform strategies that control device interoperability across kitchen and laundry applications. These three firms represent contrasting archetypes: the diversified incumbent optimizing replacement-cycle profitability, the Korean technology conglomerate leveraging vertical manufacturing integration, and the ecosystem platform builder capturing early-adopter households in Alberta's solar-equipped suburbs.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics |
| LG Electronics |
| Electrolux Group |
| Haier Group |
| Panasonic Holdings Corporation |
| Robert Bosch GmbH |
| Midea Group |
| AO Smith Corporation |
| Others |
Value Chain & Pricing Dynamics
Guangdong Province's compressor manufacturing clusters anchor global refrigeration component supply, with capacity utilization swings directly transmitting to OEM pricing power in Canadian retail channels. Natural Resources Canada's ENERGY STAR certification gates create tiered procurement thresholds that amplify these upstream cost movements.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate compressor and motor sourcing agreements between Asian suppliers and North American OEMs. Three-tier pricing structure across premium ENERGY STAR Most Efficient, standard certified, and uncertified economy levels reflects certification grade and after-sales service bundling. Pricing pressure stems from provincial rebate programs compressing margins on non-compliant inventory. Price-sensitive rural households in Atlantic Canada resist premium tiering, while Alberta solar-equipped suburbs absorb connected-product premiums.
Supply Chain Analysis
Export control restrictions on advanced semiconductor components for inverter motor controllers constrain flows from Taiwan and South Korea to Chinese final assembly plants. China's dominance in rare earth magnet production for high-efficiency motors, Thailand's compressor component machining, and Mexico's proximity assembly for USMCA compliance define geographic concentration. Steel and copper price volatility creates raw material cost instability. Distribution runs through Vancouver and Toronto port clusters into big-box retail and builder-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's home appliances market rewards service-attach strategies, with appliance-as-a-service subscription revenue in Toronto's rental towers expanding faster than hardware unit sales. Extended warranty and predictive maintenance contracts capture recurring value from installed smart appliance bases.
For Market Incumbents: Harden ENERGY STAR certification pipelines against Natural Resources Canada's tightening Most Efficient thresholds by accelerating inverter motor R&D partnerships. Consolidate builder-direct procurement relationships in Vancouver and Toronto condominium developments to lock out import-only distributors facing CSA Group certification delays. Vertical integration into compressor controller firmware protects margin structure against semiconductor supply volatility. For New Entrants and Emerging Players: Atlantic Canada's underpenetrated heat pump adoption relative to federal electrification targets represents the most penetrable entry point for cold-climate rated HVAC-appliance bundles. Nova Scotia and New Brunswick utility rebate programs lack incumbent saturation. Direct sales to institutional landlords in Halifax's purpose-built rental pipeline bypass retail channel establishment costs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with captive inverter motor or heat pump dryer technology over brand-dependent assemblers. Long-term viability rests on utility-integrated demand response capability and provincial rebate program alignment. Watch for Natural Resources Canada announcements on smart meter compatibility expansion as inflection signal for IoT-enabled category acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Acceleration | Natural Resources Canada's tightening ENERGY STAR thresholds reward early compliance investment with retail placement security. |
| Builder-Direct Channel Capture | Toronto and Vancouver institutional landlords consolidate procurement power through multi-unit appliance-as-a-service contracts. |
| Voice-Assistant Platform Integration | Alexa and Google Home compatibility enables Hydro-Québec and BC Hydro demand response program participation. |
| Cold-Climate Heat Pump Development | Atlantic Canada electrification mandates create white space for systems rated below -25°C operation. |
| Aftermarket Service Network Expansion | Health Canada PMRA refrigerant certification requirements create skilled technician scarcity that captive service networks exploit. |
Study Parameters
Initial hypotheses were tested against primary input from appliance manufacturer product strategy directors, provincial utility rebate program administrators, retail category buyers, and HVAC contractor network managers and refined through secondary validation. Primary interviews combined with Natural Resources Canada ENERGY STAR certification databases, CSA Group safety standard filings, BC Hydro and Hydro-Québec incentive program disclosures, and customs import records. Bottom-up unit shipment modeling and top-down expenditure estimates were triangulated to anchor market sizing.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology tier, and distribution channel, with provincial regulatory cluster as the industry-specific overlay. CAGRs were derived from replacement cycle analysis, housing formation projections, and efficiency standard adoption curves. Smart meter penetration rates and solar installation growth in Alberta informed connected-product diffusion assumptions.
Practitioners should monitor Health Canada refrigerant policy shifts and Natural Resources Canada ENERGY STAR threshold revisions for early signals of category disruption. Forecasts reflect assumptions on provincial rebate program continuity and steel-copper price stabilization. Material shifts in CSA Group certification timelines or USMCA rules-of-origin enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Range Hood Market
Home Appliances
Saudi Arabia Small Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
China Small Home Appliances Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
White Goods Market