
 Induction Stove Market | 2026-2036
Induction Stove Market Size, Share, and Industry Trends Forecast 2026-2036
Induction Stove Market Analysis
Software-enabled energy monitoring and subscription-based maintenance programs is consolidating what manufacturers capture from each installation. Robert Bosch GmbH leverages its service network to anchor recurring revenue in European commercial kitchens. Samsung Electronics competes through smart-home integration that extends control interfaces beyond the appliance itself. Miele Group specializes in premium built-in configurations that dominate architect-specified residential projects.
An induction stove converts electrical energy into heat through electromagnetic induction between a copper coil and ferromagnetic cookware, achieving thermal efficiencies above 90% while eliminating open flames. Built-in and freestanding product types lead residential sales, though portable units are capturing renovation-averse renters and outdoor catering operators. Electromagnetic and induction cooktop technologies concentrate the largest installed base, while hybrid systems that combine induction with radiant elements are gaining traction among restaurants seeking operational redundancy.
EU F-Gas Regulation and CE marking requirements shape product design and market access across Europe, while China's GB standards and MIIT efficiency mandates govern domestic manufacturing and import eligibility. The US Department of Energy and EPA ENERGY STAR specifications influence North American procurement patterns for residential and commercial buyers. Stakeholders must monitor how efficiency standard tightening and building electrification mandates alter replacement timing and channel economics across major economies.
Market Dynamics
Building electrification mandates and copper supply concentration are compressing procurement timelines while forcing manufacturers to redesign coil assemblies for thinner gauge windings. The EU F-Gas Regulation and China's MIIT efficiency directives are accelerating replacement cycles across residential and commercial channels.
Growth Catalysts
- EU Green Deal building mandates:France, Germany, and the Netherlands are prohibiting new gas connections in residential construction, forcing developers to specify induction systems in architect drawings.
- MIIT manufacturing directives:China's efficiency tiering system creates automatic obsolescence for Class 2 and 3 appliances, shortening domestic replacement intervals to four-year cycles.
- Copper coil thermal optimization:Advances in litz wire winding patterns are pushing thermal efficiency above 92 percent in premium built-in configurations.
Market Restraints
- Ferromagnetic cookware dependency:The technology requires cast iron or magnetic stainless steel vessels, excluding aluminum and copper cookware owners from adoption without replacement investment.
- Copper supply concentration:Chile and Peru account for over 40 percent of global refined copper output, exposing coil manufacturers to concentrate price volatility and export restriction risk.
- Electromagnetic interference constraints:FCC Part 18 and CE EMC Directive emission limits add certification cost and design complexity for high-wattage commercial units.
Strategic Opportunities
- India residential electrification:Ujjwala scheme subsidies and CEA grid reliability improvements are creating first-time appliance demand in tier-2 and tier-3 cities previously dependent on LPG cylinders.
- Outdoor catering portability:Battery-powered induction systems are capturing food truck operators and temporary event vendors seeking flameless cooking compliance in municipal fire codes.
- Software-enabled maintenance:IoT coil health monitoring is enabling subscription-based service contracts that extend manufacturer revenue beyond the initial hardware sale.
Industry Challenges
- Electromagnetic compatibility certification:Multi-jurisdiction testing for FCC, CE, and GB standards requires 14-18 month pre-market timelines that compress product refresh windows.
- Skilled winding technician scarcity:Precision coil assembly demands specialized litz wire handling expertise that vocational programs have not scaled to match production expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Induction Stove Market |
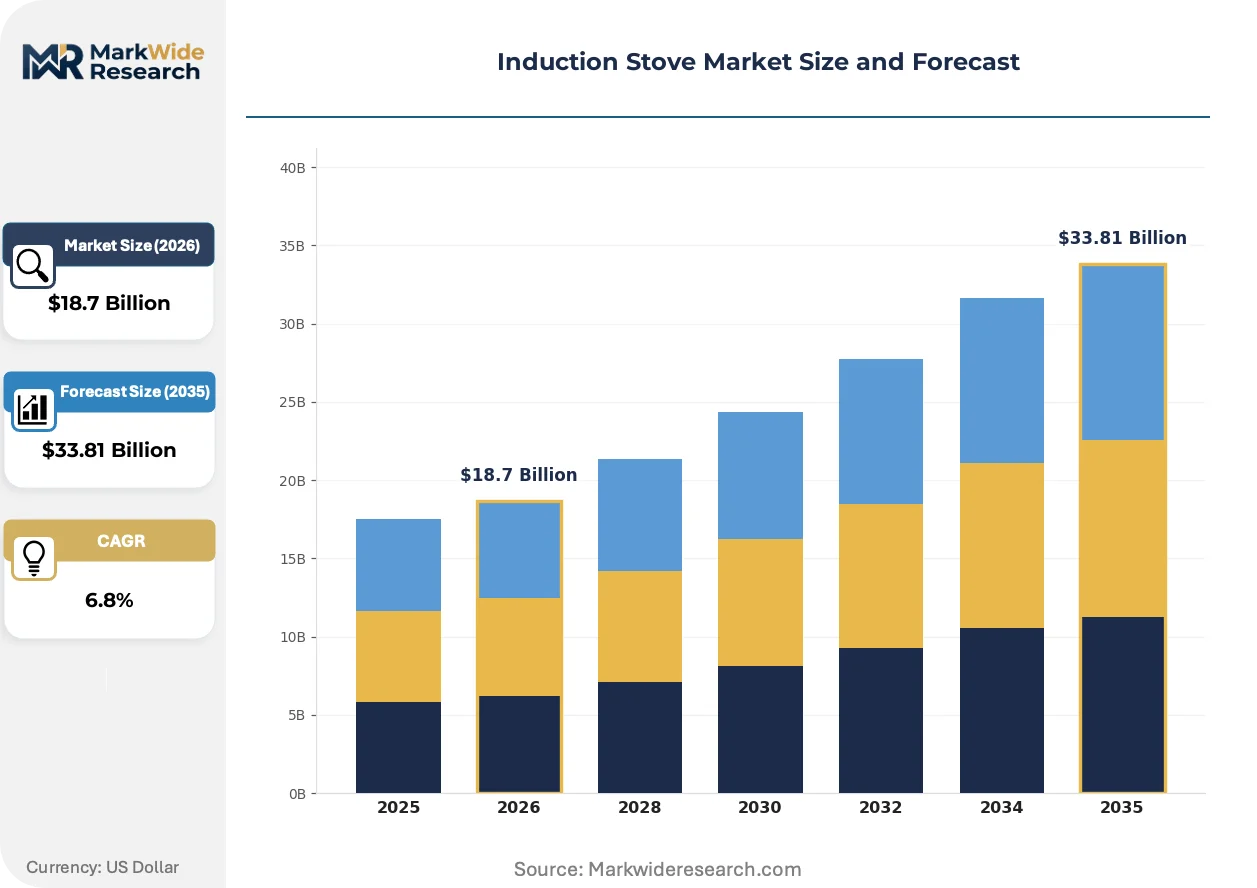
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-In, Freestanding, Portable, Commercial End User: Residential, Restaurants, Cafés, Catering Services Technology: Electromagnetic, Induction Cooktop, Induction Range, Hybrid Application: Cooking, Heating, Food Preparation, Laboratory |
| Companies Covered | Whirlpool Corporation, LG Electronics, Panasonic Corporation, Samsung Electronics, Robert Bosch GmbH, Electrolux Group, Koninklijke Philips N.V., SMEG S.p.A., Miele Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Induction Stove Market Emerging Trajectories
Intelligent power management and modular coil architectures are transforming how manufacturers differentiate across price tiers. Software-defined thermal profiles now enable single appliances to serve multiple cooking modalities without hardware variation.
Adaptive resonant frequency control is automating real-time impedance matching between coil and cookware, eliminating manual power adjustment. Commercial kitchen operators in Germany and South Korea are deploying these systems to reduce energy waste during low-load periods. The technology is automating load detection previously requiring chef intervention, compressing training requirements for high-turnover foodservice staff.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in cooling appliances while tightening embodied carbon disclosure requirements under CSRD. Induction stove manufacturers must now document full lifecycle emissions from copper mining through end-of-life recycling. Premium built-in suppliers are responding with blockchain-tracked supply chain certification to satisfy architect-specified green building standards.
Direct-to-installer procurement is displacing traditional distributor networks in North American commercial channels. Restaurant groups in Texas and California are negotiating fleet pricing directly with manufacturers, bypassing the two-step distribution that historically captured 18-22 percent margin. Foodservice equipment leasing companies are capturing this disintermediation value by bundling installation, maintenance, and upgrade rights into single contracts.
Induction Stove Market Segmentation
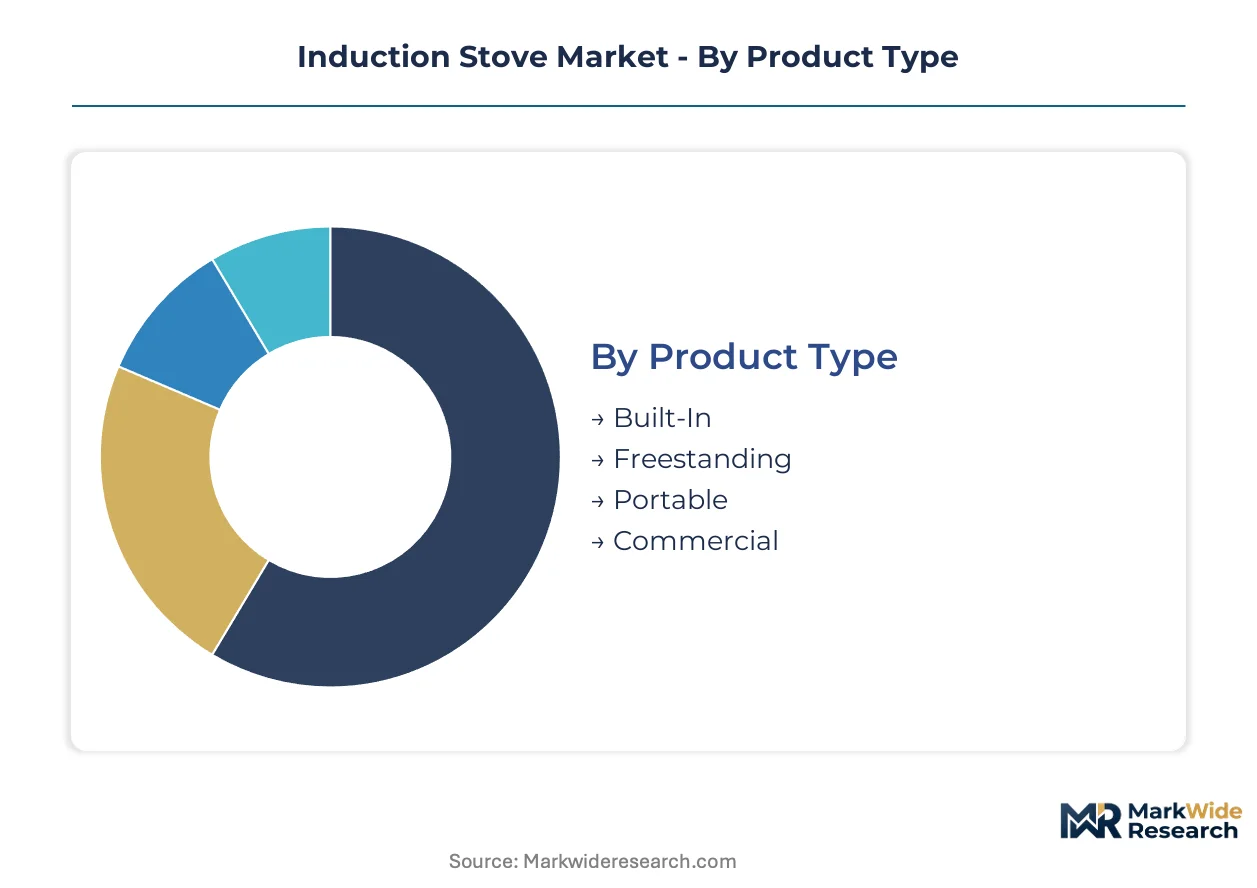
Segmentation in the induction stove market determines procurement economics, installation complexity, and service revenue potential. Manufacturers configure coil architectures, control systems, and thermal management differently across each category to match capital budgets and operational intensity.
Product Type:
Built-in configurations demand the highest upfront capital commitment, requiring custom countertop fabrication and electrical infrastructure upgrades.
- Built-In:Flush-mounted units integrate with stone or composite countertops, demanding dedicated 240V circuits and professional installation. Urban apartment developers in France and the Netherlands specify these under EU Green Deal mandates prohibiting gas connections.
- Freestanding:Self-contained units with integrated ovens dominate replacement cycles in existing residential kitchens. German and Italian manufacturers optimize these for retrofit compatibility with legacy electrical panels.
- Portable:Compact single-burner units plug into standard outlets, serving renovation-averse renters and outdoor operators.
- Commercial:Heavy-gauge stainless steel housings withstand continuous operation in high-throughput kitchens.
Built-in systems absorb the bulk of installed capacity in new European construction; portable units are expanding most quickly among food truck operators and temporary event vendors.
End User:
Operational intensity and duty cycles vary dramatically across end-use categories, dictating warranty terms and service contract structures.
- Residential:Intermittent daily use drives demand for intuitive controls and self-cleaning surfaces. Chinese households under MIIT efficiency directives replace Class 2 and 3 appliances on compressed four-year cycles.
- Restaurants:Continuous operation requires redundant coil configurations and rapid thermal recovery. Operators in South Korea deploy adaptive resonant frequency control to automate load detection and reduce training requirements.
- Cafés:Moderate throughput prioritizes compact footprints and rapid boil times for beverage preparation.
- Catering Services:Mobile deployment demands battery-powered flameless systems compliant with municipal fire codes at temporary events.
Residential channels anchor volume shipments; catering services are climbing the fastest as outdoor event formats proliferate.
Technology:
Coil architecture and power electronics sophistication determine thermal efficiency ceilings and electromagnetic compatibility certification burden.
- Electromagnetic:Copper coil assemblies with ferrite backing plates achieve baseline efficiency above 85 percent. FCC Part 18 and CE EMC Directive testing adds 14-18 month pre-market timelines for high-wattage commercial variants.
- Induction Cooktop:Modular surface configurations enable zoneless cooking across entire countertop sections. German commercial kitchen operators favor these for flexible station arrangements during service peaks.
- Induction Range:Combined cooktop and oven units consolidate appliance counts in space-constrained installations.
- Hybrid:Dual-mode systems pair induction coils with radiant elements, providing operational redundancy for restaurants requiring backup heating during coil maintenance.
Electromagnetic systems dominate the installed base; hybrid configurations are gaining share fastest among risk-averse foodservice operators.
Application:
Precision requirements and thermal control granularity determine sensor density and software sophistication across use cases.
- Cooking:Sauté, simmer, and sear modalities demand rapid power modulation across 12-15 discrete levels. Samsung Electronics extends control interfaces through smart-home integration beyond the appliance itself.
- Heating:Holding and warming applications prioritize temperature stability over response speed. Robert Bosch GmbH anchors recurring revenue through service network coverage of these lower-intensity installations.
- Food Preparation:Precise temperature control for emulsions and sugar work requires dedicated low-temperature zones.
- Laboratory:Cleanroom-compatible sealed surfaces and chemical-resistant coatings serve pharmaceutical and materials science applications.
Cooking applications command the majority of unit shipments; laboratory segments are expanding most quickly as cleanroom standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Pudong district anchors the highest concentration of induction stove manufacturing capacity, with Guangdong and Zhejiang provinces housing the majority of coil winding and power electronics assembly operations serving both domestic and export demand.
China
Urban apartment developers in Beijing and Shenzhen specify built-in units under MIIT efficiency directives that mandate Class 1 appliances in new construction. GB standards and NMPA certification requirements compress replacement cycles to four-year intervals. The Yangtze River Delta cluster around Shanghai dominates copper coil production and ferrite backing plate fabrication.
Germany
Commercial kitchen operators in Munich and Hamburg deploy adaptive resonant frequency control systems to automate load detection. The EU F-Gas Regulation and CE marking requirements shape product design for export eligibility. Baden-Württemberg's industrial corridor hosts precision winding equipment manufacturers supplying coil assembly lines across Europe.
United States
Restaurant groups in Texas and California negotiate fleet pricing directly with manufacturers, bypassing traditional distribution channels. EPA ENERGY STAR specifications and Department of Energy efficiency mandates influence procurement patterns for residential and commercial buyers. The Pacific Northwest sees concentrated adoption of portable units among outdoor catering operators.
France
Architect-specified residential projects in Paris and Lyon dominate premium built-in configuration demand under EU Green Deal prohibitions on new gas connections. The country's national energy regulator enforces building electrification mandates that force developer specification of induction systems. Île-de-France hosts the largest concentration of foodservice equipment leasing companies bundling installation and maintenance contracts.
India
Tier-2 and tier-3 cities including Pune and Ahmedabad generate first-time appliance demand as Ujjwala scheme subsidies and CEA grid reliability improvements displace LPG cylinder dependence. BIS certification requirements govern domestic manufacturing and import eligibility. Maharashtra's industrial belt is scaling assembly operations for battery-powered portable units targeting food truck operators.
Induction Stove Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the induction stove market, with integrated manufacturers controlling coil winding and power electronics assembly while specialist brands outsource fabrication to contract foundries. The vendor base clusters around three strategic archetypes: diversified home appliance conglomerates, premium built-in specialists, and commercial foodservice equipment providers. Consolidation pressure is accelerating through direct-to-installer procurement displacement and fleet pricing negotiations that compress distributor margins. Geographic expansion and technology licensing dominate competitive moves as manufacturers seek to bypass traditional channel economics.
Among diversified appliance conglomerates, Whirlpool Corporation and LG Electronics represent scale-driven archetypes with broad residential distribution networks. Robert Bosch GmbH exemplifies the premium-tier specialist position, leveraging service network density to anchor recurring revenue in European commercial installations. Samsung Electronics occupies a position defined by smart-home ecosystem integration, extending control interfaces beyond the appliance itself through proprietary connectivity platforms.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| LG Electronics |
| Panasonic Corporation |
| Samsung Electronics |
| Robert Bosch GmbH |
| Electrolux Group |
| Koninklijke Philips N.V. |
| SMEG S.p.A. |
| Miele Group |
| Others |
Supply Flow & Price Mechanics
Copper coil assemblies trace from Chilean and Peruvian mining operations through Yangtze River Delta winding facilities to three-tier pricing structures across premium, standard, and economy levels in end-user markets. Litz wire thermal optimization and ferrite backing plate sourcing concentrate manufacturing margins in the upstream tier, while downstream buyers absorb installation complexity premiums for built-in configurations.
Pricing Analysis
Throughput-based uptime guarantees anchor value-based pricing for commercial kitchen operators, with adaptive resonant frequency control systems commanding premiums against baseline electromagnetic units. Price differentiation separates CE-marked Class 1 efficiency tiers from lower-grade imports, while volume fleet negotiations by Texas restaurant groups compress distributor-captured margins. Cost compression in standard-tier freestanding units intensifies as Chinese MIIT directives accelerate four-year replacement cycles. Residential buyers in European urban apartments show lowest price sensitivity for architect-specified built-in systems, whereas India's tier-2 cities exhibit highest sensitivity for first-time portable unit purchases.
Supply Chain Analysis
FCC Part 18 and CE EMC Directive certification gating stretches pre-market timelines to 14-18 months, favoring incumbent manufacturers with established testing relationships over new entrants. Coil winding capacity concentrates in China, Germany, and South Korea, with precision litz wire handling expertise anchored in Baden-Württemberg's industrial corridor. Raw material dependencies span Chilean copper cathode, Chinese ferrite ceramics, and Japanese power electronics components. Single-source vulnerability in copper concentrate exposes manufacturers to export restriction risk from Andean producers. Distribution runs through foodservice equipment leasing companies in France and direct-to-installer channels in North America, bypassing traditional two-step networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around direct-to-installer procurement displacement and fleet pricing negotiations that squeeze distributor margins, forcing sub-scale winding operations toward acquisition or exit.
For Market Incumbents: Lock in coil supply through backward integration into Yangtze River Delta ferrite backing plate fabrication or long-term offtake agreements with Chilean copper producers. Capture service contract anchoring by deploying IoT coil health monitoring across European commercial installations before emerging Asian competitors scale comparable maintenance networks. Defensive priority rests on certifying next-generation adaptive resonant frequency control systems under tightening GB standards before replacement cycle acceleration in China closes window for premium positioning. For New Entrants and Emerging Players: Enter via battery-powered portable configurations targeting India's food truck operators and outdoor catering vendors, where Ujjwala scheme electrification creates first-time appliance demand without incumbent brand loyalty. White-space concentration sits in tier-2 Indian cities and temporary event compliance markets seeking flameless cooking alternatives. Go-to-market leverage emerges through municipal fire code certification partnerships that bypass traditional distributor relationships entirely. For Investors and Strategic Acquirers: MIIT efficiency tier upgrades accelerating to four-year replacement cycles is the leading indicator that coil winding capacity scarcity will concentrate value capture among integrated manufacturers. Long-term viability favors asset-heavy producers with captive ferrite ceramic supply and precision winding technician training pipelines over design-only brands dependent on contract foundries. Acquisition target archetype: mid-tier European commercial equipment providers with CE certification infrastructure and underutilized service network density. Watch for South Korean adaptive control technology licensing deals as signal of competitive inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Ceramics | Captive supply of backing plate material insulates margin from Chinese export quota volatility. |
| Adaptive Resonant Frequency Control Licensing | South Korean automation technology reduces training costs for high-turnover foodservice staff. |
| Direct-to-Installer Channel Establishment | Texas restaurant fleet pricing negotiations bypass 18-22 percent distributor margin capture. |
| IoT-Enabled Service Contract Bundling | Robert Bosch GmbH anchors recurring revenue beyond hardware sale through coil health monitoring. |
| Battery-Powered Portable Certification | Maharashtra assembly operations target Indian food truck compliance with municipal fire codes. |
Methodological Framework
Multi-period observation of MIIT efficiency tier migrations, EU F-Gas Regulation implementation timelines, and copper concentrate export patterns anchored the trend analysis, supplemented by interviews with commercial kitchen operators, precision winding technicians, foodservice equipment leasing executives, and architect-specification consultants. Secondary validation drew from customs trade databases, SEC 10-K filings of listed appliance manufacturers, EPA ENERGY STAR certification records, and NMPA registration filings. Bottom-up coil production capacity estimates triangulated against top-down residential replacement cycle modeling.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework, with built-in, freestanding, and portable configurations each assigned penetration trajectory coefficients. CAGRs derived from regression against historical efficiency standard tightening patterns and building electrification mandate adoption curves. Industry-specific forecast inputs included copper price volatility indices and skilled winding technician graduation rates from German and Chinese vocational programs.
Revisions become necessary when Chilean or Peruvian export restrictions materialize, when FCC Part 18 certification timelines extend beyond 18 months, or when India's CEA grid reliability improvements accelerate faster than Ujjwala subsidy disbursement. Forecasts reflect assumptions about continued EU Green Deal enforcement and MIIT directive compliance without major regulatory rollback. A model refresh is warranted upon material change in copper concentrate supply concentration or breakthrough in aluminum-copper hybrid coil technology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
Electric Corkscrew Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Global Baking Tools Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market