
 Asia Pacific Portable Washing Machine Market | 2026-2036
Asia Pacific Portable Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Portable Washing Machine Market Insights
Stainless steel drum assemblies are rebalancing cost structures as manufacturers substitute heavier cast components with lighter, corrosion-resistant alloys. Haier Group leverages integrated die-casting facilities in Shandong to compress lead times on compact drum housings. Samsung Electronics anchors its premium positioning through direct-drive inverter motor technology that reduces unit depth. Midea Group competes on scale, operating multi-plant capacity across Guangdong and Hefei that feeds price-sensitive Southeast Asian channels.
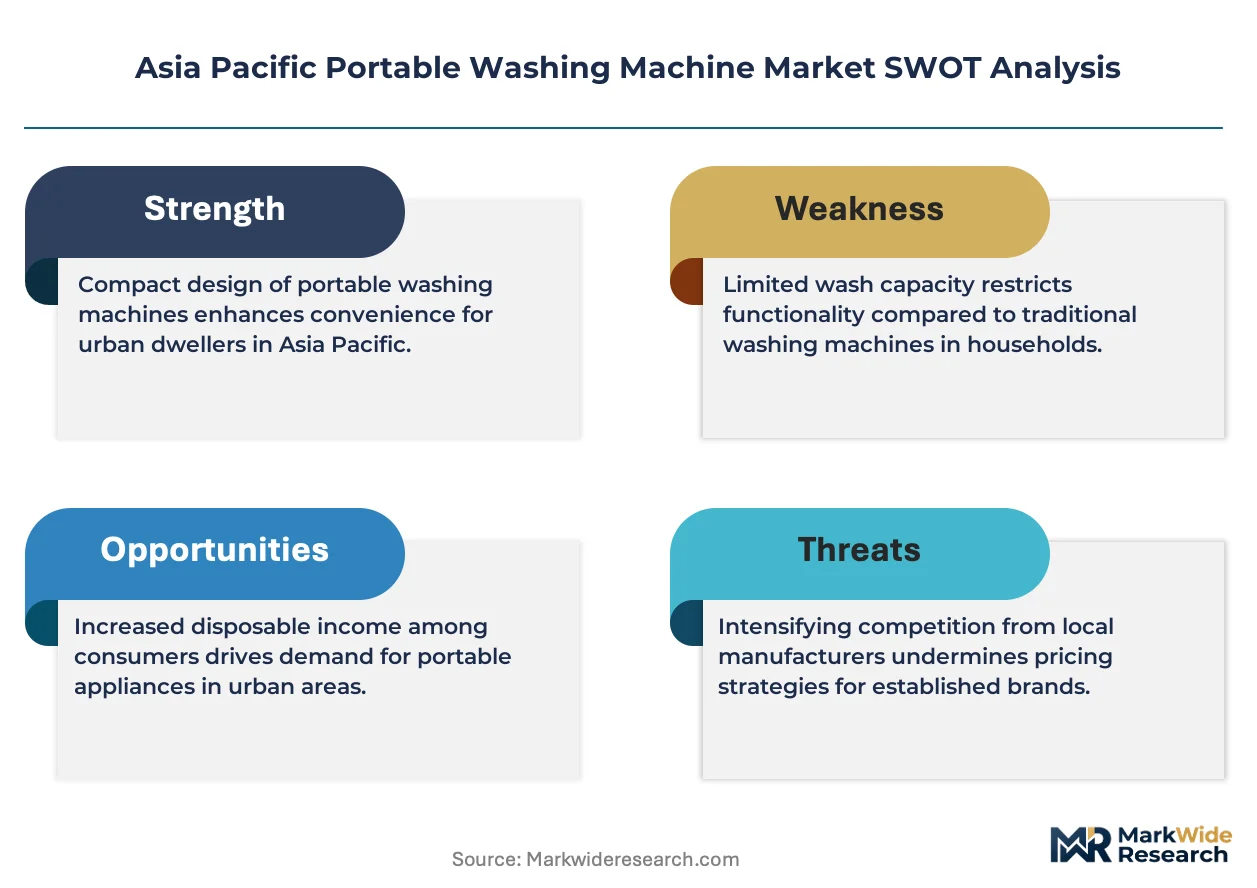
Asia Pacific portable washing machines are self-contained laundry appliances designed for spatially constrained environments, typically measuring under 60 cm in width and operating on standard 220-240V residential supply with water consumption below 50 liters per cycle. Twin tub and semi-automatic configurations retain dominant volume share across India and Indonesia where intermittent power supply and manual water filling remain operational realities. Fully automatic mini units represent the fastest-expanding segment as urban studio apartments proliferate in Ho Chi Minh City and Manila. Energy-efficient technology classifications are capturing margin pools as electricity tariffs climb and BIS, China GB, and Vietnam MOIT labeling schemes intensify compliance differentiation.
BIS mandates under India's Compulsory Registration Scheme enforce minimum performance standards for washing machine energy consumption and water efficiency, compelling redesigns of motor and heating elements. China's GB 12021.4 standard and MIIT circular economy directives are accelerating rare-earth magnet substitution in compressor motors. The EU F-Gas Regulation's extraterritorial influence on refrigerant supply chains indirectly affects heat-pump dryer integration in premium portable combo units. Stakeholders must monitor how India's PLI scheme for white goods components reshapes supplier geography and whether Vietnam's rapid urban rental stock expansion sustains import demand for compact automatic formats.
Market Dynamics
India's BIS energy-labeling mandates are compressing design cycles as manufacturers redesign motor assemblies to meet tightening efficiency thresholds before compulsory enforcement deadlines.
Growth Catalysts
- China GB 12021.4 Standard:China's MIIT circular economy directives accelerate rare-earth magnet substitution in compressor motors, opening procurement flexibility for regional assemblers.
- Studio Apartment Proliferation:Ho Chi Minh City and Manila rental stock expansion sustains import demand for fully automatic mini units under 45 cm depth.
- Heat-Pump Dryer Integration:The EU F-Gas Regulation's extraterritorial influence on refrigerant supply chains creates compliance-driven upgrade cycles in premium portable combo units.
Market Restraints
- Stainless Steel Input Volatility:Drum assembly cost structures fluctuate with nickel alloy pricing, squeezing margin pools on economy-tier twin-tub configurations.
- Shandong Die-Casting Concentration:Integrated housing production clusters in eastern China create single-source vulnerability for compact drum supply.
- Intermittent Power Infrastructure:Manual water-filling requirements persist across Indonesia's outer islands, limiting automatic format penetration.
Strategic Opportunities
- Vietnam Manufacturing Corridors:Rapid urban rental stock expansion in Bac Ninh and Hai Phong industrial zones sustains B2B procurement channels for fleet-deployable compact units.
- India PLI Scheme:White goods component incentives reshape supplier geography toward domestic motor and heating element production.
- Direct-Drive Inverter Convergence:Permanent magnet motor technology merges with IoT-enabled load sensing, enabling predictive maintenance service layers.
Industry Challenges
- BIS Certification Timelines:Compulsory Registration Scheme testing backlogs delay product launches by 4-6 months, compressing seasonal selling windows.
- Skill Gaps in Rare-Earth Motor Assembly:Precision magnet alignment expertise concentrates in Guangdong and Hefei, constraining geographic diversification of production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Portable Washing Machine Market |
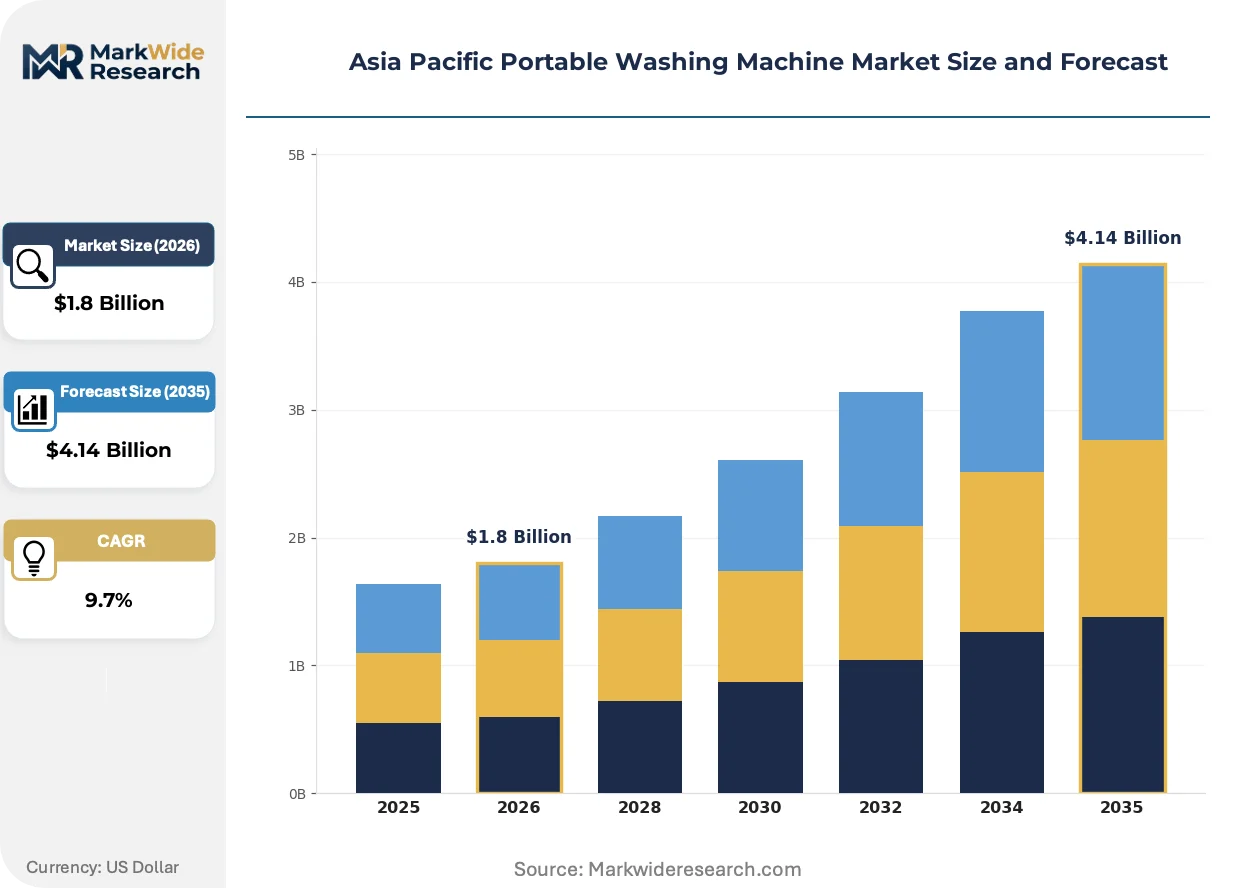
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
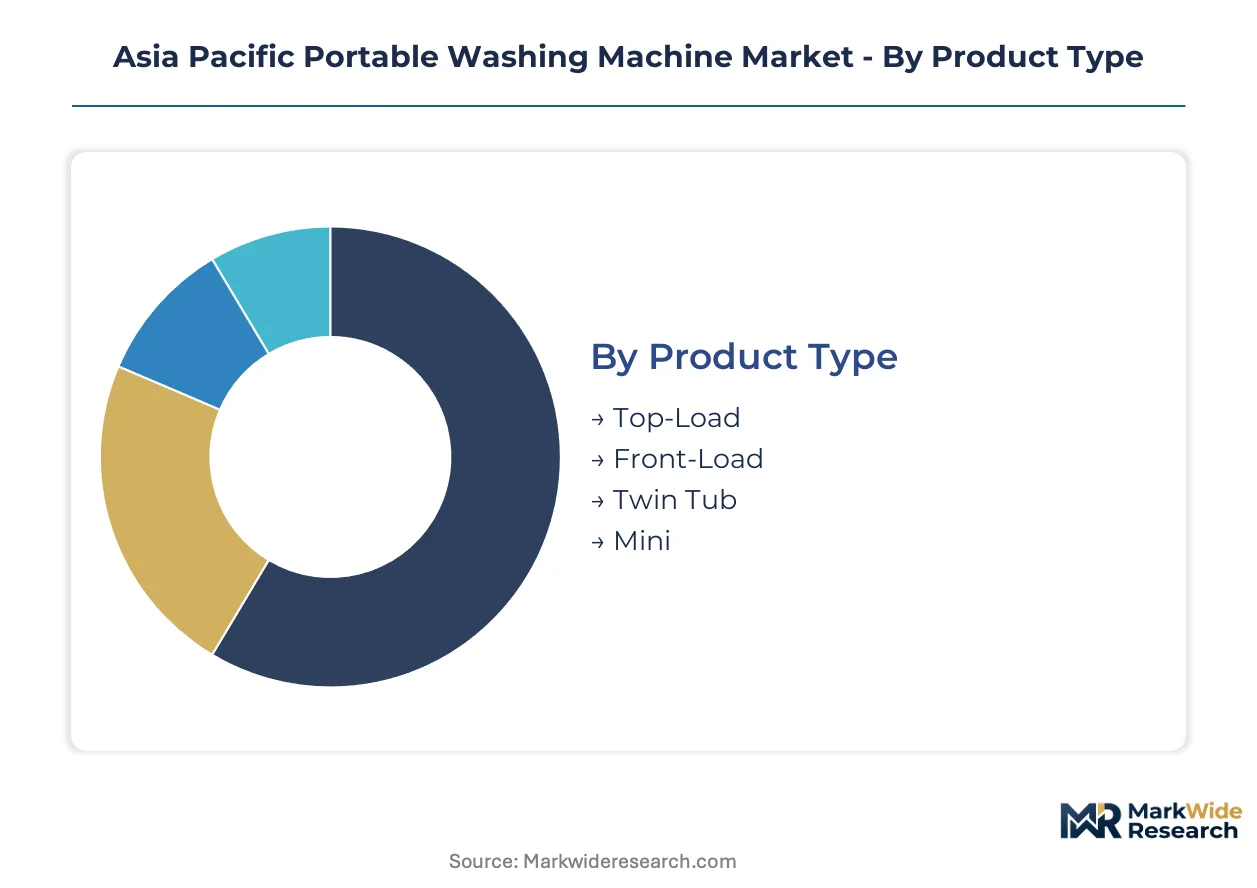
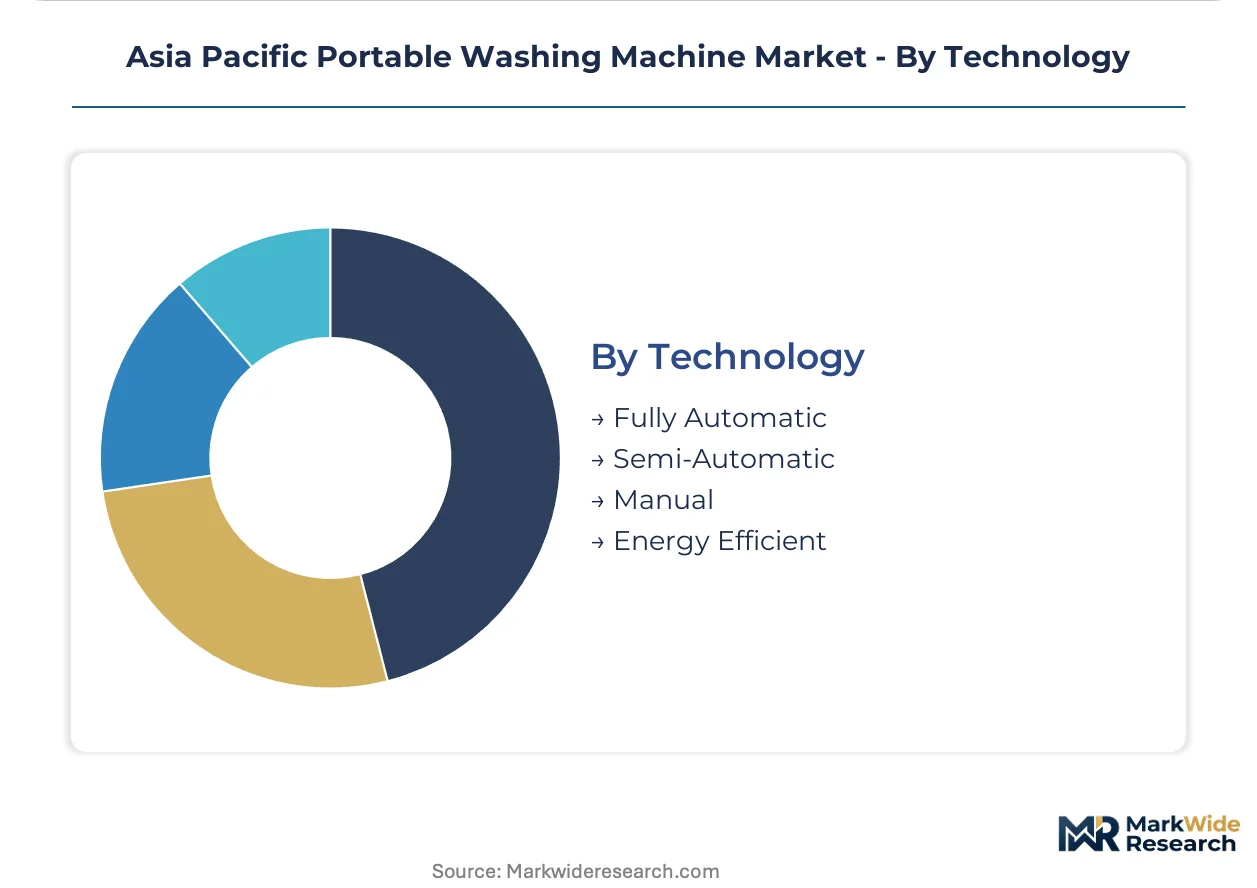
| Segmentation | Product Type: Top-Load, Front-Load, Twin Tub, Mini End User: Residential, Hotels, Hospitals, Dormitories Capacity: 6 kg, 8 kg, 10 kg, 12 kg Technology: Fully Automatic, Semi-Automatic, Manual, Energy Efficient |
| Companies Covered | LG Electronics, Samsung Electronics, Haier Group, Whirlpool Corporation, Electrolux, Bosch, Midea Group, Panasonic Corporation, Godrej Enterprises, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Portable Washing Machine Market Trends and Innovations
Smart load-sensing algorithms and connected diagnostics are redefining value capture models, shifting competition from hardware specifications toward software-enabled service differentiation.
Direct-drive inverter motor technology is decentralizing power transmission architectures by eliminating belt-and-pulley assemblies. Rental housing operators in Bangkok and Jakarta are specifying these units for reduced maintenance downtime. The technology is decentralizing service requirements from centralized repair depots toward on-site component swaps.
India's BIS Compulsory Registration Scheme enforces minimum performance standards for washing machine energy consumption and water efficiency. Manufacturers must redesign heating elements and motor windings to meet tightened thresholds. Semi-automatic twin-tub producers serving rural Maharashtra and Tamil Nadu face the steepest compliance cost absorption.
Outcome-based fleet management contracts are displacing unit purchase models among Southeast Asian rental housing operators. Equipment-as-a-service providers in Singapore and Kuala Lumpur bundle maintenance and detergent logistics into per-cycle pricing. Vietnam's manufacturing corridor dormitory complexes represent the fastest-adopting vertical for this procurement shift.
Asia Pacific Portable Washing Machine Market Segmentation
Portable washing machine procurement patterns diverge sharply across certification regimes, with BIS, GB, and MOIT labeling schemes creating tiered compliance burdens that reshape manufacturer segment prioritization. Understanding these regulatory-driven segment boundaries reveals where margin pools concentrate versus where volume flows.
Product Type:
BIS Compulsory Registration Scheme testing timelines stretch longest for fully automatic configurations, while twin-tub variants face lighter documentation burdens under current thresholds.
- Top-Load:Vertical-axis drum orientation accommodates intermittent power supply conditions prevalent across Indonesia's outer islands. Demand concentrates in India's tier-two cities where consumers prioritize loading ergonomics over water efficiency metrics.
- Front-Load:Horizontal drum rotation achieves superior water extraction rates, reducing drying energy for studio apartment dwellers in Ho Chi Minh City and Manila. BIS water-efficiency mandates are accelerating redesign cycles for heating element integration in this configuration.
- Twin Tub:Separate wash and spin compartments enable manual water conservation. Rural Maharashtra and Tamil Nadu households favor this format where piped water pressure remains unreliable.
- Mini:Sub-45 cm depth units target rental fleet deployment. Bac Ninh and Hai Phong industrial zone dormitories specify these for space-constrained worker housing.
Leading the category by volume: Twin Tub. Growing fastest: Mini.
End User:
Procurement scale and maintenance responsibility allocation split sharply between individual ownership and institutional fleet deployment models.
- Residential:Individual household purchases dominate absolute unit volumes across India and Vietnam. Electricity tariff escalation is redirecting attention toward energy-efficient technology classifications in this segment.
- Hotels:Boutique properties in Bangkok and Jakarta specify compact units for guest laundry services. Direct-drive inverter motors reduce service call frequency for these operators.
- Hospitals:Infection control protocols demand stainless steel drum surfaces with elevated temperature wash cycles. Compliance documentation burdens exceed standard appliance certification requirements.
- Dormitories:Vietnam's manufacturing corridor worker housing represents the fastest-expanding vertical. Outcome-based fleet management contracts are displacing unit purchase models in this segment.
Dominating absolute volume: Residential. Expanding most quickly: Dormitories.
Capacity:
Load-size specifications correlate with housing typology and family structure variations across the region.
- 6 kg:Single-person occupancy and studio apartment constraints define this specification. Urban rental stock in Ho Chi Minh City and Manila sustains import demand.
- 8 kg:Nuclear family configurations across India's tier-two cities concentrate demand here. BIS energy-labeling mandates are compressing motor assembly redesign cycles for this mid-range specification.
- 10 kg:Extended household structures in rural Indonesia favor larger drum volumes despite space constraints. Manual water-filling requirements persist for semi-automatic configurations at this capacity.
- 12 kg:Institutional dormitory and hotel laundry rooms specify maximum load efficiency. Shandong die-casting concentration creates supply vulnerability for drum housings at this scale.
Highest shipment volumes: 8 kg. Steepest expansion trajectory: 6 kg.
Technology:
Automation level determines regulatory exposure and service infrastructure requirements across deployment contexts.
- Fully Automatic:Single-cycle operation with integrated water level sensing. Urban studio apartment proliferation in Southeast Asian cities drives specification of these units despite higher unit costs.
- Semi-Automatic:Operator-mediated water transfer between wash and spin compartments. Intermittent power infrastructure across Indonesia's outer islands sustains demand for this lower-automation format.
- Manual:Hand-cranked or gravity-fed operation without electrical dependency. Remote island communities maintain residual demand where grid connectivity remains absent.
- Energy Efficient:Direct-drive inverter motor technology and heat-pump dryer integration define this classification. China's GB 12021.4 standard and MIIT circular economy directives accelerate rare-earth magnet substitution for compressors in this tier.
Capturing dominant volume: Semi-Automatic. Gaining share fastest: Energy Efficient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates in India's tier-two cities and Vietnam's manufacturing corridors, where rental housing operators and industrial dormitory complexes drive fleet-scale demand for compact laundry units.
India
Tier-two cities including Pune, Ahmedabad, and Kochi generate accelerating demand as nuclear family configurations shift toward apartment living. BIS Compulsory Registration Scheme mandates force redesigns of motor assemblies and heating elements to meet tightened energy-efficiency thresholds. Manufacturing clusters in Maharashtra and Tamil Nadu absorb the steepest compliance cost pressures for semi-automatic twin-tub producers serving rural markets.
Vietnam
Bac Ninh and Hai Phong industrial zones sustain B2B procurement channels for fleet-deployable compact units in worker dormitories. MOIT energy-labeling schemes intensify compliance differentiation for imported automatic formats. Ho Chi Minh City rental stock expansion drives specification of sub-45 cm depth mini units for studio apartment installations.
China
Shandong Province die-casting facilities compress lead times on compact drum housings for regional assemblers. MIIT circular economy directives and GB 12021.4 standards accelerate rare-earth magnet substitution in compressor motors. Guangdong and Hefei multi-plant capacity feeds price-sensitive Southeast Asian distribution channels.
Indonesia
Intermittent power infrastructure across outer islands sustains demand for manual water-filling twin-tub configurations. Semi-automatic formats retain dominant volume share where piped water pressure remains unreliable. Jakarta and Surabaya urban cores show emerging specification of fully automatic mini units for rental apartment conversions.
Philippines
Manila studio apartment proliferation drives import demand for front-load configurations with superior water extraction rates. Electricity tariff escalation redirects residential attention toward energy-efficient technology classifications. Boutique hotel operators in Cebu and Davao specify compact units with direct-drive inverter motors to reduce service call frequency.
Asia Pacific Portable Washing Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated appliance conglomerates commanding premium positioning while regional fabricators capture volume in price-sensitive channels. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with inverter motor IP, dedicated white goods specialists leveraging multi-plant scale, and regional contract manufacturers serving OEM private-label programs. Capacity expansion and rare-earth magnet procurement flexibility constitute the dominant competitive moves reshaping positioning.
Among diversified electronics conglomerates, Samsung Electronics and LG Electronics occupy positions anchored by direct-drive inverter technology and connected diagnostics capabilities. Haier Group exemplifies the integrated manufacturing archetype through captive die-casting and drum housing production. Midea Group represents scale-driven competition with multi-plant capacity across Guangdong and Hefei feeding Southeast Asian distribution. Panasonic Corporation and Godrej Enterprises sit within regionally focused specialist tiers addressing country-specific certification requirements and voltage standards.
| Leading Market Players |
|---|
| LG Electronics |
| Samsung Electronics |
| Haier Group |
| Whirlpool Corporation |
| Electrolux |
| Bosch |
| Midea Group |
| Panasonic Corporation |
| Godrej Enterprises |
| Others |
Pricing and Supply Chain Analysis
BIS energy-labeling mandates for India's Compulsory Registration Scheme are forcing motor assembly redesigns that compress supplier margins and redirect procurement toward certified component tiers. This specification pressure cascades through Shandong die-casting clusters and Guangdong motor winding facilities, concentrating pricing power with integrated manufacturers who absorb compliance costs internally.
Pricing Analysis
Volume-margin splits separate twin-tub economy tiers from premium direct-drive inverter configurations. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification grade and after-sales service bundling. Pricing pressure stems from nickel alloy volatility in stainless steel drum assemblies. Dormitory fleet operators in Vietnam's manufacturing corridors exhibit highest price sensitivity, while boutique hoteliers in Bangkok prioritize reduced service call frequency over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Vietnam's Bac Ninh and Hai Phong industrial zone dormitories, while distributor networks serve India's tier-two city retail. Supply concentrates in China's Shandong Province for die-cast drum housings and Guangdong-Hefei corridor for motor assemblies. Raw material dependencies include rare-earth magnets, nickel-bearing stainless alloys, and copper windings. Single-source vulnerability in Shandong die-casting creates supply chain risk. Distribution runs through Southeast Asian electronics wholesalers and India white goods retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as direct-drive inverter motors displace belt-and-pulley architectures across premium and mid-tier segments. Permanent magnet motor technology is replacing legacy induction motor designs, compressing maintenance requirements and enabling predictive service layers.
For Market Incumbents: Anchor premium positioning through captive rare-earth magnet procurement and BIS pre-certification investments that compress competitor launch timelines. Defend against Midea Group scale advantages by deepening inverter motor IP moats and locking Ho Chi Minh City rental operator contracts through outcome-based fleet management structures. Prioritize backward integration into Shandong die-casting capacity to offset stainless steel input volatility. For New Entrants and Emerging Players: Launch via outcome-based equipment-as-a-service contracts targeting Vietnam's manufacturing corridor dormitories, where procurement is shifting from unit purchase to per-cycle pricing. Penetrate Indonesia's outer islands with semi-automatic twin-tub formats designed for intermittent power and manual water-filling conditions. White-space exists in connected diagnostics software layers that rental operators increasingly specify for predictive maintenance. For Investors and Strategic Acquirers: Re-rating potential sits with integrated manufacturers possessing captive die-casting and direct-drive inverter IP, given BIS and MOIT labeling scheme acceleration. Long-term viability favors archetypes with multi-plant geographic diversification and rare-earth magnet procurement flexibility. Signal to monitor: India's PLI scheme for white goods components reshaping supplier geography toward domestic motor production.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Backward Integration | Captive neodymium sourcing insulates margin pools from China's MIIT export licensing volatility. |
| BIS Pre-Certification Investment | Early compliance with India's Compulsory Registration Scheme compresses rival product launch windows by 4-6 months. |
| Outcome-Based Fleet Contracting | Per-cycle pricing models lock Vietnam dormitory operators into multi-year service relationships. |
| Direct-Drive Inverter Platform Standardization | Unified motor architecture reduces SKU complexity across premium and mid-tier product lines. |
| IoT-Enabled Predictive Maintenance Launch | Connected diagnostics create recurring revenue streams from rental housing operator segments. |
Research Methodology
Document review covered BIS registration databases, China GB standard filings, and Vietnam MOIT energy-labeling records, complemented by interviews with white goods manufacturing executives, rental housing procurement managers, and component supplier technical directors. Secondary sources included customs trade data, MIIT circular economy directives, and India PLI scheme disclosure documents. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Market size and growth trajectories across the analysis window reflect segment-level modeling across product type, capacity specification, automation level, and end-use vertical. CAGRs derived from regression analysis of historical shipment patterns and elasticity-adjusted demand projections. Industry-specific inputs incorporated BIS certification timeline data, rare-earth magnet price indices, and Vietnam industrial zone rental stock expansion rates.
Nickel alloy price volatility, BIS testing backlog extensions, and Vietnam import tariff adjustments are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding regulatory enforcement timelines and infrastructure electrification rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
United States Household Refrigerators Market
Home Appliances
Chile Home Appliances Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
South Korea Major Home Appliances Market
Home Appliances
Refrigerator Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
Europe White Goods Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Small Home Appliances Market