
 Smart Home Appliances Market | 2026-2036
Smart Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Appliances Market Intelligence
The integration of standardized System-on-Chips (SoCs) over proprietary microcontrollers is repositioning the economic calculus for appliance manufacturing. This shift lowers the barrier for new features and accelerates development cycles. Samsung Electronics leverages its vast semiconductor division for critical components, creating a significant cost and supply advantage. Haier Smart Home dominates the expansive Chinese market through its U+ smart life platform. LG Electronics differentiates its product line with the ThinQ AI-powered diagnostics and proactive service features.
Smart home appliances are electromechanical devices for household tasks, embedded with network connectivity hardware and software. These products utilize protocols such as Wi-Fi, Bluetooth, or Zigbee to connect to a central hub or cloud service for remote monitoring and control. Among product types, smart thermostats are a mature segment, while smart refrigerators offer high-margin growth through advanced features. Energy management and home security applications represent the primary value propositions driving homeowner adoption across different device categories.
Product design and market access are shaped by a complex web of regional regulations. The EU's forthcoming Cyber Resilience Act will mandate cybersecurity standards for all connected devices, impacting development costs. In the United States, the EPA's ENERGY STAR program sets voluntary efficiency benchmarks that influence consumer choice. The future competitive landscape will be defined by manufacturer decisions to support open ecosystems versus cultivating proprietary, brand-specific platforms.
Market Dynamics
The central force shaping the smart home appliance market is the commoditization of connectivity hardware through standardized System-on-Chips. This technological shift is displacing proprietary systems, lowering development costs, and accelerating the pace of feature integration for manufacturers.
Growth Catalysts
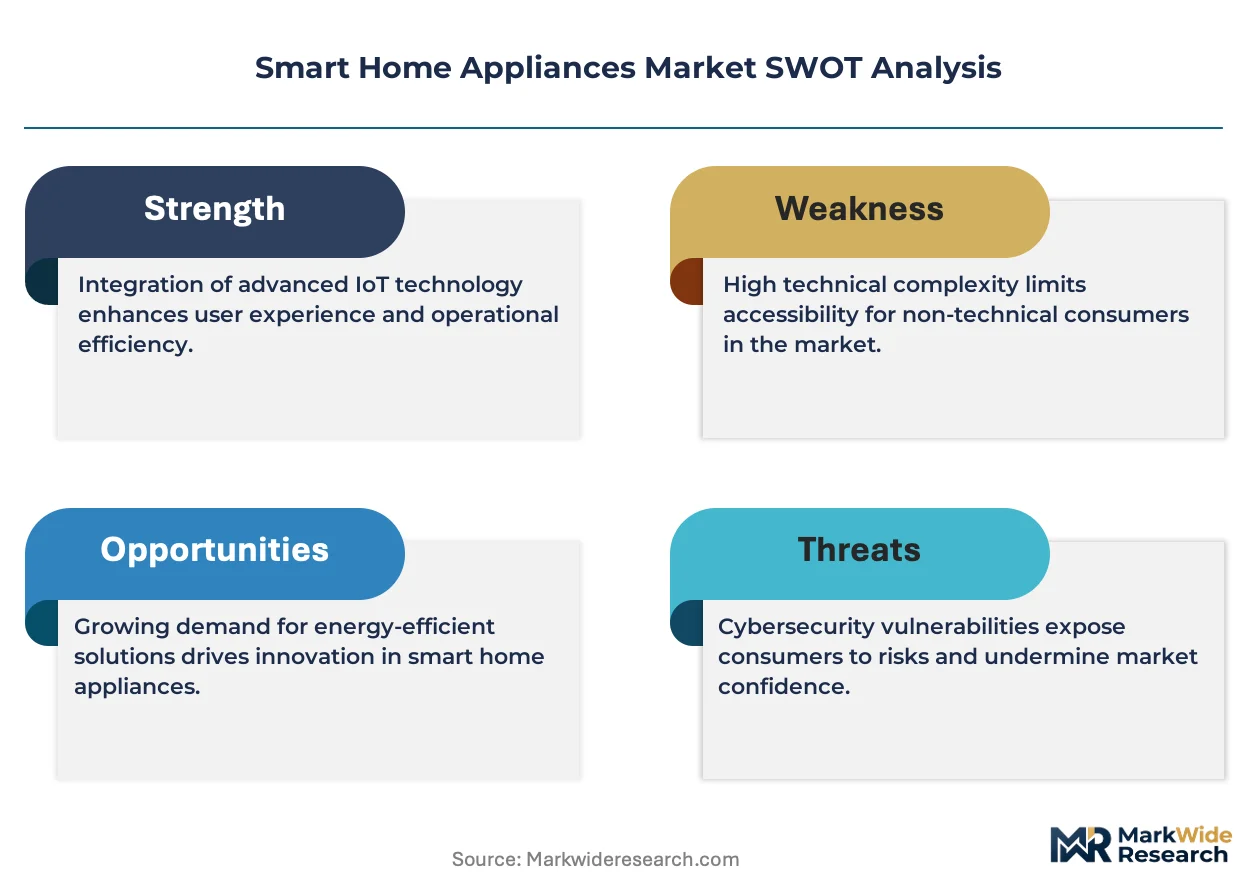
- Energy Efficiency Mandates:Government programs, including the EPA's ENERGY STAR in the United States and EU ecodesign requirements, incentivize the purchase of energy-efficient smart appliances, particularly thermostats and large white goods, by offering rebates and creating clear consumer benchmarks.
- Interoperability Standards:The maturation of connectivity protocols like Matter simplifies device setup and integration for consumers, removing a significant adoption barrier. This allows devices from different brands to work together seamlessly within a single smart home ecosystem.
- Rapid Urbanization:In economies such as China and India, the growth of dense urban centers and smaller living spaces increases consumer demand for appliances that offer convenience, automation, and efficient space utilization.
Market Restraints
- High Initial Cost:The significant price premium of smart appliances over their conventional counterparts remains a primary deterrent for price-sensitive consumers. This cost difference slows mass-market penetration beyond early adopters and high-income households.
- Data Privacy Concerns:Consumer apprehension regarding the collection and security of personal data by connected devices creates a structural barrier of trust. Incidents of data breaches amplify these concerns and can negatively impact purchasing decisions.
- Regulatory Fragmentation:A patchwork of differing data privacy and security regulations across geographies, such as the GDPR in Europe and various state-level laws in the US, increases compliance costs and complexity for global manufacturers.
Strategic Opportunities
- Predictive Maintenance Services:Leveraging sensor data and AI to offer proactive diagnostics and predictive maintenance subscriptions represents a significant opportunity. This creates recurring revenue streams beyond the initial hardware sale and enhances customer loyalty.
- Health and Wellness Integration:There is a growing opportunity to integrate smart appliances with health and wellness platforms. For instance, smart refrigerators can track food inventory for diet plans, and air purifiers can adjust based on local air quality data.
- Emerging Market Expansion:Untapped demand in regions like Southeast Asia and Latin America presents a major growth vector. Rising disposable incomes and expanding internet infrastructure in these areas create a fertile ground for market entry.
Industry Challenges
- Ecosystem Interoperability:Despite standards like Matter, ensuring flawless and reliable communication between a vast array of devices, platforms, and legacy systems remains a persistent technical and operational challenge for the industry.
- Cybersecurity Compliance:Adhering to new and evolving cybersecurity mandates, such as the EU's Cyber Resilience Act, demands continuous investment in secure development practices and long-term software support, impacting product timelines and costs.
- Talent Scarcity:A shortage of skilled professionals with expertise in both embedded software engineering and cloud-based data analytics can constrain a manufacturer's ability to innovate and compete on advanced features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Appliances Market |
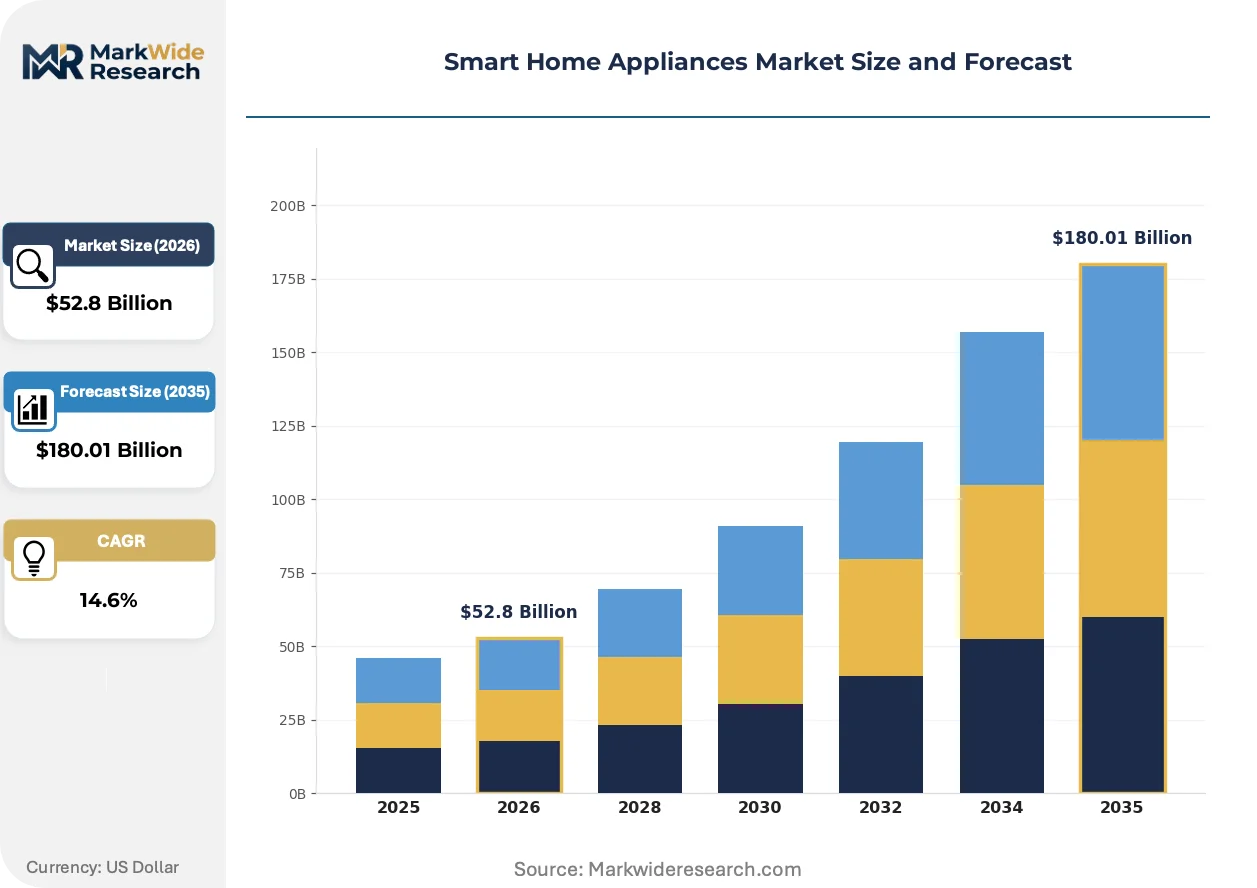
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $180.01 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Refrigerators, Smart Washing Machines, Smart Thermostats, Smart Security Cameras, Smart Lighting Systems Technology: Wi-Fi, Bluetooth, Zigbee, Z-Wave, Thread Application: Energy Management, Home Security, Appliance Control, Health & Wellness, Entertainment End User: Homeowners, Property Managers, Rental Tenants, Vacation Rental Hosts |
| Companies Covered | AB Electrolux, Haier Smart Home Co., Ltd., Samsung Electronics Co., Ltd., Midea Group Co., Ltd., Panasonic Corporation, LG Electronics Inc., BSH Hausgeräte GmbH, GE Appliances, Whirlpool Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Appliances Market Strategic Shifts & Innovations
Intelligence embedded within appliances, not just connectivity, defines current market evolution. The focus is shifting from remote control to autonomous operation and ecosystem integration, creating new value for consumers and manufacturers alike.
Edge AI Edge AI processes data locally on the device, enhancing responsiveness and user privacy. Appliance manufacturers are rapidly adopting this for features like real-time voice recognition and personalized user settings. This on-device intelligence is expanding into proactive functions, such as refrigerators suggesting recipes based on contents or washing machines optimizing cycles.
Cybersecurity by Design The European Union's Cyber Resilience Act imposes mandatory cybersecurity requirements for products with digital elements. This regulation forces manufacturers to integrate security throughout the product design lifecycle, from development to end-of-life support. The smart appliance segment is most affected, requiring significant investment in software updates and vulnerability management to maintain EU market access.
Service-Based Models A consumer shift values ongoing services over one-time hardware purchases. This disrupts the traditional retail model, with manufacturers offering premium subscriptions for enhanced diagnostics, automated consumable replenishment, and exclusive digital content. This trend is most visible in North America and Europe within the high-end smart kitchen appliance category.
Smart Home Appliances Market Segmentation
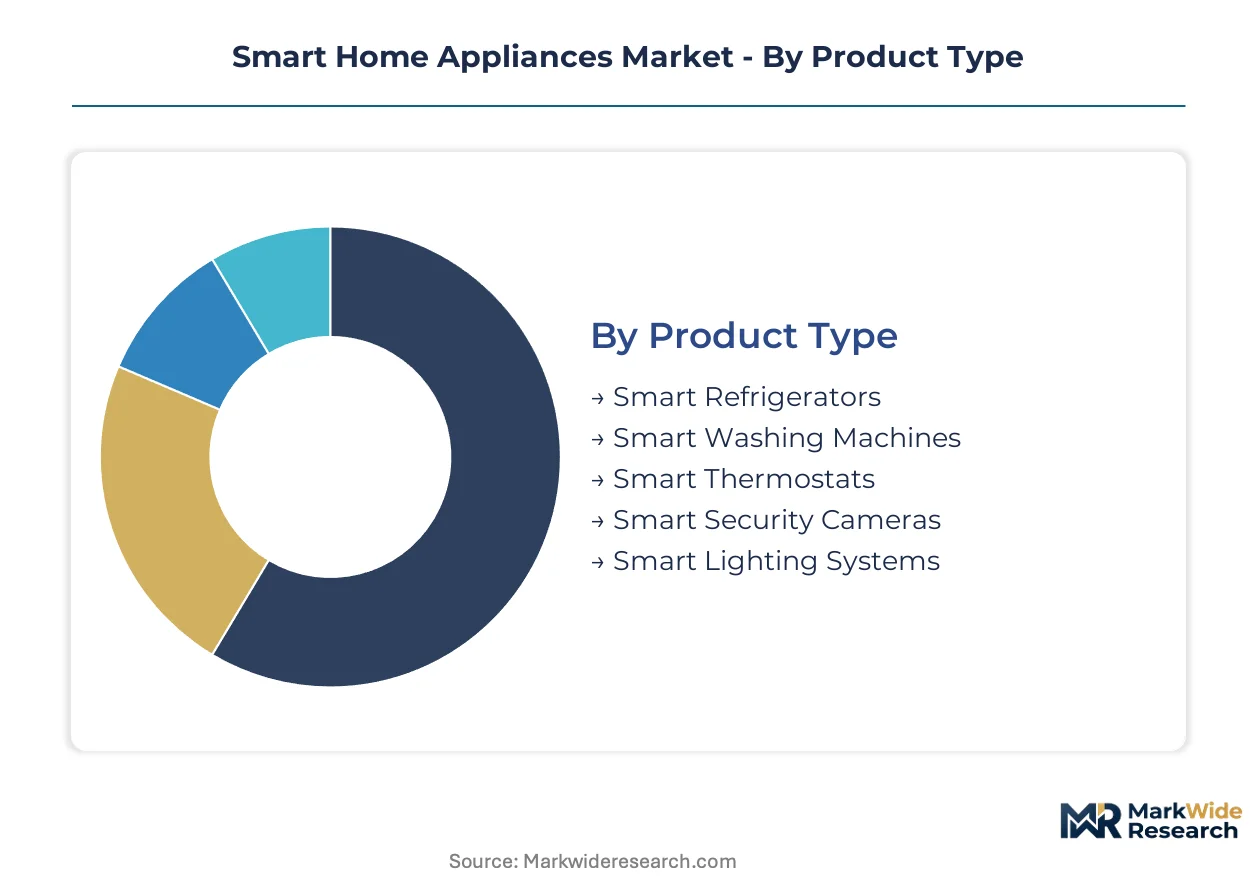
The smart home appliances market comprises diverse product types, technologies, applications, and end-users, each with distinct characteristics and growth trajectories. Understanding these segments clarifies the varying investment requirements and market penetration strategies for manufacturers. This granular segmentation provides essential insights into specific demand drivers and competitive dynamics.
Product Type:
The capital intensity of smart home appliance manufacturing varies significantly across product types, with large appliances demanding substantial upfront investment in production lines and complex supply chains.
- Smart Refrigerators:These devices integrate advanced sensors, AI, and connectivity for features like inventory management and predictive maintenance. Demand concentrates in developed economies, particularly the United States, driven by consumer desire for convenience.
- Smart Thermostats:These electromechanical devices regulate home climate, incorporating learning algorithms and remote control capabilities. Adoption is widespread in North America, propelled by energy efficiency mandates.
- Smart Washing Machines:These appliances offer remote control, optimized wash cycles, and diagnostic capabilities via network connectivity.
- Smart Security Cameras:These connected devices provide real-time monitoring and alerts, integrating with broader home security systems.
- Smart Lighting Systems:These systems allow remote control, scheduling, and color temperature adjustments for enhanced ambiance.
Most installed capacity flows through Smart Thermostats. Expansion is steepest in Smart Refrigerators.
Technology:
Supply concentration for smart appliance connectivity technologies varies, with established standards benefiting from broad component availability and newer protocols requiring specialized chipsets.
- Wi-Fi:This ubiquitous wireless communication protocol enables direct internet connectivity for smart appliances, leveraging existing home network infrastructure. Its widespread adoption in China simplifies integration with cloud services.
- Thread:This low-power, mesh networking protocol forms the backbone for many Matter-compliant devices, ensuring robust and scalable connectivity. Its deployment accelerates in European markets.
- Bluetooth:This short-range wireless technology often facilitates direct device-to-device communication or initial setup processes.
- Zigbee:This mesh network protocol offers low-power consumption and is widely used for smaller smart home devices.
- Z-Wave:This proprietary wireless communication protocol specializes in home automation, providing reliable and secure connectivity.
Wi-Fi holds the largest market share due to its established presence. Thread is gaining traction as a foundational element for next-generation interoperability.
Application:
Customer type preferences heavily influence the adoption patterns across smart appliance applications, with homeowners prioritizing different functionalities than property managers.
- Energy Management:This application optimizes appliance operation to reduce energy consumption and costs, integrating with smart grids and utility programs. Homeowner adoption in Germany is strong, driven by high energy prices.
- Home Security:This segment includes features like remote monitoring, access control, and intrusion detection, enhancing safety and peace of mind. Demand is high in urban areas across the United States.
- Appliance Control:This application enables remote operation and scheduling of devices via mobile applications.
- Health & Wellness:This category includes smart appliances that monitor personal health metrics or contribute to a healthier living environment.
- Entertainment:This application integrates smart appliances with home entertainment systems, offering features like smart screens or audio streaming.
Energy Management applications are generating the most revenue for the market. Health & Wellness applications are experiencing the most rapid expansion.
End User:
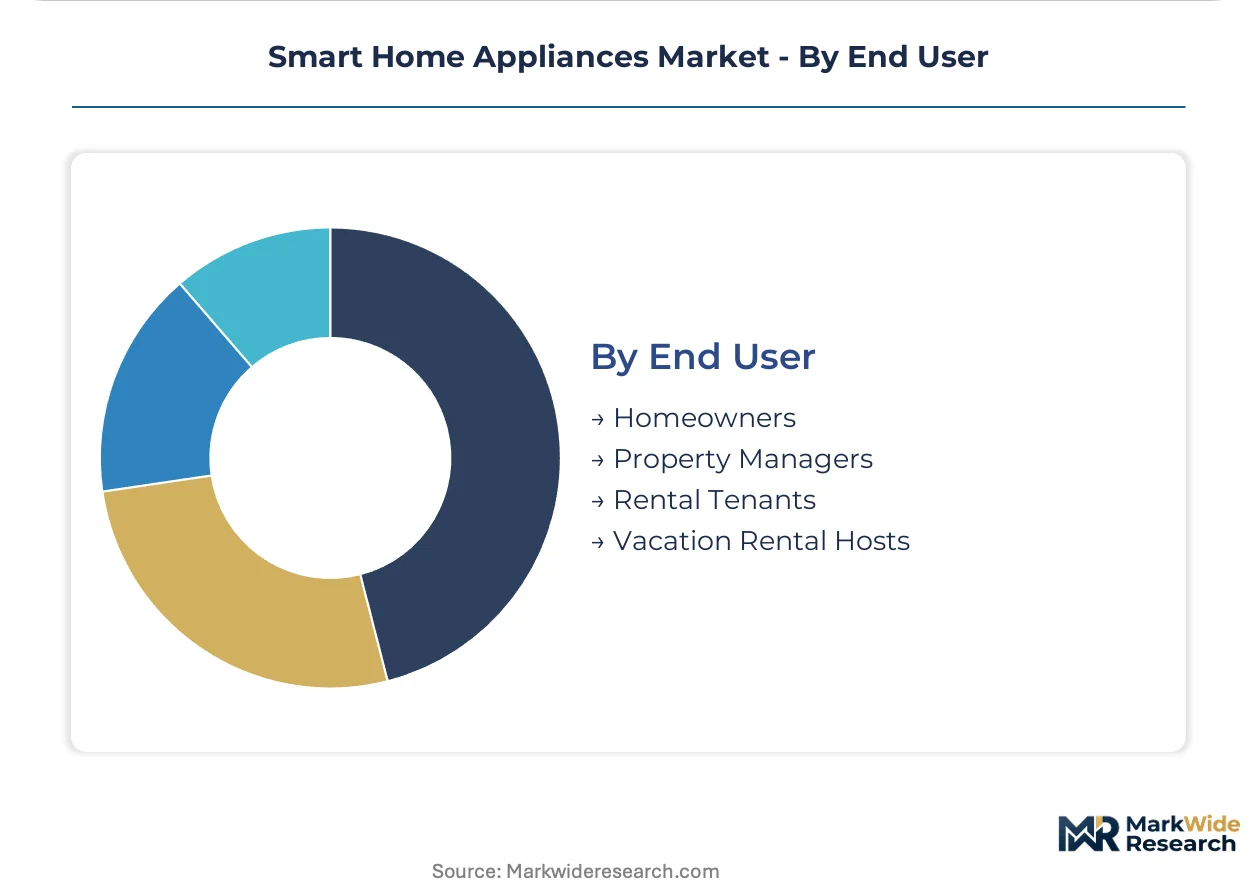
Volume of smart appliance purchases varies significantly across end-user segments, with individual homeowners representing the largest purchasing cohort.
- Homeowners:This segment comprises individuals purchasing smart appliances for their primary residences, seeking convenience, energy savings, and enhanced lifestyle features. Demand is concentrated in affluent suburban areas of the United States.
- Property Managers:These professionals integrate smart appliances into rental properties to enhance tenant experience, reduce operational costs, and improve building efficiency. Urban centers in Canada show increasing adoption.
- Rental Tenants:This group typically utilizes smart appliances provided by landlords, influencing future purchasing decisions.
- Vacation Rental Hosts:These users deploy smart appliances in short-term rental properties to automate tasks and monitor usage.
Homeowners currently dominate the user base for smart home appliances. Property Managers are demonstrating significant uptake as smart building technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's consumer electronics manufacturing base drives significant market activity across diverse geographies. Rapid urbanization and rising disposable incomes fuel demand for connected appliances. Government incentives for energy efficiency also shape regional market dynamics.
China
Rapid urbanization and a vast consumer electronics manufacturing base drive demand for smart appliances. The country's GB standards ensure product quality and safety for devices entering this market. Major technology hubs like the Yangtze River Delta actively develop new smart home solutions and integrate AI.
United States
Homeowner demand for convenience and energy savings propels sales of smart refrigerators and thermostats. The EPA's ENERGY STAR program influences consumer choice through efficiency benchmarks. Silicon Valley innovators continually push boundaries for new features and platform integrations.
Germany
High energy prices and strong environmental awareness foster demand for energy management applications. The EU's Cyber Resilience Act mandates stringent cybersecurity standards for connected devices sold here. Bavaria's strong engineering sector supports advanced appliance manufacturing and R&D activities.
South Korea
Tech-savvy consumers and high internet penetration drive significant adoption of advanced smart home devices. KC certification ensures electrical product safety and electromagnetic compatibility for market entry. The Seoul Capital Area serves as a hub for R&D and advanced manufacturing of smart electronics.
India
Rising disposable incomes and expanding internet infrastructure create fertile ground for smart appliance market entry. BIS standards guide product quality and safety for consumer electronics within the country. Bengaluru's IT industry supports the integration of smart home ecosystems and cloud services.
Smart Home Appliances Market Key Industry Players
Global majors compete with regional champions across market access and technological innovation. The market structure exhibits consolidation among established appliance manufacturers, alongside fragmentation among niche smart home solution providers. Strategic archetypes include integrated electronics conglomerates, specialized smart appliance developers, and platform-centric ecosystem builders. Dominant competitive moves involve strategic partnerships for ecosystem expansion and continuous investment in AI-driven feature development.
On the integrated electronics conglomerate vector, Samsung Electronics Co., Ltd. and LG Electronics Inc. exemplify companies leveraging vast internal semiconductor divisions for cost and supply advantages. Samsung Electronics focuses on critical component supply, while LG Electronics differentiates its product line with ThinQ AI-powered diagnostics. Haier Smart Home Co., Ltd. occupies a position as a platform-centric ecosystem builder, particularly dominating the expansive Chinese market through its U+ smart life platform. These players continually push for advanced features and seamless user experiences within their respective ecosystems, driving innovation in connectivity and autonomous operation.
| Leading Market Players |
|---|
| AB Electrolux |
| Haier Smart Home Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Midea Group Co., Ltd. |
| Panasonic Corporation |
| LG Electronics Inc. |
| BSH Hausgeräte GmbH |
| GE Appliances |
| Whirlpool Corporation |
| Others |
Cost & Logistics Intelligence
The EU's Cyber Resilience Act, mandating cybersecurity standards for connected devices, gates qualified supply and premium-tier pricing access for smart home appliance manufacturers. This regulation necessitates significant investment in secure development, impacting product costs and market entry for non-compliant devices. Such mandates reshape the economic landscape for advanced appliance features.
Pricing Analysis
Input cost pass-through for critical components like standardized System-on-Chips influences smart appliance pricing. The market exhibits a hybrid pricing model, combining transactional hardware sales with emerging subscription-based services for enhanced diagnostics. Price differentiation stems from brand premium and certified energy efficiency, such as EPA's ENERGY STAR ratings. Pricing pressure stems from the commoditization of connectivity hardware, particularly impacting standard-tier appliances. Price-sensitive consumers remain deterred by high initial costs, while affluent homeowners prioritize advanced features and convenience.
Supply Chain Analysis
Skilled workforce availability in key manufacturing geographies like China and South Korea is crucial for smart appliance production. Supply concentration centers on these nations, alongside Germany, leveraging their advanced manufacturing capabilities. The supply chain depends on critical components such as standardized System-on-Chips, advanced sensors, and network connectivity hardware. Regulatory restrictions, particularly varying cybersecurity compliance across regions, represent a structural risk. Distribution runs through established retail channels, direct-to-consumer online platforms, and increasingly via B2B partnerships with property management firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart home appliance market remains a stable compounder, with interoperability standards driving steady growth in device adoption. This consistent expansion offers predictable returns for strategic participants across the value chain.
For Market Incumbents: Deepen internal semiconductor integration to secure critical component supply and reduce manufacturing costs. Invest in Edge AI capabilities and long-term software support for proprietary platforms, defending against generic solutions. This strategy mitigates margin pressure from new entrants leveraging standardized SoCs. Focus R&D on proactive diagnostics and predictive maintenance services to enhance recurring revenue streams.
For New Entrants and Emerging Players: Underserved property managers represent a significant white-space target for smart appliance solutions tailored to multi-unit dwellings. Focus on Health & Wellness integration and energy management applications in emerging markets like Southeast Asia. A go-to-market angle emphasizing Matter-compliant interoperability simplifies integration for property managers, lowering adoption barriers. Offer subscription-based service models for enhanced diagnostics and maintenance, creating recurring revenue.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized smart appliance developers with strong intellectual property in Edge AI and cybersecurity-by-design. The long-term viability of this market is strong, driven by sustained consumer demand for convenience and efficiency. Target platform-centric ecosystem builders with proven recurring revenue from service models. The adoption rate of Matter-compliant devices serves as a key signal to watch for market inflection and ecosystem consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Edge AI Capabilities | Enhances on-device processing for faster responses and improved user privacy in smart appliances. |
| Invest in Cybersecurity Standards | Ensures compliance with regulations like the EU Cyber Resilience Act, securing market access. |
| Develop Service-Based Revenue Models | Creates recurring income streams beyond hardware sales and fosters customer loyalty. |
| Target Emerging Urban Markets | Captures new demand in rapidly urbanizing economies like India and Southeast Asia. |
| Strengthen Matter Interoperability | Simplifies device integration for consumers and broadens ecosystem compatibility across brands. |
Research Approach
Coverage spans China, United States, Germany, South Korea, and India, with primary inputs from each region informing market dynamics. The analysis combines in-depth primary interviews with industry stakeholders, including appliance R&D engineers, retail channel managers, and property management firm executives. Secondary validation draws from national statistics agencies, industry association reports, patent databases, and regulatory body publications. This approach ensures robust bottom-up and top-down triangulation of market data.
Granular modeling across product type, technology, application, end-user, and regional market penetration defines the forecast framework. The analytical framework projects market evolution across the modeling period, with CAGRs derived through rigorous regression analysis and expert consensus. Key industry-specific forecast inputs include Matter standard adoption rates and urban population growth projections, critically influencing market expansion figures.
Underlying measurement precision varies by segment; smart thermostats and Wi-Fi technology carry tighter precision than others due to established data availability. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Evolving cybersecurity regulations and potential supply chain disruptions for critical components represent specific risk factors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
Japan Home Appliances Market
Home Appliances
Italy Home Appliances Market
Home Appliances
China Small Home Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Built-In Appliance Market
Home Appliances
Qatar Small Home Appliances Market