
 India Small Home Appliances Market | 2026-2036
India Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
India Small Home Appliances Market Foresight
Maharashtra's expanding manufacturing corridor around Pune and Aurangabad is reshaping component sourcing for small home appliances. Havells India Ltd. leverages its vertically integrated cable and motor operations to control input costs across fan and mixer grinder lines. Bajaj Electricals Ltd. anchors its position through an extensive rural distribution network spanning tier-3 towns and district trade channels. Philips Domestic Appliances differentiates via sustained R&D spending on inductive heating and precision temperature control systems.
Small home appliances comprise electrically powered portable devices designed for domestic tasks, typically operating below 2,500 watts with plastic or stainless steel housings, universal motors or BLDC drives, and safety interlocks meeting IEC 60335 standards. Kitchen appliances dominate volume throughput due to daily-use frequency in Indian households, while personal care appliances capture expanding margin pools as male grooming and hair styling segments professionalize at home. Energy-efficient devices within the technology dimension are gaining structural priority as DISCOMs implement time-of-day tariffs and consumers face rising electricity bills.
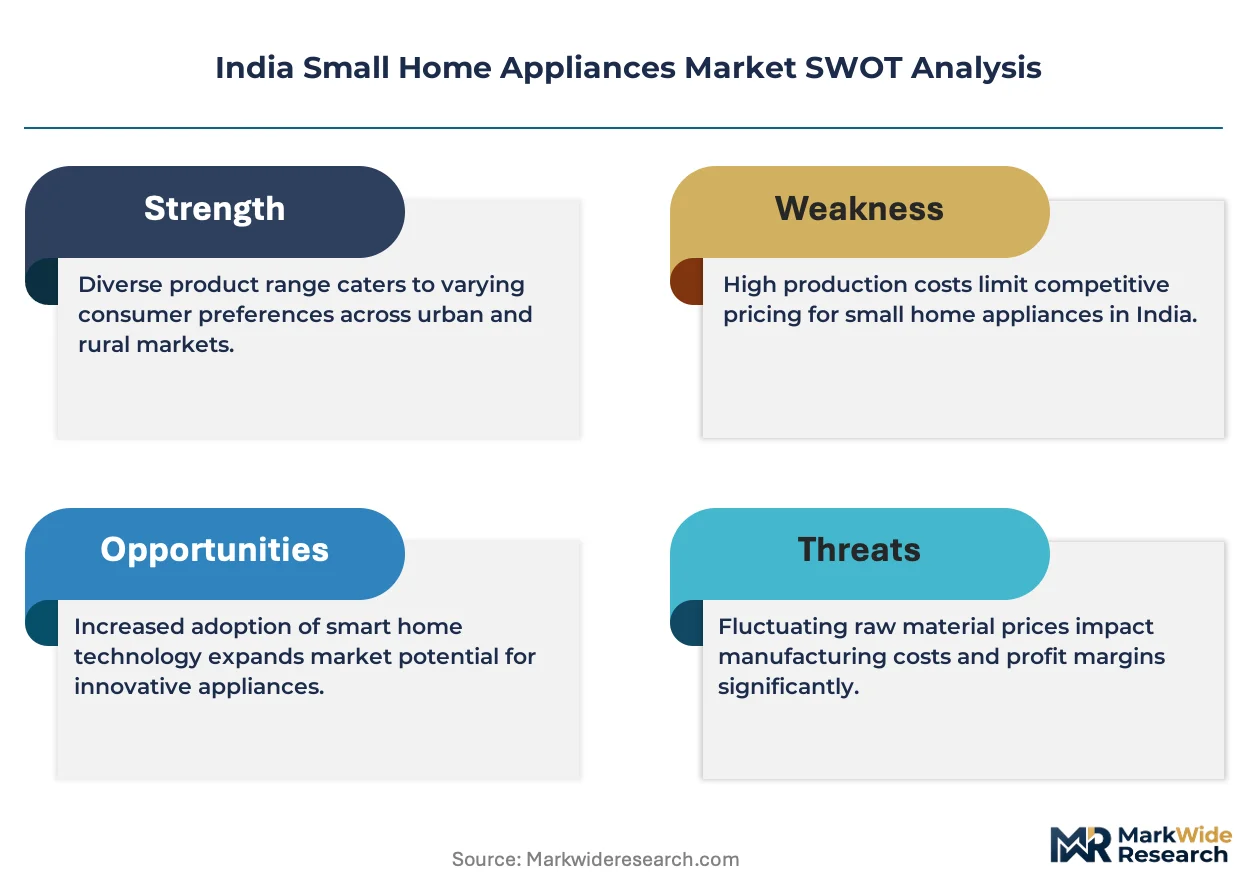
BIS mandates compulsory registration for household electrical goods under the CRS scheme, while the Bureau's ISI mark governs safety and electromagnetic compatibility thresholds. The PLI scheme for white goods extends subsidy coverage to component makers, incentivizing domestic motor and controller production. Stakeholders must monitor state-level RPO regulations and EESL bulk procurement tenders, as these channels increasingly determine volume allocation and pricing benchmarks for entry-level product tiers.
Market Dynamics
The shift from universal motors to BLDC drives is compressing energy consumption benchmarks across India's small home appliances sector, forcing manufacturers to redesign thermal management systems and controller architectures.
Growth Catalysts
- PLI scheme extension:The government's production-linked incentive scheme for white goods subsidizes domestic motor and controller manufacturing, reducing import dependence for critical components.
- Metro nuclear families:Urban households in Mumbai and Bengaluru drive daily-use kitchen appliance replacement cycles, creating sustained volume demand for mixer grinders and induction cooktops.
- BIS CRS mandate:Compulsory registration for household electrical goods under the Bureau of Indian Standards scheme elevates quality floors and accelerates informal-to-formal channel migration.
Market Restraints
- Copper price volatility:Winding wire costs fluctuate with LME copper benchmarks, squeezing margin stability for motor-dependent product lines.
- Controller chip concentration:Semiconductor sourcing clusters in East Asia create single-point vulnerability for smart appliance production schedules.
- ISI certification friction:Electromagnetic compatibility testing timelines extend product launch windows by 8-12 weeks for new market entrants.
Strategic Opportunities
- EESL bulk procurement:Energy Efficiency Services Limited tenders for entry-tier appliances open institutional volume channels bypassing traditional retail markups.
- Tier-3 electrification:District-level grid saturation in Rajasthan and Madhya Pradesh unlocks first-time appliance ownership in previously underserved settlements.
- Inductive heating convergence:Precision temperature control systems from personal care appliances migrate into kitchen equipment, enabling premium positioning.
Industry Challenges
- BLDC firmware talent scarcity:Embedded motor control engineering expertise concentrates in Bengaluru and Hyderabad, creating recruitment bottlenecks for Pune-based manufacturers.
- Multi-state RPO compliance:Renewable purchase obligation regulations vary across Maharashtra, Karnataka, and Tamil Nadu, complicating pan-India production planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Small Home Appliances Market |
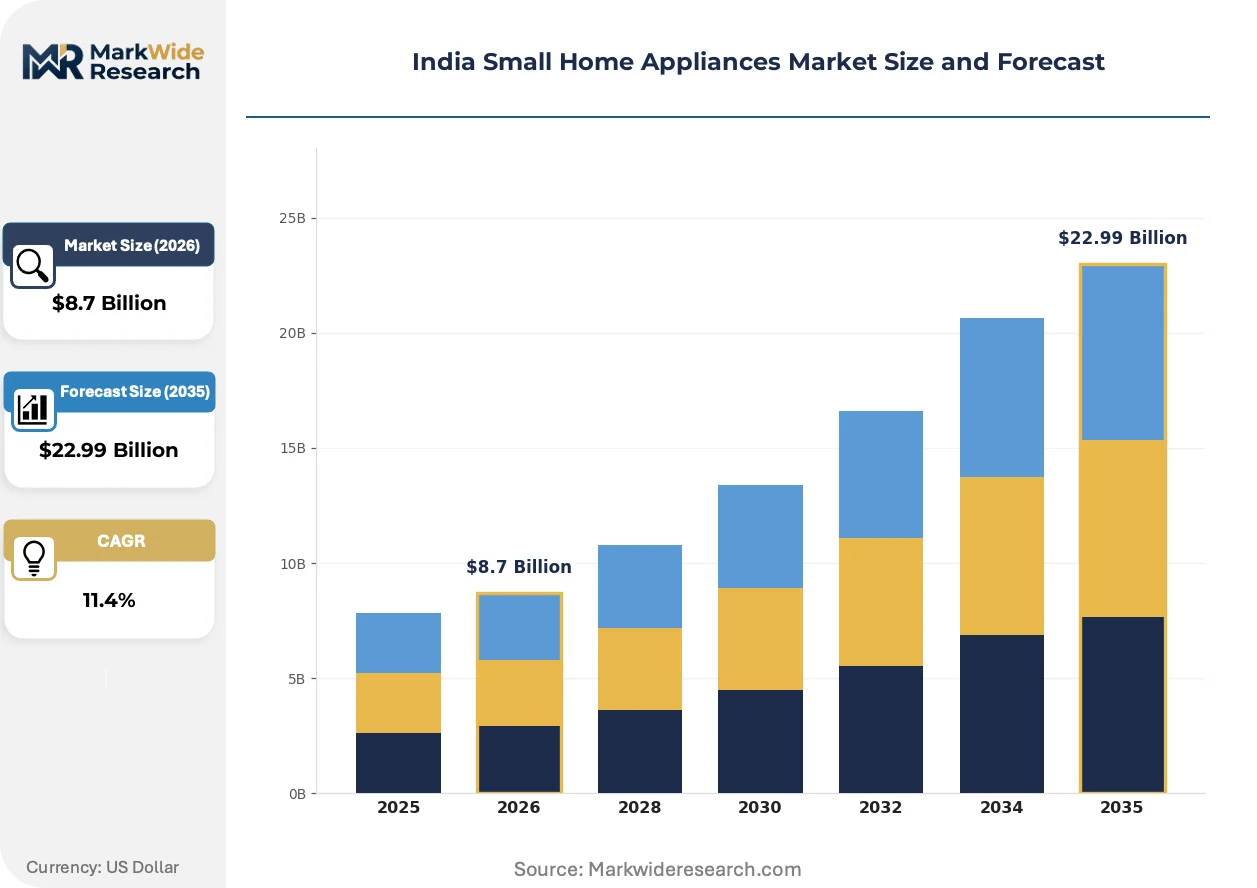
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Appliances, Cleaning Appliances, Personal Care Appliances, Heating Appliances End User: Residential Users, Commercial Users, Hotels, Restaurants Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Technology: Smart Appliances, Energy-efficient Devices, Cordless Technology, Traditional Appliances |
| Companies Covered | Havells India Ltd., BSH Household Appliances, Philips Domestic Appliances, Whirlpool of India, Godrej Consumer Products Limited, Bajaj Electricals Ltd., Panasonic India Pvt. Ltd., LG Electronics, TTK Prestige Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Small Home Appliances Market Shifts & Advancements
Component-level innovation and regulatory tightening are converging to redefine performance benchmarks and procurement patterns across India's small home appliances value chain.
BLDC motor platforms with integrated variable frequency drives are rendering obsolete single-speed universal motor architectures in ceiling fans and mixer grinders. Tier-1 manufacturers in Pune and Aurangabad have accelerated adoption timelines, compressing the technology refresh cycle from seven years to under four. The structural consequence is a bifurcation between energy-efficient premium tiers and residual inventory clearance channels.
BIS tightened electromagnetic compatibility thresholds under amended ISI mark requirements for household electrical goods. Testing laboratories in Mumbai and Delhi face capacity constraints as compliance deadlines approach, forcing manufacturers to sequence product certifications. Induction cooktop and smart fan controllers encounter the steepest compliance cost escalation.
Appliance ownership is fragmenting across consumption occasions rather than consolidating in multi-function devices. Urban households in Bengaluru and Hyderabad now maintain separate units for grinding, blending, and food processing rather than relying on single mixer-grinder platforms. This pattern concentrates in western and southern states where nuclear family density and disposable income levels support specialization.
India Small Home Appliances Market Segmentation
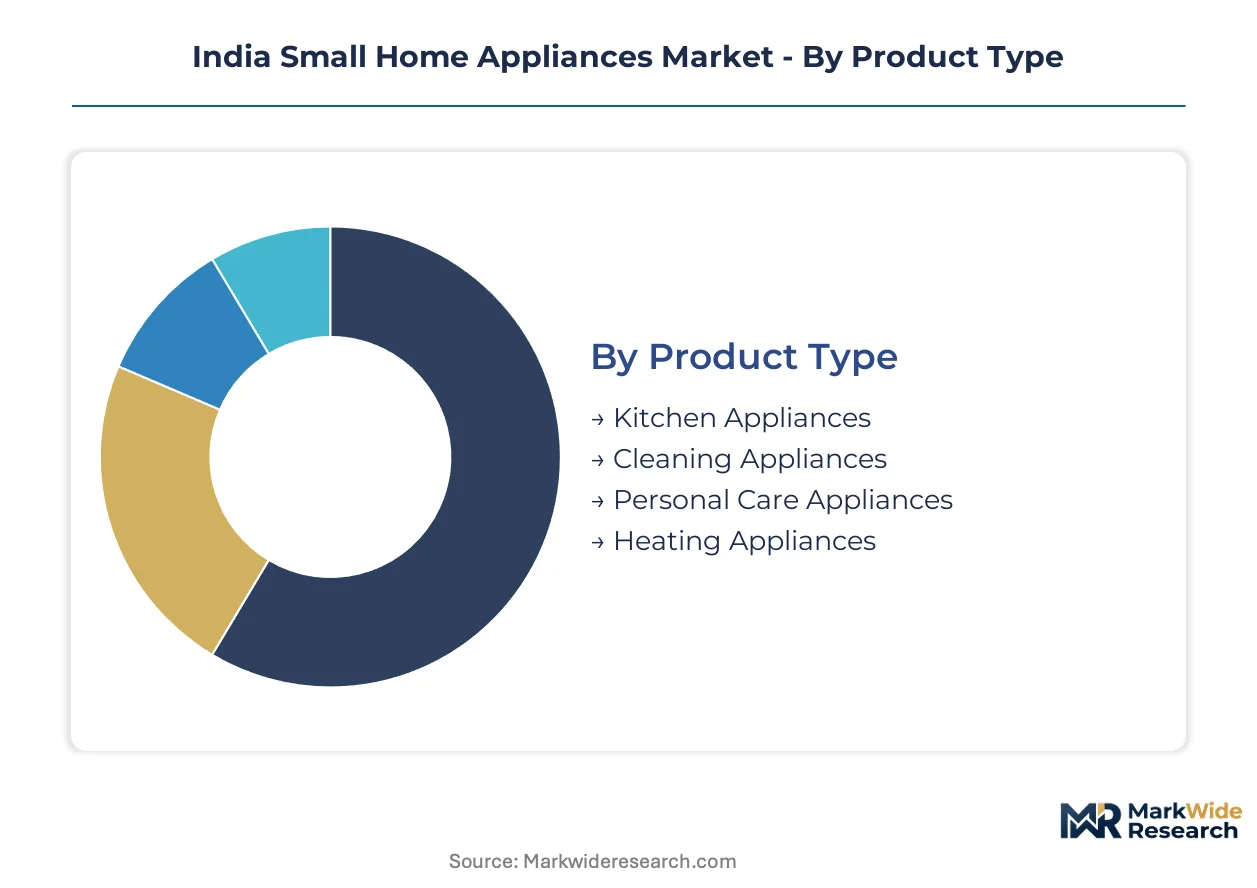
Segmentation in India's small home appliances sector reveals how electrification gradients, urban household structures, and regulatory compliance thresholds fragment demand across product tiers and channel pathways. Manufacturers must align R&D allocation and distribution investments to these distinct velocity pockets.
Product Type:
Mature kitchen equipment anchors installed base volumes while emerging personal care and smart-enabled categories reshape margin pools and replacement cycles.
- Kitchen Appliances:Mixer grinders, induction cooktops, and electric kettles incorporate universal or BLDC motor platforms with thermal cutoffs meeting BIS ISI standards. Demand clusters in Maharashtra and Karnataka's nuclear family households where daily-use frequency drives 3-5 year replacement cycles. Havells and Bajaj Electricals dominate this segment through tier-3 distribution depth and component backward integration.
- Cleaning Appliances:Vacuum cleaners and pressure washers deploy sealed suction motors or lithium-ion battery packs in cordless configurations. Adoption accelerates in Bengaluru and Hyderabad's apartment complexes where dust accumulation and water scarcity elevate mechanized cleaning priority.
- Personal Care Appliances:Hair dryers, trimmers, and styling tools leverage ceramic heating elements and precision temperature controllers. Male grooming professionalization in Mumbai and Delhi NCR expands addressable base beyond traditional female-skewed ownership.
- Heating Appliances:Room heaters and water heaters rely on immersion elements or PTC ceramic cores with IPX4 moisture protection. Seasonal demand spikes in northern states during winter months create inventory planning volatility for distributors.
Kitchen Appliances retain volume leadership; Personal Care Appliances hold the steepest expansion curve.
End User:
Customer archetypes span cost-conscious first-time owners in electrifying districts to premium-specification buyers in metro high-rises, each imposing distinct service and certification requirements.
- Residential Users:Urban nuclear families in Mumbai and Bengaluru prioritize smart connectivity and energy efficiency ratings, while rural tier-3 households in Rajasthan and Madhya Pradesh focus on durability and after-sales service accessibility. DISCOM time-of-day tariffs sharpen electricity cost sensitivity across both segments.
- Commercial Users:Co-working spaces and serviced apartments procure institutional-grade equipment with extended warranty terms and bulk maintenance contracts. EESL tenders increasingly capture this demand pool through centralized procurement.
- Hotels:Mid-scale and budget properties in Goa and Kerala's tourism corridors specify fire-retardant housings and voltage surge protection for guest room appliances. BIS CRS compliance is non-negotiable for property insurance coverage.
- Restaurants:Cloud kitchen operators in Pune and Gurgaon demand high-duty-cycle mixer grinders and induction arrays with rapid thermal recovery. Equipment downtime costs exceed capital outlay in this segment, favoring established brands with service networks.
Residential Users command absolute volume; Commercial Users are climbing the fastest as institutional procurement channels mature.
Distribution Channel:
Channel economics diverge sharply between asset-light digital platforms requiring working capital efficiency and fixed-cost retail networks demanding inventory turns.
- Online Retail:Amazon and Flipkart dominate with festival-season discounting and EMI financing penetration. Return logistics costs erode margins on bulky items like vacuum cleaners, constraining category participation.
- Specialty Stores:Croma and Reliance Digital outlets in metro malls enable tactile evaluation and immediate delivery. Staff commission structures favor high-margin personal care and smart appliance attachments.
- Supermarkets:BigBasket and DMart hyperlocal formats stock entry-tier kitchen appliances for impulse substitution purchases. Limited SKU depth restricts brand representation.
- Direct Sales:Eureka Forbes pioneered this model for water purifiers; residual application persists in tier-2 towns where digital literacy gaps persist. High customer acquisition costs limit scalability.
Online Retail leads transaction velocity; Specialty Stores are gaining share fastest through experience-driven premium conversion.
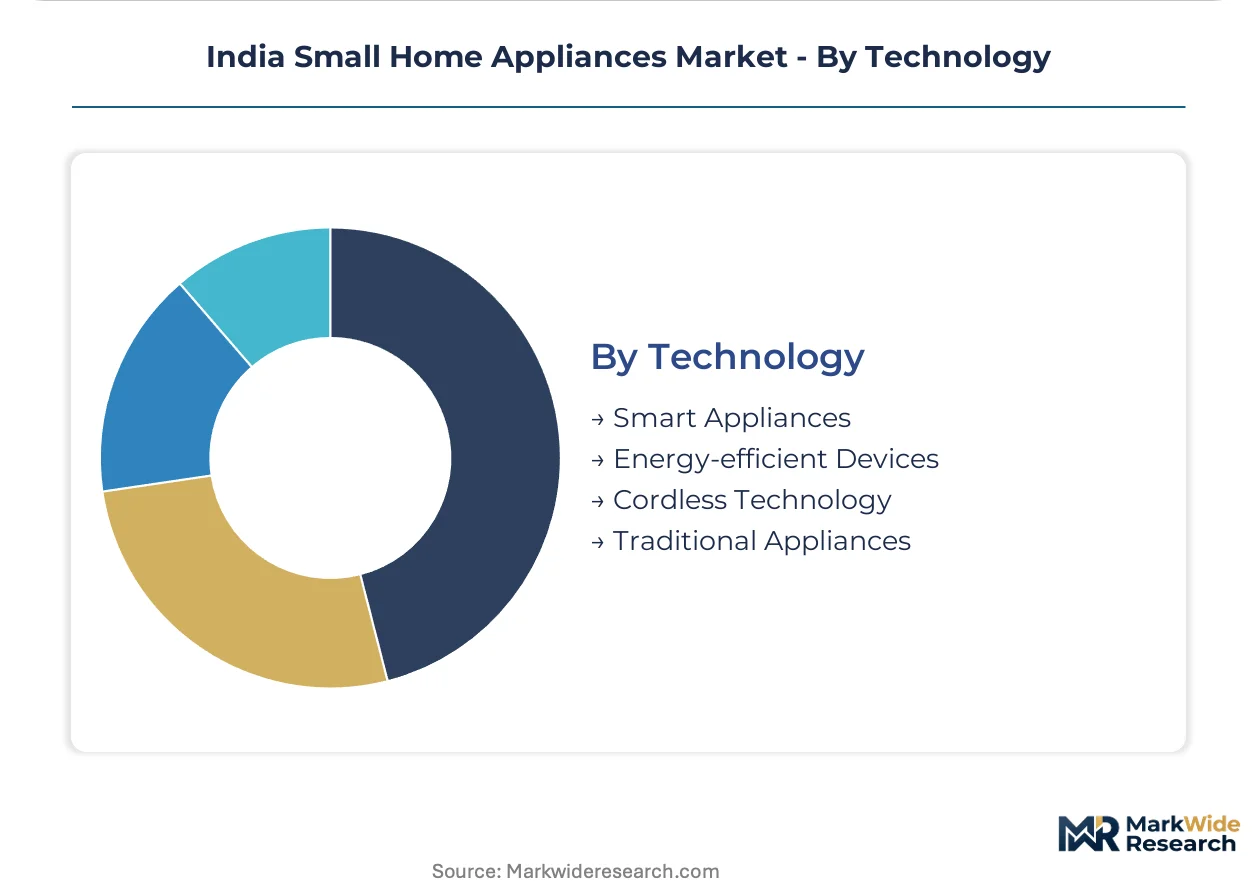
Technology:
Technology tiers stratify around energy efficiency mandates, semiconductor availability, and firmware development capabilities concentrated in Bengaluru and Hyderabad.
- Smart Appliances:Wi-Fi-enabled fans and induction cooktops integrate cloud-connected controllers for remote operation and usage analytics. Firmware talent scarcity in Pune manufacturing clusters delays product launch timelines.
- Energy-efficient Devices:BLDC motor platforms with variable frequency drives reduce power consumption 40-60% versus universal motor predecessors. PLI scheme subsidies for domestic motor production accelerate cost parity achievement.
- Cordless Technology:Lithium-ion battery packs enable portable vacuum cleaners and personal grooming tools. Cell sourcing concentration in East Asia creates supply vulnerability during trade disruptions.
- Traditional Appliances:Single-speed universal motor architectures persist in price-sensitive rural markets. Inventory clearance pressure intensifies as BIS efficiency mandates tighten.
Traditional Appliances retain installed base dominance; Smart Appliances are expanding most quickly as metro households upgrade connectivity infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western and southern states dominate appliance consumption through nuclear family density and higher electrification rates, while northern and eastern regions exhibit sharper seasonality and lower replacement frequency.
Maharashtra
Mumbai's compact nuclear households drive rapid replacement cycles for mixer grinders and induction cooktops. The state's BIS ISI certification requirements for household electrical goods mandate electromagnetic compatibility testing for all new product launches. Pune and Aurangabad host manufacturing clusters where component makers supply motors and controllers to tier-1 appliance brands.
Karnataka
Bengaluru's tech workforce sustains premium demand for smart-enabled kitchen appliances with Wi-Fi connectivity and precision temperature control. Karnataka's renewable purchase obligation regulations require manufacturers to source specified shares of power from solar and wind installations. The state's capital anchors firmware development talent pools that support BLDC motor controller design for fan and mixer grinder lines.
Tamil Nadu
Chennai's apartment complexes generate concentrated demand for compact cleaning appliances and personal grooming devices. Tamil Nadu's state-level RPO compliance thresholds vary from neighboring Karnataka, complicating pan-India production scheduling for multi-facility operators. Coimbatore's industrial belt houses precision temperature controller manufacturers supplying hair styling and inductive heating equipment makers.
Gujarat
Ahmedabad and Surat's merchant trading communities sustain wholesale channel volumes for entry-tier kitchen appliances. The state's grid electrification saturation in district towns unlocks first-time appliance ownership among previously underserved rural settlements. Vadodara's engineering institutes feed embedded systems talent into motor control firmware development pipelines.
Delhi-NCR
The capital's co-working space proliferation and serviced apartment expansion drive institutional procurement of extended-warranty appliances. Delhi's air quality alerts seasonally spike demand for air purifiers and related climate-control devices. Gurgaon's cloud kitchen operators specify high-duty-cycle equipment with rapid thermal recovery for commercial food preparation.
India Small Home Appliances Market Competitive Landscape
Capability concentration sits with integrated component manufacturers; scale advantage sits with distribution-heavy electrical conglomerates. The market structures around three tiers: vertically integrated specialists controlling motor and cable production, multi-category electrical houses leveraging rural retail networks, and global appliance brands importing premium positioning through R&D differentiation. Dominant competitive moves include backward integration into controller and motor manufacturing and EESL tender participation for institutional volume capture.
Among India-based electrical conglomerates, Havells India Ltd. and Bajaj Electricals Ltd. exemplify scale-driven distribution models, while Philips Domestic Appliances represents the premium R&D-intensive archetype. Havells anchors the integrated manufacturing tier through captive cable and motor operations. Bajaj Electricals occupies a position defined by tier-3 town penetration and district trade channel density. Philips exemplifies sustained technology investment in inductive heating and precision control systems.
| Leading Market Players |
|---|
| Havells India Ltd. |
| BSH Household Appliances |
| Philips Domestic Appliances |
| Whirlpool of India |
| Godrej Consumer Products Limited |
| Bajaj Electricals Ltd. |
| Panasonic India Pvt. Ltd. |
| LG Electronics |
| TTK Prestige Ltd. |
| Others |
Supply & Pricing Matrix
Undercapacity in Aurangabad's motor winding facilities is compressing supplier margins and forcing tier-1 manufacturers toward captive production investments, reshaping both procurement postures and end-product pricing across Maharashtra's appliance corridor.
Pricing Analysis
Long-term offtake contracts anchor procurement for copper winding wire and silicon steel laminations, insulating tier-1 manufacturers from LME spot volatility while informal assemblers absorb spot-market exposure. Pricing stratifies across ISI-certified premium tiers, BIS-CRS-compliant standard tiers, and uncertified economy tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying as BIS mandates tighten compliance timelines. Rural tier-3 households exhibit highest price sensitivity, while metro nuclear families prioritize energy efficiency ratings over absolute cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier relationships with East Asian semiconductor foundries, straining working capital for controller-dependent product lines. Component sourcing draws from China for lithium-ion cells, Taiwan for motor driver ICs, and domestic Maharashtra and Karnataka clusters for BLDC stator assemblies. Single-source vulnerability concentrates in precision temperature controller supply from Coimbatore. Distribution runs through multi-tier networks: direct-to-retail for metros, distributor-led for tier-2 towns, and wholesale mandi channels for rural penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India small home appliances market is cycling through a replacement-driven recovery phase, with metro nuclear family equipment refresh rates accelerating as pandemic-deferred purchases converge with BLDC upgrade incentives.
For Market Incumbents: Insulate margin stability by accelerating captive motor controller production in Pune and Aurangabad manufacturing clusters, countering semiconductor supply concentration risk from East Asian foundries. Deepen certification investment ahead of BIS electromagnetic compatibility threshold tightening to force informal competitor exit. Prioritize EESL tender participation for institutional volume capture that bypasses retail markup compression.
For New Entrants and Emerging Players: Tier-3 district towns in Rajasthan and Madhya Pradesh undergoing electrification saturation represent the most penetrable entry point for first-time appliance ownership, with lower certification compliance density and reduced incumbent service network coverage. Cloud kitchen equipment leasing in Gurgaon and Pune offers recurring revenue positioning. Pursue direct-to-installer go-to-market angles that bypass established distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart appliance sub-segments as firmware development and cloud connectivity infrastructure demands expand fixed-cost bases. Long-term viability over the next decade favors targets with demonstrated BLDC platform migration and state-level RPO compliance capabilities. Monitor PLI scheme extension announcements as inflection indicators for domestic component manufacturing competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Havells and tier-1 peers reduce copper wire cost exposure through captive Aurangabad winding facilities. |
| BIS CRS Certification Acceleration | Early compliance with electromagnetic compatibility thresholds forces informal assembler market exit. |
| EESL Tender Participation | Institutional procurement channels bypass retail margin compression for entry-tier volume capture. |
| Firmware Development Center Establishment | Bengaluru and Hyderabad talent pools enable BLDC controller design for smart appliance differentiation. |
| Tier-3 Distribution Network Expansion | Bajaj Electricals' district trade channel density secures first-mover advantage in electrifying settlements. |
Research Methodology
A spread of perspectives from appliance product managers at Havells and Bajaj Electricals, BIS certification laboratory directors in Mumbai and Delhi, DISCOM procurement officers in Maharashtra and Karnataka, and EESL tender evaluation committees converged on the working assumptions. These primary insights combined with secondary validation from BIS CRS registration databases, PLI scheme disbursement records, state electricity regulatory commission RPO compliance filings, and customs import data for semiconductor components. Bottom-up channel volume estimates triangulated against top-down electrification penetration models.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeled across product type, end-user archetype, distribution channel, and technology tier dimensions. CAGRs derived from replacement cycle velocity in metro nuclear families and first-time ownership curves in electrifying districts. Industry-specific forecast inputs incorporated DISCOM time-of-day tariff implementation timelines and BIS compliance deadline sequencing.
Macroeconomic conditions sit as an overlay; deviation in rural electrification subsidy disbursement rates or LME copper price volatility bands would shift the trajectory. Forecasts reflect documented assumptions regarding PLI scheme continuity and BIS enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Washing Machine Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Russia Home Appliances Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
Side-By-Side Smart Refrigerator Market