
 Smart Home Connect Dishwasher Market | 2026-2036
Smart Home Connect Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Connect Dishwasher Market Insights
Modular smart home packages that bundle connected dishwashers with unified control hubs is realigning buyer choice across premium residential segments. Samsung Electronics leverages its SmartThings ecosystem to anchor appliance interoperability in North American developments. Bosch competes through specialized energy-efficient motor platforms that sustain margin pools in European markets. Midea dominates cost-optimized manufacturing scale across Asia-Pacific distribution channels.
A smart home connect dishwasher integrates water-level sensors, soil-detection algorithms, and cloud-based cycle optimization through Wi-Fi, Bluetooth, Zigbee, or Thread protocols to automate dish cleaning with remote monitoring and predictive maintenance capabilities. Built-in configurations lead residential installations due to seamless kitchen integration and higher average selling prices, while Thread connectivity represents the fastest-expanding protocol segment as Matter standard adoption accelerates across device ecosystems. Energy-efficient features command the deepest margin pools as utility rebate programs and Ecodesign labeling requirements shift procurement criteria toward connected load-management capabilities.
The EU Ecodesign Directive and Energy Labeling Framework regulate minimum efficiency thresholds and connected standby power limits for smart dishwashers sold across member states, while the FCC in the United States governs wireless transmission standards for Wi-Fi and Zigbee radio modules. China's GB standards and MIIT connectivity certifications shape product access requirements for domestic manufacturers exporting to international markets. Stakeholders must monitor evolving interoperability mandates and cybersecurity disclosure rules as regulatory scope expands beyond energy efficiency into data governance and device authentication protocols.
Market Dynamics
The EU Ecodesign Directive and California water-efficiency standards are forcing manufacturers to embed sensor-driven connectivity as a baseline requirement, compressing development cycles and reshaping supplier qualification criteria across residential appliance supply chains.
Growth Catalysts
- EU Ecodesign Directive:Mandates connected standby power limits and minimum efficiency thresholds, accelerating R&D investment in cloud-optimized motor platforms across member states.
- Smart home ecosystem bundling:Luxury residential developers in New York, London, and Singapore are standardizing Wi-Fi-enabled units with unified control hubs, creating specification pull-through at the project level.
- Soil-detection algorithms:Machine learning-driven cycle optimization reduces water consumption per load, aligning with utility rebate programs that favor connected load-management capabilities.
Market Restraints
- Semiconductor input volatility:Wi-Fi, Zigbee, and Thread radio modules depend on constrained foundry capacity, creating bill-of-materials unpredictability for mid-tier manufacturers.
- Supply concentration in China:Midea and Haier control tier-one city distribution channels, creating barriers for foreign entrants seeking cost-competitive manufacturing scale.
- Cybersecurity disclosure friction:Expanding regulatory scope into device authentication protocols extends product certification timelines without harmonized international standards.
Strategic Opportunities
- Thread protocol acceleration:Matter standard adoption creates interoperability white space for manufacturers able to certify cross-platform compatibility ahead of ecosystem consolidation.
- Utility-driven procurement models:Connected load-management capabilities unlock demand response program participation, creating new channel relationships with energy retailers.
- Predictive maintenance service layers:Cloud-based cycle data enables subscription revenue streams from water-level sensor analytics and automated consumable replenishment.
Industry Challenges
- Embedded systems talent scarcity:Firmware development for multi-protocol stacks (Wi-Fi, Bluetooth, Zigbee, Thread) outpaces available engineering capacity in European and North American markets.
- Legacy kitchen integration complexity:Retrofit installations face physical constraints that limit sensor placement and cloud connectivity reliability in aging residential stock.
- Certification timeline compression:Simultaneous FCC wireless transmission approvals, EU energy labeling, and MIIT connectivity certifications create parallel compliance bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Connect Dishwasher Market |
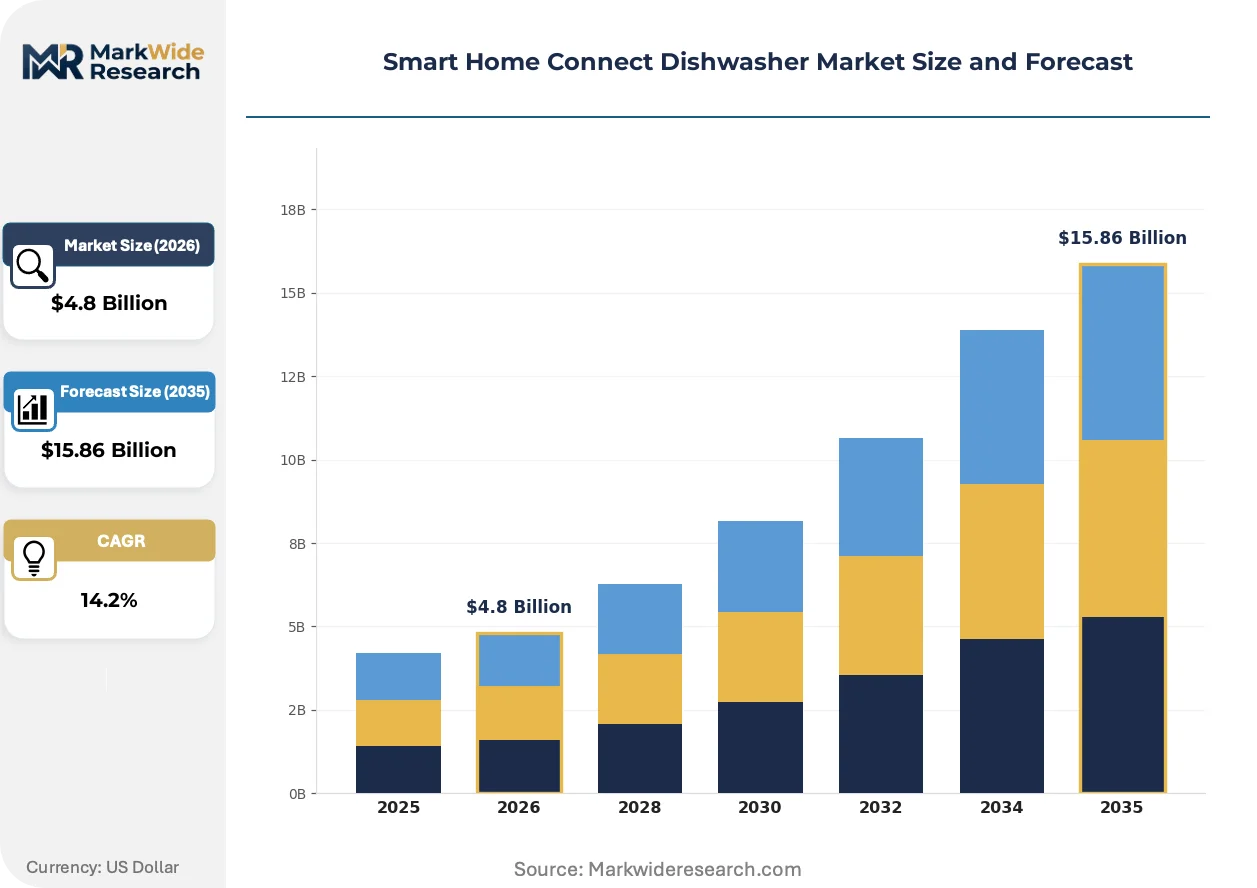
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Portable, Drawer, Under-counter Connectivity: Wi-Fi, Bluetooth, Zigbee, Thread End User: Residential, Commercial, Industrial, Cooperative Features: Smart Controls, Energy Efficient, Noise Reduction, Self-cleaning |
| Companies Covered | Samsung Electronics, LG Electronics, GE Appliances, Bosch, Whirlpool Corporation, Haier, Siemens, Midea, Miele, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Connect Dishwasher Market Trends and Innovations
Connectivity protocol convergence and regulatory energy mandates are compressing product development cycles while shifting competitive differentiation from hardware specifications to software-defined service capabilities.
Thread connectivity is unifying previously fragmented smart home ecosystems under the Matter standard, enabling cross-brand interoperability that was technically impossible under proprietary Zigbee implementations. Bosch and Samsung Electronics are certifying dishwashers for Matter compatibility ahead of 2025 ecosystem rollouts. This unifying architecture is compressing the addressable market for single-protocol specialists and favoring manufacturers with multi-platform firmware capabilities.
California's tightening water-efficiency standards are mandating connected sensor feedback loops that automatically adjust cycle parameters based on real-time soil detection. The industrial consequence is a shift from standalone appliance sales to bundled water-management solutions. European manufacturers are responding fastest, leveraging existing Ecodesign compliance infrastructure to meet California's thresholds with minimal product reconfiguration.
Buyers in China's tier-one cities are consolidating procurement decisions at the property developer level rather than individual consumer choice, shifting channel power toward smart home system integrators. Haier and Midea are capturing this consolidation through direct specification relationships with luxury apartment developers. This concentration is most visible in Shanghai and Shenzhen, where bundled amenity packages now determine dishwasher brand presence before residents occupy units.
Smart Home Connect Dishwasher Market Segmentation
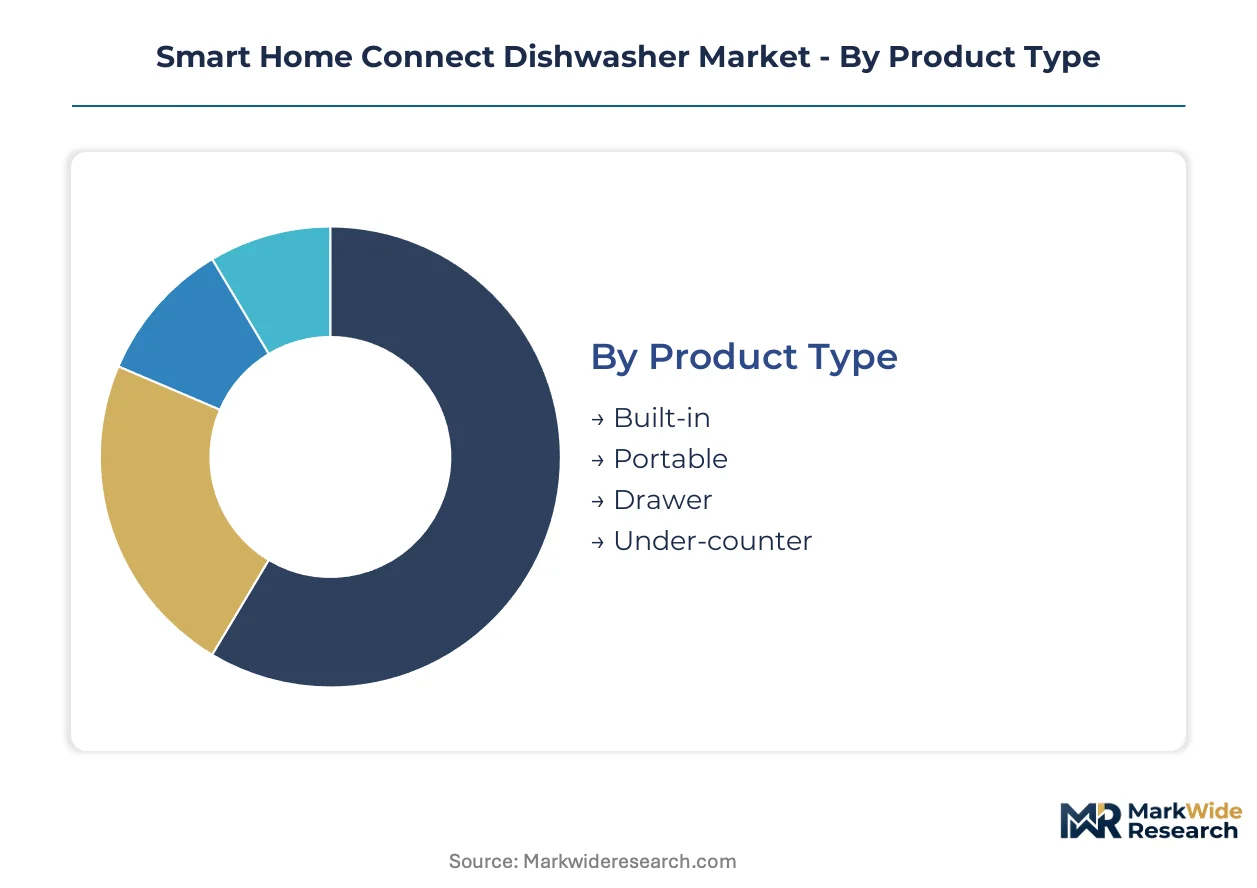
Smart home connect dishwasher segmentation reveals how connectivity protocols, installation formats, and feature bundles reshape procurement patterns across residential and commercial channels. Manufacturers calibrate R&D investment and channel strategy against these axes to capture specification pull-through in luxury developments and utility-driven retrofit programs.
Product Type:
Installation format determines margin structure, sensor integration depth, and developer specification rates in premium residential construction.
- Built-in:These units integrate seamlessly beneath countertops with concealed control panels and hardwired connectivity modules. Demand concentrates in New York, London, and Singapore luxury apartment developments where developers bundle Wi-Fi-enabled units as standard amenities, driven by specification requirements for unified smart home ecosystems.
- Portable:Freestanding units with external water connections and plug-in Wi-Fi modules serve rental markets and temporary installations. Adoption clusters in China's tier-one cities where Midea and Haier dominate cost-optimized distribution through direct developer relationships, constrained by limited soil-detection algorithm sophistication.
- Drawer:Dual-drawer configurations enable simultaneous cycle separation with independent cloud connectivity per compartment.
- Under-counter:Compact units fit standardized cabinetry dimensions with modular radio module slots for protocol flexibility.
Mature deployment sits with Built-in configurations. Newer deployment is concentrated in Drawer formats as space-optimized kitchen designs gain specification traction.
Connectivity:
Protocol selection governs interoperability certification costs, ecosystem bundling opportunities, and firmware development complexity across regional regulatory environments.
- Wi-Fi:Direct cloud connectivity enables remote monitoring and over-the-air cycle optimization without hub dependency. Deployment dominates North American residential channels where FCC transmission standards govern radio module approvals, though standby power consumption creates EU Ecodesign compliance friction.
- Thread:Mesh networking architecture enables cross-brand interoperability under the Matter standard with ultra-low power consumption. Certification pipelines accelerate fastest across European and North American markets as Bosch and Samsung Electronics prioritize Matter compatibility ahead of ecosystem consolidation, climbing the fastest among protocol segments.
- Bluetooth:Short-range pairing suits hub-proximate installations with minimal latency for cycle initiation.
- Zigbee:Proprietary mesh implementations retain installed base in legacy smart home systems pending Matter migration.
Established volume sits with Wi-Fi modules. Steepest expansion trajectory is concentrated in Thread as Matter standard adoption compresses single-protocol addressable markets.
End User:
Procurement authority and specification timing vary sharply across customer types, shifting channel power toward property developers or facility managers.
- Residential:Individual homeowners and rental tenants purchase through retail or landlord-provisioned channels. China's tier-one cities show accelerating consolidation at the developer level where Haier and Midea capture specification decisions before occupancy, displacing traditional retail-driven selection.
- Commercial:Restaurants, hotels, and institutional kitchens demand industrial-grade soil-detection and predictive maintenance capabilities. California's tightening water-efficiency standards mandate connected sensor feedback loops for cycle optimization, creating compliance-driven specification pull-through in hospitality retrofits.
- Industrial:High-throughput food processing facilities require stainless-steel construction with HACCP-aligned cloud logging.
- Cooperative:Shared housing developments and coliving spaces prioritize multi-user access control and usage-based billing integration.
Volume concentration sits with Residential procurement. Fastest share gain is occurring in Commercial segments as utility rebate programs favor connected load-management capabilities.
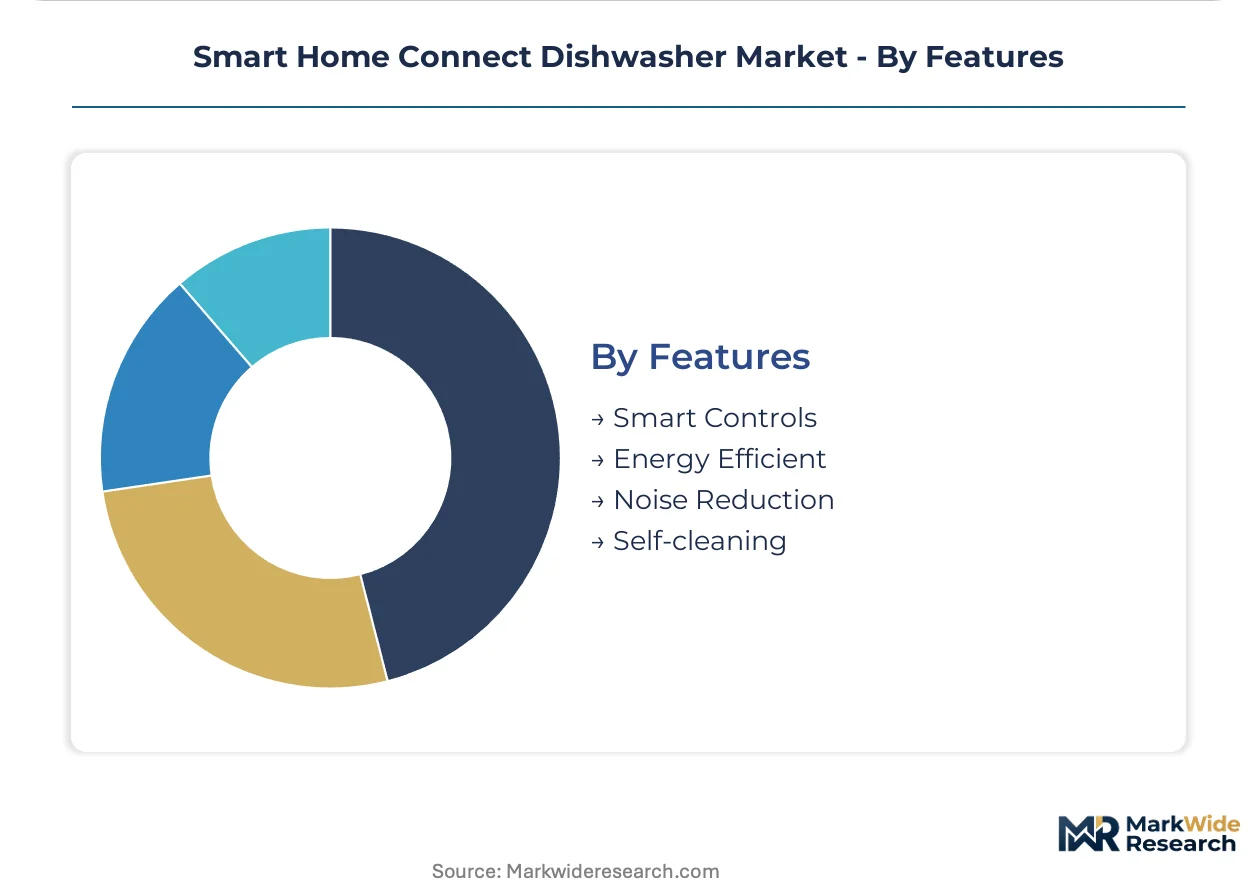
Features:
Feature bundling determines margin pools and regulatory qualification for incentive programs across energy and water efficiency mandates.
- Energy Efficient:Variable-speed motor platforms and heat-pump drying systems minimize connected standby power and per-cycle consumption. These configurations command the deepest margin pools as EU Ecodesign labeling requirements and California utility rebate programs shift procurement criteria toward connected load-management capabilities.
- Smart Controls:Soil-detection algorithms and cloud-based cycle optimization enable predictive maintenance and automated consumable replenishment. Machine learning-driven water-level sensor analytics reduce consumption per load, aligning with utility-driven procurement models that unlock demand response program participation.
- Noise Reduction:Insulated cabinetry and brushless motor designs target open-plan kitchen installations in premium developments.
- Self-cleaning:Automated filter maintenance and descaling cycles reduce service intervention frequency in commercial deployments.
Regulatory qualification sits with Energy Efficient features. Emerging specification pull-through is concentrated in Smart Controls as subscription revenue models gain traction among manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury apartment developments in New York, London, and Singapore function as concentrated demand zones where Wi-Fi-enabled dishwashers bundle with unified smart home systems as standard amenities. China's tier-one cities anchor manufacturing scale through Midea and Haier distribution control. The EU Ecodesign Directive and California water-efficiency standards compress development cycles across three continents.
United States
California's tightening water-efficiency standards mandate connected sensor feedback loops for automatic cycle adjustment. The FCC governs wireless transmission standards for Wi-Fi and Zigbee radio modules. New York luxury developments standardize Wi-Fi-enabled units with unified control hubs, creating specification pull-through at the project level.
Germany
The EU Ecodesign Directive mandates connected standby power limits and minimum efficiency thresholds across member states. Bosch leverages specialized energy-efficient motor platforms to sustain margin pools in domestic and export markets. Berlin and Munich anchor R&D concentration for cloud-optimized motor platforms.
China
MIIT connectivity certifications and GB standards shape product access requirements for domestic manufacturers exporting internationally. Midea and Haier control tier-one city distribution channels in Shanghai and Shenzhen. Property developers bundle smart home amenity packages before resident occupancy, displacing retail-driven selection.
Singapore
Luxury residential developments standardize Wi-Fi-enabled dishwashers with unified control hubs as baseline amenities. The country's building codes emphasize water efficiency in high-density vertical construction. Marina Bay and Orchard Road clusters concentrate specification decisions at the developer level.
United Kingdom
London luxury apartment developers bundle connected appliances with smart home ecosystems as competitive differentiators. The EU Ecodesign Directive's efficiency thresholds apply during the post-Brexit transition alignment period. Canary Wharf and Kensington developments concentrate specification pull-through for built-in configurations.
Smart Home Connect Dishwasher Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across protocol certification and ecosystem bundling vectors. The market exhibits tiered concentration where scale-driven manufacturers face margin pressure from software-defined service capabilities. Three archetypes dominate: ecosystem-anchored electronics conglomerates, energy-efficiency-focused European industrial groups, and cost-optimized Asian manufacturing specialists. Competitive moves center on Matter standard certification acceleration and predictive maintenance service layer development.
Within the ecosystem-anchored tier, Samsung Electronics represents multi-platform firmware capabilities through SmartThings integration. Bosch exemplifies the energy-efficiency archetype with Ecodesign compliance infrastructure. Midea occupies the cost-optimized manufacturing position across Asia-Pacific distribution channels.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| GE Appliances |
| Bosch |
| Whirlpool Corporation |
| Haier |
| Siemens |
| Midea |
| Miele |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between Matter-compatible Thread units and legacy Wi-Fi-only configurations splits both pricing power and supplier qualification criteria across the smart home connect dishwasher market. Premium Thread-certified products command specification preference in New York and Singapore luxury developments, while commodity Wi-Fi modules face margin compression from constrained foundry capacity and Chinese manufacturing scale.
Pricing Analysis
Short lead-time premiums for Thread radio modules with Matter certification run 15-20% above standard Wi-Fi configurations in North American channels. Three-tier pricing structure across premium Matter-certified, standard Wi-Fi-enabled, and economy Bluetooth-paired levels reflects certification investment and firmware complexity. Cost compression in mid-tier Wi-Fi segments intensifies because semiconductor input volatility from constrained foundry capacity elevates bill-of-materials unpredictability. Property developers in China's tier-one cities show least price sensitivity given bundled amenity procurement, while rental market buyers in portable segments exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Midea and Haier's developer specification relationships in Shanghai and Shenzhen. Manufacturing concentrates in China, Germany, and South Korea, with Bosch anchoring European motor platform production and Samsung Electronics sourcing from Korean fabs for SmartThings integration. Radio module supply draws from constrained Taiwan and China foundry capacity, creating single-source vulnerability for Thread and Zigbee chipsets. Distribution runs through smart home system integrators in luxury residential developments and traditional appliance retail for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around ecosystem-anchored players as Matter standard adoption forces single-protocol specialists toward acquisition or exit. Regulatory energy mandates and certification timeline compression disproportionately burden smaller manufacturers lacking multi-platform firmware capabilities.
For Market Incumbents: Extend Matter certification pipelines ahead of ecosystem lock-in by Bosch and Samsung Electronics. Acquire embedded systems talent in Berlin and Munich to address firmware development scarcity for multi-protocol stacks. Deepen control over Thread radio module supply through captive relationships with Taiwanese foundry partners, insulating against semiconductor volatility that threatens mid-tier competitors.
For New Entrants and Emerging Players: Launch via utility-driven procurement channels targeting California hospitality retrofits and European demand response programs. White-space availability concentrates in predictive maintenance service layers and automated consumable replenishment subscriptions. Penetrate commercial segments where connected load-management capabilities unlock rebate program participation, avoiding saturated residential specification battles dominated by incumbent developer relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with energy-efficiency-focused European industrial groups given EU Ecodesign Directive acceleration and California water-efficiency alignment. Long-term viability favors manufacturers with cloud-optimized motor platforms and existing Ecodesign compliance infrastructure. Monitor Thread protocol certification velocity as inflection indicator for ecosystem consolidation timing and acquisition target valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Standard Certification | Cross-platform interoperability unlocks specification access in SmartThings and Apple HomeKit ecosystems. |
| Predictive Maintenance Service Launch | Cloud-based water-level sensor analytics enable recurring revenue from automated detergent replenishment. |
| Thread Radio Module Backward Integration | Captive supply of ultra-low-power chipsets insulates margins from foundry capacity constraints. |
| Utility Partnership Development | Demand response program participation creates channel bypass around traditional retail concentration. |
| Embedded Systems Talent Acquisition | Multi-protocol firmware capabilities compress development cycles for simultaneous FCC and EU approvals. |
Research Methodology
Multi-period observation of Matter certification pipelines, utility rebate program enrollment, and developer specification rates anchored the trend analysis, supplemented by interviews with smart home system integrators, appliance procurement directors at luxury residential developers, firmware engineering leads, and regulatory compliance officers at major manufacturers. Secondary validation drew from FCC equipment authorization databases, EU Ecodesign implementing measure texts, MIIT connectivity certification registries, and SEC 10-K filings from diversified electronics conglomerates. Bottom-up shipment estimates by connectivity protocol and installation format triangulated against top-down construction spending projections for premium residential developments.
Input-output matrix modeling connected macro drivers including regulatory energy mandates, semiconductor foundry capacity utilization, and smart home ecosystem adoption curves to segment-level demand forecasts across the projection horizon. Segmentation dimensions included installation format, connectivity protocol, end-user category, and feature bundle tier. CAGRs derived from regression analysis of historical premium residential construction permits against appliance specification rates, with cross-validation against utility rebate program budget allocations and manufacturer R&D disclosure patterns.
The model assumes a particular technology adoption path; alternative pathways for Thread protocol penetration would alter the outlook if proprietary Zigbee implementations retain installed base longer than projected. Forecasts reflect assumptions regarding Matter standard enforcement timelines and foundry capacity expansion trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Europe White Goods Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
China Small Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
China Home Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
India Small Home Appliances Market