
 Household Fridge Market | 2026-2036
Household Fridge Market Size, Share, and Industry Trends Forecast 2026-2036
Household Fridge Market Analysis
A shift from single-source compressor procurement to multi-source qualification is restructuring supply economics for household refrigerator manufacturers. Samsung Electronics leverages its in-house semiconductor division to control inverter compressor chip supply. LG Electronics anchors its competitive stance through frost-free platform standardization across price tiers. Haier Smart Home dominates emerging-market distribution through localized assembly networks.
A household refrigerator is an electrically powered thermal insulation cabinet that maintains food-storage temperatures between 0°C and 5°C in fresh compartments and below −18°C in freezer sections, using vapor-compression refrigeration cycles with isobutane or R-600a refrigerant. Its primary purpose is to extend perishable food shelf life and reduce household waste in residential settings. French door configurations now capture premium margin pools in North American and European kitchens where width and aesthetic integration command price premiums. Inverter compressor technology is displacing conventional fixed-speed units as energy-efficiency regulations tighten across major markets. Smart connectivity remains a niche feature with concentrated demand from tech-forward single households rather than mass-market rental properties.
The US Department of Energy enforces minimum energy conservation standards that dictate compressor efficiency thresholds and insulation foam specifications. The EU Ecodesign Directive and F-Gas Regulation jointly restrict refrigerant global warming potential and mandate repairability labeling, altering product development priorities for exporters. China's GB standards and energy-efficiency labeling program create a parallel compliance track for domestic manufacturers and foreign entrants. Stakeholders must monitor regulatory divergence between efficiency metrics and refrigerant phase-down timelines when allocating R&D budgets across regional product portfolios.
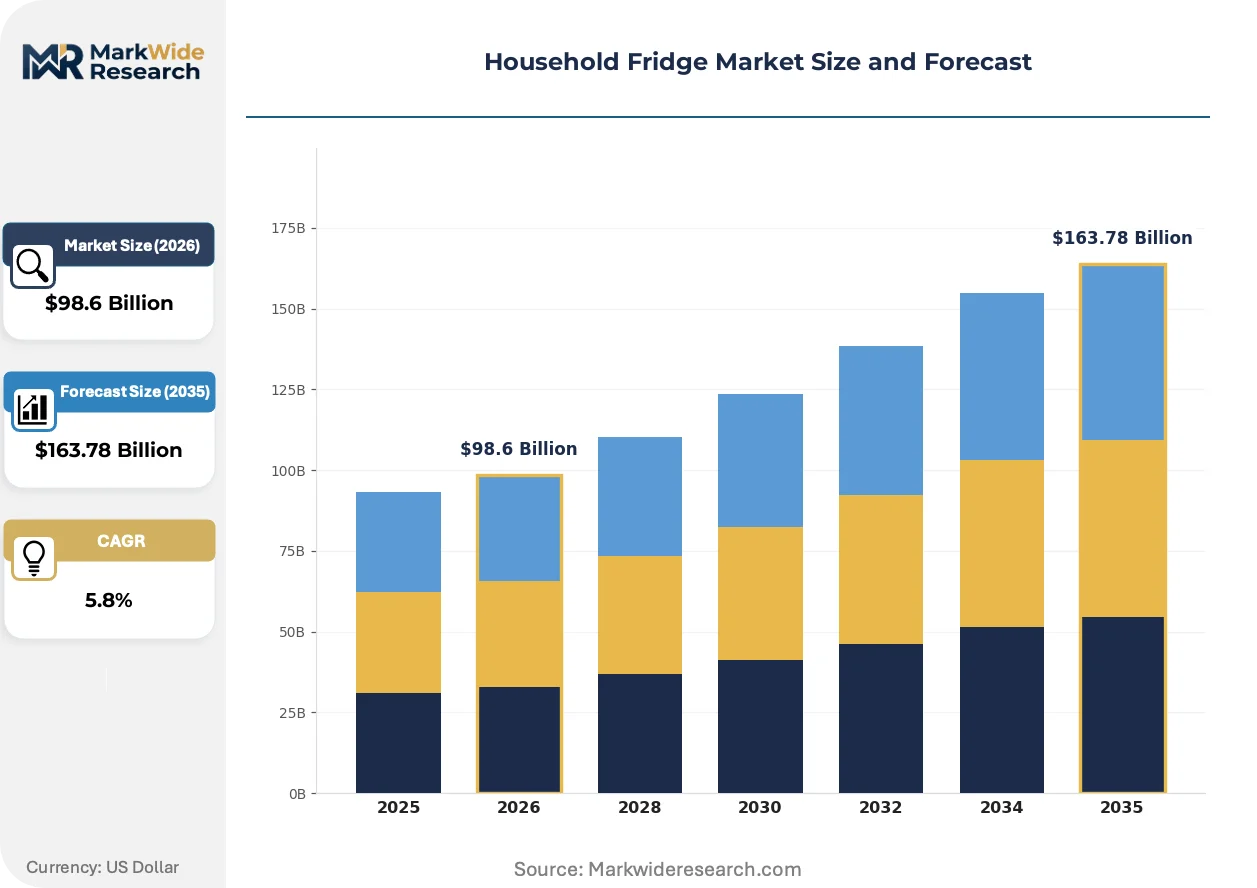
Market Dynamics
Inverter compressor technology is forcing wholesale redesigns of refrigeration platforms as energy-efficiency mandates tighten across major economies. Manufacturers must simultaneously qualify multiple compressor suppliers while retooling assembly lines for variable-speed electronics.
Growth Catalysts
- Urban co-living expansion:Rental property portfolios in China, India, and Brazil are scaling appliance procurement volumes as multi-unit residential construction accelerates.
- US DOE efficiency standards:Periodic tightening of minimum energy conservation standards compels compressor redesigns that favor higher-margin inverter platforms.
- Emerging middle-class formation:First-time upgraders across Brazil and India are concentrating replacement demand for frost-free configurations.
Market Restraints
- Copper and steel input volatility:Compressor housings and heat exchanger tubing face raw material price swings that compress margin predictability.
- Refrigerant supply concentration:Isobutane and R-600a production clusters in select chemical manufacturing regions create procurement risk.
- EU F-Gas Regulation friction:Repairability labeling mandates and global warming potential restrictions extend product development timelines for exporters.
Strategic Opportunities
- Localized assembly networks:Brazil and India offer white space for regional production hubs that bypass import tariff structures.
- Smart connectivity convergence:Integration of IoT sensors with inverter control systems creates premium positioning for tech-forward single households.
- Channel innovation via property management platforms:Bulk procurement relationships with institutional landlords bypass traditional retail markups.
Industry Challenges
- Variable-speed electronics skill gap:Inverter compressor programming and motor control expertise remains scarce in legacy appliance engineering teams.
- Dual certification complexity:Parallel compliance tracks for China's GB standards and EU Ecodesign Directive strain regulatory affairs bandwidth.
- Legacy platform integration:Frost-free architectures require fundamental retooling of insulation foam injection and door-sealing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Fridge Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $163.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Freezer, Bottom Freezer, Side-by-Side, French Door, Compact, Mini Technology: Direct Cool, Frost Free, Inverter Compressor, Smart Connectivity, Energy Efficient Application: Single Household, Shared Housing, Rental Properties, Vacation Homes, Co-Living Spaces, Dormitories Distribution Channel: Specialty Electronics Stores, Large Retail Chains, E-Commerce Platforms, Appliance Wholesalers, Local Dealers |
| Companies Covered | Whirlpool Corporation, Samsung Electronics, LG Electronics, Haier Smart Home, AB Electrolux, Robert Bosch GmbH, Panasonic Corporation, GE Appliances, Midea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Fridge Market Emerging Trajectories
Refrigeration platforms are absorbing semiconductor-enabled control systems that transform fixed mechanical cycles into adaptive thermal management. This shift is compressing development timelines while expanding the boundary between appliance and electronics supply chains.
Variable-speed inverter compressors are absorbing power electronics that modulate cooling output to match thermal load rather than cycling on-off. Property developers specifying for rental portfolios are adopting these platforms to meet lease-mandated utility allowances. The technology is absorbing margin from conventional fixed-speed units as efficiency regulations harden.
The EU F-Gas Regulation and Ecodesign Directive are jointly restricting refrigerant global warming potential and mandating repairability labeling. Exporters must redesign sealing systems and document component accessibility for European customs clearance. French door configurations for North American kitchens face the steepest compliance cost increases due to larger refrigerant charges.
Institutional landlords are consolidating appliance procurement through property management platforms that negotiate direct manufacturer relationships. Traditional retail channels serving individual homeowners are losing volume share in urban rental corridors. This pattern is most visible in Chinese and Indian metropolitan markets where co-living operators standardize unit specifications across portfolios.
Household Fridge Market Segmentation
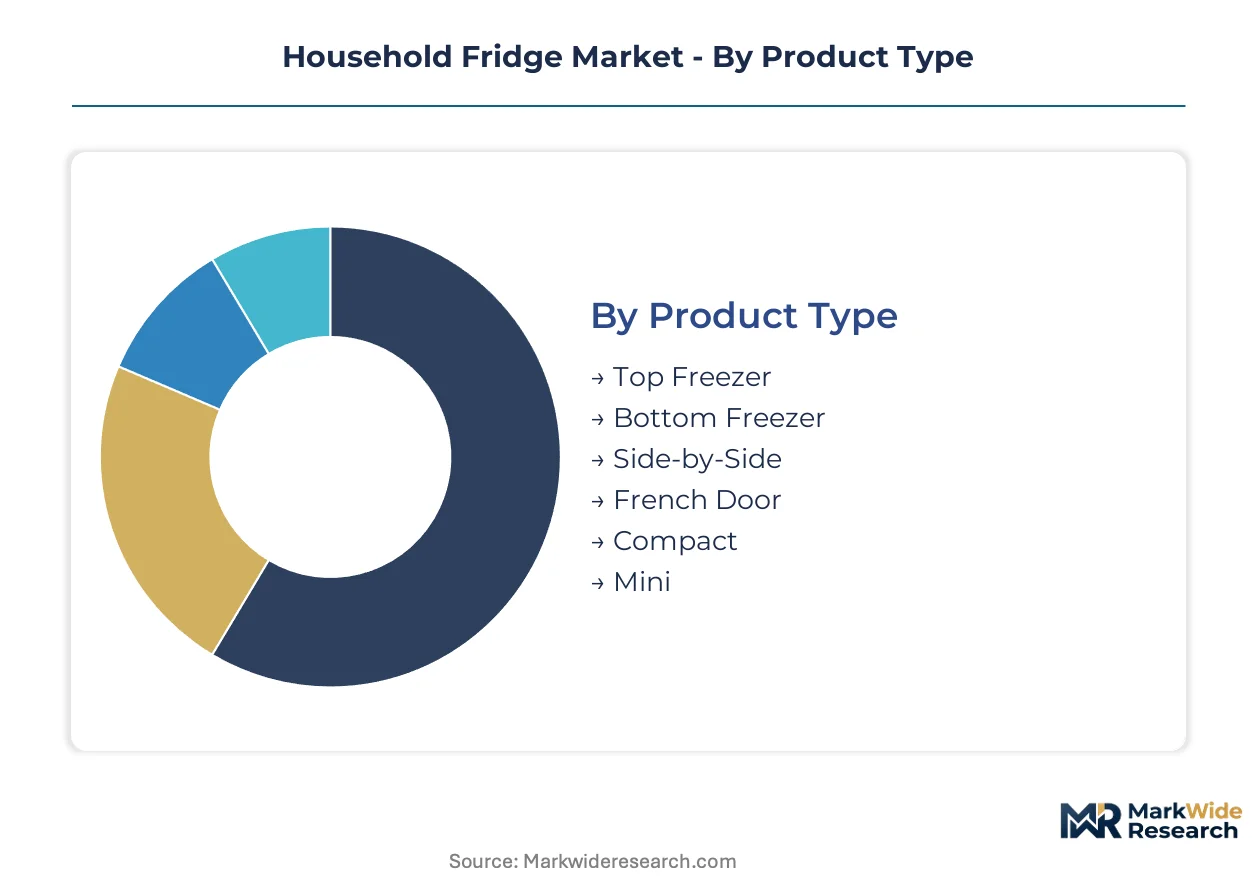
Segmentation in the household refrigerator market reveals how procurement patterns split between institutional bulk buyers and individual consumers. Understanding these divides helps manufacturers align platform investments with channel economics and regulatory exposure.
Product Type:
Supply concentration for door configurations varies sharply by regional kitchen architecture and margin structure.
- French Door:Dual-refrigerator compartments with bottom-mount freezer drawers maximize usable width for countertop-depth installations. Demand concentrates in US suburban renovations where kitchen island sightlines drive aesthetic premiums alongside DOE efficiency thresholds.
- Side-by-Side:Vertical split between fresh and frozen compartments optimizes narrow kitchen footprints. US and Brazilian apartment developers specify these for rental portfolios where door swing clearance is constrained.
- Top Freezer:Conventional over-under configuration dominates replacement cycles in price-sensitive markets.
- Bottom Freezer:Eye-level fresh food access commands modest premiums in European retrofit markets.
- Compact:Under-counter and counter-height units serve secondary refrigeration needs in vacation properties.
- Mini:Dormitory and co-living operators in India and China procure these for individual room allocations.
French door configurations absorb the bulk of installed capacity in premium North American kitchens; compact units are expanding most quickly through institutional co-living procurement.
Technology:
Cost tier stratification separates legacy mechanical platforms from semiconductor-enabled control systems.
- Inverter Compressor:Variable-speed motor control modulates refrigerant flow to match thermal load rather than cycling fixed output. Property management platforms in Chinese and Indian urban corridors specify these to meet lease-mandated utility allowances as GB standards and BEE labeling tighten.
- Frost Free:Forced-air circulation with automatic defrost cycles eliminates manual ice removal. Brazil and India's emerging middle-class replacement demand concentrates here as first-time upgraders abandon direct-cool units.
- Direct Cool:Natural convection cooling with manual defrost retains cost leadership in rural price-sensitive segments.
- Smart Connectivity:IoT-enabled temperature monitoring and energy diagnostics serve tech-forward single households in Seoul and Tokyo.
- Energy Efficient:Insulation foam and compressor combinations optimized for EU Ecodesign Directive thresholds.
Frost free platforms absorb the bulk of installed capacity across emerging-market upgrade cycles; inverter compressor systems are expanding most quickly through regulatory mandate compliance.
Application:
Customer type determines whether procurement flows through retail markup structures or direct manufacturer negotiation.
- Rental Properties:Institutional landlords consolidate appliance specifications across multi-unit portfolios to streamline maintenance and warranty administration. China's rental housing construction targets and Brazil's Minha Casa Minha Vida program concentrate volume here.
- Co-Living Spaces:Shared kitchen facilities in urban density projects require durable, standardized units with minimal feature variation. Operators in Mumbai, São Paulo, and Shenzhen negotiate direct procurement relationships bypassing traditional retail.
- Single Household:Individual homeowners drive feature differentiation and premium positioning in developed markets.
- Shared Housing:Roommate arrangements split demand between full-size and supplementary refrigeration.
- Vacation Homes:Seasonal occupancy patterns favor compact or mini configurations with standby efficiency.
- Dormitories:University housing authorities in India and China specify mini units for individual student rooms.
Rental properties absorb the bulk of institutional procurement volume; co-living spaces are climbing the fastest as urban density policies accelerate in Asia-Pacific and Latin American metros.
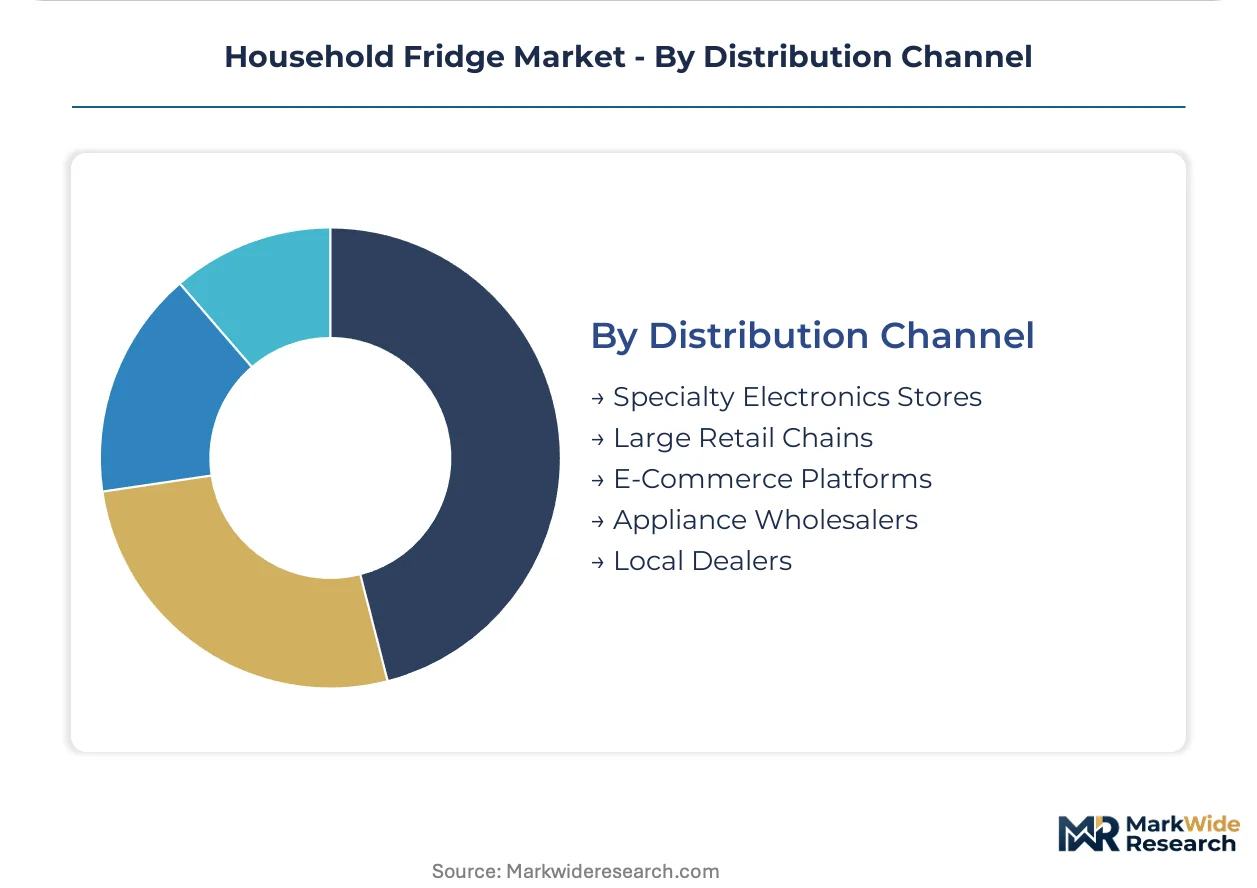
Distribution Channel:
Volume concentration shifts from retail footprint toward platform-mediated bulk purchasing.
- E-Commerce Platforms:Online marketplaces aggregate price transparency and delivery logistics for replacement purchases. India's Flipkart and Amazon India, plus China's JD.com and Tmall, capture urban appliance procurement as smartphone penetration deepens.
- Appliance Wholesalers:Regional distributors serve contractor and developer channels with volume pricing and staging coordination. Brazilian and Indian construction booms sustain this channel for multi-unit project fulfillment.
- Specialty Electronics Stores:Kitchen design showrooms retain relevance for premium configuration selection.
- Large Retail Chains:Big-box formats anchor replacement demand in suburban US and European markets.
- Local Dealers:Independent retailers penetrate rural and small-town service territories with installation and repair bundling.
Appliance wholesalers absorb the bulk of new construction procurement; e-commerce platforms are gaining share fastest as urban consumers shift replacement purchasing online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel coil from Baoshan anchors Chinese compressor housing supply chains. Copper cathode from Chilean mines feeds heat exchanger tubing across Asian assembly networks. These material flows concentrate manufacturing investment in coastal industrial zones with port access.
United States
Suburban kitchen renovations and rental property portfolios drive French door and side-by-side procurement. The US Department of Energy periodically tightens minimum energy conservation standards, compelling inverter compressor redesigns. Manufacturing clusters in the Midwest and Southeast serve domestic demand with integrated assembly and distribution networks.
China
Urban co-living construction and emerging middle-class upgrades concentrate volume in frost-free configurations. GB standards and the national energy-efficiency labeling program create compliance requirements for domestic and foreign manufacturers. Yangtze River Delta assembly hubs leverage localized component ecosystems for cost-competitive export production.
India
First-time upgraders from direct-cool to frost-free platforms and institutional rental housing procurement expand market depth. Bureau of Energy Efficiency labeling mandates and the Bureau of Indian Standards certification framework shape product specifications. Maharashtra and Gujarat industrial corridors host regional assembly operations serving domestic and South Asian export markets.
Brazil
Minha Casa Minha Vida program targets and urban rental construction concentrate demand for standardized appliance specifications. ANVISA and INMETRO regulations govern product safety and energy efficiency compliance. São Paulo state anchors manufacturing investment with established supplier networks and port logistics for Mercosur distribution.
Germany
Premium kitchen retrofit cycles and repairability-conscious consumers sustain high-value segment demand. The EU Ecodesign Directive and F-Gas Regulation jointly restrict refrigerant global warming potential and mandate component accessibility documentation. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate engineering-intensive platform development for European market supply.
Household Fridge Market Vendor Landscape
Global majors compete with regional champions across technology platforms and distribution reach. Market structure tilts toward consolidated tier-one players with captive compressor supply and fragmented regional assemblers serving price-sensitive segments. Three archetypes dominate: vertically integrated electronics conglomerates, specialized appliance OEMs with platform standardization strategies, and emerging-market champions leveraging localized assembly networks. Competitive moves center on multi-source compressor qualification and direct procurement relationships with institutional property developers bypassing traditional retail channels.
Within the integrated electronics tier, Samsung Electronics and LG Electronics anchor competitive positioning through semiconductor-enabled control systems and platform breadth. Haier Smart Home exemplifies the emerging-market champion archetype with distribution depth across Asia-Pacific and Latin American corridors. Robert Bosch GmbH occupies the engineering-intensive premium segment serving European retrofit demand with repairability-compliant configurations.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics |
| LG Electronics |
| Haier Smart Home |
| AB Electrolux |
| Robert Bosch GmbH |
| Panasonic Corporation |
| GE Appliances |
| Midea Group |
| Others |
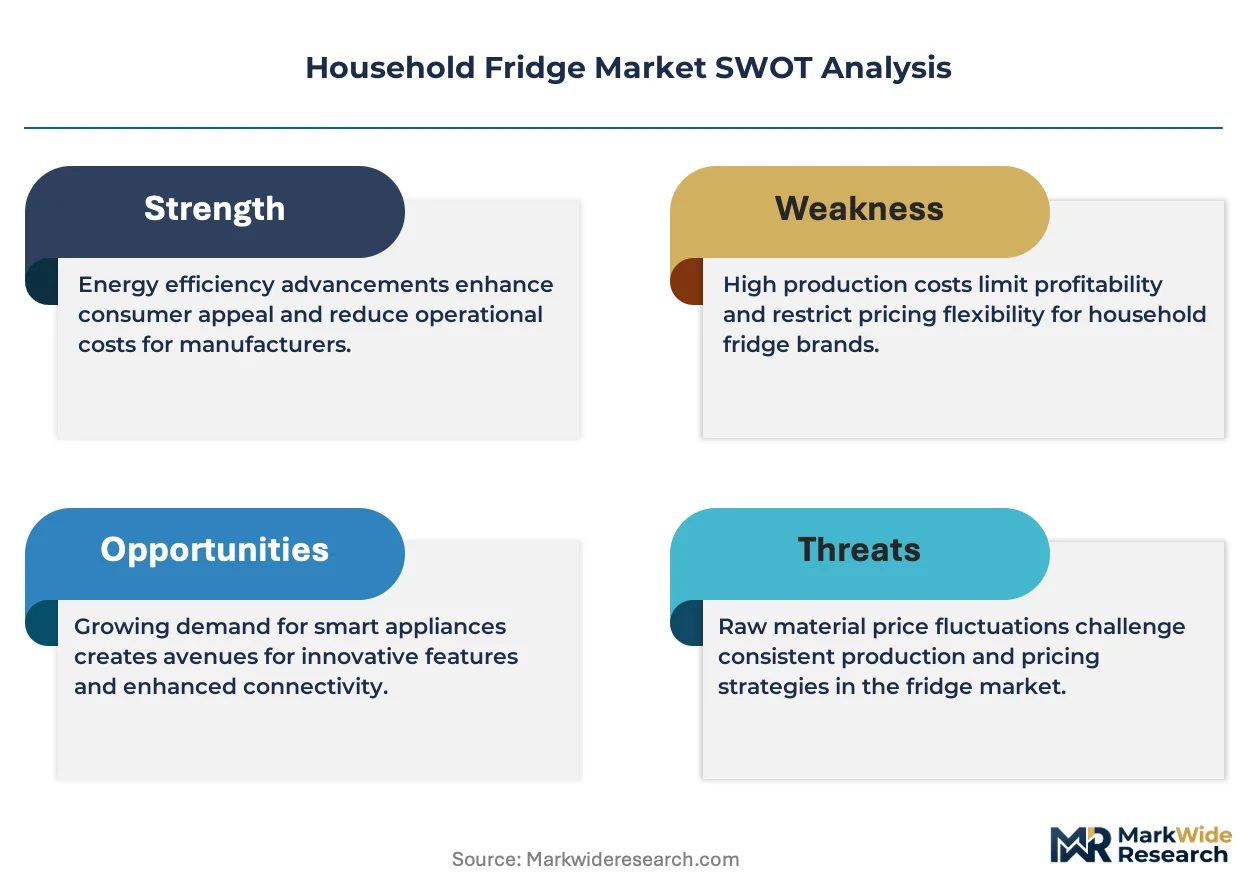
Supply Flow & Price Mechanics
Inverter compressor programming expertise concentrated in South Korea's semiconductor corridors widens labor-cost differentials between premium inverter platforms and fixed-speed economy tiers. This skill scarcity feeds into pricing spreads as manufacturers absorb variable-speed electronics premiums or cede share to regional assemblers with simpler mechanical platforms.
Pricing Analysis
Warranty bundling separates premium OEM service contracts from unbundled third-party repair exposure in economy segments. Three-tier pricing structure across premium, standard, and economy levels reflects inverter compressor chip sourcing, BEE labeling tier, and after-sales network density. Pricing pressure stems from Brazilian and Indian rental portfolio procurement negotiating volume discounts. Institutional landlords exhibit lowest price sensitivity; rural direct-cool replacement buyers face highest cost elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale property developer demand while appliance wholesalers stage multi-unit project fulfillment. Compressor housing steel draws from Baoshan mills; copper cathode feeds from Chilean mines into Yangtze River Delta assembly. Single-source vulnerability concentrates in isobutane refrigerant production clusters. Distribution runs through regional distributors for construction-channel volume and e-commerce platforms for replacement retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive inverter chip supply and localized compressor assembly determine margin capture. Players pursuing backward integration into semiconductor control systems or regional manufacturing hubs gain structural cost advantages.
For Market Incumbents: Hedge against emerging-market champion expansion by qualifying secondary compressor suppliers in India and Brazil. Secure direct procurement relationships with Chinese co-living operators before regional assemblers capture institutional volume. Invest in GB standards and EU Ecodesign dual certification capacity to defend export positioning.
For New Entrants and Emerging Players: Enter via frost-free platform standardization for Brazilian Minha Casa Minha Vida rental specifications. Target Maharashtra and Gujarat industrial corridors for regional assembly partnerships bypassing import tariff structures. Lead with appliance wholesaler channel relationships rather than retail footprint buildout.
For Investors and Strategic Acquirers: Re-rating potential sits with inverter compressor control specialists given DOE efficiency mandate tightening. Long-term viability favors platforms with semiconductor-enabled thermal management and repairability-compliant European export capacity. Monitor EU F-Gas Regulation refrigerant phase-down timelines as margin inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Compressor Qualification | Reduces procurement risk from single-source inverter chip dependencies while meeting DOE efficiency thresholds. |
| Localized Assembly Network Expansion | Bypasses Brazilian and Indian import tariffs through regional manufacturing hubs with established supplier ecosystems. |
| Smart Connectivity Platform Integration | Captures tech-forward single household premiums in Seoul and Tokyo through IoT-enabled inverter control systems. |
| Direct Procurement Relationship Development | Secures volume commitments with institutional landlords bypassing traditional retail markup structures in urban corridors. |
| Dual Certification Capacity Investment | Enables simultaneous compliance with China's GB standards and EU Ecodesign Directive for export flexibility. |
Methodological Framework
Multi-period observation of compressor procurement patterns, energy-efficiency labeling adoption, and rental construction permits anchored the trend analysis, supplemented by interviews with appliance OEM platform engineers, property management procurement directors, inverter control system designers, and regional distributor operations heads. Secondary validation drew from US DOE efficiency standard filings, EU Ecodesign Directive implementation reports, BEE and GB standards documentation, and customs trade data for steel coil and copper cathode flows. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Segment-weighting applied product type, technology platform, application customer type, and distribution channel dimensions across the modeling period. CAGRs derived from fitted growth curves against regulatory mandate timelines and replacement cycle data. Forecast inputs incorporated inverter compressor penetration rates by region and frost-free upgrade velocity in emerging markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material price volatility and refrigerant supply disruption scenarios. Projections reflect assumptions on efficiency regulation enforcement timing and rental housing construction policy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Australia Home Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Chile Home Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Israel Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Saudi Arabia Small Home Appliances Market
Home Appliances
Electric Fireplace Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
UAE Small Home Appliances Market