
 Dry Laundry Detergents Market | 2026-2036
Dry Laundry Detergents Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Laundry Detergents Market Foresight
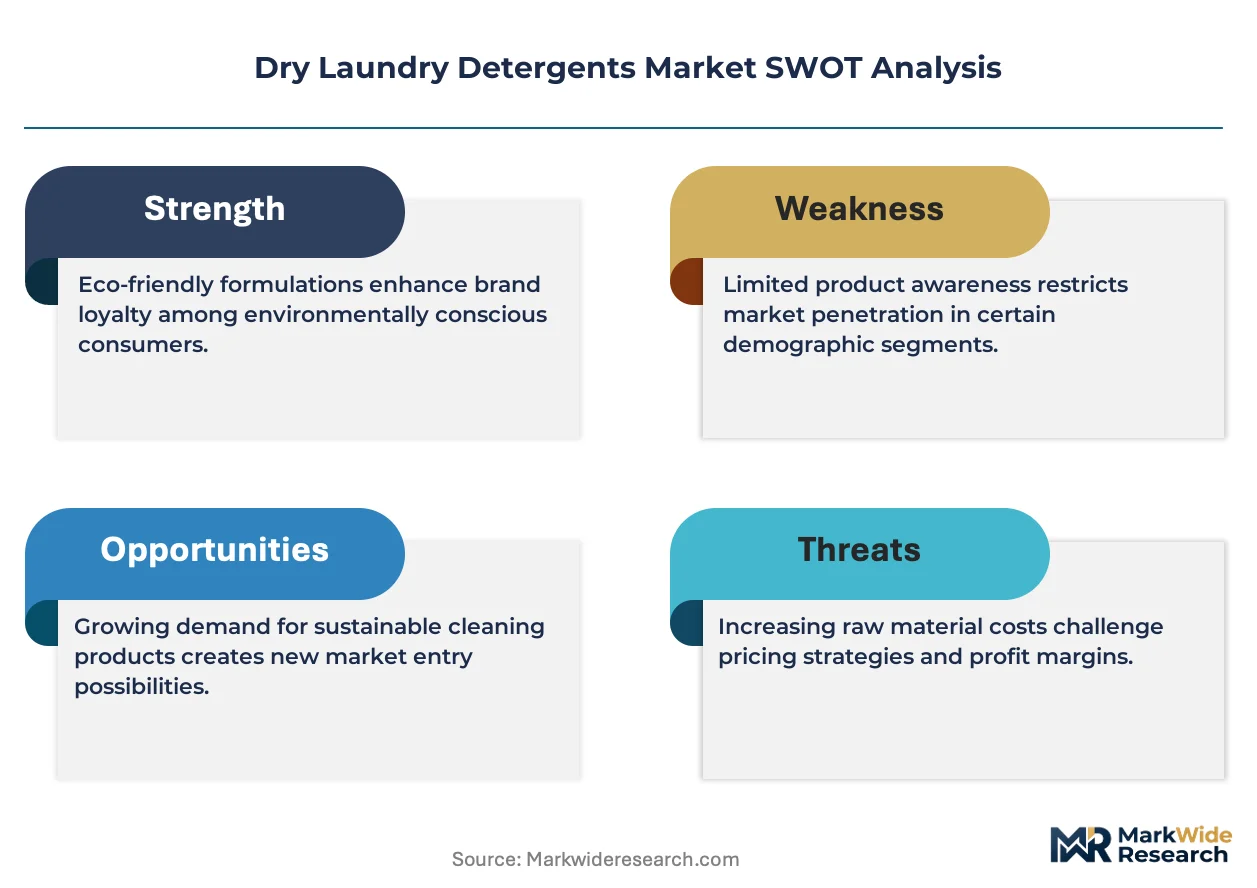
Skilled formulation chemists with surfactant expertise is reorganizing competitive dynamics as manufacturers race to replace petrochemical-derived cleaning agents with bio-based alternatives. Procter & Gamble leverages its captive enzyme R&D pipeline to sustain premium positioning in concentrated powder lines. Henkel AG & Co. KGaA anchors European supply through backward integration into alkyl polyglucoside feedstocks. Unilever competes across emerging markets with region-specific fragrance and hardness-adjusted formulations.
Dry laundry detergents encompass water-free or low-moisture cleaning formulations, typically comprising anionic and non-ionic surfactants, builders such as zeolites or phosphates, enzymes, and optical brighteners, manufactured through spray-drying or dry-mixing processes to deliver soil removal in automatic washing equipment. The commercial purpose centers on delivering effective textile cleaning with reduced packaging weight, extended shelf stability, and lower transport costs versus liquid alternatives. Powdered detergents still occupy the largest volume position across mass-market retail channels, though pods are capturing margin pools through unit-dose convenience and dosing accuracy that reduces consumer waste. Biodegradable formulations are gaining fastest traction where regulatory pressure intersects with corporate sustainability commitments, particularly in European and North American institutional procurement.
EPA Safer Choice standards, EU REACH restrictions on phosphates, and India's BIS detergent grade specifications collectively determine which chemistries achieve market access and which face reformulation costs. The EU F-Gas Regulation and parallel state-level chemical disclosure rules in California are tightening transparency requirements for fragrance components and preservative systems. Stakeholders must monitor how fragmented national labeling regimes reshape export complexity and whether enzyme stability innovations can unlock cold-water performance claims without triggering new dermatological testing mandates.
Market Dynamics
Enzyme stability innovations are compressing formulation refresh cycles as manufacturers chase cold-water efficacy claims without triggering EU dermatological testing mandates. The race to replace petrochemical surfactants with bio-based alternatives is reorganizing competitive positioning across the value chain.
Growth Catalysts
- EU REACH phosphate restrictions:Biodegradable zeolite builders are gaining procurement preference in German and French institutional laundries as compliance deadlines harden formulation roadmaps.
- Concentrated powder formats:Commercial hospitality and healthcare laundries are expanding unit-dose adoption to reduce transport costs and dosing variability in high-volume operations.
- Brazil:Modern retail penetration and professional washing infrastructure scaling are concentrating demand growth in São Paulo and Rio de Janeiro metro corridors.
Market Restraints
- Alkyl polyglucoside feedstock concentration:European backward integration into bio-surfactant precursors limits supplier diversity and amplifies agricultural commodity exposure.
- Cold-water enzyme stability: Technical performance gaps below 20°C force trade-offs between energy claims and soil removal efficacy in Northern European installations.
- India BIS detergent grade specifications:Fragmented national labeling regimes impose reformulation costs on exporters targeting multiple state-level compliance thresholds.
Strategic Opportunities
- India:Underpenetrated professional laundry infrastructure in Tier-2 cities offers white space for hardness-adjusted regional formulations.
- EU F-Gas Regulation:Transparency mandates for fragrance components are creating first-mover advantage for full-disclosure product lines in Nordic institutional procurement.
- E-commerce direct-to-institutional:Bypassing traditional chemical distributor networks is unlocking margin capture in mid-sized Brazilian hotel chains.
Industry Challenges
- Surfactant formulation chemistry expertise:Skilled talent scarcity in bio-based alternative development is elongating R&D timelines for REACH-compliant replacements.
- California chemical disclosure rules:Preservative system documentation requirements are extending product registration cycles by 8-14 months for US market entry.
- Spray-drying asset reconfiguration:Legacy capital equipment designed for phosphate-builder slurries requires retrofit investment to handle concentrated zeolite pastes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Laundry Detergents Market |
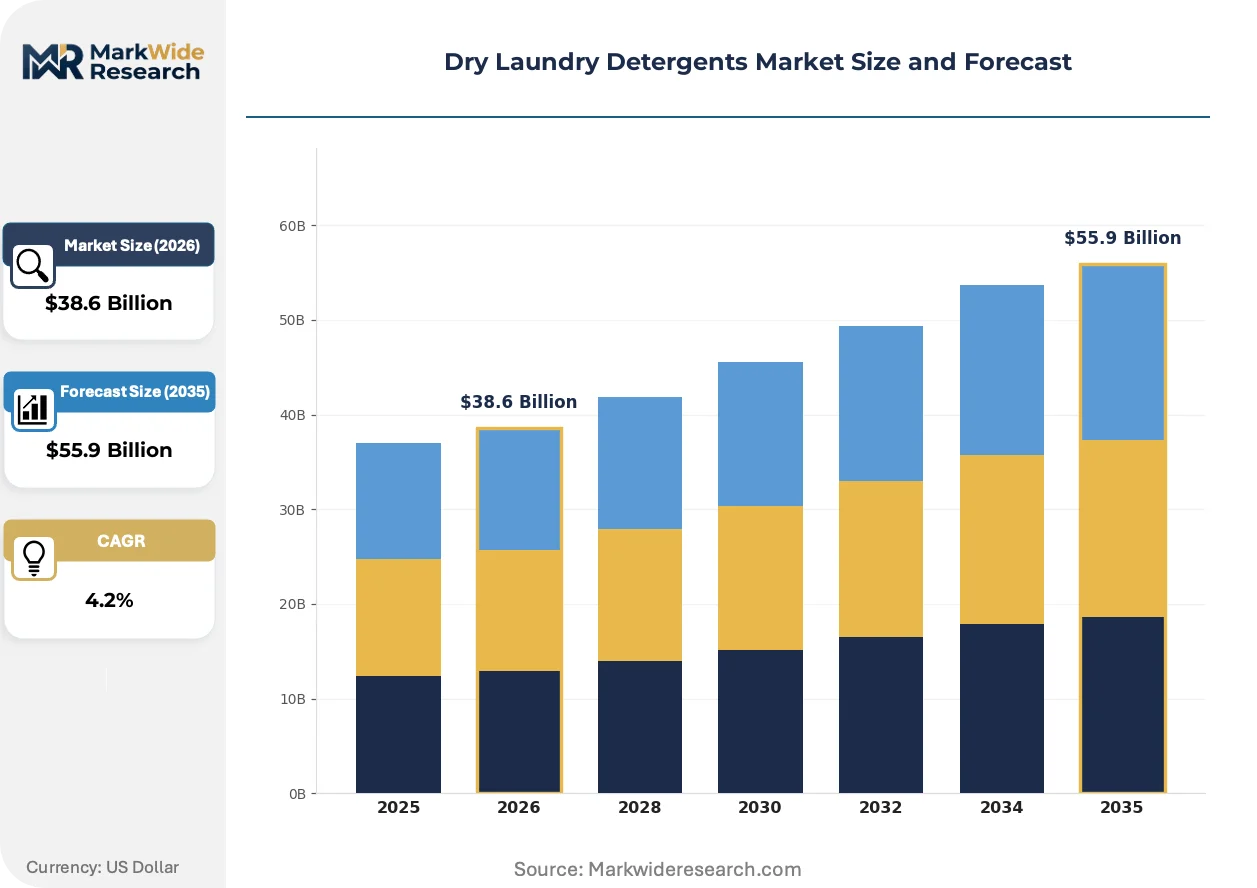
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $55.9 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Detergents, Pods, Tablets, Granules Formulation: Biodegradable, Non-Biodegradable, Scented, Fragrance-Free End User: Households, Commercial Laundries, Hotels, Institutional Users Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Procter & Gamble, Henkel AG & Co. KGaA, Unilever, Reckitt Benckiser Group, Church & Dwight Co., Inc., Kao Corporation, The Clorox Company, S. C. Johnson & Son, Inc., Lion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Laundry Detergents Market Shifts & Advancements
Cold-water chemistry breakthroughs, regulatory transparency mandates, and channel restructuring are converging to reshape how detergents are formulated, certified, and procured across institutional and retail segments.
Enzyme encapsulation technology is miniaturizing. Subtilisin variants housed in polyvinyl alcohol shells release active agents only upon water contact, preserving potency in low-humidity storage. German hospital laundries are adopting these systems at pace to meet energy reduction targets. The technology is miniaturizing the performance gap between ambient and heated wash cycles, compressing the premium positioning of legacy hot-water formulations.
EU F-Gas Regulation parallel disclosure frameworks are tightening fragrance component transparency. Industrial laundries in France and Benelux now demand full preservative system documentation to satisfy corporate sustainability reporting under CSRD-aligned procurement rules. Premium positioned suppliers are responding with open-source ingredient lists that trade formulation secrecy for contract security in institutional RFPs.
Buyer concentration in Brazilian hospitality chains is consolidating procurement decisions from property-level to corporate headquarters. Centralized chemical sourcing agreements are displacing regional distributor relationships that dominated the market for decades. This pattern is most visible in Rio de Janeiro state, where international hotel flags are standardizing detergent specifications across branded properties to reduce operational variability.
Dry Laundry Detergents Market Segmentation
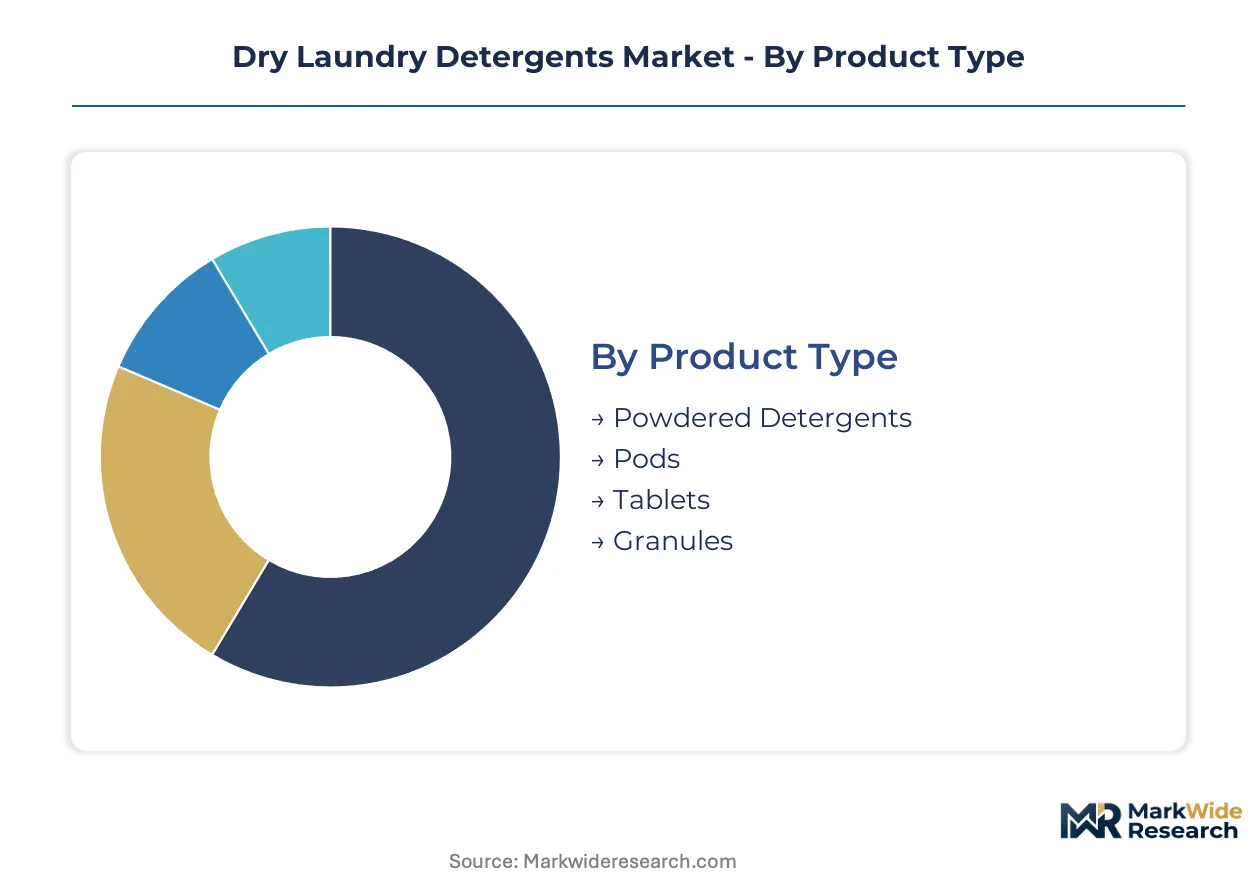
Dry laundry detergents traverse distinct channel ecosystems where formulation chemistry, packaging format, and end-use concentration determine margin capture. Manufacturers align R&D investment and supply chain configuration to the specific procurement logic governing each segment boundary.
Product Type:
Powdered formats dominate mass retail shelf space while unit-dose innovations are capturing institutional procurement contracts through dosing precision and transport efficiency.
- Powdered Detergents:Spray-dried or dry-mixed formulations containing anionic and non-ionic surfactants, zeolite builders, and enzyme blends. Demand concentrates in German and Brazilian mass retail where price-per-wash metrics dominate household purchasing decisions and phosphate-free reformulations satisfy EU REACH mandates.
- Pods:Polyvinyl alcohol-encapsulated unit doses with pre-measured surfactant and enzyme loads. Hospitality procurement in São Paulo and Rio de Janeiro metro corridors is expanding pod adoption to reduce housekeeping labor and eliminate dosing variability across branded properties.
- Tablets:Compressed powder matrices with controlled dissolution rates for automatic dosing systems. German hospital laundries favor tablet formats for integration with tunnel washer installations.
- Granules:Agglomerated formulations with enhanced solubility profiles for cold-water washing. Indian professional laundry infrastructure in Tier-2 cities is testing granule adoption for hardness-adjusted regional performance.
Powdered detergents dominate installed base. Pods are where expansion concentrates.
Formulation:
Regulatory pressure and corporate sustainability commitments are bifurcating procurement between disclosure-heavy European institutional channels and cost-optimized emerging market retail.
- Biodegradable:Alkyl polyglucoside and plant-derived surfactant systems with zeolite or citrate builders. EU F-Gas Regulation-aligned procurement in Nordic countries and Benelux is mandating full preservative documentation, rewarding suppliers with open-source ingredient disclosure.
- Non-Biodegradable:Petrochemical-derived linear alkylbenzene sulfonate and phosphate-builder formulations. Price-sensitive retail segments in India maintain volume concentration where BIS detergent grade specifications permit legacy chemistries.
- Scented:Fragrance-component formulations with encapsulated release systems. Brazilian hospitality chains standardizing corporate-level procurement are specifying scent profiles for brand consistency across properties.
- Fragrance-Free:Hypoallergenic formulations with dermatological testing documentation. German healthcare laundries pursuing energy reduction targets are adopting fragrance-free cold-water variants to minimize patient skin sensitivity risks.
Non-biodegradable formulations anchor volume. Biodegradable variants are climbing the fastest.
End User:
Procurement centralization is restructuring channel relationships as buyer concentration shifts decision authority from regional distributors to corporate headquarters.
- Households:Individual consumers purchasing through retail or e-commerce channels. Indian urban households scaling washing machine penetration are driving powder-to-pod transition in modern trade formats.
- Commercial Laundries:Independent and chain-operated textile cleaning facilities with high-throughput equipment. Concentrated powder procurement is expanding in German institutional laundries to reduce transport costs and comply with REACH phosphate restrictions.
- Hotels:Branded hospitality properties with standardized operational protocols. Brazilian hotel chains in Rio de Janeiro state are consolidating chemical sourcing agreements from property-level to corporate headquarters.
- Institutional Users:Healthcare, education, and government facilities with sustainability reporting obligations. French hospital laundries under CSRD-aligned procurement rules are demanding full fragrance component transparency.
Households represent the deepest volume base. Commercial laundries are where margin expansion concentrates.
Distribution Channel:
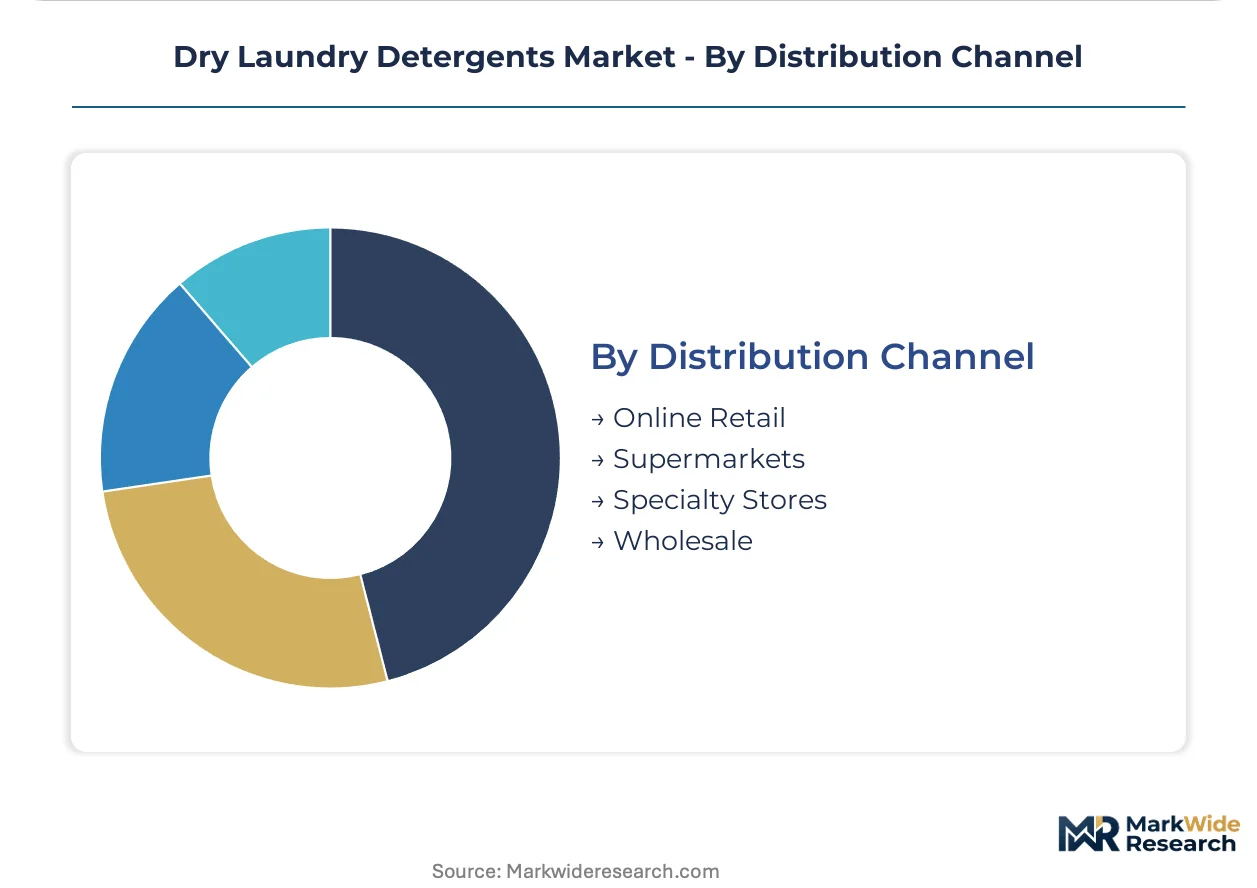
Channel restructuring is compressing traditional distributor margins as direct institutional relationships and platform commerce displace legacy wholesale networks.
- Online Retail:E-commerce platforms and direct-to-consumer fulfillment. Brazilian mid-sized hotel chains are bypassing chemical distributor networks through e-commerce direct-to-institutional procurement.
- Supermarkets:Mass-market retail with high-frequency household traffic. German and French supermarket chains are expanding shelf space for concentrated powder formats with EU Safer Choice certification.
- Specialty Stores:Professional cleaning supply and hospitality equipment vendors. Indian Tier-2 city professional laundry infrastructure is sourcing hardness-adjusted formulations through regional specialty distributors.
- Wholesale:Bulk chemical distributors serving institutional and commercial accounts. Traditional wholesale relationships in Brazilian hospitality are contracting as buyer centralization consolidates procurement decisions.
Supermarkets dominate household reach. Online retail is gaining share fastest in institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dry laundry detergent consumption patterns diverge sharply across geographies. German institutional buyers prioritize phosphate-free zeolite formulations under REACH deadlines. Brazilian hospitality chains consolidate procurement at corporate headquarters. Indian households transition from loose powder to packaged formats as washing machine penetration climbs.
Germany
Hospital laundries in North Rhine-Westphalia and Bavaria are retrofitting tunnel washer installations for cold-water enzyme systems. REACH phosphate restrictions have eliminated legacy builder chemistries from institutional procurement. Berlin-Brandenburg healthcare clusters now mandate fragrance-component documentation under CSRD-aligned sustainability reporting.
India
Tier-2 cities in Maharashtra and Gujarat are scaling professional laundry infrastructure for hospitality and healthcare sectors. BIS detergent grade specifications create state-level compliance fragmentation that elongates product registration cycles. Mumbai and Pune industrial corridors are testing hardness-adjusted regional formulations for local water chemistry.
Brazil
São Paulo and Rio de Janeiro metro corridors concentrate hospitality procurement centralization as international hotel flags standardize chemical specifications. Modern retail penetration in Minas Gerais and Rio Grande do Sul is accelerating pod format adoption among urban households. ANVISA transparency requirements are tightening fragrance disclosure for institutional buyers.
United States
California chemical disclosure rules extend product registration timelines by 8-14 months for preservative system documentation. EPA Safer Choice certification dominates institutional procurement in the Northeast and Pacific Northwest. Texas and Florida commercial laundries are expanding concentrated powder adoption to reduce transport costs in high-volume operations.
France
Île-de-France hospital laundries under CSRD-aligned procurement rules demand full fragrance component transparency from suppliers. Benelux-adjacent industrial zones in Hauts-de-France are consolidating bio-surfactant precursor supply chains. ECHA enforcement of EU F-Gas Regulation is reshaping preservative system selection for institutional textile cleaning.
Dry Laundry Detergents Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the dry laundry detergent market. Multinational consumer goods conglomerates with captive enzyme R&D pipelines and backward integration into bio-surfactant feedstocks control premium positioning. Mid-scale regional formulators compete on price-per-wash metrics in emerging market retail. Specialist chemical suppliers occupy niche positions in institutional fragrance-free and hypoallergenic segments. Competitive moves center on REACH-compliant reformulation investments and direct-to-institutional e-commerce channel development.
Among the integrated tier, Procter & Gamble and Henkel AG & Co. KGaA exemplify divergent strategic anchors. Procter & Gamble occupies a position emphasizing premium concentrated powder lines with proprietary enzyme technology. Henkel AG & Co. KGaA represents European supply security through in-house production of alkyl polyglucoside feedstocks. Unilever sits within the emerging market specialization archetype, with regional fragrance and hardness-adjusted formulation capabilities.
| Leading Market Players |
|---|
| Procter & Gamble |
| Henkel AG & Co. KGaA |
| Unilever |
| Reckitt Benckiser Group |
| Church & Dwight Co., Inc. |
| Kao Corporation |
| The Clorox Company |
| S. C. Johnson & Son, Inc. |
| Lion Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German hospital laundries and alkyl polyglucoside suppliers lock in feedstock access and price visibility across the REACH compliance horizon, insulating institutional buyers from agricultural commodity volatility while compressing spot-market liquidity for smaller formulators.
Pricing Analysis
Contract-based long-term offtake dominates institutional procurement in Germany and France, with spot-market activity concentrated in Indian retail channels. Price differentiation rests on REACH certification tier and volume scale, with fragrance-component disclosure mandates in Nordic markets commanding premium positioning. Cost compression in economy-tier powdered formats is intensifying because Brazilian modern retail chains are standardizing corporate-level specifications. Household segments in India exhibit highest price sensitivity, while German healthcare laundries prioritize energy-reduction performance over per-wash economics.
Supply Chain Analysis
Germany and Brazil anchor spray-drying capacity for concentrated powder production, with India scaling agglomeration infrastructure for hardness-adjusted regional formulations. Raw material dependencies draw from palm-derived fatty alcohols, zeolite builders, and encapsulated enzyme systems. Single-source vulnerability concentrates in European alkyl polyglucoside feedstock production controlled by backward-integrated multinationals. Distribution runs through chemical distributor networks in institutional segments, while e-commerce direct-to-institutional channels are displacing traditional wholesale relationships in Brazilian hospitality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-water enzyme stability breakthroughs are disrupting formulation economics, with EU energy-reduction mandates compressing the performance premium of legacy hot-water chemistries and accelerating procurement shifts toward ambient-temperature systems.
For Market Incumbents: Consolidate backward integration into bio-surfactant precursors to defend margin position against agricultural commodity exposure in alkyl polyglucoside supply. Lock in German and French institutional contracts through CSRD-aligned fragrance disclosure documentation before smaller competitors complete reformulation cycles.
For New Entrants and Emerging Players: Anchor in Indian Tier-2 city professional laundry infrastructure where hardness-adjusted regional formulations face limited incumbent specialization. Bypass traditional chemical distributors through e-commerce direct-to-institutional channels targeting mid-sized Brazilian hotel chains with pod-format dosing precision.
For Investors and Strategic Acquirers: Capital is best deployed toward specialist formulators with captive enzyme encapsulation technology and established REACH compliance documentation. Watch for inflection when cold-water performance claims achieve mass-market penetration without triggering new EU dermatological testing mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Surfactant Feedstocks | Henkel's captive alkyl polyglucoside production secures European supply against agricultural price volatility. |
| Enzyme Encapsulation Technology Investment | Polyvinyl alcohol shell systems unlock cold-water efficacy claims in German hospital laundries. |
| Direct-to-Institutional E-Commerce Launch | Brazilian mid-sized hotel chains bypass distributor margins through centralized corporate procurement platforms. |
| CSRD-Aligned Fragrance Disclosure Program | Full preservative documentation satisfies French institutional sustainability reporting requirements. |
| Hardness-Adjusted Regional Formulation Development | Maharashtra and Gujarat professional laundries source chemistry matched to local water conditions. |
Research Methodology
Initial hypotheses were tested against primary input from formulation chemists, institutional procurement managers at German hospital laundries, Brazilian hospitality chain operations directors, and specialty chemical distributors, then refined through secondary validation against EU REACH regulatory filings, BIS detergent grade specifications, customs trade data for surfactant precursors, and SEC 10-K disclosures from listed consumer goods conglomerates. Bottom-up volume modeling triangulated with top-down value estimates across product type, formulation chemistry, end-user concentration, and regional regulatory cluster dimensions.
Variance decomposition across the analysis window isolates enzyme stability innovation effects, REACH compliance cost pass-through, and channel restructuring impacts from baseline growth assumptions. Segmentation modeling incorporated product format, biodegradability tier, end-user procurement centralization, and distribution channel evolution. CAGRs were derived from installed base projections and replacement cycle dynamics, with cold-water performance adoption curves and institutional sustainability mandate timelines as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable EU F-Gas Regulation enforcement and continued Brazilian modern retail consolidation; material deviation in agricultural commodity prices or REACH reformulation deadlines would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Janitorial Cleaning Equipment and Supplies Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Fabric Care Market
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Fabric Freshener Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Screen Cleaner Market