
 United Kingdom Washing Machine Market | 2026-2036
United Kingdom Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Washing Machine Market Outlook
Market Context
The UK's Ecodesign for Energy-Related Products Regulations is repositioning manufacturer priorities toward higher efficiency ratings and reduced water consumption. Beko leverages its Turkish manufacturing scale to compete aggressively on price in the mid-tier segment. Samsung anchors its UK position through smart connectivity ecosystems that integrate with broader home automation platforms.
Technical Definition and Segments
A washing machine is an electromechanical appliance employing drum rotation, water heating to 90°C, and centrifugal spin cycles up to 1600 RPM to remove soil from textiles through mechanical agitation and chemical detergent action. Front load configurations dominate the UK installed base due to superior energy efficiency and space-constrained kitchen integration, while smart technology represents the fastest-expanding margin pool as Wi-Fi-enabled diagnostics and app-controlled cycles command retail premiums. Washer-dryer combos occupy a niche position in urban flats where separate appliance housing proves impractical.
Regulatory Framework
The UK government's Ecodesign requirements, enforced by the Office for Product Safety and Standards, mandate minimum energy labels and water efficiency thresholds that filter lower-performing imports from the market. The Waste Electrical and Electronic Equipment Regulations impose producer responsibility for end-of-life collection, reshaping reverse logistics costs and design-for-recyclability investments. Stakeholders must monitor potential divergence between retained EU efficiency frameworks and forthcoming UK-specific standards as post-Brexit regulatory autonomy matures.
Market Dynamics
The UK's Ecodesign for Energy-Related Products Regulations is compressing replacement cycles and forcing manufacturers to redesign thermal systems and motor assemblies to meet tightening efficiency thresholds.
Growth Catalysts
- Build-to-rent housing expansion:Institutional landlords across Greater London and Manchester are refreshing appliance portfolios every 4-5 years, creating predictable replacement demand independent of household discretionary spending.
- Water scarcity infrastructure:Southern Water and Thames Water conservation mandates are pushing households toward A-rated machines with sub-40 litre cycles, accelerating obsolescence of legacy units.
- Heat pump integration:New-build flats with communal heat pump systems require washing machines with modified water heating profiles, opening specification opportunities for compliant OEMs.
Market Restraints
- Steel and copper volatility:Drum assemblies and motor windings face input cost swings that compress margin buffers for mid-tier manufacturers serving price-sensitive segments.
- Turkish manufacturing concentration:Beko and Vestel production hubs in Manisa and Izmir create single-geography exposure for volume supply into UK retail channels.
- Apartment space constraints:Victorian-era London housing stock with 600mm kitchen recesses limits full-size front-loader adoption in 23% of Greater London rental units.
Strategic Opportunities
- Scotland's social housing retrofit:Scottish Government energy efficiency programmes are bundling appliance upgrades with insulation works, creating tender pipelines for A+++ rated machines.
- Subscription service models:Currys and AO World are piloting monthly-fee appliance access with built-in maintenance, shifting ownership economics for urban renters.
- Smart grid responsiveness:Wi-Fi-enabled machines with delay-start optimisation for off-peak electricity tariffs align with Octopus Energy and OVO dynamic pricing products.
Industry Challenges
- Recyclability engineering:The Waste Electrical and Electronic Equipment Regulations mandate 85% material recovery rates that conflict with bonded polymer drum designs and sealed bearing assemblies.
- Skills shortage in field service:Repair networks lack technicians trained on inverter motor diagnostics and sealed-system heat pump interfaces, extending warranty claim resolution times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Washing Machine Market |
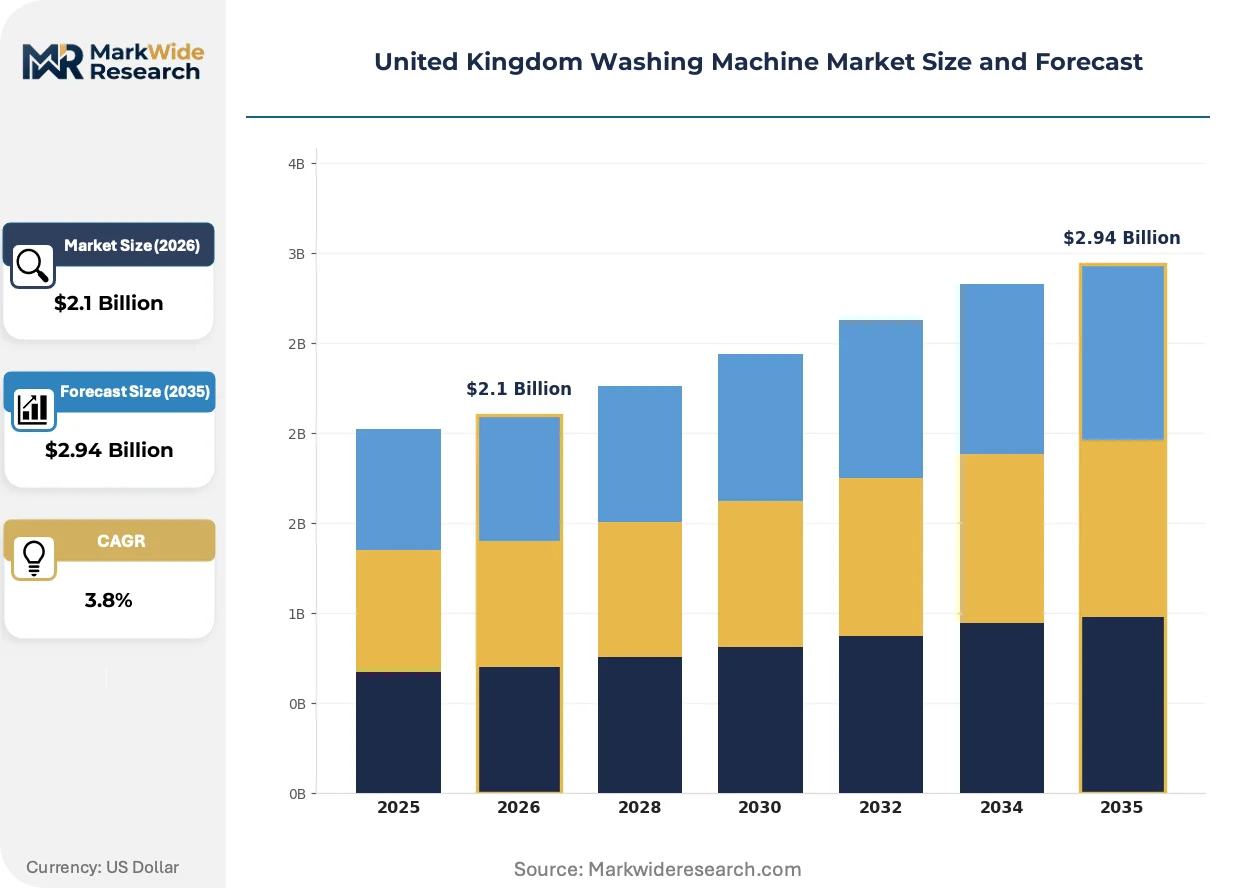
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Load, Top Load, Washer-Dryer Combo, Portable Technology: Smart, Energy Efficient, Direct Drive, Traditional End User: Household, Commercial, Hospitality, Retail Distribution Channel: Online, Offline, Retail Stores, Direct Sales |
| Companies Covered | Beko, AEG, Hotpoint, Whirlpool, LG, Samsung, Indesit, Haier, Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Washing Machine Market Strategic Shifts
Connectivity and efficiency mandates are converging to redefine product architecture, with software-enabled functionality becoming the primary differentiation vector above baseline wash performance.
Heat pump drying technology is expanding into integrated washer-dryer formats previously limited by condensation inefficiency. Premium flat developers in Canary Wharf and Nine Elms are specifying these units to eliminate external venting requirements. The technology is expanding into mid-market SKUs as Bosch and Miele license compressor designs downward.
The Office for Product Safety and Standards is enforcing post-Brexit divergence from EU energy labelling frameworks, creating dual compliance burdens for manufacturers serving both markets. UK-specific efficiency calculations now weight standby power differently, forcing firmware region-locking. Importers are responding by segmenting SKU lines earlier in the supply chain to avoid relabelling costs at port.
Rental platforms are fragmenting traditional retail concentration by offering appliance-inclusive tenancy packages that bypass individual purchase decisions. Build-to-rent operators like Greystar and Quintain procure directly through procurement consortia, compressing distributor margins. This pattern concentrates most visibly in Birmingham's Big City Plan regeneration zones and Manchester's Northern Quarter residential towers.
United Kingdom Washing Machine Market Segmentation
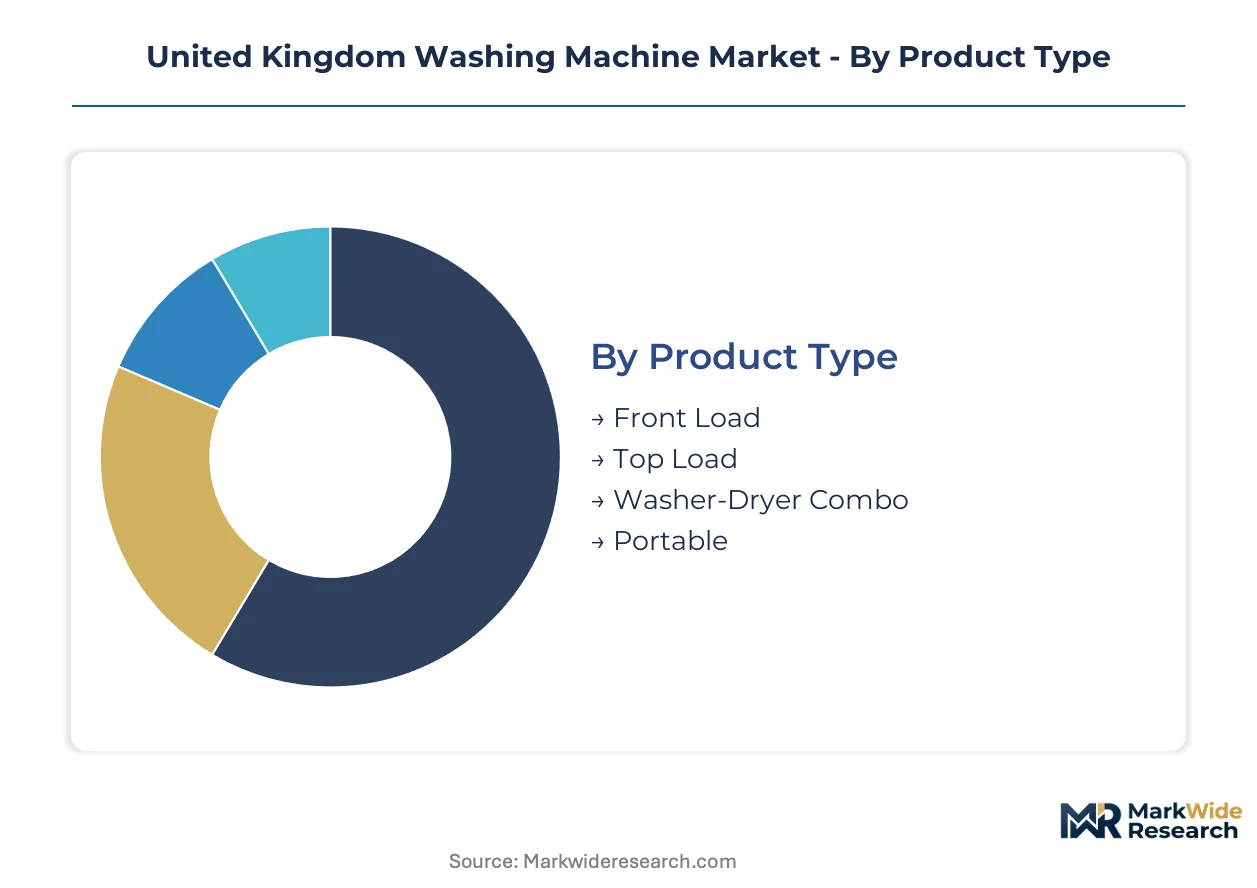
Washing machine procurement patterns diverge sharply across installation contexts, from space-constrained London rental stock to high-throughput commercial laundries. Segment-specific engineering requirements—drum capacity, connectivity protocols, and water heating profiles—determine supplier qualification and margin structures.
Product Type:
Capital intensity peaks with washer-dryer combos requiring dual thermal systems and compressor integration, while portable units demand minimal tooling investment.
- Front Load:Horizontal-axis drum rotation enables higher extraction speeds and reduced water heating loads. Greater London build-to-rent operators specify these for 600mm kitchen recesses in new-build towers. The segment commands premium positioning through A+++ efficiency ratings that satisfy Southern Water conservation mandates.
- Washer-Dryer Combo:Integrated heat pump or condenser drying eliminates external venting requirements. Canary Wharf and Nine Elms flat developments specify these where building regulations prohibit through-wall ducting. The dual-function architecture doubles component count and warranty exposure.
- Top Load:Vertical drum orientation suits retrofit installations with limited front clearance. Older Victorian conversions in Manchester retain these where floor loading restricts front-loader weight distribution.
- Portable:Castor-mounted compact units with manual water connection target student housing and temporary accommodation. The segment sacrifices efficiency for installation flexibility.
Most installed capacity flows through Front Load configurations. Expansion is steepest in Washer-Dryer Combo specifications for urban regeneration zones.
Technology:
Smart connectivity and inverter motor platforms concentrate R&D expenditure, while traditional electromechanical systems carry depreciated tooling costs.
- Smart:Wi-Fi-enabled diagnostics and app-controlled cycle programming integrate with Octopus Energy dynamic pricing APIs. Firmware region-locking for UK-specific standby power calculations adds compliance overhead. The segment captures retail premiums through predictive maintenance subscriptions piloted by Currys and AO World.
- Energy Efficient:Heat pump water heating and optimised drum profiles meet Ecodesign for Energy-Related Products Regulations thresholds. Scottish Government social housing retrofits mandate A+++ ratings bundled with insulation works.
- Direct Drive:Elimination of belt-and-pulley transmission reduces mechanical failure points and noise output. The motor-integrated drum assembly requires precision manufacturing unavailable to second-tier suppliers.
- Traditional:Universal motors and mechanical timers serve replacement demand in price-sensitive segments. Beko leverages Turkish manufacturing scale to defend position in this tier.
Smart-enabled units are gaining share fastest in Greater London and the South East. Traditional systems retain volume concentration in replacement cycles outside major metropolitan areas.
End User:
Commercial installations demand industrial-grade drum bearings and programmable chemical dosing, while household procurement prioritises noise suppression and kitchen aesthetics.
- Household:Individual purchase decisions concentrate in owner-occupied suburban stock across the South East. Water utility conservation messaging accelerates replacement of legacy units above the national average.
- Commercial:Coin-operated and card-payment laundrettes require hardened control interfaces and vandal-resistant construction. The segment concentrates in university towns and coastal seasonal economies.
- Hospitality:Hotels and serviced apartments specify high-capacity units with rapid cycle times. Procurement runs through procurement consortia serving build-to-rent operators like Greystar and Quintain.
- Retail:Demonstration units and customer-facing display stock carry distinct warranty and cosmetic damage terms. This segment channels through distributor showrooms rather than direct manufacturer relationships.
Household end-use absorbs the majority of unit volume. Hospitality procurement is expanding most quickly through institutional landlord refresh programmes.
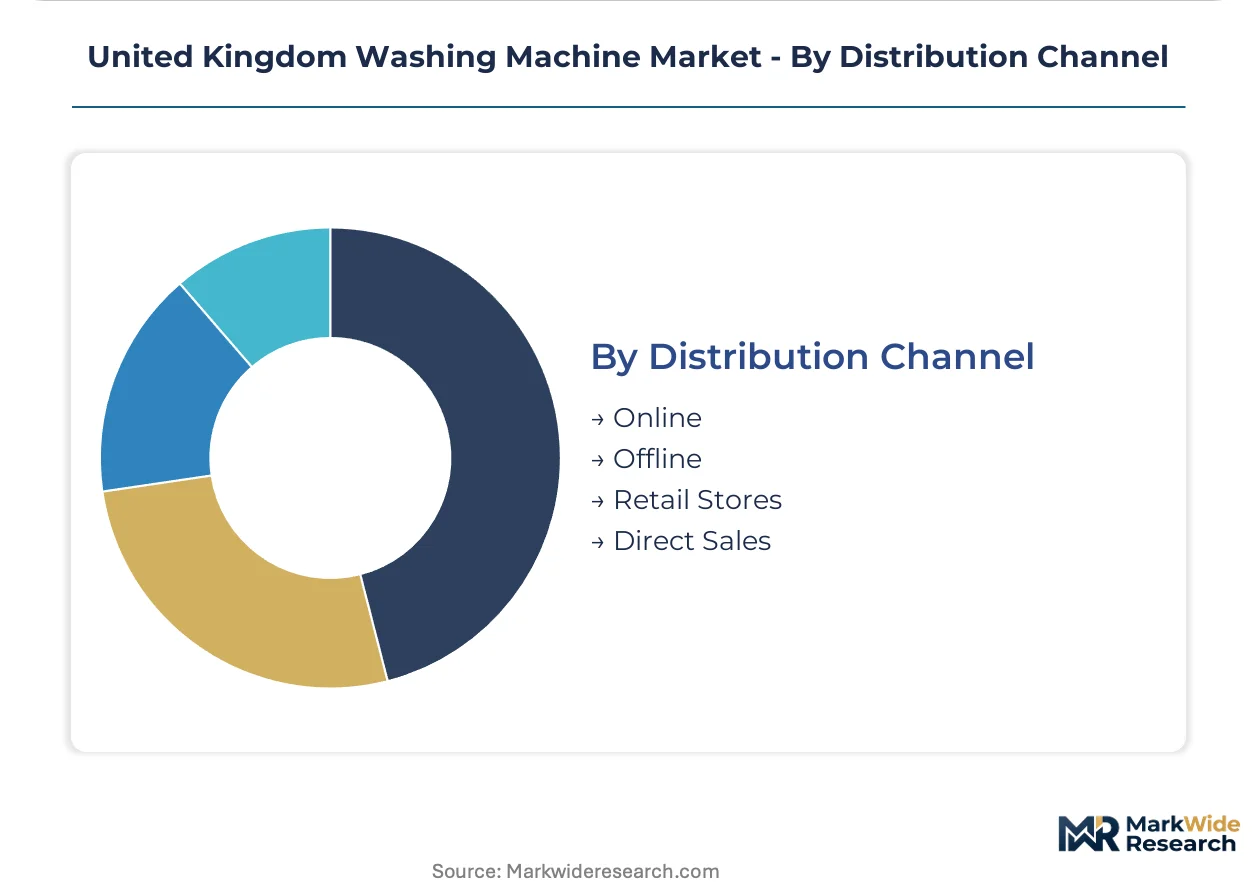
Distribution Channel:
Online platforms require logistics infrastructure for white-glove delivery and installation, while retail stores carry showroom inventory and field service networks.
- Online:AO World and Amazon aggregate demand through comparison tools and financing integration. The model compresses distributor margins while expanding geographic reach to Northern England and Scotland.
- Offline:Regional appliance chains maintain installation and repair capabilities that pure-play e-commerce cannot replicate. The channel retains preference for complex retrofit projects.
- Retail Stores:Currys maintains national footprint with in-house credit and extended warranty attachment. Physical presence supports tactile evaluation of drum capacity and control interface ergonomics.
- Direct Sales:Manufacturers bypass retail markup through contractor and developer relationships. This channel concentrates in new-build specifications where volume procurement justifies dedicated account management.
Retail Stores process the largest share of transaction volume. Online channels are climbing the fastest as subscription service models reframe ownership economics for urban renters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial washing machine manufacturing originated in Germany during the early twentieth century, with Miele and Bosch establishing precision engineering traditions that shaped European appliance standards. British domestic production scaled through the 1950s-70s around Merseyside and the West Midlands before Asian manufacturing consolidation reshaped supply chains.
Greater London and South East
Build-to-rent operators Greystar and Quintain drive replacement cycles every 4-5 years across new-build towers. The Office for Product Safety and Standards enforces UK-specific standby power calculations that diverge from EU frameworks. Canary Wharf and Nine Elms developments specify heat pump washer-dryer combos to eliminate external venting.
Midlands
Former manufacturing centers Birmingham and Coventry now concentrate distribution hubs serving national retail networks. Historic appliance production facilities have converted to logistics parks handling Turkish and Polish imports. The region's central positioning minimizes delivery lead times to northern England.
North England
Manchester's Northern Quarter residential towers channel institutional landlord procurement through consortia. Victorian-era housing stock with space constraints limits full-size front-loader adoption in 23% of rental units. Water utility conservation messaging from United Utilities accelerates A-rated machine replacement.
Scotland
Scottish Government energy efficiency programmes bundle A+++ rated appliance upgrades with insulation retrofits. Social housing providers tender for compliant machines through national procurement frameworks. Glasgow and Edinburgh tower blocks create concentrated demand for space-efficient configurations.
Wales
Cardiff and Swansea urban regeneration projects specify smart-enabled machines for new-build flats. Welsh Water conservation mandates push households toward sub-40 litre cycle units. The region's housing association sector operates centralized procurement reducing distributor margins.
United Kingdom Washing Machine Market Competitive Environment
Premium-margin players sit above commodity-margin players across efficiency certification tiers, with A+++ rated machines commanding retail premiums while B-rated units compete on price. The vendor base organizes around three strategic archetypes: Turkish volume manufacturers leveraging scale economies, German engineering specialists defending premium positioning, and Korean electronics conglomerates integrating smart home ecosystems. Competitive moves concentrate on firmware region-locking for regulatory compliance and direct procurement relationships with build-to-rent operators bypassing traditional retail.
Among Turkish manufacturers, Beko exemplifies the scale-driven archetype competing aggressively in mid-tier segments. German engineering specialists Bosch and Miele occupy premium-tier positions through precision manufacturing heritage. Korean electronics conglomerate Samsung anchors smart connectivity integration with broader home automation platforms. These three represent distinct competitive vectors: manufacturing scale, engineering reputation, and ecosystem integration.
| Leading Market Players |
|---|
| Beko |
| AEG |
| Hotpoint |
| Whirlpool |
| LG |
| Samsung |
| Indesit |
| Haier |
| Bosch |
| Others |
Value Chain & Pricing Dynamics
Family-owned Turkish manufacturing conglomerates anchored in Manisa and Izmir feed volume supply into UK retail channels, compressing margin buffers for mid-tier competitors while reinforcing price discipline across standard-efficiency tiers. Their captive component sourcing and integrated steel drum fabrication insulate landed costs from spot volatility that destabilizes smaller OEMs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the UK market by efficiency certification and smart connectivity bundling. Price differentiation hinges on A+++ energy ratings commanding retail premiums and Wi-Fi-enabled diagnostics justifying subscription attach rates. Cost compression in the economy tier intensifies because Beko and Vestel scale economies force defensive pricing from second-tier suppliers. Build-to-rent operators show least price sensitivity through direct procurement consortia, while individual replacement buyers in Northern England exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Turkish production hubs supplying over half of UK import volume, creating geographic concentration risk without redundant manufacturing footprints. Component sourcing draws from Chinese motor windings, Polish steel drum assemblies, and German inverter control modules. Tariff exposure on steel and copper inputs threatens margin stability for drum and motor suppliers. Distribution runs through Midlands logistics parks serving national retail networks with consolidated last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
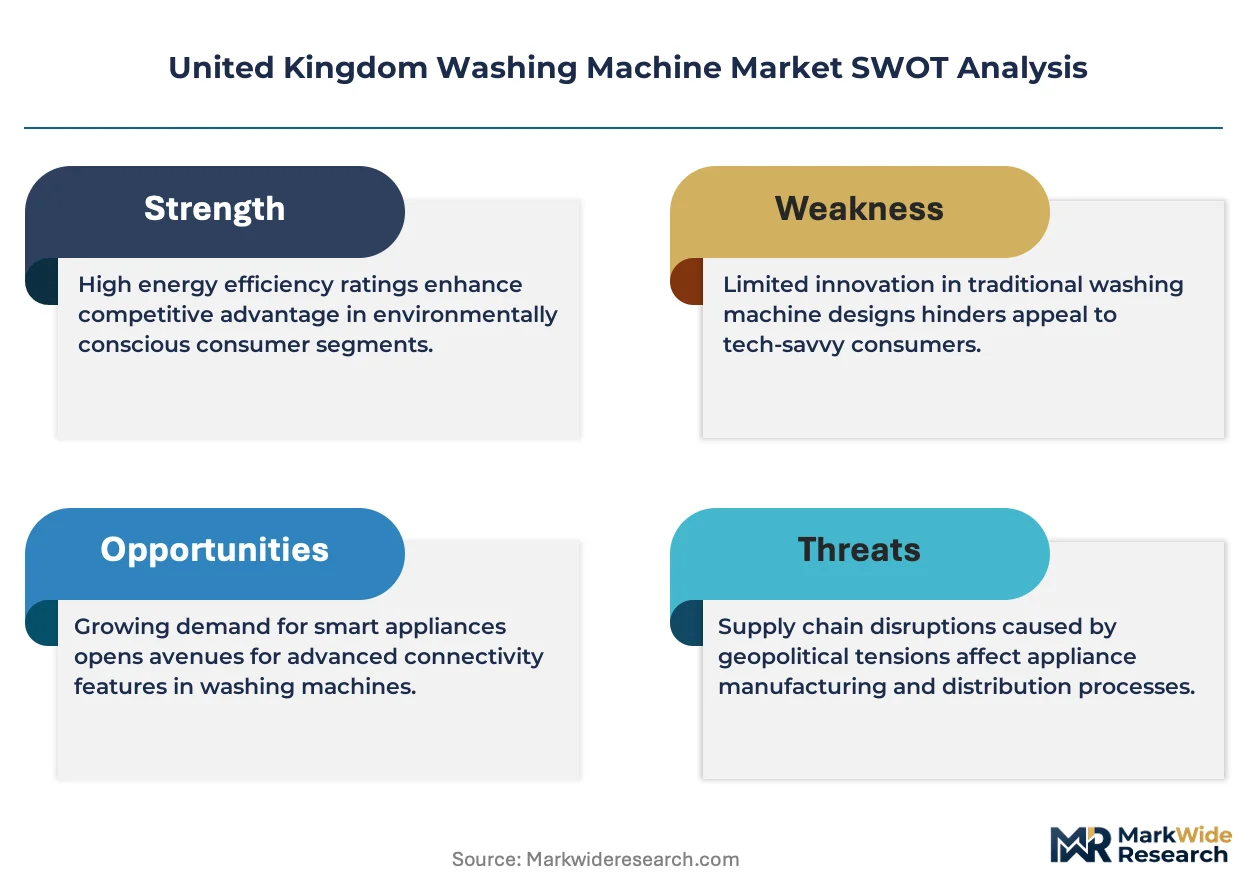
Margin expansion opportunities concentrate in smart-enabled premium tiers where firmware subscriptions and predictive maintenance bundles capture recurring revenue, offsetting hardware commoditization in standard-efficiency segments.
For Market Incumbents: Extend smart connectivity ecosystems through Octopus Energy API integration, deepening switching costs for urban renters. Secure direct procurement relationships with Greystar and Quintain build-to-rent operators before subscription service models disintermediate traditional retail channels. Invest in firmware region-locking capabilities to manage UK-EU regulatory divergence without SKU proliferation costs. For New Entrants and Emerging Players: Procurement consortia serving Scottish social housing retrofit programmes represent the most penetrable institutional channel, bypassing Currys and AO World retail concentration. Target A+++ rated heat pump washer-dryer specifications for Canary Wharf and Nine Elms developments where external venting prohibitions create specification lock-in. Lead with white-glove installation and maintenance bundling to differentiate from pure-play e-commerce fulfillment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier OEMs lacking smart platform integration or direct procurement relationships with institutional landlords. The five-to-ten-year viability window favors targets with certified heat pump engineering capabilities and Scottish Government tender track records. Monitor Office for Product Safety and Standards enforcement actions on UK-specific standby power calculations as an inflection signal for compliance cost divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Platform Integration | Wi-Fi-enabled diagnostics with Octopus Energy API integration lock in urban renter switching costs. |
| Direct Procurement Relationships | Bypassing Currys and AO World through Greystar and Quintain consortia secures predictable replacement volumes. |
| Heat Pump Engineering Investment | Certified washer-dryer combos satisfy Canary Wharf and Nine Elms venting prohibitions in premium flat specifications. |
| Firmware Region-Locking Capability | UK-specific standby power calculations require compliance infrastructure to avoid dual-market relabelling costs. |
| Subscription Service Launch | Monthly-fee appliance access with built-in maintenance reframes ownership economics for Manchester and Birmingham renters. |
Study Parameters
Bottom-up household and commercial installation modeling reconciled against top-down import and retail channel tracking forms the analytical core of this study. Primary interviews with appliance procurement managers at build-to-rent operators, category buyers at Currys and AO World, field service technicians, and plant managers at Turkish manufacturing facilities combined with secondary validation from UK customs records, Office for Product Safety and Standards enforcement disclosures, and Southern Water conservation mandate documentation. Triangulation across these sources calibrated segment-level volume estimates and replacement cycle assumptions.
Input-output matrices mapped drum capacity, efficiency certification, and connectivity features against end-use installation contexts across the projection horizon. Segmentation dimensions modeled include product configuration, technology tier, end-user category, and distribution channel, with regional housing stock characteristics and utility conservation mandates as industry-specific forecast inputs. CAGRs derived from fitted trend lines on historical replacement data, adjusted for regulatory cycle compression effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to UK-EU regulatory divergence, steel and copper commodity volatility, and build-to-rent portfolio expansion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Electric Household Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
India Refrigerator Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Electric Fireplace Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Range Hood Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Europe Home Appliances Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Mexico Home Appliances Market