
 Middle East and Africa Home Appliances Market | 2026-2036
Middle East and Africa Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Home Appliances Market Foresight
Multi-source component procurement is rebalancing toward regional assembly partnerships as brands seek tariff efficiency and faster fulfillment. Samsung Electronics leverages its Egyptian manufacturing base to anchor North African distribution. Haier Smart Home sustains competitive positioning through localized refrigerator production in South Africa. LG Electronics differentiates via inverter compressor technology leadership across Middle Eastern climate zones.
Home appliances encompass electromechanical devices designed for domestic tasks, typically operating on 220-240V at 50Hz with energy consumption ratings measured in kilowatt-hours annually; these units automate food preservation, garment cleaning, thermal comfort, and meal preparation for residential and commercial end users. Refrigerators and air conditioners command the largest revenue pools given extreme ambient temperatures across Gulf states and prolonged cooling seasons. Washing machines exhibit structural momentum as water-scarce markets demand low-consumption drum designs. Smart Appliances and IoT-enabled categories attract premium positioning though offline retail channels still dominate actual transaction volume across the region.
Saudi Standards, Metrology and Quality Organization (SASO) mandates energy efficiency labeling for imported cooling equipment, directly conditioning market access for non-compliant manufacturers. South Africa's National Regulator for Compulsory Specifications enforces safety standards on electrical appliances, creating compliance cost barriers for budget entrants. Egypt's Consumer Protection Agency exercises growing oversight on warranty terms and after-sales service commitments. Stakeholders must monitor evolving compulsory specification expansions and decide whether to absorb certification costs or cede share to pre-certified regional competitors.
Market Dynamics
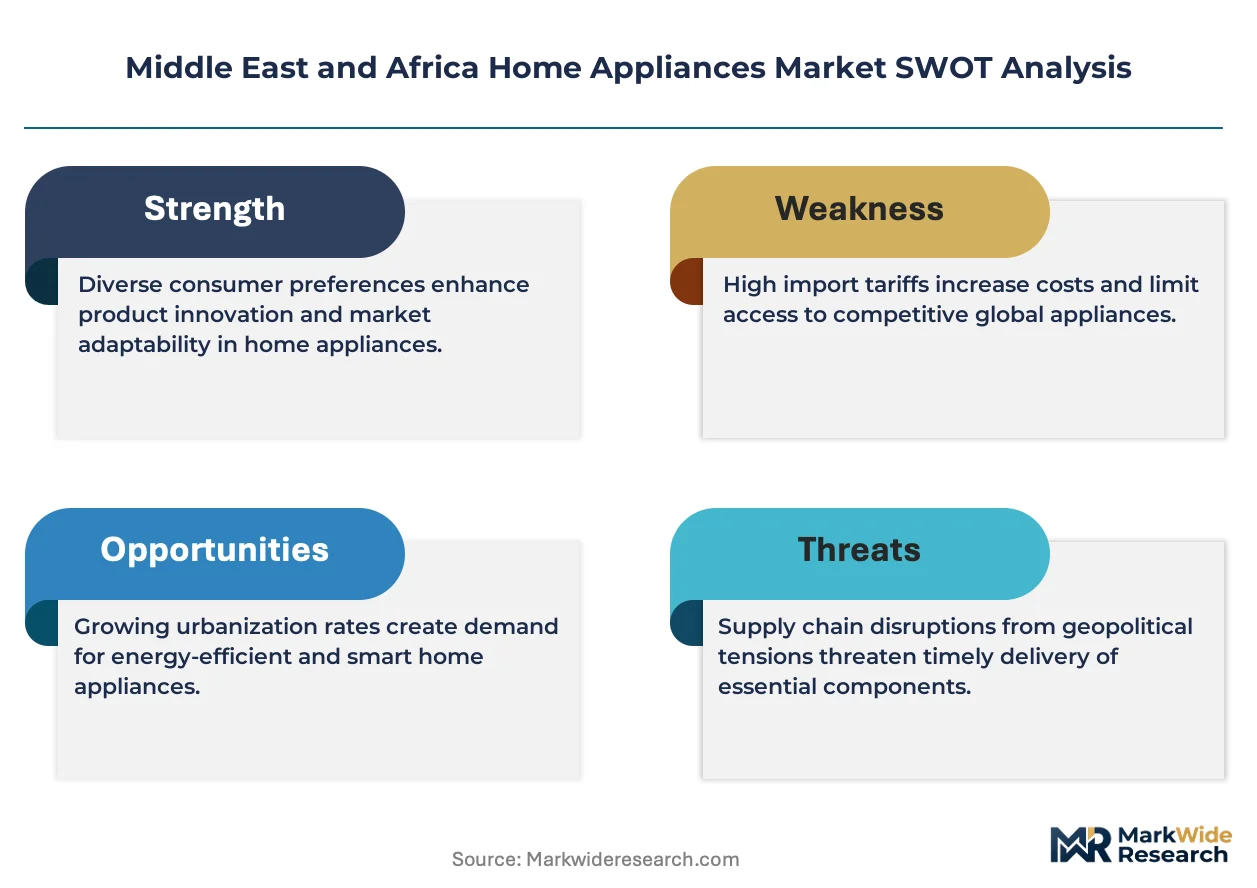
Energy efficiency mandates from Gulf regulators are compressing product refresh cycles while South African import standards reshape competitive access for cooling equipment manufacturers.
Growth Catalysts
- SASO Energy Labeling Mandate:Saudi Arabia's compulsory efficiency grades for air conditioners and refrigerators force technology upgrades, expanding replacement demand among urban households.
- Urban Residential Construction:New housing stock across Dubai, Riyadh, and Cairo creates first-time buyer pipelines for built-in kitchen appliances and climate control systems.
- Inverter Compressor Diffusion:Variable-speed cooling technology reduces electricity consumption by 30-50% versus conventional units, justifying premium pricing in high-tariff markets.
Market Restraints
- Copper and Steel Input Volatility:Raw material price swings compress assembler margins, particularly for sheet metal refrigerator cabinets and motor winding components.
- Single-Source Compressor Supply:Gulf markets depend heavily on Thai and Chinese compressor imports, creating vulnerability to shipping disruptions and currency fluctuations.
- Water Scarcity Engineering Limits:Washing machine drum designs face hard constraints on rinse-cycle water reduction without compromising garment care performance.
Strategic Opportunities
- Nigerian Electrification Gap:Grid expansion and generator-dependent households in Lagos and Abuja represent untapped demand for low-wattage, voltage-stabilized appliances.
- Smart Appliance Convergence:Integration of Wi-Fi modules with energy management platforms enables utility-linked demand response programs in Saudi and UAE smart city developments.
- Direct-to-Installer Channels:Bypassing traditional retail through HVAC contractor networks captures replacement-cycle revenue in commercial and residential cooling segments.
Industry Challenges
- Certification Timeline Compression:SASO and South Africa's NRCS require 4-6 month testing cycles for new product introductions, delaying revenue recognition against competitor launches.
- After-Sales Network Density:Sparse authorized service coverage in secondary Egyptian and Nigerian cities elevates warranty claim costs and erodes brand equity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Home Appliances Market |
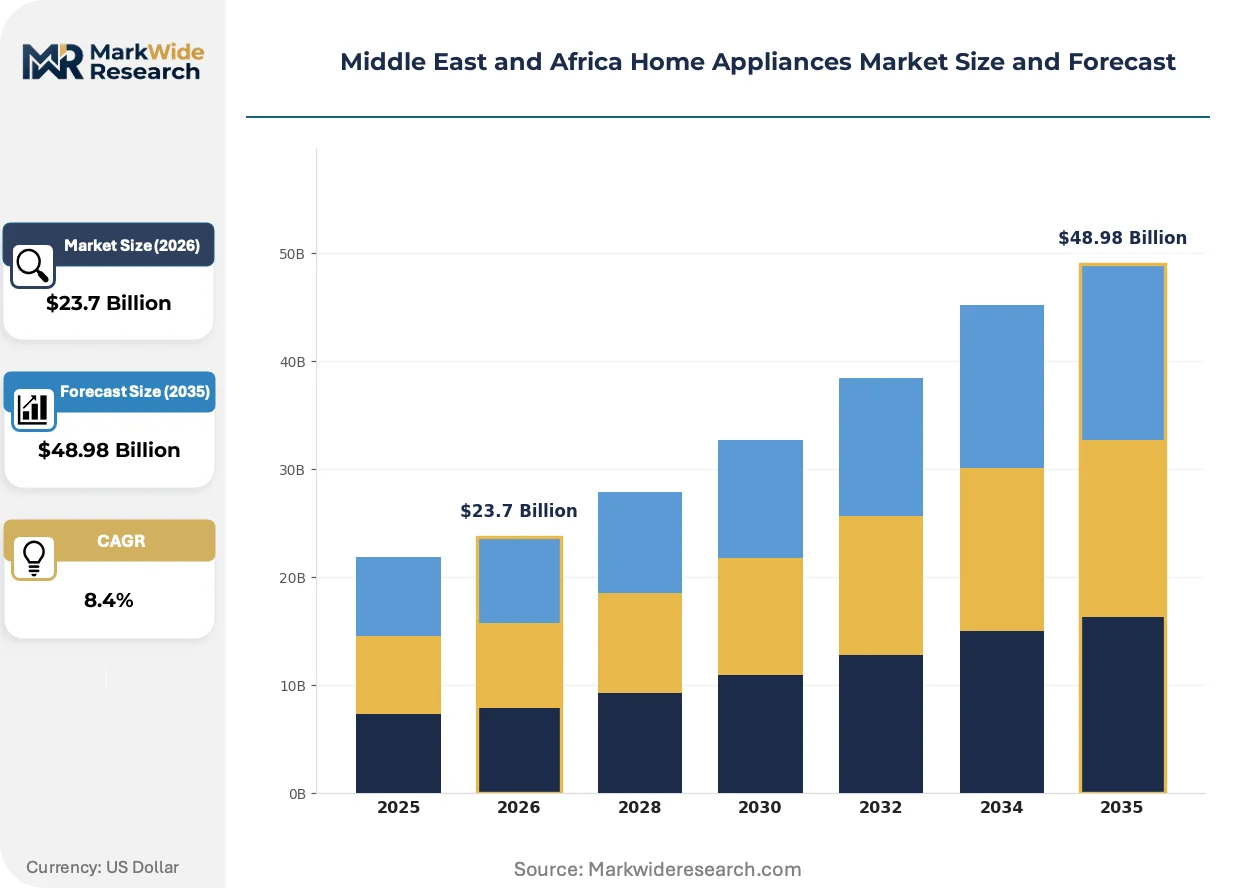
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwave Ovens, Air Conditioners End User: Households, Restaurants, Hotels, Offices Technology: Smart Appliances, Energy Efficient, Traditional, IoT-enabled Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Samsung Electronics, Whirlpool Corporation, Haier Smart Home, BSH Hausgeräte, LG Electronics, Electrolux AB, Midea Group, Panasonic Holdings Corp, Gorenje Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Home Appliances Market Shifts & Advancements
Climate-adaptive engineering and regulatory compliance automation are redefining product development priorities across Middle Eastern and African appliance markets.
Photovoltaic-integrated cooling systems are integrating DC-powered compressor architectures with rooftop solar installations in Saudi Arabia's residential sector. Off-grid villas and compound developments in Riyadh and Jeddah adopt these units to circumvent peak-hour electricity tariffs. The technology is integrating energy storage management with appliance control logic, compressing payback periods below five years in high-insolation zones.
South Africa's National Regulator for Compulsory Specifications expanded safety testing requirements for electrical appliance imports, mandating third-party laboratory verification for all new product registrations. This regulatory tightening elevates compliance costs for budget manufacturers while creating certification backlogs at accredited testing facilities. Mid-tier brands now pre-submit portfolios 8-12 months ahead of planned launches to secure market access.
Water-stressed households across the Gulf Cooperation Council states increasingly specify drum washing machines with sub-40 liter cycle consumption over traditional agitator designs. Retail channels in Dubai and Doha report accelerating substitution of top-load units with front-load alternatives despite 20-30% price premiums. Egyptian and Jordanian markets show parallel preference migration as municipal water rationing intensifies during summer months.
Middle East and Africa Home Appliances Market Segmentation
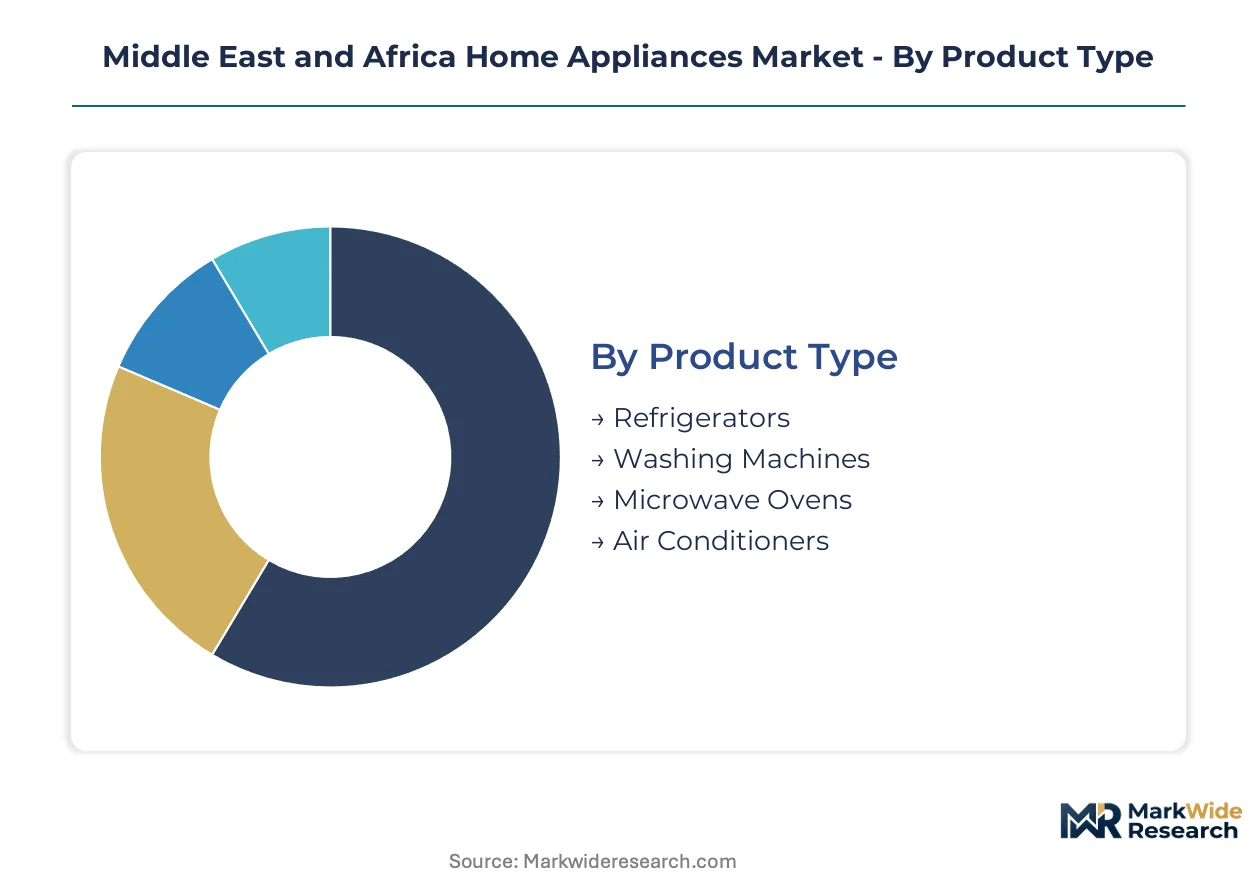
Segmentation across the Middle East and Africa Home Appliances Market reveals divergent purchasing logic between Gulf urban households prioritizing energy ratings and African commercial buyers optimizing capital deployment. Understanding these fault lines enables targeted product portfolio allocation and channel investment decisions.
Product Type:
Product selection across this market tracks ambient climate severity and water availability rather than discretionary preference.
- Refrigerators:Units range from 150-liter single-door to 600-liter French-door configurations with inverter compressors and multi-zone cooling. Saudi Arabia and the UAE drive specification upgrades toward frost-free designs and energy labeling compliance under SASO mandates.
- Washing Machines:Front-load drum designs with sub-40 liter cycle consumption displace top-load agitators in water-stressed Gulf markets despite price premiums. Egyptian and Jordanian municipalities intensify summer rationing, accelerating this substitution pattern.
- Microwave Ovens:Solo and convection variants serve compact urban kitchens in Cairo and Casablanca high-rise developments.
- Air Conditioners:Split-type inverter units dominate residential installation across Dubai, Riyadh, and Jeddah.
Volume sits with refrigerators; growth tilts toward washing machines.
End User:
End-user categories separate replacement-cycle predictability from infrastructure-dependent expansion potential.
- Households:Urban residential construction across Riyadh, Dubai, and Cairo creates first-time buyer pipelines for built-in kitchen appliances and climate control systems. SASO energy labeling mandates force technology upgrades among existing owners.
- Restaurants:Commercial food service operators in Lagos and Nairobi specify heavy-duty refrigeration and meal preparation equipment for extended operating hours.
- Hotels:Hospitality developments along Saudi Arabia's Red Sea coast and UAE tourism corridors demand integrated appliance suites with centralized energy management.
- Offices:Corporate facilities in Johannesburg and Cape Town prioritize compact refrigeration and beverage preparation units for pantry installations.
Households anchor current revenue; hotels and restaurants are expanding most quickly.
Technology:
Technology tiers map to electricity tariff structures and smart city infrastructure maturity across the region.
- Smart Appliances:Wi-Fi-enabled refrigerators and air conditioners integrate with home energy management platforms. Saudi and UAE smart city developments enable utility-linked demand response programs.
- Energy Efficient:Inverter compressor technology reduces electricity consumption versus conventional units, justifying premium positioning in high-tariff Gulf markets.
- Traditional:Fixed-speed compressors and mechanical controls serve price-sensitive segments in secondary Egyptian and Nigerian cities.
- IoT-enabled:Connected appliances with predictive maintenance capabilities target commercial installations in Dubai and Riyadh where downtime costs exceed hardware premiums.
Energy efficient models dominate transaction volume; smart appliances claim the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects trust requirements for durable goods and installation complexity variations.
- Online Retail:E-commerce platforms capture growing share for standardized small appliances in Saudi Arabia and the UAE. Delivery infrastructure limitations constrain penetration in Nigerian and Egyptian secondary cities.
- Offline Retail:Electronics hypermarkets and dedicated appliance stores dominate actual transaction volume across the region. Physical inspection remains critical for major appliance purchases.
- Direct Sales:HVAC contractor networks capture replacement-cycle revenue in commercial and residential cooling segments, bypassing traditional retail markup.
- Wholesale:Distributors supply independent retailers and construction project installers across North African and Sub-Saharan markets.
Offline retail holds volume concentration; direct sales channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Gulf Cooperation Council states where residential construction and energy efficiency mandates drive replacement cycles. Saudi Arabia and the UAE anchor volume, while South Africa and Egypt shape competitive access through regulatory compliance requirements.
Saudi Arabia
Urban households in Riyadh and Jeddah upgrade kitchen and cooling equipment as residential construction accelerates. SASO mandates energy efficiency labeling for imported air conditioners and refrigerators, forcing technology upgrades among existing owners. The Eastern Province industrial corridor hosts assembly operations serving domestic distribution.
United Arab Emirates
Dubai's high-rise developments create first-time buyer pipelines for built-in kitchen appliances and climate control systems. MOHAP oversees product safety standards alongside municipal building codes. Abu Dhabi's smart city developments enable utility-linked demand response programs for connected appliances.
South Africa
Johannesburg and Cape Town corporate facilities prioritize compact refrigeration for pantry installations. The National Regulator for Compulsory Specifications enforces safety standards on electrical appliances, creating compliance cost barriers. Durban serves as the primary import gateway for regional distribution.
Egypt
Cairo's compact urban kitchens drive microwave and refrigeration demand in high-rise developments. The Consumer Protection Agency exercises growing oversight on warranty terms and after-sales service commitments. The Suez Canal Economic Zone anchors North African assembly partnerships for regional fulfillment.
Nigeria
Grid expansion and generator-dependent households in Lagos and Abuja represent demand for low-wattage, voltage-stabilized appliances. The country's national standards regulator maintains import compliance requirements for electrical safety. Kano's commercial corridors concentrate wholesale distribution for West African markets.
Middle East and Africa Home Appliances Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers localize assembly to secure tariff efficiency and faster fulfillment. The vendor base structures across three tiers: multinational electronics conglomerates with regional manufacturing bases, mid-scale regional assemblers serving specific trade blocs, and import-dependent distributors focusing on price-sensitive segments. Strategic archetypes include technology leaders differentiating through inverter compressor innovation, scale players optimizing production costs through captive component supply, and regional specialists leveraging government procurement relationships. Geographic expansion and strategic partnerships represent the dominant competitive moves, with direct-to-installer channel development gaining traction in commercial cooling segments.
Among Asia-Pacific-based conglomerates, Samsung Electronics, Haier Smart Home, and LG Electronics exemplify the integrated manufacturing archetype. Samsung Electronics leverages its Egyptian manufacturing base to anchor North African distribution. Haier Smart Home sustains competitive positioning through localized refrigerator production in South Africa. LG Electronics differentiates via inverter compressor technology leadership across Middle Eastern climate zones.
| Leading Market Players |
|---|
| Samsung Electronics |
| Whirlpool Corporation |
| Haier Smart Home |
| BSH Hausgeräte |
| LG Electronics |
| Electrolux AB |
| Midea Group |
| Panasonic Holdings Corp |
| Gorenje Group |
| Others |
Supply & Pricing Matrix
Captive compressor manufacturing in Thailand and China anchors pricing power for Gulf-market cooling equipment, while Egyptian and South African assembly partnerships compress landed costs for regional brands. This integration choice determines margin sustainability against SASO compliance investments and raw material volatility.
Pricing Analysis
Warranty bundling separates premium positioning from economy tiers, with authorized service networks commanding 15-25% price premiums over gray-market alternatives. Three-tier pricing structure across premium inverter, standard fixed-speed, and economy mechanical-control levels tracks SASO energy grade certification. Price differentiation stems from compressor technology tier and after-sales coverage density. Cost compression in economy segments intensifies because copper and steel input volatility outpaces assembler hedging capacity. Commercial buyers in Saudi Arabia and the UAE exhibit lowest price sensitivity; generator-dependent households in Lagos and Abuja remain most price-constrained.
Supply Chain Analysis
Direct-to-installer channels handle commercial cooling replacement demand across Dubai and Riyadh, bypassing retail markup. Manufacturing concentrates in China, Thailand, and South Korea for compressor and control module supply. Component sourcing draws from Vietnamese sheet metal, Egyptian plastic molding, and Turkish copper winding operations. Single-source compressor dependency creates vulnerability to Red Sea shipping disruptions. Distribution runs through Durban for South African domestic supply and Suez Canal Economic Zone transshipment for North African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SASO energy labeling mandates erect barrier-to-entry moats favoring pre-certified incumbents with testing laboratory relationships.
For Market Incumbents: Acquire accredited testing facility partnerships to compress SASO certification timelines from six months to ninety days. Expand inverter compressor in-house production to reduce Thai import dependency. Defend against mid-tier Egyptian assemblers by locking HVAC contractor networks through exclusive spare parts supply agreements.
For New Entrants and Emerging Players: Launch via direct-to-installer channels targeting commercial cooling replacement cycles in Jeddah and Abu Dhabi. Prioritize Nigerian voltage-stabilized product lines for generator-dependent households in Lagos. White-space concentration sits with low-wattage refrigerators for grid-expansion zones where formal retail remains underdeveloped.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale acquisition by Asia-Pacific conglomerates seeking North African manufacturing footholds. Five-to-ten year viability favors regional assemblers with government procurement relationships and captive component supply. Monitor SASO specification expansion announcements as inflection signal for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Technology Licensing | LG Electronics and Samsung anchor premium positioning through variable-speed cooling IP across Gulf climate zones. |
| Regional Assembly Partnership Expansion | Haier's South African refrigerator production demonstrates tariff efficiency gains for sub-Saharan distribution. |
| SASO Pre-Certification Investment | Eight-to-twelve month advance submission timelines secure market access against testing facility backlogs. |
| HVAC Contractor Network Development | Direct-to-installer channels capture commercial replacement revenue bypassing traditional retail markup. |
| Photovoltaic-Integrated Cooling Launch | DC-powered compressor architectures with rooftop solar integration compress payback periods in Saudi high-insolation zones. |
Research Methodology
Trade databases, customs records, and regulatory filing repositories formed the secondary backbone for this analysis. Primary interviews with appliance manufacturing executives, SASO certification specialists, HVAC contractor network managers, and retail category buyers validated demand assumptions. Bottom-up and top-down triangulation reconciled production capacity data with channel inventory flows across Egyptian, South African, and Gulf distribution nodes.
Bottom-up modeling anchored volume projections to housing completion data and replacement-cycle assumptions across the analysis window. Segmentation dimensions included product type, technology tier, end-user category, and distribution channel. CAGRs derived from regression analysis of historical penetration rates against income and electrification proxies. Inverter diffusion curves and SASO compliance cost trajectories served as industry-specific forecast inputs.
Regulatory specification expansion, raw material price spikes, and currency volatility against the dollar are the dominant revision risks. Forecasts reflect base-case assumptions regarding SASO enforcement consistency and Suez Canal transit reliability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Kuwait Home Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Brazil Home Appliances Market
Home Appliances
UAE Small Home Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
Residential Washing Machine Market
Home Appliances
Household Fridge Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
China Home Appliances Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
Built-In Appliance Market