
 Global Total Knee Replacement Market | 2026-2036
Global Total Knee Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Total Knee Replacement Market Foresight
Cross-linked polyethylene is expanding its share against conventional ultra-high-molecular-weight polyethylene in tibial insert manufacturing, cutting wear debris and extending implant longevity. Zimmer Biomet leverages integrated robotic platforms to anchor its position in precision-aligned procedures. Stryker sustains competitive pressure through its Mako SmartRobotics ecosystem, while Smith & Nephew differentiates via cementless fixation systems optimized for younger, active patient cohorts.
Total knee replacement denotes the surgical resurfacing of damaged knee joint surfaces with metallic and polymeric prosthetic components, typically featuring cobalt-chromium femoral runners, titanium tibial trays, and polyethylene inserts engineered to restore kinematic function and alleviate end-stage arthritic pain. Fixed bearing implants retain dominant commercial share due to established clinical track records and surgeon familiarity, though robotic-assisted surgery represents the fastest-expanding technology segment as hospitals justify capital expenditure through reduced revision rates and shortened length of stay. Cemented fixation commands the largest application volume, while cementless designs capture margin pools in premium segments targeting younger patients with stronger bone stock.
The FDA governs premarket notification and quality system regulation for U.S. device commercialization, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements across European markets, and Japan's PMDA maintains rigorous biocompatibility and long-term durability testing protocols that shape product development timelines. These layered approval frameworks compel manufacturers to maintain parallel regulatory capabilities and region-specific dossier strategies. Stakeholders must weigh capital allocation between robotic platform deployment and next-generation bearing surface innovation as reimbursement thresholds tighten across major markets.
Market Dynamics
Robotic-assisted surgical platforms are compressing revision rates and length-of-stay metrics, forcing hospitals to justify capital outlays against measurable outcome improvements rather than traditional implant cost benchmarks.
Growth Catalysts
- Aging Demographics:Germany, Japan, and the United States face accelerating osteoarthritis prevalence as populations over 65 expand, creating procedure volume tailwinds in reimbursed healthcare systems.
- FDA 510(k) Streamlining:The FDA's premarket notification pathway for robotic-assisted knee systems accelerates technology commercialization timelines compared to full PMA review cycles.
- Cross-linked Polyethylene:Advanced bearing surfaces cut wear debris generation and extend implant functional longevity, reducing revision burden and total lifetime cost of care.
Market Restraints
- Cobalt-Chromium Supply Concentration:Specialty alloy production clusters in limited foundry geographies, exposing manufacturers to input volatility and geopolitical sourcing risk.
- EMA MDR Clinical Evidence Burden:The European Medical Device Regulation imposes stricter post-market surveillance and clinical data requirements, extending dossier preparation timelines.
- Alternative Conservative Therapies:Biologic injections and osteotomy procedures retain preference among younger patients with partial joint involvement, delaying arthroplasty conversion.
Strategic Opportunities
- Outpatient Migration:Ambulatory surgery centers in the United States capture shifting reimbursement incentives favoring same-day discharge protocols.
- Cementless Fixation Expansion:Porous titanium coatings and biologic ingrowth surfaces open premium segments for active patients under 60 with preserved bone stock.
- AI-Assisted Preoperative Planning:Machine learning algorithms converging with robotic execution platforms enable personalized implant sizing and alignment predictions.
Industry Challenges
- Robotic System Integration Complexity:Hospitals face steep learning curves combining capital equipment deployment with surgeon retraining and OR workflow redesign.
- PMDA Durability Testing Timelines:Japan's Pharmaceuticals and Medical Devices Agency mandates extended biocompatibility and wear testing protocols that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Total Knee Replacement Market |
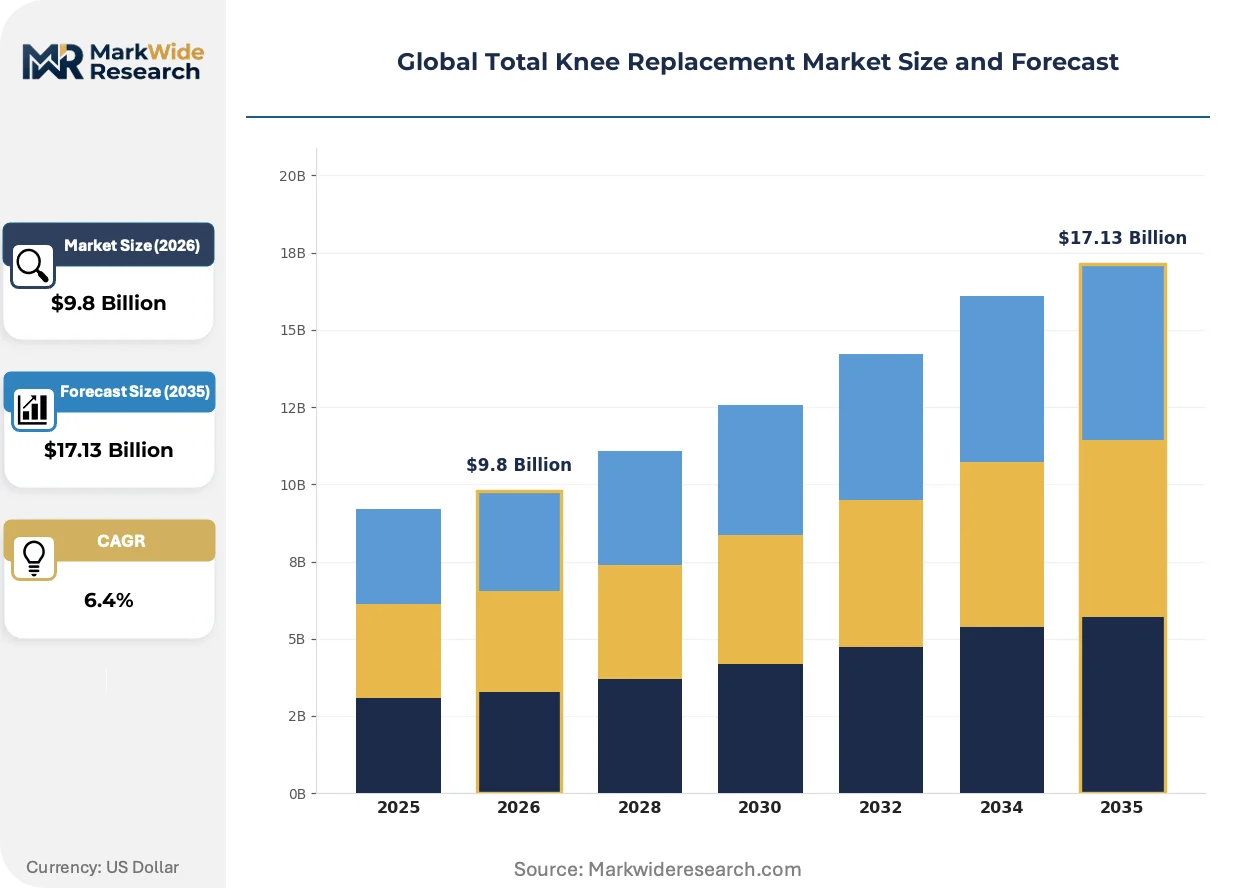
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Bearing, Mobile Bearing, Cemented, Cementless, Hybrid Technology: Patient-Specific Implants, Minimally Invasive Surgery, Robotic-Assisted Surgery, Navigation Systems Application: Osteoarthritis, Rheumatoid Arthritis, Post-Traumatic Arthritis, Avascular Necrosis End User: Orthopedic Clinics, Ambulatory Surgery Centers, Specialized Hospitals, Outpatient Facilities |
| Companies Covered | Zimmer Biomet, Stryker, DePuy Synthes, Smith & Nephew, MicroPort Scientific Corporation, ConforMIS, Exactech, Medacta International, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Total Knee Replacement Market Shifts & Advancements
Digital surgical ecosystems and advanced biomaterials are restructuring how knee replacement value is measured, shifting competitive advantage from implant hardware alone to integrated procedural outcomes.
Patient-specific instrumentation derived from preoperative CT or MRI datasets is absorbing planning variability into disposable cutting guides. Academic medical centers in Germany and the United States adopt these workflows fastest, compressing operative time and reducing alignment outliers that drive early polyethylene wear.
REACH regulation across European Union member states tightens scrutiny of cobalt and chromium compound handling in manufacturing facilities. Suppliers must document substance registration and safe-use protocols, raising compliance overhead for alloy sourcing while accelerating exploration of titanium-zirconium alternatives in femoral component production.
Hospital procurement committees now bundle implant selection with robotic platform access and post-acute care coordination. This consolidated purchasing compresses vendor fragmentation, favoring suppliers offering capital equipment, disposable instruments, and remote technical support under unified contracts. The United States exhibits this consolidation most acutely as health systems absorb independent ASC networks.
Global Total Knee Replacement Market Segmentation
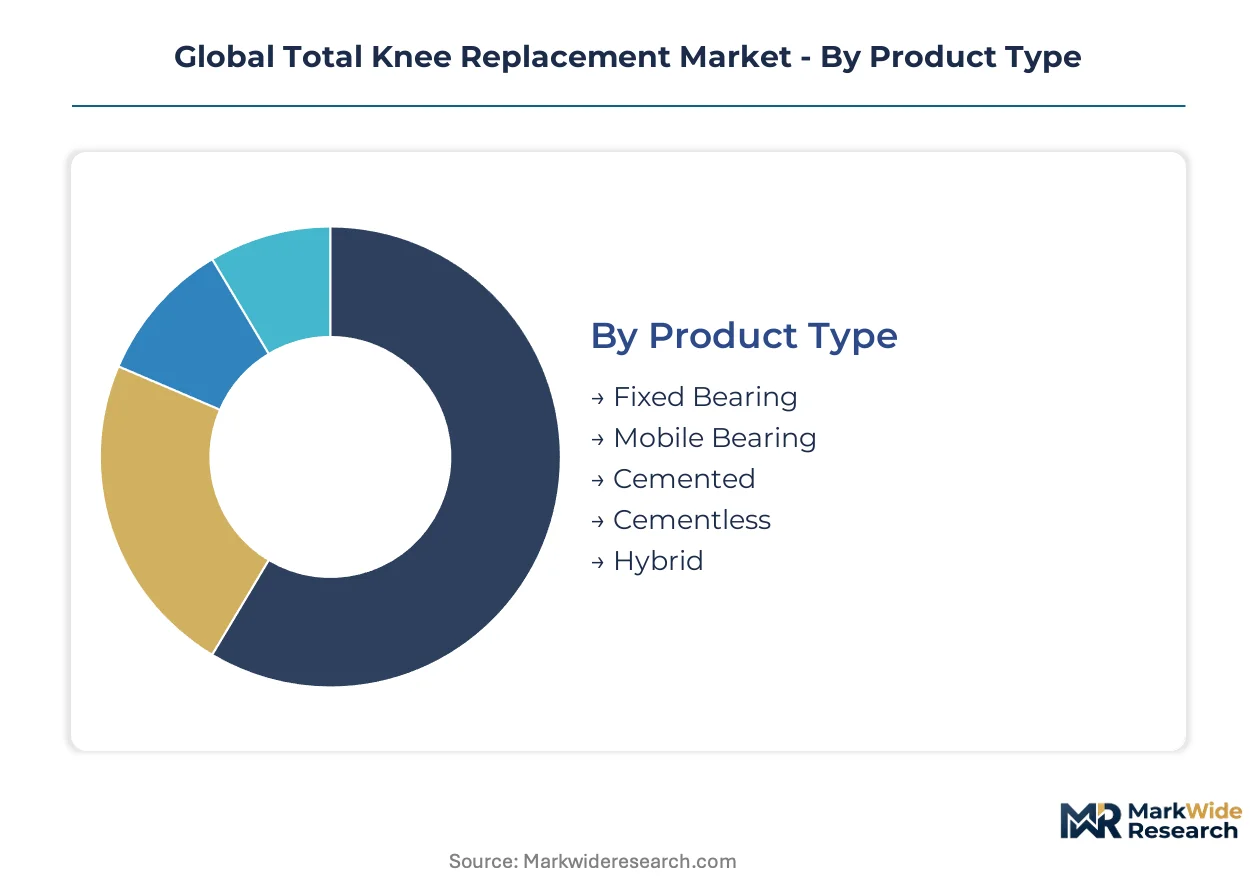
Segmentation in total knee replacement reveals distinct capital allocation profiles across implant hardware, enabling technologies, and care delivery settings. Manufacturers must align R&D spending with segment-specific reimbursement pathways and surgeon training requirements.
Product Type:
Capital intensity varies sharply across fixation and bearing configurations, with robotic-compatible implant systems demanding the steepest upfront tooling investment.
- Fixed Bearing:Cobalt-chromium femoral components mate with locked polyethylene tibial inserts. Demand concentrates in Germany and the United States where established surgeons prioritize proven wear characteristics over mobility features.
- Mobile Bearing:Rotating platform designs reduce shear stress on polyethylene through self-aligning articulation. Japanese hospitals and academic centers in the United States adopt these for younger patients seeking greater range of motion, though bearing dislocation risk constrains universal uptake.
- Cemented:Polymethylmethacrylate fixation dominates elderly patient protocols.
- Cementless:Porous titanium and hydroxyapatite coatings enable bone ingrowth.
- Hybrid:Combines cemented tibial and cementless femoral components.
Fixed bearing implants absorb the bulk of installed capacity; cementless designs are expanding most quickly among patients under 60.
Technology:
Technology segments stratify by integration complexity, with navigation systems requiring lower capital outlays than full robotic platforms.
- Robotic-Assisted Surgery:Haptic-guided cutting tools execute preoperative plans with sub-millimeter precision. United States health systems justify capital expenditure through reduced revision rates and shortened length of stay, while Germany's university hospitals leverage these systems for training and outcomes research.
- Patient-Specific Implants:Additive-manufactured components match individual anatomy from CT datasets. Japanese orthopedic centers and specialized United States clinics drive adoption where off-the-shelf sizing fails morphological outliers.
- Minimally Invasive Surgery:Quadriceps-sparing approaches reduce soft tissue trauma.
- Navigation Systems:Optical or electromagnetic tracking guides manual instrumentation.
Robotic-assisted platforms command the highest capital commitment; patient-specific implants show the steepest expansion trajectory among younger, active cohorts.
Application:
Application segments diverge by patient age distribution and timing of surgical intervention relative to conservative therapy failure.
- Osteoarthritis:Degenerative cartilage loss drives the vast majority of procedures. Germany, Japan, and the United States exhibit concentration as aging demographics expand the addressable population within reimbursed systems.
- Post-Traumatic Arthritis:Fracture sequelae and ligament injury progression necessitate late-stage reconstruction. United States trauma centers and German referral hospitals manage complex deformity cases requiring custom implant solutions.
- Rheumatoid Arthritis:Inflammatory joint destruction affects multiple compartments.
- Avascular Necrosis:Subchondral bone collapse from vascular compromise.
Osteoarthritis accounts for the dominant procedure volume; post-traumatic arthritis is climbing fastest as trauma survival rates improve.
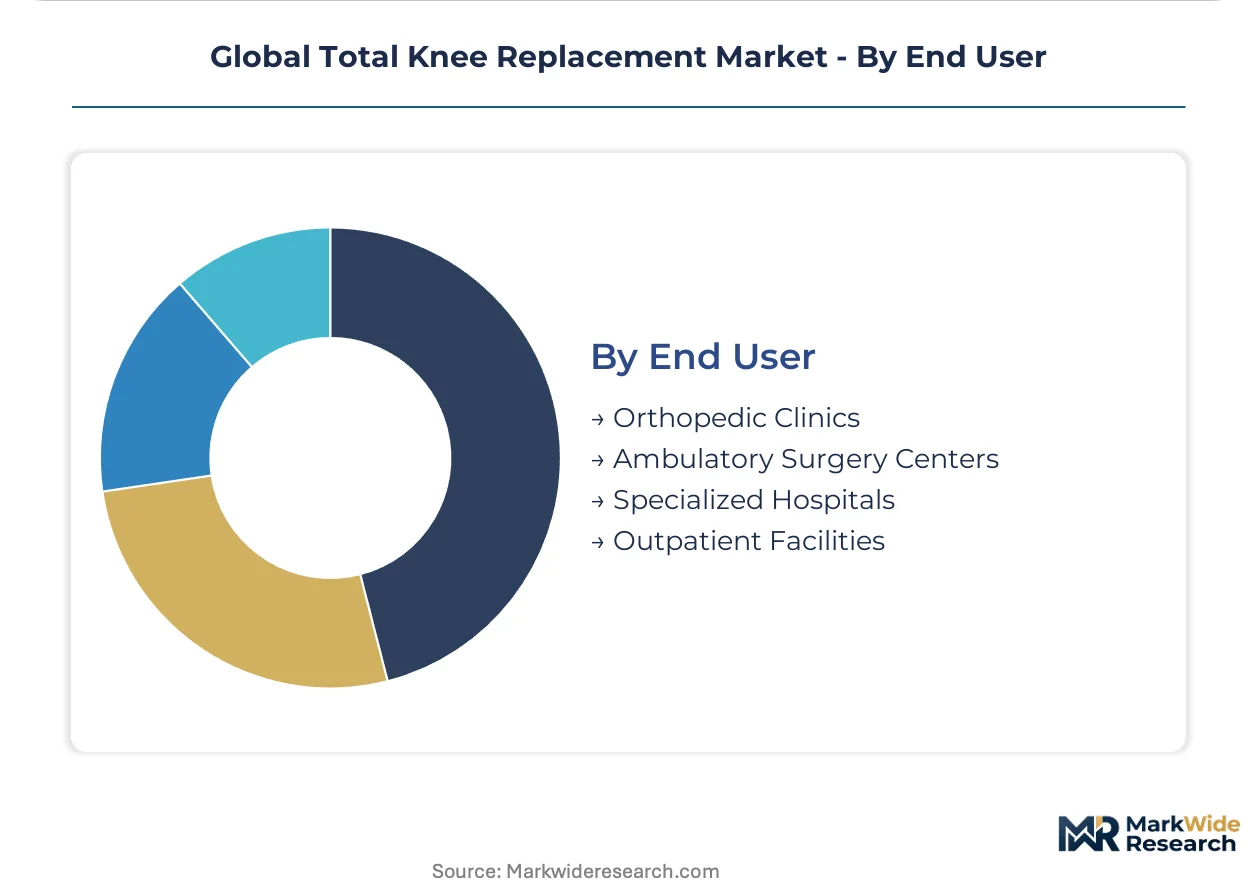
End User:
End user segments reflect diverging facility economics, with ambulatory settings capturing migration from inpatient reimbursement frameworks.
- Ambulatory Surgery Centers:Same-day discharge protocols reduce facility fees and accelerate patient throughput. United States ASC networks absorb shifting Medicare reimbursement incentives, while German day-clinic structures expand under DRG pressure.
- Specialized Hospitals:Academic medical centers manage complex revision cases and training pipelines. Japan's national university hospitals and United States teaching institutions concentrate research activity and high-complexity referrals.
- Orthopedic Clinics:Physician-owned settings handle routine primary procedures.
- Outpatient Facilities:Hospital-based units without overnight admission.
Specialized hospitals retain the deepest installed base; ambulatory surgery centers are gaining share fastest where reimbursement alignment permits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procedure volume concentrates in three reimbursed healthcare systems where aging demographics and orthopedic infrastructure align. The United States, Germany, and Japan absorb the dominant share of implant demand, while regulatory frameworks and care delivery models diverge sharply across these markets.
United States
Medicare reimbursement shifts favor ambulatory surgery center migration for same-day discharge protocols. The FDA's 510(k) pathway accelerates robotic-assisted system commercialization compared to PMA review cycles. Academic medical centers in Boston and the Midwest concentrate training pipelines and outcomes research for precision-aligned procedures.
Germany
DRG pressure expands day-clinic structures while university hospitals leverage robotic platforms for training and research. The EMA's Medical Device Regulation imposes stricter clinical evidence requirements than predecessor directives. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host precision machining suppliers for cobalt-chromium femoral components.
Japan
PMDA mandates extended biocompatibility and wear testing protocols that compress product launch windows for foreign manufacturers. National university hospitals in Tokyo and Osaka concentrate complex revision case volume and research activity. Mobile bearing designs find preference among younger patients seeking greater range of motion.
United Kingdom
NICE technology appraisals shape implant procurement criteria across NHS trusts. Brexit-related regulatory divergence from EU MDR frameworks creates parallel compliance obligations for manufacturers. Specialist orthopedic centers in London and the Midlands drive adoption of patient-specific instrumentation workflows.
Switzerland
Swissmedic maintains rigorous quality system oversight that aligns with but exceeds EU baseline requirements. Premium reimbursement tiers support cementless fixation adoption among active patient cohorts under 60. Basel and Zurich anchor research collaborations between university hospitals and precision engineering suppliers.
Global Total Knee Replacement Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated robotic platform vendors commanding premium positioning against implant-only suppliers. The vendor base stratifies into three tiers: diversified medtech conglomerates with capital equipment ecosystems, mid-scale orthopedic pure-plays with regional density, and emerging specialists in additive manufacturing or patient-specific solutions. Dominant competitive moves include strategic partnerships bundling implants with enabling technologies, and geographic expansion through distributor acquisition in underpenetrated Asian markets.
Among diversified medtech conglomerates, Zimmer Biomet, Stryker, and Smith & Nephew represent the capital-intensive tier anchoring competitive dynamics. Zimmer Biomet exemplifies integrated robotic platform strategy, Stryker occupies a position within haptic-guided surgical ecosystems, and Smith & Nephew anchors cementless fixation specialization for younger patient cohorts. These three entities collectively illustrate how scale, technology integration, and biomaterial innovation define strategic positioning in precision-aligned knee replacement procedures.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| DePuy Synthes |
| Smith & Nephew |
| MicroPort Scientific Corporation |
| ConforMIS |
| Exactech |
| Medacta International |
| B. Braun |
| Others |
Supply & Pricing Matrix
Orthopedic machining specialists concentrated in Baden-Württemberg and North Rhine-Westphalia anchor femoral component production, with labor-cost differentials between German precision engineers and Asian contract manufacturers driving three-tier spreads across premium robotic-compatible implants, standard fixed-bearing systems, and economy tibial trays.
Pricing Analysis
Volume-margins split sharply between cemented fixed-bearing implants commanding commodity-scale procurement and robotic-assisted platform bundles capturing premium positioning. Price differentiation rests on CE marking tier and surgeon training certification depth, with FDA 510(k) clearance adding measurable brand premium. Cost compression in standard polyethylene inserts intensifies as hospital GPOs consolidate vendor panels. Ambulatory surgery centers exhibit acute price sensitivity; academic medical centers prioritize outcome metrics over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with cobalt-chromium alloy foundries clustered in Germany, the United States, and Japan. Raw material dependencies encompass titanium sponge from Ukrainian and Russian feedstock, polyethylene resin from Saudi and South Korean petrochemical complexes, and hydroxyapatite coatings from specialized Japanese ceramics producers. Tariff exposure on Chinese-sourced precision instrumentation compresses margin buffers. Distribution runs through hospital procurement committees and orthopedic GPOs consolidating implant, instrument, and capital equipment sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The total knee replacement market sits in a technology-transition phase as robotic-assisted surgical platforms displace conventional manual instrumentation, with haptic-guided cutting tools replacing mechanical alignment jigs across reimbursed health systems.
For Market Incumbents: Lock in surgeon training pipelines and service contracts to defend installed base against emerging robotic pure-plays. Prioritize backward integration into cobalt-chromium foundry capacity to offset alloy supply volatility. Cementless fixation R&D represents the critical lever for capturing younger patient lifetime value. For New Entrants and Emerging Players: Begin with patient-specific instrumentation workflows targeting morphological outliers underserved by off-the-shelf sizing. The most penetrable white space sits in additive-manufactured tibial trays for revision cases. A direct-to-ASC distribution model bypasses consolidated hospital procurement committees. For Investors and Strategic Acquirers: Re-rating potential sits with cementless fixation specialists given EMA MDR durability data requirements creating regulatory moats. Long-term viability centers on platforms spanning implant hardware, enabling software, and post-acute monitoring. Watch PMDA approval timelines as the inflection signal for Japanese market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Platform Integration | Haptic-guided systems reduce revision rates that justify capital expenditure across US health systems. |
| CE Marking Pathway | MDR clinical evidence requirements extend dossier timelines but create defensive positioning for compliant manufacturers. |
| Hospital System Partnership | Bundled contracts spanning implants, instruments, and remote technical support compress vendor fragmentation. |
| Software Companion Development | AI-assisted preoperative planning algorithms differentiate precision-aligned procedure offerings. |
| Reimbursement Strategy | Medicare ASC migration incentives reshape procurement criteria toward same-day discharge protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EMA MDR submission logs, PMDA approval registries, and hospital procurement databases supplied segmentation validation. Bottom-up implant volume estimates reconciled with top-down healthcare expenditure flows.
Data-stream reconciliation across procedure registries, capital equipment shipment records, and implant utilization surveys informed the analytical framework. Segmentation dimensions encompassed fixation type, bearing configuration, technology integration level, patient age cohort, and regional regulatory cluster. CAGRs derived from logistic diffusion curves modeling robotic adoption saturation. Forecast inputs incorporated DRG reimbursement trajectory shifts and ambulatory surgery center network expansion.
Underlying measurement precision varies by segment; robotic-assisted surgery and patient-specific implants carry tighter precision than commodity fixed-bearing volumes given disclosed capital expenditure and regulatory filing transparency. Forecasts reflect documented assumptions regarding surgeon training velocity and ASC reimbursement alignment. Deviation in PMDA durability testing timelines or cobalt-chromium supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Total Wrist Prosthesis Market
Orthopedic Devices
Smart Orthopedic Implants Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Devices Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Global Spinal Fusion Devices Market
Orthopedic Devices
Hip Resurfacing Implants Market