
 Distal Compression Plates Market | 2026-2036
Distal Compression Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Distal Compression Plates Market Outlook
Implant maintenance and surgical navigation software subscriptions is broadening revenue streams beyond hardware sales for manufacturers serving the distal compression plates space. Stryker leverages its integrated trauma platform to sustain high attach rates for proprietary screw systems. Zimmer Biomet anchors its competitive stance through specialized distal radius plating portfolios that dominate North American teaching hospitals.
Distal compression plates are rigid internal fixation devices engineered from titanium or stainless steel alloys, typically ranging from 1.5 mm to 3.5 mm in thickness, designed to stabilize metaphyseal and epiphyseal fractures through controlled compression across the fracture site while preserving periosteal blood supply. Locking plate configurations now lead volume shipments due to their angular stability in osteoporotic bone, while biodegradable polymer plates represent the fastest-growing material segment as surgeons seek to eliminate secondary removal procedures. Ambulatory surgical centers are capturing disproportionate margin pools as case migration accelerates from inpatient settings.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape product development cycles and market access timelines for distal compression plate manufacturers. ISO 5832 standards for metallic implant materials and ASTM F138 specifications for surgical stainless steel govern material qualification protocols that directly influence procurement decisions by hospital value analysis committees. Stakeholders must monitor evolving CMS procedural reimbursement codes and hospital bundled payment models that increasingly determine whether advanced plating systems secure formulary placement.
Market Dynamics
Locking plate configurations are displacing conventional compression systems across trauma centers, driven by angular stability requirements in osteoporotic fracture fixation and surgeon preference for single-assembly constructs.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States sustain procedural volumes through expanding elderly populations requiring distal radius and tibia fracture stabilization.
- FDA 510(k) Streamlining:Predicate device pathways accelerate clearance timelines for titanium alloy plate iterations, compressing commercialization cycles for manufacturers.
- Biodegradable Polymers:Poly-lactic acid and poly-glycolic acid plate systems eliminate secondary removal surgeries, capturing surgeon preference in pediatric and geriatric cohorts.
Market Restraints
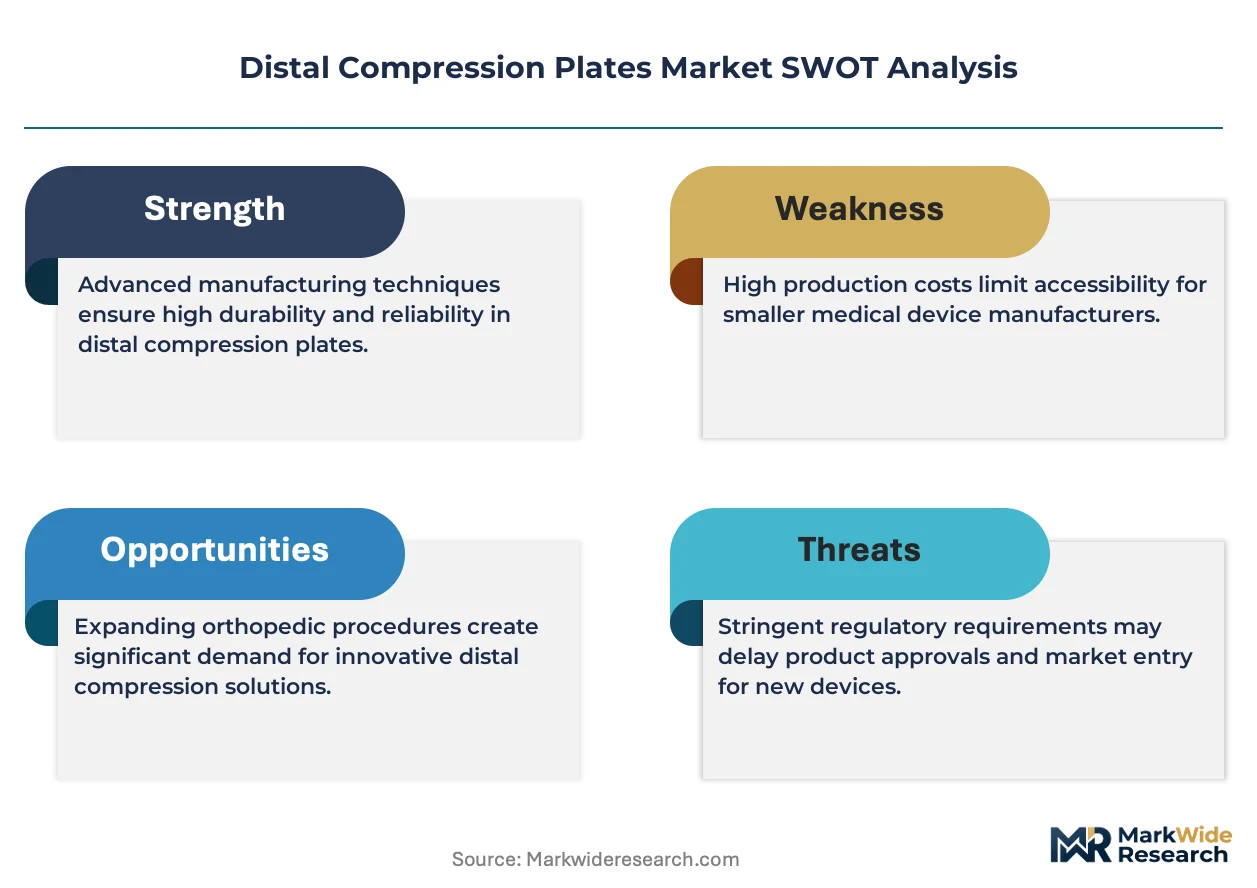
- Titanium Price Volatility:Sponge and alloy input costs fluctuate with aerospace demand cycles, pressuring gross margins for implant manufacturers.
- EU MDR Documentation Burden:Technical file requirements and notified body capacity constraints extend CE marking timelines by 12-18 months versus previous directives.
- External Fixation Substitution:Circular and hybrid frame systems retain cost advantage in open fracture protocols, limiting plating penetration in resource-constrained settings.
Strategic Opportunities
- India Trauma Infrastructure:Government hospital modernization programs and medical device PLI schemes create entry pathways for mid-tier plating manufacturers.
- Ambulatory Surgical Center Migration:Outpatient distal radius fixation protocols expand addressable case volume beyond traditional inpatient settings.
- Patient-Specific Instrumentation:3D-printed surgical guides paired with standard plates reduce operative time and fluoroscopy exposure, differentiating premium offerings.
Industry Challenges
- Surgeon Training Compression:Fellowship programs emphasize arthroplasty over trauma, narrowing the pipeline of skilled open-reduction internal fixation specialists.
- Legacy ERP Integration:Hospital supply chain systems require custom API development to track implant lot numbers against UDI mandates, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distal Compression Plates Market |
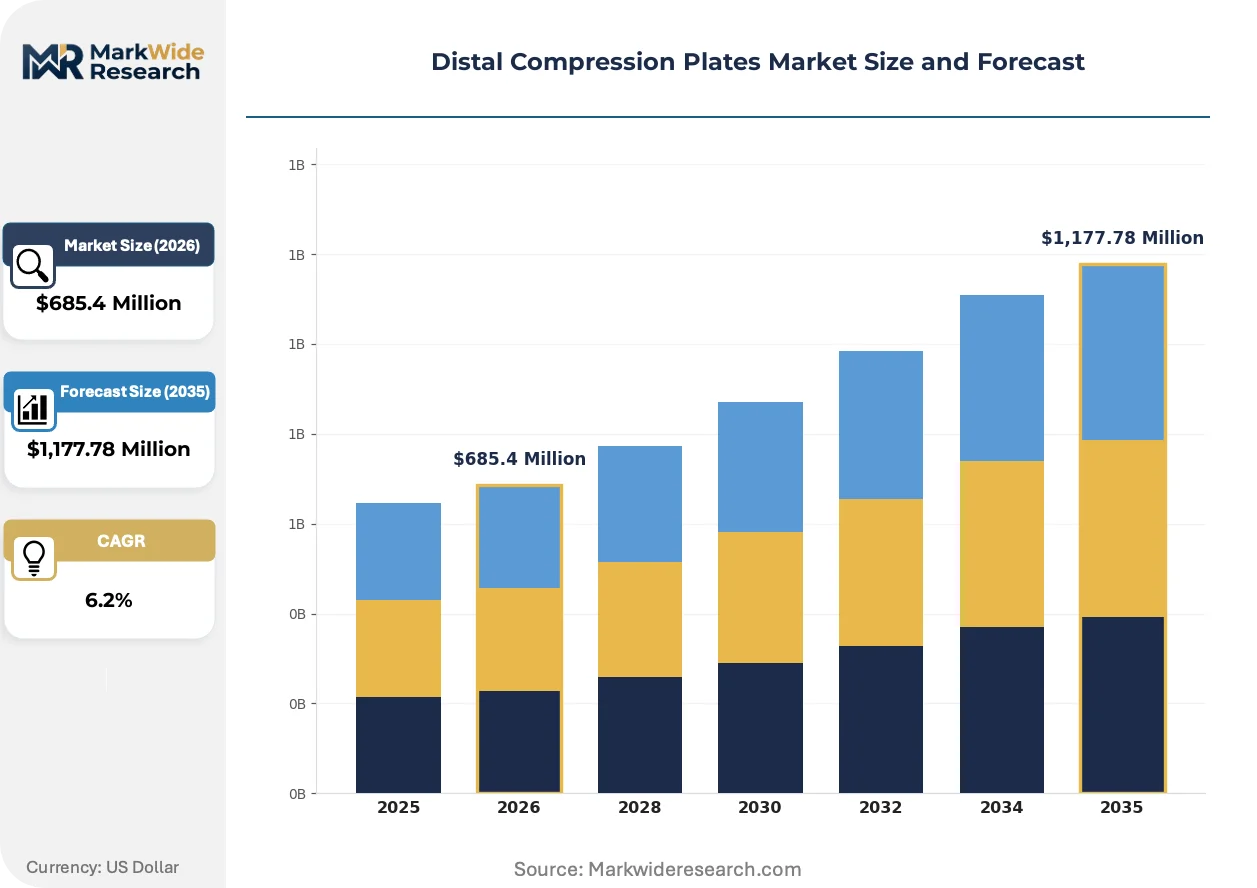
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locking Plates, Non-locking Plates, Cannulated Plates, Hybrid Plates Material: Titanium, Stainless Steel, Polymer, Biodegradable Materials End User: Hospitals, Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Delivery Mode: Surgical, Outpatient, Emergency, Elective |
| Companies Covered | Stryker, Zimmer Biomet, DePuy Synthes, Smith & Nephew, Medtronic, B. Braun Melsungen AG, Acumed, Arthrex, Orthofix Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distal Compression Plates Market Strategic Shifts
Digital preoperative planning platforms and additive manufacturing are converging to reshape how distal compression plates are selected, customized, and deployed in surgical workflows.
Variable-angle locking screw technology is expanding into distal radius and fibular plating systems, permitting intraoperative trajectory adjustment without compromising construct rigidity. Academic medical centers in the United States and Germany are adopting these configurations for complex intra-articular fractures. This flexibility is compressing revision rates and enabling plate standardization across broader fracture pattern indications.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to revalidate clinical data for legacy predicate devices. Small and mid-cap firms face disproportionate compliance costs, triggering portfolio rationalization and accelerated market exits. European orthopedic distributors are consolidating supplier relationships to reduce quality audit burdens.
Hospital value analysis committees now mandate lifecycle cost evidence alongside upfront device pricing, unbundling traditional vendor-procurement relationships. Integrated delivery networks in the United States are negotiating multi-year consignment agreements that shift inventory risk to manufacturers. This behavioral shift is most pronounced in California and Texas health systems with mature bundled payment contracts for orthopedic episodes.
Distal Compression Plates Market Segmentation
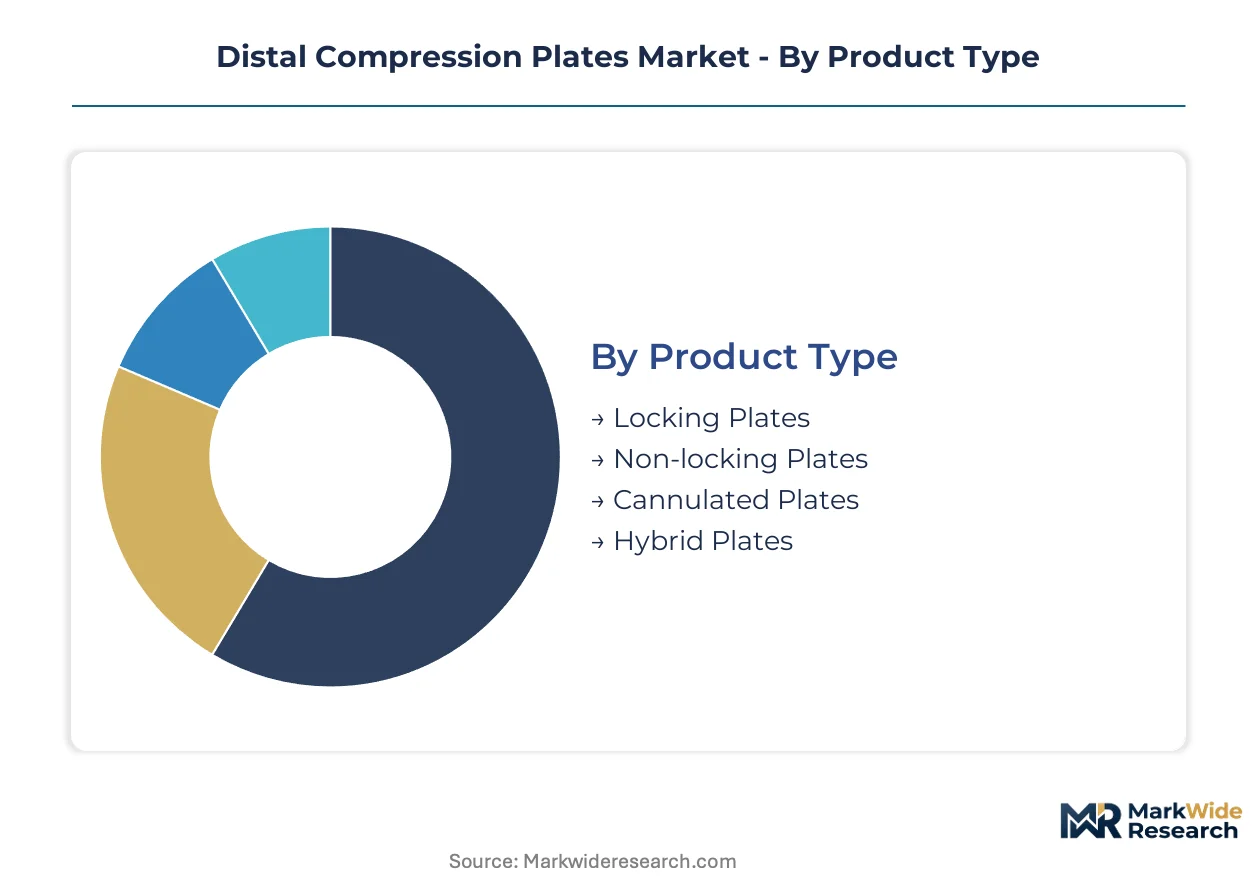
Distal compression plates serve heterogeneous clinical environments from Level I trauma centers to outpatient hand surgery suites. Segmentation reveals how material science, fixation mechanics, and care setting economics stratify procurement patterns across the installed base.
Product Type:
Locking screw-plate interfaces distinguish mechanical performance across fracture stability requirements and bone quality profiles.
- Locking Plates:Fixed-angle screw-plate constructs deliver angular stability in osteoporotic metaphyseal bone without fragment compression. Demand concentrates in United States teaching hospitals managing geriatric distal radius fractures where construct rigidity reduces revision burden.
- Non-locking Plates:Conventional compression plating achieves direct fragment apposition through eccentric screw loading in younger patients with simple fracture patterns. Cost-sensitive procurement in German municipal hospitals sustains residual volume despite technology displacement.
- Cannulated Plates:Hollow screw designs permit guidewire-assisted placement for percutaneous fixation of extra-articular fractures.
- Hybrid Plates:Combined locking-compression holes enable intraoperative construct conversion based on bone quality assessment.
Mature deployment sits with Non-locking Plates. Newer deployment is concentrated in Locking Plates.
Material:
Biocompatibility profiles and secondary procedure economics drive alloy selection against polymer alternatives.
- Titanium:Ti-6Al-4V ELI and commercially pure grades offer favorable strength-to-weight ratios and MRI compatibility. Japanese orthopedic clinics specify titanium for distal tibia plating where long-term implant retention is anticipated.
- Stainless Steel:ASTM F138-compliant 316L variants maintain cost advantage in high-volume trauma settings. Indian government hospital tenders specify stainless steel for budget-constrained distal femur fracture protocols.
- Polymer:PEEK and carbon-fiber-reinforced plates provide radiolucency for postoperative imaging assessment.
- Biodegradable Materials:Poly-lactic acid and poly-glycolic acid copolymers eliminate hardware removal in pediatric populations.
Stainless Steel anchors procurement in established trauma infrastructure. Biodegradable Materials are climbing the fastest in pediatric and geriatric cohorts seeking elimination of secondary procedures.
End User:
Site-of-care economics and reimbursement mechanics fragment demand across institutional categories.
- Hospitals:Inpatient trauma services manage polytrauma and complex intra-articular fractures requiring extended monitoring. United States Level I centers capture high-acuity distal femur and pilon fracture volumes under diagnosis-related group reimbursement.
- Orthopedic Clinics:Specialist-owned facilities concentrate elective distal radius and fibular plating with streamlined scheduling. German ambulatory surgery centers leverage procedure-specific fee schedules for isolated fracture fixation.
- Ambulatory Surgical Centers:Outpatient distal radius protocols exploit bundled payment structures in mature United States markets.
- Rehabilitation Centers:Post-acute settings manage hardware complications and delayed union interventions.
Procedure concentration favors Hospitals for complex trauma. Orthopedic Clinics are gaining share fastest in elective fracture stabilization.
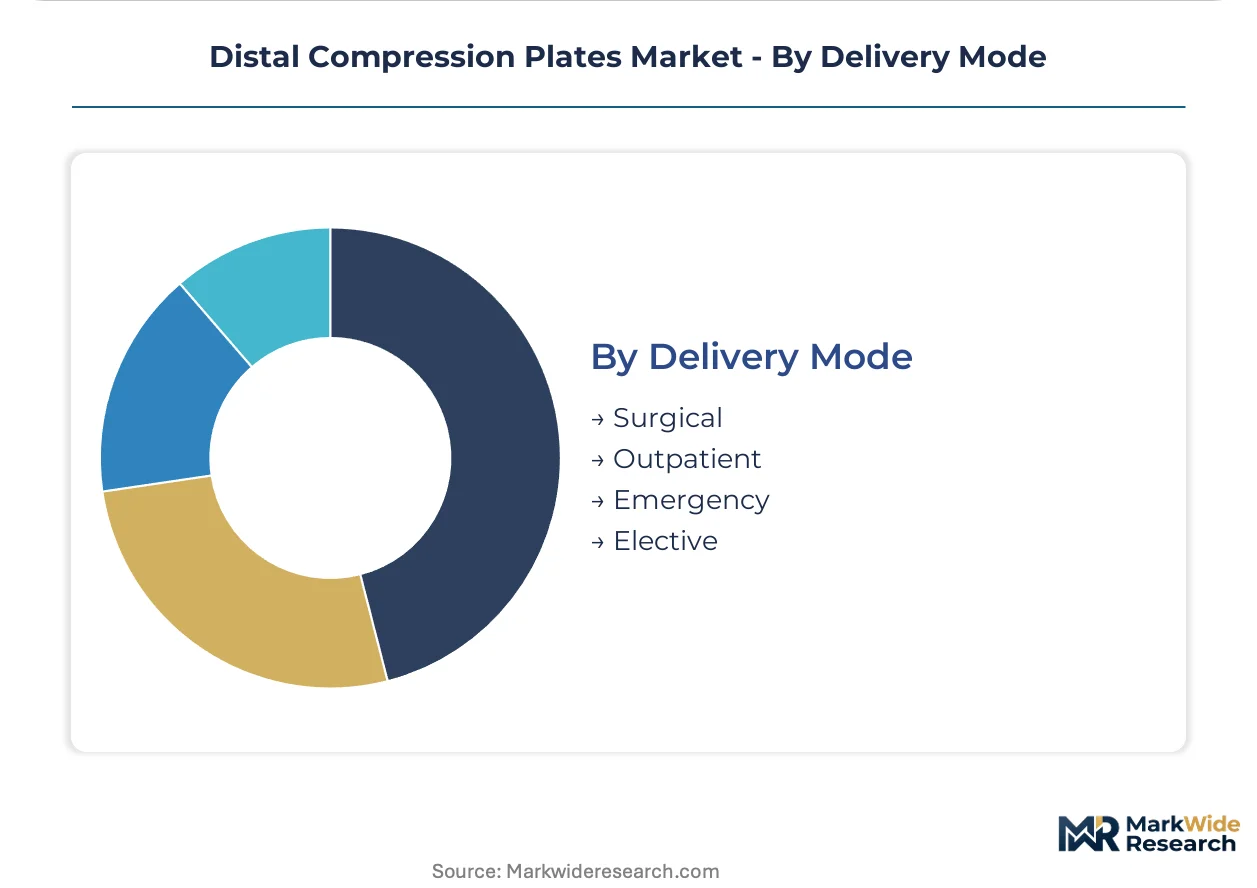
Delivery Mode:
Clinical urgency and scheduling flexibility determine resource allocation and device configuration.
- Surgical:Open reduction internal fixation in operating theater environments requires full sterile instrument sets and fluoroscopy support.
- Outpatient:Same-day discharge protocols demand minimized soft tissue dissection and rapid construct stability.
- Emergency:Trauma bay stabilization of open fractures prioritizes damage control principles with provisional external fixation conversion.
- Elective:Delayed definitive fixation permits swelling resolution and preoperative optimization in complex periarticular injuries.
Emergency deployment dominates acute trauma pathways. Elective scheduling is expanding most quickly in geriatric fracture management programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States where precision machining clusters serve export markets, while procedural consumption clusters in aging economies with high trauma case volumes. The United States, Germany, and Japan absorb the majority of distal compression plate deployments through distinct reimbursement and procurement frameworks.
United States
Geriatric distal radius fractures and polytrauma cases drive procedural volumes at Level I trauma centers in Baltimore and Houston. CMS bundled payment models for orthopedic episodes reshape procurement negotiations, pressuring manufacturers toward consignment inventory arrangements. The Midwest industrial corridor around Warsaw, Indiana anchors domestic plate fabrication and sterile packaging operations.
Germany
Municipal hospital networks in Bavaria and North Rhine-Westphalia sustain demand for both locking and non-locking plate configurations. EU MDR technical documentation requirements extend CE marking timelines, favoring established manufacturers with dedicated regulatory affairs teams. The Tuttlingen surgical instrument cluster supplies precision-machined plate blanks to European OEMs.
Japan
Super-aged demographics in Tokyo and Osaka metropolitan areas generate sustained distal tibia and radius fracture volumes. PMDA marketing authorization pathways prioritize clinical data from domestic patient registries, creating barriers for non-Japanese manufacturers. The Kobe medical device manufacturing zone hosts titanium alloy processing facilities serving domestic orthopedic firms.
India
Government hospital modernization under the Ayushman Bharat scheme expands access to trauma fixation in Maharashtra and Karnataka. CDSCO medical device rules and PLI scheme incentives attract mid-tier manufacturers to establish local assembly operations. The Chennai-Coimbatore corridor emerges as a hub for stainless steel plate fabrication serving price-sensitive public tenders.
United Kingdom
NHS England procurement frameworks standardize distal radius plating protocols across teaching hospitals in London and Manchester. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UKCA marking pathways. The Leeds medical technology cluster supports specialized plating design and rapid prototyping services.
Distal Compression Plates Market Competitive Environment
Top-tier vendors anchor premium pricing through integrated trauma platforms, while mid-cap specialists compete on procedure-specific portfolio depth. The vendor base stratifies across three tiers: multinational conglomerates with broad orthopedic portfolios, regional specialists in extremity fixation, and emerging manufacturers targeting price-sensitive tenders. Two dominant competitive moves define current positioning: M&A activity to acquire locking screw technology IP, and backward integration into titanium alloy forging to secure input cost stability.
Within the multinational tier, Stryker and Zimmer Biomet exemplify platform-centric strategies that bundle plates with proprietary screw systems and surgical navigation tools. DePuy Synthes occupies a position bridging premium and mid-market segments through its trauma heritage and global distribution scale. These three firms collectively represent the consolidation logic driving European distributor rationalization and hospital value analysis committee standardization.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| DePuy Synthes |
| Smith & Nephew |
| Medtronic |
| B. Braun Melsungen AG |
| Acumed |
| Arthrex |
| Orthofix Medical |
| Others |
Value Chain & Pricing Dynamics
Hospital value analysis committees in the United States and Germany concentrate purchasing power for distal compression plates, anchoring procurement around multi-year consignment agreements that shift inventory risk to manufacturers and compress margins through bundled payment exposure.
Pricing Analysis
Margin tightening in mid-tier stainless steel plating traces to Indian government hospital tenders that prioritize lowest-compliant-bid awards over brand premium. Three-tier pricing structure across premium locking systems, standard hybrid constructs, and economy non-locking plates stratifies procurement across academic medical centers, community hospitals, and municipal facilities. Cost-down pressure on titanium alloy variants accelerates because aerospace demand cycles spike sponge input costs. Public tenders in India and Brazil exhibit highest price sensitivity; Japanese teaching hospitals show lowest sensitivity due to PMDA-mandated quality tiers.
Supply Chain Analysis
Explant return flows and plate recycling through authorized refurbishment channels in Germany and the United States recover titanium alloy for reprocessing, reducing virgin material exposure. Manufacturing concentrates in Germany, the United States, and Japan. Raw material dependencies draw from Ukrainian titanium sponge, Chinese rare earth processing, and Swiss precision machining equipment. Single-source vulnerability sits with aerospace-qualified titanium alloy forging capacity. Distribution runs through orthopedic distributor networks that consolidate under EU MDR audit burdens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Distal compression plates occupy a technology-transition phase as variable-angle locking systems displace conventional compression plating across trauma centers, with biodegradable polymers emerging as the next material inflection.
For Market Incumbents: Extend proprietary screw-plate ecosystem dominance by deepening backward integration into titanium alloy forging to neutralize aerospace demand volatility, while accelerating FDA 510(k) predicate device filings to compress clearance timelines against emerging polymer competitors. Locking technology IP consolidation and hospital GPO contract renewals represent critical defensive levers. For New Entrants and Emerging Players: Biodegradable polymer plate systems targeting pediatric and geriatric elimination-of-removal cohorts offer the most penetrable white-space entry. Focus initial commercialization on Indian government hospital modernization programs under PLI scheme incentives, where price-sensitive tenders favor local assembly partnerships over established import brands. For Investors and Strategic Acquirers: The window for entry favors mid-cap manufacturers with dedicated EU MDR regulatory affairs infrastructure and established CE marking pathways for legacy predicate devices. Acquisition targets should demonstrate sterilization validation capabilities and orthopedic distributor relationships. Monitor notified body capacity constraints and MDR Article 10 technical documentation completion rates as inflection signals for European market exit acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation revalidation determines European market access timelines for legacy devices. |
| Backward Integration | In-house titanium alloy forging secures input cost stability against aerospace demand cycle volatility. |
| Hospital System Partnership | Multi-year consignment agreements with IDNs shift inventory risk and lock formulary placement. |
| Software Companion Development | Surgical navigation subscriptions broaden revenue streams beyond hardware-only transactional sales. |
| Reimbursement Strategy | CMS bundled payment alignment secures procedural coverage under orthopedic episode contracts. |
Study Parameters
FDA 510(k) premarket notification databases, EU MDR notified body technical documentation filings, and orthopedic implant procurement records formed the secondary backbone, cross-referenced with primary interviews with trauma surgeons, hospital value analysis committee members, biomedical engineers, and GPO contracts managers. Bottom-up triangulation against top-down macroeconomic drivers validated volume estimates across the analysis window.
Historical procedural volume trendlines in distal radius and tibia fracture fixation established baseline growth patterns, with segmentation modeling across locking versus non-locking constructs, titanium versus stainless steel versus biodegradable materials, and hospital versus ambulatory surgical center site-of-care economics. CAGRs derived from elasticity-adjusted price-volume relationships and demographic trauma incidence projections. Forecast inputs incorporated PMDA marketing authorization pathway timelines and Indian PLI scheme capacity buildout schedules.
Several conditions sit outside the modeled scope, including regulatory pathway disruptions, raw material supply shocks, and reimbursement code revisions. Forecasts reflect documented assumptions about procedural migration rates and competitive pricing behavior. Practitioners should monitor EU MDR notified body capacity expansion, titanium sponge price indices, and CMS orthopedic bundled payment participation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Computer-Assisted Orthopedic Surgery Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market