
 Gas Exchange Monitor Market | 2026-2036
Gas Exchange Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Exchange Monitor Market Analytics
Multi-source procurement for sensor modules is consolidating as manufacturers seek supply security amid semiconductor allocation pressures. COSMED leverages in-house optical sensor fabrication to reduce dependency on external photonics suppliers. Siemens Healthineers anchors its position through captive manufacturing of mass spectrometry components for high-throughput laboratory systems. GE Healthcare competes on geographic dominance, with installed bases across North American academic medical centers creating substantial replacement demand cycles.
A gas exchange monitor measures respiratory gas concentrations and flow rates to calculate metabolic and ventilatory parameters, typically employing infrared absorption spectroscopy at specific wavelengths to quantify carbon dioxide and oxygen fractions with response times under 100 milliseconds. The device serves primarily to assess pulmonary function, diagnose respiratory pathologies, and guide mechanical ventilation in critical care settings. Portable monitors lead volume shipments as point-of-care testing expands beyond traditional pulmonary laboratories, while mass spectrometry technology commands premium positioning in research institutions where simultaneous multi-gas analysis justifies capital intensity. Wireless systems represent the fastest-growing product configuration, driven by telemetry integration with electronic health record platforms and remote patient monitoring infrastructures.
The FDA enforces premarket notification requirements for gas exchange monitors under 21 CFR 892, mandating clinical validation of accuracy claims across intended use populations. The EU Medical Device Regulation requires notified body certification for Class IIa respiratory diagnostic equipment, with EMA pharmacovigilance obligations extending to post-market surveillance of device-related adverse events. ISO 80601-2-55 establishes international safety and performance standards for respiratory gas monitors, shaping design verification protocols that manufacturers must document for market access. Stakeholders should monitor evolving harmonization gaps between FDA predicate device pathways and MDR clinical evidence expectations when prioritizing regulatory submission sequencing.
Market Dynamics
Semiconductor allocation pressures are forcing sensor module procurement consolidation as manufacturers seek captive supply security for photonic components essential to infrared spectroscopy systems.
Growth Catalysts
- EU Medical Device Regulation:The MDR's tightened performance validation requirements for Class IIa respiratory diagnostic equipment is accelerating hospital upgrades to compliant gas exchange monitoring platforms.
- Integrated health networks:Multi-site standardization of pulmonary function testing protocols across United States health systems is creating replacement demand cycles for wireless telemetry-enabled monitors.
- Point-of-care expansion:Portable monitor shipments are accelerating as testing migrates beyond traditional pulmonary laboratories into emergency departments and ambulatory surgical centers.
Market Restraints
- Photonics supply concentration:Dependency on external suppliers for optical sensors creates vulnerability when semiconductor foundry capacity tightens, particularly for infrared wavelength-specific components.
- Mass spectrometry capital intensity:Research institutions face prohibitive acquisition costs for simultaneous multi-gas analysis systems, limiting addressable market penetration despite superior analytical capability.
- ISO 80601-2-55 compliance friction:International safety and performance documentation requirements extend design verification timelines and inflate regulatory submission costs for new market entrants.
Strategic Opportunities
- Remote patient monitoring infrastructure:Wireless system integration with electronic health record platforms opens telemetry-enabled gas exchange monitoring for post-acute and home-based respiratory care.
- German hospital expansion:Non-invasive cardiopulmonary testing equipment adoption is accelerating in German acute care facilities seeking to reduce invasive procedure volumes.
- EMA pharmacovigilance extension:Post-market surveillance obligations for device-related adverse events create recurring revenue streams through compliance monitoring services and software updates.
Industry Challenges
- Predicate device pathway divergence:Harmonization gaps between FDA 510(k) clearance expectations and MDR clinical evidence requirements force manufacturers to maintain dual regulatory submission strategies.
- Legacy system integration complexity:Academic medical centers with extensive installed bases face technical friction when upgrading to wireless telemetry architectures without disrupting existing electronic health record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Exchange Monitor Market |
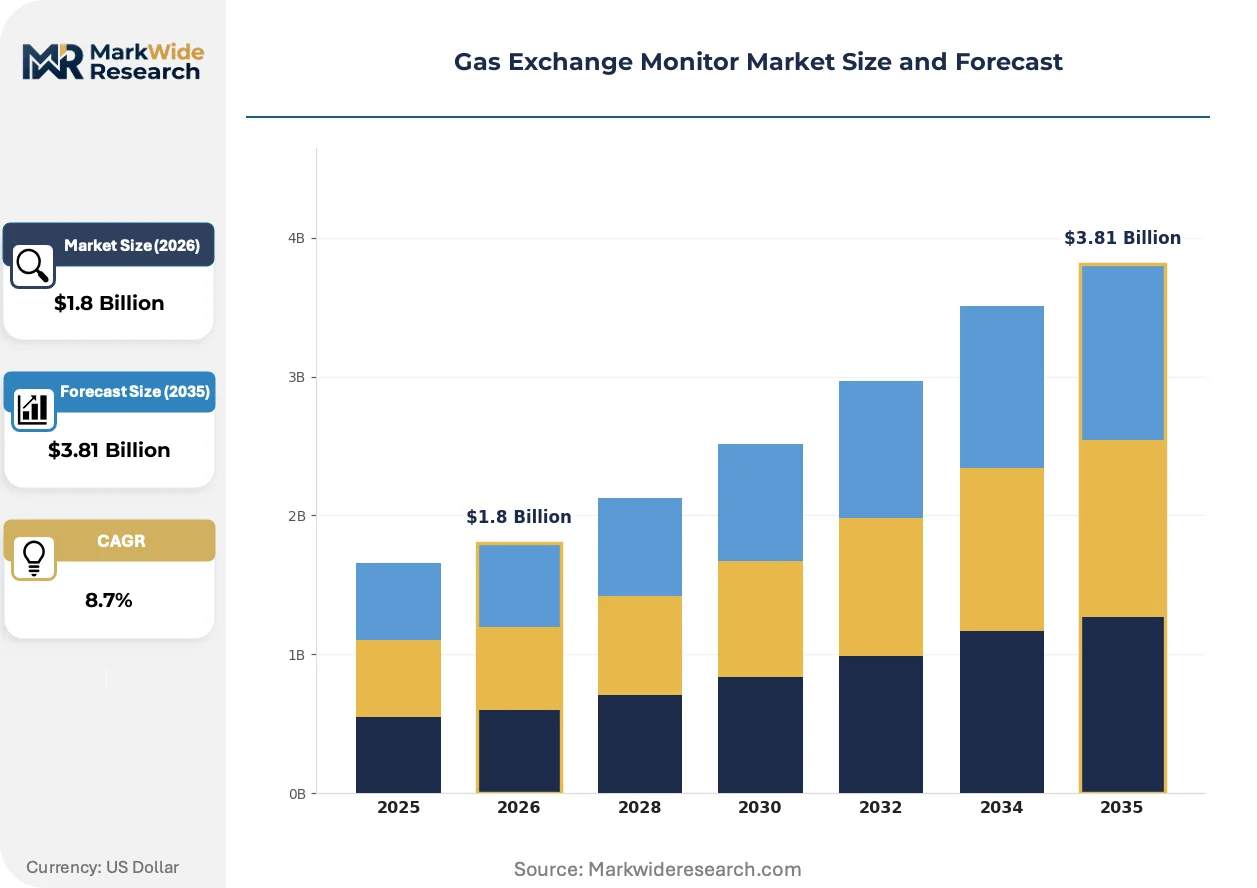
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Stationary Devices, Handheld Units, Wireless Systems Technology: Infrared Sensors, Electrochemical Sensors, Optical Sensors, Mass Spectrometry End User: Hospitals, Laboratories, Homecare Providers, Research Institutions Application: Clinical Monitoring, Environmental Testing, Research Studies, Industrial Use |
| Companies Covered | Vyaire, Schiller, COSMED, Vitalograph, ECO MEDICS AG, Siemens Healthineers, GE Healthcare, Philips Healthcare, Masimo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Exchange Monitor Market Evolving Landscape
Telemetry integration is compressing the traditional boundary between bedside monitoring and centralized pulmonary laboratories, reshaping how respiratory diagnostics are delivered across care continuums.
Photonic sensor miniaturization is overtaking conventional benchtop spectroscopy architectures in critical care deployments. These solid-state infrared detectors enable sub-100 millisecond response times for carbon dioxide and oxygen fraction quantification. Intensive care units in tertiary hospitals are adopting chip-scale sensors at accelerating rates. The technology is overtaking legacy flow-cell designs by eliminating optical path maintenance and reducing calibration drift.
The EU Medical Device Regulation's clinical evidence requirements are restructuring competitive positioning for respiratory diagnostic equipment. Notified body certification mandates for Class IIa devices now demand prospective validation studies across intended use populations. German and French manufacturers with established quality management systems are capturing share from competitors lacking MDR transition readiness. Hospital procurement committees are prioritizing CE-marked devices with documented post-market surveillance capabilities.
After-sales service unbundling is fragmenting traditional equipment-vendor relationships in the United States. Integrated delivery networks are separating hardware acquisition from preventive maintenance contracts, pressuring original equipment manufacturers to compete on service pricing transparency. Third-party clinical engineering firms are capturing multi-vendor service agreements for gas exchange monitor fleets. This pattern is most visible in California and Texas health systems with centralized biomedical equipment management functions.
Gas Exchange Monitor Market Segmentation
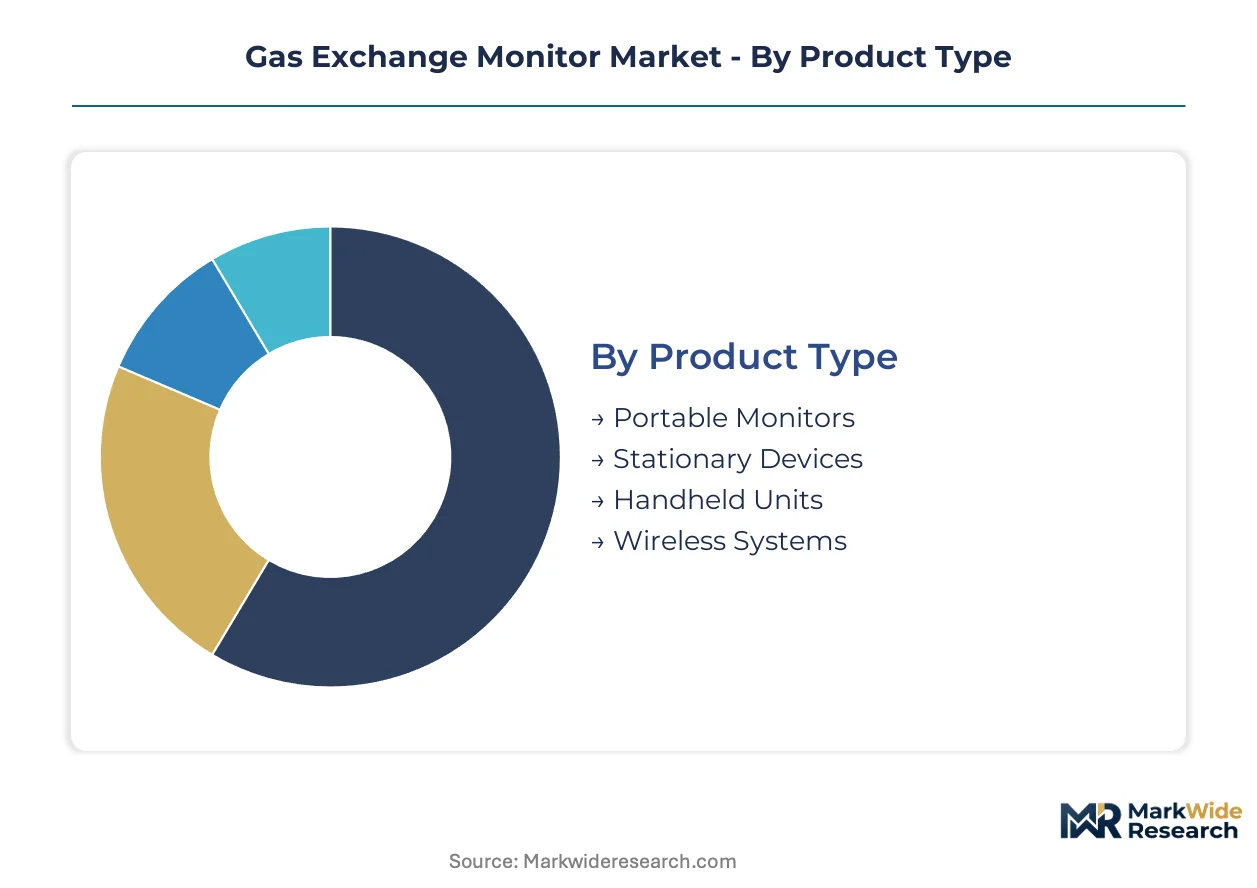
Gas exchange monitor procurement patterns diverge sharply between high-throughput institutional installations and distributed point-of-care deployments. Technology choices cascade through product configuration decisions, with spectroscopic methods commanding premium positioning while electrochemical alternatives penetrate cost-sensitive segments.
Product Type:
Portable configurations dominate shipment volumes while stationary systems anchor revenue concentration in tertiary care centers.
- Portable Monitors:Battery-powered units with integrated infrared spectroscopy modules enable bedside metabolic assessment without patient transport. United States emergency departments and ambulatory surgical centers are standardizing these for pre-operative pulmonary evaluation, displacing traditional laboratory referrals. The fastest-expanding trajectory sits here.
- Stationary Devices:Rack-mounted systems with multi-gas calibration capabilities serve high-throughput pulmonary function laboratories. German hospital networks favor these for comprehensive cardiopulmonary exercise testing protocols, accepting extended procurement cycles for precision specifications.
- Handheld Units:Single-parameter screening tools with reduced analytical precision target primary care screening applications.
- Wireless Systems:Telemetry-enabled architectures with EHR integration support remote patient monitoring infrastructures.
Current volume leader: Portable Monitors. Emerging disruptor: Wireless Systems.
Technology:
Optical methods concentrate in critical care settings demanding sub-100 millisecond response times, while electrochemical approaches capture price-sensitive screening markets.
- Infrared Sensors:Non-dispersive infrared absorption at specific wavelengths quantifies carbon dioxide and oxygen fractions with response times under 100 milliseconds. United States academic medical centers specify these for mechanical ventilation guidance, prioritizing drift stability over acquisition cost.
- Mass Spectrometry:Simultaneous multi-gas analysis with parts-per-billion detection limits serves research institutions conducting complex metabolic studies. The capital intensity limits penetration despite superior analytical capability.
- Electrochemical Sensors:Amperometric detection cells offer lower unit economics for routine screening applications.
- Optical Sensors:Solid-state photonic detectors enable chip-scale integration for miniaturized critical care deployments.
Installed base concentration: Infrared Sensors. Steepest expansion trajectory: Optical Sensors.
End User:
Procurement authority varies across institutional settings, with integrated delivery networks consolidating purchasing decisions while research institutions retain decentralized acquisition autonomy.
- Hospitals:Acute care facilities with mechanical ventilation capabilities require continuous respiratory gas monitoring for critical care units. German hospital expansion of non-invasive cardiopulmonary testing is accelerating replacement demand for MDR-compliant platforms.
- Homecare Providers:Post-acute respiratory monitoring services are adopting wireless telemetry systems for chronic obstructive pulmonary disease management. Reimbursement coding changes in United States Medicare are expanding addressable demand.
- Laboratories:Reference pulmonary function testing centers specify stationary high-throughput configurations.
- Research Institutions:Metabolic research programs purchase mass spectrometry systems for simultaneous multi-gas analysis.
Primary revenue source: Hospitals. Fastest-climbing demand: Homecare Providers.
Application:
Clinical validation requirements separate regulated medical device markets from industrial and environmental segments with divergent certification pathways.
- Clinical Monitoring:FDA 510(k) cleared devices for mechanical ventilation guidance and pulmonary function assessment require accuracy validation across intended use populations. United States integrated health networks are standardizing protocols across multi-site operations.
- Research Studies:Investigational use exemptions permit deployment of non-validated configurations for protocol-specific metabolic phenotyping.
- Environmental Testing:Ambient air quality monitoring applications operate outside medical device regulations.
- Industrial Use:Occupational exposure monitoring for confined space entry employs simplified sensor configurations.
Regulatory gravity center: Clinical Monitoring. Emerging volume opportunity: Research Studies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital networks anchor demand concentration for non-invasive cardiopulmonary testing equipment. Procurement patterns across the United States, Germany, France, Japan, and China reveal divergent regulatory pressures and infrastructure maturity driving adoption timelines.
United States
Integrated health networks standardize pulmonary function testing protocols across multi-site operations, creating replacement demand cycles for wireless telemetry-enabled monitors. FDA enforces premarket notification requirements under 21 CFR 892, mandating clinical validation of accuracy claims. Academic medical centers in Boston and the Research Triangle maintain extensive installed bases generating substantial hardware refresh demand.
Germany
Acute care facilities expand adoption of non-invasive cardiopulmonary testing equipment to reduce invasive procedure volumes. EU Medical Device Regulation tightens performance validation requirements for Class IIa respiratory diagnostic equipment, accelerating hospital upgrades to compliant platforms. Medical technology clusters in Baden-Württemberg and Bavaria concentrate manufacturing competence for spectroscopic sensor modules.
France
Hospital procurement committees prioritize CE-marked devices with documented post-market surveillance capabilities under EMA pharmacovigilance obligations. French manufacturers with established quality management systems capture share from competitors lacking MDR transition readiness. The Paris-Saclay medical technology corridor hosts specialized respiratory diagnostic equipment development facilities.
Japan
Metabolic research programs purchase mass spectrometry systems for simultaneous multi-gas analysis in university-affiliated hospitals. PMDA maintains stringent clinical evidence requirements for novel respiratory monitoring technologies. The Kansai region, particularly Osaka, concentrates precision medical device manufacturing supply chains serving domestic and export markets.
China
Domestic hospital groups accelerate procurement of portable monitors for bedside metabolic assessment in tier-one city medical centers. NMPA streamlines registration pathways for Class II medical devices while tightening post-market surveillance. The Yangtze River Delta medical device manufacturing base expands production capacity for infrared spectroscopy components.
Gas Exchange Monitor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless telemetry integration and point-of-care miniaturization. The vendor base stratifies across three maturity tiers: diversified medical technology conglomerates with captive component manufacturing, mid-scale specialists with regional distribution density, and venture-backed innovators targeting telemetry-enabled configurations. Competitive moves concentrate on backward integration into photonic sensor supply and strategic partnerships with electronic health record platform vendors.
Within the diversified conglomerate tier, Siemens Healthineers and GE Healthcare occupy positions defined by geographic installed base scale and captive manufacturing of analytical components. COSMED exemplifies the specialist archetype with in-house optical sensor fabrication capabilities reducing external supplier dependency. These three anchors represent distinct competitive vectors: scale-driven service networks, component-level supply security, and optical technology integration depth.
| Leading Market Players |
|---|
| Vyaire |
| Schiller |
| COSMED |
| Vitalograph |
| ECO MEDICS AG |
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Masimo |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in the United States concentrate procurement authority for gas exchange monitors, driving contract-based long-term offtake pricing with bundled preventive maintenance. This buyer consolidation shifts negotiation leverage toward volume-scale discounts and service pricing transparency, pressuring original equipment manufacturers to unbundle traditional hardware-service packages.
Pricing Analysis
Input-cost pass-through from photonic sensor modules shapes pricing trajectories for infrared spectroscopy systems. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified platforms with documented post-market surveillance from basic portable configurations. Price differentiation centers on ISO 80601-2-55 compliance documentation and wireless telemetry integration depth. Cost compression in the handheld segment intensifies as electrochemical alternatives displace optical methods for primary care screening. Academic medical centers demonstrate lowest price sensitivity, prioritizing drift stability and sub-100 millisecond response times over acquisition cost.
Supply Chain Analysis
Precision photonics manufacturing clusters in Baden-Württemberg and Bavaria face tightening availability of specialized optical engineering talent, constraining expansion timelines for spectroscopic sensor production. Component sourcing draws from Germany for optical modules, China for infrared detector substrates, and Japan for precision gas calibration standards. Single-source vulnerability concentrates in semiconductor foundry capacity for wavelength-specific photonic components. Distribution runs through hospital procurement committees and group purchasing organizations in the United States, with direct-to-facility logistics for German acute care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in gas exchange monitoring rests on photonic sensor miniaturization reducing bill-of-materials intensity, while wireless telemetry integration commands premium positioning in post-acute care.
For Market Incumbents: Anticipate displacement pressure from venture-backed innovators targeting telemetry-enabled configurations by deepening backward integration into optical sensor fabrication. COSMED's captive photonics supply model offers a template for reducing external supplier dependency. Prioritize MDR transition readiness to defend positioning in German and French hospital procurement cycles where notified body certification now gates market access. For New Entrants and Emerging Players: EU Medical Device Regulation in Europe opens a window for capturing share from legacy competitors lacking clinical evidence documentation for Class IIa respiratory diagnostic equipment. Target homecare providers in the United States where Medicare reimbursement coding changes expand addressable demand for wireless respiratory monitoring. Pursue software companion development as the primary go-to-market angle, integrating telemetry data streams with electronic health record platforms to bypass incumbent hardware lock-in. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking point-of-care miniaturization capabilities to complement centralized laboratory portfolios. Long-term viability hinges on regulatory compliance infrastructure rather than single-product innovation cycles. Monitor EMA pharmacovigilance enforcement patterns as the inflection indicator for recurring revenue potential in compliance monitoring services.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | Notified body approval for Class IIa devices gates German and French hospital procurement decisions. |
| Photonic Sensor Miniaturization | Chip-scale infrared detectors enable sub-100 millisecond response times in critical care deployments. |
| Hospital System Partnership | Integrated delivery network standardization creates replacement demand cycles across multi-site operations. |
| Software Companion Development | Telemetry integration with electronic health record platforms supports remote patient monitoring reimbursement. |
| Reimbursement Strategy | Medicare coding alignment for post-acute respiratory monitoring expands homecare provider addressable demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and respiratory therapy directors with secondary validation. FDA 510(k) filings, EMA notified body certification databases, CMS Medicare reimbursement schedules, and ISO 80601-2-55 technical documentation provided foundational data. Bottom-up shipment estimates by product configuration and technology type were triangulated against top-down hospital capital expenditure surveys.
Segment-weighting approaches distributed value and volume across portable, stationary, handheld, and wireless product configurations, with further stratification by infrared sensor, mass spectrometry, electrochemical, and optical technology methods. End-user segmentation modeled hospitals, homecare providers, laboratories, and research institutions as distinct procurement authority clusters. CAGRs were derived from replacement demand cycle analysis and point-of-care expansion trajectories, incorporating semiconductor allocation pressures and regulatory transition timelines as constraint variables.
Revisions become necessary when EU Medical Device Regulation enforcement intensity shifts, semiconductor foundry capacity allocation changes, or Medicare reimbursement coding for remote patient monitoring deviates from current trajectory assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Neurology Patient Monitoring Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market