
 Closed Heel Nursing Shoes Market | 2026-2036
Closed Heel Nursing Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Closed Heel Nursing Shoes Market Analytics
Ethylene-vinyl acetate foam is rebalancing cost-performance trade-offs across mid-tier closed heel nursing shoes, displacing heavier polyurethane midsoles in volume production. Dansko leverages its Danish manufacturing heritage to sustain premium positioning in clog-based clinical footwear. Skechers competes through athletic-derived cushioning platforms adapted for twelve-hour nursing shifts. New Balance anchors its presence via width-specific lasts that address occupational foot health requirements.
Closed heel nursing shoes are engineered footwear with enclosed posterior counters, slip-resistant outsoles certified to ASTM F2913 standards, and antimicrobial linings designed for contamination control in clinical environments. Their primary purpose is to reduce musculoskeletal injury and pathogen transmission among healthcare workers during prolonged standing and patient contact. Clogs retain the largest volume share due to institutional purchasing patterns, while sneakers represent the fastest-expanding category as younger nursing cohorts prioritize athletic aesthetics. Leather commands the highest margin pool in premium channels, though synthetic materials are gaining share as REACH-compliant formulations improve durability benchmarks.
The EU Green Deal and REACH framework restrict phthalate-based plasticizers in synthetic uppers, compelling reformulation across European supply chains. The FDA does not directly regulate nursing footwear, but OSHA workplace safety guidelines influence hospital procurement specifications for slip resistance and impact protection. ASTM International publishes F2913 slip resistance standards that most US health systems incorporate into vendor qualification requirements. Stakeholders must monitor how evolving PFAS restrictions in the EU and emerging US state-level chemical disclosure laws reshape material specifications and supplier compliance costs.
Market Dynamics
Hospital procurement departments are consolidating vendor lists under single-source contracts, compressing supplier margins while demanding ASTM F2913-certified slip resistance and antimicrobial linings as baseline specifications.
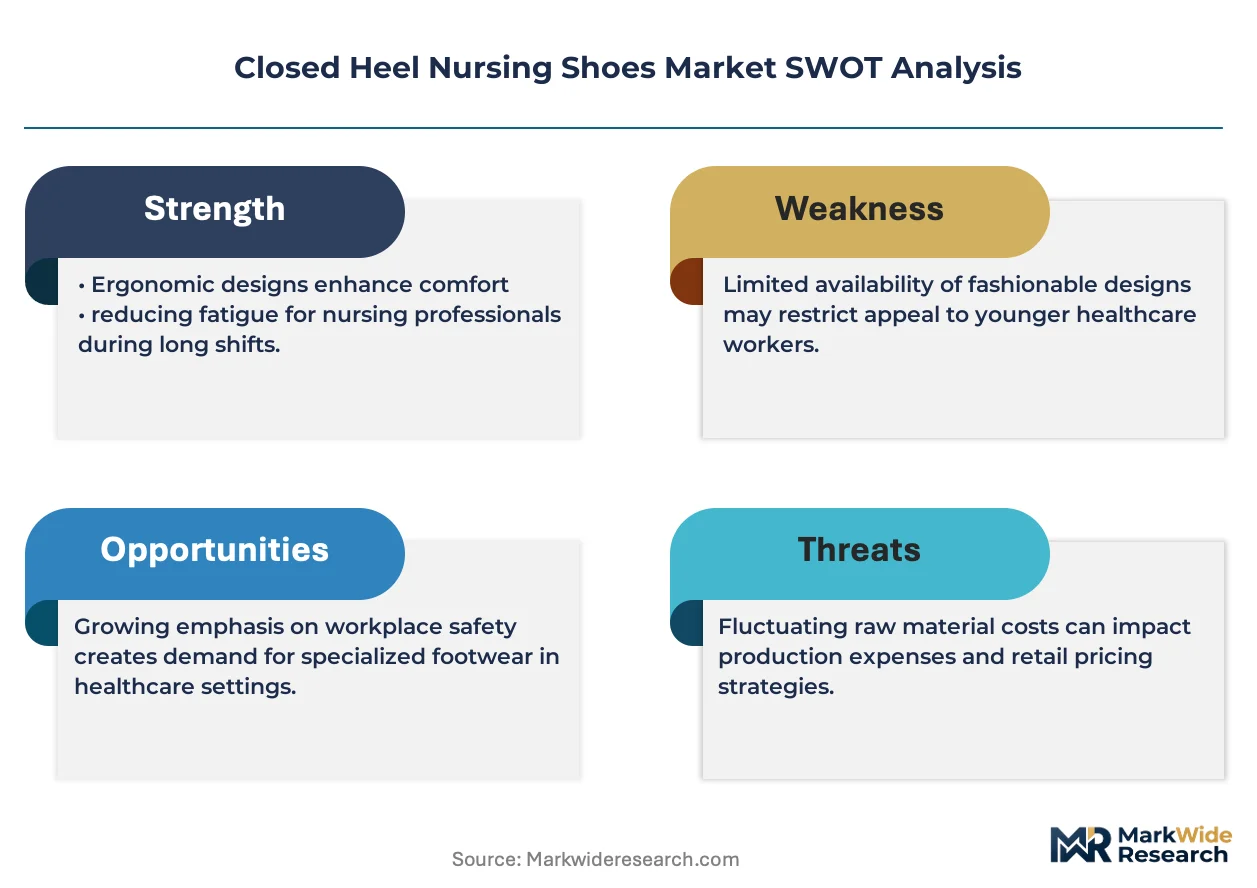
Growth Catalysts
- REACH-compliant synthetic formulations:ECHA restrictions on phthalate plasticizers are accelerating bio-based polyurethane adoption in European manufacturing, opening premium positioning for compliant suppliers.
- Twelve-hour shift physiology:Occupational health research on nursing musculoskeletal injury is mandating enclosed heel protection and energy-return midsoles in institutional purchasing guidelines.
- German workforce standards:Federal regulations mandating enclosed footwear for clinical staff during extended shifts are concentrating demand in Central European supply chains.
Market Restraints
- Petrochemical feedstock volatility:Ethylene-vinyl acetate and polyurethane precursor costs fluctuate with crude oil indices, squeezing mid-tier manufacturer margins.
- East Asian mold and outsole concentration:Slip-resistant rubber compound production clusters in Guangdong and Zhejiang provinces create single-source vulnerability for Western brands.
- ASTM F2913 testing bottlenecks:Limited accredited laboratories for slip resistance certification extend product launch timelines by four to six months.
Strategic Opportunities
- India nursing education expansion:Government targets for one nurse per 500 population by 2030 are building institutional purchasing infrastructure in tier-two cities.
- EU Green Deal bio-based mandates:Public procurement rules favoring 50% renewable content in medical textiles extend to footwear for national health service contracts.
- Direct-to-department e-procurement:Amazon Business and specialized healthcare marketplaces are disintermediating traditional medical supply distributors for smaller clinic orders.
Industry Challenges
- Biomechanical engineering talent scarcity:Fewer than twelve academic programs globally produce footwear-specific occupational health researchers, constraining R&D pipeline speed.
- Legacy ERP integration with hospital procurement systems:Vendor onboarding to platforms like GHX and Prodigo requires six-figure customization investments for mid-size manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Closed Heel Nursing Shoes Market |
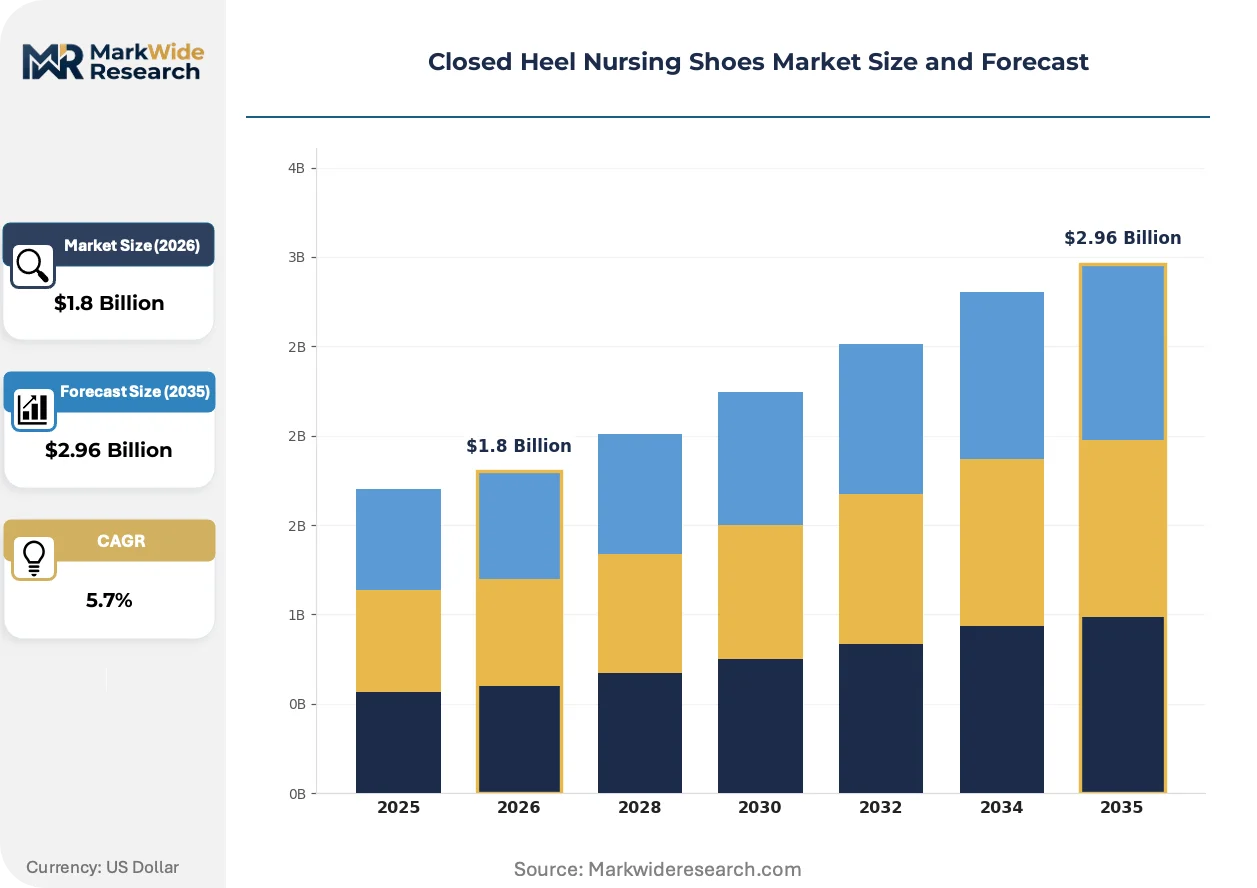
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clogs, Sneakers, Loafers, Slip-Ons Material: Leather, Synthetic, Mesh, Rubber Usage Scenario: Daily Shift, Surgical, Nursing Home, Home Care Size: Small, Medium, Large, Extra Large |
| Companies Covered | Dansko, Alegria, Birkenstock, Crocs, Cherokee, Skechers, New Balance, Nurse Mates, Hoka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Closed Heel Nursing Shoes Market Evolving Landscape
Material science breakthroughs and procurement digitization are compressing traditional product development cycles while elevating performance certification from optional to mandatory in vendor qualification.
Ethylene-vinyl acetate foam is overtaking denser polyurethane midsoles in volume production lines. The material delivers equivalent energy return at 40% lower weight, enabling hospital systems to reduce workplace injury claims. North American health networks with self-insured workers compensation programs are specifying EVA-based platforms in technical requirements documents.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of water-resistant treatments for synthetic uppers. Manufacturers serving EU hospital systems must validate alternative chemistries through ECHA-registered testing bodies. German and Dutch procurement consortia are rejecting pre-2023 inventory that lacks PFAS-free certification.
Younger nursing cohorts are prioritizing athletic aesthetics over traditional clog silhouettes, reshaping category mix in hospital uniform allowances. Sneaker-format closed heel shoes with knit uppers and running-derived cushioning platforms are capturing preference share among staff under age 35. This shift is most visible in US magnet hospital systems competing for retention in tight labor markets.
Closed Heel Nursing Shoes Market Segmentation
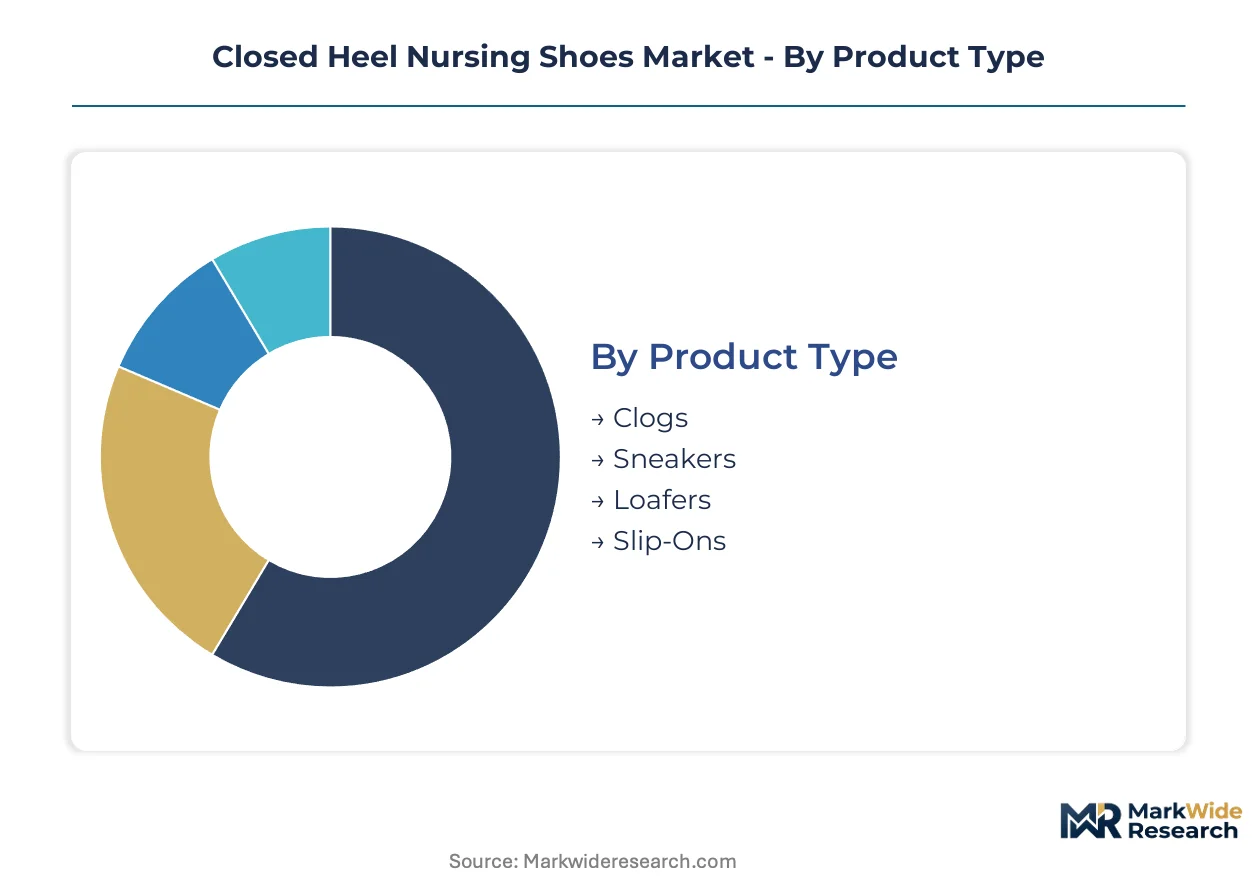
Closed heel nursing shoes segment across four dimensions that shape procurement decisions. Hospital systems specify product type and material in technical requirements documents, while usage scenario determines ASTM F2913 certification levels and antimicrobial lining specifications.
Product Type:
Supply concentration in clogs reflects institutional purchasing patterns and legacy vendor relationships with European manufacturers.
- Clogs:Enclosed heel designs with rocker-bottom outsoles dominate hospital system contracts. German workforce standards mandate this silhouette for extended shifts, concentrating procurement volume in Central European supply chains.
- Sneakers:Athletic-derived cushioning platforms with knit uppers address twelve-hour shift physiology. Younger nursing cohorts in US magnet hospital systems prioritize this aesthetic, accelerating share gains in competitive labor markets.
- Loafers:Slip-resistant dress-casual hybrids serve administrative nursing roles with lighter mobility demands.
- Slip-Ons:Elastic-gore closures target rapid donning requirements in emergency department environments.
Clogs absorb the bulk of installed capacity; sneakers are expanding most quickly.
Material:
REACH-compliant synthetic formulations are displacing legacy materials as ECHA restrictions tighten across European manufacturing.
- Leather:Full-grain uppers with moisture-wicking linings command premium positioning in specialty retail channels. REACH Annex XVII phthalate restrictions have limited European sourcing options, compressing margin pools for non-compliant inventory.
- Synthetic:Bio-based polyurethane alternatives validated through ECHA-registered testing bodies serve EU hospital procurement. Dutch and German consortia now reject pre-2023 stock lacking PFAS-free certification.
- Mesh:Knit uppers with antimicrobial treatments address thermal comfort in high-acuity surgical settings.
- Rubber:Molded outsole compounds certified to ASTM F2913 standards concentrate production in Guangdong and Zhejiang provinces.
Synthetic materials climb the fastest as regulatory compliance reshapes supplier qualification; leather retains the steepest margin premium.
Usage Scenario:
Application-specific certification tiers segment demand across institutional procurement channels with varying technical requirements.
- Daily Shift:Standard ASTM F2913 slip resistance and energy-return midsoles serve general ward nursing. North American self-insured health networks specify EVA-based platforms to reduce workers compensation claims.
- Surgical:Fluid-resistant uppers with sealed seams and enhanced antimicrobial linings meet operating theater contamination protocols.
- Nursing Home:Reinforced toe caps and extended-width lasts address geriatric care mobility requirements.
- Home Care:Lightweight constructions prioritize vehicle egress and community-based patient visits over institutional durability benchmarks.
Daily shift applications dominate procurement volume; surgical specifications command the highest certification premiums.
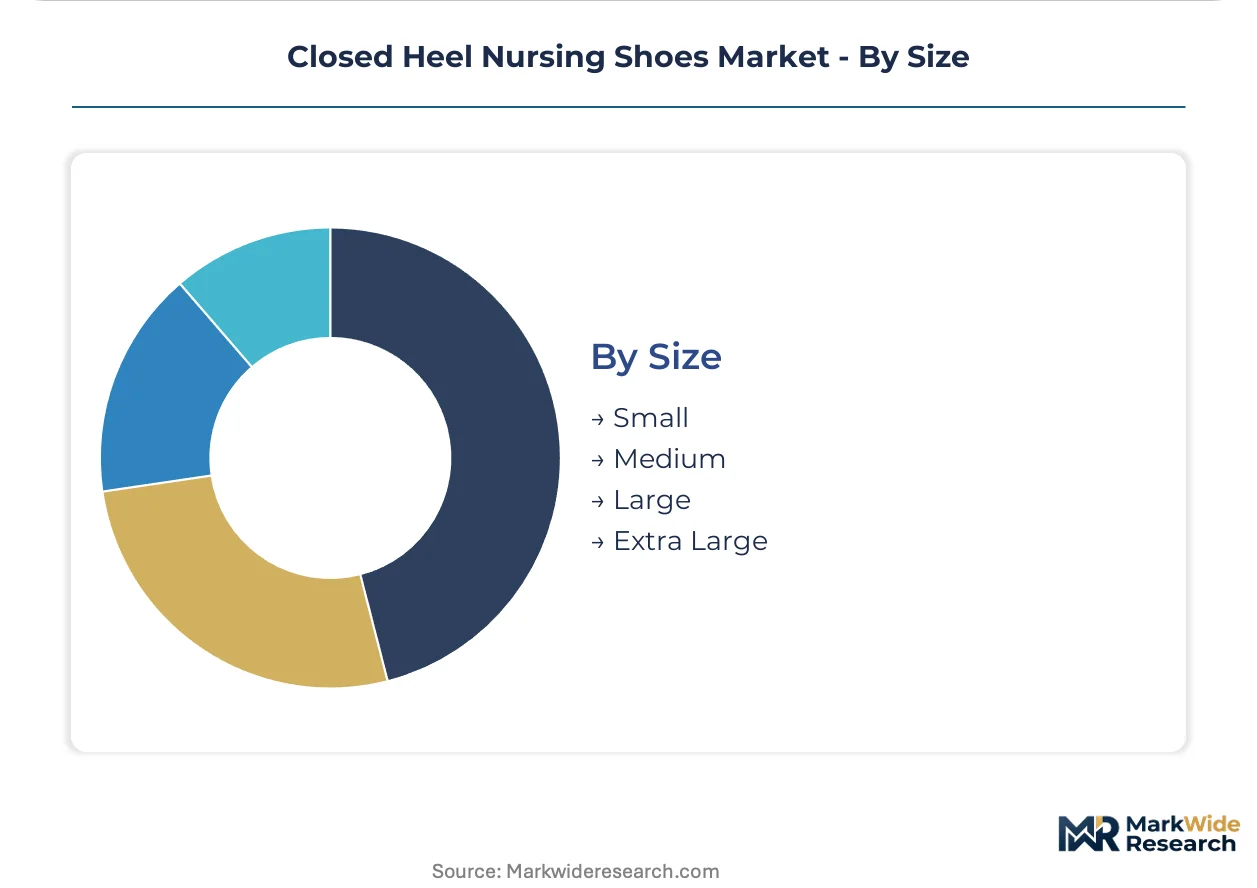
Size:
Width-specific production capabilities differentiate vendor positioning in occupational foot health segments.
- Small:Narrow lasts with reduced heel counters serve pediatric nursing and smaller-stature clinical staff.
- Medium:Standard-volume production lines optimize economies for institutional bulk purchasing.
- Large:Extended sizing with reinforced structural elements addresses male nursing workforce growth.
- Extra Large:Custom last development and orthopedic collaboration requirements constrain supplier participation.
Medium sizes capture standard procurement volume; extra large represents the most underserved addressable segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States and Germany concentrate institutional demand for closed heel nursing shoes, with federal workforce standards and self-insured workers compensation programs driving specification tightening across both markets.
United States
Magnet hospital systems competing for nursing retention specify athletic-derived cushioning platforms in uniform allowances, with ASTM F2913 slip resistance certification now mandatory in technical requirements documents. OSHA workplace safety guidelines influence procurement specifications for impact protection and enclosed heel designs. Manufacturing concentration in Massachusetts and Minnesota serves health networks with self-insured workers compensation programs seeking EVA-based platforms to reduce injury claims.
Germany
Federal regulations mandating enclosed footwear for clinical staff during extended shifts concentrate procurement volume in Central European supply chains. REACH Annex XVII restrictions on phthalate plasticizers and PFAS compounds force reformulation of water-resistant treatments for synthetic uppers. The Baden-Württemberg and Bavaria industrial clusters host ECHA-registered testing bodies validating bio-based polyurethane alternatives for Dutch and German hospital consortia.
United Kingdom
National Health Service procurement frameworks increasingly incorporate EU Green Deal bio-based mandates for medical textiles and footwear, favoring suppliers with 50% renewable content validation. The country's national pharmaceutical regulator influences contamination control protocols in operating theater environments. Greater Manchester and West Midlands manufacturing bases supply sealed-seam surgical specifications with enhanced antimicrobial linings.
India
Government targets for one nurse per 500 population by 2030 build institutional purchasing infrastructure in tier-two cities including Pune, Hyderabad, and Ahmedabad. The Bureau of Indian Standards and CDSCO shape quality benchmarks for clinical footwear distributed through public health programs. Tamil Nadu and Karnataka textile clusters develop antimicrobial mesh uppers for high-acuity surgical settings serving expanding nursing education institutions.
Japan
METI guidelines on occupational health equipment support demand for width-specific lasts addressing foot health requirements in aging nursing workforces. JIS standards for slip resistance align with ASTM F2913 certification levels in hospital procurement specifications. The Kansai region around Osaka maintains production capacity for rocker-bottom clog silhouettes serving domestic health systems and export markets.
Closed Heel Nursing Shoes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning held by heritage European names while athletic-derived entrants capture younger nursing cohorts. The vendor base organizes around three strategic archetypes: Danish clog specialists leveraging occupational health credibility, athletic footwear brands adapting cushioning platforms for clinical environments, and width-specific producers addressing biomechanical requirements. Consolidation pressure intensifies as hospital procurement departments compress vendor lists under single-source contracts. Dominant competitive moves include backward integration into REACH-compliant synthetic material production and direct-to-department e-procurement channel development.
Among heritage European specialists, Dansko and Birkenstock occupy positions anchored by decades of occupational health credibility in hospital system contracts. Skechers represents the athletic-derived archetype, adapting running shoe cushioning platforms for twelve-hour nursing shift requirements. New Balance sits within the biomechanical specialization tier, using width-specific lasts to address occupational foot health segments underserved by standard-volume producers. These three names illustrate how competitive positioning fragments across distinct demand vectors rather than consolidating around uniform product strategies.
| Leading Market Players |
|---|
| Dansko |
| Alegria |
| Birkenstock |
| Crocs |
| Cherokee |
| Skechers |
| New Balance |
| Nurse Mates |
| Hoka |
| Others |
Value Network & Pricing Analysis
Backward integration into REACH-compliant synthetic material production anchors both supply security and margin protection for manufacturers serving EU hospital procurement. Captive control over bio-based polyurethane formulations insulates premium positioning against feedstock volatility while compressing compliance costs for Dutch and German consortia rejecting pre-2023 inventory.
Pricing Analysis
Volume concentrates in clogs while margins pool in leather-upper premium channels. Three-tier pricing structure across premium, standard, and economy levels separates ASTM F2913-certified surgical specifications from general ward daily shift products. Cost compression in mid-tier EVA platforms is intensifying because hospital procurement departments consolidate vendor lists under single-source contracts. Price-sensitive buyers cluster in Indian tier-two city institutional purchasing infrastructure, while German workforce standard compliance commands lowest elasticity.
Supply Chain Analysis
Workforce availability constraints in Guangdong and Zhejiang provinces limit mold and outsole capacity expansion despite Western brand demand. Manufacturing draws from ethylene-vinyl acetate foam feedstocks, bio-based polyurethane alternatives, and antimicrobial mesh textiles. Single-source vulnerability concentrates in East Asian rubber compound production clusters. Distribution runs through Amazon Business and specialized healthcare marketplaces disintermediating traditional medical supply distributors for smaller clinic orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The closed heel nursing shoes market sits in a materials-transition phase as ethylene-vinyl acetate foam displaces heavier polyurethane midsoles across volume production lines. This substitution rewrites cost-performance trade-offs and procurement specifications simultaneously.
For Market Incumbents: Acquire ECHA-registered testing body relationships to lock in REACH Annex XVII compliance validation ahead of PFAS restriction tightening. Deepen captive supply of bio-based synthetic formulations to defend margin position against petrochemical feedstock volatility. Hospital procurement consolidation into single-source contracts threatens mid-tier suppliers lacking certification infrastructure. For New Entrants and Emerging Players: REACH Annex XVII restrictions in the European Union open a window for premium positioning through PFAS-free certification that legacy inventory cannot match. Target Indian nursing education expansion in tier-two cities where institutional purchasing infrastructure is building but vendor relationships remain unconsolidated. Lead with direct-to-department e-procurement channel development to bypass entrenched medical supply distributors. For Investors and Strategic Acquirers: Exit pathways concentrate in athletic-derived cushioning platform specialists capturing younger nursing cohort preference shifts. The five-to-ten year viability window favors biomechanical engineering capabilities and width-specific last development over commodity clog production. Watch ASTM F2913 testing laboratory capacity expansion as inflection signal for product launch velocity constraints easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Synthetics | Captive REACH-compliant polyurethane production secures EU hospital procurement qualification against ECHA restriction tightening. |
| Direct-to-Department E-Procurement Launch | Amazon Business channel development disintermediates traditional medical supply distributors for smaller clinic order capture. |
| ASTM F2913 Certification Investment | Accredited slip resistance validation accelerates product launch timelines compressed by testing laboratory bottlenecks. |
| Width-Specific Last Development | New Balance demonstrates underserved extra-large segment addressability through orthopedic collaboration requirements. |
| PFAS-Free Formulation Transition | ECHA-registered alternative chemistry validation enables Dutch and German consortia procurement qualification. |
Research Methodology
Independent corroboration across hospital procurement managers, footwear manufacturing executives, and occupational health researchers underwrites the qualitative findings in this study. Primary fieldwork with GPO contracts managers and biomedical engineers combined with secondary validation from ASTM International standards documentation, ECHA regulatory filings, and hospital technical requirements databases. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates product type shifts, material substitution effects, and geographic demand migration across the projection horizon. The analytical framework models clogs, sneakers, loafers, and slip-ons against leather, synthetic, mesh, and rubber material tiers, with usage scenario certification levels and size-specific width requirements as cross-cutting dimensions. CAGRs derive from shift-level injury claim data, nursing workforce demographic projections, and institutional purchasing pattern evolution.
Caveats apply where ASTM F2913 testing laboratory capacity constraints, REACH Annex XVII regulatory enforcement timing, or Indian nursing education infrastructure buildout pace could materially shift the outlook. Forecasts embed assumptions about hospital procurement consolidation velocity and petrochemical feedstock stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
China Spinal Surgery Devices Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Intramedullary Nails Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Global Hip Replacement Implants Market