
 Global Post Surgery Bras Market | 2026-2036
Global Post Surgery Bras Market Size, Share, and Industry Trends Forecast 2026-2036
Global Post Surgery Bras Market Foresight
Premium post surgery bras with medical-grade compression engineering is decoupling from basic retail recovery wear in both price architecture and distribution channels. Amoena leverages decades of mastectomy specialization to sustain direct relationships with oncology centers across Western Europe. Medline Industries anchors hospital procurement contracts through scale manufacturing of front closure and wireless configurations. The Marena Group differentiates via textile R&D intensity, competing on fabric breathability metrics that exceed standard cotton-nylon blends.
Post surgery bras are engineered compression garments constructed with graduated elastane blends, typically incorporating spandex ratios between 15% and 25% to deliver controlled pressure measured in millimeters of mercury for tissue stabilization and lymphatic drainage support after breast procedures. Compression bras lead product type demand due to established clinical protocols following mastectomy and reconstruction, while front closure designs represent the fastest-growing configuration as postoperative mobility limitations drive preference for accessible fastening systems. Cotton-dominant material segments command stable volume in home care channels, though nylon-spandex compositions capture margin concentration through specialty store and plastic surgery clinic distribution.
FDA 510(k) requirements govern medical device classification for compression garments sold through healthcare channels in the United States, while the EU Medical Device Regulation mandates CE marking and clinical evaluation documentation for market access across European member states. Japan's Ministry of Health, Labour and Welfare enforces QMS certification through PMDA oversight, creating layered compliance costs that favor established manufacturers with dedicated regulatory affairs functions. Stakeholders must monitor evolving reimbursement coding for post-mastectomy supplies as payors recalibrate coverage policies between durable medical equipment and cosmetic procedure categories.
Market Dynamics
Hospital outpatient procurement protocols are consolidating compression garment purchasing around single-source contracts, compressing vendor margins while elevating technical specification requirements for post-mastectomy recovery programs.
Growth Catalysts
- FDA 510(k) Clearance Pathway:Class I medical device registration streamlines market entry for compression garment manufacturers targeting US hospital channels, reducing time-to-revenue for engineered recovery wear.
- Front Closure Engineering:Postoperative mobility limitations drive preference for accessible fastening systems, expanding addressable demand among reconstruction patients with restricted arm range.
- Germany:Statutory health insurance reimbursement frameworks for breast surgery aftercare create predictable payment flows that stabilize manufacturer revenue visibility in Western Europe's largest medical textile market.
Market Restraints
- Elastane Price Volatility:Petroleum-derived spandex inputs expose margin structures to upstream chemical feedstock fluctuations, compressing gross margins for nylon-spandex blend manufacturers.
- EU MDR Compliance Costs:Clinical evaluation documentation and notified body fees for CE marking create capital barriers that disadvantage smaller medical textile producers seeking European market access.
- Cotton Substitution Pressure:Natural fiber recovery bras compete on price in home care channels, limiting premium capture for engineered compression garments in direct-to-consumer segments.
Strategic Opportunities
- Japan:PMDA QMS certification requirements favor established manufacturers with dedicated regulatory affairs functions, creating acquisition targets for Western firms seeking Asia-Pacific expansion.
- Smart Textile Convergence:Integration of moisture-wicking nanofibers with graduated compression engineering enables premium positioning through measurable breathability performance metrics.
- Plastic Surgery Clinic Channel:Elective aesthetic procedure volumes outpace oncological reconstruction in select metropolitan markets, opening parallel distribution paths outside hospital procurement systems.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Cross-border 510(k), CE marking, and PMDA submission expertise concentrates among specialized consultants, inflating compliance labor costs for mid-scale manufacturers.
- Millimeter-of-Mercury Calibration:Compression consistency across production lots requires capital-intensive testing infrastructure, elevating fixed cost structures for quality-assured medical-grade output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Post Surgery Bras Market |
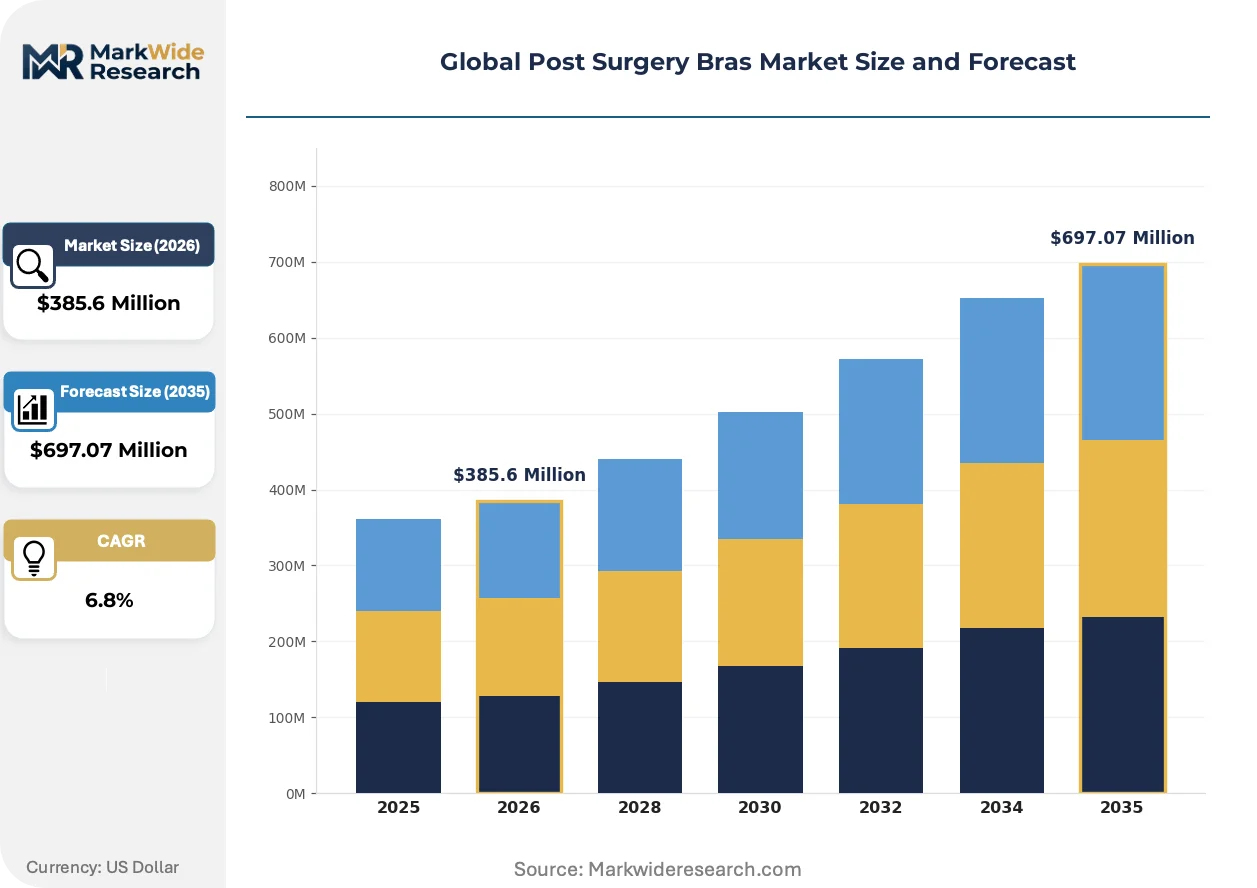
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Bras, Front Closure Bras, Wireless Bras, Adjustable Strap Bras, Soft Cup Bras Material: Cotton, Nylon, Spandex, Polyester, Lace Application: Breast Reconstruction, Mastectomy Recovery, Cosmetic Surgery, Trauma Recovery, Postpartum Support End User: Plastic Surgeons, Oncology Centers, Rehabilitation Clinics, Specialty Stores, Home Care Patients |
| Companies Covered | Medline Industries, Cardinal Health, Dale Medical, Amoena, The Marena Group, Tytex, Anita Dr. Helbig GmbH, Jodee Post-Mastectomy Fashions, Medical Z, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Post Surgery Bras Market Shifts & Advancements
Textile engineering advances are fragmenting competitive positioning between medical-grade compression specialists and retail recovery wear brands, with technical differentiation now governing procurement decisions in institutional channels.
Graduated elastane-spandex blends incorporating 15-25% spandex ratios are unifying tissue stabilization and lymphatic drainage functions in single-garment designs. Oncology centers in the United States and Germany specify these engineered compositions in procurement tenders, compressing demand for basic cotton-nylon alternatives. The technology is unifying previously separate product categories—compression bras and recovery camisoles—into modular postoperative systems.
EU Medical Device Regulation clinical evaluation requirements are elevating documentation burdens for compression garment manufacturers seeking CE marking renewal. Notified body backlogs extend certification timelines, forcing inventory pre-positioning ahead of regulatory deadlines. Post-mastectomy bra segments face the steepest compliance cost inflation due to their classification as active therapeutic devices under MDR Article 51.
Patient-directed purchasing through specialty surgical supply retailers is fragmenting traditional hospital discharge kit monopolies. Reconstruction patients in Japan and the United States increasingly self-source recovery garments based on online peer recommendations, displacing institutional brand loyalty. This channel rotation concentrates margin capture among direct-to-consumer brands with digital-native distribution infrastructure.
Global Post Surgery Bras Market Segmentation
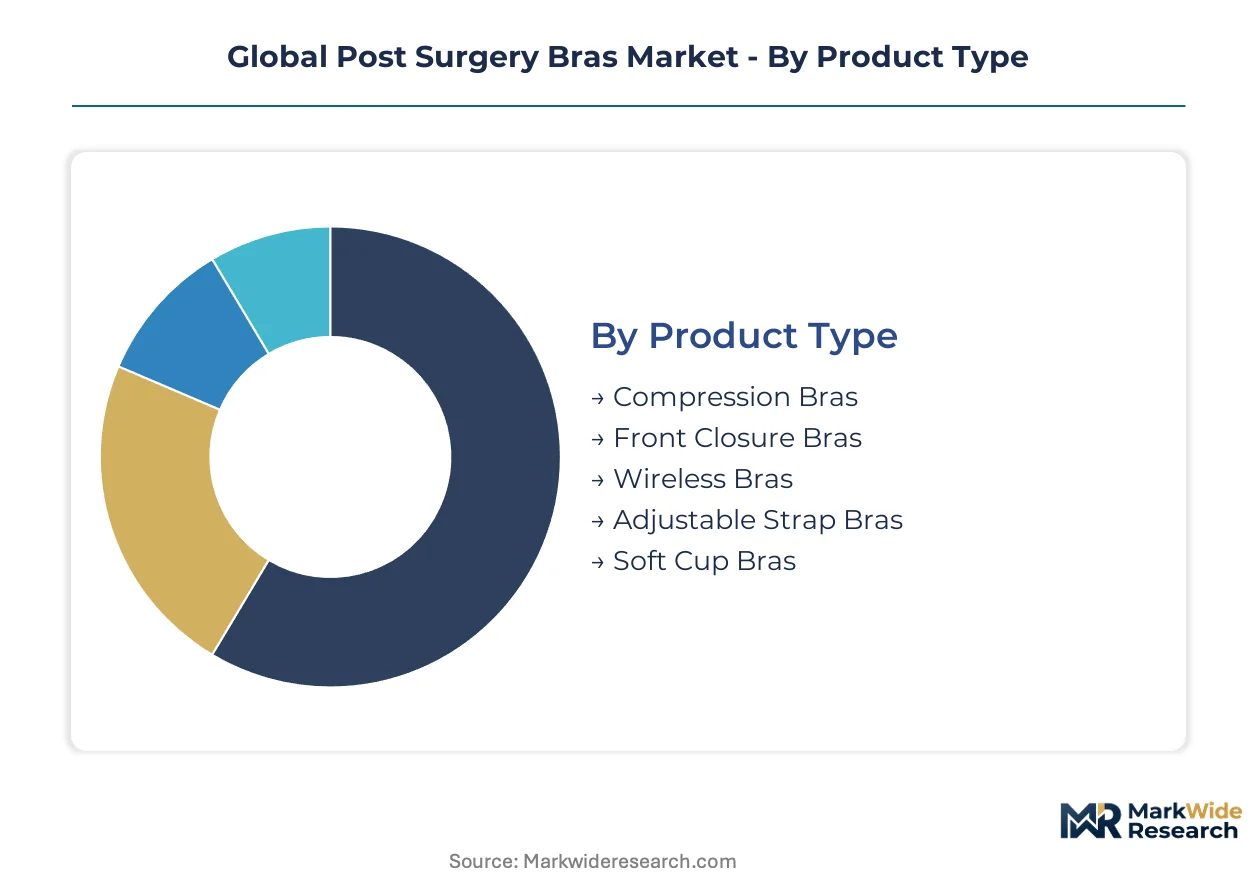
Segmentation in post surgery bras reflects divergent clinical protocols across recovery settings. Compression specifications, material composition, and distribution channel access determine pricing power and margin capture for manufacturers serving institutional versus direct-to-consumer demand.
Product Type:
Standardization dominates basic recovery configurations while engineered compression solutions command customization premiums through millimeter-of-mercury calibration.
- Compression Bras:Engineered with graduated elastane-spandex blends delivering 15-25% spandex ratios for controlled pressure measured in millimeters of mercury. Demand concentrates in hospital outpatient mastectomy programs across the United States and Germany where clinical protocols mandate tissue stabilization and lymphatic drainage support.
- Front Closure Bras:Accessible fastening systems address postoperative mobility limitations with restricted arm range following reconstruction procedures. Expansion is steepest in Japan and United States metropolitan markets where patient-directed purchasing through specialty surgical supply retailers fragments traditional hospital discharge kit monopolies.
- Wireless Bras:Elimination of underwire components reduces pressure points during tissue healing phases.
- Adjustable Strap Bras:Modular fit systems accommodate swelling fluctuations across recovery timelines.
- Soft Cup Bras:Gentle contouring prioritizes comfort over compression in home care recovery settings.
Most installed capacity flows through Compression Bras. Expansion is steepest in Front Closure Bras.
Material:
Cost tier stratification separates petroleum-derived synthetic blends from natural fiber alternatives, with performance metrics governing institutional procurement decisions.
- Nylon:Synthetic polymer base providing structural integrity for graduated compression engineering. Oncology centers in Germany and the United States specify nylon-dominant compositions in procurement tenders for post-mastectomy recovery programs.
- Spandex:Elastane component delivering 15-25% blend ratios essential for millimeter-of-mercury pressure consistency. Price volatility in petroleum-derived feedstocks exposes margin structures to upstream chemical market fluctuations.
- Cotton:Natural fiber competing on price in home care channels with limited premium capture potential.
- Polyester:Moisture-wicking synthetic supporting breathability performance metrics in extended wear applications.
- Lace:Aesthetic overlay material targeting elective aesthetic procedure segments outside clinical procurement systems.
Volume concentration sits with Nylon. Premium margin expansion tracks Spandex.
Application:
Customer type divergence splits reimbursable medical necessity from elective cosmetic expenditure, reshaping distribution channel requirements.
- Mastectomy Recovery:Oncological reconstruction protocols driving reimbursement-eligible demand through hospital outpatient settings. FDA 510(k) clearance pathways and Germany's statutory health insurance frameworks create predictable payment flows.
- Breast Reconstruction:Postoperative tissue stabilization requirements spanning implant-based and autologous reconstruction techniques. Patient-directed purchasing through digital-native retailers is gaining share fastest in United States and Japanese metropolitan markets.
- Cosmetic Surgery:Elective aesthetic procedures including augmentation and reduction mammoplasty outside insurance coverage systems.
- Trauma Recovery:Acute injury rehabilitation applications with variable compression specifications.
- Postpartum Support:Lactation and tissue recovery needs in obstetric care settings with distinct sizing protocols.
Procurement scale favors Mastectomy Recovery. Channel rotation is most pronounced in Breast Reconstruction.
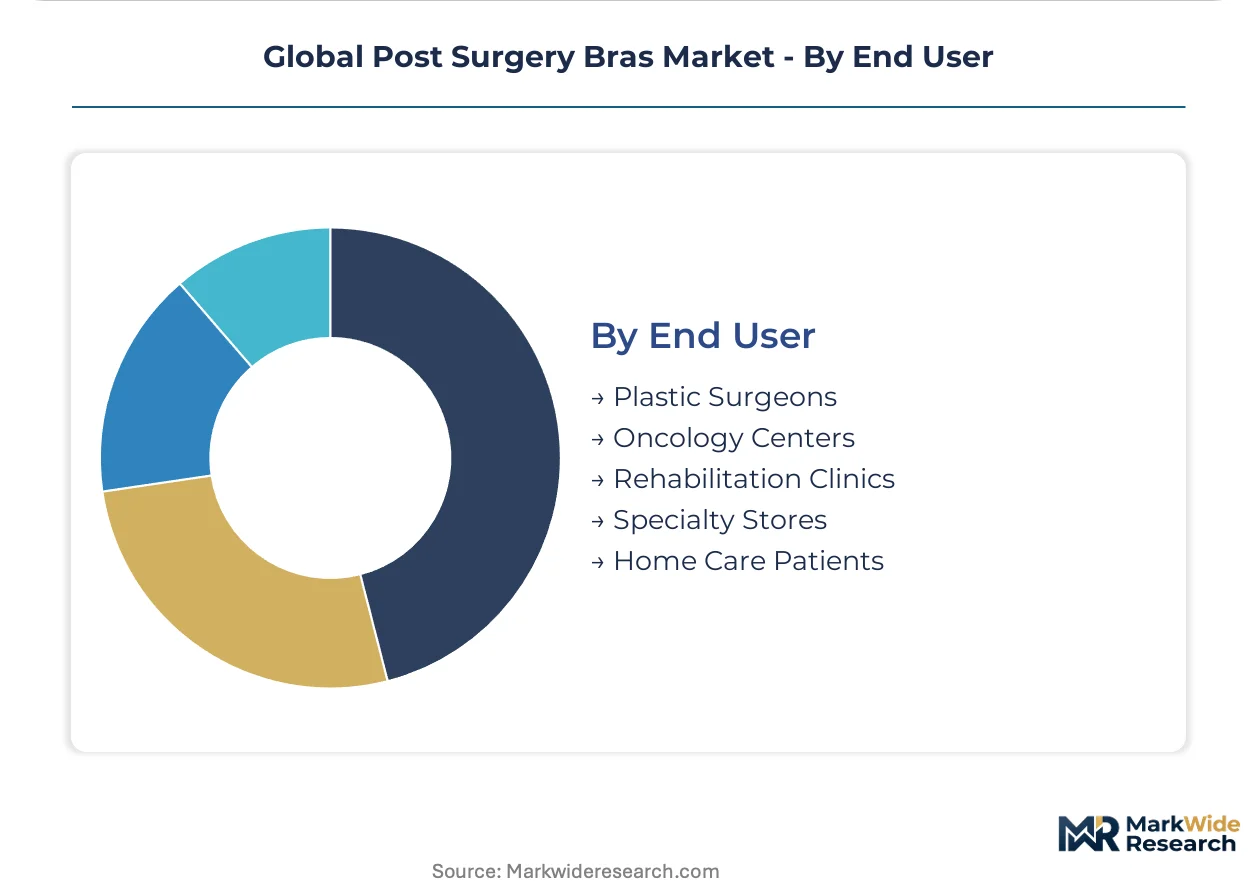
End User:
Supply concentration among institutional buyers contrasts with fragmented direct-to-consumer acquisition patterns, determining margin structures and regulatory compliance burdens.
- Oncology Centers:Hospital outpatient procurement protocols consolidating compression garment purchasing around single-source contracts with elevated technical specification requirements. EU MDR clinical evaluation documentation and FDA 510(k) registration mandates favor established manufacturers.
- Home Care Patients:Self-directed purchasing through specialty surgical supply retailers and digital channels based on online peer recommendations. This segment displaces institutional brand loyalty in United States and Japanese markets.
- Plastic Surgeons:Elective aesthetic procedure channels outside hospital procurement systems with distinct margin profiles.
- Rehabilitation Clinics:Postoperative physical therapy settings requiring graduated compression protocols.
- Specialty Stores:Brick-and-mortar surgical supply retailers serving patient-directed demand.
Contract value aggregates in Oncology Centers. Acquisition cost efficiency is climbing fastest among Home Care Patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized textile engineers and regulatory affairs professionals cluster in Germany, the United States, and Japan, anchoring the geographic concentration of post-surgery bra manufacturing expertise and compliance infrastructure.
United States
FDA 510(k) clearance pathways for Class I medical devices streamline market entry for compression garment manufacturers targeting hospital outpatient channels. Medicare and private payor reimbursement frameworks for post-mastectomy supplies create predictable revenue flows. The Greater Boston and Minneapolis-St. Paul metropolitan areas host dense concentrations of medical textile R&D facilities serving oncology center procurement networks.
Germany
Statutory health insurance reimbursement for breast surgery aftercare stabilizes manufacturer revenue visibility in Western Europe's largest medical textile market. EU Medical Device Regulation mandates CE marking and clinical evaluation documentation, elevating compliance barriers. The Rhine-Ruhr industrial corridor anchors production capacity for graduated compression engineering serving hospital procurement contracts across German-speaking Europe.
Japan
PMDA QMS certification requirements through the Ministry of Health, Labour and Welfare favor established manufacturers with dedicated regulatory affairs functions. Aging demographics and rising breast cancer screening rates expand addressable patient populations. The Kanto region surrounding Tokyo concentrates specialty surgical supply retailers where patient-directed purchasing is displacing traditional hospital discharge kit monopolies.
United Kingdom
NHS procurement frameworks for post-mastectomy garments consolidate purchasing around approved supplier lists with elevated technical specifications. Brexit-related regulatory divergence from EU MDR creates parallel compliance pathways for market access. The East Midlands and West Yorkshire textile manufacturing clusters retain specialized elastic fabric weaving capacity for medical-grade compression applications.
France
ANSM oversight of medical device classification governs compression garment market access alongside EU MDR harmonization requirements. Regional health agency reimbursement policies for oncological reconstruction create payment flow variability across metropolitan versus rural care settings. The Lyon and Paris metropolitan areas concentrate plastic surgery clinic networks serving elective aesthetic procedure segments outside hospital procurement systems.
Global Post Surgery Bras Market Competitive Landscape
Top-tier vendors anchor hospital procurement contracts, while mid-scale specialists compete on textile engineering differentiation and direct-to-consumer channel access. The vendor base stratifies between scale-driven manufacturers with diversified medical supply portfolios and focused compression garment specialists with dedicated mastectomy expertise. Two dominant archetypes emerge: institutional procurement anchors with broad distribution infrastructure, and R&D-intensive textile engineers competing on fabric performance metrics. Competitive moves concentrate on regulatory certification accumulation and specialty retail channel expansion.
Among established European specialists, Amoena and Anita Dr. Helbig GmbH occupy positions within the dedicated mastectomy garment tier, representing decades of oncological reconstruction focus. Medline Industries anchors the scale-driven institutional procurement segment, exemplifying diversified medical supply manufacturers with hospital contract concentration. The Marena Group sits within the textile R&D-intensive archetype, representing fabric engineering specialists competing on breathability and compression calibration metrics.
| Leading Market Players |
|---|
| Medline Industries |
| Cardinal Health |
| Dale Medical |
| Amoena |
| The Marena Group |
| Tytex |
| Anita Dr. Helbig GmbH |
| Jodee Post-Mastectomy Fashions |
| Medical Z |
| Others |
Supply & Pricing Matrix
Captive spandex production in Germany and the United States anchors margin stability for medical-grade compression garment manufacturers, insulating premium tiers from petroleum feedstock volatility while forcing price discipline on outsourced competitors serving home care channels. This integration choice concentrates pricing power among established vendors with in-house elastane blending capacity, compressing margins for pure assemblers dependent on spot-market synthetic fiber purchases.
Pricing Analysis
Bundled hospital discharge kits versus unbundled patient-directed purchasing splits pricing architecture across institutional and retail channels. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) certification status and millimeter-of-mercury calibration precision. Pricing pressure stems from single-source contract consolidation in oncology center procurement, compressing vendor margins on volume commitments. Home care patients exhibit highest price sensitivity, while hospital purchasing committees prioritize technical specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with petroleum-derived spandex feedstocks concentrated in Germany, the United States, and Japan. Raw material dependencies center on elastane polymers, nylon 6,6 chips, and medical-grade cotton from certified organic sources. Supply chain risk manifests as tariff exposure on Asian textile imports into Western markets. Distribution runs through hospital procurement systems, specialty surgical supply retailers, and direct-to-consumer digital channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The post surgery bras market compounds steadily as aging demographics and expanding breast cancer screening protocols generate predictable procedure volumes across developed economies. Reimbursement framework stability in Germany, the United States, and Japan supports recurring revenue visibility for compliant manufacturers.
For Market Incumbents: Lock in oncology center procurement contracts through dedicated regulatory affairs staffing for FDA 510(k) and EU MDR submission velocity. Deepen backward integration into elastane polymer production to defend margin position against petroleum feedstock volatility. Counter patient-directed purchasing fragmentation by acquiring digital-native direct-to-consumer brands with established peer-review credibility.
For New Entrants and Emerging Players: Plastic surgery clinic networks in French and Japanese metropolitan markets represent underserved buyer archetypes outside hospital procurement monopolies. Elective aesthetic procedure volumes outpace oncological reconstruction in these channels, opening parallel distribution paths with less stringent technical specification requirements. Pursue white-label manufacturing partnerships with established textile engineers to bypass capital-intensive compression calibration infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale compression garment specialists because EU MDR compliance costs and PMDA QMS certification barriers prevent organic entry by new competitors. Target manufacturers with existing notified body relationships and hospital system reference accounts. Watch for inflection in patient-directed purchasing share as signal of channel power shift toward digital-native brands.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Class I medical device registration unlocks hospital outpatient procurement channels and Medicare reimbursement eligibility. |
| EU MDR CE Marking Investment | Clinical evaluation documentation and notified body engagement secure market access across German-speaking European oncology networks. |
| Backward Integration into Elastane | In-house polymer blending capacity insulates margin structures from petroleum feedstock price volatility in spandex markets. |
| Direct-to-Consumer Channel Launch | Digital-native distribution captures patient-directed purchasing growth displacing traditional hospital discharge kit monopolies in Japan and the United States. |
| Smart Textile R&D Partnership | Moisture-wicking nanofiber integration enables premium positioning through measurable breathability performance metrics exceeding standard blends. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and France, with primary inputs from each market cluster. The research combines structured interviews with oncology center procurement managers, biomedical textile engineers, regulatory affairs consultants, GPO contracts specialists, and specialty surgical supply retailers with secondary validation. Sources include FDA 510(k) filings, EU MDR notified body registries, PMDA QMS certification databases, hospital procurement tender records, and trade data on medical textile imports. Bottom-up patient volume estimates and top-down manufacturer revenue triangulation anchor market sizing.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type, material composition, application, and end-user channel with regional regulatory cluster overlays. CAGRs derive from procedure volume projections, reimbursement policy trajectories, and channel shift assumptions. Industry-specific forecast inputs incorporate breast cancer incidence screening expansion rates and elective aesthetic procedure volume trends in metropolitan markets.
Underlying measurement precision varies by segment; hospital outpatient procurement data carries tighter precision than patient-directed purchasing estimates. Forecasts reflect documented assumptions regarding reimbursement stability, regulatory timeline continuity, and feedstock price normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Oral Syringes Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Skin Tac Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Drosophila Bottles Market