
 Global Copper Clad Steel (CCS) Wire Market | 2026-2036
Global Copper Clad Steel (CCS) Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Global Copper Clad Steel (CCS) Wire Market Analysis
The EU Green Deal is expanding copper recovery mandates across electrical supply chains, pushing OEMs toward clad-metal alternatives that reduce virgin copper dependence. Copperweld Bimetallics leverages continuous cladding patents to dominate North American utility specifications. Fisk Alloy sustains niche dominance in corrosion-resistant marine-grade strands through proprietary annealing control. AFL Global anchors Asian telecom infrastructure with high-volume production of standardized conductor reels.
Copper clad steel wire consists of a steel core metallurgically bonded with a copper outer layer, typically achieving conductivity of 21% to 40% IACS depending on copper thickness ratio, engineered where tensile strength and moderate conductivity outweigh pure copper economics. Stranded CCS wire leads volume in telecommunications grounding and coaxial shielding where flex resistance matters, while insulated CCS wire captures margin pools in automotive OEM harnesses requiring lightweighting without sacrificing ampacity. Standard CCS wire remains mature in power cable applications where cost minimization dominates procurement.
The US EPA and China's MEE enforce divergent heavy-metal and recycling standards that fragment cross-border product certification, forcing manufacturers to maintain parallel compliance documentation. REACH in Europe restricts certain surface treatment chemistries used in wire drawing lubricants, redirecting R&D toward aqueous coating systems. Buyers must monitor how Japan's METI updates JIS conductivity benchmarks, as tighter tolerances would disqualify legacy cladding ratios from premium supply tiers.
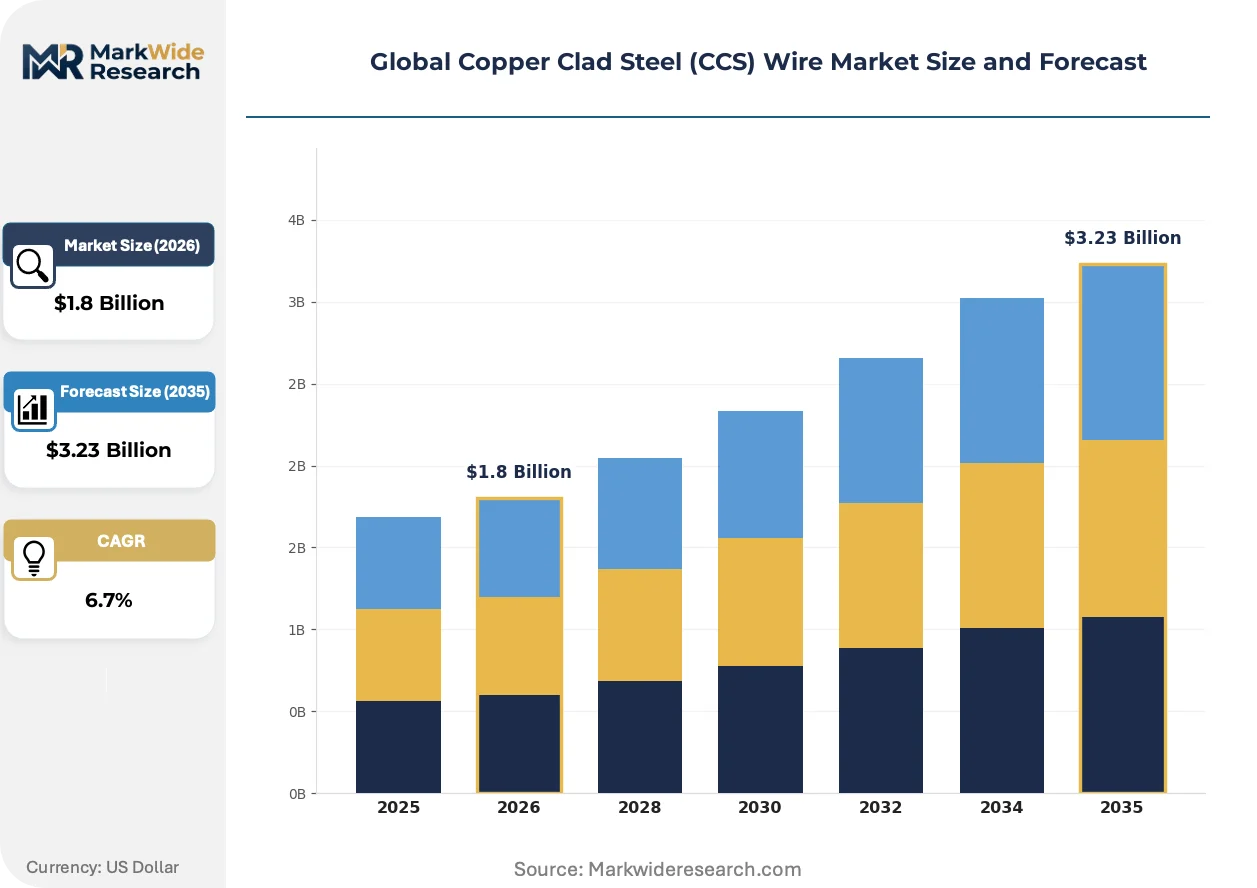
Market Dynamics
China's dual carbon goals are forcing wire manufacturers to redesign cladding processes around material efficiency mandates, compressing acceptable copper thickness ratios while preserving conductivity benchmarks for grid infrastructure.
Growth Catalysts
- India's rural electrification:Grid modernization programs under the Ministry of Power prioritize cost-effective conductor alternatives. CCS wire captures procurement slots where pure copper exceeds budget thresholds.
- REACH surface treatment restrictions:ECHA's lubricant chemistry limits redirect R&D spending toward aqueous coating systems. European manufacturers accelerate compliant process development.
- 5G backhaul buildouts:Telecom infrastructure builders in Southeast Asia specify stranded CCS wire for grounding and shielding applications where flex resistance matters.
Market Restraints
- Copper price volatility:London Metal Exchange pricing swings compress cladding economics unpredictably. Manufacturers hedge exposure through forward contracts or absorb margin erosion.
- Conductivity ceiling:40% IACS represents the practical upper bound for standard CCS ratios. Applications requiring higher ampacity exclude the material regardless of cost advantage.
- Cross-border certification fragmentation:US EPA heavy-metal standards diverge from China's MEE recycling mandates. Parallel documentation burdens inflate compliance overhead.
Strategic Opportunities
- Automotive lightweighting:OEM harness specifications increasingly accept insulated CCS wire where ampacity requirements allow. Tier-1 suppliers qualify alternative conductors for EV platforms.
- EU Green Deal copper recovery:Recovery mandates across electrical supply chains push OEMs toward clad-metal alternatives reducing virgin copper dependence.
- Marine-grade corrosion resistance:Proprietary annealing control enables penetration of offshore wind and shipbuilding applications previously served by solid copper.
Industry Challenges
- Cladding process engineering talent:Continuous metallurgical bonding expertise concentrates at legacy facilities. New entrants face recruitment barriers for specialized technicians.
- JIS tolerance compliance:Japan's METI conductivity benchmark updates threaten disqualification of legacy cladding ratios. Manufacturers must requalify production lines against tighter specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Copper Clad Steel (CCS) Wire Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard CCS Wire, Stranded CCS Wire, Bare CCS Wire, Insulated CCS Wire Application: Telecommunications, Automotive Wiring, Power Cables, Electrical Appliances End User: Construction Industry, Electronics Manufacturers, Automotive OEMs, Renewable Energy Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | Copperweld Bimetallics, Fisk Alloy, LM Cables, MWS Wire Industries, Copperhead Industries, AFL Global, Nippon Steel Wire & Cable, Fushi Copperweld, Changzhou Clad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Copper Clad Steel (CCS) Wire Market Emerging Trajectories
Continuous cladding patents and aqueous coating chemistries are reshaping how manufacturers balance conductivity, tensile strength, and environmental compliance across telecom, automotive, and power transmission verticals.
Ultrasonic-assisted cladding is expanding into high-volume production of thin-copper-layer CCS wire for telecommunications grounding. Southeast Asian telecom infrastructure builders adopt these conductors for 5G backhaul networks where moderate conductivity suffices. The process is expanding into applications previously reserved for solid copper braid, compressing material costs without sacrificing flex performance.
REACH restrictions on surface treatment chemistries used in wire drawing lubricants are forcing European manufacturers toward aqueous coating systems. ECHA's regulatory timeline compresses R&D cycles for compliant process development. Automotive OEM harness specifications in Germany and France now require documentation of lubricant chemistry chains, disqualifying traditional oil-based treatments from premium supply tiers.
Buyer consolidation among Indian state electricity boards is compressing supplier qualification timelines. Grid modernization procurement now bundles conductor specifications across transmission and distribution segments, favoring manufacturers with multi-product portfolios. This concentration is most visible in Maharashtra and Gujarat, where single-tender awards displace fragmented municipal purchasing.
Global Copper Clad Steel (CCS) Wire Market Segmentation
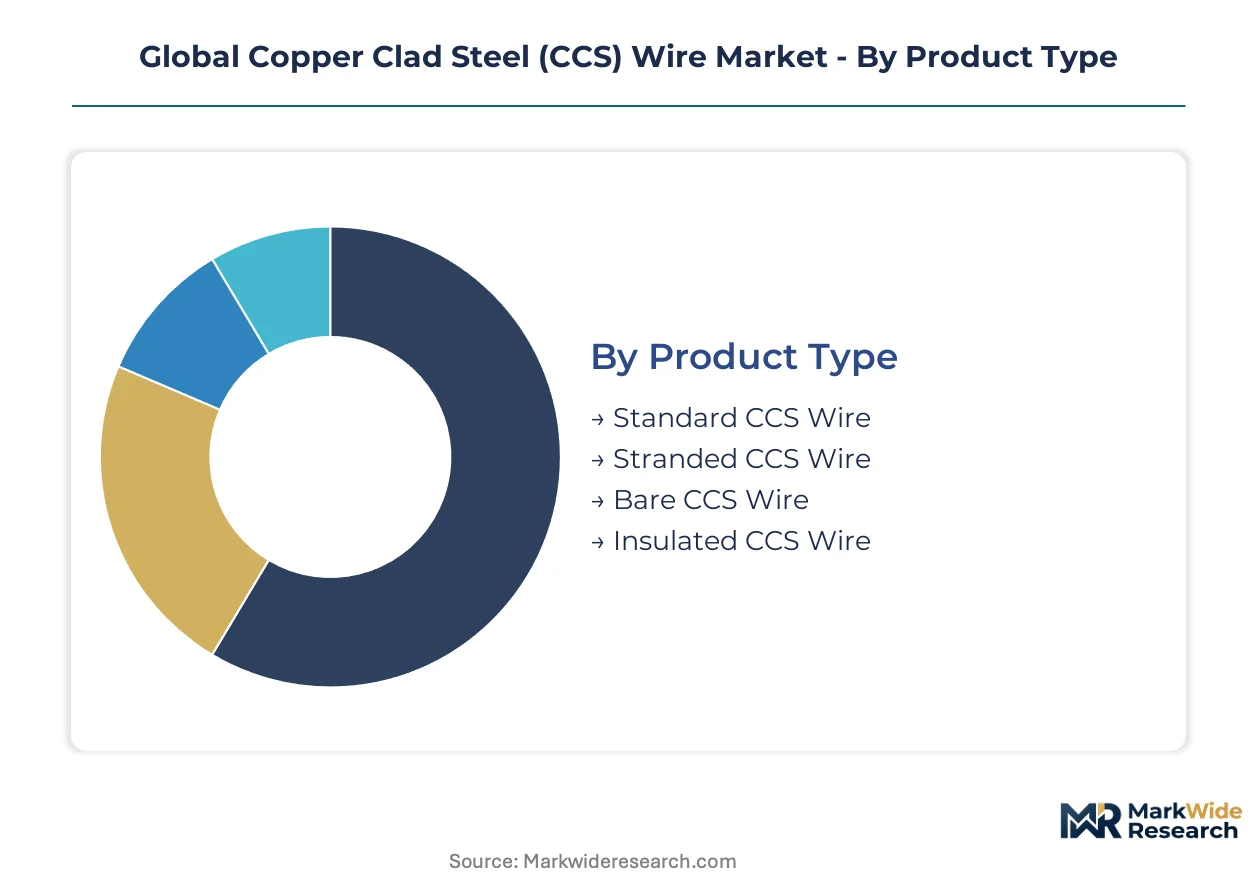
Copper clad steel wire manufacturers must align production configurations against four distinct segmentation axes. Product specifications determine cladding process investments. Application requirements dictate conductivity and tensile strength trade-offs. End-user procurement patterns govern inventory positioning and technical support intensity.
Product Type:
Continuous cladding equipment and metallurgical bonding lines represent the heaviest capital commitments, with multi-million dollar furnace investments amortized across product mix decisions.
- Standard CCS Wire:Single-layer copper cladding on steel core achieves 21-30% IACS conductivity through conventional rolling or drawing processes. India's state electricity boards specify this grade for rural distribution networks where cost thresholds exclude pure copper alternatives.
- Stranded CCS Wire:Multiple CCS strands twisted into flexible conductors deliver superior flex resistance for dynamic applications. Southeast Asian 5G infrastructure builders procure stranded configurations for grounding systems and coaxial cable shielding where installation bending demands exceed solid wire limits.
- Bare CCS Wire:Uninsulated conductors serve direct-burial grounding electrodes and overhead guy wires. Corrosion performance depends entirely on copper layer integrity and steel core metallurgy.
- Insulated CCS Wire:Polymer-jacketed conductors penetrate automotive OEM harness specifications where weight reduction targets intersect with moderate ampacity requirements. REACH-compliant jacket chemistries now dominate European sourcing.
Standard CCS wire absorbs the bulk of installed capacity; insulated CCS wire is expanding most quickly.
Application:
Volume concentration varies sharply across end-use sectors, with telecommunications and power transmission commanding fundamentally different technical qualification protocols.
- Telecommunications:Grounding and shielding applications prioritize flex resistance and corrosion durability over maximum conductivity. Stranded CCS configurations displace solid copper braid in 5G backhaul infrastructure across Indonesia, Vietnam, and the Philippines.
- Automotive Wiring:OEM harness specifications increasingly accept insulated CCS conductors for non-critical circuits where ampacity headroom exists. Tier-1 suppliers in Germany and France qualify alternative materials against gram-per-meter weight targets.
- Power Cables:Utility procurement emphasizes cost minimization for grid modernization programs. Standard CCS ratios satisfy transmission efficiency requirements in emerging market distribution networks.
- Electrical Appliances:Internal wiring for motors and heating elements demands precise conductivity control. BIS certification requirements in India filter supplier participation for appliance-grade conductors.
Power cables anchor volume demand; automotive wiring gains share fastest.
End User:
Procurement sophistication diverges across customer categories, with renewable energy developers imposing the most stringent documentation and traceability requirements.
- Construction Industry:Building grounding systems and lightning protection specify bare CCS wire for cost-effective earth electrode installations. Project-based purchasing patterns create demand lumpiness.
- Electronics Manufacturers:Connector and component producers source precision-drawn CCS wire for RF shielding and signal transmission applications. JIS conductivity tolerances from METI constrain Japanese market participation.
- Automotive OEMs:Platform-level conductor qualification cycles extend 24-36 months. Insulated CCS wire penetration depends on harness architecture decisions at Volkswagen, Stellantis, and Hyundai-Kia.
- Renewable Energy:Offshore wind and solar farm developers specify marine-grade corrosion-resistant strands. Proprietary annealing control from specialized suppliers penetrates this premium tier.
Construction industry offtake dominates current volumes; renewable energy is climbing the fastest.
Distribution Channel:
Channel economics reflect order fragmentation and technical support intensity, with direct relationships commanding margin premiums for complex specifications.
- Direct Sales:Manufacturer-direct relationships serve automotive OEMs and major utilities requiring collaborative design and lot traceability. Account teams coordinate cladding ratio customization and certification documentation.
- Distributors:Electrical supply houses aggregate fragmented construction and maintenance demand. Inventory positioning in Maharashtra and Gujarat state electricity board territories captures Indian grid modernization procurement.
- Retailers:Counter sales serve small-scale contractors and repair operations. Standard CCS wire SKUs dominate this channel with minimal technical differentiation.
- Online Platforms:Digital procurement penetration remains limited for specification-grade conductors. Sample verification and certification authentication requirements constrain pure e-commerce adoption.
Distributors handle the majority of transaction volume; direct sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China and India where continuous cladding capacity serves domestic infrastructure buildouts, while consumption tilts toward Southeast Asian telecom networks and European automotive OEMs seeking weight-reduced conductors.
China
State Grid Corporation procurement under dual carbon mandates compresses acceptable copper thickness ratios while preserving conductivity benchmarks. MIIT material efficiency standards force cladding process redesigns at Yangtze River Delta facilities. Jiangsu and Zhejiang province manufacturers supply stranded CCS wire for domestic 5G backhaul and export to Indonesian telecom builders.
United States
Utility specification dominance by continuous cladding patent holders anchors North American demand. EPA heavy-metal standards diverge from Asian recycling mandates, forcing parallel compliance documentation. Ohio and Pennsylvania industrial clusters serve automotive OEM harness qualification programs for EV platform lightweighting.
India
Ministry of Power grid modernization and rural electrification programs prioritize cost-effective conductor alternatives where pure copper exceeds budget thresholds. BIS certification requirements filter supplier participation for appliance-grade and utility-grade conductors. Maharashtra and Gujarat state electricity board procurement consolidation favors manufacturers with multi-product portfolios.
Japan
METI JIS conductivity benchmark updates threaten disqualification of legacy cladding ratios from premium supply tiers. Electronics manufacturers in Kanto and Kansai regions source precision-drawn CCS wire for RF shielding applications. Tighter tolerance enforcement drives requalification investments at domestic production lines.
Germany
REACH surface treatment restrictions redirect R&D spending toward aqueous coating systems for wire drawing lubricants. Automotive OEM harness specifications in Stuttgart and Munich now require documentation of lubricant chemistry chains. Tier-1 suppliers qualify insulated CCS conductors against gram-per-meter weight targets for EV platforms.
Global Copper Clad Steel (CCS) Wire Market Vendor Landscape
The competitive structure tilts toward technology-differentiated specialists rather than scale-driven commodity producers. Patent-protected continuous cladding processes concentrate among North American and Chinese incumbents, creating qualification barriers for new entrants. Two strategic archetypes dominate: metallurgical bonding specialists with proprietary annealing control, and high-volume reel manufacturers serving standardized telecom specifications. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players defend position in automotive and renewable energy verticals.
Among North American metallurgical specialists, Copperweld Bimetallics and Fisk Alloy occupy positions defined by continuous cladding patents and corrosion-resistant marine-grade expertise respectively. AFL Global anchors the high-volume telecom infrastructure tier with standardized conductor reel production for Asian 5G buildouts. Chinese fabricators including Fushi Copperweld and Changzhou Clad exemplify the scale-driven archetype serving domestic grid modernization and export markets. Japanese and European players sit within premium-tier positioning shaped by JIS tolerance compliance and REACH-aligned aqueous coating capabilities.
| Leading Market Players |
|---|
| Copperweld Bimetallics |
| Fisk Alloy |
| LM Cables |
| MWS Wire Industries |
| Copperhead Industries |
| AFL Global |
| Nippon Steel Wire & Cable |
| Fushi Copperweld |
| Changzhou Clad |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange copper pricing cascades through CCS wire manufacturing into three distinct procurement tiers, with spot volatility compressing cladding economics and forcing buyers toward long-term offtake structures that lock in raw material spreads against steel substrate costs.
Pricing Analysis
Conductivity-per-dollar throughput anchors value-based pricing across utility, automotive, and telecom verticals. Premium-mid-economy pricing differentiation separates marine-grade corrosion-resistant strands with proprietary annealing control from standard grid-grade conductors serving Indian state electricity boards. Cost compression in standard CCS tiers is intensifying because buyer consolidation among Maharashtra and Gujarat utilities compresses supplier margins. Automotive OEMs exhibit lowest price sensitivity due to 24-36 month qualification cycles, while construction contractors purchasing through electrical supply houses drive hardest bargain on per-meter basis.
Supply Chain Analysis
Certification gating through BIS, JIS, and EPA standards fragments supplier participation across export markets. Manufacturing concentrates in China, India, and the United States, with Jiangsu and Zhejiang province facilities serving domestic 5G infrastructure and Indonesian telecom export demand. Raw material flows draw from Chilean copper cathode, domestic steel rod, and REACH-compliant aqueous coating chemistries. Single-source vulnerability concentrates in continuous cladding furnace equipment where multi-million dollar capital commitments tether capacity expansion to incumbent technology licensors. Distribution runs through direct manufacturer relationships for automotive OEMs and electrical supply house networks for fragmented construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CCS wire market sits in a metallurgical bonding technology transition, with ultrasonic-assisted cladding displacing conventional rolling processes in thin-copper-layer telecommunications applications.
For Market Incumbents: Lock in continuous cladding patent licensing revenue streams before aqueous coating process patents mature. Defend utility specification dominance by embedding field engineering teams with State Grid Corporation and Indian state electricity boards. Capacity addition in Yangtze River Delta facilities preserves proximity to Southeast Asian telecom infrastructure builders while MIIT material efficiency mandates compress acceptable copper thickness ratios. For New Entrants and Emerging Players: Launch via distributor partnerships in Maharashtra and Gujarat state electricity board territories where procurement consolidation favors multi-product portfolios. Marine-grade corrosion-resistant strands for offshore wind developers offer lowest incumbent saturation. Target automotive OEM harness qualification programs in Stuttgart and Munich where gram-per-meter weight targets open specification slots for insulated CCS alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor metallurgical bonding specialists with proprietary annealing control in East Asian manufacturing clusters. Long-term viability hinges on technology licensing moats rather than commodity scale. Watch for JIS conductivity benchmark enforcement by METI as inflection indicator disqualifying legacy cladding ratios from premium Japanese electronics supply tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Cladding Patent Licensing | Technology licensors capture recurring revenue from Yangtze River Delta capacity expansions. |
| Aqueous Coating Process Development | REACH compliance investments redirect European R&D spending toward ECHA-aligned chemistries. |
| Automotive OEM Harness Qualification | Platform-level decisions at Volkswagen and Stellantis determine insulated CCS penetration rates. |
| Marine-Grade Corrosion Resistance Certification | Proprietary annealing control unlocks offshore wind procurement previously reserved for solid copper. |
| Direct Utility Relationship Expansion | Field engineering embedment with State Grid Corporation secures dual carbon mandate procurement slots. |
Methodological Framework
Multi-period observation of London Metal Exchange copper spreads, State Grid Corporation procurement volumes, and MIIT material efficiency standard implementations anchored the trend analysis, supplemented by interviews with continuous cladding furnace operators, utility procurement directors at Indian state electricity boards, automotive OEM harness engineers, and aqueous coating chemistry R&D leads. Secondary validation drew from customs trade data, SEC filings of listed wire manufacturers, BIS certification registries, and ECHA REACH restriction timelines. Bottom-up production capacity tallies triangulated against top-down consumption estimates across telecommunications, automotive, and power transmission verticals.
Input-output matrices modeled cladding ratio configurations against conductivity benchmarks and tensile strength requirements across the projection horizon. Segmentation dimensions included product type, application sector, end-user procurement sophistication, and distribution channel intensity. CAGRs were derived from elasticity-adjusted demand curves incorporating raw material price sensitivity and regulatory compliance cost pass-through. Forecast inputs weighted ultrasonic-assisted cladding adoption rates in Southeast Asian 5G buildouts and JIS tolerance tightening scenarios from METI.
Copper price volatility, regulatory fragmentation between EPA and MEE standards, and automotive OEM platform architecture decisions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding cladding process yield rates and qualification timeline durations. A model refresh is warranted upon material change in METI conductivity benchmark enforcement or State Grid Corporation dual carbon procurement weightings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
Europe Busbar Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
India Electrical Enclosures Market