
 Global Sealed DC Contactor Market | 2026-2036
Global Sealed DC Contactor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sealed DC Contactor Market Outlook
Project finance tied to EV battery gigafactories is rewriting capital requirements for sealed DC contactor suppliers. TE Connectivity leverages vertical integration into ceramic-to-metal sealing to anchor high-voltage product lines. Sensata Technologies sustains R&D intensity in solid-state contactor architectures. Schaltbau competes through railway certification depth across European networks.
Sealed DC contactors are hermetically enclosed electromechanical or solid-state switching devices rated for direct-current interruption, typically employing hydrogen or vacuum dielectrics to suppress arc formation in high-voltage environments. Their primary purpose is to enable safe, repeatable make-break operations in battery electric vehicles, photovoltaic inverters, and traction power systems where ambient contamination would degrade conventional open-frame designs. Electromechanical variants still occupy the majority of unit volume, though solid-state contactors are capturing margin pools in premium automotive battery management where semiconductor switching eliminates mechanical wear. End-user demand from renewable energy installations is expanding fastest, driven by utility-scale solar and offshore wind converters requiring sealed reliability in harsh climates.
FDA oversight of medical-grade power systems, EPA emissions frameworks indirectly pressuring fleet electrification, and China's NMPA alignment with GB standards for new energy vehicles collectively elevate sealing integrity and materials traceability requirements. The EU AI Act and CSRD disclosure rules are adding supply-chain transparency mandates that contactor vendors must now document. Stakeholders should monitor how IEC revision cycles and emerging battery safety regulations in automotive target markets redefine qualification thresholds before committing to platform-specific designs.
Market Dynamics
Automotive OEMs are consolidating supplier relationships around hermetic sealing capabilities as battery pack voltages climb past 800V, forcing contactor vendors to requalify platforms under compressed development cycles.
Growth Catalysts
- EV Battery Gigafactory Buildouts:Electric vehicle manufacturers in China, Germany, and the United States are localizing contactor procurement to secure supply chain resilience for high-voltage battery management systems.
- IEC 60947 Revision Cycles:Tightening arc-quenching and sealing requirements across major manufacturing jurisdictions are mandating upgraded contactor designs that lock in replacement demand.
- Hydrogen Dielectric Adoption:Hydrogen-filled contactor architectures are displacing older nitrogen designs in premium automotive applications where switching speed and arc suppression determine pack safety margins.
Market Restraints
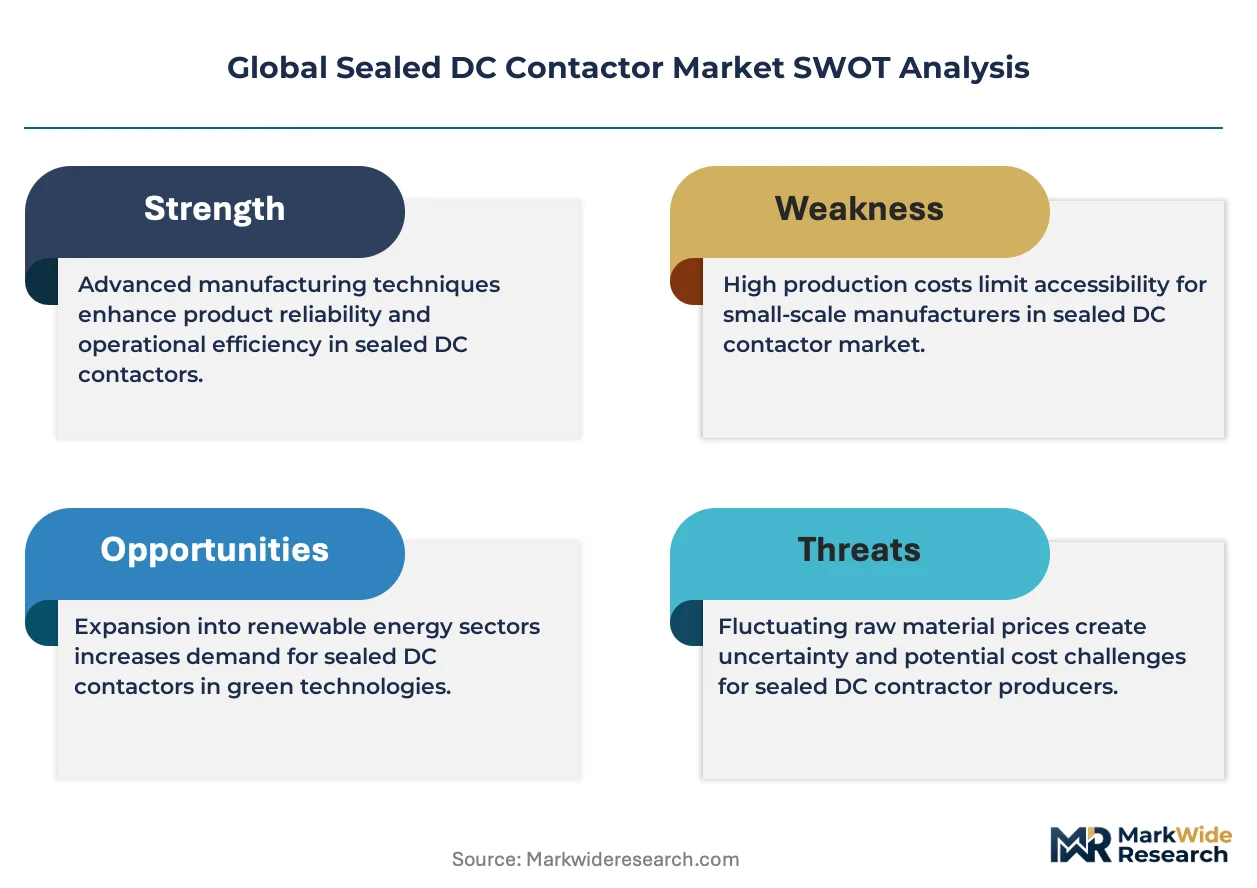
- Silver-Copper Alloy Volatility:Contact material costs fluctuate with precious metal markets, compressing margin stability for electromechanical product lines.
- Ceramic-to-Metal Sealing Concentration:Three specialized suppliers control high-integrity feedthrough manufacturing, creating single-source vulnerability for hermetic contactor producers.
- Solid-State Substitution Threat:Silicon carbide power modules are capturing switching applications below 400A in stationary energy storage, narrowing the addressable market for electromechanical alternatives.
Strategic Opportunities
- Offshore Wind Converter Demand:Utility-scale installations in the North Sea and East Asian waters require sealed reliability in salt-laden, humid environments where open-frame contactors fail prematurely.
- India PLI Scheme Alignment:Production-linked incentives for advanced chemistry cell manufacturing are attracting contactor vendors to establish local assembly for domestic battery integrators.
- Solid-State Electromechanical Convergence:Hybrid architectures combining semiconductor pre-switching with mechanical isolation are opening premium automotive segments previously closed to pure electromechanical designs.
Industry Challenges
- Hermetic Welding Specialist Scarcity:Electron beam and laser sealing technicians command premium wages as aerospace and medical device sectors compete for the same talent pool.
- Multi-Jurisdiction Certification Overlap:Simultaneous UL 508, IEC 60947, and GB standard compliance extends qualification timelines by 8-14 months for platform launches targeting multiple automotive markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sealed DC Contactor Market |
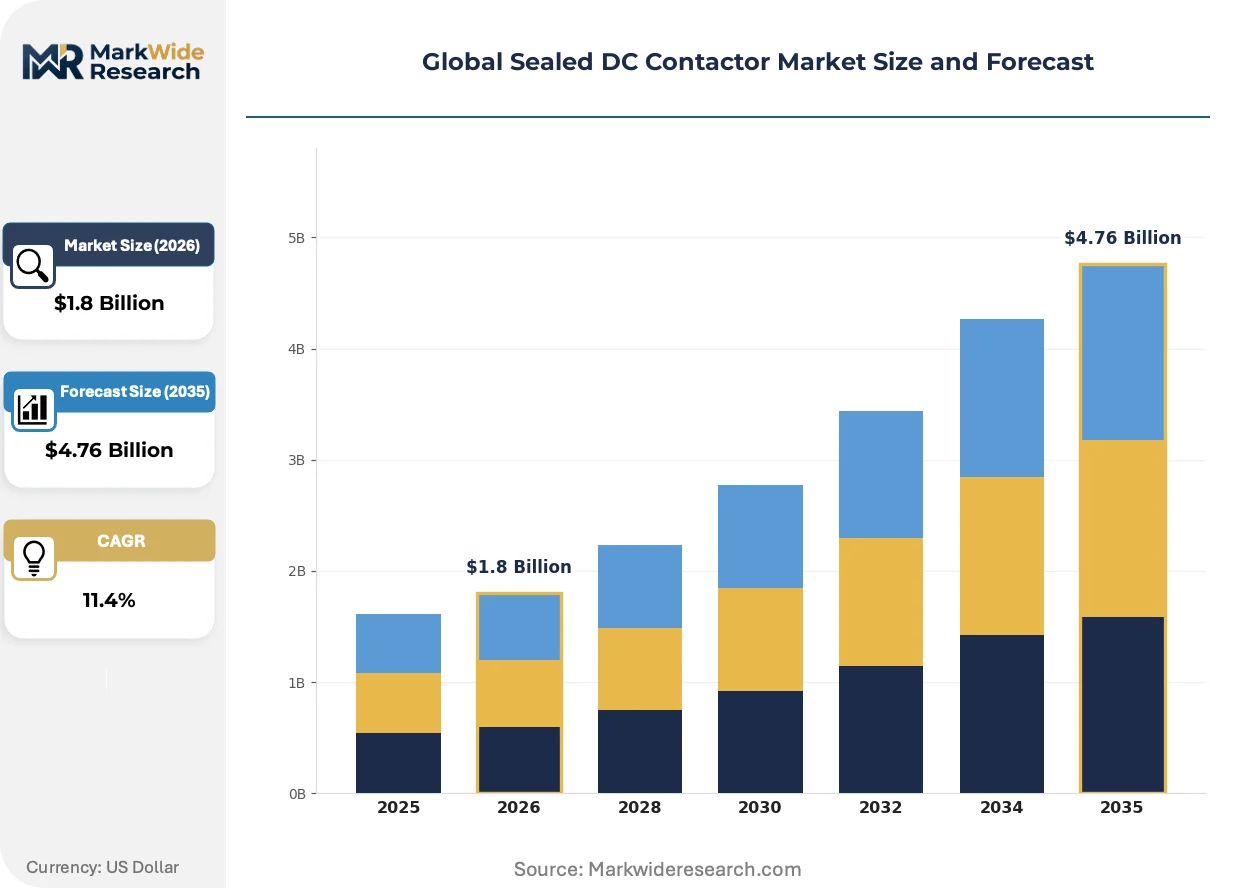
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Solid State, Relay Type, Miniature Type End User: Automotive, Renewable Energy, Industrial Equipment, Railways Application: Motor Control, Power Switching, Automation Systems, Battery Management Material: Plastic, Metal, Composite, Other |
| Companies Covered | TE Connectivity, Sensata Technologies, Schaltbau, ABB, Schneider Electric, Siemens AG, Mitsubishi Electric, Eaton Corporation, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sealed DC Contactor Market Strategic Shifts
Sealed DC contactor technology is bifurcating between legacy electromechanical reliability and solid-state switching speed, with hybrid architectures emerging as the contested middle ground for next-generation battery systems.
Ceramic-to-metal feedthrough technology is hybridizing vacuum and hydrogen dielectric designs into unified platforms that adapt switching characteristics to load profiles in real time. Tier 1 automotive suppliers are piloting these architectures for 800V+ battery management systems where arc energy varies with state-of-charge. The structural consequence is compressing the performance gap between premium solid-state and mid-tier electromechanical price points.
REACH substance restrictions on lead-bearing solders and cadmium-plated components are forcing contactor manufacturers to requalify termination metallurgies under accelerated life testing protocols. Industrial consequences include 12-18 month redesign cycles for established product families and elevated qualification costs passed through to battery integrators. European railway and renewable energy OEMs are most affected, with several delaying platform launches to accommodate supply chain requalification.
Buyer consolidation among battery pack integrators is compressing supplier negotiation cycles from annual to quarterly frameworks, with technical scorecards now weighting sealing integrity traceability above unit cost. Direct OEM procurement teams are displacing traditional distributor networks for volumes above 50,000 units annually. This pattern is most visible in China's Yangtze River Delta cluster, where CATL and BYD procurement offices maintain resident engineer programs at contactor manufacturing sites.
Global Sealed DC Contactor Market Segmentation
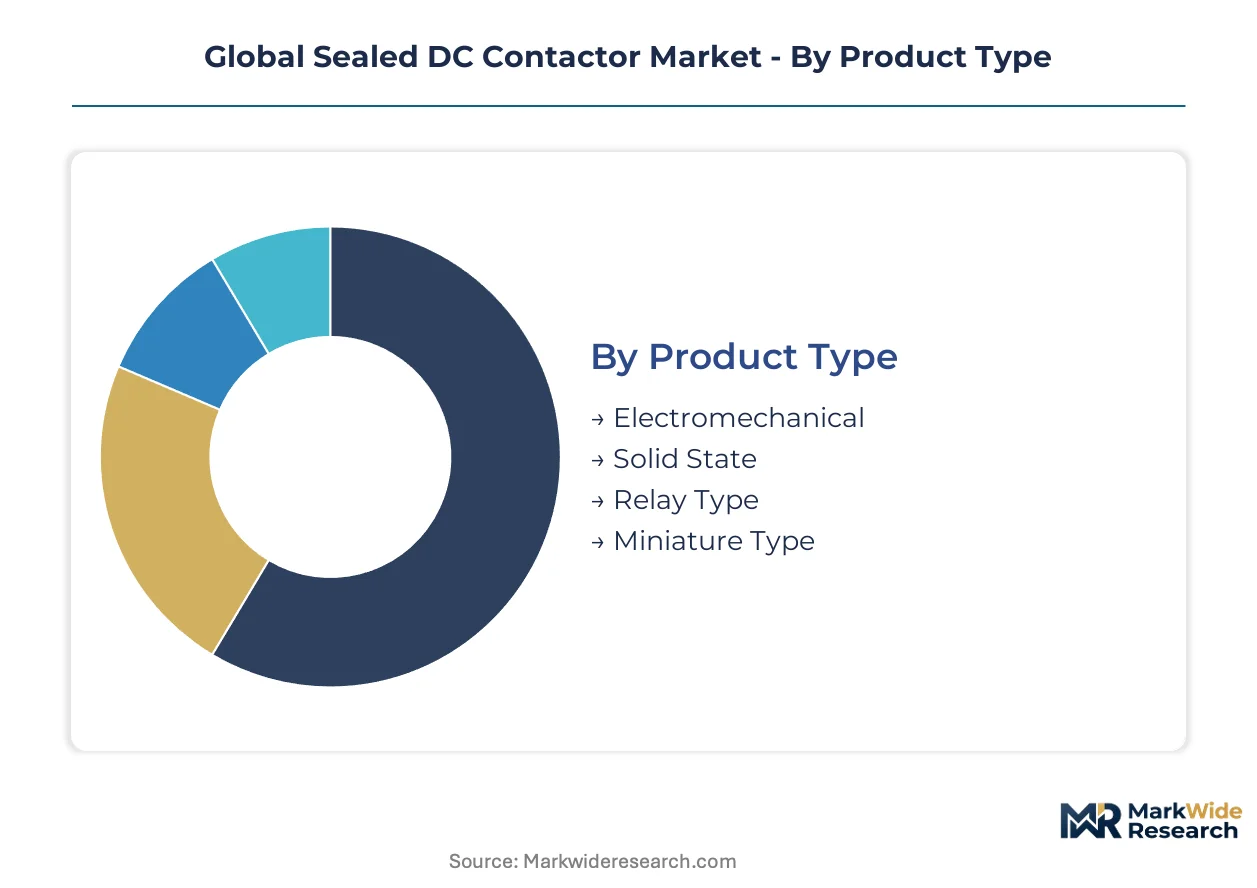
Sealed DC contactor segmentation reveals how technology choices, end-use environments, and material specifications create distinct competitive arenas. Each dimension carries different margin profiles, certification burdens, and supplier capability requirements that shape vendor positioning strategies.
Product Type:
Cost tier differentiation separates mature electromechanical platforms from emerging solid-state architectures and specialized miniature formats.
- Electromechanical:Hydrogen or vacuum dielectric enclosures with ceramic-to-metal feedthroughs enable repeatable make-break operations above 800V. Demand concentrates in Chinese and German automotive OEM battery packs where IEC 60947 qualification is mandatory and switching cycle reliability determines pack warranty costs.
- Solid State:Silicon carbide and IGBT-based semiconductor switching eliminates mechanical wear and arc formation entirely. Premium battery management systems in United States EV platforms are adopting these for sub-millisecond switching speeds where electromechanical contactors introduce unacceptable latency.
- Relay Type:Lower-current signal switching variants with simplified sealing requirements serve auxiliary circuits in industrial automation.
- Miniature Type:Compact footprints below 50mm housing width target space-constrained medical devices and aerospace power distribution.
Electromechanical contactors command the established base. The steepest expansion runs through solid-state architectures.
End User:
Application environment severity dictates hermetic integrity grades, with automotive and offshore renewable installations imposing the most demanding specifications.
- Automotive:Battery electric vehicle manufacturers require contactors rated for 1,000V DC interruption with hydrogen dielectric and ceramic feedthroughs. CATL and BYD procurement offices in China's Yangtze River Delta cluster enforce resident engineer programs at supplier manufacturing sites for volumes above 50,000 units annually.
- Renewable Energy:Utility-scale solar inverters and offshore wind converters in the North Sea and East Asian waters demand salt spray resistance and humidity tolerance that open-frame designs cannot provide.
- Industrial Equipment:Factory automation and material handling systems use mid-tier sealing grades where contamination protection matters but extreme cycling does not.
- Railways:European network operators mandate EN 50155 compliance for traction power contactors, with Schaltbau and similar vendors competing on certification depth across Deutsche Bahn and SNCF networks.
Automotive applications anchor current procurement volumes. Renewable energy installations are climbing the fastest as offshore wind buildouts accelerate.
Application:
Functional role determines switching frequency, current magnitude, and arc energy management requirements across contactor specifications.
- Motor Control:High inrush current handling with inductive load interruption in industrial drives and traction motors.
- Power Switching:Main contactor functions in EV battery disconnect and grid-tied inverter isolation.
- Automation Systems:Programmable logic controller integration with feedback signaling for manufacturing line control.
- Battery Management:Pre-charge and main contactor pairs manage state-of-charge-dependent arc characteristics in lithium-ion packs. Hydrogen-filled architectures displace nitrogen designs as pack voltages climb past 800V and arc suppression margins tighten.
Battery management applications concentrate the most stringent technical requirements. Motor control functions are expanding most quickly with industrial electrification trends.
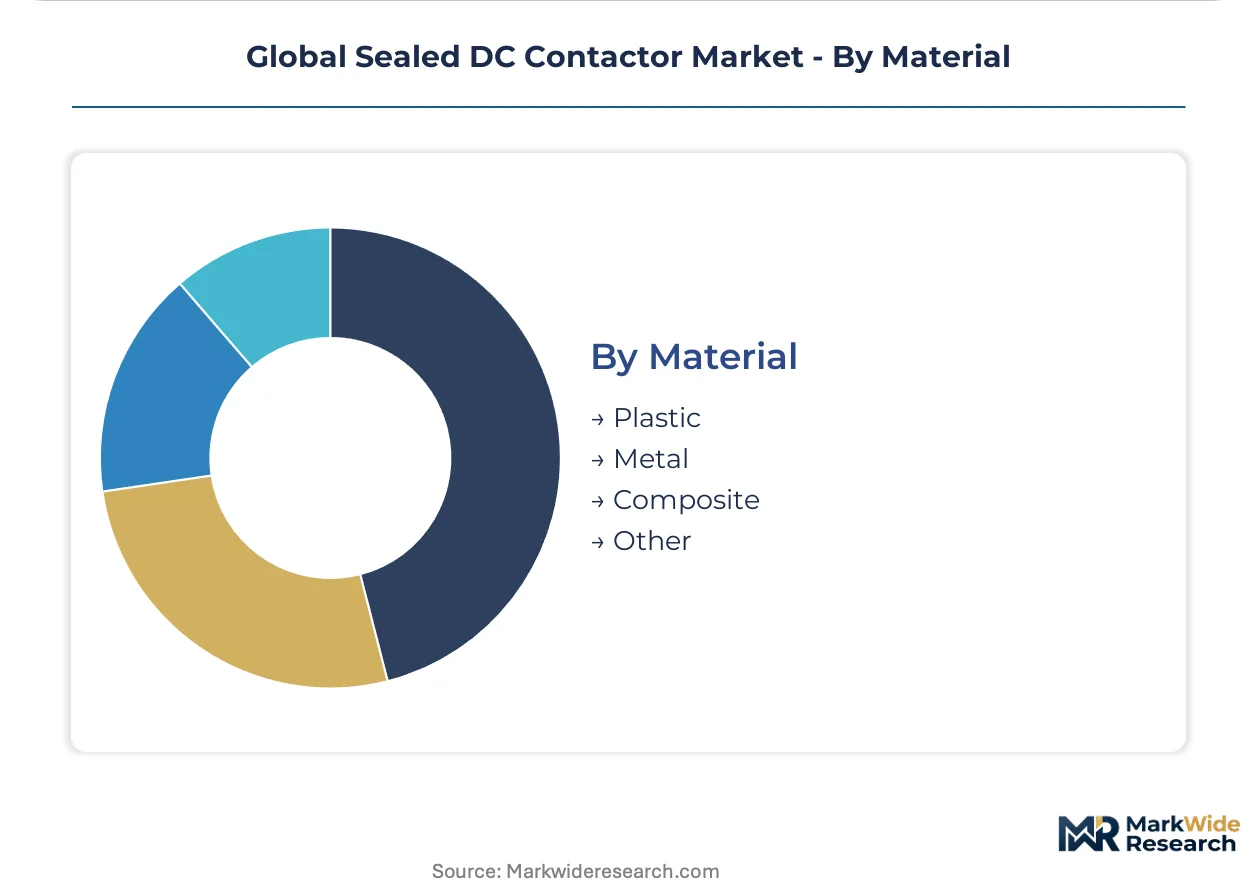
Material:
Housing and structural material selection balances hermetic integrity, thermal management, and REACH compliance costs against unit economics.
- Plastic:Glass-reinforced thermoplastics serve cost-sensitive industrial applications where operating temperatures remain below 150°C.
- Metal:Aluminum and stainless steel enclosures dominate automotive and railway segments where electromagnetic shielding and mechanical robustness are essential. REACH substance restrictions on lead-bearing solders and cadmium-plated components are forcing 12-18 month redesign cycles for established product families.
- Composite:Ceramic-polymer hybrids and metal-matrix composites target weight-critical aerospace and premium automotive applications.
- Other:Specialized glass and ceramic monoliths for extreme temperature or radiation environments.
Metal housings command the established base. Composite materials are gaining share fastest as weight reduction targets intensify across mobility applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives for advanced chemistry cell manufacturing are redirecting sealed DC contactor procurement toward jurisdictions with localized battery supply chains. Germany's KBA enforcement of UN ECE R100 battery safety standards and China's MIIT alignment with GB/T standards for high-voltage systems are elevating hermetic sealing requirements. Industrial clusters in the Yangtze River Delta, Bavaria, and Michigan are anchoring supplier engineering presence.
China
CATL and BYD procurement offices enforce resident engineer programs at contactor manufacturing sites for volumes above 50,000 units annually. MIIT's GB/T 31467 standards for new energy vehicle battery systems mandate upgraded arc-quenching performance. The Yangtze River Delta cluster concentrates supplier technical centers serving domestic OEM localization requirements.
Germany
Deutsche Bahn and SNCF network electrification programs sustain demand for railway-certified contactor architectures. KBA enforcement of UN ECE R100 and REACH substance restrictions on lead-bearing solders force 12-18 month redesign cycles. Bavaria hosts specialized hermetic welding facilities supplying automotive OEM battery pack integrators.
United States
EV battery gigafactory buildouts in Michigan, Tennessee, and Texas are localizing contactor procurement for 800V+ battery management systems. NHTSA FMVSS 305 electrical safety standards and EPA emissions frameworks indirectly pressuring fleet electrification elevate sealing integrity requirements. The Midwest industrial corridor concentrates supplier technical service operations.
India
PLI scheme incentives for advanced chemistry cell manufacturing are attracting contactor vendors to establish local assembly for domestic battery integrators. BIS certification alignment with IEC 60947 standards compresses qualification timelines for multinational suppliers. Gujarat and Tamil Nadu industrial zones host emerging supplier engineering facilities.
Japan
METI's dual carbon goals and JIS standards for high-voltage automotive components are tightening hermetic sealing specifications for export-oriented suppliers. Precision manufacturing clusters in the Nagoya and Osaka regions maintain specialized electron beam welding capabilities. Domestic semiconductor equipment demand sustains miniature contactor production for industrial automation.
Global Sealed DC Contactor Market Competitive Environment
On the supply side, the industry is consolidating around hermetic sealing capabilities as battery pack voltages climb past 800V. Three strategic archetypes dominate: diversified electrical component conglomerates with captive ceramic-to-metal sealing operations, specialized railway and industrial contactor manufacturers with deep certification portfolios, and emerging solid-state switching specialists. Competitive moves center on backward integration into feedthrough manufacturing and compressed platform requalification cycles for multi-jurisdiction automotive launches.
Within the diversified conglomerate tier, TE Connectivity, Sensata Technologies, and Schaltbau occupy positions defined by their respective vertical integration depth. TE Connectivity exemplifies the sealing-integrated archetype through captive ceramic-to-metal feedthrough production. Sensata Technologies represents the solid-state transition vector with semiconductor switching investments. Schaltbau anchors the railway-specialist position with EN 50155 certification depth across European networks. These three patterns illustrate how supplier positioning stratifies between electromechanical reliability legacy and solid-state switching speed.
| Leading Market Players |
|---|
| TE Connectivity |
| Sensata Technologies |
| Schaltbau |
| ABB |
| Schneider Electric |
| Siemens AG |
| Mitsubishi Electric |
| Eaton Corporation |
| Omron Corporation |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta manufacturing cluster anchors global hermetic sealing capacity, with CATL and BYD procurement offices extracting quarterly price concessions through resident engineer programs that compress supplier margins. This geographic concentration of ceramic-to-metal feedthrough production grants battery integrators outsized leverage in contract negotiations, while REACH compliance costs and silver-copper alloy volatility force contactor vendors to absorb input cost spikes rather than pass them downstream.
Pricing Analysis
Certification level creates the primary spread across the contactor market, with UL 508 and IEC 60947 qualified platforms commanding substantial premiums over industrial-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects arc-quenching performance, switching cycle ratings, and hydrogen dielectric purity grades. Cost compression in mid-tier electromechanical segments is intensifying because solid-state substitution threats narrow the addressable market below 400A. Battery pack integrators above 50,000 unit annual volumes exhibit lowest price sensitivity, while industrial automation buyers prioritize unit economics over hermetic integrity specifications.
Supply Chain Analysis
Extended payment terms from automotive OEMs now stretch to 90-120 days, forcing contactor vendors to utilize supply-chain finance facilities and compress working capital cycles. Manufacturing concentrates in China, Germany, and the United States, with Bavaria and Michigan hosting specialized hermetic welding facilities that draw from aerospace and medical device talent pools. Silver-copper contact materials, ceramic feedthroughs, and hydrogen gas supplies constitute critical input dependencies. Single-source vulnerability in electron beam sealing equipment creates structural risk, as three specialized suppliers control high-integrity feedthrough manufacturing globally. Distribution runs through direct OEM procurement channels that displace traditional distributor networks above volume thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron beam and laser sealing technician scarcity defines competitive boundaries in this market, with aerospace and medical device sectors competing for the same specialized talent pool. Hermetic welding capability gaps constrain capacity expansion regardless of capital availability, privileging incumbents with established training pipelines and certification depth.
For Market Incumbents: Entrench ceramic-to-metal sealing capabilities through captive feedthrough production or exclusive supplier partnerships before solid-state architectures capture premium automotive share. Accelerate multi-jurisdiction certification pipelines for IEC 60947, UL 508, and GB standard alignment to compress 8-14 month qualification timelines. Prioritize resident engineer relationships with Yangtze River Delta battery integrators to defend volume positions against emerging competitors. For New Entrants and Emerging Players: Offshore wind converter demand in the North Sea and East Asian waters represents the most penetrable entry point, as salt-laden environments disqualify open-frame alternatives and established suppliers underinvest in marine-grade sealing certifications. India's PLI scheme for advanced chemistry cell manufacturing offers second-mover advantages for domestic assembly partnerships with Gujarat and Tamil Nadu battery integrators. Target technical service relationships rather than volume manufacturing to build qualification track records before scaling. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid electromechanical-solid-state architectures that bridge performance gaps while semiconductor switching matures for high-current applications. Long-term viability hinges on backward integration into ceramic-to-metal sealing or exclusive access to electron beam welding talent pipelines. Watch solid-state switching cost curves as the critical inflection indicator for electromechanical addressable market erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-to-Metal Sealing Integration | Captive feedthrough production insulates TE Connectivity and Sensata from single-source supplier vulnerabilities. |
| Hydrogen Dielectric Platform Expansion | Hydrogen-filled architectures displace nitrogen designs as CATL and BYD battery packs exceed 800V operating thresholds. |
| Solid-State Switching R&D Investment | Silicon carbide development targets premium automotive segments where sub-millisecond switching eliminates mechanical wear. |
| Multi-Jurisdiction Certification Acceleration | Compressed UL 508, IEC 60947, and GB alignment timelines secure platform launches across Chinese, German, and United States markets. |
| Offshore Wind Converter Qualification | Marine-grade sealing certifications open utility-scale North Sea and East Asian installations to new supplier entry. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with hermetic sealing technicians, battery pack procurement managers at CATL and BYD, railway certification specialists at Schaltbau, and ceramic-to-metal feedthrough manufacturing engineers; alongside secondary validation through IEC 60947 revision documentation, UL 508 standard filings, MIIT GB/T battery safety submissions, and customs trade data for silver-copper alloy imports. Bottom-up triangulation across contactor unit shipments and top-down reconciliation against EV battery gigafactory capacity announcements anchored volume estimates.
Forecast inputs incorporate product type segmentation across electromechanical, solid-state, relay, and miniature formats; end-user demand from automotive, renewable energy, industrial equipment, and railway applications; and material specifications spanning plastic, metal, and composite housings. CAGRs derive from regression analysis of historical procurement patterns against battery electric vehicle production trajectories and offshore wind installation pipelines across the projection horizon. Hydrogen dielectric adoption curves and solid-state switching cost reduction trajectories constitute critical industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in precious metal prices, semiconductor equipment lead times, or EV battery gigafactory construction schedules would shift the trajectory. Forecasts reflect documented assumptions regarding IEC revision cycle timing, REACH substance restriction implementation, and automotive OEM platform standardization patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Asia-Pacific Circuit Breakers Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
Electric Wall Heaters Market