
 Global Busbar Market | 2026-2036
Global Busbar Market Size, Share, and Industry Trends Forecast 2026-2036
Global Busbar Market Analysis
Chinese busbar foundry output is decoupling from traditional grid build cycles as renewable energy and data center orders reshape order books. ABB leverages vertical integration from copper refining to laminated busbar assembly across European industrial sites. Siemens sustains technology leadership in gas-insulated busbar systems for high-voltage substations. Chint Group anchors its position through cost-optimized aluminum busbar production serving utility-scale solar farms across Asia.
A busbar is a metallic conductor—typically copper or aluminum with purity grades exceeding 99%—engineered to distribute substantial electrical current across switchgear, transformers, and distribution panels through welded or bolted junctions. Copper busbars dominate power distribution applications where conductivity losses must stay below 0.5% across transmission distances, while aluminum variants penetrate renewable energy installations where weight reduction and material cost control outweigh efficiency premiums. Flexible busbars are capturing margin pools in data center white space deployments where thermal cycling and vibration tolerance exceed rigid conductor performance. Tubular busbars occupy a mature niche in high-current industrial automation bus systems where corona discharge suppression governs specification.
China's MEE enforces GB standards on conductor efficiency in grid-connected renewable projects, directly shaping aluminum busbar alloy specifications. The EU Green Deal and F-Gas Regulation are redirecting utility procurement toward low-loss copper busbars in substation modernization programs. India's CEA mandates localized content thresholds under PLI scheme guidelines for transmission infrastructure. Stakeholders must monitor how evolving efficiency standards across these three regulatory jurisdictions reshape material substitution timelines and certification requirements for cross-border project bids.
Market Dynamics
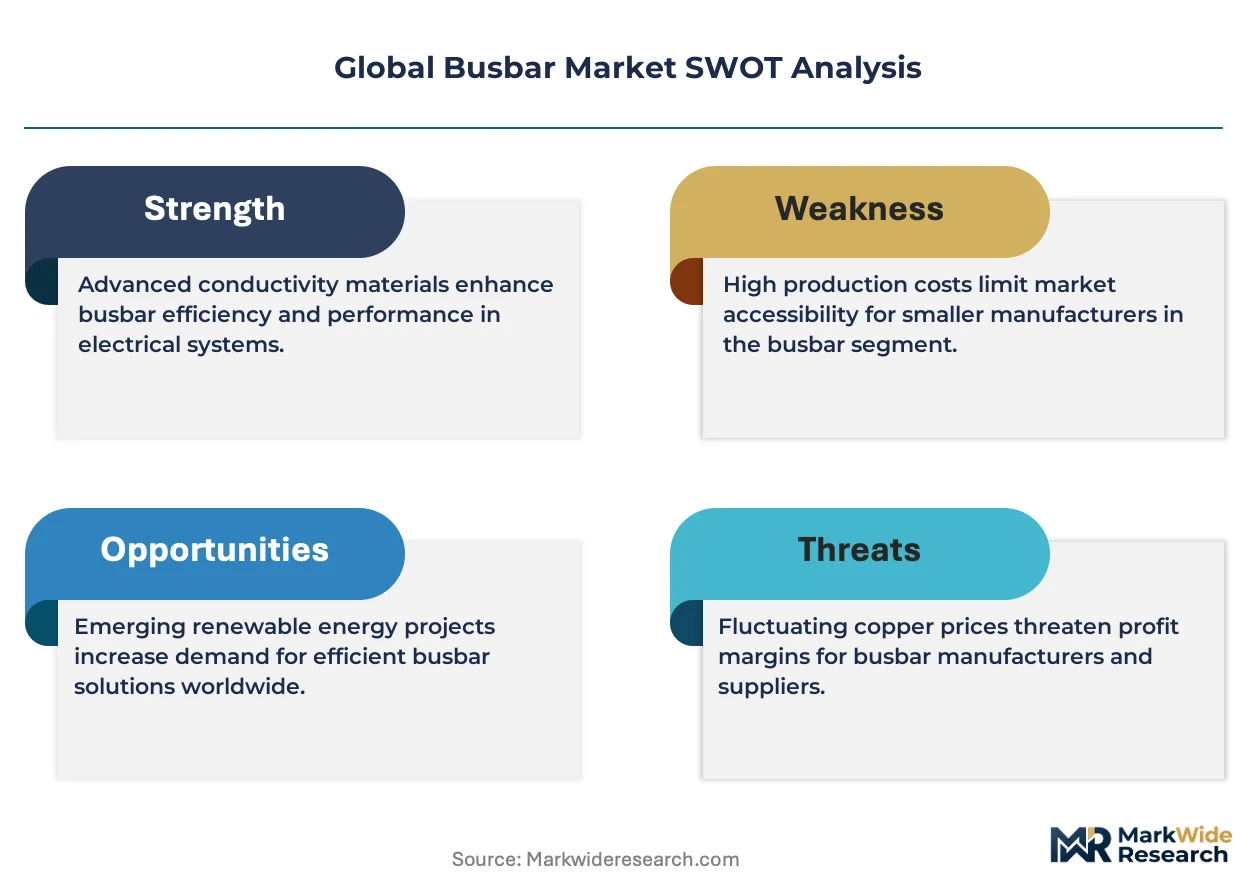
Copper price volatility above historical baselines is forcing procurement teams to rebalance conductor specifications across renewable and data center buildouts, compressing traditional material preference cycles and accelerating aluminum alloy qualification programs.
Growth Catalysts
- Data center power density:Hyperscale operators are specifying laminated copper busbars for 50kW-plus rack configurations, pulling demand from conventional cable distribution systems.
- India's PLI scheme:Domestic manufacturing incentives under CEA guidelines are localizing busbar supply chains for solar and EV charging infrastructure deployment.
- GB standards enforcement:China's MEE conductor efficiency mandates are redirecting utility-scale renewable procurement toward certified aluminum alloy specifications.
Market Restraints
- Copper concentrate supply:Chilean and Peruvian mine output constraints are transmitting price instability directly into busbar fabrication cost structures.
- Technical conductivity ceiling:Aluminum busbars face permanent efficiency penalties in high-current applications where copper maintains mandatory sub-0.5% loss thresholds.
- REACH compliance burden:European surface treatment chemical restrictions are extending certification timelines for laminated busbar assemblies.
Strategic Opportunities
- Flexible busbar white space:Data center white space deployments are creating demand for vibration-tolerant conductor configurations in hyperscale facilities.
- EU F-Gas Regulation:Gas-insulated switchgear phase-down mandates are redirecting substation investment toward solid-dielectric busbar systems.
- Modular fabrication:Prefabricated electrical skids are opening direct OEM channels that bypass traditional distribution hierarchies.
Industry Challenges
- Welding technician scarcity:Ultrasonic and friction stir welding specializations required for laminated busbar production are concentrated among a limited pool of certified operators.
- Cross-border certification lag:GB standard compliance for Chinese projects does not reciprocate automatically with IEC certification for Middle Eastern or African bids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Busbar Market |
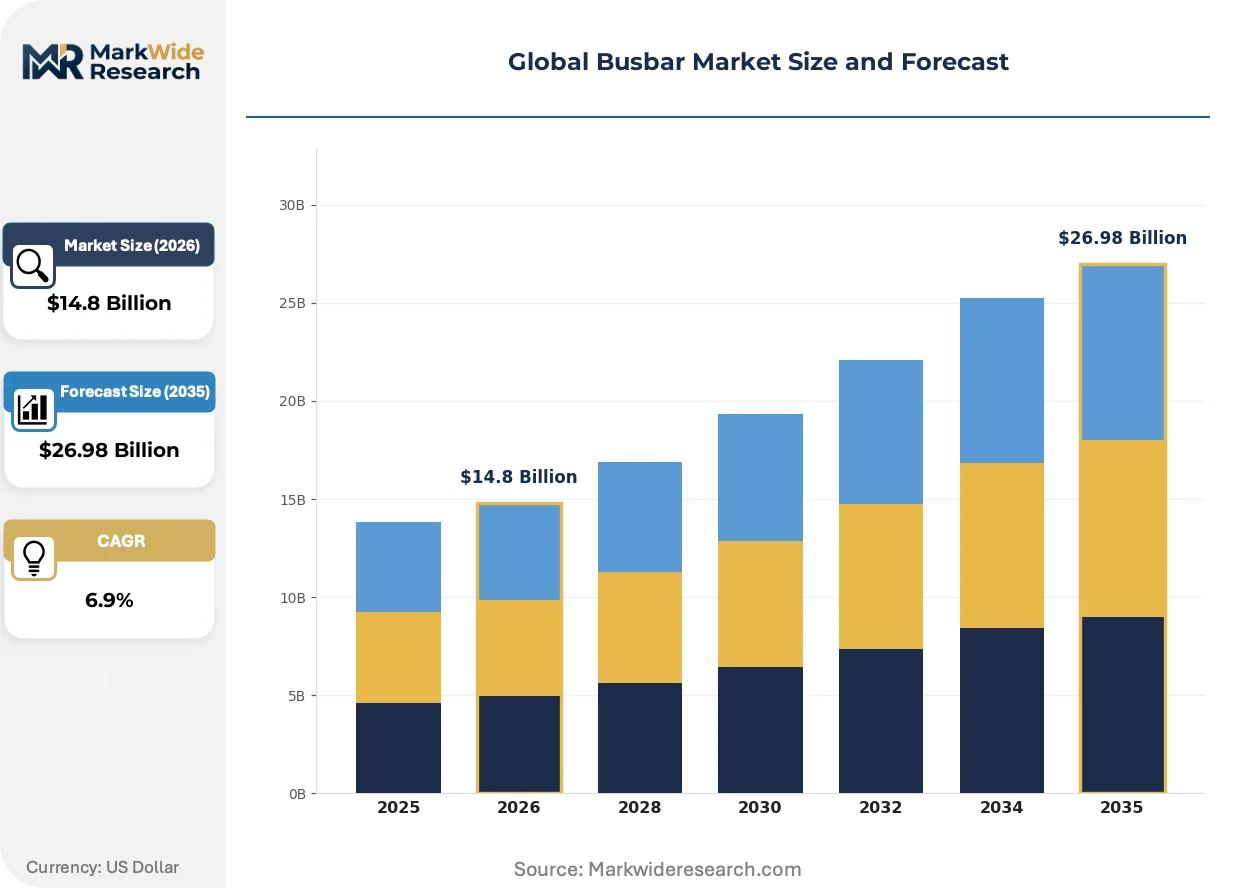
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Busbars, Tubular Busbars, Rigid Busbars, Flexible Busbars Material: Copper, Aluminum, Alloy, Composite Application: Power Distribution, Renewable Energy, Industrial Automation, Data Centers End User: Utilities, Commercial, Residential, Industrial |
| Companies Covered | Eaton Corporation, Legrand, ABB, TE Connectivity, GE, Schneider Electric, Mersen, Chint Group, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Busbar Market Emerging Trajectories
Material science advances and procurement model compression are restructuring how conductor systems are specified, fabricated, and deployed across power infrastructure verticals.
Laminated flexible busbars are absorbing thermal cycling stress in data center environments where rigid conductors fail under vibration and expansion loads. Hyperscale operators in Northern Virginia and Frankfurt are specifying these configurations for 400V-plus distribution zones. The technology is absorbing margin pools previously captured by conventional cable tray and lug assembly suppliers.
China's MEE is enforcing GB/T 5585 efficiency thresholds on grid-connected solar and wind projects, directly shaping aluminum alloy composition requirements for domestic busbar orders. Foundries are reformulating 6101 and 6063 alloys to meet conductivity benchmarks while maintaining cost positioning against copper alternatives. Utility EPCs are responding by pre-qualifying dual-certified suppliers capable of bridging GB and IEC documentation.
Buyers are consolidating vendor relationships around vertically integrated producers capable of delivering conductor, insulation, and termination hardware as unified skids. This pattern is displacing component-level procurement through electrical distributors in European industrial automation and Middle Eastern utility sectors. Contractors in Saudi Arabia and the UAE are now specifying skid-mounted substation packages that compress installation schedules and reduce interface risk.
Global Busbar Market Segmentation
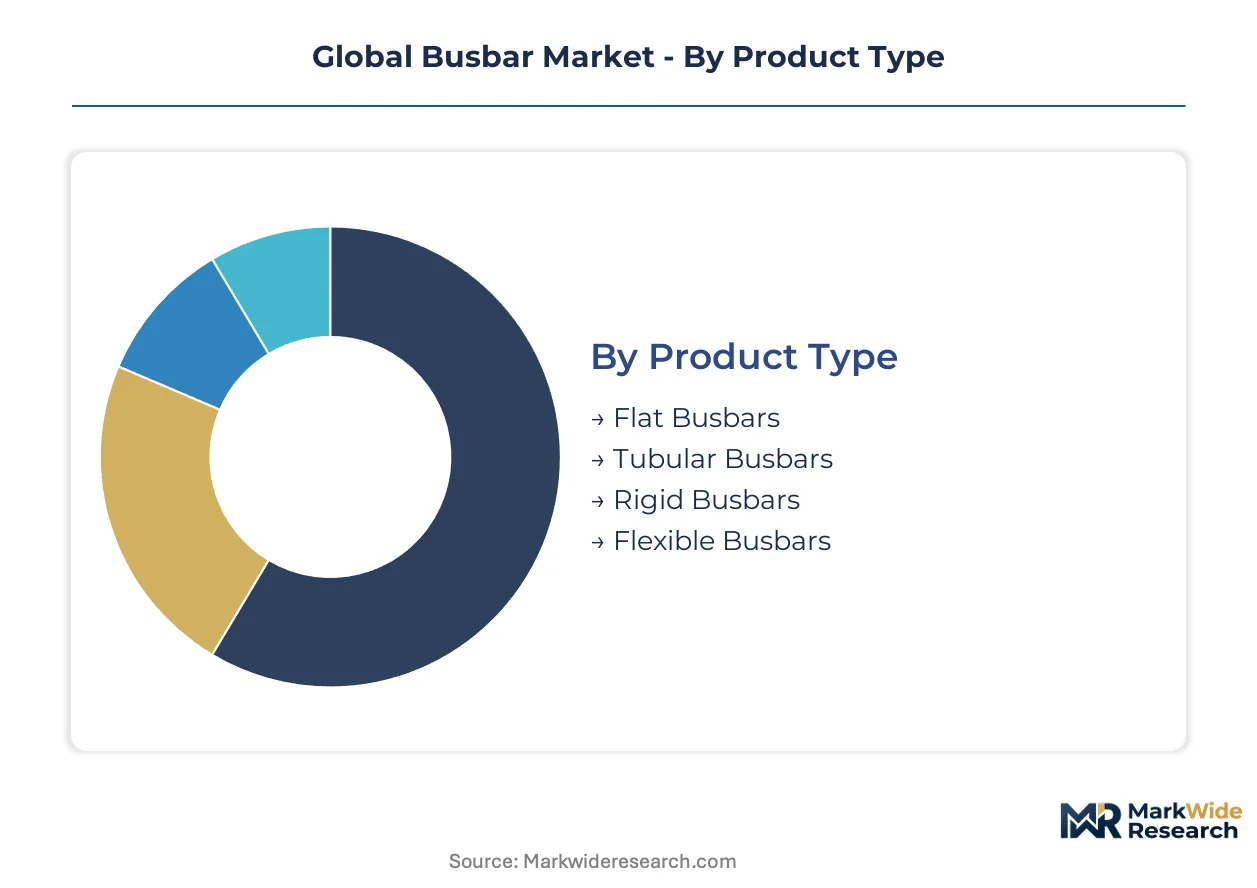
Busbar specification varies dramatically across voltage classes and thermal environments. Procurement teams segment by conductor geometry, alloy composition, and installation context to match electrical performance with mechanical constraints.
Product Type:
Capital intensity peaks in laminated flexible configurations requiring precision welding and polymer interleaving, while rigid extrusions demand heavy pressing equipment but simpler tooling.
- Flat Busbars:Rectangular copper or aluminum extrusions dominate switchgear and panelboard installations where surface area maximizes heat dissipation. Data center operators in Northern Virginia and Frankfurt specify these for 400V distribution zones where space constraints favor planar conductor geometry over cable alternatives.
- Tubular Busbars:Hollow cylindrical conductors suppress corona discharge in high-voltage substations above 132kV. Siemens and ABB deploy these configurations in gas-insulated switchgear across European utility modernization programs constrained by EU F-Gas Regulation phase-down timelines.
- Rigid Busbars:Solid bar stock serves industrial automation bus systems with fixed mounting requirements.
- Flexible Busbars:Laminated copper layers with polymer insulation absorb thermal cycling in vibration-prone environments.
Most installed capacity flows through Flat Busbars. Expansion is steepest in Flexible Busbars.
Material:
Raw material sourcing strategy divides the supply base between captive copper refiners and aluminum alloy importers.
- Copper:Electrolytic tough pitch and oxygen-free grades exceed conductivity thresholds for applications where transmission losses must stay below mandatory limits. Chilean concentrate supply constraints are transmitting price volatility directly into fabrication cost structures, forcing procurement teams toward longer-term offtake agreements.
- Aluminum:6101 and 6063 alloys penetrate utility-scale solar and wind installations where weight reduction offsets efficiency penalties. China's MEE enforces GB/T 5585 conductivity benchmarks that foundries must meet through precise magnesium and silicon content control.
- Alloy:Copper-aluminum bimetallic combinations bridge conductivity and cost requirements in select industrial applications.
- Composite:Carbon fiber reinforced polymer cores with conductive cladding address niche aerospace and marine weight-critical installations.
Copper commands the highest unit margins. Aluminum is gaining share fastest in renewable energy procurement.
Application:
Customer technical requirements stratify across voltage tolerance, thermal cycling frequency, and fault current withstand.
- Power Distribution:Utility substations and switchgear assemblies specify rigid copper busbars for 11kV through 400kV infrastructure. India's CEA mandates localized content thresholds under PLI scheme guidelines, redirecting domestic foundry output toward transmission infrastructure bids.
- Renewable Energy:Solar farm combiner boxes and wind turbine nacelles favor aluminum conductors where material cost control outweighs efficiency premiums. China's dual carbon goals are accelerating aluminum substitution in utility-scale projects governed by GB standards.
- Industrial Automation:Motor control centers and assembly line power distribution require corrosion-resistant surface treatments.
- Data Centers:Hyperscale rack power distribution above 50kW per cabinet pulls demand toward laminated copper flexible configurations.
Power Distribution absorbs the largest project volumes. Data Centers are expanding most quickly as rack densities climb.
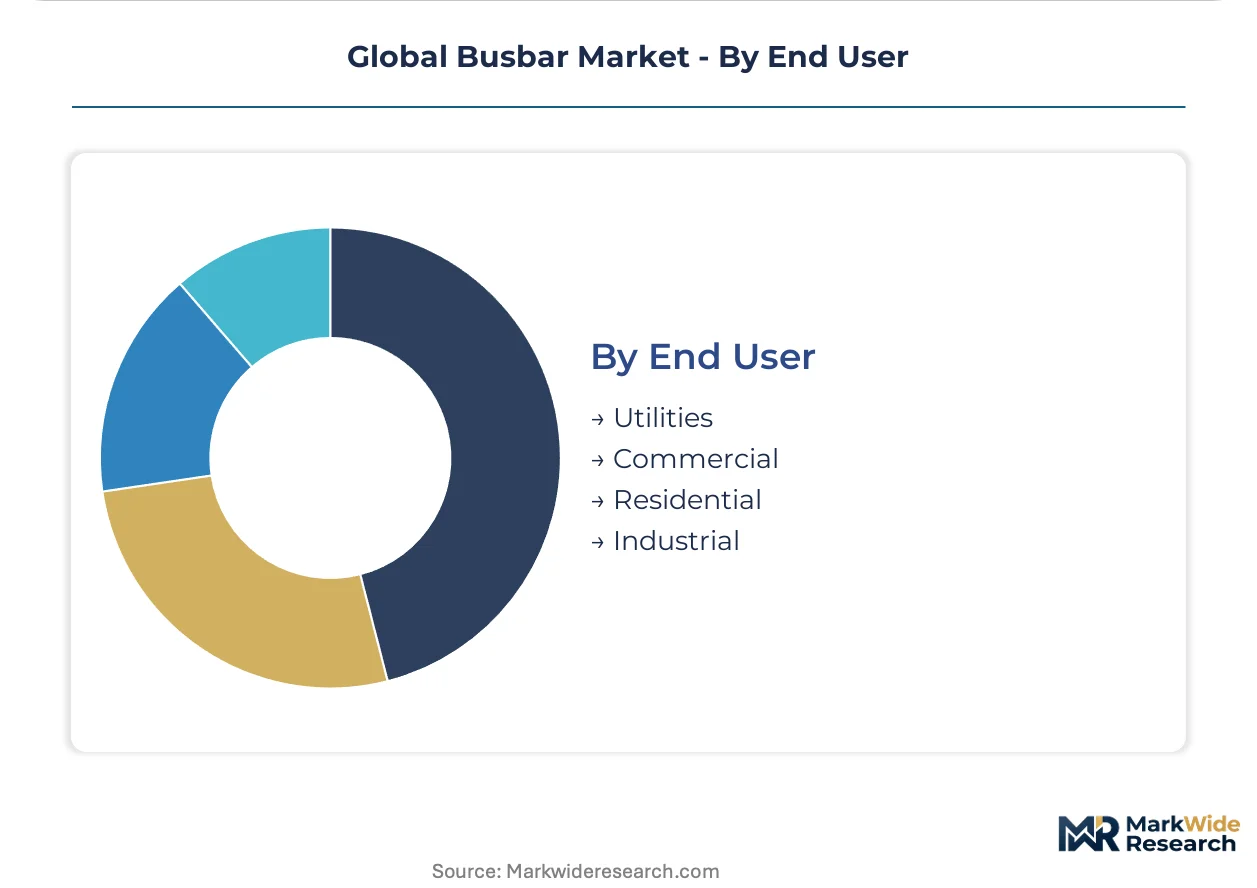
End User:
Procurement sophistication varies from centralized utility engineering departments to fragmented commercial electrical contractors.
- Utilities:National grid operators and regional distribution companies specify IEC or GB certified busbar systems for substation buildouts. Saudi Arabia and UAE contractors are consolidating vendor relationships around skid-mounted packages that compress installation schedules.
- Commercial:Office complexes, retail centers, and healthcare facilities source through electrical distributors with limited technical specification involvement.
- Residential:Multi-unit dwelling panelboards represent a price-sensitive segment with minimal differentiation.
- Industrial:Manufacturing plants and processing facilities demand customized conductor configurations for heavy motor loads.
Utilities represent the most concentrated procurement volume. Industrial end users are diversifying fastest into modular fabrication channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting busbar fabrication capacity toward jurisdictions with lower compliance burdens and stronger raw material access. Chinese foundries exploit GB standard alignment with domestic renewable procurement, while Indian manufacturers leverage PLI scheme subsidies to capture solar and EV charging infrastructure orders.
China
Dual carbon goals and MEE-enforced GB/T 5585 standards are accelerating aluminum busbar substitution in utility-scale solar and wind projects. Yangtze River Delta foundries in Jiangsu and Zhejiang provinces dominate 6101 and 6063 alloy production for certified renewable energy conductors. Shanghai-based EPCs now require dual GB-IEC documentation from suppliers bidding on Belt and Road transmission projects.
India
CEA-mandated localized content thresholds under PLI scheme guidelines are pulling busbar manufacturing capacity toward domestic solar farm and EV charging infrastructure deployment. Gujarat and Maharashtra industrial corridors host expanding copper and aluminum extrusion capacity serving transmission infrastructure bids. Domestic foundries in Pune and Ahmedabad are qualifying for utility-scale renewable project supplier lists previously dominated by imports.
Germany
EU F-Gas Regulation phase-down mandates are redirecting substation investment toward solid-dielectric and gas-insulated busbar systems. Bavaria and North Rhine-Westphalia anchor industrial demand from automotive electrification and automation bus retrofits. Siemens and ABB maintain fabrication and assembly operations in Nuremberg and Frankfurt serving European utility modernization programs.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth is pulling laminated copper busbar demand for 50kW-plus rack configurations. FERC grid interconnection standards shape conductor specifications for utility-scale solar and battery storage projects. Domestic fabricators face copper concentrate price volatility transmitted from Chilean and Peruvian supply constraints.
Saudi Arabia
NEOM and Red Sea Project infrastructure buildouts are consolidating procurement around skid-mounted substation packages compressing installation schedules. Contractors in Riyadh and the Eastern Province specify IEC-certified busbar systems for 132kV-plus transmission infrastructure. SFDA and national grid operator procurement frameworks favor suppliers delivering unified conductor, insulation, and termination hardware.
Global Busbar Market Vendor Landscape
European producers anchor the premium-tier segment through captive refining and precision welding capabilities; Chinese fabricators hold cost-optimized volume positions in aluminum alloy production. The supply base stratifies across three archetypes: vertically integrated electrical conglomerates, specialized conductor foundries, and modular skid packagers. Capacity expansion and backward integration into copper refining represent the dominant competitive moves as raw material volatility compresses margins.
Within the integrated electrical systems tier, Eaton Corporation and Schneider Electric exemplify full-spectrum power distribution portfolios spanning switchgear, busbar, and control systems. ABB occupies a position bridging European industrial automation demand with Middle Eastern utility infrastructure deployment. Chint Group represents the cost-optimized aluminum busbar archetype serving utility-scale solar markets across Asia through GB-standard certified production.
| Leading Market Players |
|---|
| Eaton Corporation |
| Legrand |
| ABB |
| TE Connectivity |
| GE |
| Schneider Electric |
| Mersen |
| Chint Group |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Copper concentrate costs transmit directly from Chilean and Peruvian mine output through laminated busbar fabrication tiers, with procurement teams in Northern Virginia and Frankfurt data centers absorbing volatility through long-term offtake structures while utility-scale solar developers in Gujarat and Maharashtra shift alloy specifications to escape price spikes.
Pricing Analysis
Distributor margin compression runs through European industrial automation channels where electrical wholesalers face displacement from direct OEM skid procurement. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified laminated configurations from GB-standard aluminum extrusions and uncertified rigid bar stock. Pricing pressure stems from Chilean concentrate supply constraints transmitting cost instability into copper fabrication. Utility procurement teams in Saudi Arabia and the UAE exhibit lowest price sensitivity due to consolidated skid-package specifications, while commercial electrical contractors in multi-unit residential construction remain most exposed to spot aluminum volatility.
Supply Chain Analysis
Welding technician scarcity concentrates in Jiangsu and Zhejiang provinces where ultrasonic and friction stir specializations required for laminated busbar production remain limited to certified operator pools. Supply concentrates in China, India, and Germany for extrusion and assembly capacity. Raw material flows draw from Chilean copper concentrate, Chinese 6101 and 6063 aluminum alloy ingot, and European polymer interleaving films. Single-source vulnerability sits with Chilean mine output disruptions propagating through copper refining tiers. Distribution runs through direct OEM channels for skid-mounted substation packages in Middle Eastern utility sectors, bypassing traditional electrical distributor hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Busbar Market functions as a regulatory compounder where China's MEE-enforced GB/T 5585 efficiency thresholds and India's CEA-mandated PLI localization are restructuring procurement specifications across utility-scale renewable deployment.
For Market Incumbents: Anchor technology leadership in gas-insulated and solid-dielectric systems as EU F-Gas Regulation phase-down mandates redirect substation investment. Defend against aluminum alloy substitution by locking long-term copper concentrate offtake agreements with Chilean and Peruvian suppliers. Invest in dual GB-IEC certification capabilities to capture Belt and Road transmission project bids where Shanghai-based EPCs now require unified documentation. For New Entrants and Emerging Players: India's PLI scheme opens a window for domestic manufacturing qualification in Gujarat and Maharashtra industrial corridors where CEA-mandated localized content thresholds are displacing import-dependent supply chains. Target data center flexible busbar white space in Northern Virginia and Frankfurt where vibration-tolerant laminated configurations absorb margin pools from conventional cable distributors. Pursue skid-mounted packaging partnerships with Saudi and UAE contractors compressing installation schedules for NEOM infrastructure buildouts. For Investors and Strategic Acquirers: Consolidation pressure builds where welding technician scarcity and cross-border certification lag fragment production capacity among sub-scale regional fabricators. Long-term viability centers on vertical integration from copper refining through precision welding assembly, with acquisition value accruing to dual-certified suppliers bridging GB and IEC standards. Watch for aluminum alloy conductivity breakthroughs in 6101 and 6063 formulations as inflection signals threatening copper's high-current efficiency premium.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Refining | Captive concentrate offtake from Chilean and Peruvian sources insulates fabrication margins from spot volatility. |
| Dual GB-IEC Certification Investment | Shanghai-based EPCs require unified documentation for Belt and Road transmission project supplier qualification. |
| Flexible Busbar Capacity Expansion | Hyperscale operators in Northern Virginia specify laminated configurations for 50kW-plus rack power distribution. |
| Skid-Mounted Packaging Partnership | Saudi and UAE contractors consolidate procurement around compressed-installation substation packages. |
| Aluminum Alloy Formulation R&D | China's MEE enforces GB/T 5585 conductivity benchmarks reshaping 6101 and 6063 magnesium-silicon content control. |
Methodological Framework
Coverage spans China, India, Germany, the United States, and Saudi Arabia, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged utility planning officers, EPC procurement leads, data center infrastructure directors, busbar fabrication plant managers, and electrical distributor category buyers. Secondary sources included customs and trade flow databases, CEA and MEE regulatory filings, FERC grid interconnection standards documentation, SEC 10-K disclosures from listed electrical conglomerates, and project development databases tracking utility-scale solar and wind deployment. Bottom-up unit economics and top-down market sizing underwent cross-validation to anchor volume and value estimates.
Rate-of-change decomposition separated volume growth from price movement across the projection horizon. Segmentation dimensions modeled include product type, conductor material, voltage class, application vertical, and end-user procurement sophistication. CAGRs derived from fitted growth curves applied to base-year estimates, with industry-specific inputs incorporating copper concentrate price volatility indices, data center rack density trajectories, and renewable energy capacity addition pipelines by geography.
Revisions become necessary when Chilean or Peruvian mine output disruptions exceed baseline assumptions, when China's MEE adjusts GB/T 5585 efficiency thresholds, or when India's PLI scheme localization requirements expand to additional component categories. Forecasts reflect documented assumptions about regulatory stability, raw material supply continuity, and welding technician training pipeline throughput. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Insulator Market
Electrical Equipment
North America Thermal Protector Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
Middle East and Africa Electric Drives Market