
 Industrial Plugs and Sockets Market | 2026-2036
Industrial Plugs and Sockets Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Plugs and Sockets Market Outlook
Specialized electrical distribution channels serving heavy industry is fragmenting as direct procurement from manufacturers displaces traditional wholesale relationships. ABB leverages its integrated automation portfolio to bundle connectivity solutions with motor control systems. Schneider Electric anchors its position through extensive specification engineer relationships that influence project design standards. Mennekes sustains dominance in European industrial connector specifications through deep certification expertise.
Industrial plugs and sockets are electromechanical coupling devices rated for voltages from 110V to 1000V AC, constructed with thermoplastic or metal housings featuring pin-and-sleeve configurations designed to prevent mismating under load. Their primary purpose is to deliver safe, reliable power connections in environments exposed to moisture, dust, vibration, and mechanical impact. Waterproof sockets command premium positioning due to stringent IP67 and IP69K requirements in food processing and offshore applications, while locking connectors capture expanding share in mobile equipment where accidental disconnection risks catastrophic downtime. Manufacturing facilities represent the most mature application segment, with margin pools shifting toward modular quick-connect systems that reduce installation labor.
IEC 60309, NEMA standards, and the EU's CE marking framework collectively dictate housing materials, contact geometries, and ingress protection thresholds that determine market access across jurisdictions. OSHA electrical safety regulations in the United States and the EU's Low Voltage Directive enforce periodic inspection regimes that accelerate replacement cycles in aging industrial infrastructure. Stakeholders must monitor evolving harmonization gaps between regional certification requirements as modular factory designs spread across multinational footprints.
Market Dynamics
Electrification mandates in heavy extractive industries are forcing wholesale replacement of legacy diesel infrastructure with shore-powered mobile equipment, compressing replacement cycles and demanding higher ingress protection ratings across the installed base.
Growth Catalysts
- IEC 60309 Standard Revisions:Updated ingress protection thresholds are compelling facility managers to upgrade aging connector inventories ahead of scheduled maintenance windows.
- Chilean Mining Electrification:State-owned copper operators are replacing diesel haul trucks with tethered electric variants requiring high-amperage locking connectors rated for 1000V AC.
- Factory Automation Retrofits:Germany's industrial corridor is seeing concentrated demand for modular quick-connect systems that slash installation labor in brownfield automation deployments.
Market Restraints
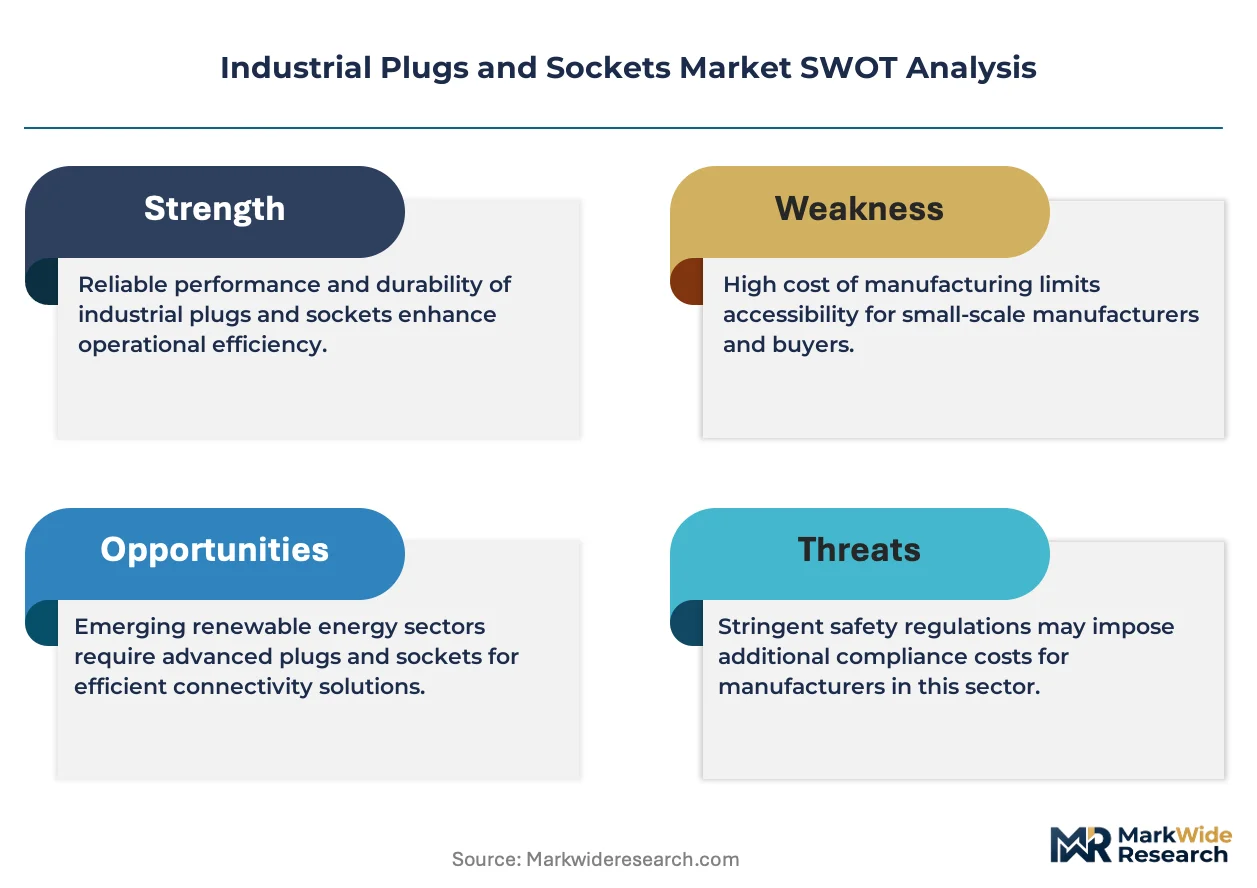
- Copper Price Volatility:Contact material costs fluctuate with commodity markets, squeezing margin predictability for manufacturers of high-amperage industrial connectors.
- Specialized Certification Concentration:European notified body capacity for IP69K marine and food-grade validation creates bottlenecks extending lead times by months.
- Wireless Power Transmission:Inductive charging pilots in automated guided vehicles threaten to displace physical connectors in controlled indoor material handling environments.
Strategic Opportunities
- Australian Mining Expansion:Iron ore and lithium extraction operations in Western Australia are accelerating electrification programs with government-backed decarbonization incentives.
- Offshore Wind Service Vessels:Turbine maintenance fleets require IP67-rated connectors capable of withstanding salt spray and dynamic positioning vibration.
- CE Marking Harmonization Gaps:Divergent national interpretations of the EU's Low Voltage Directive create arbitrage opportunities for certification-savvy manufacturers to capture cross-border project specifications.
Industry Challenges
- Qualified Electrician Scarcity:Installation of high-voltage industrial connectors demands certified technicians, with labor shortages in North American manufacturing hubs extending project timelines.
- Legacy System Integration:Retrofitting IEC 60309-compliant connectors into aging NEMA-standard infrastructure requires custom adapter fabrication and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Plugs and Sockets Market |
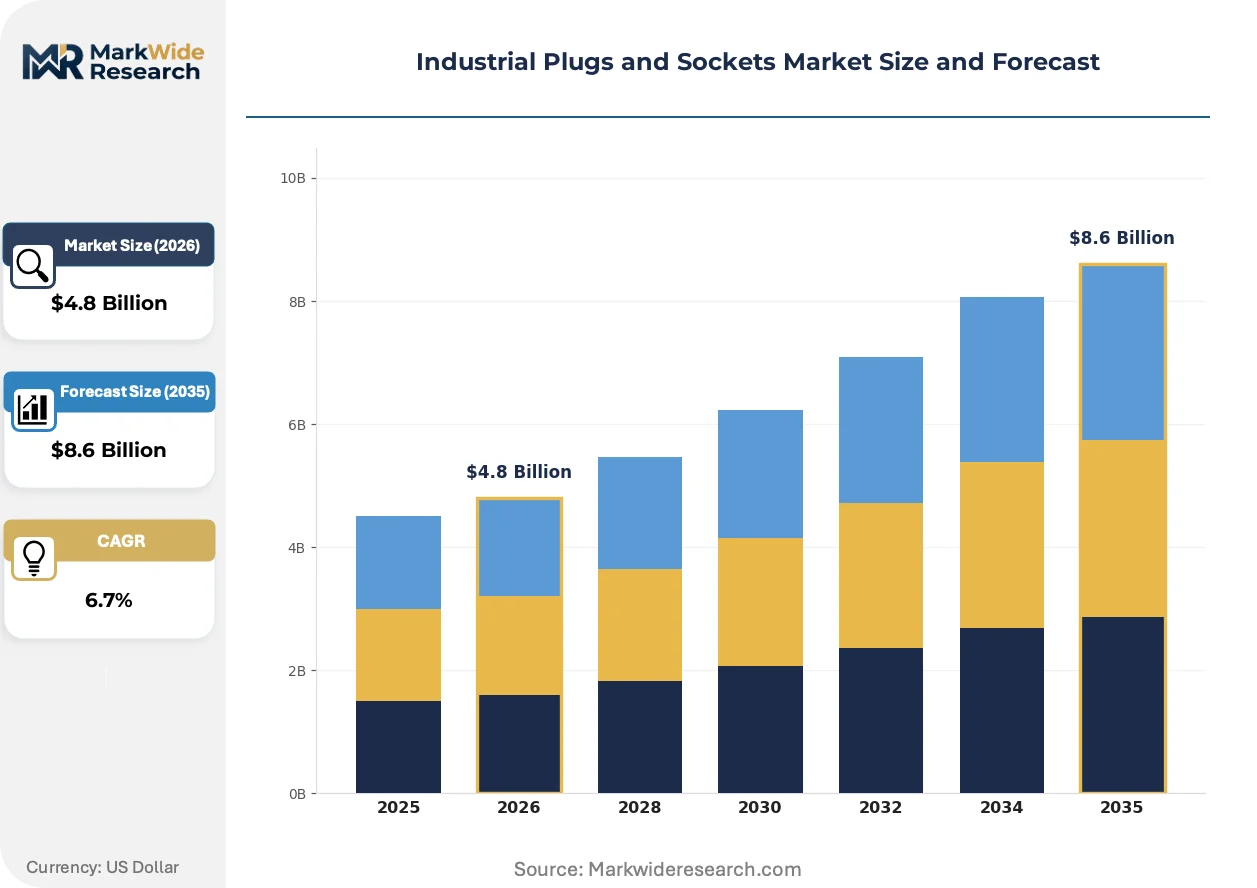
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Plugs, Waterproof Sockets, Industrial Connectors, Locking Connectors Application: Manufacturing Facilities, Construction Sites, Mining Operations, Agricultural Equipment Installation Type: Wall-Mounted, Portable, Flush-Mounted, Surface-Mounted Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | Amphenol Corporation, ABB, Schneider Electric, Legrand, Emerson Electric, Eaton, Siemens, Mennekes, Hubbell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Plugs and Sockets Market Strategic Shifts
Connector architecture is bifurcating between ultra-ruggedized metal housings for extreme environments and lightweight thermoplastic designs for mobile equipment, with digital monitoring capabilities embedding across both paths.
Composite polymer housings reinforced with glass fiber are hybridizing traditional metal connector durability with thermoplastic weight advantages. Offshore oil platform operators in the North Sea are specifying these hybrid designs for helicopter refueling and subsea equipment power drops. The technology is hybridizing procurement criteria by collapsing the historical trade-off between impact resistance and installation ergonomics.
REACH substance restrictions on halogenated flame retardants are forcing reformulation of housing materials across the European supply base. Manufacturers must validate alternative chemistries through extended thermal cycling tests before CE marking approval. Food processing facilities in Denmark and the Netherlands are experiencing the tightest compliance timelines due to concurrent IP69K sanitation requirements.
Direct procurement from original equipment manufacturers is displacing traditional electrical wholesale channels for large capital projects. Mining and energy sector engineering-procurement-construction firms now maintain approved vendor lists that bypass distributor markups. This pattern is most pronounced in Chile and Australia where multinational resource operators have centralized supply chain governance.
Industrial Plugs and Sockets Market Segmentation
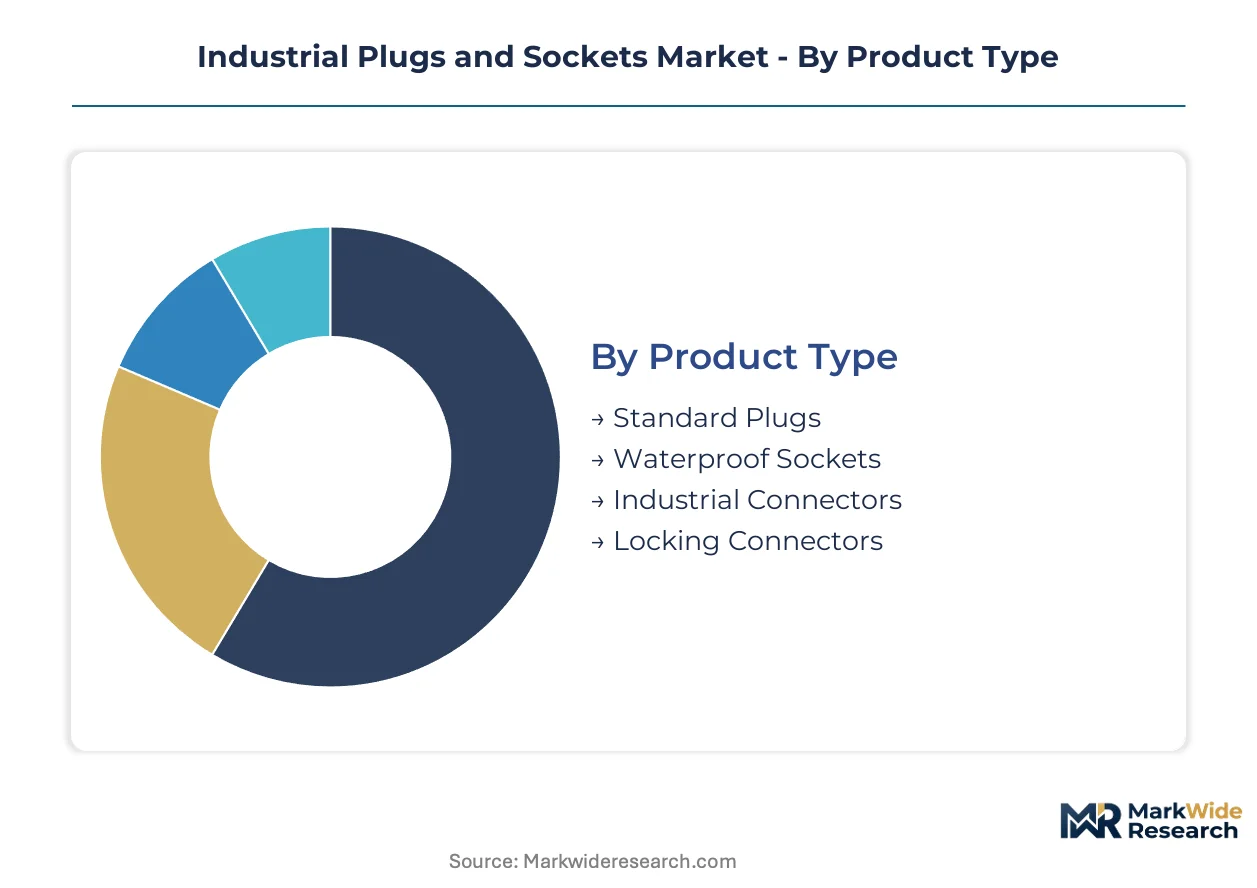
Segmentation in industrial plugs and sockets reveals distinct replacement rhythms across product architectures, with cycle times ranging from annual safety inspections to decade-long infrastructure overhauls. Understanding these temporal patterns helps suppliers align inventory and certification investments with actual demand velocity.
Product Type:
Cycle times vary dramatically by product architecture, with mobile equipment connectors turning over every 2-3 years under mechanical stress while fixed infrastructure endures 15-20 year service lives.
- Standard Plugs:Basic pin-and-sleeve configurations in thermoplastic housings dominate brownfield replacement volumes. Manufacturing facilities in Germany's industrial corridor consume these at steady rates driven by OSHA-mandated inspection regimes that flag wear before failure.
- Waterproof Sockets:IP67 and IP69K-rated housings with sealed gaskets command extended lead times due to ECHA REACH compliance testing for halogen-free flame retardants. Food processing plants in Denmark and offshore platforms in the North Sea specify these for washdown and salt spray exposure, compressing replacement cycles to 5-7 years in corrosive environments.
- Industrial Connectors:High-amperage modular systems rated to 1000V AC serve Chilean copper mining electrification programs replacing diesel haul trucks.
- Locking Connectors:Twist-lock or lever-actuated designs prevent accidental disconnection in mobile equipment; Australian iron ore operations specify these for tethered electric vehicle fleets.
Standard plugs anchor the volume base while waterproof sockets gain share at the steepest rate.
Application:
Margin concentration follows application risk profiles, with hazardous environment deployments capturing premium pricing over controlled indoor settings.
- Manufacturing Facilities:Factory automation retrofits in Germany drive modular quick-connect adoption to reduce installation labor. Brownfield sites balance legacy NEMA infrastructure migration against IEC 60309 compliance deadlines.
- Mining Operations:Chilean state-owned copper operators and Western Australian lithium extractors are accelerating electrification with government-backed decarbonization incentives. Tethered electric haul trucks require high-amperage locking connectors with 1000V AC ratings and IP67 ingress protection.
- Construction Sites:Temporary power distribution demands portable, impact-resistant housings; OSHA electrical safety regulations enforce periodic inspection cycles.
- Agricultural Equipment:Mobile machinery in exposed environments favors thermoplastic housings for weight reduction; moisture and vibration drive replacement demand.
Manufacturing facilities generate the steadiest replacement demand while mining operations show the most rapid expansion trajectory.
Installation Type:
Installation modality determines labor cost exposure and field service requirements, with permanent mounting offering lower total cost of ownership despite higher upfront expenditure.
- Wall-Mounted:Fixed bracket installations in permanent infrastructure dominate manufacturing and mining site builds. German factory automation projects specify these for centralized power distribution panels.
- Portable:Cable-mounted connectors with strain relief serve construction and maintenance operations where power sources relocate frequently. Mobile equipment electrification in Australian mining favors this flexibility.
- Flush-Mounted:Recessed housings protect connectors from mechanical impact in high-traffic areas; food processing facilities specify these for sanitation compliance.
- Surface-Mounted:Exposed installations on conduit or cable tray suit rapid deployment in temporary or expanding facilities.
Wall-mounted installations retain the largest installed base while portable configurations are climbing the fastest as mobile electrification spreads.
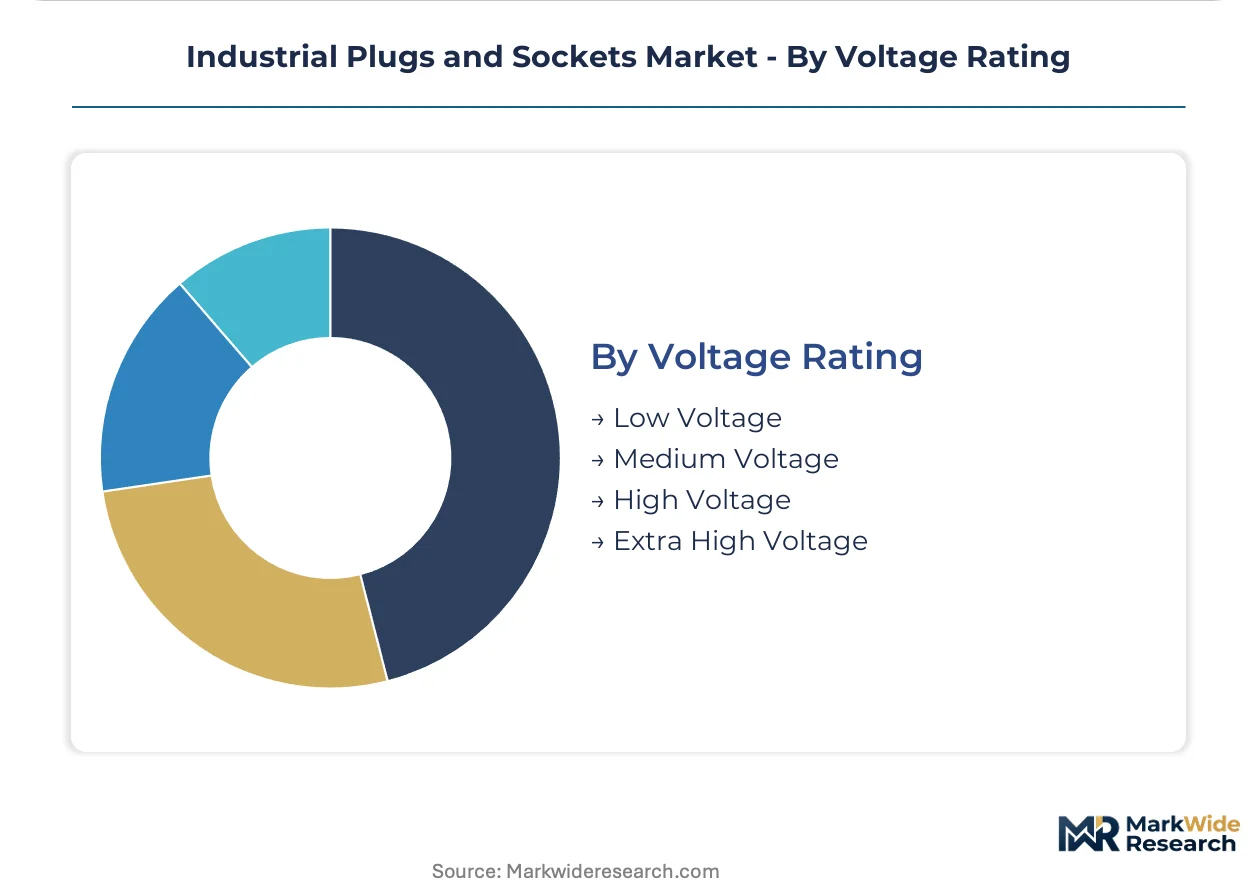
Voltage Rating:
Certification complexity escalates with voltage tier, with high and extra-high voltage segments requiring specialized notified body validation that extends lead times.
- Low Voltage:110V-240V AC applications dominate construction and light industrial settings. Standard IEC 60309 compliance applies; replacement cycles align with general maintenance windows.
- Medium Voltage:241V-600V AC serves manufacturing automation and agricultural machinery. German industrial corridor retrofits concentrate demand here.
- High Voltage:601V-1000V AC ratings are mandatory for Chilean and Australian mining electrification programs. ECHA REACH substance restrictions and IP69K validation create European supply bottlenecks.
- Extra High Voltage:Above 1000V AC applications remain niche, confined to heavy infrastructure and utility interconnections with specialized safety interlocks.
Low voltage ratings sustain the broadest installed base while high voltage segments are expanding most quickly on mining electrification momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container terminal electrification underwrites Germany's central role in European industrial power distribution infrastructure. Copper concentrate export corridors through Antofagasta and Escondida anchor Chile's mining electrification momentum. The Pilbara rail network's expansion of autonomous haulage systems drives connector demand across Western Australia's iron ore belt.
Germany
Factory automation retrofits in the Ruhr industrial corridor and Bavarian manufacturing belt concentrate demand for modular quick-connect systems. ECHA REACH substance restrictions on halogenated flame retardants force housing material reformulations ahead of CE marking deadlines. Stuttgart's automotive component suppliers specify IP67-rated connectors for washdown-compliant production lines.
Chile
State-owned Codelco copper operations are replacing diesel haul trucks with tethered electric variants requiring 1000V AC locking connectors. The Ministry of Mining's National Electrification Program accelerates capital allocation toward shore-powered mobile equipment. Antofagasta's Calama mining district hosts concentrated deployment of high-amperage industrial connectors for open-pit extraction.
Australia
Western Australian lithium and iron ore extractors are expanding electrification programs with federal Clean Energy Finance Corporation backing. TGA-equivalent electrical safety inspections enforce replacement cycles for aging connector inventories. The Pilbara's Port Hedland iron ore export hub drives specification of IP69K-rated connectors for salt spray exposure.
United States
OSHA electrical safety regulations mandate periodic inspection regimes that accelerate replacement demand in aging manufacturing infrastructure. The Inflation Reduction Act's domestic content provisions influence procurement patterns for federally funded industrial projects. Houston's petrochemical corridor and Detroit's automotive assembly plants represent concentrated demand pockets for NEMA-to-IEC migration adapters.
China
GB standard harmonization with IEC 60309 frameworks facilitates export-oriented manufacturing of industrial connectors. MIIT industrial upgrading directives push domestic factories toward higher ingress protection ratings in automated production environments. The Yangtze River Delta's Shanghai-Suzhou manufacturing cluster generates sustained demand for medium-voltage quick-connect systems.
Industrial Plugs and Sockets Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the specification chain. The industrial plugs and sockets market structures around three tiers: diversified electrical conglomerates bundling connectivity with automation portfolios, specialized connector manufacturers with deep certification expertise, and regional fabricators serving price-sensitive construction segments. Consolidation pressure concentrates among mid-scale European specialists facing REACH compliance cost escalation. Dominant competitive moves include backward integration into contact material supply chains and strategic partnerships with mining engineering-procurement-construction firms to secure approved vendor list status.
Among diversified electrical conglomerates, ABB and Schneider Electric exemplify platform integrators leveraging automation portfolios to bundle connectivity solutions with motor control systems. Mennekes occupies a position within the specialized certification tier, anchoring European industrial connector specifications through notified body relationships. These three entities represent distinct archetypes: the automation-integrated conglomerate, the specification-influencing electrical giant, and the certification-centric connector specialist.
| Leading Market Players |
|---|
| Amphenol Corporation |
| ABB |
| Schneider Electric |
| Legrand |
| Emerson Electric |
| Eaton |
| Siemens |
| Mennekes |
| Hubbell |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Antwerp-Rotterdam freight corridor's container rate volatility feeds directly into landed cost spreads between German manufacturers and Australian mining sites, compressing margin buffers for mid-tier suppliers while amplifying pricing power among certification-heavy specialists with captive logistics arrangements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies around IP certification grade and volume commitment depth. Premium tiers capture IEC 60309 notified body validation costs and REACH-compliant material premiums, while economy tiers compete on copper contact weight and thermoplastic housing grades. Pricing pressure stems from Chilean and Australian mining procurement teams consolidating approved vendor lists to extract volume discounts. Construction sector buyers exhibit highest price sensitivity due to project-based purchasing with minimal after-service bundling.
Supply Chain Analysis
Export-control restrictions on high-purity copper refining technology limit contact material flows from select smelter jurisdictions into European connector fabrication. Manufacturing concentrates in Germany, China, and Italy, with each hub drawing from distinct copper concentrate sources. Supply chain risk centers on ECHA REACH substance restriction timelines that force unplanned housing material reformulations. Distribution runs through direct OEM procurement channels for mining and energy EPC firms, bypassing traditional electrical wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial plug and socket demand sits in early-cycle expansion as mining electrification mandates force wholesale replacement of legacy diesel infrastructure with shore-powered mobile equipment, accelerating replacement velocities beyond historical maintenance rhythms.
For Market Incumbents: Entrench specification influence through deeper notified body relationships for IP69K marine and food-grade validation, locking in European project design standards ahead of REACH compliance deadlines. Backward integration into halogen-free flame retardant compound supply secures material allocation priority when ECHA restrictions tighten. Wireless power transmission pilots in automated guided vehicles threaten physical connector displacement in controlled indoor environments. For New Entrants and Emerging Players: Southeast Asian manufacturing automation retrofits offer underpenetrated white space with less consolidated procurement governance than German or Australian markets. Target mid-voltage quick-connect systems for factory automation integrators seeking alternatives to incumbent lead times. Partner with regional EPC firms in Indonesia and Vietnam to secure approved vendor list status before direct procurement channels mature. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electrical conglomerates seeking to divest non-core connectivity divisions amid automation portfolio restructuring. Long-term viability hinges on certification asset durability and mining sector relationship depth rather than commodity copper exposure. Watch for IEC 60309 standard revision timing as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Material Supply | Captive copper alloy sourcing insulates margin from LME price swings affecting high-amperage connector production. |
| IP69K Marine Certification Investment | Notified body validation for North Sea offshore wind service vessels opens premium pricing tier in salt-exposure applications. |
| Direct EPC Partnership Program | Approved vendor list status with Chilean and Australian mining engineering-procurement-construction firms displaces distributor channels. |
| Halogen-Free Housing Material Reformulation | REACH-compliant thermoplastic compounds secure CE marking continuity for European food processing and offshore specifications. |
| Modular Quick-Connect Platform Launch | German factory automation retrofits demand reduced installation labor in brownfield IEC 60309 migration projects. |
Study Parameters
The analysis maps waterproof socket, locking connector, and high-amperage industrial connector sub-sectors, each validated through specification engineers at mining EPC firms, plant maintenance directors in German automotive component facilities, and procurement leads at Chilean state-owned copper operators. Primary interview findings triangulate against IEC 60309 standard revision documentation, ECHA REACH substance restriction filings, and Australian Clean Energy Finance Corporation electrification grant disclosures. Bottom-up unit demand estimates from mining fleet electrification programs reconcile with top-down industrial power distribution infrastructure spending patterns.
Assumptions hold copper price bands within historical volatility ranges, mining electrification capital allocation at announced program levels, and REACH compliance timelines per current ECHA consultation drafts across the analysis window. Segmentation modeling incorporates product architecture, voltage rating tier, installation modality, and application risk profile dimensions. CAGRs derive from replacement cycle compression in mobile equipment electrification and infrastructure overhaul velocities in factory automation retrofits. Input sensitivity tests vary mining electrification adoption pace and wireless power transmission displacement thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese manufacturers or accelerated wireless charging adoption by automated guided vehicle fleets would shift outcomes. Material shifts in IEC 60309 ingress protection threshold timing or ECHA substance restriction enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Smart Fan Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market