
 Consumer Electronics High Voltage Electric Capacitor Market | 2026-2036
Consumer Electronics High Voltage Electric Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Electronics High Voltage Electric Capacitor Market Insights
Gaming console power supply design is expanding as a high-volume application for high-voltage electric capacitors. Murata Manufacturing leverages its ceramic dielectric expertise to anchor premium segments in compact console architectures. TDK Corporation sustains R&D intensity in multilayer ceramic formulations for high-ripple current environments. Samsung Electro-Mechanics dominates captive supply chains for Korean consumer hardware OEMs.
Consumer electronics high voltage electric capacitors are passive components engineered to store and release electrical energy at elevated voltages, typically employing ceramic, film, or electrolytic dielectrics with rated withstand thresholds exceeding standard low-voltage counterparts; they stabilize power delivery, filter noise, and protect sensitive semiconductor circuits in compact electronic assemblies. Ceramic capacitors lead unit volume in smartphone and wearable miniaturization due to their favorable volumetric efficiency, while film capacitors command margin pools in gaming console and home automation inverters where thermal endurance and self-healing properties justify premium positioning. Electrolytic variants retain structural importance in audio equipment power supplies where bulk capacitance and cost efficiency outweigh form-factor constraints.
FCC electromagnetic compatibility mandates in the United States shape capacitor selection for RF-sensitive consumer devices, while EU RoHS and REACH frameworks restrict hazardous substances in dielectric formulations and electrode materials. China's SAMR enforces GB standards for component safety certification that gate market access for imported high-voltage capacitors. Japan's METI energy efficiency directives for consumer electronics indirectly tighten requirements for power factor correction components. Stakeholders must monitor evolving substance restrictions and regional certification reciprocity to align sourcing strategies with compliance timelines.
Market Dynamics
Gaming console power supply miniaturization is compressing procurement timelines for high-voltage film capacitors, forcing suppliers to compress lead times while maintaining dielectric withstand ratings under tighter thermal constraints.
Growth Catalysts
- Samsung Electro-Mechanics captive ecosystem:Korean consumer hardware OEMs are consolidating procurement around domestic high-voltage capacitor suppliers, creating pull-through demand for certified components.
- China GB standards tightening:SAMR enforcement of stricter dielectric withstand requirements is accelerating replacement cycles in imported capacitor inventories.
- Gaming console thermal density:Power supply modules in next-generation consoles require high-ripple film capacitors that tolerate elevated operating temperatures without derating.
Market Restraints
- Polypropylene film supply concentration:Biaxially oriented polypropylene dielectric substrate production clusters in Germany and Japan, exposing capacitor manufacturers to input bottlenecks.
- RoHS substance restrictions:ECHA REACH frameworks limit lead-bearing electrode materials and certain flame-retardant epoxy formulations, forcing reformulation costs.
- Aluminum electrolytic substitution ceiling:Ceramic multilayer capacitors above 100nF at 500V+ remain technically constrained, blocking full category displacement.
Strategic Opportunities
- India BIS certification pathway:Underpenetrated consumer electronics manufacturing zones in Tamil Nadu and Karnataka offer first-mover positioning for GB-compliant suppliers.
- GaN power adapter convergence:Gallium nitride switching frequencies above 100kHz create demand for low-ESR high-voltage ceramics in compact charger architectures.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases in manufacturing processes incentivize dry-film capacitor expansion over liquid-impregnated alternatives.
Industry Challenges
- MLCC formulation expertise scarcity:Multilayer ceramic high-voltage dielectric engineering requires rare combinations of materials science and sintering process control.
- Dual certification timeline compression:Simaneous GB mark and UL recognition for gaming console power modules extends qualification cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Electronics High Voltage Electric Capacitor Market |
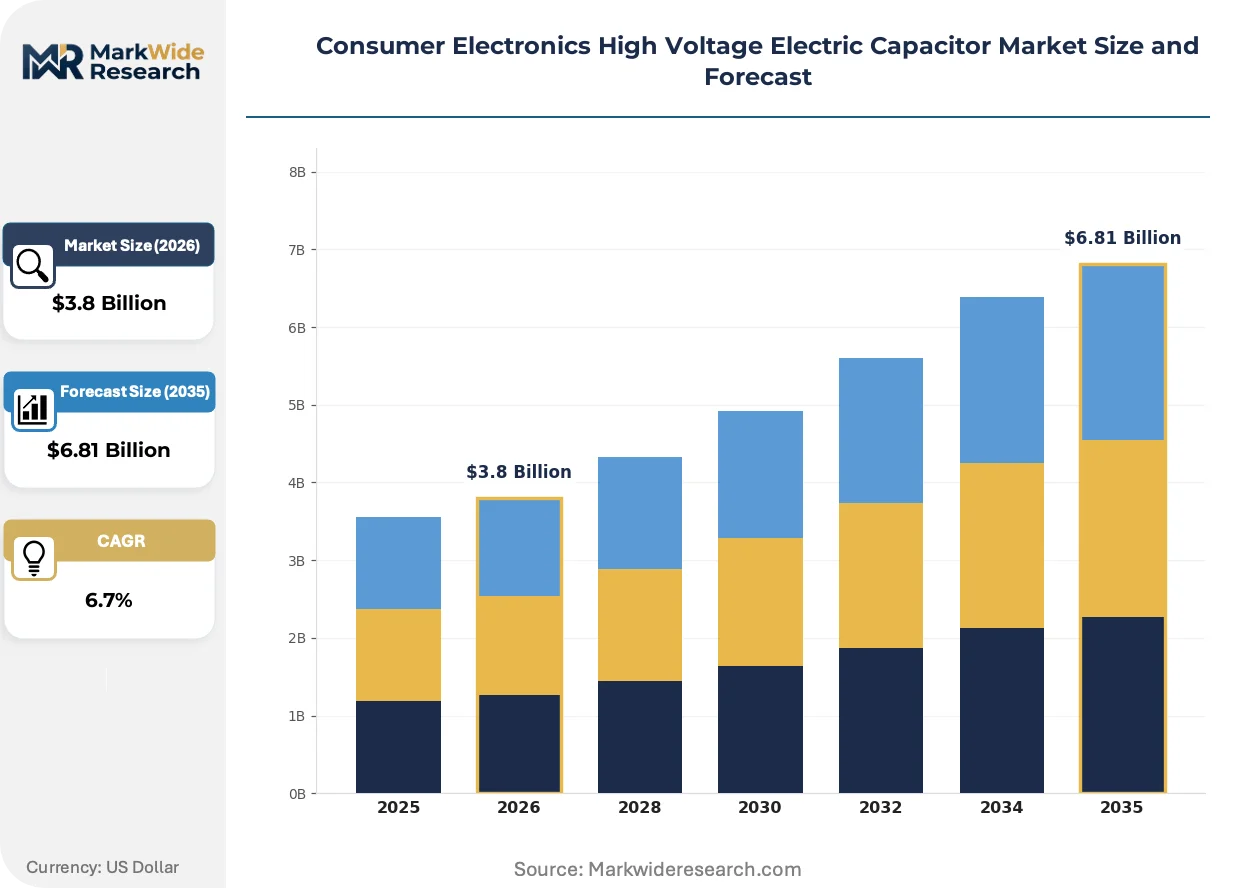
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Capacitors, Film Capacitors, Electrolytic Capacitors, Tantalum Capacitors, Mica Capacitors Technology: Surface Mount, Radial Lead, Axial Lead, Modular, Mixed Technology Application: Smartphones, Wearable Devices, Home Automation, Gaming Consoles, Audio Equipment End User: Consumer Hardware Manufacturers, Electronics Assemblers, Electronic Repair Services, OEMs, Aftermarket Suppliers |
| Companies Covered | Murata Manufacturing, TDK Corporation, Panasonic Industry, Nichicon, Rubycon, Vishay Intertechnology, KYOCERA AVX Components, Yageo Corporation, Samsung Electro-Mechanics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Electronics High Voltage Electric Capacitor Market Trends and Innovations
Dielectric material science and power semiconductor evolution are rewriting component specifications faster than legacy qualification protocols can absorb, compressing the window between technical feasibility and commercial deployment.
Nanocomposite polymer dielectrics with embedded ceramic fillers are converging with high-frequency power conversion architectures. Gaming peripheral manufacturers are adopting these formulations for compact external power supplies operating above 150kHz. This convergence is collapsing the traditional separation between film and ceramic capacitor application boundaries.
China's GB 4943.1-2022 safety standard for audio and video equipment mandates reinforced insulation distances and higher impulse withstand voltages for components in accessible circuits. Capacitor suppliers must redesign terminal geometries and coating systems to maintain creepage compliance. Korean OEMs are responding by pre-qualifying dual-certified parts before domestic GB mark audits complete.
Direct procurement from tier-two capacitor specialists is displacing distribution-heavy purchasing in high-volume console manufacturing. Contract manufacturers in Dongguan and Suzhou are establishing technical qualification teams to bypass traditional component distributors. This pattern is most pronounced in South Korea's domestic supply chain, where Samsung Electro-Mechanics maintains parallel direct and distributor channels.
Consumer Electronics High Voltage Electric Capacitor Market Segmentation
Component selection in high-voltage capacitor procurement tracks directly to thermal constraints, form-factor limitations, and certification requirements specific to each end-use. Understanding how these dimensions intersect reveals where margin pools concentrate and where suppliers must retool formulations to capture replacement-cycle demand.
Product Type:
Upgrade cycles in gaming console and smartphone architectures are forcing procurement teams to reassess dielectric choices against tighter thermal envelopes and shrinking board space.
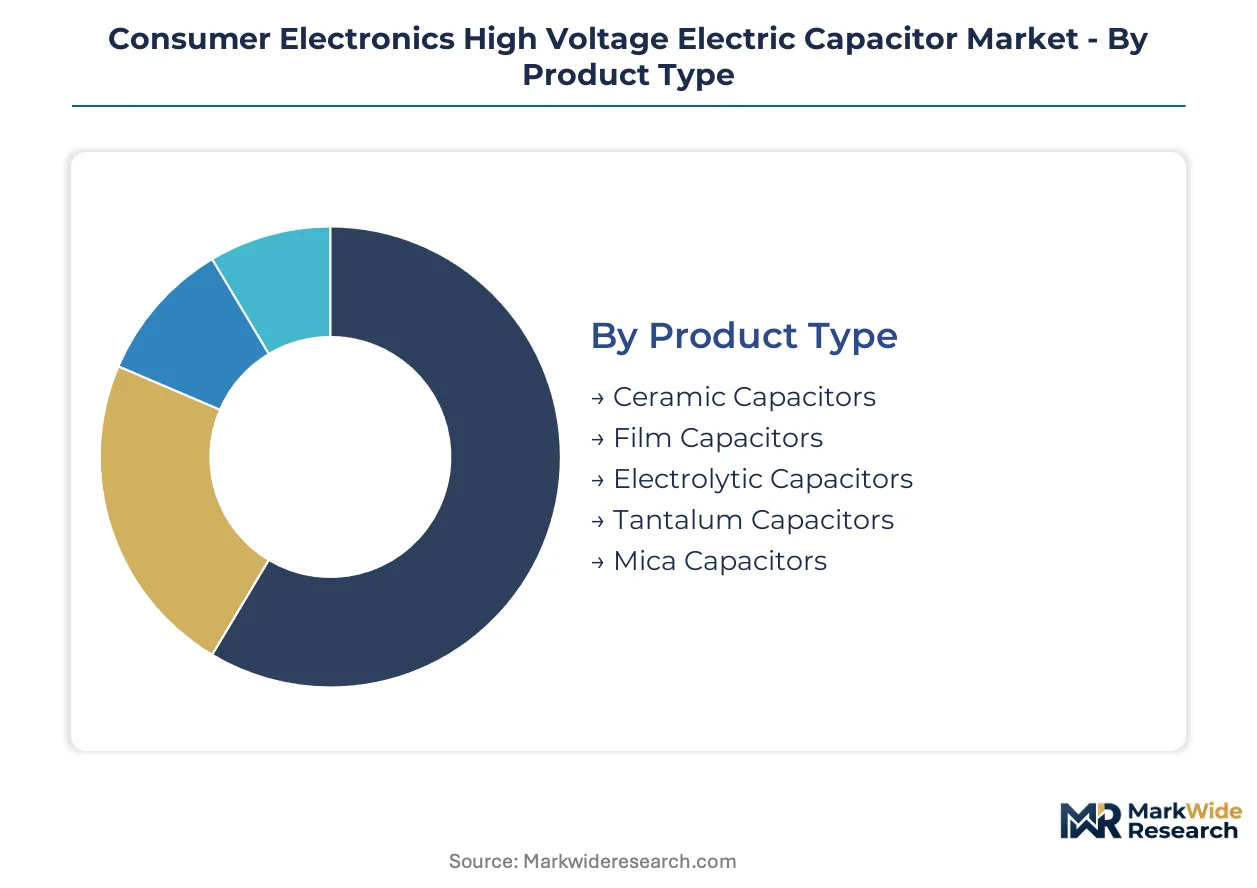
- Ceramic Capacitors:Multilayer ceramic formulations dominate unit volume in smartphone and wearable miniaturization due to favorable volumetric efficiency and surface-mount compatibility. Samsung Electro-Mechanics and Murata Manufacturing anchor supply for Korean and Japanese consumer hardware OEMs requiring sub-millimeter thickness at 500V+ ratings.
- Film Capacitors:Biaxially oriented polypropylene dielectrics with self-healing properties command premium positioning in gaming console power supplies where thermal endurance exceeds 105°C. Procurement lead times for these components are compressing as next-generation console launches accelerate.
- Electrolytic Capacitors:Aluminum oxide dielectric systems retain structural importance in audio equipment power supplies where bulk capacitance and cost efficiency outweigh form-factor constraints.
- Tantalum Capacitors:Manganese dioxide and polymer cathode variants serve niche applications in compact wearables requiring stable capacitance across temperature extremes.
- Mica Capacitors:Silvered mica constructions persist in RF filtering applications within home automation gateways where dielectric absorption must remain minimal.
Ceramic capacitors sit at the top of the volume ranking, with film capacitors climbing the fastest as gaming console thermal density intensifies.
Technology:
Mounting technology selection correlates directly with manufacturing automation levels and rework accessibility requirements across contract assembly ecosystems.
- Surface Mount:Tape-and-reel packaging dominates high-volume smartphone and wearable production lines in Dongguan and Suzhou assembly clusters, enabling pick-and-place speeds exceeding 100,000 components per hour.
- Radial Lead:Through-hole constructions retain relevance in audio equipment and aftermarket repair channels where manual soldering and component substitution remain economically viable.
- Axial Lead:Cylindrical form factors with lead wires extending from opposite ends serve legacy gaming console power supply designs and industrial retrofit applications.
- Modular:Pre-assembled capacitor banks with integrated thermal management reduce qualification burden for OEMs sourcing complete subsystems rather than discrete components.
- Mixed Technology:Hybrid mounting approaches accommodate transition designs where surface-mount ICs coexist with through-hole power components in home automation inverters.
Surface mount technology captures the dominant production share, with modular assemblies expanding most quickly as direct procurement from tier-two specialists displaces distribution channels.
Application:
End-use thermal profiles and certification stringency create divergent specification requirements that fragment capacitor procurement strategies.
- Smartphones:Sub-millimeter multilayer ceramic capacitors in 0201 and 01005 case sizes filter switching noise from gallium nitride chargers while occupying minimal PCB real estate.
- Wearable Devices:Solid tantalum and polymer aluminum capacitors tolerate mechanical flex stress in fitness bands and smartwatches where rigid ceramic formulations risk fracture.
- Home Automation:Film and electrolytic combinations smooth rectified AC in smart thermostat and security camera power supplies subject to FCC Part 15 emissions limits.
- Gaming Consoles:High-ripple film capacitors in 450V to 600V ratings stabilize power delivery for GPU and CPU loads cycling between idle and peak thermal states.
- Audio Equipment:Large-can aluminum electrolytics provide reservoir capacitance in amplifier power supplies where audible ripple rejection outweighs energy density priorities.
Gaming consoles anchor the fastest specification evolution, with wearables gaining share as health-monitoring features expand component counts per device.
End User:
Procurement authority distribution determines pricing leverage and technical qualification depth across the value chain.
- Consumer Hardware Manufacturers:Samsung, Sony, and Nintendo direct captive procurement teams specify dielectric formulations and terminal geometries for GB 4943.1-2022 compliance.
- Electronics Assemblers:Foxconn, Pegatron, and Jabil negotiate volume pricing while managing dual-certification timelines for UL and GB mark convergence.
- Electronic Repair Services:Independent technicians and authorized service centers source replacement capacitors through distributor channels with expedited delivery requirements.
- OEMs:Original equipment manufacturers without captive component engineering rely on contract manufacturer recommendations for capacitor selection.
- Aftermarket Suppliers:Third-party accessory manufacturers procure unbranded capacitors for replacement chargers and power adapters sold through e-commerce platforms.
Consumer hardware manufacturers command the deepest technical engagement, with electronics assemblers expanding procurement authority as direct sourcing displaces distributor intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capacitor production migrates toward jurisdictions where GB standard compliance costs diverge from legacy UL certification burdens, creating arbitrage windows for contract manufacturers optimizing dual-mark product flows. South Korea and China exploit this gap through captive supply chains and accelerated domestic certification pathways. Germany and Japan retain premium positioning via materials science specialization in polypropylene dielectric substrates.
China
Gaming console contract manufacturing clusters in Dongguan and Suzhou drive procurement volume for 500V+ film capacitors. SAMR enforces GB 4943.1-2022 dielectric withstand requirements that accelerate inventory replacement cycles for non-compliant imports. Yangtze River Delta assembly hubs are establishing technical qualification teams to bypass traditional distributor channels.
South Korea
Samsung Electro-Mechanics anchors captive demand for high-voltage MLCCs in domestic consumer hardware OEMs. MFDS alignment with GB mark reciprocity protocols compresses dual-certification timelines for power supply modules. Seoul Capital Area manufacturing zones concentrate procurement authority for next-generation console launches.
Japan
METI energy efficiency directives tighten power factor correction requirements for consumer electronics exports. Kansai and Chubu industrial corridors maintain biaxially oriented polypropylene substrate production critical to film capacitor thermal endurance. Osaka-based specialists leverage ceramic dielectric expertise for compact gaming peripheral architectures.
Germany
ECHA REACH substance restrictions force reformulation of lead-bearing electrode materials and flame-retardant epoxy systems. Bavarian chemical clusters supply nanocomposite polymer dielectrics converging with GaN switching frequencies above 100kHz. Baden-Württemberg capacitor specialists face input bottlenecks from concentrated polypropylene film supply.
United States
FCC Part 15 electromagnetic compatibility mandates shape RF-sensitive device capacitor selection for gaming and wearable applications. EPA and OSHA frameworks intersect with RoHS-aligned substance restrictions in California and Texas electronics assembly zones. Design engineering in Greater Boston and Pacific Northwest corridors specifies high-ripple film components for premium audio equipment.
Consumer Electronics High Voltage Electric Capacitor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive supply chains consolidating procurement around domestic champions while independent distributors serve aftermarket repair channels. The vendor base organizes into three tiers: vertically integrated materials-to-components conglomerates, mid-scale regional specialists with formulation expertise, and commodity assemblers competing on lead-time compression. M&A activity concentrates on ceramic dielectric IP portfolios, while capacity expansion targets GaN-compatible low-ESR production lines.
Within the vertically integrated tier, Murata Manufacturing and TDK Corporation exemplify archetypes combining materials science depth with surface-mount packaging scale. Samsung Electro-Mechanics occupies a distinct position anchoring Korean captive demand through parallel direct and distributor channel strategies. These three entities represent the dominant competitive anchors against which mid-scale specialists and regional assemblers calibrate positioning.
| Leading Market Players |
|---|
| Murata Manufacturing |
| TDK Corporation |
| Panasonic Industry |
| Nichicon |
| Rubycon |
| Vishay Intertechnology |
| KYOCERA AVX Components |
| Yageo Corporation |
| Samsung Electro-Mechanics |
| Others |
Pricing and Supply Chain Analysis
Biaxially oriented polypropylene resin indices cascade through capacitor manufacturing into three distinct pricing tiers, compressing margins for distributors while amplifying cost pass-through leverage for integrated dielectric substrate producers in Germany and Japan.
Pricing Analysis
Distributor margin layers in high-voltage film capacitors absorb 12-18 point spreads between factory gate and OEM dock, while direct procurement channels from Samsung Electro-Mechanics and Murata Manufacturing command volume-scaled discounts that bypass intermediary markups entirely. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified automotive-grade parts from consumer electronics tiers and unbranded aftermarket substitutes. Pricing pressure stems from polypropylene substrate supply bottlenecks, with contract manufacturers in Dongguan exhibiting highest price sensitivity due to compressed console launch timelines, while Korean captive supply chains show lowest sensitivity through in-house dielectric production.
Supply Chain Analysis
Reverse-logistics flows for failed gaming console power supplies concentrate in Shenzhen refurbishment hubs, where reclaimed film capacitors re-enter secondary channels after dielectric withstand testing. Manufacturing gravity centers on China, South Korea, and Japan, with biaxially oriented polypropylene substrate production drawing from German and Japanese chemical clusters. Supply chain risk hinges on single-source vulnerability in polypropylene film supply, with distribution running through tier-two specialists displacing traditional distributor channels in high-volume console procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's SAMR certification costs and South Korea's MFDS reciprocity protocols creates procurement cost differentials that favor dual-certified inventory positioning in Seoul Capital Area hubs.
For Market Incumbents: Hedge against polypropylene substrate supply disruption through backward integration into dielectric film production or long-term offtake agreements with Bavarian chemical clusters. Defend margin position by accelerating GB 4943.1-2022 pre-certification ahead of competitor qualification timelines, while channel control through direct procurement teams in Dongguan assembly zones limits distributor margin extraction. For New Entrants and Emerging Players: Launch via modular capacitor bank subsystems rather than discrete component competition, targeting India's BIS certification pathway in Tamil Nadu and Karnataka manufacturing zones where GB-compliant suppliers remain underpenetrated. White-space opportunity sits with GaN-compatible low-ESR ceramic formulations for compact charger architectures above 100kHz switching frequencies. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale regional specialists possessing nanocomposite polymer dielectric IP portfolios and existing SAMR certification infrastructure. Long-term viability favors acquisition targets with captive ceramic formulation expertise and parallel direct-distributor channel strategies. Watch for polypropylene film supply disruption signals and GB mark reciprocity expansion announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Substrate Production | Mitigates input bottlenecks from German and Japanese chemical clusters while securing dielectric supply for high-ripple film capacitor expansion. |
| Dual GB-UL Certification Pre-Qualification | Compresses eight-to-fourteen month qualification cycles for gaming console power modules ahead of competitor market entry. |
| GaN-Compatible Low-ESR Ceramic Capacity Expansion | Captures demand from gallium nitride switching frequencies above 100kHz in compact charger architectures. |
| Direct Procurement Channel Establishment | Bypasses distributor margin layers in Dongguan and Suzhou contract manufacturing clusters through technical qualification teams. |
| Nanocomposite Polymer Dielectric R&D Investment | Converges film and ceramic application boundaries for gaming peripheral power supplies operating above 150kHz. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with capacitor procurement managers at Foxconn and Pegatron, power supply design engineers at gaming console OEMs, SAMR certification specialists, and polypropylene substrate procurement leads at film capacitor manufacturers. Secondary validation drew from customs trade data for biaxially oriented polypropylene resin flows, SEC filings from vertically integrated component manufacturers, GB standard certification databases, and ECHA REACH substance restriction updates. Bottom-up demand modeling from console and smartphone production forecasts triangulated against top-down market sizing from dielectric substrate consumption patterns.
Comparable-period anchoring aligned the projection horizon against historical replacement cycles in gaming console architectures and smartphone upgrade cadences, with CAGR derivation reflecting segment-specific growth differentials across ceramic, film, and electrolytic dielectric categories. Segmentation dimensions modeled included dielectric material type, mounting technology, end-use application, and regional certification cluster. Forecast inputs incorporated polypropylene substrate supply elasticity, SAMR enforcement intensity for GB 4943.1-2022 compliance, and GaN charger adoption curves in consumer electronics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polypropylene supply disruption or accelerated SAMR certification timeline compression. Practitioners should monitor biaxially oriented polypropylene resin price indices, GB mark reciprocity protocol expansions, and GaN switching frequency migration patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Fiberglass Electrical Enclosure Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
Smart Fan Market
Electrical Equipment
Magnetic Contactors Market