
 PDU Power Cords Market | 2026-2036
PDU Power Cords Market Size, Share, and Industry Trends Forecast 2026-2036
PDU Power Cords Market Analytics
The capital-intensity divergence between integrated manufacturers and assembly-focused suppliers is rotating competitive advantage toward firms with captive cable extrusion and connector molding operations. Schneider Electric leverages its vertically integrated energy management portfolio to anchor premium cord sets for hyperscale facilities. Eaton Corporation sustains North American manufacturing scale through dedicated industrial cord production lines. Legrand competes across European commercial infrastructure with modular PDU cord systems.
PDU power cords are electrical interconnect assemblies that distribute power from rack-mounted power distribution units to individual servers, switches, and IT equipment, typically incorporating IEC C13/C14 or C19/C20 connectors with 12 to 14 AWG conductors rated for 10A to 20A service. These cords function as the final physical link in data center power architecture, where reliability failures can trigger cascading downtime events across mission-critical compute environments. Standard cords dominate current volume due to universal compatibility with legacy rack designs, while configurable cords capture expanding margin pools as operators demand custom lengths and color-coded phase identification for load balancing. Data centers represent the fastest-growing end-user segment as cloud providers and colocation operators scale facility footprints to support generative AI training clusters.
UL 817 governs cord-and-plug-set safety in the United States, IEC 60320 defines international connector interchangeability, and RoHS restricts hazardous substances in European-sold cord insulation compounds. These frameworks elevate compliance costs for cross-border suppliers while creating specification stickiness for incumbent certifiers. Stakeholders must monitor evolving ampacity requirements as liquid-cooled racks push power densities beyond traditional 15A thresholds.
Market Dynamics
Hyperscale data center operators are pushing rack power densities beyond 30kW per cabinet, forcing cord manufacturers to redesign conductor gauges and insulation systems for sustained high-ampacity operation without thermal degradation.
Growth Catalysts
- AI Training Cluster Expansion:Cloud providers deploying GPU-intensive infrastructure require C19/C20 cord sets rated for 20A continuous duty, creating specification pull for heavy-gauge assemblies.
- IEC 60320 Amendment:Updated connector temperature-rise limits are mandating upgraded contact materials across European data center retrofits, accelerating replacement cycles.
- Liquid Cooling Adoption:Immersion and direct-to-chip cooling systems are relocating PDUs closer to heat sources, demanding shorter custom-length cords with enhanced flex ratings.
Market Restraints
- Copper Price Volatility:Raw material swings compress margin predictability for extrusion-dependent manufacturers, particularly those without long-term cathode supply agreements.
- Connector Supply Concentration:Molded IEC C13/C19 housings source predominantly from specialized Taiwanese toolers, creating single-point vulnerability for assembly-focused cord suppliers.
- UL 817 Recertification Burden:Strain-relief and flammability testing updates impose six-to-nine month approval timelines that freeze product iteration for North American-bound shipments.
Strategic Opportunities
- India Data Center Buildout:Noida, Mumbai, and Chennai greenfield projects lack established cord supply chains, opening first-mover positioning for certified manufacturers.
- Color-Coded Phase Identification:Three-phase load balancing requirements are driving demand for custom-jacketed cords in distinct hues, commanding premium positioning over commodity black assemblies.
- CEA Grid Modernization:India's central electricity authority mandates are expanding industrial power distribution upgrades, extending PDU cord applications beyond IT into manufacturing automation.
Industry Challenges
- High-Frequency Testing Expertise:Validating cord performance under switched-mode power supply harmonics requires scarce RF engineering talent that incumbent wire harness suppliers rarely retain.
- Legacy Rack Interoperability:Decades-old server installations with C14 inlets persist in enterprise colocation facilities, forcing manufacturers to maintain obsolete connector tooling alongside next-generation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PDU Power Cords Market |
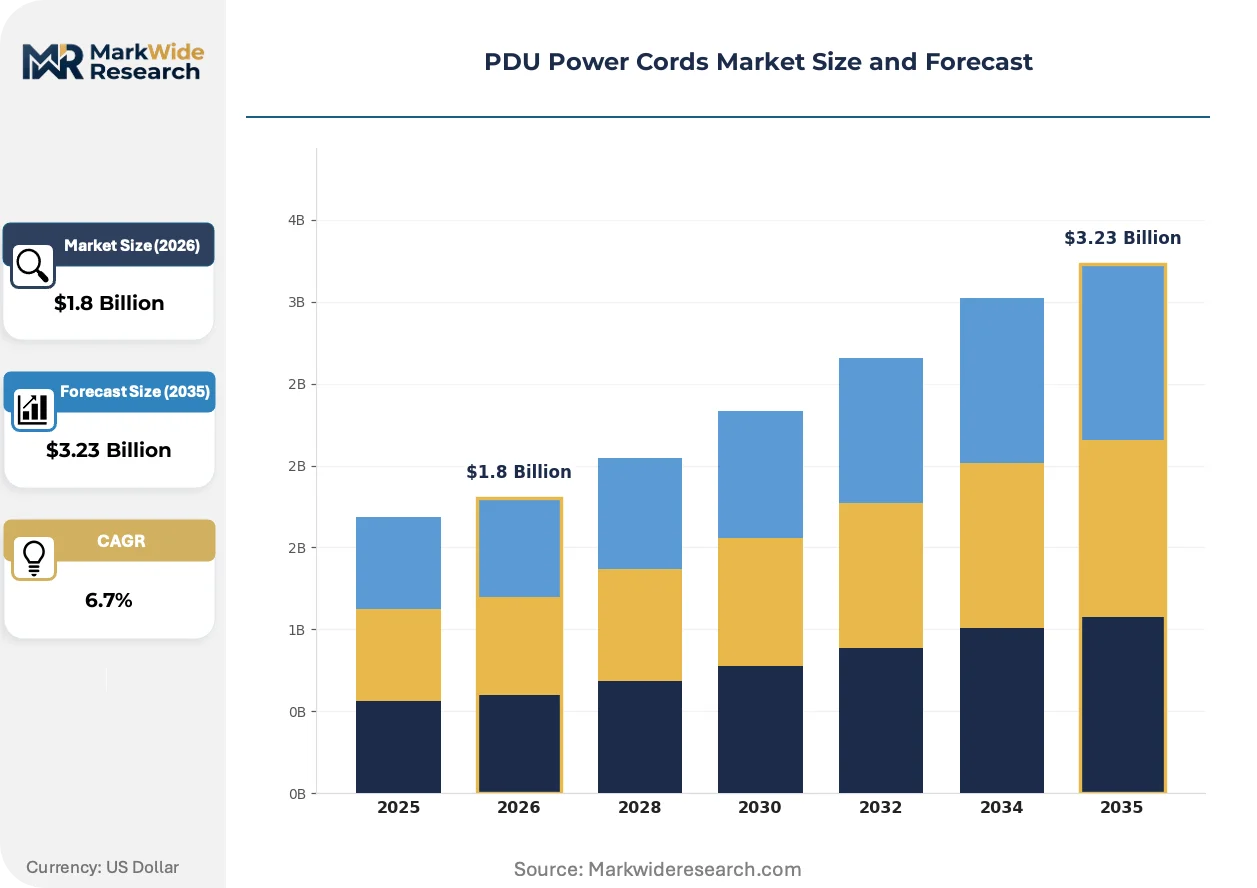
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cords, Retractable Cords, Extension Cords, Configurable Cords End User: Data Centers, Industrial Facilities, Commercial Offices, Healthcare Institutions Material: PVC, Rubber, Nylon, Silicone Power Rating: 5A, 10A, 15A, 20A |
| Companies Covered | Schneider Electric, Eaton Corporation, Vertiv Group, Legrand, Amphenol, Panduit, Tripp Lite, CyberPower Systems, Belden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PDU Power Cords Market Evolving Landscape
Active materials and connector architectures are diverging along performance tiers as liquid-cooled hyperscale facilities decouple from air-cooled enterprise standards.
Silicone-insulated conductor assemblies are bifurcating the thermal-performance tier. These cords maintain flexibility at sustained 105°C operating temperatures where PVC jackets harden and crack. Hyperscale operators in Singapore and Frankfurt are specifying silicone for high-density GPU racks. The technology is compressing commoditized PVC cord margins while creating specialty-tier pricing power for certified silicone extruders.
RoHS substance restrictions are tightening permissible phthalate content in jacket compounds sold across EU member states. ECHA enforcement is accelerating migration to TPE and TPU alternatives with superior oil resistance for edge computing deployments. German industrial automation integrators are now rejecting non-compliant cord stock, forcing Asian suppliers to reformulate compound recipes or lose continental shelf access.
Direct procurement from certified manufacturers is displacing distributor intermediaries among top-ten cloud operators. These buyers now mandate factory audits and lot-traceability systems that electrical wholesalers cannot replicate. The pattern is most visible in Northern Virginia and Ashburn data center clusters, where procurement teams source C19/C20 assemblies in ten-thousand-unit annual contracts with dedicated production lines.
PDU Power Cords Market Segmentation
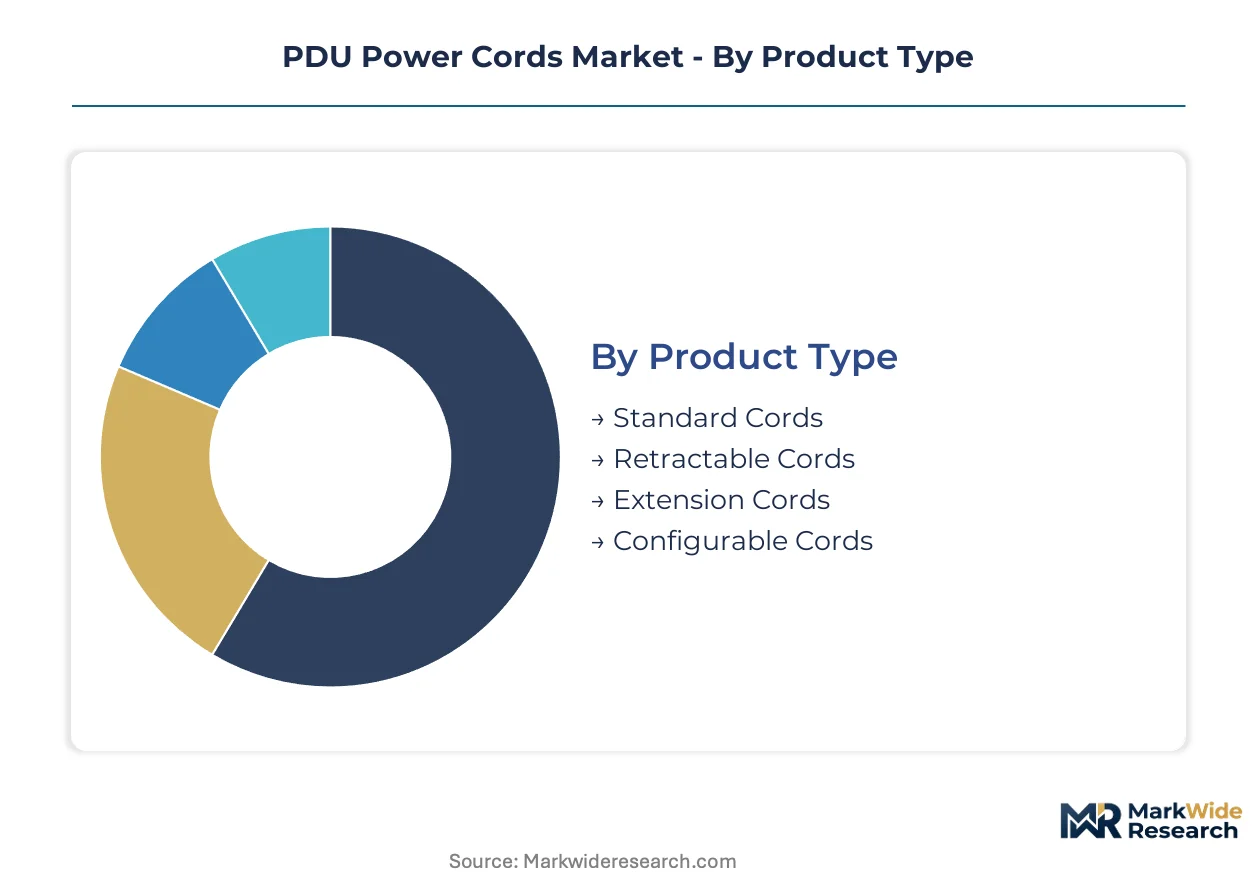
PDU power cord segmentation reveals how regulatory frameworks and performance tiers fragment procurement across mission-critical infrastructure. Specification divergence between IEC 60320 and UL 817 jurisdictions creates parallel product lines that resist standardization.
Product Type:
Regulatory differentiation separates commodity assemblies from certified specialty cords through connector testing protocols and flammability ratings.
- Standard Cords:Fixed-length assemblies with IEC C13/C14 or C19/C20 connectors dominate legacy rack deployments. Enterprise colocation facilities in Germany and the United States specify these for 10A-15A service where cost predictability outweighs customization needs.
- Configurable Cords:Custom-length, color-coded assemblies allow precise phase balancing in three-phase hyperscale environments. Cloud operators in Northern Virginia and Ashburn mandate factory-direct procurement with lot-traceability systems for these specifications.
- Retractable Cords:Spring-loaded reel mechanisms serve mobile maintenance applications in industrial automation settings where cable management flexibility reduces trip hazards.
- Extension Cords:Intermediate jumper assemblies bridge PDU-to-equipment gaps in retrofit data centers with non-standard rack spacing.
Established volume favors Standard Cords; emerging adoption favors Configurable Cords.
End User:
Application-specific duty cycles and failure-cost profiles drive material and certification tier selection.
- Data Centers:Hyperscale GPU clusters demand C19/C20 20A assemblies with silicone insulation for sustained high-ampacity operation. Singapore and Frankfurt operators specify these for liquid-cooled racks exceeding 30kW per cabinet.
- Industrial Facilities:Manufacturing automation lines require oil-resistant TPU jacket compounds under ECHA RoHS enforcement. German automotive integrators reject non-compliant stock, forcing compound reformulation across supplier bases.
- Commercial Offices:Distributed IT closets and edge computing nodes utilize standard PVC-jacketed cords where thermal stress remains moderate.
- Healthcare Institutions:Patient-care environments mandate enhanced strain-relief and antimicrobial jacket surfaces under FDA electrical safety guidance.
Data Centers command the steepest expansion trajectory; Industrial Facilities anchor replacement-cycle stability.
Material:
Cost tier stratification separates commodity extrusion from specialty polymer formulations.
- Silicone:Maintains flexibility at 105°C operating temperatures where PVC hardens. Hyperscale operators specify these for high-density GPU racks in Singapore and Frankfurt, compressing PVC margins while creating specialty-tier pricing power.
- PVC:Standard insulation for 10A-15A service in cost-sensitive enterprise deployments. Price volatility in chlorine and plasticizer feedstocks compresses margin predictability for extrusion-dependent manufacturers.
- Rubber:Heavy-duty jacketing for industrial environments with mechanical abrasion and chemical exposure.
- Nylon:Braided reinforcement layers enhance cut resistance in manufacturing floor applications.
PVC retains volume dominance; Silicone captures expanding margin pools.
Power Rating:
Customer type and rack density requirements segment procurement across ampacity thresholds.
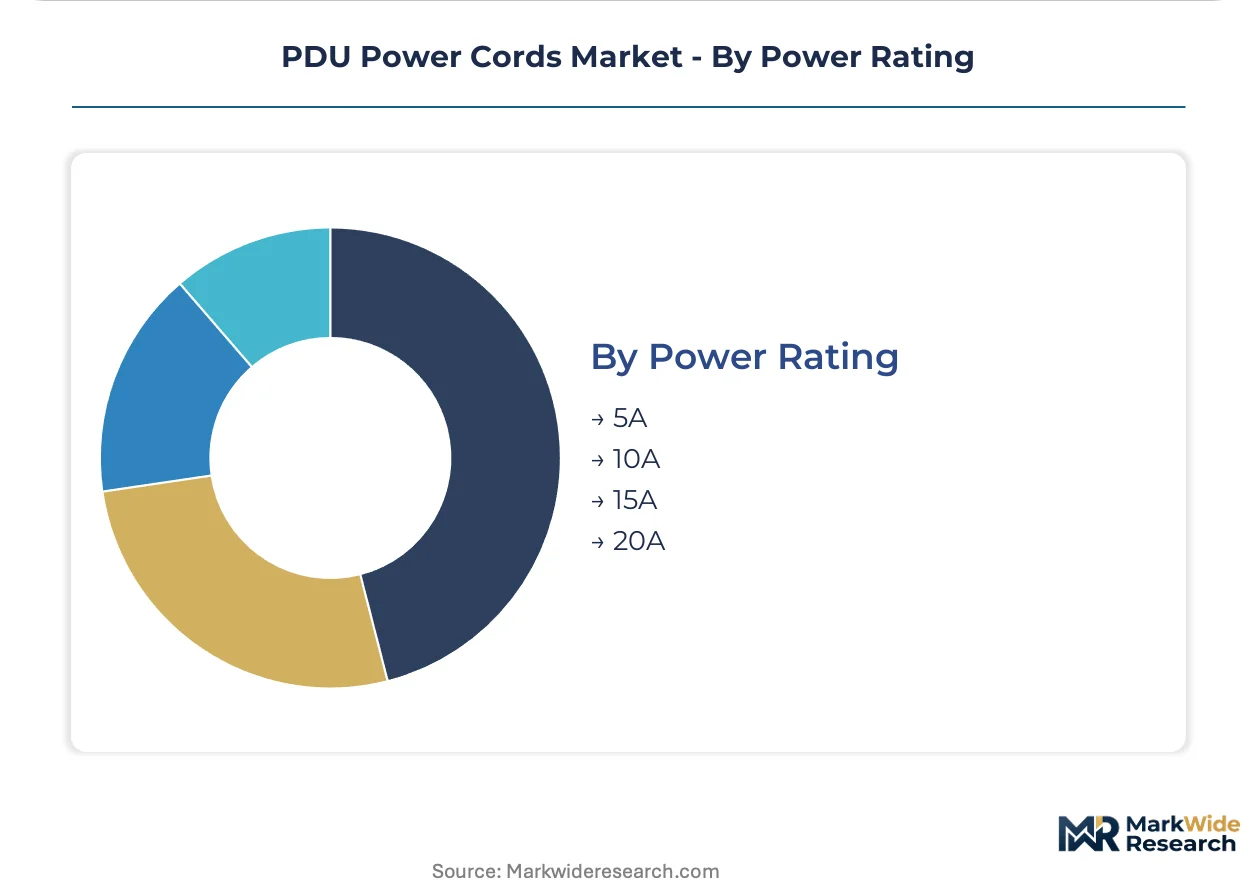
- 20A:C19/C20 connector assemblies serve GPU-intensive AI training clusters. Cloud providers deploy these for continuous-duty operation in liquid-cooled cabinets exceeding traditional thermal envelopes.
- 15A:Legacy air-cooled enterprise racks and standard server configurations utilize these ratings where power density remains below 15kW per cabinet.
- 10A:Network switches, storage arrays, and peripheral equipment populate this tier with C14 inlet compatibility.
- 5A:Low-power edge devices and embedded systems require minimal conductor gauge.
20A ratings gain share fastest as rack densities climb; 15A ratings defend installed-base replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in PDU power cords tilt toward deficit positions in data center construction hotspots while established manufacturing bases in East Asia sustain export surpluses. Import dependence concentrates in markets where hyperscale buildouts outpace domestic cable extrusion capacity.
United States
Northern Virginia and Ashburn data center clusters consume C19/C20 assemblies at volumes exceeding regional production capacity. UL 817 recertification timelines stretch six-to-nine months, freezing product iteration for domestic-bound shipments. Texas and Arizona greenfield projects source heavily from Taiwanese connector suppliers to bridge supply gaps.
China
Yangtze River Delta and Pearl River Delta house concentrated molding operations for IEC C13/C19 connector housings. MIIT standards on electrical interconnects govern domestic data center procurement, while export-oriented extruders face RoHS compliance audits for EU-bound shipments. Shenzhen toolers supply molded components to assembly-focused cord suppliers worldwide.
Germany
Frankfurt's liquid-cooled hyperscale facilities specify silicone-insulated cords rated for 105°C continuous operation. ECHA enforcement of phthalate restrictions in jacket compounds accelerates migration to TPE alternatives. Bavarian industrial automation integrators reject non-compliant stock, forcing supplier base reformulation.
India
Noida, Mumbai, and Chennai greenfield data centers lack established cord supply chains, opening first-mover positioning for certified manufacturers. CEA grid modernization mandates expand industrial power distribution upgrades beyond IT into manufacturing automation. Domestic production capacity remains underdeveloped against construction pipeline velocity.
Singapore
High-density GPU racks in island facilities demand silicone-jacketed assemblies for thermal performance beyond PVC limits. The city-state's position as regional cloud hub concentrates procurement authority for Southeast Asian expansion. Local distributors face displacement as direct procurement from certified manufacturers takes hold among top-ten cloud operators.
PDU Power Cords Market Competitive Landscape
Concentration sits with integrated energy management conglomerates and specialized electrical infrastructure suppliers. The vendor base separates into captive extrusion operators with connector molding capabilities and assembly-focused intermediaries dependent on outsourced components. Two strategic archetypes dominate: vertically integrated industrial conglomerates with energy management portfolios, and specialized connectivity suppliers with dedicated data center product lines. Competitive moves center on backward integration into cable extrusion and factory-direct procurement relationships with hyperscale operators.
Among integrated industrial conglomerates, Schneider Electric, Eaton Corporation, and Legrand occupy positions that exemplify divergent geographic anchoring strategies. Schneider Electric represents the European-centered archetype with energy management portfolio breadth. Eaton Corporation sits within the North American manufacturing scale tier. Legrand exemplifies modular system specialization across commercial infrastructure segments. These three companies illustrate how vertical integration depth separates premium-tier positioning from assembly-dependent competitors.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| Vertiv Group |
| Legrand |
| Amphenol |
| Panduit |
| Tripp Lite |
| CyberPower Systems |
| Belden |
| Others |
Value Network & Pricing Analysis
Ninety-day connector housing lead times from Taiwanese toolers concentrate pricing power with integrated manufacturers possessing captive molding operations, while assembly-focused suppliers absorb margin compression from copper cathode volatility. This structural asymmetry rewards backward integration into cable extrusion and forces distributors toward transactional commodity positioning.
Pricing Analysis
The customization-premium spread between standard C13/C14 assemblies and factory-direct configurable cords with color-coded phase identification spans three performance tiers. Pricing stratifies across silicone-insulated premium cords for liquid-cooled hyperscale racks, PVC-jacketed standard assemblies for legacy enterprise deployments, and economy-grade black cords for cost-sensitive edge computing nodes. Price differentiation hinges on IEC 60320 certification grade and volume scale, with ten-thousand-unit annual contracts commanding dedicated production line access. Pricing pressure stems from raw material swings in copper and chlorine feedstocks, compressing margin predictability for extrusion-dependent manufacturers. Cloud operators exhibit lowest price sensitivity, prioritizing lot-traceability and factory audit compliance over per-unit cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane elevate inbound logistics costs for North American-bound shipments, particularly for UL 817 recertification-dependent product lines. Manufacturing gravity centers on China's Yangtze River Delta for connector housing molding, Germany's Bavarian industrial corridor for silicone extrusion, and the United States' Texas-Arizona axis for final assembly. Raw material dependencies span Chilean copper cathodes, Taiwanese PET resin for jacket compounds, and Japanese contact alloy for high-ampacity C19/C20 connectors. Supply chain risk concentrates in single-source vulnerability for IEC C13/C19 molded housings. Distribution runs through direct procurement relationships with hyperscale operators, displacing electrical wholesale intermediaries in Northern Virginia and Ashburn clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among top-ten cloud operators mandating factory audits and lot-traceability systems, fragmenting pricing authority away from distributor intermediaries toward certified manufacturers with captive production.
For Market Incumbents: Fortify positioning through backward integration into silicone extrusion capacity and captive connector molding operations, neutralizing Taiwanese tooler dependency. Defensive moves require UL 817 pre-certification investment ahead of strain-relief testing updates, locking six-to-nine month approval timelines against assembly-focused competitors. Threat substitution from active busbar architectures in next-generation liquid-cooled racks demands R&D allocation toward high-frequency harmonic validation capabilities. For New Entrants and Emerging Players: Aftermarket service-layer gaps in legacy rack interoperability present exploitable white space, where decades-old C14 inlet installations persist in enterprise colocation facilities. The most penetrable segment spans color-coded phase identification cords for three-phase load balancing in Indian greenfield data centers, where Noida, Mumbai, and Chennai construction pipelines outpace domestic supply chain maturity. A go-to-market angle anchored in CEA grid modernization compliance for industrial automation extensions beyond IT infrastructure unlocks manufacturing automation procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicone-insulated specialty tiers, favoring acquisition targets with certified 105°C extrusion capabilities and established hyperscale factory-direct relationships. Long-term viability over the projection horizon rests on positioning for liquid-cooled rack density trajectories exceeding 30kW per cabinet. The signal to watch is IEC 60320 amendment implementation velocity across European retrofit cycles, indicating replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Extrusion | Captive 105°C insulation capacity secures hyperscale GPU rack specifications in Singapore and Frankfurt. |
| UL 817 Pre-Certification Investment | Accelerated strain-relief approval timelines lock North American market access against assembly-dependent competitors. |
| Factory-Direct Procurement Relationships | Lot-traceability systems and dedicated production lines displace distributor intermediaries in Ashburn clusters. |
| Color-Coded Phase Identification Product Lines | Custom-jacketed cords command premium positioning over commodity black assemblies in three-phase environments. |
| CEA Grid Modernization Compliance | Industrial power distribution certification extends addressable market beyond IT into manufacturing automation. |
Research Methodology
The analysis maps standard cord, configurable cord, retractable cord, and extension cord sub-sectors, each validated through data center procurement directors, industrial automation integrators, cable extrusion plant managers, and electrical distribution channel partners. Primary interview insights combined with secondary validation from MIIT electrical interconnect standards, ECHA RoHS enforcement databases, UL certification registries, and hyperscaler capex disclosures. Bottom-up unit demand modeling and top-down market sizing triangulate volume estimates across the analysis window.
Consistency-check validation against external benchmarks ensures analytical rigor in output generation. The projection framework segments by product type, end-user application, material formulation, and power rating tier, with CAGRs derived from installed-base replacement cycles and greenfield construction pipeline velocity. Forecast inputs incorporate liquid-cooled rack density trajectories, IEC 60320 amendment adoption curves, and copper price volatility assumptions.
Underlying assumptions cover regulatory enforcement continuity, hyperscale construction pipeline execution, and raw material supply stability, with deviation risk concentrated in UL 817 recertification timeline extensions, Taiwanese connector housing supply disruptions, and ECHA phthalate restriction acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Busbar Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Europe Busbar Market
Electrical Equipment
India Electrical Enclosures Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Passover Humidifiers Market
Electrical Equipment
Medium Voltage Circuit Breakers Market