
 Global Dehydrating Breather Market | 2026-2036
Global Dehydrating Breather Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dehydrating Breather Market Intelligence
ISO 9001 certification is rotating as the baseline qualification for OEM supply contracts in this sector. Maschinenfabrik Reinhausen GmbH leverages its transformer accessory heritage to dominate European utility procurement channels. Parker-Hannifin Corporation anchors North American distribution through its industrial filtration network. HYDAC International competes on hydraulic system integration, extending breather sales into mobile equipment aftermarket channels.
A dehydrating breather is a moisture-exclusion device installed on sealed fluid systems, typically incorporating silica gel or molecular sieve media within a vented housing to adsorb atmospheric water vapor during thermal breathing cycles. The unit maintains dielectric fluid integrity by limiting relative humidity ingress to below critical saturation thresholds, preventing sludge formation and insulation degradation in oil-filled electrical equipment. Silica gel breathers occupy the volume lead due to low procurement cost and color-change indicator convenience, though molecular sieve breathers are gaining share in cold-climate transformer applications where sub-zero performance thresholds matter. Adsorption technology sustains the dominant revenue position, while regeneration-enabled breathers are emerging as a margin pool for operators seeking reduced desiccant replacement labor.
FDA oversight of silicate desiccant material safety intersects with EPA guidelines on industrial chemical containment, while IEC 60695 flammability standards govern housing material selection for electrical equipment adjacency. India's CEA mandates moisture monitoring protocols for grid transformers above specified ratings, directly conditioning breather specification in utility tenders. Stakeholders must weigh desiccant chemistry selection against evolving regional disposal regulations and circular-economy mandates for maintenance consumables.
Market Dynamics
Transformer fleet electrification and refrigerant-phaseout mandates are compressing replacement cycles for moisture-control equipment across electrical infrastructure networks. The EU F-Gas Regulation and India's CEA protocols are forcing utilities to upgrade from passive silica gel systems to monitored breather architectures with predictive maintenance capabilities.
Growth Catalysts
- EU F-Gas Regulation:Tightened moisture-control standards for electrical infrastructure are mandating breather upgrades across European transformer fleets, accelerating replacement demand.
- India's CEA protocols:State-owned utilities are deploying silica gel breathers across aging distribution networks, creating concentrated procurement volume in grid modernization tenders.
- Molecular sieve technology:Cold-climate transformer applications in sub-zero environments are shifting specification preference toward molecular sieve media for performance reliability.
Market Restraints
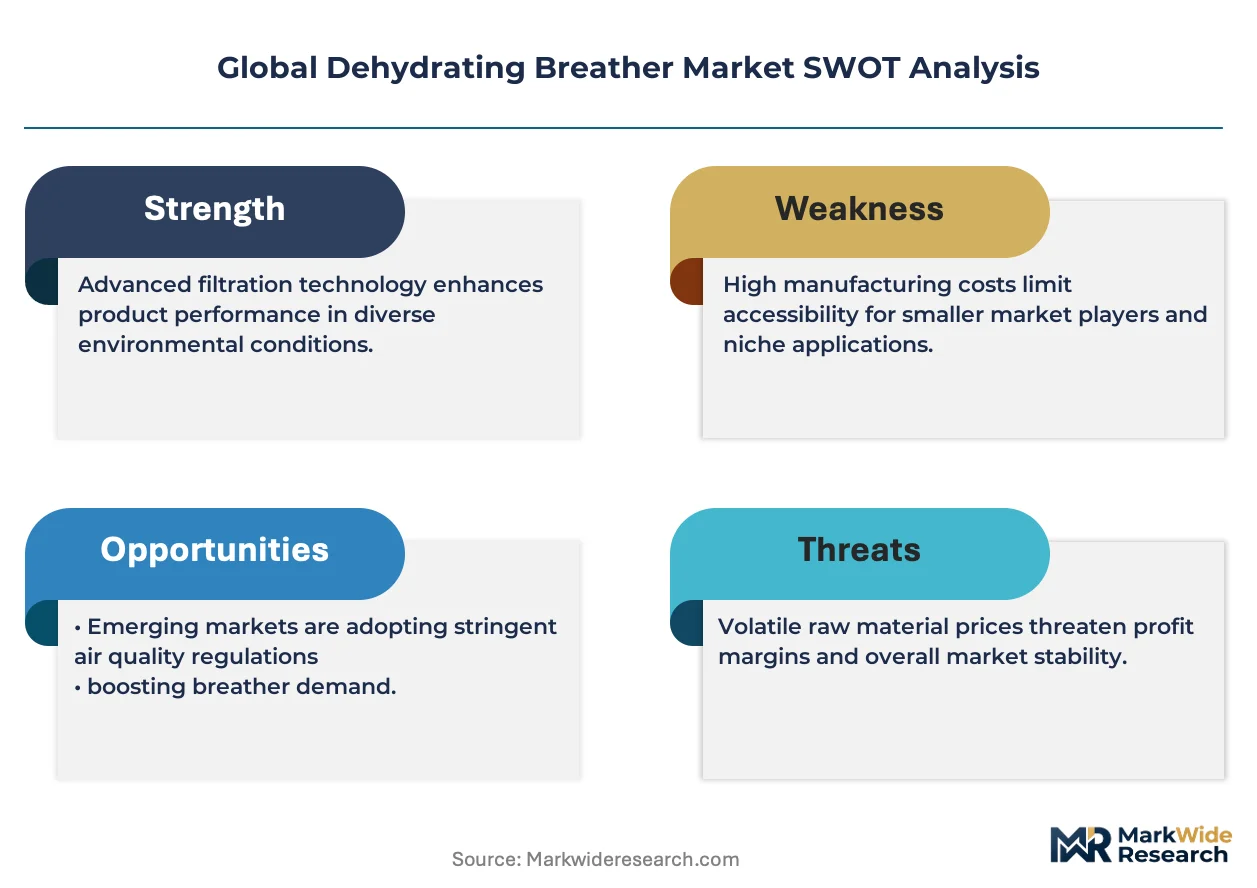
- Silica gel cost volatility:Raw material price swings for silicate desiccants compress margin stability for low-cost breather manufacturers serving price-sensitive utility segments.
- European supply concentration:OEM procurement channels for transformer accessories concentrate among heritage suppliers with established utility relationships, limiting new entrant access.
- Technical performance ceiling:Passive adsorption breathers face physical limits on moisture capacity in high-humidity coastal environments, constraining deployment geography.
Strategic Opportunities
- Regeneration-enabled systems:Operators seeking reduced desiccant replacement labor are creating a margin pool for reusable breather technologies with heating element integration.
- Mobile equipment aftermarket:Hydraulic system integration pathways extend breather sales into construction and mining equipment service channels beyond stationary electrical infrastructure.
- CEA-mandated monitoring:India's moisture monitoring protocols for grid transformers above specified ratings are conditioning breather specification toward smart, sensor-equipped units.
Industry Challenges
- IEC 60695 compliance timelines:Flammability certification for housing materials adjacent to electrical equipment extends product development cycles and delays market entry.
- Circular-economy disposal friction:Evolving regional regulations for spent desiccant classification as industrial chemical waste complicate maintenance logistics and service contract structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dehydrating Breather Market |
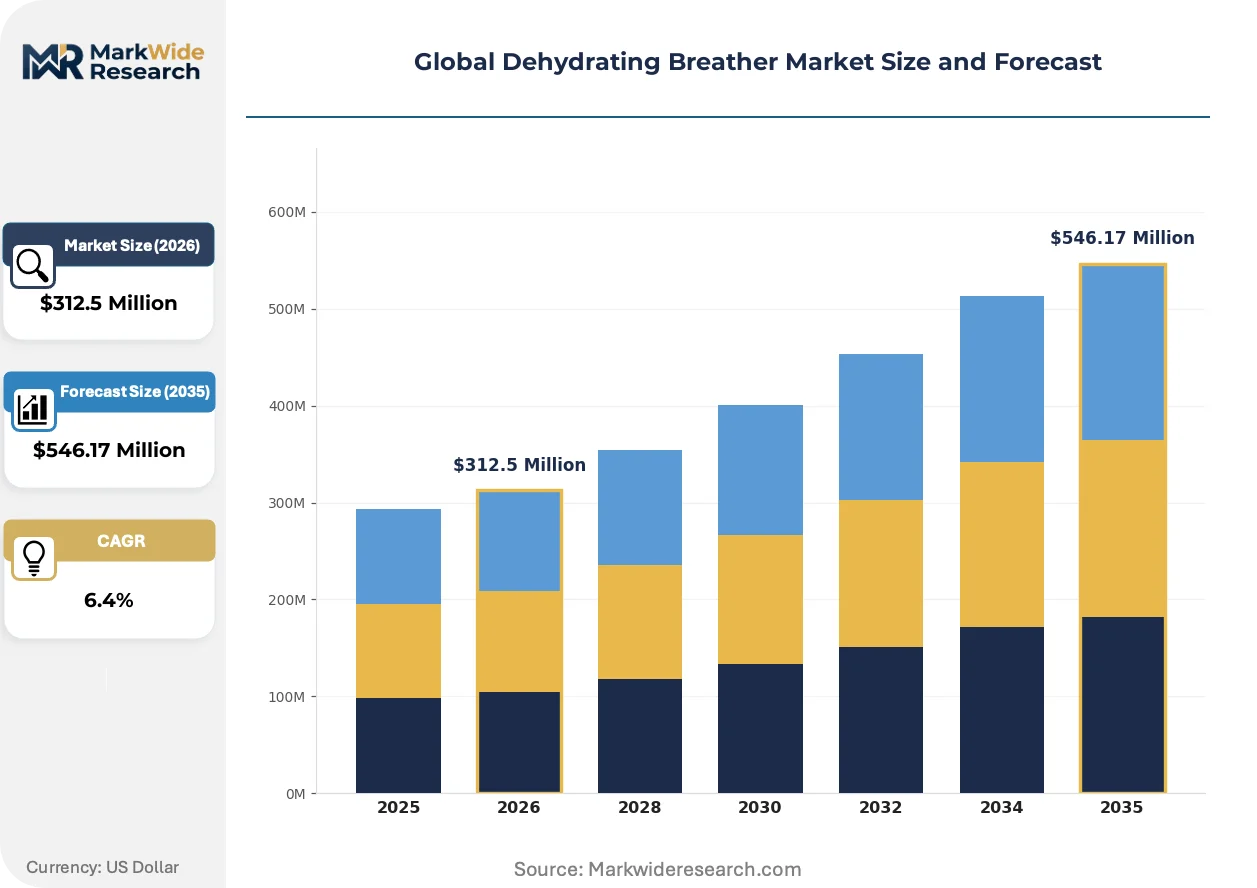
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Gel Breathers, Molecular Sieve Breathers, Activated Alumina Breathers, Clay Desiccant Breathers Technology: Ventilation, Filtration, Adsorption, Absorption, Regeneration Application: Transformers, Gearboxes, Switchgear, Hydraulic Systems, Compressors End User: Power Generation Plants, Manufacturing Units, Transportation Equipment, Renewable Energy Facilities |
| Companies Covered | ABB Ltd., Des-Case Corporation, AGM Container Controls Inc., Qualitrol Corporation, Maschinenfabrik Reinhausen GmbH, Hitachi, Ltd., Parker-Hannifin Corporation, Drytech Inc., HYDAC International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dehydrating Breather Market Strategic Shifts & Innovations
Moisture-control architectures are shifting from consumable media replacement toward regenerative systems with embedded sensing, altering the fundamental economics of transformer maintenance contracts.
Regeneration-enabled breather technology is decomposing the traditional silica gel replacement service model. Utilities in Germany and Scandinavia are piloting heated desiccant cartridges that restore adsorption capacity on-site, eliminating truck rolls for media swaps. This capability is compressing aftermarket service revenue pools while shifting supplier value capture toward hardware-plus-software subscription structures.
REACH compliance requirements for chemical substance registration are tightening material traceability obligations across European breather supply chains. Manufacturers must now document desiccant sourcing through full production cycles, adding administrative overhead but creating differentiation for suppliers with vertically controlled material flows. Transformer OEMs in France and Germany are prioritizing vendors with pre-validated substance dossiers to accelerate project timelines.
Service unbundling is fragmenting traditional breather procurement patterns. North American industrial buyers are separating hardware acquisition from installation and media replacement, sourcing breathers through industrial filtration distributors while contracting maintenance to regional electrical service firms. This channel decomposition is most advanced in Texas and California utility districts, where specialized transformer service providers now compete directly with OEM-affiliated field teams for recurring revenue streams.
Global Dehydrating Breather Market Segmentation
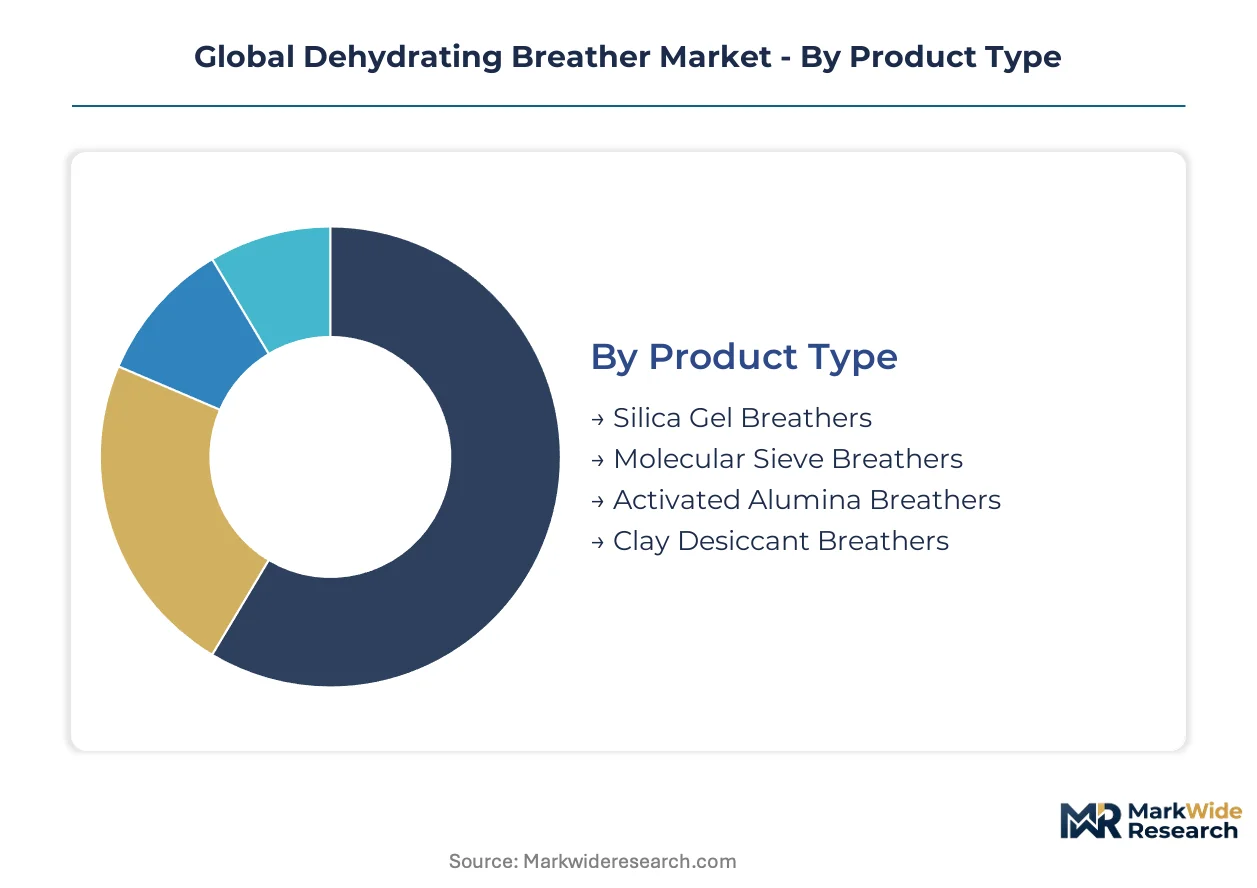
Dehydrating breather procurement patterns fragment sharply across media chemistry, system architecture, and end-use duty cycles. Specification decisions hinge on moisture-load profiles, maintenance access economics, and regional regulatory stringency rather than unit cost alone.
Product Type:
Margin pools concentrate in molecular sieve formulations where cold-climate performance commands specification premiums, while silica gel variants compete on replacement volume in cost-sensitive utility fleets.
- Silica Gel Breathers:Orange-to-green color-change indicators simplify field inspection protocols for utility maintenance crews. India's state-owned distribution utilities are deploying these units across aging transformer networks under CEA-mandated moisture monitoring programs, though silica gel cost volatility compresses manufacturer margins on large tenders.
- Molecular Sieve Breathers:Synthetic zeolite media maintain adsorption capacity below freezing where silica gel fails. Scandinavian and German utilities specify these for sub-zero transformer installations, with OEM procurement channels concentrating supply among heritage European manufacturers with pre-validated REACH substance dossiers.
- Activated Alumina Breathers:High-crush-strength media suit high-vibration gearbox and compressor applications in mining equipment.
- Clay Desiccant Breathers:Natural bentonite formulations serve price-sensitive industrial buyers with moderate moisture-load requirements.
Silica Gel Breathers hold installed capacity. Molecular Sieve Breathers is rotating up the share rankings.
Technology:
Revenue capture is shifting from consumable media replacement toward hardware-plus-software subscription models as regeneration-enabled architectures displace passive systems.
- Adsorption:Physical binding of water vapor onto desiccant surfaces dominates transformer protection applications. Silica gel and molecular sieve media both operate on this principle, with adsorption sustaining the dominant revenue position across electrical infrastructure networks.
- Regeneration:Heated cartridge systems restore desiccant capacity on-site, eliminating truck rolls for media swaps. German utilities are piloting these units, compressing traditional aftermarket service revenue while shifting supplier value capture toward predictive maintenance platforms.
- Ventilation:Passive airflow management without active moisture removal serves low-criticality auxiliary equipment.
- Filtration:Particulate exclusion layers protect desiccant beds from contamination in dusty environments.
- Absorption:Chemical reaction-based moisture capture sees limited use due to irreversible media consumption.
Adsorption commands current deployment share. Regeneration is climbing the fastest as utilities modernize maintenance economics.
Application:
Transformer applications concentrate procurement volume, though hydraulic system integration is opening aftermarket channels beyond stationary electrical infrastructure.
- Transformers:Oil-filled power and distribution transformers require continuous moisture exclusion to prevent dielectric fluid degradation. EU F-Gas Regulation and India's CEA protocols are forcing upgrades from passive systems to monitored architectures with predictive capabilities.
- Hydraulic Systems:Mobile construction and mining equipment incorporate breathers on reservoir tanks. Parker-Hannifin's industrial filtration network anchors North American distribution into these aftermarket service channels.
- Switchgear:Gas-insulated switchgear demands ultra-low humidity maintenance during thermal cycling.
- Gearboxes:Wind turbine drivetrains and industrial gear systems use breathers to protect lubricant integrity.
- Compressors:Rotary and reciprocating compressor crankcases require moisture control to prevent corrosion and oil emulsification.
Transformers anchor specification volume. Hydraulic Systems is expanding most quickly into mobile equipment segments.
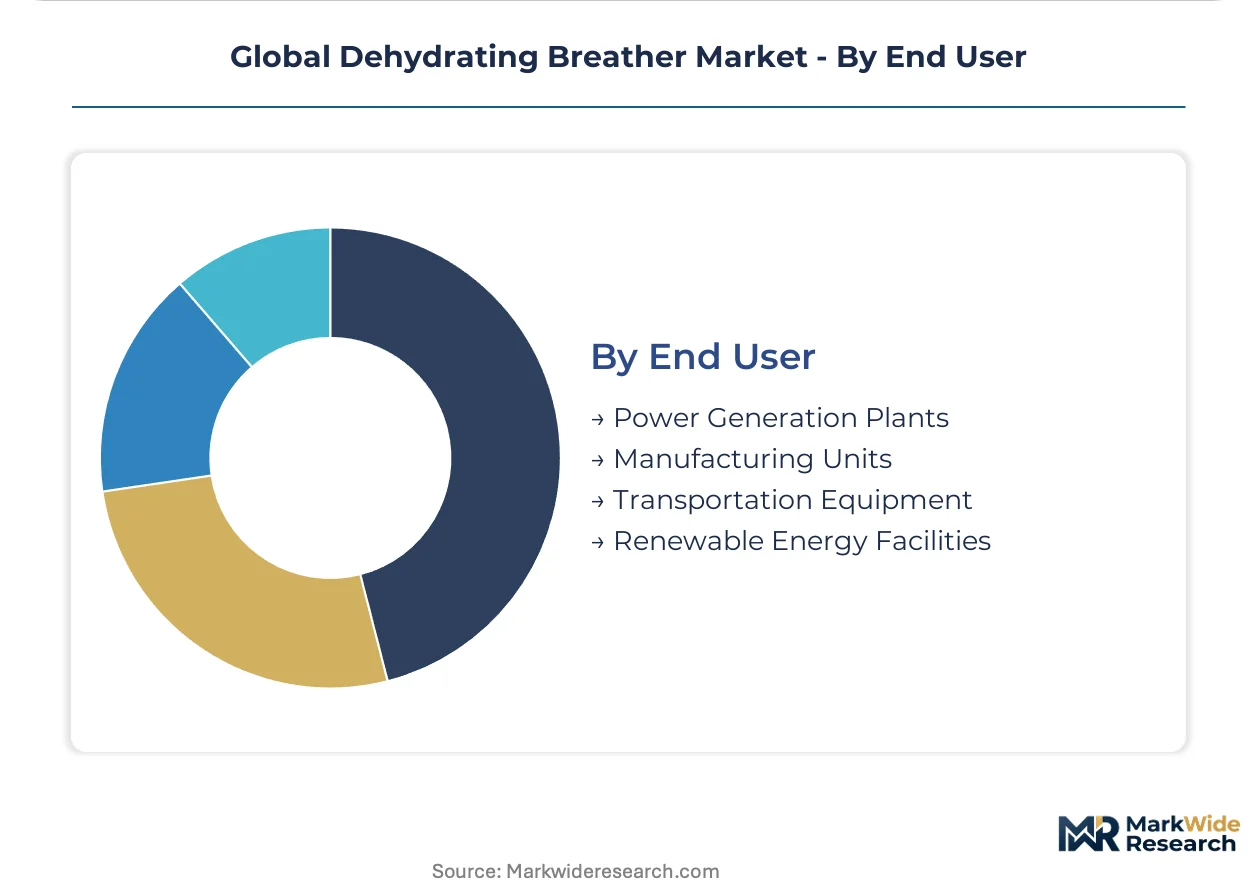
End User:
Power generation plants represent the steepest expansion trajectory as utilities modernize transformer fleets under tightening moisture-control mandates.
- Power Generation Plants:Centralized generation and grid-scale storage facilities operate large transformer banks with critical moisture-management requirements. Modernization programs across European and Indian utilities are accelerating replacement demand for advanced breather systems.
- Renewable Energy Facilities:Wind and solar installations require distributed transformer protection across geographically dispersed assets. Offshore wind projects in the North Sea specify molecular sieve breathers for salt-air and cold-climate reliability.
- Manufacturing Units:Process industries with continuous production lines prioritize breather reliability to avoid unplanned downtime.
- Transportation Equipment:Rail traction transformers and electric vehicle charging infrastructure create emerging specification opportunities.
Power Generation Plants dominate tender volume. Renewable Energy Facilities is gaining share fastest on capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation and India's CEA protocols are forcing utility procurement toward monitored breather architectures, while cold-climate specifications concentrate demand in Northern European and North American transformer fleets.
United States
EPA guidelines on industrial chemical containment intersect with utility modernization programs across Texas and California utility districts. Specialized transformer service providers now compete directly with OEM-affiliated field teams for recurring revenue streams in these states. Parker-Hannifin's industrial filtration network anchors North American distribution into hydraulic system aftermarket channels.
Germany
REACH compliance requirements for chemical substance registration tighten material traceability obligations across breather supply chains. German utilities are piloting heated desiccant cartridges that restore adsorption capacity on-site, eliminating truck rolls for media swaps. Transformer OEMs in France and Germany prioritize vendors with pre-validated substance dossiers to accelerate project timelines.
India
CEA-mandated moisture monitoring protocols for grid transformers above specified ratings directly condition breather specification in utility tenders. State-owned distribution utilities are deploying silica gel breathers across aging transformer networks under modernization programs. Procurement volume concentrates in grid tenders where low-cost silica gel variants compete on replacement volume.
Sweden
Sub-zero transformer installations in Scandinavian utilities specify molecular sieve media where silica gel fails to maintain adsorption capacity. Synthetic zeolite formulations command specification premiums in cold-climate performance applications. OEM procurement channels concentrate supply among heritage European manufacturers with established utility relationships.
China
Dual carbon goals and grid infrastructure expansion are accelerating transformer fleet electrification across provincial power networks. National standards for electrical equipment flammability govern housing material selection for breather adjacency to transformers. Manufacturing clusters in eastern coastal provinces face moisture-capacity constraints for passive adsorption breathers in high-humidity environments.
Global Dehydrating Breather Market Key Industry Players
Listed leaders compete with private specialists across utility procurement channels, creating a tiered structure where heritage transformer accessory suppliers hold established relationships while filtration-focused industrials expand through distribution networks. The vendor base clusters around three strategic archetypes: integrated electrical equipment OEMs with captive breather lines, specialized desiccant technology firms with material science differentiation, and diversified industrial filtration suppliers leveraging cross-product bundling. Dominant competitive moves include strategic partnerships with transformer OEMs for specification anchoring and geographic expansion through regional electrical service firm alliances.
Within the heritage European supplier tier, Maschinenfabrik Reinhausen GmbH exemplifies the transformer accessory specialist archetype, while Parker-Hannifin Corporation represents the diversified industrial filtration model with North American distribution strength. HYDAC International occupies a position bridging hydraulic system integration with breather technology, extending reach into mobile equipment aftermarket channels beyond stationary electrical infrastructure.
| Leading Market Players |
|---|
| ABB Ltd. |
| Des-Case Corporation |
| AGM Container Controls Inc. |
| Qualitrol Corporation |
| Maschinenfabrik Reinhausen GmbH |
| Hitachi, Ltd. |
| Parker-Hannifin Corporation |
| Drytech Inc. |
| HYDAC International |
| Others |
Cost & Logistics Intelligence
Sixty-day silica gel inventory cycles at Indian state utilities compress procurement leverage for low-cost breather manufacturers, concentrating pricing power with heritage European suppliers holding pre-validated REACH dossiers. This lead-time asymmetry between raw material desiccant sourcing and finished breather delivery shapes margin structures across utility tender channels.
Pricing Analysis
Certification level creates the primary spread across breather tiers, with ISO 9001 and IEC 60695 flammability compliance commanding premium positioning in EU utility procurement. Project-based contract structures dominate transformer fleet upgrades, though regeneration-enabled systems are shifting value capture toward hardware-plus-software subscriptions. Cost compression in silica gel variants intensifies as Indian CEA-mandated tenders prioritize replacement volume over performance tier. State-owned distribution utilities exhibit acute price sensitivity, while German and Scandinavian grid operators absorb premiums for molecular sieve cold-climate reliability.
Supply Chain Analysis
Synthetic zeolite feedstock chokepoints in Germany and Belgium tether molecular sieve breather production to heritage European chemical suppliers. Desiccant chemistry draws from silicate mining operations in China, bentonite deposits in India, and specialty zeolite synthesis in Western Europe. Single-source vulnerability concentrates in REACH-compliant desiccant formulations, where substance dossier validation timelines extend eighteen months. Distribution runs through transformer OEM specification anchoring and regional electrical service firm alliances, with Parker-Hannifin's industrial filtration network penetrating North American hydraulic aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among European and Indian utilities running centralized transformer fleet modernization programs, fragmenting incumbent supplier relationships and opening specification windows for monitored breather architectures.
For Market Incumbents: Shield specification anchoring with transformer OEMs by accelerating IEC 60695 flammability certification pipelines ahead of EU F-Gas Regulation enforcement waves. Deepen backward integration into desiccant chemistry to buffer silica gel cost volatility from Indian tender compression. Prioritize regeneration-enabled system R&D to capture predictive maintenance platform revenue as German utilities pilot heated cartridge restoration. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission aligns market entry with EU F-Gas Regulation upgrade cycles. Target India's CEA-mandated moisture monitoring protocols for grid transformers above specified ratings, where smart sensor-equipped units remain underpenetrated against passive silica gel legacy install base. Partner with regional electrical service firms in Texas and California utility districts to bypass OEM-affiliated field team incumbency. For Investors and Strategic Acquirers: Long-term, this sits as a maintenance-economics transformation play because regeneration-enabled architectures are decomposing traditional consumable media replacement service models. Acquisition targets should display vertical control over REACH-compliant desiccant sourcing or embedded sensing integration capabilities. Watch German and Scandinavian utility pilot conversion rates as the inflection signal for regenerative system adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Substance Dossier Pre-Validation | Accelerates project timelines for transformer OEMs in France and Germany prioritizing compliant vendors. |
| Regeneration-Enabled System Launch | Captures predictive maintenance platform revenue as German utilities eliminate truck rolls for media swaps. |
| Regional Electrical Service Firm Alliance | Penetrates Texas and California utility districts where specialized providers compete for recurring revenue streams. |
| CEA-Mandated Smart Breather Specification | Aligns product development with India's moisture monitoring protocols conditioning tender requirements. |
| Molecular Sieve Cold-Climate Positioning | Commands specification premiums in Scandinavian sub-zero transformer installations where silica gel fails. |
Research Approach
A standing panel of transformer maintenance directors, utility procurement officers, OEM specification engineers, and aftermarket service heads provided ongoing calibration across the study duration. Primary interviews with these stakeholders combined with secondary validation from IEC standards documentation, EU F-Gas Regulation implementation reports, Indian CEA protocol filings, and trade customs data for desiccant material flows. Bottom-up unit economics triangulated against top-down transformer fleet electrification projections to anchor market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning media chemistry, system architecture, end-use duty cycles, and regional regulatory stringency clusters. CAGRs derived from utility modernization program pacing, refrigerant-phaseout mandate timelines, and cold-climate specification shift velocities. Industry-specific forecast inputs incorporated silica gel cost volatility bands and REACH compliance timeline distributions.
Underlying assumptions cover EU F-Gas Regulation enforcement continuity, Indian CEA protocol expansion scope, and synthetic zeolite supply stability, with deviation risk concentrated in desiccant material classification shifts under evolving circular-economy mandates. Practitioners should keep alternative scenarios live as regional disposal regulations for spent desiccant and flammability standard revision timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Portable Fan Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
Low Voltage Electric Motor Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
France DC Motors Market