
 North America Electrical Bushing Market | 2026-2036
North America Electrical Bushing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electrical Bushing Market Analytics
High-voltage specification upgrades is rotating demand toward extra-high-voltage and high-voltage tiers as utilities replace aging transformer infrastructure. GE Vernova leverages its vertical integration across turbine and grid hardware to capture utility procurement cycles. ABB anchors its position through R&D intensity in composite insulation systems. Siemens Energy differentiates via technology leadership in gas-insulated bushing designs for compact substations.
An electrical bushing is a hollow insulating structure that channels a conductor through a grounded barrier such as a transformer tank or circuit breaker housing, typically engineered from porcelain, polymer composites, or resin-impregnated paper with specified creepage distances and partial discharge limits. Its primary purpose is to maintain dielectric integrity while managing thermal expansion and mechanical load in high-stress electrical environments. Porcelain bushings still occupy the largest installed base across North American utilities, though polymer and composite alternatives represent the fastest-growing material category due to lighter weight and vandalism resistance. Voltage rating segmentation shows high-voltage and extra-high-voltage tiers capturing the deepest margin pools as refurbishment cycles concentrate on transmission-grade assets.
The Federal Energy Regulatory Commission and the National Electrical Safety Code shape product standards for grid-connected bushing installations across the United States, while CSA standards and provincial regulators in Ontario and Quebec govern Canadian procurement specifications. EPA rules on sulfur hexafluoride leakage intensify scrutiny of gas-insulated bushing designs and accelerate R&D into dry-air and vacuum alternatives. Stakeholders must monitor how state-level renewable portfolio standards in California, Texas, and New York reshape procurement timing for transformer and bushing bundles tied to interconnection queues.
Market Dynamics
Grid interconnection queues across Texas, California, and the Midwest are compressing procurement timelines for high-voltage transformer and bushing bundles, forcing utilities to pre-position inventory and accelerate supplier qualification cycles ahead of renewable project commissioning deadlines.
Growth Catalysts
- The Inflation Reduction Act:Direct investment into grid modernization and clean energy deployment channels federal capital toward transmission infrastructure upgrades requiring extra-high-voltage bushing specifications.
- Composite insulation systems:Polymer and resin-impregnated paper alternatives are displacing porcelain in new installations due to lighter weight, reduced maintenance burden, and vandalism resistance across utility-scale solar and wind interconnection points.
- Midwest renewable clusters:Utility-scale wind development concentrated in Iowa, Illinois, and Minnesota is generating concentrated demand for 345 kV and 500 kV bushing replacements in aging transformer fleets.
Market Restraints
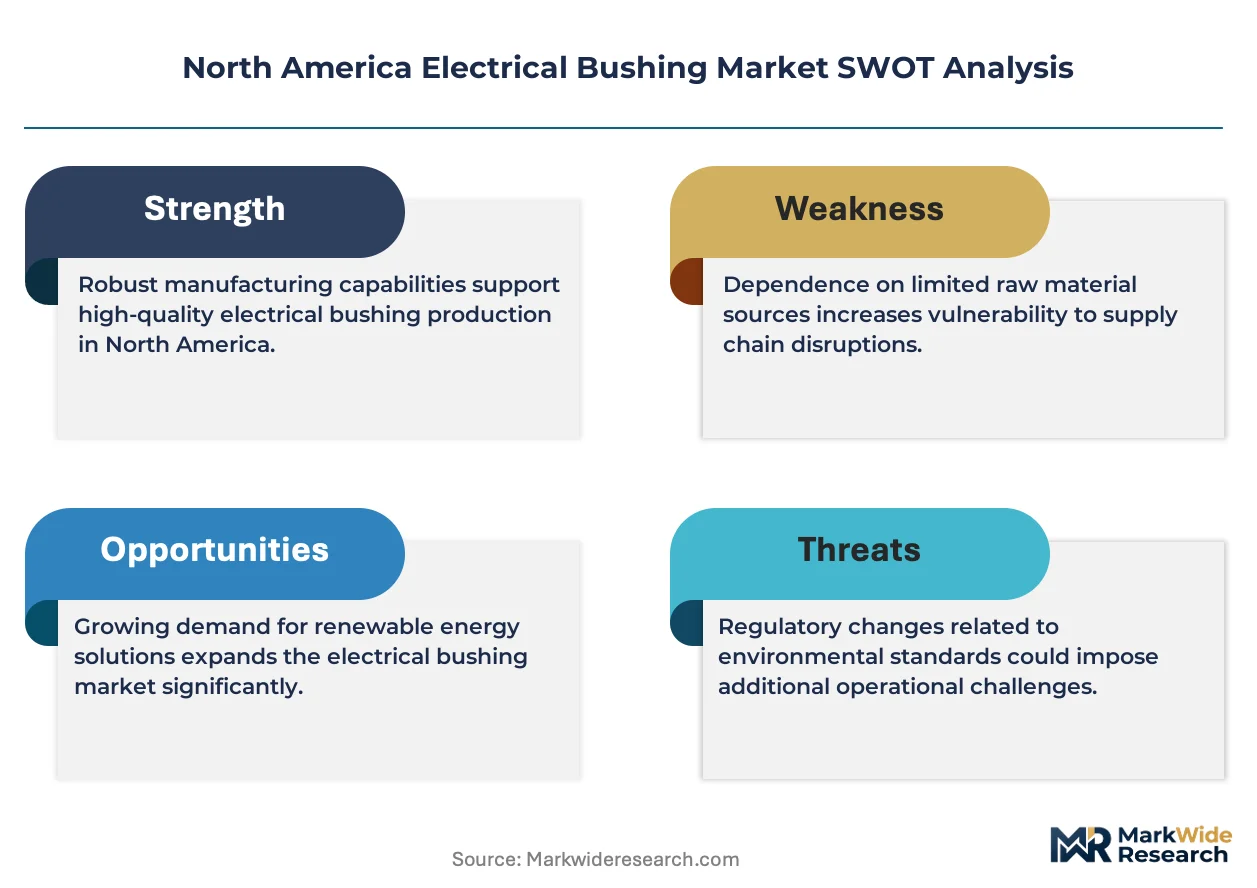
- Raw material concentration:High-purity alumina for porcelain bushings and specialized epoxy resins for composite systems face supply bottlenecks concentrated in Chinese and German chemical processing facilities.
- EPA sulfur hexafluoride regulations:Stringent leakage monitoring requirements for gas-insulated bushing designs are extending R&D timelines and elevating compliance costs for manufacturers maintaining SF6-dependent product lines.
- Skilled technician scarcity:Field installation and high-voltage testing of extra-high-voltage bushings requires specialized certification that utilities and contractors struggle to staff across rural transmission corridors.
Strategic Opportunities
- Dry-air and vacuum insulation:SF6-free bushing technologies are opening procurement pathways in California and New York where state-level decarbonization mandates accelerate green procurement preferences.
- Aftermarket service unbundling:Predictive maintenance contracts for installed bushing fleets represent recurring revenue streams as utilities defer full transformer replacement in favor of targeted bushing refurbishment.
- Canadian provincial expansion:Ontario and Quebec transmission operators are advancing interconnection capacity for hydroelectric export, creating parallel demand for cold-climate-rated composite bushings with enhanced thermal cycling performance.
Industry Challenges
- Partial discharge testing certification:Utilities are tightening acceptance criteria for factory and field testing, requiring manufacturers to invest in upgraded diagnostic equipment and technician training programs.
- Legacy porcelain compatibility:Composite bushing retrofits into existing transformer turrets demand precise dimensional matching and interface engineering that extends design cycles and complicates inventory planning.
- Interconnection queue volatility:Renewable project delays and cancellations are disrupting forecast accuracy for bundled transformer-bushing procurement, stranding capital in semi-custom inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electrical Bushing Market |
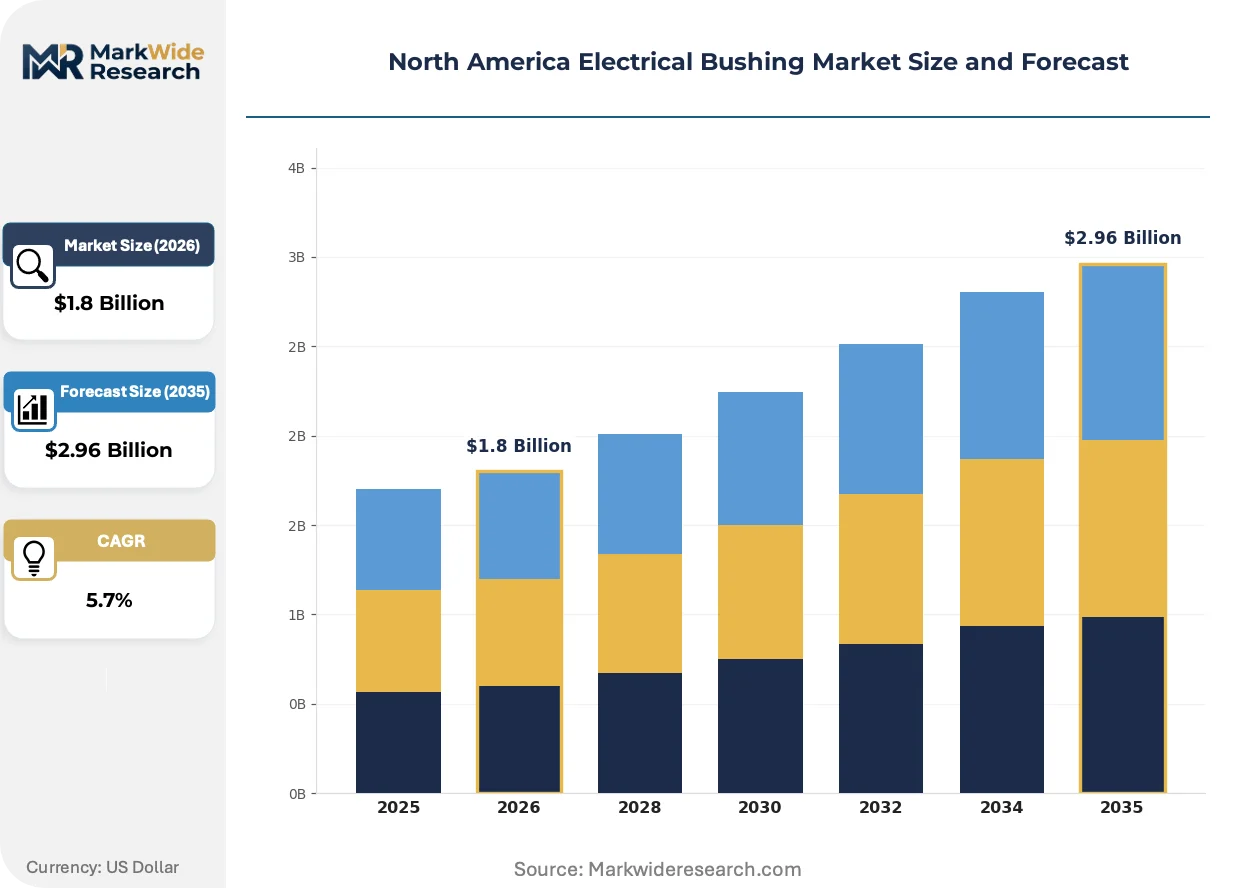
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Polymer, Composite, Glass Voltage Rating: High Voltage, Medium Voltage, Low Voltage, Extra High Voltage Installation Type: Indoor, Outdoor, Underground, Above Ground End User: Utilities, Industrial, Commercial, Renewable Energy |
| Companies Covered | GE Vernova, ABB, Siemens Energy, Eaton, Hubbell Power Systems, Nexans, Trench Group, RHM International, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electrical Bushing Market Evolving Landscape
Material science advances and regulatory pressure on insulating gases are converging to reshape product architectures across voltage tiers, while procurement compression in renewable interconnection is forcing channel restructuring.
Silicone rubber housing with fiberglass-reinforced epoxy cores is miniaturizing bushing profiles for compact gas-insulated substations without sacrificing creepage distance performance. Urban utilities in California and the Northeast are specifying these reduced-footprint designs to address land-constrained substation expansion. The technology is miniaturizing clearances between phases and grounded enclosures, enabling 50% reduction in bay spacing compared to conventional porcelain assemblies.
FERC Order 2023 interconnection reforms are standardizing study timelines and cost allocation frameworks for transmission upgrades across the United States. The rule compresses supplier qualification windows and mandates more transparent queue management, accelerating procurement decision velocity for high-voltage bushing specifications. Texas and Midwest independent system operators are adapting interconnection agreements to align with these federal timelines, forcing earlier commitment to transformer and bushing configurations.
Consolidated procurement through transmission owner joint ventures is displacing fragmented utility-by-utility purchasing for standardized 138 kV and 230 kV bushing specifications. The MISO and SPP regional transmission organizations are facilitating multi-utility volume commitments that extract pricing concessions and accelerate supplier lead times. This concentration is most visible in the Southwest Power Pool territory where cooperative procurement pools now represent over one-third of annual high-voltage bushing demand.
North America Electrical Bushing Market Segmentation
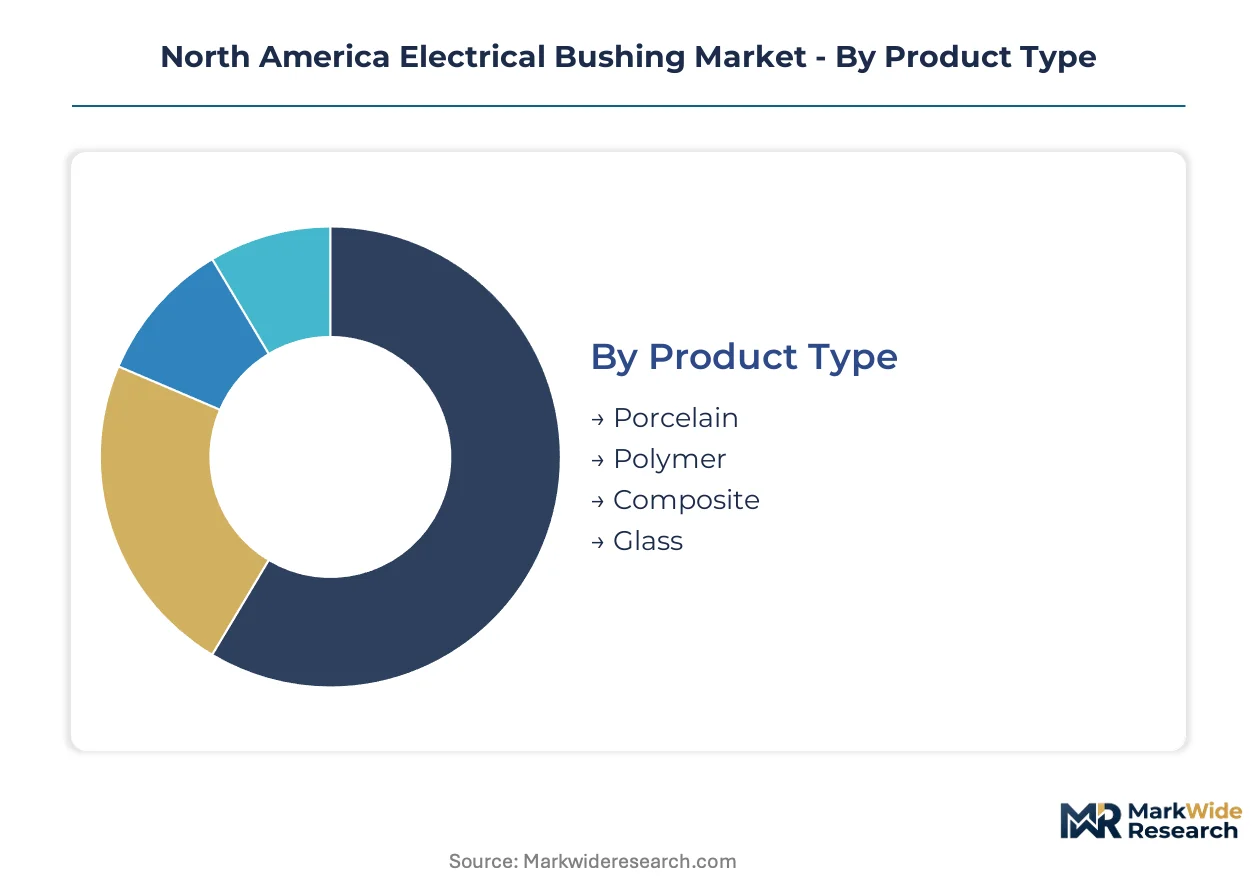
Electrical bushing procurement patterns diverge sharply across material technologies, voltage tiers, and installation environments. Understanding these splits reveals where utilities concentrate capital and where manufacturers must align R&D investments with emerging specification clusters.
Product Type:
Porcelain commands the deepest installed-base margins across North American transmission fleets, while polymer alternatives are capturing the steepest expansion trajectory in new renewable interconnection projects.
- Porcelain:Engineered from high-purity alumina ceramic with glazed surfaces and metal flange interfaces, porcelain bushings withstand extreme thermal cycling and mechanical stress. Demand concentrates in Texas and the Midwest where aging 345 kV transformer fleets require like-for-like replacements that preserve existing turret geometries and foundation anchoring.
- Polymer:Silicone rubber housings with fiberglass-reinforced epoxy cores deliver 60% weight reduction versus ceramic equivalents. California utilities and Northeast urban substations specify these for compact gas-insulated installations where seismic resilience and vandalism resistance justify premium procurement.
- Composite:Hybrid resin-impregnated paper systems with synthetic weather sheds bridge performance between porcelain longevity and polymer handling advantages. Cold-climate ratings attract Canadian hydroelectric export projects in Ontario and Quebec.
- Glass:Borosilicate and toughened glass designs occupy niche applications in specialized laboratory and testing environments with extreme chemical exposure requirements.
The dominant share belongs to Porcelain, while Polymer is closing the gap fastest.
Voltage Rating:
Specification intensity and testing certification burdens scale non-linearly with voltage tier, concentrating supplier qualification barriers in the upper ranges.
- Extra High Voltage:Ratings above 345 kV demand precision-machined grading electrodes and multi-layer insulation systems with partial discharge limits below 5 pC. Procurement clusters in Texas ERCOT zones and Midwest ISO interconnection points where 500 kV backbone expansion accommodates utility-scale wind.
- High Voltage:69 kV through 230 kV ratings serve distribution substation upgrades and regional transmission reinforcement. California IOUs and Southwest Power Pool cooperatives drive volume through bundled transformer-bushing procurement pools.
- Medium Voltage:1 kV to 69 kV specifications dominate industrial facility interconnections and commercial campus distributed generation tie-ins across manufacturing corridors.
- Low Voltage:Sub-1 kV bushings support secondary distribution transformers and pole-mounted equipment in rural cooperative networks with standardized 15 kV and 25 kV class hardware.
Extra High Voltage captures the steepest margin premiums, though High Voltage generates the largest absolute procurement volume.
Installation Type:
Environmental exposure and accessibility constraints determine material selection and maintenance protocol differentiation.
- Outdoor:Weather sheds with extended creepage distances combat pollution flashover in coastal California and Gulf Coast humidity zones. Polymer housings with hydrophobic silicone surfaces reduce contamination-induced outages.
- Indoor:Controlled-environment specifications emphasize compact dimensional envelopes for GIS bays and urban substation retrofits where real estate constraints dominate design.
- Underground:Direct-buried and vault-mounted installations in Manhattan, Chicago, and Toronto require moisture-sealed terminations with pressurized cable interfaces.
- Above Ground:Elevated structures in flood-prone regions and wildlife corridors demand mechanical reinforcement and wildlife guards.
Outdoor installations retain the largest footprint, while Indoor specifications are gaining share fastest in constrained urban markets.
End User:
Procurement sophistication and lifecycle cost horizons diverge dramatically between regulated utilities and emerging renewable developers.
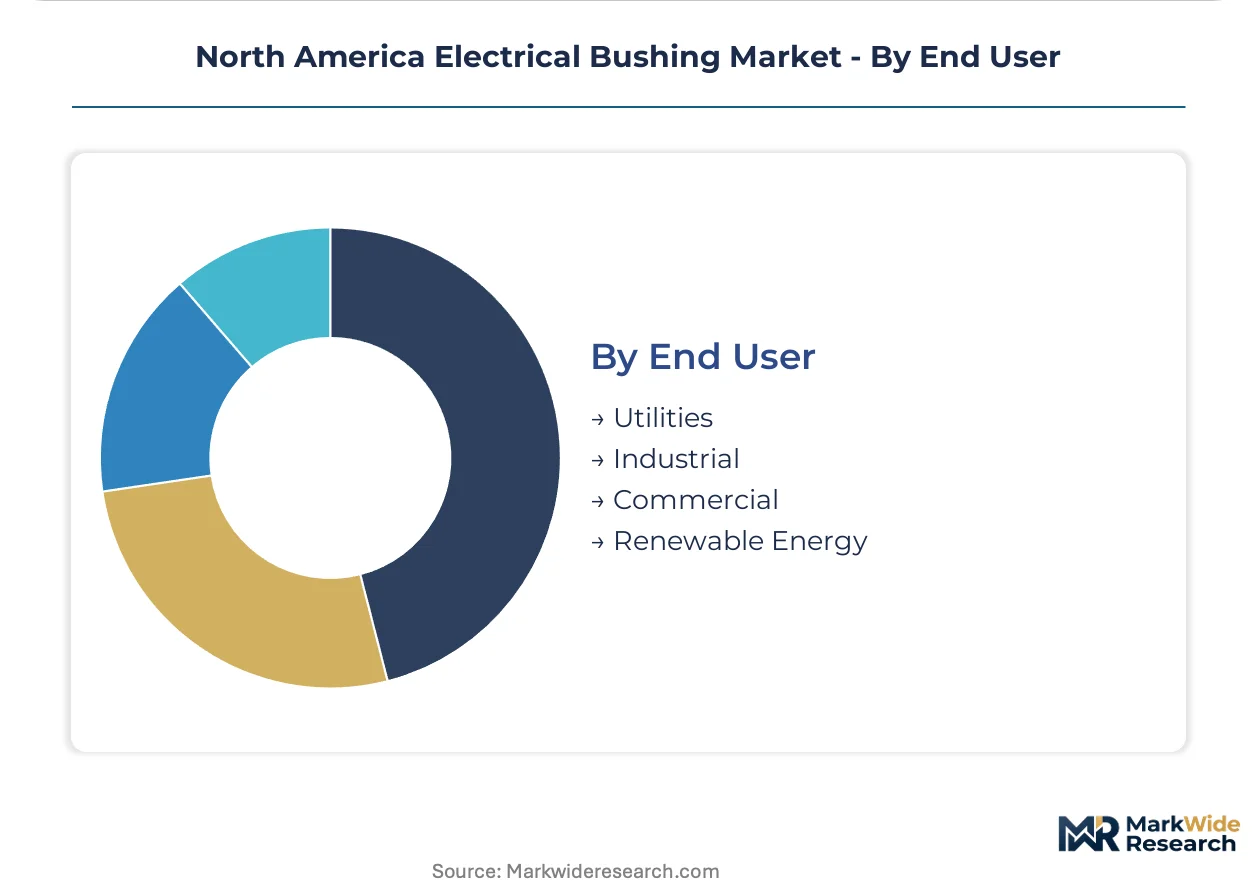
- Utilities:Investor-owned and public power entities dominate transmission-grade procurement with 40-year asset life assumptions. FERC interconnection queue compression drives advance inventory positioning.
- Renewable Energy:Solar and wind developers specify 138 kV and 230 kV bushing-transformer bundles with accelerated commissioning timelines. California and Texas interconnection clusters generate concentrated demand spikes.
- Industrial:Petrochemical, mining, and heavy manufacturing facilities specify medium-voltage bushings for captive substations with emphasis on arc-flash containment and maintenance access.
- Commercial:Data center campuses and healthcare complexes drive low-voltage and medium-voltage demand for backup power integration and on-site generation interconnection.
Utilities command the dominant procurement volume, while Renewable Energy developers are expanding their specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for specialized epoxy resins and high-purity alumina concentrates supply risk in German and Chinese chemical processing nodes, while finished bushing exports from North American manufacturers flow primarily to Canadian utility procurement pools and Mexican industrial interconnection projects.
United States
Texas ERCOT zones and California IOUs drive extra-high-voltage bushing demand through utility-scale solar and wind interconnection queues. FERC Order 2023 standardizes study timelines, compressing supplier qualification windows for 345 kV and 500 kV specifications. The Midwest ISO territory spanning Iowa, Illinois, and Minnesota generates concentrated refurbishment cycles for aging transformer fleets.
Canada
Ontario and Quebec transmission operators advance hydroelectric export capacity, creating demand for cold-climate-rated composite bushings with enhanced thermal cycling performance. CSA standards govern procurement specifications, while provincial regulators in Ontario mandate enhanced partial discharge testing protocols. Toronto and Montreal urban substations specify compact polymer designs for land-constrained GIS installations.
Mexico
Industrial corridor electrification across Nuevo León and the Bajío Region drives medium-voltage bushing demand for manufacturing facility interconnections. CFE transmission expansion programs channel investment toward 230 kV backbone reinforcement. Monterrey and Guadalajara industrial clusters specify vandalism-resistant polymer housings for exposed outdoor installations.
North America Electrical Bushing Market Competitive Landscape
Concentration sits with diversified electrical equipment conglomerates and specialized high-voltage component fabricators. Three archetypes define competitive positioning: integrated grid infrastructure suppliers with captive transformer-bushing bundling capabilities; standalone bushing specialists emphasizing material science differentiation; and regional fabricators serving utility procurement pools through cooperative purchasing agreements. Capacity expansion and strategic partnerships represent the dominant competitive moves, with joint venture structures proliferating in Texas and Midwest renewable interconnection clusters.
Among diversified electrical equipment conglomerates, GE Vernova and ABB exemplify integrated grid infrastructure positioning, while Siemens Energy occupies a distinct tier emphasizing gas-insulated system specialization. These three entities represent the archetype of suppliers capturing bundled procurement cycles through vertical control across turbine, transformer, and bushing specifications.
| Leading Market Players |
|---|
| GE Vernova |
| ABB |
| Siemens Energy |
| Eaton |
| Hubbell Power Systems |
| Nexans |
| Trench Group |
| RHM International |
| Hitachi Energy |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with transmission owner joint ventures lock in both high-purity alumina supply access and price visibility for extra-high-voltage bushing manufacturers, insulating procurement cycles from spot volatility in German and Chinese chemical processing nodes.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure with volume-tiered discounts and performance-guarantee clauses. Price differentiation separates IEC-certified premium tiers from standard NEMA-grade specifications, with customization for cold-climate ratings commanding additional premiums. Cost compression in medium-voltage tiers is intensifying because renewable developers prioritize first-cost minimization over lifecycle value. Municipal utilities exhibit the highest price sensitivity due to rate-case scrutiny, while investor-owned utilities accept premium positioning for extended warranty terms.
Supply Chain Analysis
China and Germany anchor high-purity alumina refining and specialized epoxy resin synthesis for composite insulation systems. North American bushing fabrication draws from these concentrated chemical processing hubs, with borosilicate glass and fiberglass-reinforced cores sourced from domestic specialty manufacturers. Single-source vulnerability in Chinese alumina refining creates tariff exposure and logistics chokepoint risk. Distribution runs through transmission owner cooperative procurement pools and direct OEM relationships with transformer bundlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts and refurbishment service bundles are expanding faster than hardware sales as utilities defer full transformer replacement cycles, creating a service-attach opportunity with recurring revenue characteristics.
For Market Incumbents: Fortify aftermarket service capabilities through diagnostic equipment investments and technician certification programs to capture refurbishment demand from aging porcelain installed bases. Defend margin position by accelerating dry-air and vacuum insulation R&D ahead of EPA sulfur hexafluoride enforcement tightening. Prioritize backward integration into high-purity alumina processing to reduce German and Chinese supply dependency. For New Entrants and Emerging Players: Lead with SF6-free bushing technologies targeting California and New York procurement pools where state decarbonization mandates accelerate green specification preferences. Target cold-climate-rated composite designs for Ontario and Quebec hydroelectric export expansion, the most penetrable geographic white space. Pursue joint venture structures with regional transformer OEMs to bypass lengthy utility qualification cycles. For Investors and Strategic Acquirers: Standalone bushing specialists with material science differentiation and captive composite resin formulation capabilities offer the strongest acquisition profile for grid infrastructure consolidation plays. Long-term viability hinges on exposure to transmission-grade voltage tiers and renewable interconnection queue depth rather than distribution hardware commoditization. Monitor FERC interconnection queue processing velocity as the primary inflection indicator for bundled transformer-bushing procurement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Processing | Reduces dependency on Chinese and German chemical processing nodes for porcelain feedstock. |
| SF6-Free Technology Licensing | Opens procurement pathways in California and New York under state decarbonization mandates. |
| Predictive Maintenance Platform Launch | Captures recurring revenue from utility deferred replacement cycles and diagnostic service contracts. |
| Joint Venture with Regional Transformer OEM | Accelerates utility qualification timelines for bundled bushing-transformer procurement in Texas ERCOT zones. |
| Cold-Climate Certification Investment | Enables penetration of Ontario and Quebec hydroelectric export interconnection opportunities. |
Research Methodology
Cross-validation between utility procurement officer interviews and FERC interconnection queue databases anchors the qualitative findings on demand timing and specification clustering. Primary fieldwork engaged transmission planning engineers, transformer OEM procurement leads, aftermarket service directors, and composite materials R&D specialists across the United States and Canada. Secondary validation drew from EIA transmission project databases, FERC Order 2023 implementation filings, CSA standards documentation, and EPA sulfur hexafluoride regulatory dockets. Bottom-up volume estimates from utility capital expenditure plans triangulate with top-down market sizing from equipment manufacturer revenue disclosures.
Sensitivity analysis across raw material cost scenarios and interconnection queue completion rates stress-tests the analytical framework. Segmentation modeling spans material technology, voltage rating tier, installation environment, and end-user archetype across the projection horizon. CAGRs derive from regression analysis of historical procurement cycles against renewable capacity addition trajectories. Forecast inputs incorporate Inflation Reduction Act transmission investment flows, state renewable portfolio standard compliance deadlines, and regional transmission organization interconnection reform implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained federal grid modernization funding or accelerated EPA SF6 phase-out timelines would require recalibration. Forecasts reflect documented assumptions regarding utility capital availability and renewable project developer financial commitment stability. Recalibration cycles align with material shifts in FERC interconnection queue management reforms and state-level clean energy procurement mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
Smart Heater Market
Electrical Equipment
US Electric Enclosure Market