
 Electric Capacitor Market | 2026-2036
Electric Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
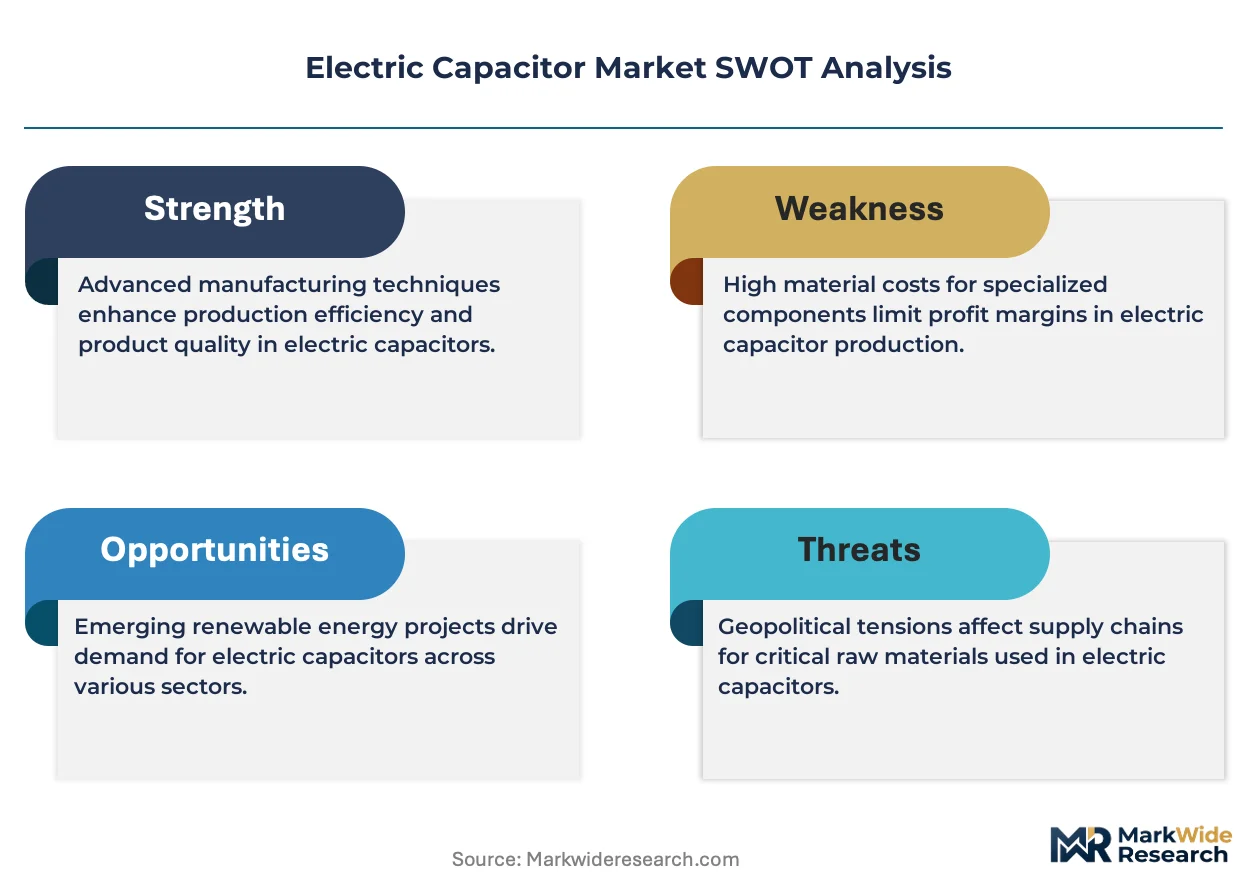
Electric Capacitor Market Analysis
Automotive OEMs is rotating procurement priority toward high-voltage DC-link capacitors as electrification programs scale. TDK Corporation leverages vertical integration in ferrite and dielectric materials to secure raw material access. Murata Manufacturing anchors ceramic capacitor supply through manufacturing scale in Japan and Southeast Asia. Samsung Electro-Mechanics competes aggressively in multilayer ceramic chip segments for mobile and computing clients.
An electric capacitor stores electrical energy in an electric field between conductive plates separated by a dielectric medium, with capacitance values spanning picofarads to thousands of farads depending on plate geometry, dielectric constant, and operating voltage. Its primary purpose is energy storage, filtering, coupling, and power conditioning across alternating and direct current circuits. Ceramic capacitors dominate unit volume in consumer electronics and telecommunications due to miniaturization trends and surface-mount compatibility. Film capacitors command premium positioning in automotive inverters and renewable energy converters where high ripple current tolerance and self-healing properties justify higher unit costs. Supercapacitors represent the fastest-expanding technology category for regenerative braking and grid frequency regulation applications requiring rapid charge-discharge cycles.
The EPA enforces material restrictions under TSCA that affect capacitor dielectric formulations, while the EU F-Gas Regulation phases down fluorinated greenhouse gases used in certain manufacturing processes. Japan's METI promotes domestic capacitor production through supply chain resilience frameworks targeting rare earth and tantalum sourcing security. Stakeholders must monitor evolving material compliance requirements across multiple jurisdictions while evaluating supercapacitor integration opportunities in heavy-duty electrification platforms.
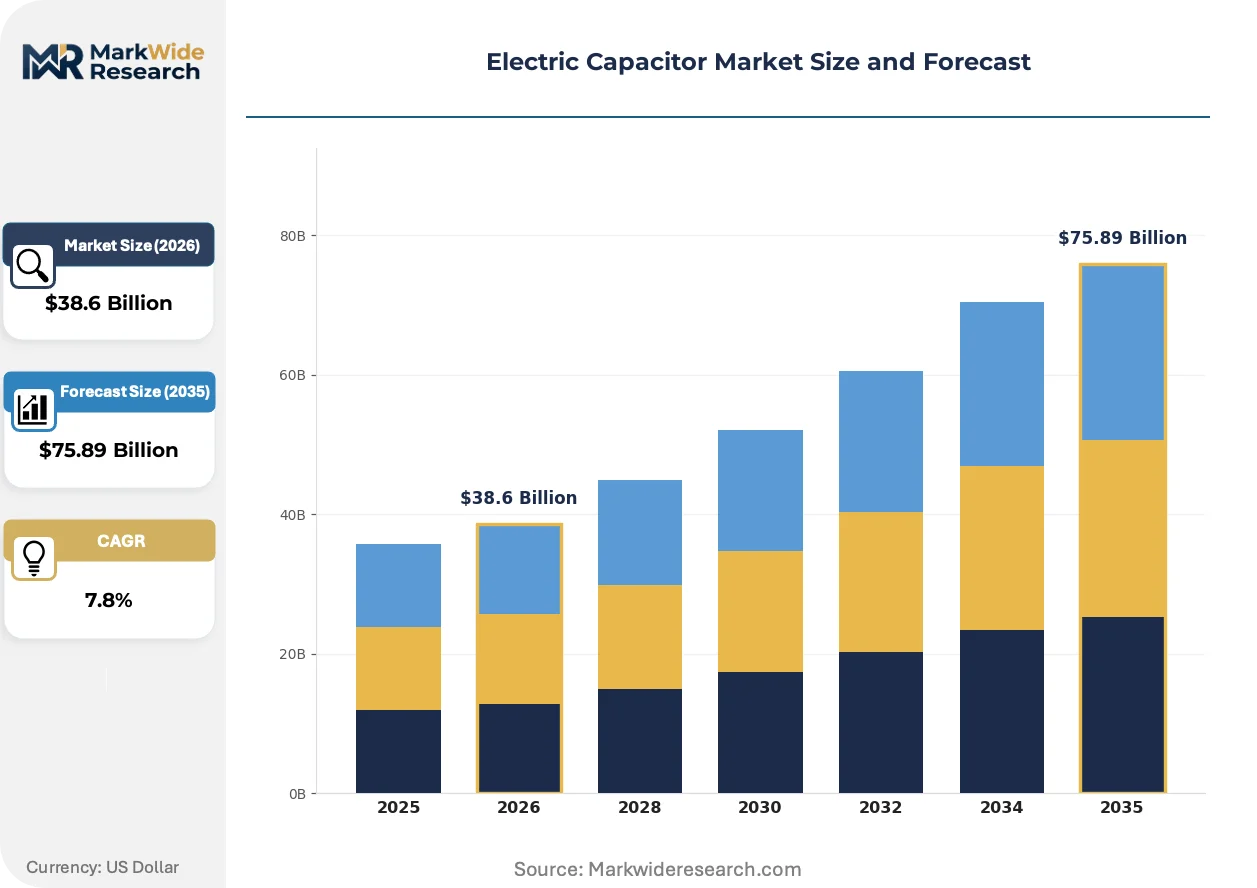
Market Dynamics
Electrification of transport and grid infrastructure is concentrating procurement toward high-voltage DC-link film capacitors, while REACH and RoHS compliance costs are compressing margins for dielectric material suppliers serving European automotive OEMs.
Growth Catalysts
- EV Inverter Demand:Battery electric vehicle production lines in China and Germany are scaling DC-link capacitor orders for 800V architectures. This pulls volume from industrial film suppliers into automotive-qualified production.
- Grid Storage Deployment:Utility-scale battery installations require power conditioning capacitors for inverter stabilization. China's dual carbon goals are accelerating procurement timelines for grid-tied film and aluminum electrolytic units.
- RoHS Material Exemptions:The EU directive's phase-out timelines for lead-containing dielectrics are forcing reformulation investments that favor suppliers with in-house ceramic powder capabilities.
Market Restraints
- Tantalum Supply Concentration:Capacitor-grade tantalum powder production concentrates in Central African mining operations and Chinese refining facilities, exposing MLCC and tantalum capacitor supply to geopolitical disruption.
- High-Voltage Film Cost Structure:Polypropylene dielectric film for DC-link applications requires biaxial orientation equipment with 24-month lead times, constraining capacity expansion for automotive-qualified grades.
- Supercapacitor Energy Density Ceiling:Activated carbon electrode technology hits physical limits around 10 Wh/kg, blocking adoption in passenger EV traction batteries despite superior cycle life.
Strategic Opportunities
- India Manufacturing Localization:The country's PLI scheme for electronic components is attracting capacitor assembly investments to serve telecom infrastructure and renewable energy converters with reduced import duties.
- Solid-State Battery Interface:Next-generation cell designs require specialized capacitors for pre-charge circuits and isolation monitoring, opening specification windows for high-reliability ceramic and film suppliers.
- EU F-Gas Phase-Down:The regulation's manufacturing process restrictions are accelerating solvent-free dielectric deposition techniques that reduce production energy intensity and qualify for green procurement tenders.
Industry Challenges
- High-Voltage Testing Talent Scarcity:Automotive DC-link qualification requires engineers experienced in partial discharge measurement and accelerated life testing under combined temperature-voltage stress, a skill set concentrated at a handful of European and Japanese testing houses.
- Multi-Jurisdiction Certification Overlap:Capacitors for medical imaging equipment must satisfy IEC 60601 safety standards alongside FDA device regulations and Japan's PMDA quality system requirements, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Capacitor Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tantalum Capacitors, Ceramic Capacitors, Aluminum Electrolytic Capacitors, Film Capacitors Application: Power Electronics, Automotive Systems, Communication Devices, Consumer Electronics Technology: Hybrid Capacitors, Supercapacitors, Traditional Capacitors, Nanocapacitors End User: Telecommunications, Aerospace, Industrial, Medical Devices |
| Companies Covered | TDK Corporation, Vishay Intertechnology, Murata Manufacturing, KYOCERA AVX, Nichicon Corporation, Panasonic Corporation, Nippon Chemi-Con Corporation, Rubycon Corporation, Samsung Electro-Mechanics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Capacitor Market Emerging Trajectories
Silicon carbide power semiconductors are forcing capacitor redesigns for faster switching frequencies, while material disclosure mandates are digitizing supply chain documentation. These shifts favor suppliers with captive dielectric production and integrated testing laboratories.
Polypropylene metallized film technology with segmented electrode patterns is displacing oil-filled paper capacitors in renewable energy inverters. Wind turbine OEMs in Denmark and Spain are specifying self-healing film units for 20-year service life. This displacement is compressing the addressable market for traditional impregnated paper dielectrics while expanding premium film capacitor margins.
Europe's F-Gas Regulation is banning fluorinated greenhouse gases in capacitor manufacturing processes by 2030. German and Italian film producers are retrofitting solvent recovery systems to maintain coating line compliance. Automotive inverter suppliers are auditing supplier F-gas inventories to preempt supply interruption.
Automotive OEMs are consolidating capacitor procurement through direct supplier contracts rather than tier-one inverter module purchases. This disintermediation is visible in German and South Korean electrification programs where battery and drivetrain divisions now specify DC-link components independently. Component suppliers are responding with dedicated automotive application engineering teams co-located near OEM technical centers.
Electric Capacitor Market Segmentation
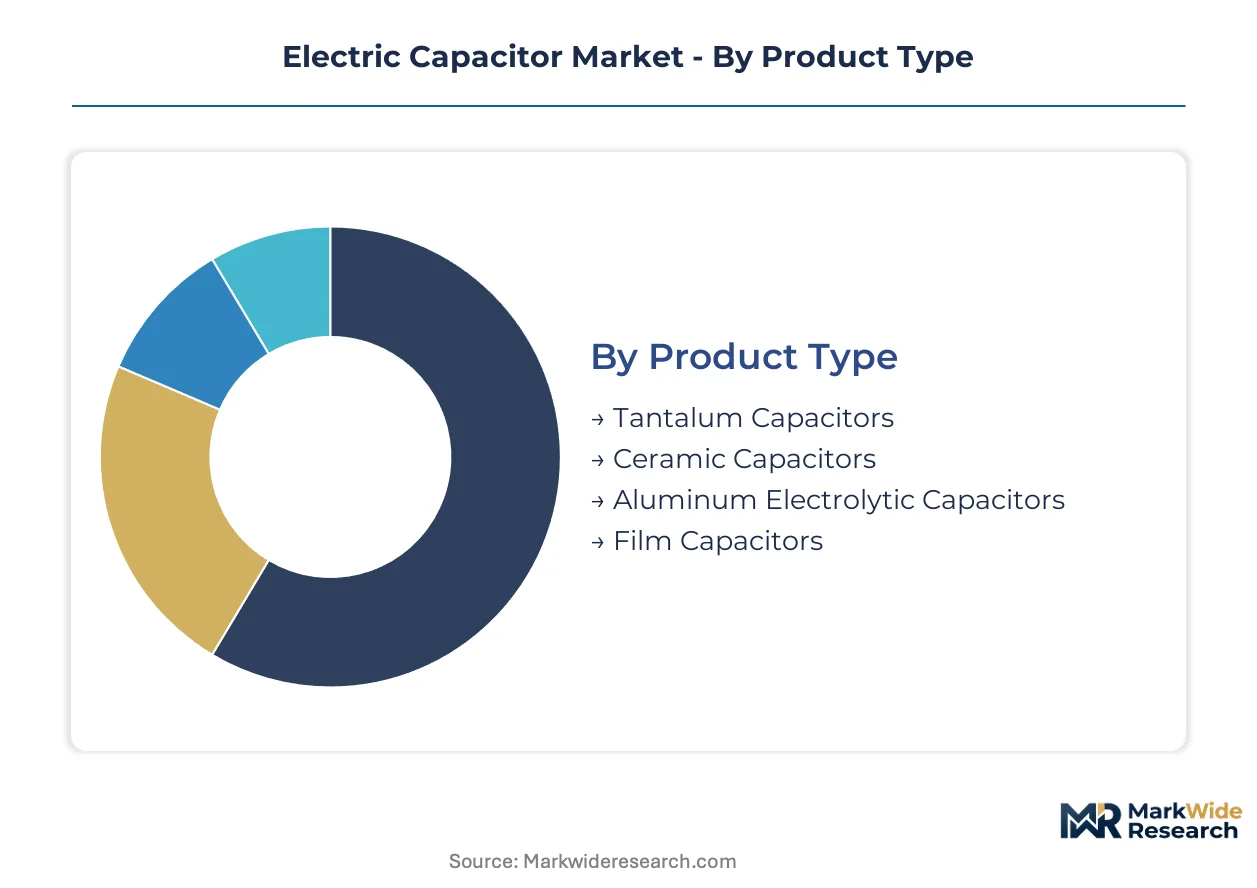
Capacitor procurement decisions hinge on dielectric material compliance with REACH and RoHS directives, while end-use voltage requirements determine whether ceramic, film, or electrolytic technologies qualify. Segmentation reveals where formulation investments concentrate and which application specifications command premium positioning.
Product Type:
REACH substance restrictions and RoHS lead exemptions differentiate capacitor dielectrics across European automotive and consumer electronics procurement.
- Ceramic Capacitors:Multilayer ceramic chip construction using barium titanate dielectrics achieves surface-mount miniaturization for mobile and computing boards. Procurement concentrates in Japan and Southeast Asia manufacturing clusters where in-house ceramic powder capabilities satisfy RoHS reformulation timelines.
- Film Capacitors:Polypropylene or polyester dielectric with metallized electrodes delivers self-healing properties and high ripple current tolerance for inverter modules. Demand is concentrating in China and Germany for 800V EV architectures where DC-link qualification requires 20-year service life specifications.
- Aluminum Electrolytic Capacitors:Liquid electrolyte systems with etched aluminum foil electrodes serve power supply filtering in industrial drives and grid-tied inverters.
- Tantalum Capacitors:Manganese dioxide or polymer cathode designs with tantalum pentoxide dielectric provide high capacitance density for aerospace and medical miniaturization.
Ceramic capacitors handle the majority of throughput; film capacitors are gaining share fastest on EV electrification pull.
Application:
Application segmentation tracks where voltage stress, thermal cycling, and reliability requirements reshape procurement specifications and supplier qualification.
- Automotive Systems:DC-link capacitors for traction inverters, onboard chargers, and DC-DC converters operate at 400V to 800V with AEC-Q200 reliability grades. German and South Korean OEMs are consolidating direct supplier contracts bypassing tier-one module manufacturers.
- Power Electronics:Filtering and snubber applications in motor drives, renewable energy converters, and uninterruptible power supplies require high ripple current endurance. China's dual carbon goals are accelerating procurement for utility-scale solar and wind installations.
- Consumer Electronics:Miniaturized multilayer ceramic chips for smartphones, laptops, and wearables prioritize footprint reduction and high-frequency response.
- Communication Devices:RF coupling and decoupling capacitors for 5G base stations and optical transceivers demand tight capacitance tolerance and low equivalent series resistance.
Automotive systems command the steepest specification escalation; power electronics is climbing fastest on grid storage deployment.
Technology:
Technology segmentation distinguishes where electrode and electrolyte innovations overcome energy density or cycle life constraints.
- Supercapacitors:Activated carbon double-layer designs with organic electrolytes achieve 10,000+ charge cycles for regenerative braking and grid frequency regulation. Deployment concentrates in heavy-duty electrification and stationary storage where rapid charge-discharge outweighs energy density limitations.
- Hybrid Capacitors:Asymmetric electrode configurations combining battery-type and capacitor-type materials bridge energy density and power density for industrial automation and backup power.
- Traditional Capacitors:Established aluminum electrolytic and ceramic architectures dominate cost-sensitive consumer and industrial applications.
- Nanocapacitors:Graphene or carbon nanotube electrode structures in early development target next-generation energy storage density breakthroughs.
Traditional capacitors retain volume leadership; supercapacitors are expanding most quickly on heavy-duty electrification adoption.
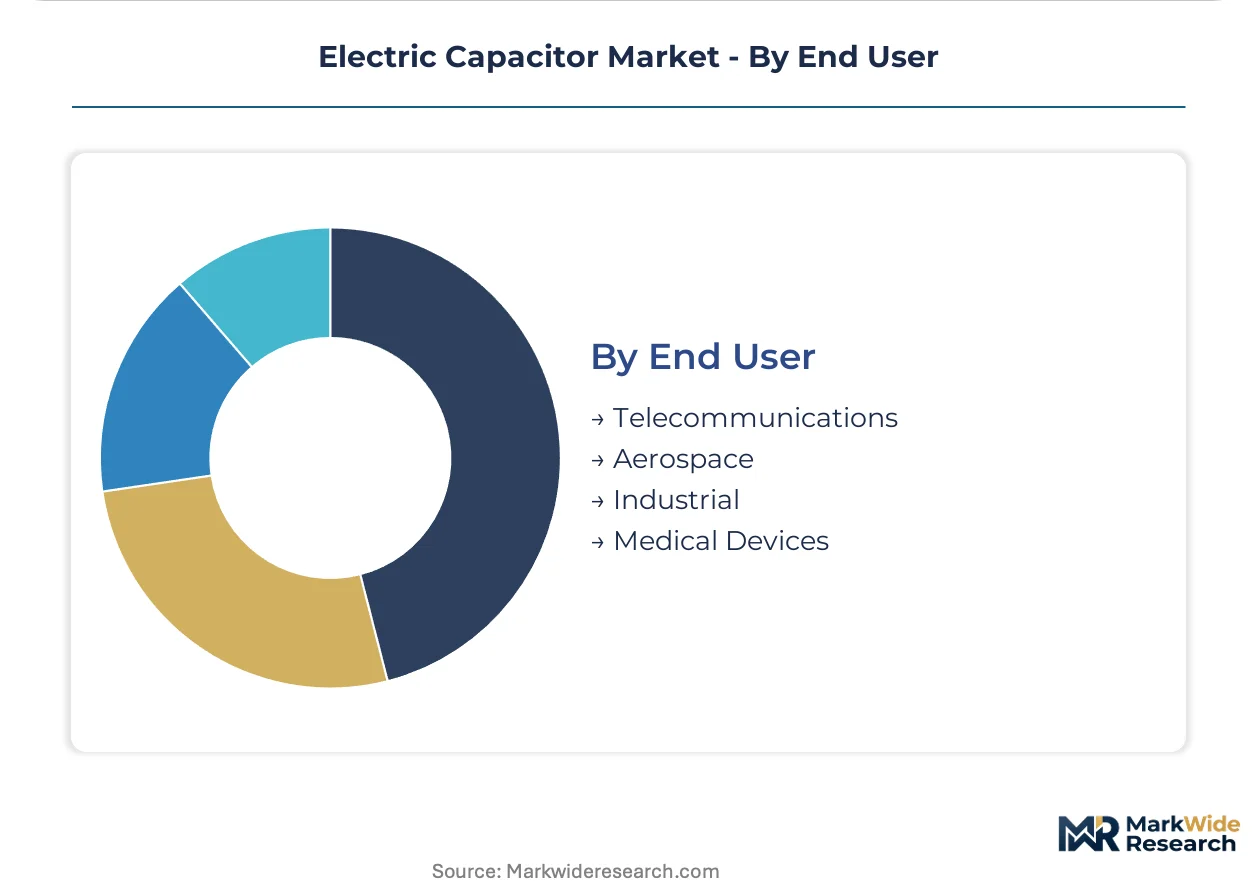
End User:
End user segmentation reflects how reliability certification, traceability, and qualification timelines fragment demand across industrial, medical, and aerospace procurement.
- Industrial:Motor drives, welding equipment, and uninterruptible power supplies require high-temperature endurance and long service life. Demand concentrates in German automation and Chinese manufacturing equipment sectors.
- Telecommunications:Base station power supplies and fiber optic infrastructure need high-reliability filtering with extended temperature range specifications.
- Aerospace:Satellites, avionics, and defense systems mandate MIL-PRF qualification with radiation tolerance and extreme temperature operation.
- Medical Devices:Implantable and imaging equipment requires IEC 60601 safety compliance alongside FDA and PMDA quality system validation.
Industrial absorbs the highest unit volume; aerospace is advancing fastest on qualification premiums and supply scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification programs and grid-scale energy storage deployments are concentrating capacitor procurement in manufacturing clusters where domestic supply chains serve high-voltage DC-link and multilayer ceramic demand.
China
Domestic capacitor production serves both consumer electronics and grid-scale energy storage applications under the MIIT's dual carbon goals framework. GB standards compliance requirements are tightening for automotive-qualified components. Manufacturing concentrates in the Yangtze River Delta and Pearl River Delta regions where integrated dielectric material supply supports 800V EV inverter programs.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are consolidating direct supplier contracts for DC-link capacitors bypassing tier-one module manufacturers. The EU F-Gas Regulation phases down fluorinated greenhouse gases in manufacturing processes by 2030. Berlin-Brandenburg hosts testing laboratories specializing in partial discharge measurement for high-voltage qualification.
Japan
METI promotes domestic capacitor production through supply chain resilience frameworks targeting rare earth and tantalum sourcing security. Kanto and Kansai regions anchor ceramic powder and film dielectric manufacturing. Aichi Prefecture's industrial corridor concentrates application engineering teams co-located with automotive OEM technical centers.
United States
EPA enforcement of TSCA material restrictions affects capacitor dielectric formulations for industrial and automotive clients. The Southeast region attracts assembly investments serving telecom infrastructure with reduced logistics costs. Texas and Michigan host power electronics clusters demanding high ripple current tolerance for renewable energy converters.
South Korea
Battery and drivetrain divisions at domestic OEMs specify DC-link components independently under electrification program scale-up. MFDS quality system requirements extend validation timelines for medical imaging capacitor applications. Gyeonggi Province manufacturing complexes serve mobile and computing clients with multilayer ceramic chip supply.
Electric Capacitor Market Vendor Landscape
Player mix skews toward vertically integrated material specialists and scale-driven ceramic manufacturers with captive dielectric production. The vendor base separates into three tiers: premium automotive-qualified suppliers, high-volume consumer electronics fabricators, and niche tantalum or supercapacitor specialists. Consolidation pressures favor backward integration into ferrite and ceramic powder supply. Capacity expansion and geographic diversification represent the dominant competitive moves as procurement regionalizes.
Among Japanese fabricators, TDK Corporation, Murata Manufacturing, and Nichicon Corporation exemplify the vertically integrated archetype with upstream control over critical raw materials. These entities occupy positions where in-house ceramic powder capabilities satisfy RoHS reformulation timelines and REACH substance disclosure requirements. Samsung Electro-Mechanics anchors the scale-driven tier competing aggressively in multilayer ceramic chip segments. KYOCERA AVX and Vishay Intertechnology sit within the premium-qualified supplier category serving automotive and aerospace certification requirements.
| Leading Market Players |
|---|
| TDK Corporation |
| Vishay Intertechnology |
| Murata Manufacturing |
| KYOCERA AVX |
| Nichicon Corporation |
| Panasonic Corporation |
| Nippon Chemi-Con Corporation |
| Rubycon Corporation |
| Samsung Electro-Mechanics |
| Others |
Supply Flow & Price Mechanics
Polypropylene metallized film displacement of oil-filled paper dielectrics in renewable energy inverters simultaneously concentrates supply geography around German and Italian coating facilities while compressing margins for legacy paper capacitor producers unable to qualify for 20-year wind turbine service specifications.
Pricing Analysis
Current-generation DC-link film capacitors for 800V EV architectures command substantial premiums over prior-generation 400V units and next-generation silicon carbide-optimized designs still in qualification. Three-tier pricing structure across automotive-qualified premium, industrial-standard, and consumer-economy levels separates AEC-Q200 certified suppliers from commodity ceramic fabricators. Price differentiation hinges on certification grade and volume scale, with automotive OEM direct contracts squeezing tier-one module supplier margins. Pricing pressure stems from REACH reformulation costs passed through European supply chains, while consumer electronics buyers exhibit highest price sensitivity and aerospace medical device buyers show lowest.
Supply Chain Analysis
Inventory accumulation at biaxial orientation equipment manufacturers stretches lead times for automotive-qualified polypropylene film to 24 months, constraining capacity expansion. Supply concentrates in China, Japan, and Germany for ceramic powder, film coating, and automotive qualification testing respectively. Raw material dependencies draw from tantalum pentoxide for high-density aerospace applications, barium titanate for multilayer ceramic chips, and polypropylene resin for DC-link film substrates. Single-source vulnerability in Central African tantalum mining operations exposes MLCC supply to geopolitical disruption. Distribution runs through direct OEM contracts consolidating in German and South Korean electrification programs, supplemented by tier-one inverter module procurement for smaller automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric capacitor market sits in early-cycle recovery as EV production scaling and grid storage deployment create sustained demand pull after capacity rationalization during the prior downcycle.
For Market Incumbents: Shield market position by deepening backward integration into ceramic powder and ferrite supply to satisfy RoHS reformulation timelines without margin erosion from external material suppliers. Prioritize capacity addition in Yangtze River Delta manufacturing clusters to serve China's dual carbon goals procurement acceleration. Defend against emerging supercapacitor specialists by embedding application engineering teams within German and South Korean OEM technical centers for DC-link specification lock-in. For New Entrants and Emerging Players: Anchor in India's PLI scheme for electronic components assembly to serve telecom infrastructure and renewable energy converters with reduced import duty access to domestic demand. Target white-space in solvent-free dielectric deposition equipment retrofitting for EU F-Gas Regulation compliance, where German and Italian film producers face 2030 phase-down deadlines. Pursue qualification partnerships with Berlin-Brandenburg testing laboratories specializing in partial discharge measurement to overcome high-voltage testing talent scarcity barriers. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors vertically integrated material specialists with captive dielectric production and integrated testing laboratories. Long-term viability over the next decade rests on securing rare earth and tantalum sourcing security through supply chain resilience frameworks. Acquisition target archetype: mid-cap film capacitor producers with automotive qualification infrastructure but limited geographic diversification. The signal to watch is biaxial orientation equipment order books at German and Japanese machinery suppliers as inflection indicator for polypropylene film capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Supply | In-house barium titanate production secures RoHS compliance timelines against REACH substance disclosure requirements. |
| Automotive Application Engineering Co-location | Teams embedded in Aichi Prefecture and Bavaria technical centers capture DC-link specification windows early. |
| Solvent-Free Dielectric Deposition Retrofit | Coating line upgrades qualify for EU green procurement tenders under F-Gas Regulation phase-down mandates. |
| India PLI Scheme Manufacturing Localization | Assembly investments serve telecom infrastructure with reduced import duties under DGFT tariff structures. |
| High-Voltage Testing Laboratory Partnership | Berlin-Brandenburg partial discharge measurement access overcomes automotive qualification talent scarcity constraints. |
Methodological Framework
A spread of perspectives from capacitor procurement managers at automotive OEMs, dielectric material R&D directors, high-voltage testing engineers, and grid storage EPC contractors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against MIIT dual carbon policy documents, EPA TSCA enforcement records, EU F-Gas Regulation implementation guidance, and customs trade data for capacitor-grade tantalum powder shipments. Bottom-up unit demand modeling for EV inverter, renewable energy converter, and consumer electronics applications triangulated against top-down market value reconstruction.
Segmentation dimensions modeled span dielectric material type, voltage rating tier, end-use application, and geographic regulatory cluster across the analysis window. CAGRs derive from installed base growth rates, content-per-vehicle expansion for 800V architectures, and utility-scale solar and wind deployment pipelines. Forecast inputs incorporate silicon carbide power semiconductor adoption curves affecting capacitor switching frequency requirements and solid-state battery interface specification evolution.
Decision-makers should treat outputs as directional under assumptions of sustained EV electrification program funding and stable tantalum supply from Central African mining operations; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Electronic Wipe Market
Electronic Components
Intel Motherboards Market
Electronic Components
GPIO Expanders Market
Electronic Components
Switch Diode Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Film Capacitor Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Impulse Relays Market
Electronic Components
Global Capacitor Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Motherboard Battery Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Display Port Adapters Market
Electronic Components
Microspeaker Market