
 France DC Motors Market | 2026-2036
France DC Motors Market Size, Share, and Industry Trends Forecast 2026-2036
France DC Motors Market Insights
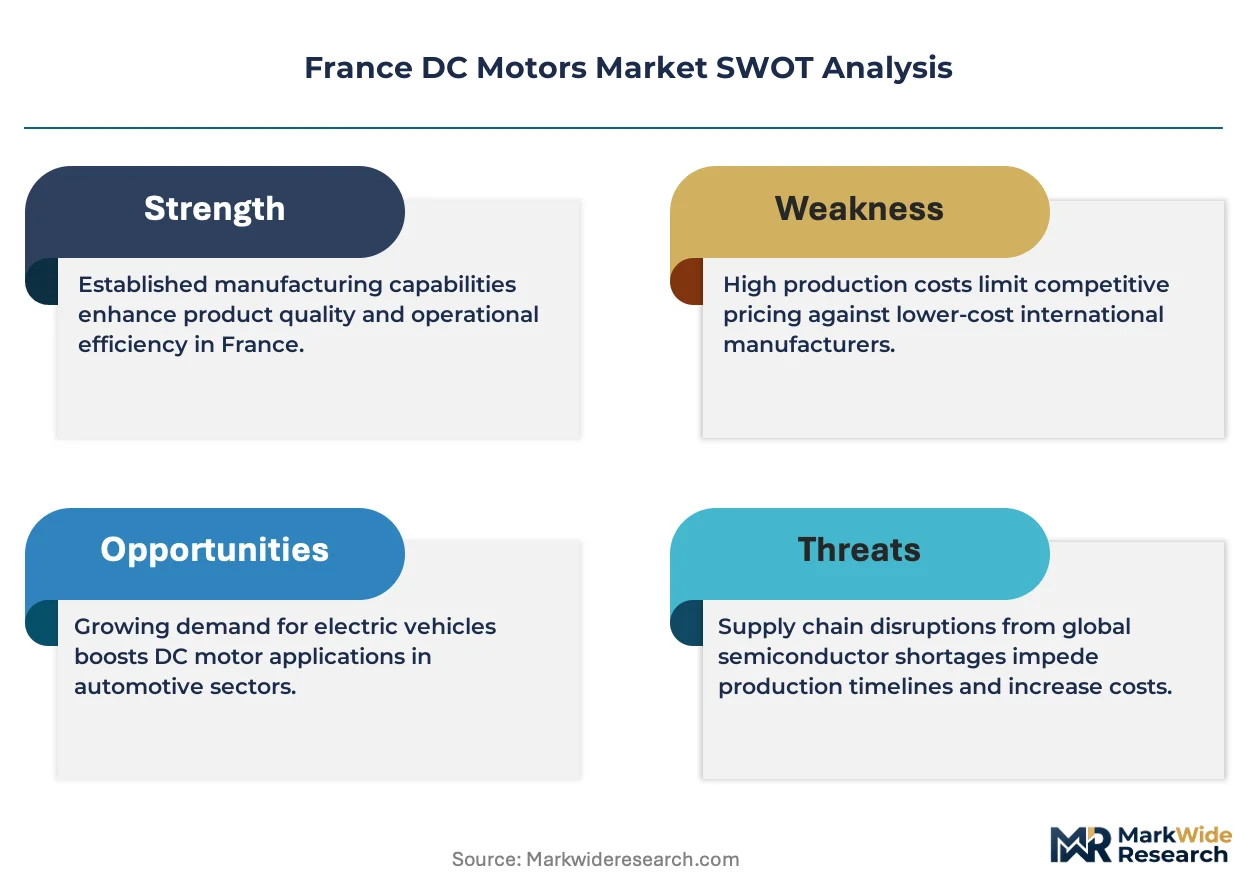
The EU F-Gas Regulation is rebalancing the cost-of-entry calculus for motor suppliers serving climate-controlled industrial applications. Nidec Corporation leverages its vertical integration in precision magnetics to sustain premium positioning across French robotics OEM channels. ABB Limited anchors its competitive stance through digital motor-drive integration that extends beyond hardware into predictive maintenance ecosystems. Faulhaber France SAS differentiates via micron-level motion control specialization that dominates medical device and optical instrumentation segments.
France DC motors are electromechanical machines converting direct current electrical energy into mechanical rotation through commutation between stationary field windings or permanent magnets and rotating armature conductors, with brushless variants achieving efficiencies exceeding ninety percent through electronic commutation eliminating mechanical brush-arc losses. Their primary industrial purpose centers on precision speed-torque control in automated manufacturing, electric vehicle subsystems, and servo-positioning equipment where variable load response exceeds alternating current motor capability. Brushless DC motors lead the product type landscape as permanent magnet material improvements and integrated drive electronics displace brushed architectures across automotive thermal management and industrial servo applications. Robotics represents the fastest-expanding application segment as French collaborative automation deployments in Burgundy and Auvergne-Rhône-Alpes manufacturing basins concentrate demand for compact, high-torque-density motor solutions.
ANSM and CNIL oversight intersects with DC motor markets where medical device motor certification and connected motor data governance impose parallel compliance burdens on suppliers targeting French healthcare automation. The EU Green Deal's extended efficiency requirements through Ecodesign for Sustainable Products Regulation are forcing motor manufacturers to document full lifecycle carbon footprints and material circularity credentials for market access. Stakeholders must monitor how France's national low-carbon strategy implementation tightens embodied carbon thresholds for imported motor components ahead of anticipated EU carbon border adjustments.
Market Dynamics
The EU Green Deal's Ecodesign for Sustainable Products Regulation is forcing French motor suppliers to reengineer supply chains around embodied carbon documentation and rare earth circularity, compressing margins for importers while advantaging vertically integrated domestic producers with captive magnet recycling capabilities.
Growth Catalysts
- Automotive Electrification Mandates:French OEM thermal management programs are specifying brushless DC architectures for battery cooling pumps and HVAC compressors, displacing belt-driven systems.
- Île-de-France Aerospace Cluster:Precision manufacturing around Paris-Saclay concentrates demand for micron-level servo motors in satellite positioning and optical instrumentation.
- EU F-Gas Regulation:Climate-controlled industrial applications are rebalancing motor efficiency requirements as refrigeration system electrification accelerates.
Market Restraints
- Neodymium Price Volatility:Permanent magnet raw material costs fluctuate with Chinese export quotas, squeezing margins for brushless motor assemblers lacking long-term supply contracts.
- Technical Talent Scarcity:Embedded motor control firmware expertise concentrates in Toulouse and Grenoble, creating hiring bottlenecks for robotics startups in peripheral regions.
- REACH Compliance Burden:Substance restriction documentation requirements for copper windings and insulation coatings add administrative overhead for small-batch medical motor suppliers.
Strategic Opportunities
- Auvergne-Rhône-Alpes Collaborative Robotics:Burgundy manufacturing basins underpenetrated by high-torque-density compact motor vendors represent whitespace for localized assembly operations.
- Medical Device Certification Premium:ANSM Class IIa motor certification creates pricing power for suppliers mastering biocompatibility and electromagnetic compatibility documentation.
- Digital Twin Integration:Predictive maintenance ecosystems are converging with motor-drive hardware, enabling recurring revenue models beyond unit sales.
Industry Challenges
- Legacy System Integration Friction:Retrofitting brushless architectures into existing French automotive stamping lines requires custom mechanical adapters and control protocol translation.
- CNIL Data Governance Complexity:Connected motor telemetry streams in healthcare automation trigger parallel compliance audits alongside ANSM device certification, extending time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France DC Motors Market |
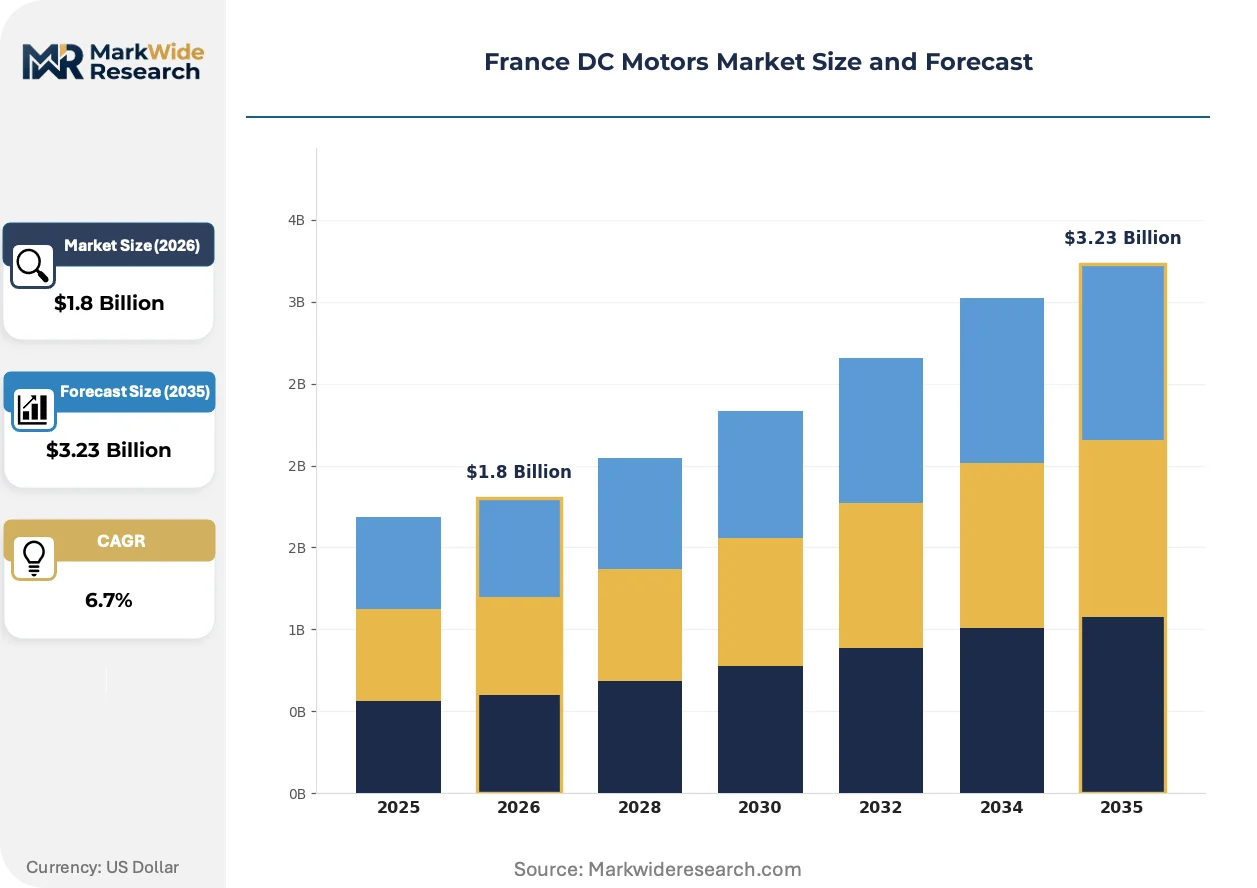
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushed, Brushless, Coreless, Stepper Application: Automotive, Industrial Equipment, Consumer Electronics, Robotics End User: Manufacturers, OEMs, Distributors, Repair Services Technology: Analog, Digital, Hybrid, IoT-enabled |
| Companies Covered | Nidec Corporation, Bühler Motor GmbH, ABB Limited, Faulhaber France SAS, Maxon, AMETEK Inc., Siemens AG, Orbex Group, T-T Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France DC Motors Market Trends and Innovations
Electronic commutation architectures are displacing mechanical brush systems across French industrial automation, while integrated drive electronics compress the traditional motor-drive-controller stack into single-package solutions.
Silicon carbide (SiC) power semiconductors are integrating into brushless DC motor drives, enabling switching frequencies above 100 kHz that reduce current ripple and acoustic noise. French automotive Tier-1 suppliers are adopting SiC-based thermal management motors for next-generation electric vehicle platforms. This integration is collapsing the historical separation between motor winding design and inverter topology optimization.
The EU Ecodesign for Sustainable Products Regulation is mandating full lifecycle carbon footprint disclosure for industrial motors above 750W, requiring suppliers to document upstream mining emissions and end-of-life recycling pathways. French motor assemblers are responding by qualifying European-sourced rare earth alternatives and investing in magnet disassembly robotics. Medical device and aerospace segments face the steepest documentation burdens due to traceability requirements.
Outcome-based service contracts are displacing traditional equipment procurement in French manufacturing, with motor suppliers retaining ownership and charging per operating hour. Automotive OEMs in Hauts-de-France are piloting this model for conveyor system motors, transferring maintenance risk to vendors. The shift compresses upfront capital requirements for buyers while demanding predictive analytics capabilities from suppliers.
France DC Motors Market Segmentation
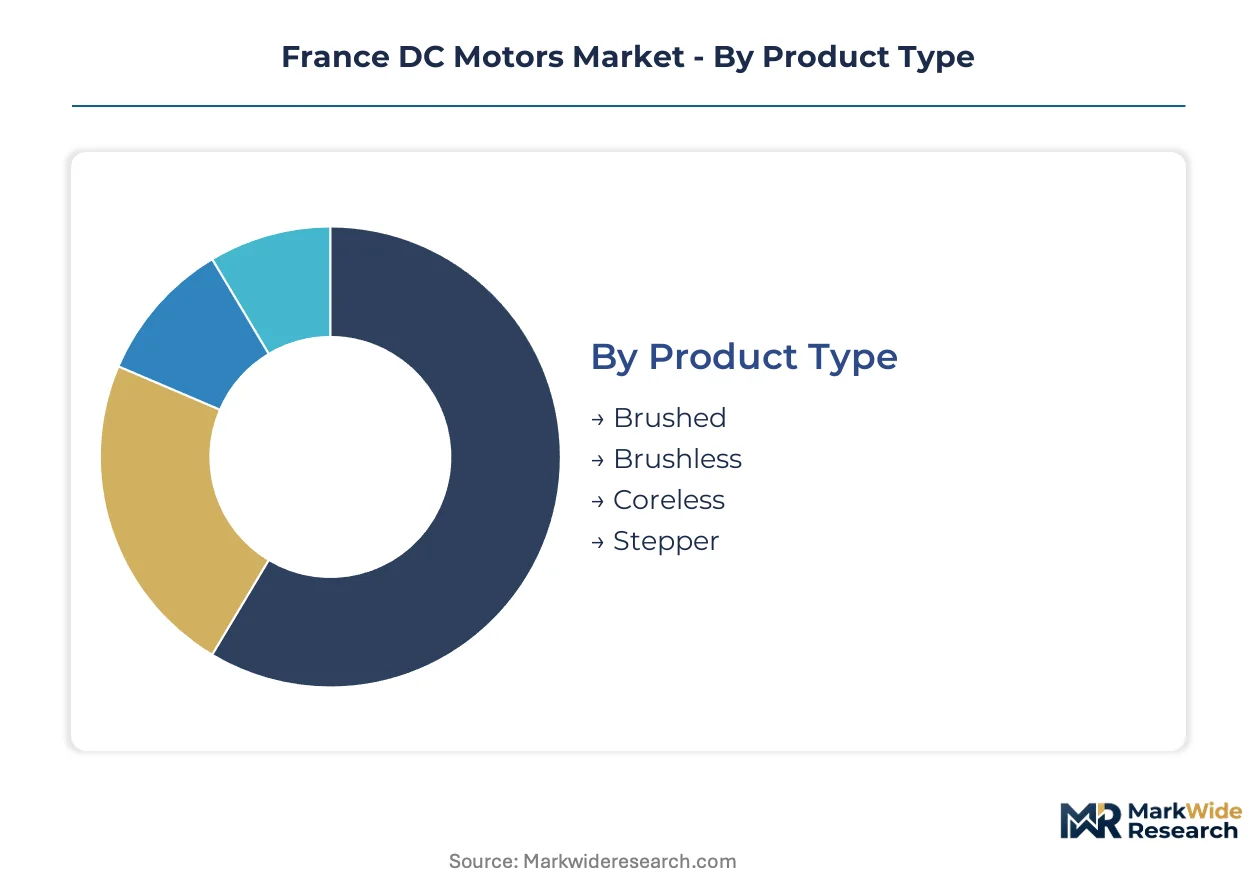
Segmentation in the France DC Motors Market reveals how procurement priorities diverge across precision-demanding aerospace applications versus cost-sensitive automotive thermal management. Understanding these fault lines enables suppliers to align R&D investment with margin concentration points.
Product Type:
Buyers select motor architectures based on lifecycle cost calculations weighing efficiency gains against upfront magnet material premiums.
- Brushless:Electronic commutation eliminates mechanical brush-arc losses, achieving efficiencies exceeding ninety percent. Demand concentrates in Île-de-France aerospace clusters where satellite positioning systems require maintenance-free operation over decade-long orbital missions. The EU Green Deal's Ecodesign mandates tighten embodied carbon thresholds, advantaging brushless architectures with documented rare earth circularity.
- Brushed:Mechanical commutation via carbon brushes delivers cost-effective torque control for intermittent-duty applications. Procurement in Auvergne-Rhône-Alpes manufacturing basins favors brushed motors for legacy conveyor retrofits where capital constraints override efficiency premiums.
- Coreless:Eliminated iron cores reduce rotor inertia for sub-millisecond acceleration response in medical device pumps and optical instrumentation.
- Stepper:Discrete angular positioning without feedback sensors dominates CNC machining and 3D printing equipment in Burgundy industrial zones.
Volume sits with Brushed motors in legacy industrial retrofit; growth tilts toward Brushless as automotive electrification mandates accelerate.
Application:
Application selection tracks the density of precision manufacturing versus commodity assembly within French industrial geography.
- Robotics:Collaborative automation deployments in Burgundy and Auvergne-Rhône-Alpes concentrate demand for compact, high-torque-density solutions. French OEMs specify integrated motor-drive packages to reduce cabinet footprint in cobot joints.
- Automotive:Battery cooling pumps and HVAC compressors displace belt-driven systems under French OEM thermal management programs. Brushless architectures dominate new platform specifications, though legacy stamping lines create retrofit friction.
- Industrial Equipment:Servo-positioning systems in Paris-Saclay precision manufacturing require micron-level repeatability for semiconductor handling.
- Consumer Electronics:Miniaturized vibration motors and camera autofocus drives face price compression from Asian contract manufacturers.
Automotive commands procurement volume; Robotics climbs fastest as collaborative automation penetrates underinvested manufacturing basins.
End User:
Channel selection reflects technical support requirements and batch size economics across the French motor value chain.
- OEMs:Direct relationships with French automotive and aerospace primes enable co-development of application-specific winding configurations. Long-term supply agreements lock in magnet pricing, insulating against neodymium volatility.
- Manufacturers:In-house motor production for captive equipment demands firmware expertise concentrated in Toulouse and Grenoble engineering clusters.
- Distributors:Stocking brushless and stepper variants for MRO channels in peripheral regions faces working capital constraints from rare earth price swings.
- Repair Services:Rewinding operations for industrial motor refurbishment compete with replacement cost curves as Chinese imports compress new motor pricing.
OEMs anchor volume through platform-level integration; Repair Services gain traction as circular economy mandates extend equipment lifecycles.
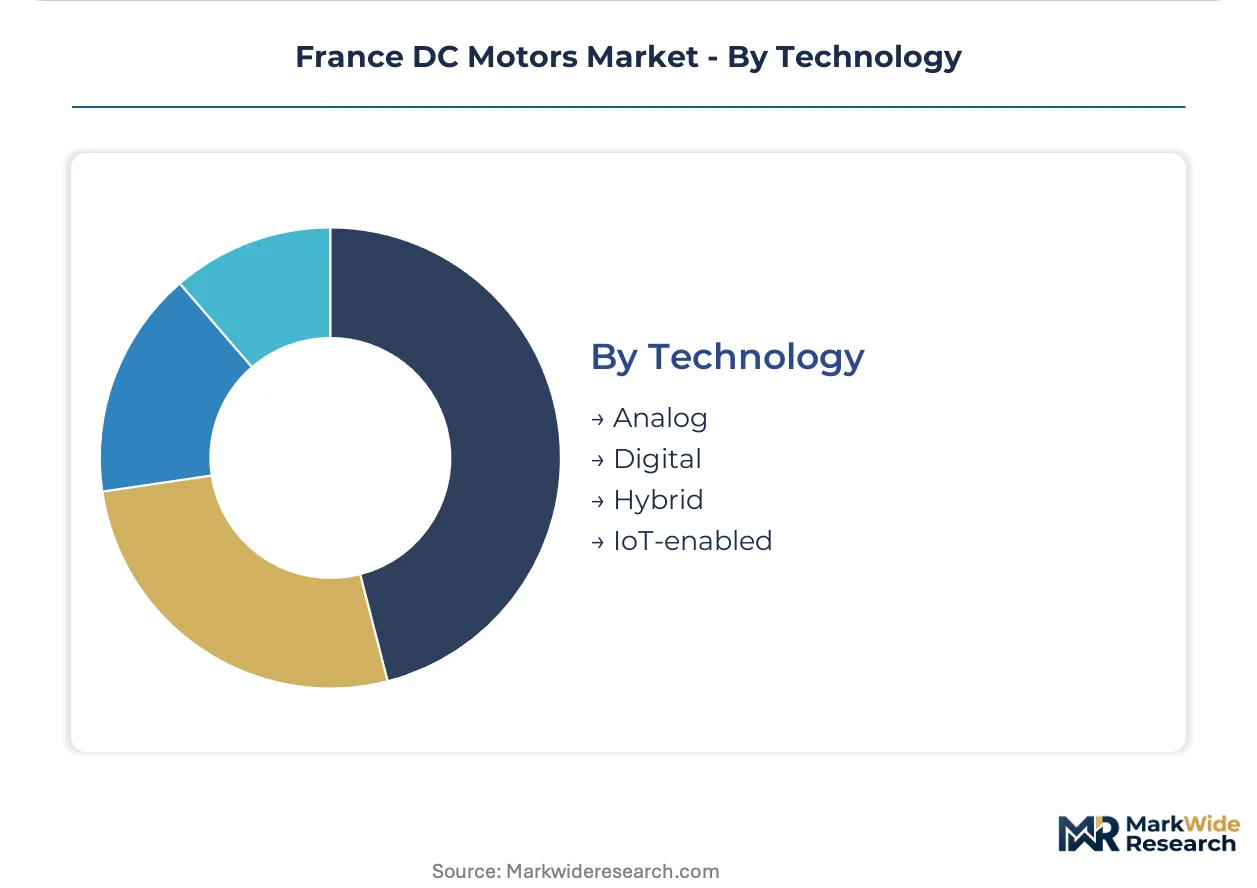
Technology:
Technology adoption correlates with connectivity infrastructure maturity and predictive maintenance capability investment.
- IoT-enabled:Embedded torque and temperature telemetry streams enable condition-based maintenance contracts. CNIL data governance requirements complicate deployment in healthcare automation, extending ANSM certification timelines.
- Digital:Field-oriented control algorithms implemented on ARM-based drive electronics displace analog servo loops in French machine tool retrofits.
- Hybrid:Mixed-signal architectures bridge legacy analog position feedback with digital network interfaces for incremental upgrade paths.
- Analog:Proportional control via operational amplifier circuits persists in cost-constrained medical device pumps where electromagnetic compatibility certification costs dominate redesign economics.
Digital implementations hold current volume; IoT-enabled systems expand most quickly as outcome-based service models displace equipment sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Parc d'Activités de Paris-Saclay drives motor supplier concentration through R&D tax credits and proximity to aerospace primes. The EU Green Deal's territorial implementation varies sharply across French industrial basins.
Île-de-France
Satellite positioning systems and optical instrumentation demand maintenance-free brushless architectures with decade-long reliability. ANSM medical device certification requirements intersect with CNIL data governance for connected motors in healthcare automation. Paris-Saclay's precision manufacturing cluster concentrates procurement for micron-level servo motors in semiconductor handling equipment.
Auvergne-Rhône-Alpes
Collaborative robotics deployments in Lyon and Grenoble manufacturing zones concentrate demand for compact high-torque-density solutions. The EU Ecodesign for Sustainable Products Regulation tightens embodied carbon thresholds for industrial motors above 750W. Embedded motor control firmware expertise concentrates in Grenoble engineering clusters, creating hiring bottlenecks for robotics startups.
Hauts-de-France
Automotive OEM thermal management programs specify brushless DC architectures for battery cooling pumps and HVAC compressors. France's national low-carbon strategy implementation tightens embodied carbon thresholds for imported motor components. Assembly operations in this northern basin pilot outcome-based service contracts for conveyor system motors.
Provence-Alpes-Côte d'Azur
Aerospace subcontracting networks around Marseille and Toulon sustain demand for precision motion control in satellite component testing. REACH compliance documentation for copper windings and insulation coatings adds administrative overhead for small-batch suppliers. Toulouse engineering talent pools support firmware development for digital motor-drive integration.
Burgundy
Underpenetrated manufacturing basins represent whitespace for localized motor assembly operations serving collaborative automation. The EU F-Gas Regulation rebalances efficiency requirements as refrigeration system electrification accelerates. Dijon-based industrial equipment retrofits favor brushed motors where capital constraints override efficiency premiums.
France DC Motors Market Competitive Landscape
Japanese and German producers anchor one tier; French specialists and Swiss precision houses hold differentiated positions in medical and aerospace channels. The vendor base stratifies across integrated multinationals with captive magnet recycling, mid-scale regional assemblers, and micron-level motion control boutiques. Three archetypes dominate: vertically integrated rare earth processors, digital twin platform operators, and certification-heavy medical device motor specialists. Competitive moves center on magnet supply contract locking and predictive maintenance ecosystem bundling.
Among the integrated multinational tier, Nidec Corporation and ABB Limited exemplify divergent strategic postures. Nidec represents upstream magnetics control, while ABB anchors digital motor-drive convergence beyond hardware into service revenue models. Faulhaber France SAS occupies the precision-specialist position, with its domestic SAS structure signaling embedded regulatory navigation for ANSM and CNIL compliance burdens.
| Leading Market Players |
|---|
| Nidec Corporation |
| Bühler Motor GmbH |
| ABB Limited |
| Faulhaber France SAS |
| Maxon |
| AMETEK Inc. |
| Siemens AG |
| Orbex Group |
| T-T Electric |
| Others |
Pricing and Supply Chain Analysis
Backward integration into rare earth magnet processing anchors supply position and pricing power for French DC motor assemblers confronting Chinese export quota volatility. The EU Ecodesign for Sustainable Products Regulation's embodied carbon documentation requirements compress margins for importers lacking captive recycling capabilities while advantaging domestic producers with European-sourced magnet alternatives.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to brushless motor orders serving Île-de-France aerospace clusters with satellite launch windows. Three-tier pricing structure across ANSM-certified medical, CE-marked industrial, and economy retrofit tiers reflects certification burden differentiation. Price erosion runs through brushed motor segments as Chinese imports compress replacement cost curves below rewinding economics. Automotive OEMs exhibit lowest price sensitivity due to platform-level co-development agreements locking magnet pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from French automotive primes while distributor networks serve MRO requirements in peripheral manufacturing basins. Neodymium and dysprosium sourcing concentrates in China, with secondary draws from Myanmar and Australia; copper windings and silicon steel laminations feed from German and Spanish mills. Single-source vulnerability in rare earth separation creates tariff exposure ahead of anticipated EU carbon border adjustments. Distribution runs through authorized technical distributors with firmware configuration capabilities for robotics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France DC Motors Market reads as a cost-of-compliance story where the EU Ecodesign for Sustainable Products Regulation creates a barrier-to-entry moat for players with documented rare earth circularity and lifecycle carbon accounting systems.
For Market Incumbents: To counter margin compression from Chinese import pricing, lock long-term magnet supply contracts with European rare earth processors and deepen captive recycling capabilities. Prioritize ANSM certification investment to sustain medical device segment pricing power against unqualified entrants. For New Entrants and Emerging Players: Capture whitespace in Burgundy collaborative automation deployments by establishing localized assembly operations with Grenoble-sourced firmware talent. Target Auvergne-Rhône-Alpes cobot joint specifications through integrated motor-drive packages reducing cabinet footprint. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated multinationals seeking European regulatory navigation capabilities. Five-to-ten year viability hinges on magnet supply security and predictive maintenance platform development. Monitor neodymium price volatility and EU carbon border adjustment implementation timing as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Recycling Capability Investment | Captive rare earth recovery insulates against Chinese export quota disruptions and satisfies EU circularity mandates. |
| Predictive Maintenance Platform Development | Outcome-based service contracts for automotive OEMs transfer maintenance risk and generate recurring revenue streams. |
| ANSM Certification Pathway Acceleration | Class IIa motor approval creates pricing power in medical device segments with biocompatibility documentation barriers. |
| SiC Power Semiconductor Integration | Switching frequencies above 100 kHz reduce acoustic noise for next-generation electric vehicle thermal management. |
| Grenoble Engineering Talent Acquisition | Embedded motor control firmware expertise concentration enables robotics startup hiring in peripheral regions. |
Research Methodology
SEC 10-K filings, EU Ecodesign regulatory impact assessments, and French customs trade data formed the secondary backbone, cross-referenced with primary interviews across motor procurement directors at automotive OEMs, biomedical engineers at medical device manufacturers, and aftermarket service heads at industrial distributors. Bottom-up and top-down triangulation validated volume estimates against production capacity disclosures and import penetration metrics.
Bottom-up modeling aggregated segment-level demand across robotics, automotive, and industrial equipment applications, while top-down analysis cross-checked against macroeconomic industrial production indices. Segmentation dimensions included product architecture, precision grade, connectivity tier, and regional manufacturing cluster concentration. CAGRs derived from trend extrapolation of brushless adoption curves and automotive electrification mandate timelines, with SiC semiconductor cost reduction trajectories informing drive electronics penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth price volatility, EU carbon border adjustment implementation sequencing, and Chinese export policy shifts. Practitioners should monitor neodymium spot pricing, ANSM certification queue lengths, and CNIL data governance enforcement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
China DC Motor Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Waveguide Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
Smart Heater Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
Europe Electric Drives Market