
 Central Vacuum Receivers Market | 2026-2036
Central Vacuum Receivers Market Size, Share, and Industry Trends Forecast 2026-2036
Central Vacuum Receivers Market Insights
Stainless steel is consolidating its position against plastic alternatives in high-purity applications where corrosion resistance and pressure ratings determine total cost of ownership. Nilfisk leverages its European manufacturing footprint to anchor supply for pharmaceutical-grade installations. Conair competes through specialized configurations for North American plastics processing plants. Shini USA differentiates with integrated controls that reduce installation complexity for mid-sized packaging facilities.
Central vacuum receivers are pressure vessels engineered to separate particulate matter from vacuum airflow, typically rated for continuous duty cycles and constructed with welded seams tested to ASME or PED protocols. The equipment serves as the collection node in centralized vacuum systems, protecting blowers from debris while enabling batch discharge of captured material. Steel tank configurations dominate installations where temperature cycling and abrasive media demand structural longevity, while aluminum tanks occupy weight-sensitive mobile environmental service rigs. Two-stage vacuum technology leads in semiconductor manufacturing cleanrooms where ultimate vacuum depth governs process yield, and regenerative blower systems sustain demand in food packaging lines requiring oil-free operation.
ASME Boiler and Pressure Vessel Code governs receiver fabrication in the United States, while the EU Pressure Equipment Directive mandates CE-marked conformity for systems deployed across member states. FDA cGMP guidelines shape material contact surface requirements in pharmaceutical applications, restricting certain coatings and weld finishes. OSHA combustible dust standards influence receiver design for chemical handling environments, driving demand for explosion-vented configurations. Stakeholders must weigh regional certification burdens against the margin advantages of standardized global platforms.
Market Dynamics
EU F-Gas Regulation is compressing refrigerant-dependent vacuum system lifecycles while pharmaceutical cleanroom standards tighten material specifications across welded pressure vessel procurement.
Growth Catalysts
- Cleanroom Standards:Semiconductor fabs in Taiwan and South Korea mandate ASME-coded receivers with sub-micron filtration. Pharmaceutical processors in Germany upgrade legacy aluminum tanks to electropolished 316L stainless configurations.
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants accelerates replacement cycles for vacuum pump-receiver packages. OEMs redesign blower systems around low-emission alternatives.
- Plastics Processing Clustering:North American resin compounders centralize material handling infrastructure. Integrated vacuum networks reduce per-line blower redundancy.
Market Restraints
- Specialized Steel Supply:ASME-certified 316L plate concentrates among a limited set of North American and European mills. Lead times for pharmaceutical-grade material extend procurement cycles.
- Certification Fragmentation:CE-marked PED compliance diverges from ASME Section VIII protocols. Dual-certified fabrication adds engineering overhead for global platform strategies.
- Regenerative Blower Substitution:Oil-sealed rotary vane pumps reclaim share in non-cleanroom chemical processing. Price-sensitive buyers tolerate contamination risk for capital savings.
Strategic Opportunities
- Indian Pharmaceutical Expansion:CDSCO-aligned cGMP adoption drives demand for FDA-equivalent surface finishes. Domestic fabricators lack electropolishing capacity.
- Mobile Environmental Services:Aluminum tank configurations penetrate asbestos abatement and hazardous material remediation. Weight-constrained service vehicles require compact receiver geometries.
- Smart Controls Integration:IoT-enabled level sensing and automated discharge valves converge with existing building management systems. Packaging facilities prioritize reduced installation complexity.
Industry Challenges
- ASME Inspector Scarcity:Certified welding inspectors for pressure vessel fabrication concentrate in legacy industrial regions. New facility commissioning faces qualification bottlenecks.
- Legacy System Integration:Existing centralized vacuum networks operate on proprietary control architectures. Receiver upgrades require protocol translation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Vacuum Receivers Market |
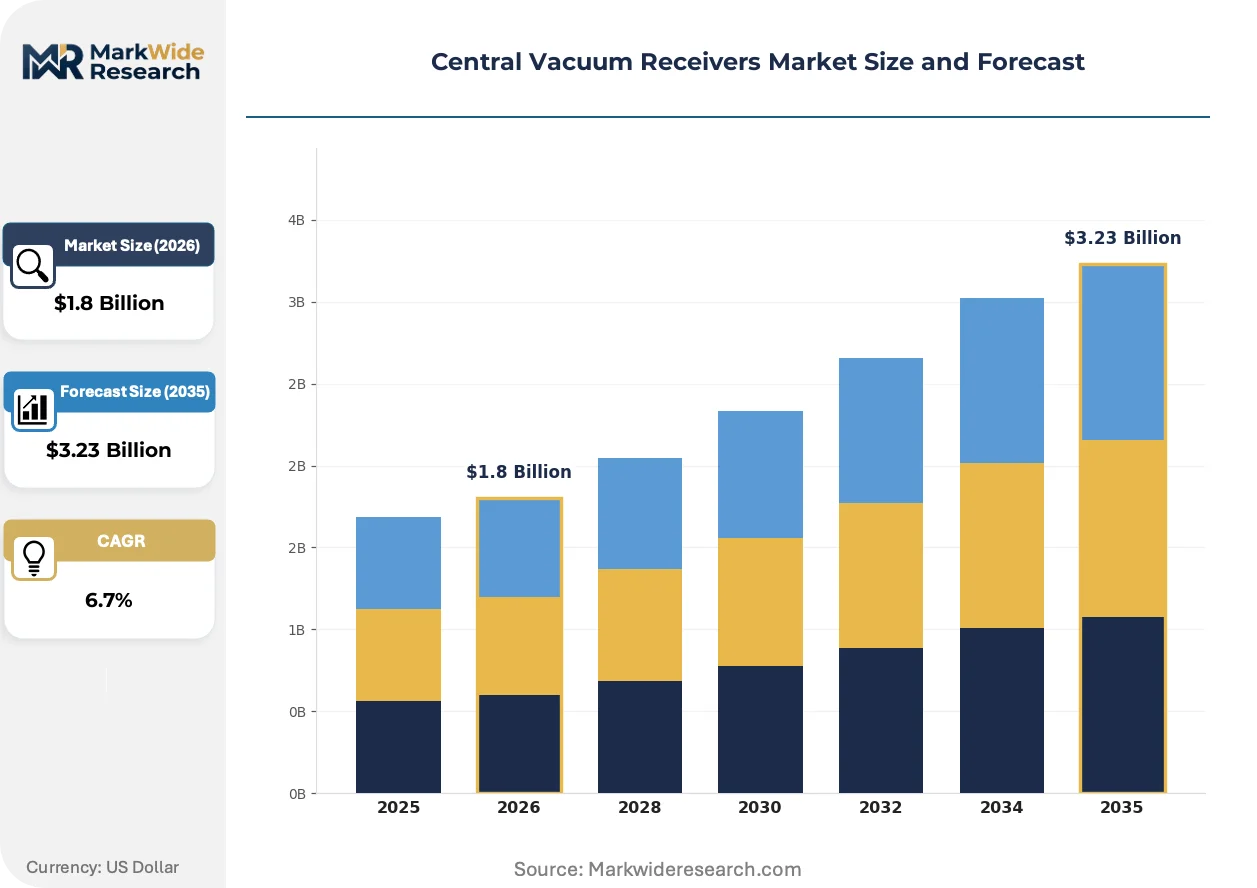
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Tank, Plastic Tank, Aluminum Tank, Composite Tank Technology: Single-Stage, Two-Stage, Regenerative Blower, Ejector Vacuum Application: Pharmaceutical Processing, Chemical Handling, Food & Beverage, Semiconductor Manufacturing End User Industry: Laboratories, Packaging Facilities, Environmental Services, Process Equipment Manufacturers |
| Companies Covered | Conair, Shini USA, Appcon, Nilfisk, Drainvac, Nuera Air, Trovac Industries, Delfin, Becker Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Vacuum Receivers Market Trends and Innovations
Modular receiver architectures are fragmenting traditional skid-mounted system procurement while regulatory pressure on refrigerants accelerates blower technology turnover.
Two-stage vacuum technology is decentralizing cleanroom infrastructure investment. Semiconductor fabs in Taiwan adopt distributed receiver arrays with localized roughing pumps. This architecture compresses central blower capacity requirements while improving fault isolation.
REACH substance restrictions are reshaping surface treatment specifications. Chromate conversion coatings face sunset dates for aerospace-adjacent applications. German process equipment OEMs qualify citric acid passivation alternatives for aluminum receiver internals.
Buyer consolidation among contract packaging organizations concentrates specification authority. Tier-one converters in the United States standardize on pre-configured receiver-blower packages. Regional distributors lose influence as direct OEM relationships deepen.
Central Vacuum Receivers Market Segmentation
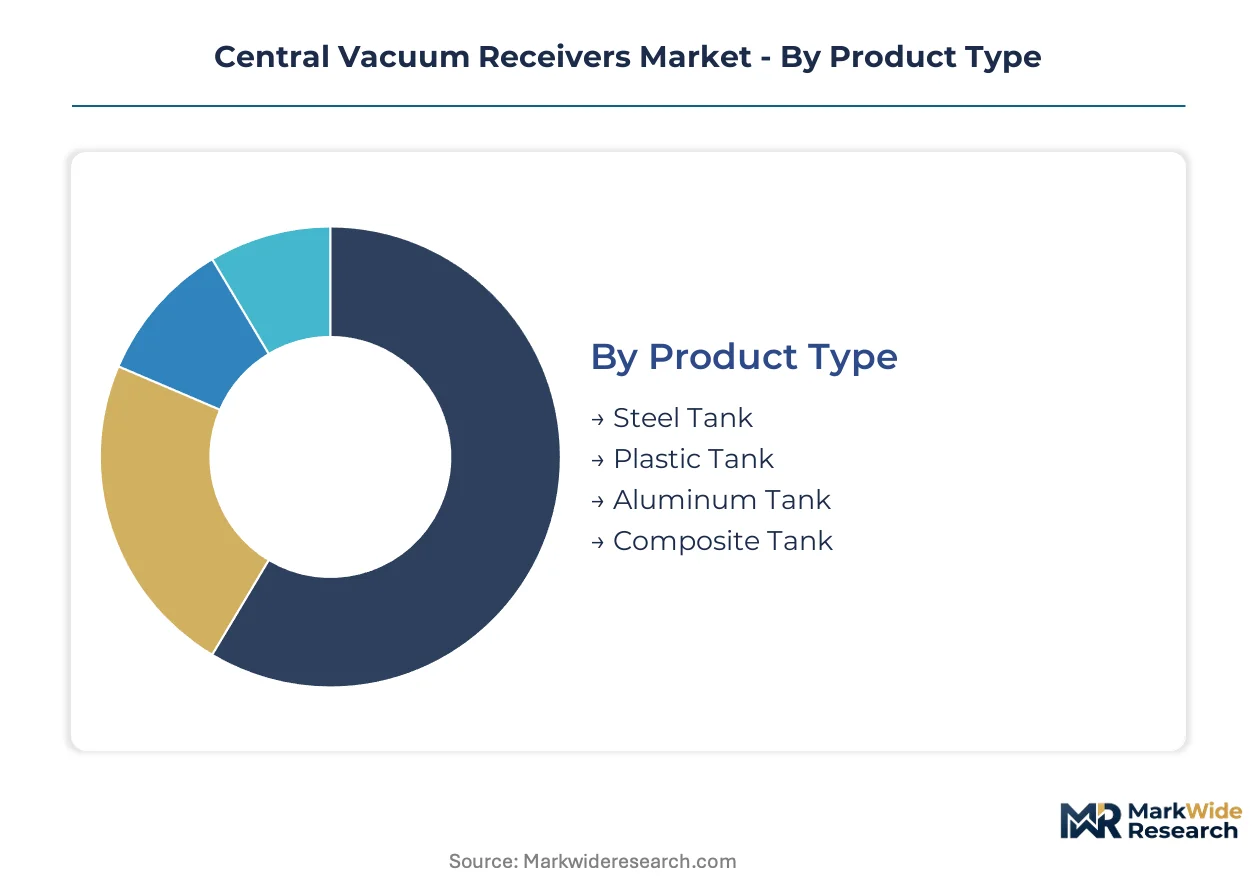
Central vacuum receiver procurement splits sharply between volume-driven commodity configurations and premium-certified installations where regulatory compliance commands price multiples. Segmentation discipline matters because material specification and certification tier determine margin structure more than unit volume across every category.
Product Type:
Volume concentrates in standard steel configurations while premium concentrates in specialized alloys and lightweight alternatives.
- Steel Tank:ASME-coded carbon and 316L stainless configurations dominate continuous-duty installations. German pharmaceutical processors specify electropolished 316L for FDA cGMP compliance, driving 30-40% price premiums over standard mill finish.
- Plastic Tank:Polypropylene and HDPE receivers serve corrosive chemical environments where metallic ion contamination threatens process integrity. North American plating operations favor plastic for acid vapor recovery, though pressure ratings limit expansion beyond atmospheric applications.
- Aluminum Tank:Weight-constrained mobile environmental service rigs in the United States specify aluminum for asbestos abatement vehicles where payload limits govern equipment selection.
- Composite Tank:Fiberglass-reinforced polymer configurations penetrate offshore oil and gas maintenance where salt spray corrosion accelerates metallic tank degradation.
Today's leader: Steel Tank. Tomorrow's challenger: Aluminum Tank.
Technology:
Application environment dictates technology selection more than capital budget, with cleanroom requirements forcing specification upgrades regardless of cost sensitivity.
- Two-Stage:Rotary vane and dry screw configurations achieve ultimate vacuum depths below 0.1 mbar for semiconductor wafer handling. Taiwan fabs deploy distributed receiver arrays with localized two-stage roughing pumps, compressing central blower capacity requirements.
- Regenerative Blower:Oil-free side-channel blowers sustain food packaging lines where compressed air purity prevents product contamination. Midwest US bakeries standardize on regenerative systems for flour and sugar conveying.
- Single-Stage:Basic liquid ring pumps serve general industrial material handling where moderate vacuum levels suffice. Price-sensitive chemical processors tolerate higher energy consumption for lower capital outlay.
- Ejector Vacuum:Steam and air ejectors handle high-volume gas loads in petrochemical distillation. Gulf Coast refineries specify corrosion-resistant ejector-receiver packages for sour gas service.
Two-stage systems command the steepest price premiums. Regenerative blowers are expanding most quickly in food-grade applications.
Application:
Regulatory intensity varies dramatically across applications, with pharmaceutical and semiconductor specifications creating effective entry barriers for uncertified suppliers.
- Pharmaceutical Processing:Electropolished surfaces, passivation protocols, and FDA-compliant documentation packages dominate procurement. Indian CDSCO-aligned facilities upgrade legacy aluminum tanks, creating demand for imported 316L fabrications.
- Semiconductor Manufacturing:Sub-micron filtration and vibration isolation requirements govern receiver specification. South Korean memory fabs mandate ASME-coded vessels with helium leak testing.
- Chemical Handling:OSHA combustible dust standards drive explosion-vented configurations for powder processing. Batch chemical operations prioritize rapid discharge cycles over ultimate vacuum depth.
- Food & Beverage:USDA sanitary standards and 3-A sanitary certifications constrain material selection. Dairy processors specify 304 stainless with specific weld bead profiles for CIP compatibility.
Pharmaceutical Processing anchors premium pricing. Semiconductor Manufacturing offers the fastest volume expansion trajectory.
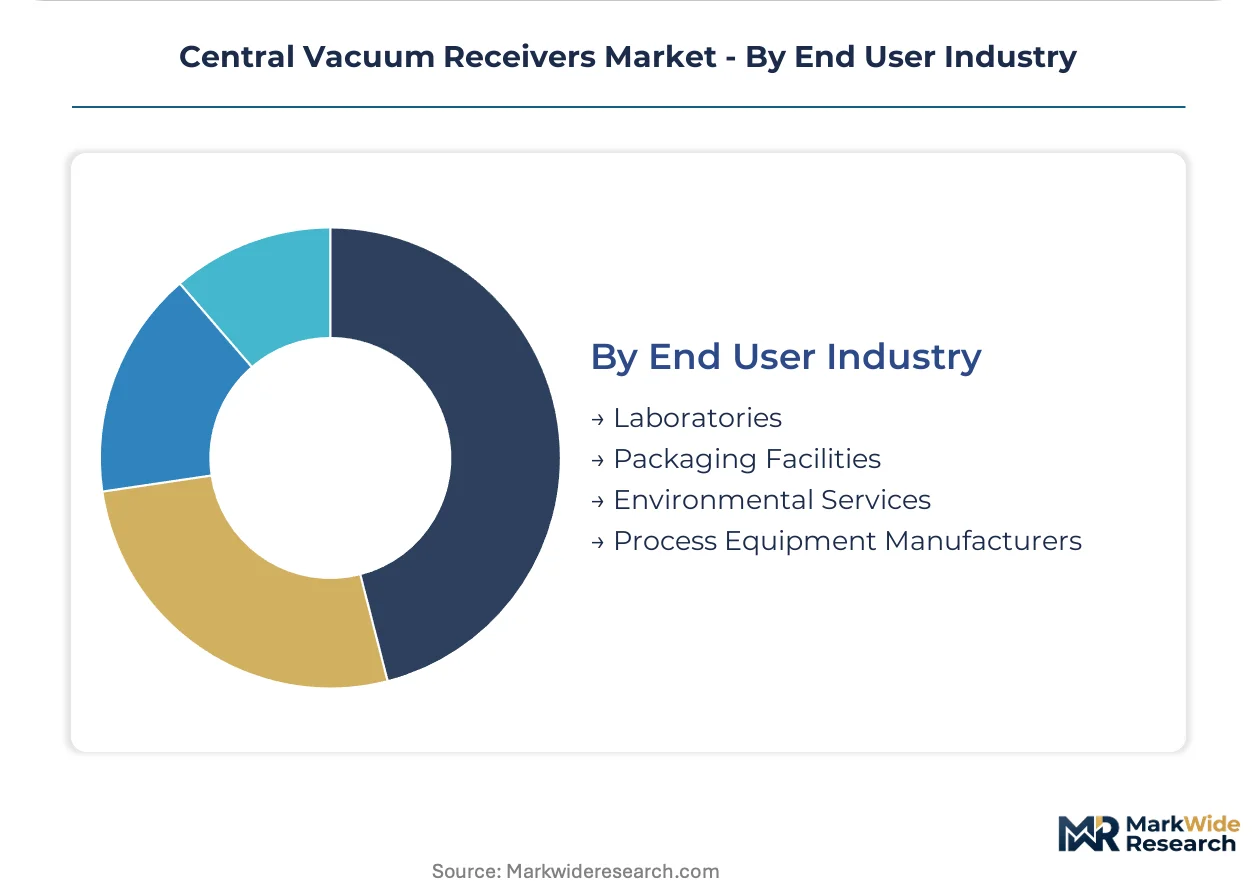
End User Industry:
Buyer sophistication and specification authority concentrate in direct OEM relationships, squeezing distributor margins across all end user categories.
- Process Equipment Manufacturers:Skid builders and system integrators specify receivers as package components. German OEMs cluster around specialized component suppliers in Baden-Württemberg's industrial corridor.
- Packaging Facilities:Contract packaging organization consolidation concentrates procurement authority. Tier-one US converters standardize on pre-configured receiver-blower packages, bypassing regional distributors.
- Laboratories:Research institutions and analytical labs require compact, quiet configurations. University procurement offices prioritize energy efficiency certifications for grant compliance.
- Environmental Services:Asbestos abatement and hazardous material remediation contractors demand portable, ruggedized equipment. Weight-constrained service vehicles drive aluminum tank specification.
Process Equipment Manufacturers dominate specification influence. Packaging Facilities are concentrating procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Baden-Württemberg industrial corridor anchors pharmaceutical-grade vacuum receiver demand, with process equipment OEMs clustering around specialized component suppliers. Regulatory pressure from Brussels and Washington reshapes procurement patterns across three continents.
United States
Midwest plastics processing clusters and Gulf Coast petrochemical operations drive steel tank configurations. OSHA combustible dust standards enforce explosion-vented designs for powder handling facilities. Houston-area system integrators package receivers with corrosion-resistant coatings for sour gas service.
Germany
Pharmaceutical processors in Baden-Württemberg upgrade legacy aluminum tanks to electropolished 316L stainless configurations. The EU F-Gas Regulation accelerates replacement cycles for refrigerant-dependent vacuum pump packages. Stuttgart-based OEMs source ASME-certified plate from specialized North American mills.
India
CDSCO-aligned cGMP adoption drives demand for FDA-equivalent surface finishes in Maharashtra and Gujarat pharmaceutical corridors. Domestic fabricators lack electropolishing capacity, creating import dependence for premium installations. Hyderabad's active pharmaceutical ingredient producers expand centralized material handling infrastructure.
South Korea
Memory fabs in Gyeonggi Province mandate ASME-coded vessels with helium leak testing for sub-micron filtration requirements. Distributed receiver arrays with localized roughing pumps compress central blower capacity. Seoul-based system integrators specify vibration isolation for cleanroom yield protection.
Taiwan
Semiconductor foundries in Hsinchu Science Park deploy two-stage vacuum technology for wafer handling below 0.1 mbar. Taiwan's national industrial regulator enforces alignment with international pressure vessel codes. Kaohsiung packaging facilities adopt regenerative blower systems for oil-free flour and sugar conveying.
Central Vacuum Receivers Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators respond to extended lead times for ASME-certified 316L plate. The vendor base separates into three tiers: multinational industrial equipment conglomerates with European manufacturing footprints, North American specialists serving plastics processing clusters, and regional fabricators competing on delivery speed. Two strategic archetypes define competitive positioning: vertically integrated pressure vessel manufacturers controlling weld certification in-house, and system integrators outsourcing fabrication to certified job shops. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players extending service networks into Indian pharmaceutical corridors and adding smart controls capabilities.
Among European-based industrial equipment groups, Nilfisk occupies a position exemplifying the multinational archetype with pharmaceutical-grade installation expertise. Conair and Shini USA represent the North American specialist tier, with the former anchoring plastics processing system integration and the latter exemplifying integrated controls differentiation for packaging facilities. These three companies illustrate how competitive positioning fragments across geographic specialization and application focus rather than converging on undifferentiated scale.
| Leading Market Players |
|---|
| Conair |
| Shini USA |
| Appcon |
| Nilfisk |
| Drainvac |
| Nuera Air |
| Trovac Industries |
| Delfin |
| Becker Pumps |
| Others |
Pricing and Supply Chain Analysis
Tier-one process equipment OEMs in Germany's Baden-Württemberg corridor concentrate procurement authority for pharmaceutical-grade receivers, anchoring a contract-based pricing model where ASME-certified 316L plate availability governs quote validity periods. Specification-grade premiums widen as electropolishing capacity tightens against cleanroom upgrade cycles.
Pricing Analysis
Input-cost pass-through from specialized steel mills dominates pricing dynamics for premium installations. Pricing stratifies across pharmaceutical-grade electropolished 316L, standard ASME-coded carbon steel, and commodity aluminum configurations. Cost compression in standard steel tanks intensifies as North American plastics processors consolidate volume procurement. Price-sensitive buyers in chemical handling tolerate regenerative blower substitutes, while semiconductor fabs absorb premiums for helium-tested vessels.
Supply Chain Analysis
Freight costs from North American and European ASME-certified mills to German pharmaceutical OEMs compress margin structures for imported plate. Supply concentrates in the United States, Germany, and India for finished receiver fabrication. Raw material flows draw from specialized 316L plate producers, electropolishing service providers, and certified welding consumables. Single-source vulnerability concentrates in ASME inspector availability for pressure vessel qualification. Distribution runs through direct OEM relationships and system integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pharmaceutical cleanroom upgrades and EU F-Gas Regulation compliance shift procurement toward premium-certified configurations regardless of capital budget pressure.
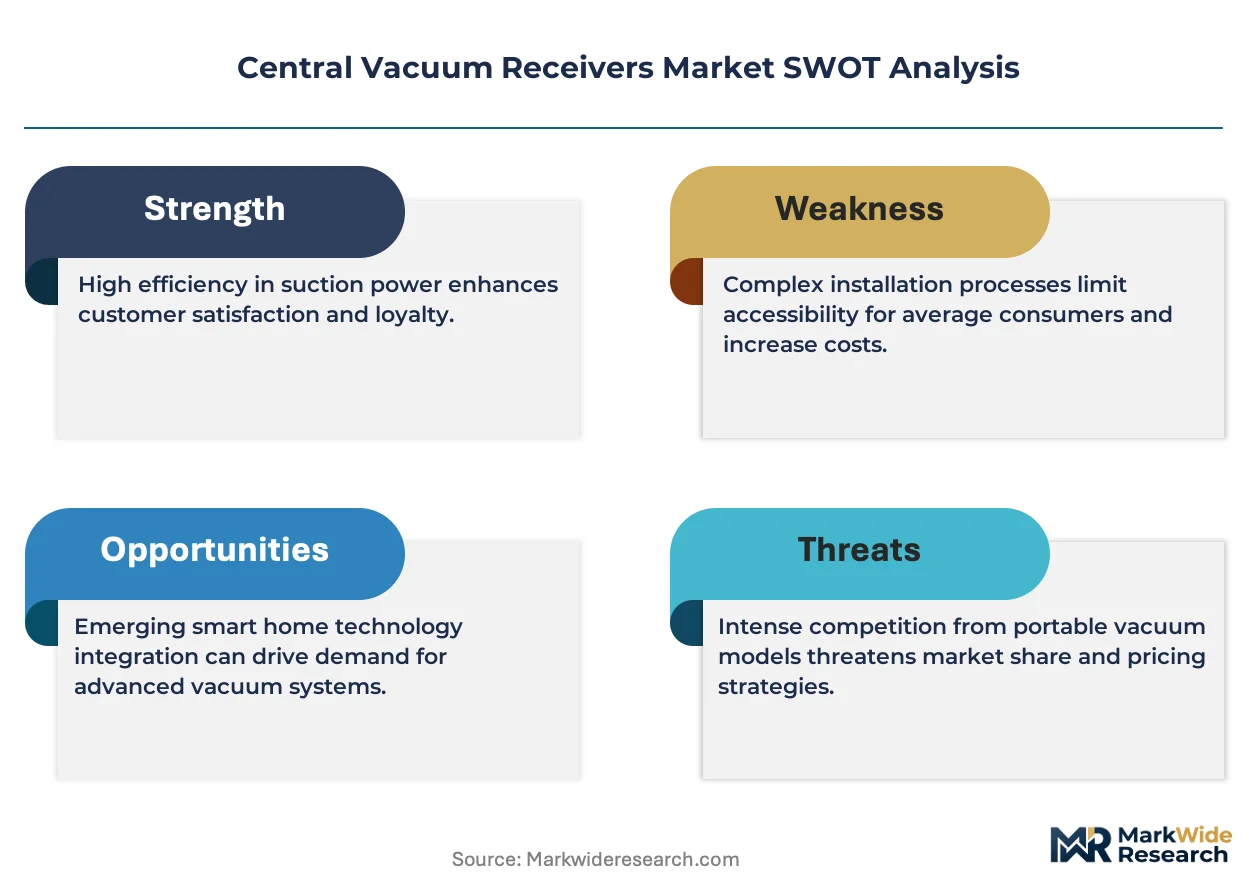
For Market Incumbents: Anchor defensive positioning through captive electropolishing capacity and dual ASME-PED certification to capture pharmaceutical upgrade cycles. Defend against regenerative blower substitution in chemical processing by embedding smart controls that reduce installation complexity. Prioritize inspector qualification programs to resolve commissioning bottlenecks. For New Entrants and Emerging Players: Launch via mobile environmental service channels where aluminum tank weight constraints create specification gaps incumbent steel specialists underserve. Target Indian pharmaceutical corridors where CDSCO-aligned cGMP adoption outpaces domestic electropolishing capacity. Penetrate through aftermarket service partnerships with asbestos abatement contractors. For Investors and Strategic Acquirers: Process equipment conglomerates with European manufacturing footprints represent the most active acquirer in this space, seeking weld certification capabilities and pharmaceutical-grade surface finish expertise. Long-term viability hinges on regulatory compliance service bundling rather than commoditized vessel fabrication. Watch ASME inspector pipeline expansion as inflection indicator for capacity-constrained premium tier growth.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adds electropolishing lines to serve German pharmaceutical OEM clusters. |
| Backward Integration | Captures ASME-certified 316L plate supply through mill partnerships. |
| Smart Controls Integration | Reduces installation complexity for mid-sized packaging facilities. |
| Geographic Expansion | Establishes fabrication presence in Indian pharmaceutical corridors. |
| Certification Investment | Dual ASME-PED qualification enables global platform standardization. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with plant engineers, OEM procurement teams, aftermarket service heads, and certified welding inspectors alongside secondary validation. Sources include ASME Boiler and Pressure Vessel Code filings, EU Pressure Equipment Directive conformity databases, FDA cGMP inspection records, and customs trade data for pressure vessel imports. Bottom-up unit economics triangulate against top-down industry spend estimates.
Granularity extends to product type, technology tier, application intensity, and end-user industry across the projection horizon. CAGRs derive from segmented demand modeling incorporating regulatory phase-in schedules and replacement cycle assumptions. Forecast inputs include EU F-Gas Regulation compliance deadlines, semiconductor fab capital expenditure patterns, and pharmaceutical cleanroom upgrade pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged ASME inspector scarcity or accelerated refrigerant phaseout timelines. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and material cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Modular Contactor Market
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Electric Motors for Conveyor System Market
Electrical Equipment
High Voltage Circuit Breaker Market