
 Motor Protection Devices Market | 2026-2036
Motor Protection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Protection Devices Market Analytics
Germany is rewriting the competitive map for motor protection devices through precision manufacturing clusters in Bavaria and Baden-Württemberg. Siemens AG leverages its domestic industrial base to sustain leadership in electromechanical overload relays. ABB Ltd. anchors its European R&D operations in Switzerland while competing aggressively in smart sensor integration. Schneider Electric SE dominates distribution channels across Western Europe and extends its digital circuitry portfolio through specialized software layers.
Motor protection devices are electromechanical and electronic apparatus designed to interrupt current flow or signal fault conditions when motors experience overload, phase imbalance, short circuit, or thermal runaway, typically operating within voltage ranges from 230V to 690V AC and coordination classes up to Type 2 per IEC 60947-4-1. Their primary purpose is to prevent insulation damage, reduce downtime, and extend operational life in continuous-duty industrial machinery. Overload relays retain the largest installed base across legacy manufacturing facilities, though smart sensors represent the fastest-expanding technology segment as facilities retrofit predictive maintenance architectures. Soft starters command premium positioning in oil and gas applications where torque control limits mechanical stress on pump and compressor systems.
The European Union's Ecodesign Directive and F-Gas Regulation are forcing motor system efficiency upgrades that cascade into replacement demand for coordinated protection hardware. In the United States, NEMA and OSHA electrical safety standards shape product certification requirements and channel access for imported equipment. China's GB standards and MIIT efficiency mandates are accelerating domestic production of digital protection relays for industrial automation. Stakeholders must monitor how converging efficiency regulations across multiple jurisdictions redefine interoperability specifications and aftermarket service obligations.
Market Dynamics
The migration from electromechanical overload relays to digital protection systems is compressing replacement cycles across industrial motor installations. IEC 60947-4-1 coordination requirements are forcing facilities to upgrade protection hardware ahead of scheduled maintenance windows.
Growth Catalysts
- Industrial Automation:Manufacturing plants in Germany and China are retrofitting legacy motor systems with digital circuitry-based protection to enable predictive maintenance architectures.
- EU F-Gas Regulation:The European Union's efficiency mandates are cascading into replacement demand for coordinated motor protection hardware that meets tightened energy performance standards.
- Oil and Gas Torque Control:Soft starter adoption is accelerating in petroleum extraction applications where mechanical stress reduction on pumps and compressors extends operational life.
Market Restraints
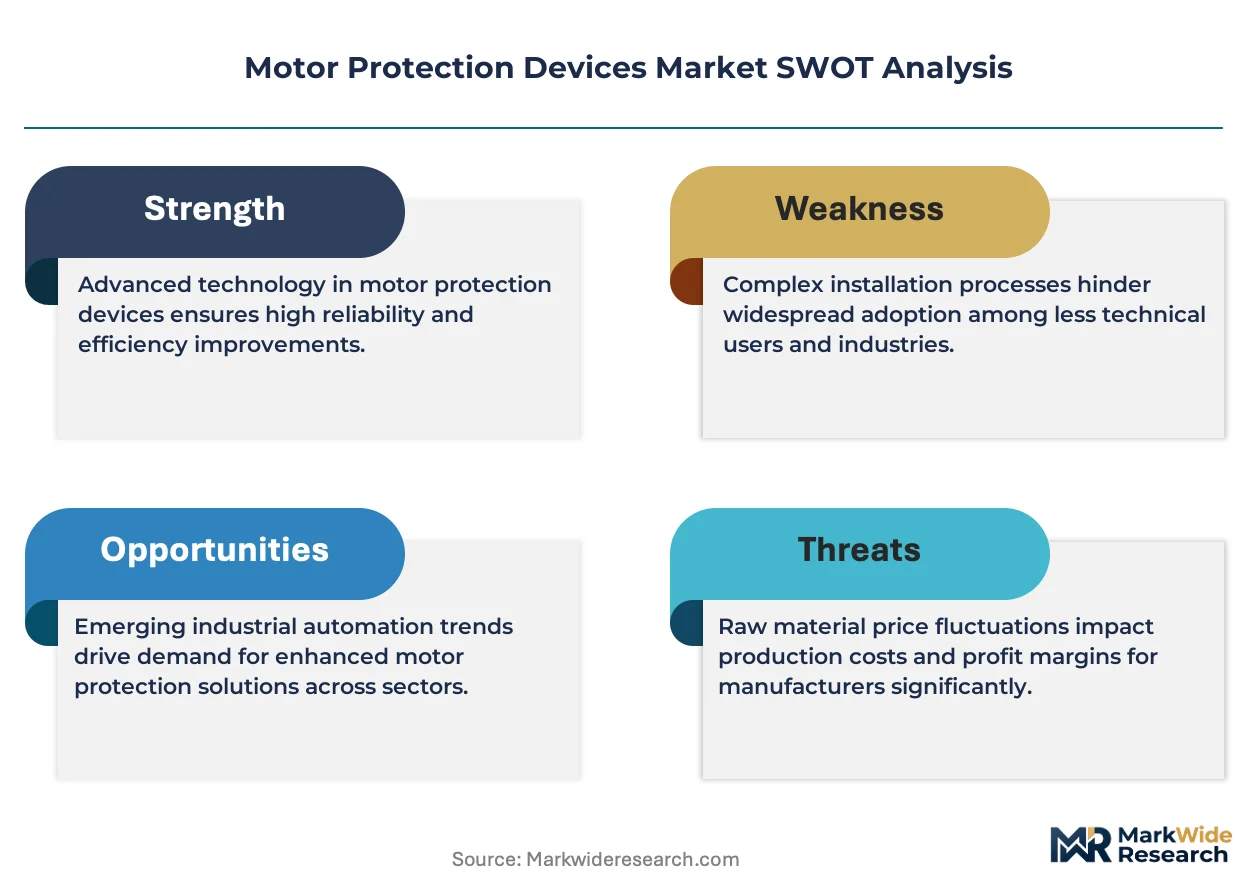
- Copper and Rare Earth Volatility:Electromechanical relay production faces input cost pressure from fluctuating copper prices and constrained neodymium supply chains concentrated in China.
- Legacy Infrastructure Lock-In:Installed base of thermal overload relays across aging manufacturing facilities in the United States creates technical friction against digital retrofitting.
- NEMA Certification Barriers:Imported protection equipment faces extended approval timelines under OSHA electrical safety standards, limiting channel access for non-domestic suppliers.
Strategic Opportunities
- Smart Sensor Convergence:Integration of vibration monitoring with thermal protection is digitizing condition-based maintenance in continuous-duty machinery across Bavarian precision manufacturing clusters.
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology directives are accelerating domestic production of digital protection relays for industrial automation retrofits.
- Aftermarket Service Unbundling:Independent service providers are capturing coordination testing and recalibration work previously bundled with OEM hardware sales.
Industry Challenges
- Embedded Systems Engineering Gap:Facilities lack personnel trained in IEC 61131-3 programming for digital protection relay configuration and fault diagnostics.
- Type 2 Coordination Complexity:Achieving damage-free motor starter protection per IEC 60947-4-1 requires precise matching of contactor, overload relay, and short-circuit protective device characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Protection Devices Market |
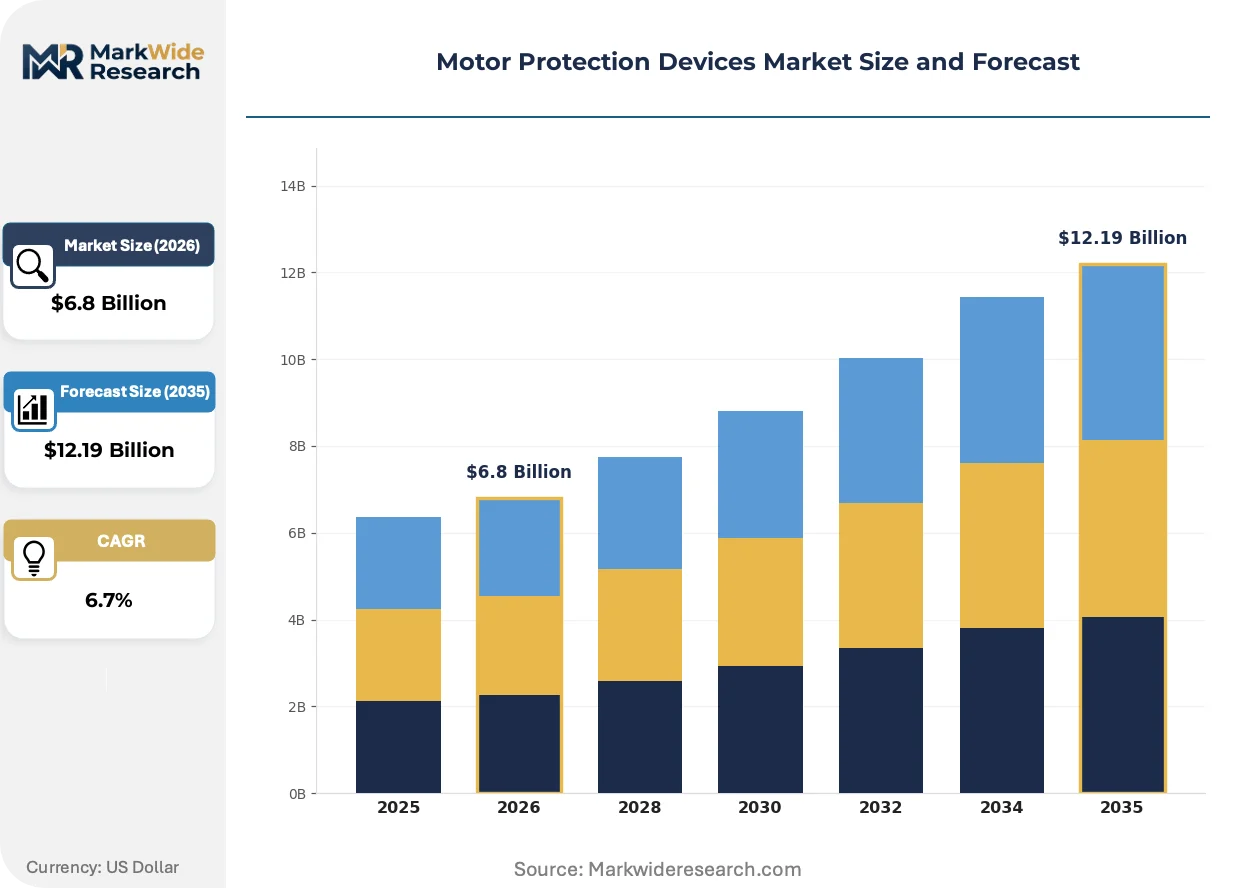
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Overload Relays, Circuit Breakers, Motor Starters, Soft Starters End User: Manufacturing, Oil & Gas, Automotive, Utilities Application: Industrial Automation, HVAC Systems, Renewable Energy, Water Treatment Technology: Digital Circuitry, Electromechanical, Smart Sensors, Analog Technology |
| Companies Covered | Schneider Electric SE, Siemens AG, ABB Ltd., Eaton Corporation plc, Rockwell Automation Inc., Mitsubishi Electric Corporation, General Electric Company, Fuji Electric Co., Ltd., Legrand Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Protection Devices Market Evolving Landscape
Digital protection architectures are displacing thermal bimetal technologies through embedded microprocessor platforms that enable real-time motor parameter monitoring. The convergence of protection hardware with industrial IoT infrastructure is reshaping how facilities manage motor asset lifecycles.
Microprocessor-based motor protection relays are digitizing fault detection and trip coordination through algorithms that process current, voltage, and temperature data streams simultaneously. Chemical processing plants and water treatment facilities are adopting these systems fastest, replacing thermal overload relays at twice the pace of discrete manufacturing. The technology is digitizing maintenance scheduling by enabling condition-based interventions rather than calendar-based replacements.
The EU Ecodesign Directive is mandating motor system efficiency upgrades that force simultaneous protection hardware replacement to maintain coordination integrity. Industrial motor installations rated above 0.75 kW must meet IE3 efficiency minimums, triggering cascade demand for compatible protection devices. Western European distribution channels are prioritizing stockholding of digitally coordinated protection systems over legacy electromechanical inventory.
Buyer procurement is fragmenting across direct OEM relationships, specialized electrical distributors, and integrated automation suppliers. Large manufacturing groups are consolidating motor protection purchasing through framework agreements with ABB and Schneider Electric, bypassing traditional wholesale channels. This consolidation is most visible in German automotive supply chains where tier-one suppliers demand unified protection platforms across multiple plant locations.
Motor Protection Devices Market Segmentation
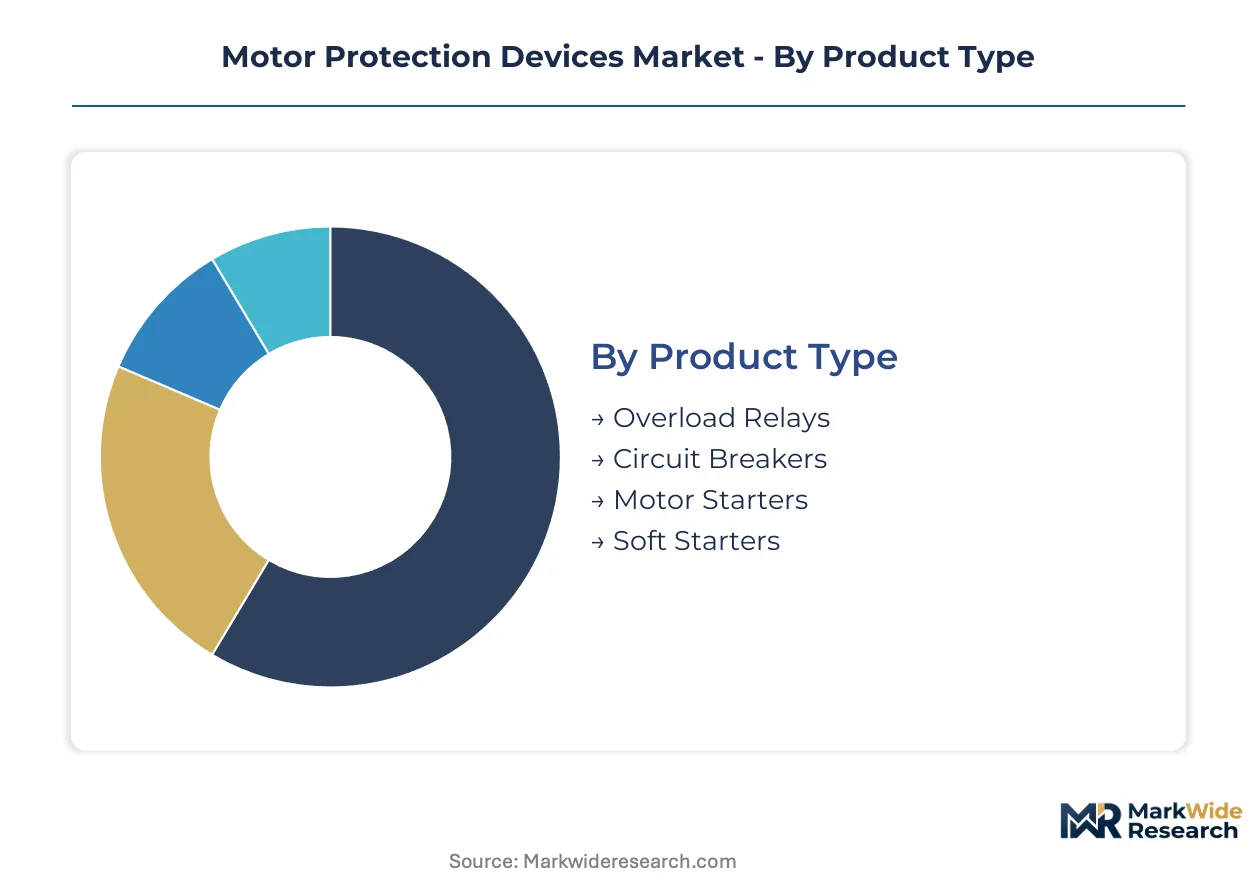
Motor protection devices serve heterogeneous operational environments where duty cycles, fault tolerance requirements, and coordination complexity vary substantially. Segmentation reveals how procurement patterns split between replacement-driven electromechanical demand and growth-oriented digital system investments. Understanding these divides enables suppliers to align R&D roadmaps with specific installation base characteristics.
Product Type:
After-sales service intensity varies sharply across product categories, with electromechanical overload relays generating recurring calibration revenue while digital platforms monetize through software subscriptions and predictive analytics licensing.
- Overload Relays:Thermal bimetal or electronic units that trip when current exceeds motor nameplate ratings for specified durations. Demand concentrates in legacy manufacturing facilities across the United States where thermal overload relays dominate installed bases and replacement cycles follow predictable maintenance windows.
- Soft Starters:Solid-state voltage ramping devices that limit inrush current and mechanical torque shock during motor acceleration. Oil and gas extraction operations in petroleum-producing regions specify these for pump and compressor protection where mechanical stress reduction extends mean time between failures.
- Circuit Breakers:Short-circuit protective devices coordinating with contactors and overload relays per IEC 60947-4-1 Type 2 requirements. Utilities and heavy industrial plants specify molded-case and air-break variants for upstream fault isolation.
- Motor Starters:Contactor-overload assemblies providing remote switching and basic protection for three-phase induction motors. Discrete manufacturing and material handling applications favor these for cost-sensitive installations with moderate duty cycles.
By volume, overload relays lead. By growth pace, soft starters are ahead.
End User:
Cost tier differentiation separates specification-grade protection systems in continuous-process industries from standard-duty hardware in intermittent manufacturing applications.
- Oil & Gas:Upstream extraction and downstream refining operations requiring explosion-proof enclosures and torque-controlled starting for large horsepower motors. North Sea and Permian Basin developments drive specification of IECEx-certified protection systems with integrated condition monitoring.
- Manufacturing:Discrete assembly and process industries with diverse motor populations spanning material handling, machine tools, and packaging equipment. German automotive supply chains consolidate procurement through framework agreements demanding unified protection platforms across multiple plant locations.
- Automotive:OEM assembly plants and tier supplier facilities with high-volume conveyor systems and robotic workcells. Paint shop and body-in-white applications specify corrosion-resistant protection hardware with rapid fault reset capabilities.
- Utilities:Water pumping stations, wastewater treatment, and power generation auxiliaries requiring coordinated protection for critical infrastructure motors. Municipal procurement favors NEMA-rated devices with documented mean time to repair metrics.
Manufacturing commands the largest installed base. Oil and gas generates the highest per-unit specification value.
Application:
Volume concentration in mature industrial automation installations contrasts with emerging demand from renewable energy integration and building system efficiency retrofits.
- Industrial Automation:Manufacturing execution system-integrated motor control centers with networked protection relays enabling centralized fault diagnostics. Bavarian precision manufacturing clusters digitize maintenance scheduling through condition-based intervention protocols.
- HVAC Systems:Chiller, air handler, and pump motor protection in commercial and institutional buildings. EU F-Gas Regulation efficiency mandates cascade into replacement demand for coordinated protection hardware meeting tightened energy performance standards.
- Water Treatment:Continuous-duty pump and blower applications in municipal and industrial wastewater facilities. Chemical resistance and ingress protection ratings dominate specification criteria for corrosive environment installations.
- Renewable Energy:Solar tracking motor arrays and wind turbine pitch/yaw drives requiring wide temperature range operation and remote diagnostic capability. Grid-scale battery storage integration creates demand for DC-capable protection architectures.
Industrial automation anchors current procurement volume. Renewable energy applications are expanding most quickly.
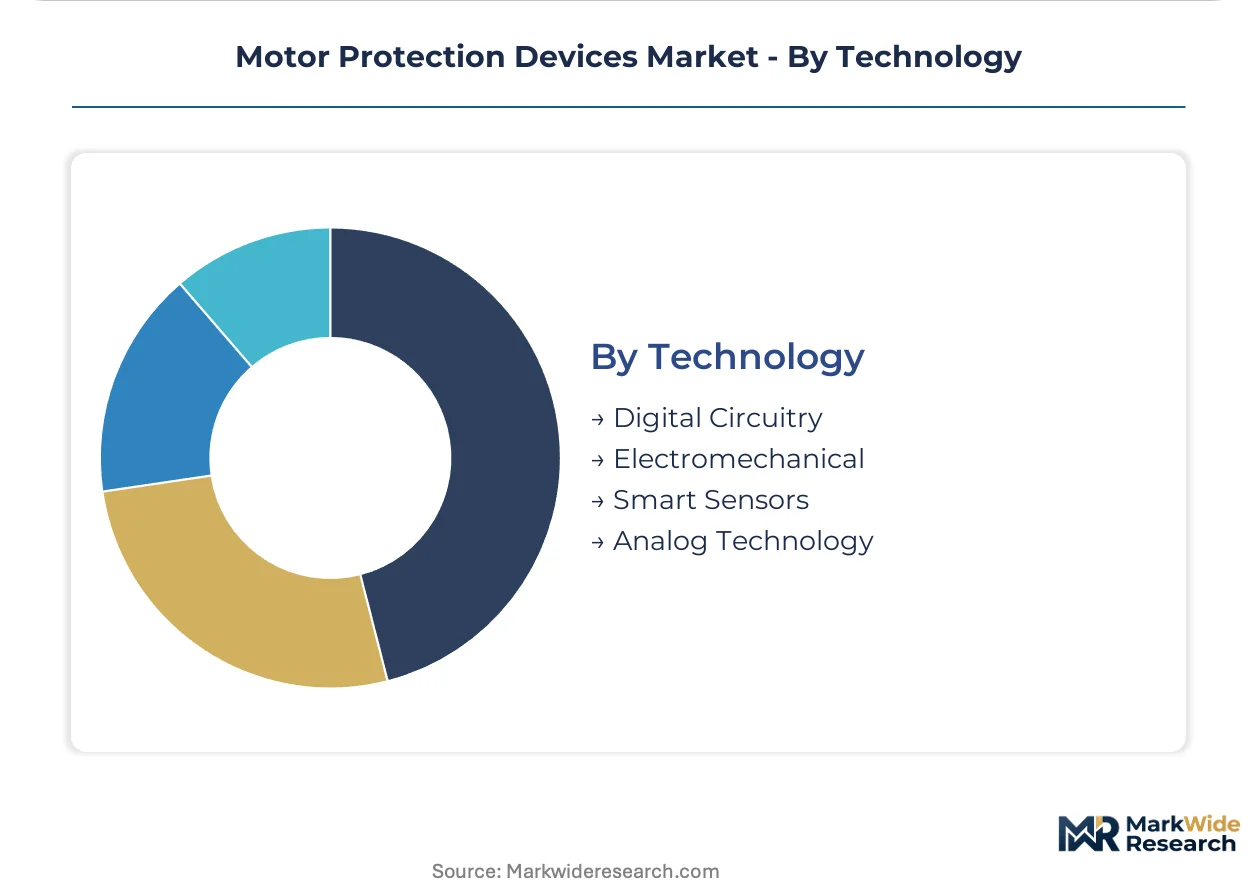
Technology:
Margin structure diverges between declining electromechanical hardware and digital platforms capturing recurring software revenue through predictive maintenance subscriptions.
- Digital Circuitry:Microprocessor-based relays processing current, voltage, and temperature data streams through embedded algorithms enabling real-time motor parameter monitoring. Chemical processing and water treatment facilities adopt these at twice the pace of discrete manufacturing sectors.
- Smart Sensors:Vibration, thermal, and current signature analysis devices converging protection hardware with industrial IoT infrastructure. Integration with predictive maintenance architectures drives fastest-expanding technology segment positioning.
- Electromechanical:Thermal bimetal overload relays and magnetic contactors with proven reliability in harsh environments but limited diagnostic capability. Aging infrastructure lock-in across United States manufacturing facilities sustains replacement demand.
- Analog Technology:Solid-state overload relays without microprocessor platforms, bridging cost and functionality between electromechanical and fully digital systems. Budget-constrained retrofits specify these for basic electronic protection without networking overhead.
Electromechanical technology retains the largest installed base. Smart sensors represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in Germany, China, and the United States concentrate the motor protection supply base, while regulatory divergence across IEC, NEMA, and GB standards fragments specification requirements. Demand patterns diverge sharply between mature retrofit markets and greenfield industrial automation installations.
Germany
Bavarian precision manufacturing clusters and Baden-Württemberg automotive supply chains drive specification-grade demand for IEC 60947-4-1 Type 2 coordinated systems. The EU Ecodesign Directive and F-Gas Regulation mandate motor efficiency upgrades that cascade into protection hardware replacement cycles. Siemens AG anchors domestic production from its Munich-area industrial base, supplying electromechanical overload relays to tier-one automotive suppliers.
China
MIIT efficiency mandates and GB standards accelerate domestic production of digital protection relays for industrial automation retrofits. Yangtze River Delta manufacturing hubs and Pearl River Delta export zones concentrate demand for smart sensor-integrated systems. Domestic suppliers compete with European and Japanese incumbents on cost-optimized digital platforms for mass-market manufacturing applications.
United States
NEMA certification requirements and OSHA electrical safety standards shape product approval timelines and channel access for imported equipment. The Permian Basin oil patch and Gulf Coast petrochemical corridors specify soft starters for torque-controlled pump protection. Aging thermal overload relay installed bases across Midwest manufacturing belts create replacement friction against digital retrofitting.
Japan
METI industrial efficiency programs and JIS standards govern protection system specifications for precision machinery and robotics applications. Kanto and Kansai manufacturing belts demand high-reliability electromechanical systems for continuous-duty semiconductor and automotive production. Mitsubishi Electric Corporation exemplifies domestic integration of protection hardware with servo and motion control portfolios.
India
CEA electrical safety regulations and BIS certification requirements structure import substitution policies for industrial protection equipment. Maharashtra and Gujarat industrial corridors drive demand for cost-optimized motor starters in textile, chemical, and pharmaceutical processing. Domestic fabrication capacity expands to serve Make in India procurement preferences for public infrastructure projects.
Motor Protection Devices Market Competitive Landscape
Diversified electrical conglomerates and specialized automation suppliers split the market across distinct capability tiers. Consolidation pressure concentrates around digital platform integration and predictive maintenance software bundling. Three strategic archetypes dominate: full-spectrum electrical majors with integrated protection portfolios, automation specialists with motion-control adjacencies, and regional component fabricators serving price-sensitive replacement demand. Competitive moves center on smart sensor convergence and aftermarket service unbundling.
Within the full-spectrum tier, Schneider Electric SE, Siemens AG, and ABB Ltd. occupy positions defined by distribution channel depth and coordination testing capabilities. Schneider dominates Western European electrical distribution with software-layer extensions. Siemens leverages its German industrial base for precision manufacturing cluster penetration. ABB anchors European R&D operations while competing on sensor integration. These three exemplify how protection hardware increasingly serves as an entry point for predictive maintenance platform sales.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| ABB Ltd. |
| Eaton Corporation plc |
| Rockwell Automation Inc. |
| Mitsubishi Electric Corporation |
| General Electric Company |
| Fuji Electric Co., Ltd. |
| Legrand Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese digital relay fabrication is compressing margins across mid-tier electromechanical suppliers while forcing tier-one European manufacturers toward premium sensor-integrated architectures. This utilization imbalance simultaneously erodes pricing power in commoditized thermal relay segments and concentrates margin capture among IEC 60947-4-1 Type 2 certification holders.
Pricing Analysis
IEC 60947-4-1 dictates the pricing tier structure across the motor protection landscape, separating IECEx-certified Type 2 coordinated systems from basic thermal overload units. Three-tier pricing structure across premium smart-sensor platforms, standard digital relays, and economy electromechanical hardware reflects certification depth and after-sales bundling intensity. Cost compression in economy electromechanical tiers is intensifying because of copper price volatility and Yangtze River Delta manufacturing overcapacity. Discrete manufacturing buyers exhibit highest price sensitivity, while oil and gas operators prioritize specification-grade coordination integrity over unit cost.
Supply Chain Analysis
Contract manufacturing for digital protection platforms concentrates among Siemens AG's in-house Munich-area facilities, ABB Ltd.'s Swiss R&D-integrated production, and domestic Chinese EMS providers serving cost-optimized relay segments. Component sourcing draws from German precision manufacturing clusters for electromechanical assemblies, Chinese rare earth processing for magnetic contactor materials, and Taiwanese semiconductor foundries for microprocessor platforms. Single-source vulnerability in neodymium supply chains concentrated under China's export licensing regime threatens electromechanical relay cost stability. Distribution runs through specialized electrical distributors in Western Europe, integrated automation suppliers in German automotive supply chains, and direct OEM relationships for large manufacturing groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motor protection device procurement is fragmenting across predictive maintenance platforms, creating niche opportunities for sensor-integrated specialists and aftermarket service unbundlers. This demand-side shift rewards players who decouple hardware from software monetization.
For Market Incumbents: Insulate margin position through captive production of microprocessor platforms and backward integration into smart sensor calibration capabilities. Siemens AG and Schneider Electric SE should deepen IEC 61131-3 programming certification offerings to lock in maintenance revenue streams. Defend against independent service providers capturing coordination testing work by bundling predictive analytics licensing with hardware refresh cycles. For New Entrants and Emerging Players: Build out aftermarket service capabilities targeting aging thermal overload relay installed bases across United States Midwest manufacturing belts, where digital retrofit friction sustains replacement demand. Focus initial penetration on water treatment and chemical processing facilities adopting microprocessor-based relays at twice the pace of discrete manufacturing. Pursue white-label sensor integration partnerships with established electrical distributors lacking in-house IoT development capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital protection relay segments as Chinese domestic suppliers achieve scale in microprocessor platform production. Long-term viability favors acquiring mid-tier automation specialists with established IEC 60947-4-1 Type 2 testing capabilities and existing relationships with German automotive tier-one suppliers. Monitor MIIT efficiency mandate acceleration as the signal indicating inflection toward domestic Chinese production substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Platform Integration | Converges vibration monitoring with thermal protection in Bavarian precision manufacturing clusters. |
| Aftermarket Service Unbundling | Captures coordination testing revenue previously bundled with OEM hardware sales. |
| IEC 61131-3 Certification Investment | Addresses embedded systems engineering gaps in facility maintenance personnel. |
| Backward Integration into Rare Earth Magnet Supply | Reduces exposure to China's neodymium export licensing volatility. |
| Predictive Maintenance Software Licensing | Monetizes digital platforms through recurring revenue beyond hardware transactional sales. |
Research Methodology
Cross-validation between primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchors the qualitative findings against secondary validation through IEC 60947-4-1 certification databases, customs trade data for electromechanical component flows, SEC 10-K filings of diversified electrical conglomerates, and MIIT efficiency mandate documentation. Bottom-up installation base modeling across manufacturing, oil and gas, automotive, and utilities segments triangulates with top-down market sizing from protection hardware shipment data.
Calibration against historical replacement cycle patterns and regulatory mandate implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, application environment, technology architecture, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating industrial automation capital expenditure trajectories, EU F-Gas Regulation compliance deadlines, and oil and gas torque control specification trends.
Stress conditions across copper price volatility bands, rare earth supply disruption scenarios, and NEMA certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding IEC 60947-4-1 Type 2 coordination adoption rates and smart sensor convergence velocity. Quarterly review of MIIT mandate acceleration indicators, EU Ecodesign Directive enforcement intensity, and Permian Basin soft starter specification trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Terminal Block Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
High-Vacuum Fiber Feedthrough Flanges Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Busbar Trunking System Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
Europe Busbar Market