
 Capacitor Bank Market | 2026-2036
Capacitor Bank Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitor Bank Market Analysis
Chinese capacitor manufacturers are shifting toward higher-voltage film dielectric production to serve ultra-high-voltage direct current projects. ABB leverages its installed base in European grid infrastructure to sustain service revenue streams across aging substation networks. Schneider Electric anchors its competitive position through integrated power management software bundled with hardware deployments. Siemens competes aggressively in rail electrification segments where harmonic filtering requirements are tightening.
A capacitor bank is an assembly of multiple capacitors connected in series or parallel configurations, typically rated between 0.4 kV and 765 kV, designed to supply reactive power compensation, improve power factor, and stabilize voltage levels in alternating current electrical systems. These assemblies employ polypropylene film or metallized paper dielectrics impregnated with biodegradable insulating oils or dry resin to achieve capacitance values ranging from tens of kilovars to hundreds of megavars while maintaining low dielectric losses below 0.5 watts per kvar. Power factor correction capacitors dominate current revenue volumes due to widespread industrial motor load compensation needs, while harmonic filter capacitors represent the fastest-expanding category as variable frequency drives and photovoltaic inverters proliferate nonlinear loads across manufacturing facilities. Energy storage capacitors command premium margins in grid-scale battery hybrid installations where rapid discharge cycling interfaces with lithium-ion systems.
FERC Order 2023 and IEEE 1531 standards in the United States mandate stricter reactive power capability requirements for inverter-based resources connecting to bulk power systems, directly expanding specification complexity for new capacitor bank installations. The EU Green Deal's F-Gas Regulation and ECHA restrictions on sulfur hexafluoride insulation are pushing manufacturers toward dry-type and vacuum-interrupter designs that eliminate greenhouse gas dependencies in switching compartments. Grid operators and industrial procurement teams must evaluate total lifecycle ownership costs against evolving interoperability standards as digital twin integration and condition-based monitoring become baseline expectations rather than differentiators.
Market Dynamics
Grid operators across India and China face simultaneous pressure from renewable integration mandates and aging infrastructure replacement cycles, forcing procurement teams to prioritize capacitor banks with embedded digital monitoring capabilities over conventional passive units.
Growth Catalysts
- FERC Order 2023:The United States mandate requires enhanced reactive power capability from inverter-based resources, compelling utilities to upgrade capacitor specifications for solar and wind interconnections.
- Industrial motor loads:Manufacturing facilities in India deploy power factor correction systems to reduce technical losses and avoid utility penalty tariffs on poor power factor.
- Metallized polypropylene film:Advances in dielectric materials enable higher energy density designs that withstand harmonic stress from variable frequency drives.
Market Restraints
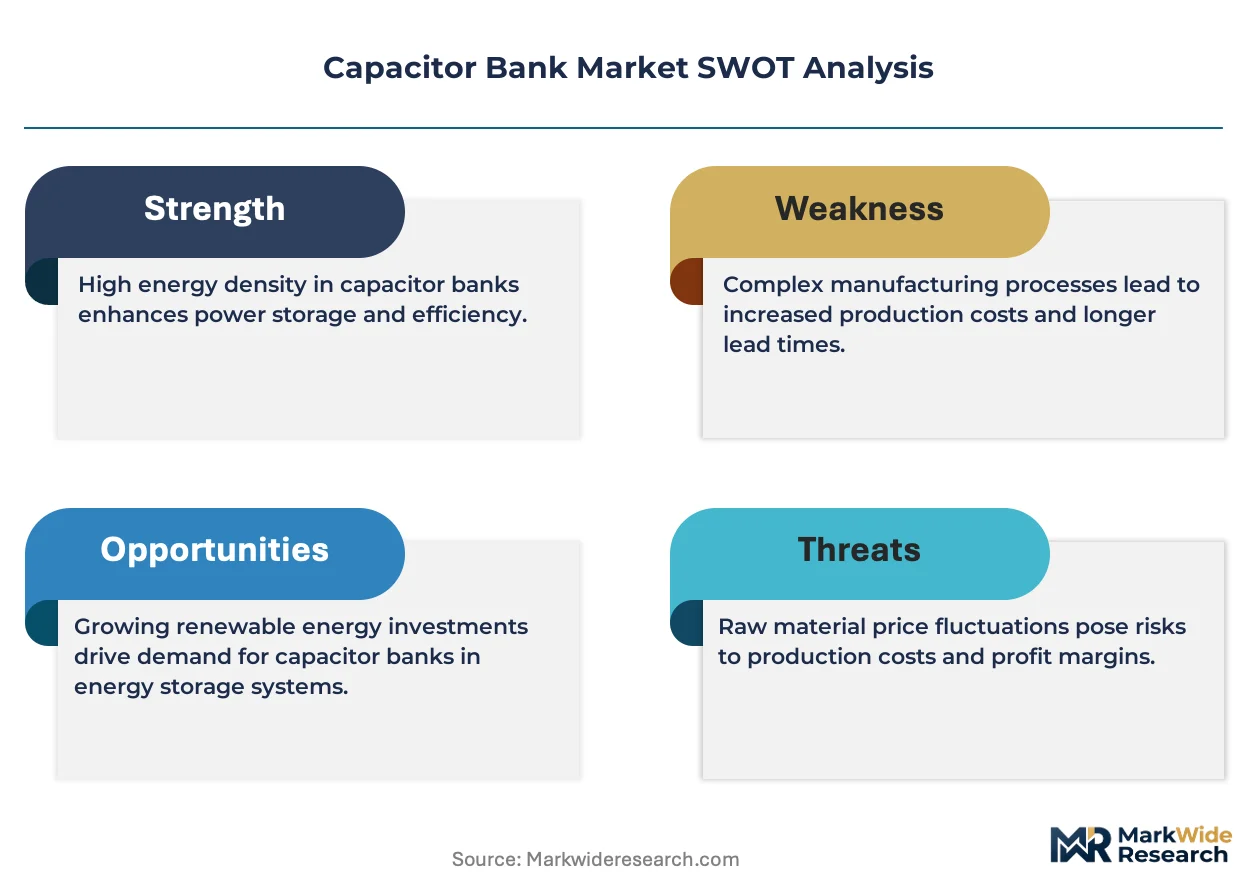
- Raw material concentration:Biaxially oriented polypropylene film supply concentrates among a limited set of specialty chemical producers in Germany and Japan, exposing capacitor manufacturers to input cost volatility.
- EU F-Gas Regulation:Restrictions on sulfur hexafluoride insulation create compliance friction for switching compartments in medium-voltage capacitor banks, extending design validation timelines.
- Technical substitution:Static synchronous compensators and STATCOM systems displace conventional capacitor banks in dynamic reactive power applications requiring sub-cycle response.
Strategic Opportunities
- Rural electrification gaps:India's state electricity boards require decentralized reactive power compensation for agricultural pump loads and distribution transformer upgrades in underserved districts.
- Digital twin integration:Convergence of capacitor hardware with cloud-based asset management platforms creates recurring software revenue streams alongside equipment sales.
- China's dual carbon goals:National Energy Administration mandates for renewable energy penetration drive procurement of harmonic filter capacitors for photovoltaic inverter installations.
Industry Challenges
- Commissioning expertise shortage:Utilities struggle to source field engineers capable of configuring protection relays and tuning harmonic filter banks for site-specific impedance conditions.
- Legacy system interoperability:Digital capacitor banks with IEC 61850 communication protocols face integration friction with electromechanical substation automation systems installed decades prior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitor Bank Market |
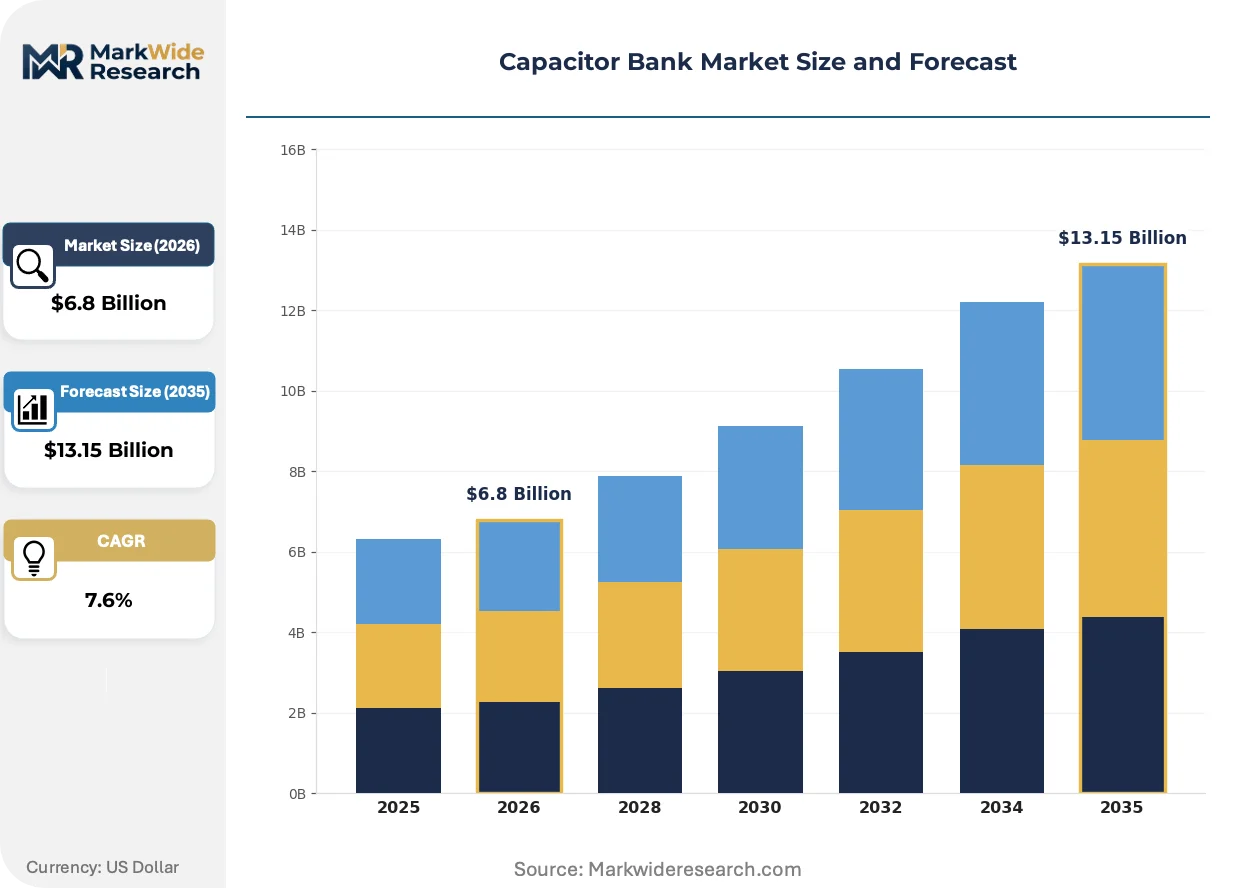
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Capacitors, Power Factor Correction Capacitors, Harmonic Filter Capacitors, Energy Storage Capacitors Application: Electrical Utilities, Renewable Energy, Industrial Automation, Rail Transportation End User: Manufacturing, Construction, Telecommunications, Transportation Technology: Electrolytic, Ceramic, Film, Aluminum |
| Companies Covered | ABB, Schneider Electric, Siemens, Eaton, General Electric, Hitachi Energy, Arteche Group, CIRCUTOR, Vishay Intertechnology Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitor Bank Market Emerging Trajectories
Capacitor bank architecture is fragmenting from centralized substation installations toward distributed edge deployments, with hardware design and service models adapting to accommodate intermittent renewable generation patterns and predictive maintenance requirements.
Self-healing metallized film technology is modularizing capacitor cell construction, allowing individual element failure without catastrophic unit loss. Distribution utilities in Germany adopt these designs for remote rural substations where maintenance access is constrained. The technology is modularizing procurement patterns, enabling utilities to specify standardized cell blocks across multiple voltage classes rather than custom-engineered assemblies.
China's GB standards for ultra-high-voltage direct current transmission mandate enhanced reactive power compensation at converter stations, tightening technical specifications for 800 kV and 1100 kV capacitor banks. Domestic manufacturers retool production lines toward higher-voltage film dielectric formulations. State Grid Corporation procurement tenders now require full traceability of polypropylene resin batches and accelerated aging test documentation.
Industrial buyers increasingly unbundle capacitor hardware purchases from installation and commissioning services, treating these as separate contract lines with distinct vendor qualification criteria. European manufacturing facilities lead this pattern, driven by internal engineering teams seeking direct control over protection settings and harmonic analysis. The shift compresses margins for traditional turnkey suppliers while opening specialist commissioning consultancies.
Capacitor Bank Market Segmentation
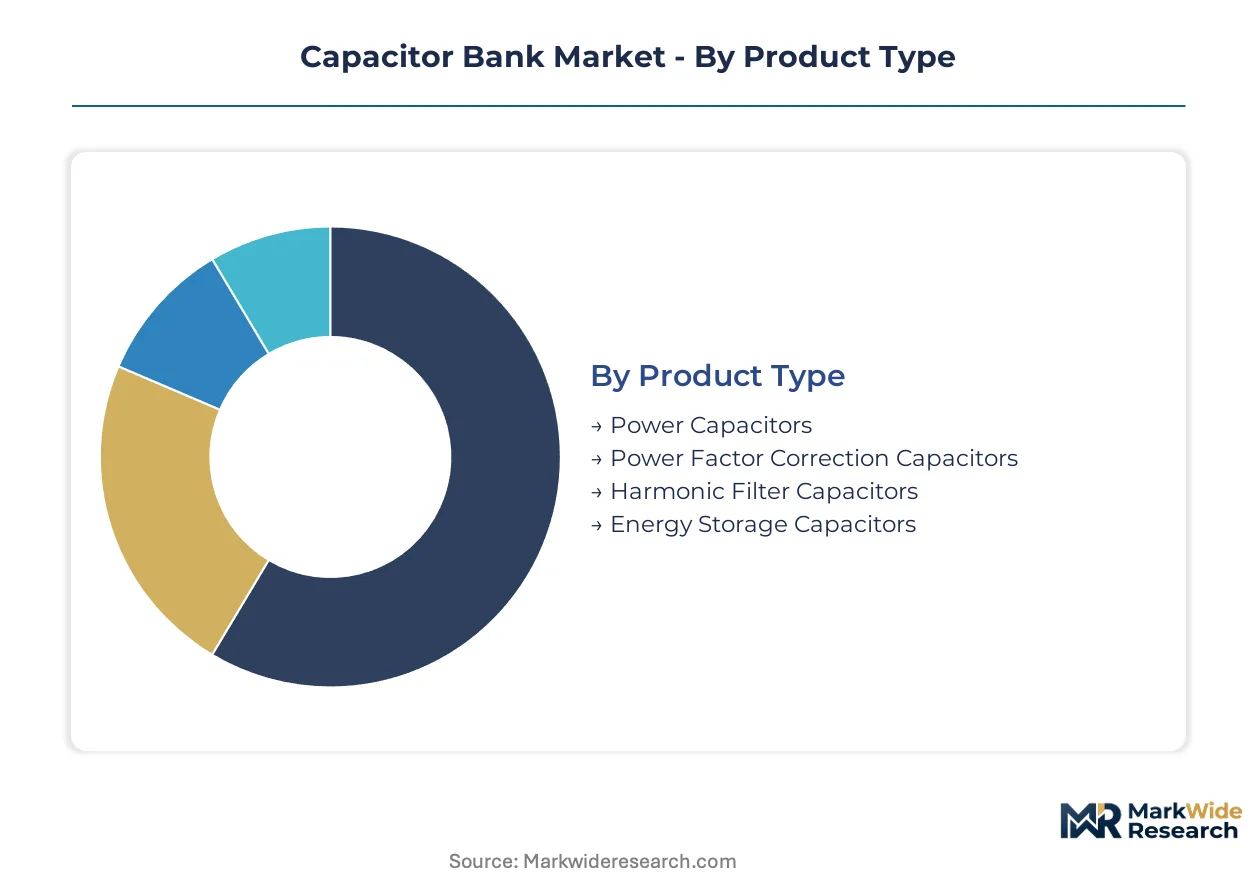
Capacitor bank procurement patterns diverge sharply between standalone substation installations and embedded systems within larger power electronics assemblies. Understanding these integration pathways clarifies where specification complexity accumulates and where commoditization pressures dominate.
Product Type:
Standalone capacitor banks occupy utility substations and industrial switchyards, while embedded variants integrate inside variable frequency drives, photovoltaic inverters, and traction power units.
- Power Factor Correction Capacitors:These assemblies employ metallized polypropylene film dielectrics rated 0.4 kV to 36 kV, delivering reactive power compensation in discrete steps through electromechanical switching. State electricity boards in Maharashtra and Gujarat deploy these units extensively to reduce technical losses across agricultural distribution feeders. Industrial facilities in Tamil Nadu specify automatic capacitor banks with detuned reactors to avoid harmonic resonance conditions.
- Harmonic Filter Capacitors:Specially wound cells with reinforced dielectric withstand capability operate at elevated temperatures under nonlinear load conditions. Manufacturing facilities with dense variable frequency drive populations in Shenzhen and Dongguan drive procurement volume as local environmental regulations tighten electromagnetic compatibility enforcement. These systems require site-specific tuning against measured impedance spectra.
- Power Capacitors:General-purpose units serve motor starting and lighting compensation applications across commercial building infrastructure.
- Energy Storage Capacitors:High-pulse-current designs interface with lithium-ion battery systems in grid-scale hybrid installations.
Volume placements concentrate in power factor correction capacitors; the faster expansion belongs to harmonic filter capacitors.
Application:
Cost tier differentiation separates mission-critical grid infrastructure from price-sensitive industrial deployments, with renewable energy installations occupying a middle tier where performance guarantees command modest premiums.
- Electrical Utilities:Transmission operators specify rack-mounted capacitor banks with IEC 61850 communication for centralized SCADA integration. State Grid Corporation procurement tenders for UHVDC converter stations mandate 800 kV and 1100 kV film dielectric formulations with full resin batch traceability. Distribution utilities prioritize maintenance access and hot-spare redundancy over capital cost minimization.
- Industrial Automation:Discrete manufacturing plants deploy compact automatic capacitor banks with integrated power factor controllers. Automotive assembly lines in Bavaria and Baden-Württemberg specify these units to avoid utility penalty tariffs while maintaining power quality for precision welding equipment. Procurement teams unbundle hardware from commissioning services to retain direct control over protection settings.
- Renewable Energy:Photovoltaic and wind farm developers face FERC Order 2023 mandates for enhanced reactive power capability at interconnection points.
- Rail Transportation:Traction substations require harmonic filtering against 25 Hz and 50 Hz rectifier ripple in electrified corridors.
Capital expenditure intensity peaks in electrical utilities; renewable energy applications are expanding most quickly as interconnection standards tighten.
End User:
Customer type segmentation reveals divergent technical literacy levels, with manufacturing and telecommunications buyers demanding predictive maintenance integration while construction and transportation procurement remains transactionally focused.
- Manufacturing:Heavy industrial facilities with continuous process loads represent the most sophisticated specification environment. Steel mills and cement plants in Chhattisgarh and Odisha deploy tuned harmonic filter banks with real-time temperature monitoring to prevent dielectric thermal runaway. These buyers negotiate lifecycle cost contracts encompassing capacitor cell replacement schedules.
- Telecommunications:Data center operators specify low-loss film capacitors for uninterruptible power supply DC-link applications. Hyperscale facilities in Frankfurt and Amsterdam prioritize fire safety through dry resin impregnation rather than oil-filled designs. Procurement emphasizes mean time between failures documentation over initial capital cost.
- Construction:Temporary power installations and building services represent price-sensitive spot purchasing with minimal technical specification.
- Transportation:Airport and port authorities deploy power factor correction for large motor loads with intermittent duty cycles.
Specification complexity concentrates in manufacturing; telecommunications shows the steepest expansion trajectory as data center construction accelerates.
Technology:
Material science maturity separates established dielectric platforms from emerging formulations, with film technology commanding premium positioning against commodity aluminum and ceramic alternatives.
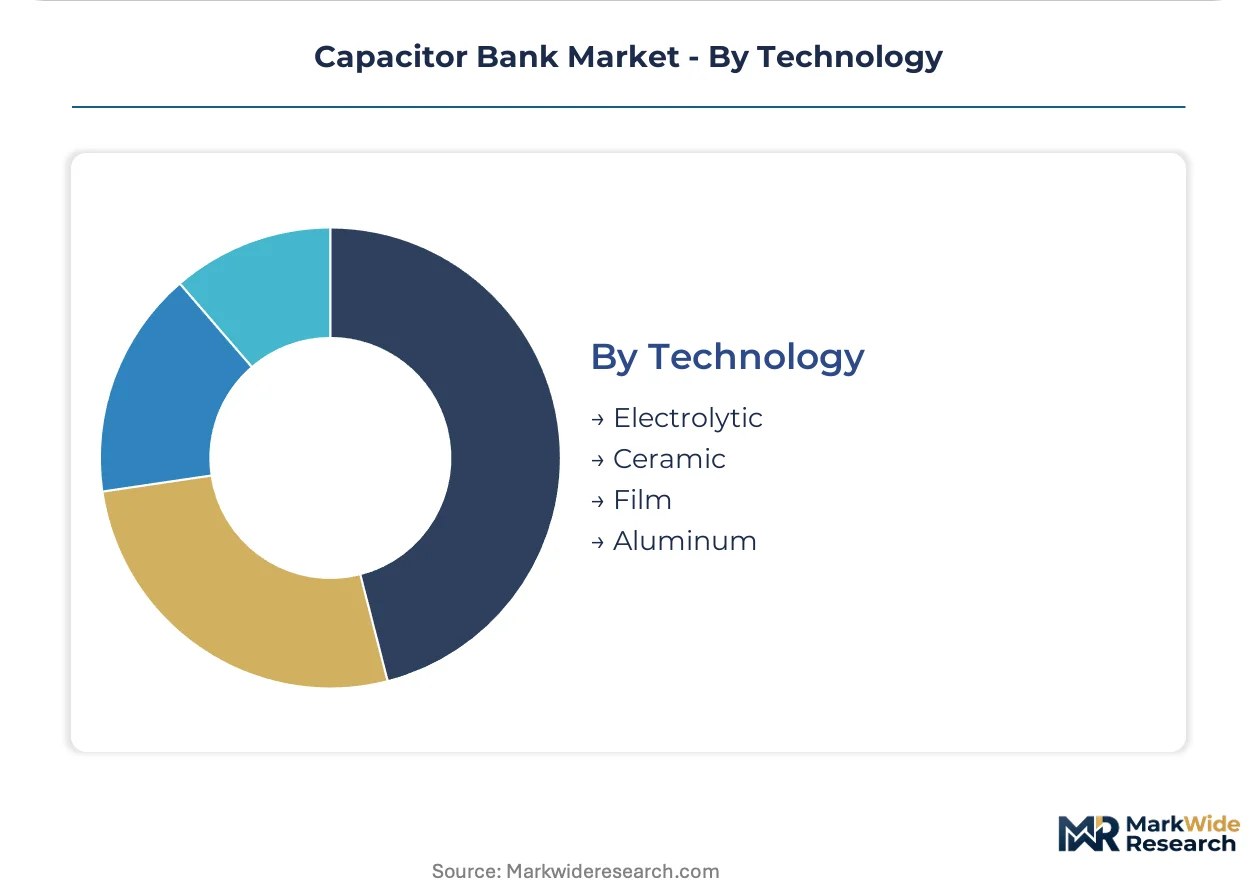
- Film:Biaxially oriented polypropylene dominates medium and high-voltage applications through self-healing metallization patterns that isolate individual element failures. German and Japanese specialty chemical producers concentrate supply of base resin, exposing capacitor manufacturers to input cost volatility. UHVDC projects in China specify accelerated aging test documentation for every resin batch.
- Electrolytic:Aluminum oxide dielectrics serve DC-link and energy storage applications where high capacitance density outweighs voltage withstand limitations. These units dominate variable frequency drive internal DC buses and photovoltaic inverter DC-link positions.
- Ceramic:Multilayer chip designs occupy low-voltage power electronics and control circuit applications.
- Aluminum:Electrolytic constructions with etched foil electrodes serve cost-driven motor run and lighting applications.
Revenue margins peak in film technology; electrolytic platforms are gaining share fastest through renewable energy inverter proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biaxially oriented polypropylene film production concentrates in Germany and Japan, anchoring supply-side geography for capacitor dielectrics while demand-side procurement accelerates across transmission utilities in India and ultra-high-voltage converter stations in China.
China
State Grid Corporation drives procurement of 800 kV and 1100 kV film capacitor banks for ultra-high-voltage direct current converter stations under National Energy Administration renewable integration mandates. GB standards mandate full resin batch traceability and accelerated aging documentation. Domestic manufacturers in Xi'an and Shenyang retool production lines toward higher-voltage dielectric formulations.
India
State electricity boards in Maharashtra, Gujarat, and Tamil Nadu deploy automatic power factor correction systems to reduce agricultural distribution losses and avoid utility penalty tariffs. Central Electricity Authority technical standards tighten reactive power compensation requirements for renewable interconnections. Industrial clusters in Pune and Ahmedabad specify detuned reactor-equipped banks for harmonic resilience.
Germany
Distribution utilities adopt self-healing metallized film designs for remote rural substations where maintenance access is constrained. EU F-Gas Regulation restrictions on sulfur hexafluoride insulation push manufacturers toward dry-type and vacuum-interrupter switching compartments. Engineering procurement in Bavaria and Baden-Württemberg unbundles hardware purchases from commissioning services.
United States
FERC Order 2023 mandates enhanced reactive power capability from inverter-based solar and wind resources connecting to bulk power systems. IEEE 1531 standards expand specification complexity for new capacitor bank installations at interconnection points. Procurement concentrates among transmission operators in Texas and California managing renewable integration on congested corridors.
Japan
Specialty chemical producers concentrate supply of biaxially oriented polypropylene base resin, exposing downstream capacitor manufacturers to input cost volatility. METI energy efficiency directives drive industrial motor load compensation in automotive and electronics manufacturing. Production clusters in Osaka and Nagoya supply metallized film dielectrics for regional and export markets.
Capacitor Bank Market Vendor Landscape
Global majors compete with regional champions across dielectric technology and voltage class positioning. The vendor base organizes around three tiers: integrated electrical conglomerates with installed base service revenues, specialized capacitor manufacturers with film metallization expertise, and emerging Asian fabricators with cost-optimized medium-voltage offerings. Strategic moves concentrate on backward integration into polypropylene resin supply and digital twin software bundling with hardware deployments.
Within the integrated conglomerate tier, ABB and Schneider Electric exemplify positioning through legacy European grid infrastructure and power management software integration. Siemens anchors the rail electrification specialization vector where harmonic filtering requirements are tightening. These entities represent archetypes of service revenue sustenance through aging substation network maintenance rather than pure equipment sales competition.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton |
| General Electric |
| Hitachi Energy |
| Arteche Group |
| CIRCUTOR |
| Vishay Intertechnology Inc |
| Others |
Supply Flow & Price Mechanics
Biaxially oriented polypropylene resin pricing indices cascade through capacitor manufacturing tiers, compressing margins for medium-voltage fabricators while premium film metallizers absorb volatility through long-term offtake contracts with State Grid Corporation and Indian state electricity boards.
Pricing Analysis
Warranty bundling separates turnkey suppliers from hardware-only vendors, with European industrial buyers increasingly unbundling commissioning services to retain control over protection relay configuration. Three-tier pricing structure across premium, standard, and economy levels reflects dielectric grade differentiation and IEC 61850 protocol integration. Cost compression in economy-tier medium-voltage banks is intensifying because Asian fabricators compete on resin efficiency and automated winding throughput. Manufacturing facilities in India's industrial corridors exhibit highest price sensitivity, while UHVDC converter station procurement teams prioritize traceability documentation over capital cost minimization.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's GB standard localization requirements are reshaping sourcing patterns, compelling multinational vendors to establish metallized film production within Xi'an and Pune industrial zones. Raw material supply draws from German and Japanese specialty chemical producers for base resin, Chinese manufacturers for aluminum metallization equipment, and domestic fabricators for steel enclosure stampings. Single-source vulnerability concentrates in biaxially oriented polypropylene film, where three producers control global supply. Distribution runs through direct utility tender participation in China and India, specialist electrical distributors in Germany, and integrated service contracts in North American transmission markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The capacitor bank market occupies a technology-transition phase where self-healing metallized film architectures displace conventional all-film designs, forcing procurement pattern adaptation across voltage classes and application segments.
For Market Incumbents: To counter displacement by static synchronous compensators in dynamic reactive power applications, ABB and Schneider Electric should deepen backward integration into polypropylene resin supply through captive sourcing agreements with German specialty chemical producers, while accelerating digital twin software bundling to sustain service revenue streams across aging European substation networks. For New Entrants and Emerging Players: Specialist commissioning consultancies represent the most penetrable service layer, given European manufacturing facilities' unbundling of hardware purchases from installation contracts. Agricultural distribution feeder upgrades across Maharashtra and Gujarat offer white-space volume, accessible through partnerships with Indian state electricity board engineering departments rather than direct OEM competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier film metallization specialists with UHVDC qualification in China's interior provinces, where State Grid Corporation procurement consolidation is squeezing subscale competitors. Long-term viability hinges on dual-use capability spanning grid infrastructure and rail electrification harmonic filtering. Watch for GB standard revision announcements as inflection indicators for technical specification tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin | Captive supply from German and Japanese specialty chemical producers insulates margin volatility from input cost swings. |
| Digital Twin Platform Integration | Cloud-based asset management bundling with hardware deployments creates recurring software revenue alongside equipment sales. |
| UHVDC Dielectric Qualification | GB standard compliance for 800 kV and 1100 kV film formulations unlocks State Grid Corporation procurement tenders. |
| Harmonic Filter Bank Specialization | Shenzhen and Dongguan manufacturing density drives procurement volume as electromagnetic compatibility enforcement tightens. |
| Commissioning Service Unbundling | Direct control over protection settings and harmonic analysis appeals to Bavarian and Baden-Württemberg engineering teams. |
Methodological Framework
Multi-period observation of capacitor bank procurement tender volumes, resin pricing indices, and UHVDC project development pipelines anchored the trend analysis, supplemented by interviews with utility planning officers at State Grid Corporation and Indian state electricity boards, EPC contractors specializing in substation automation, film dielectric R&D directors at German and Japanese specialty chemical producers, and aftermarket service heads at European electrical distributors. Secondary validation drew from FERC Order 2023 filings, EU F-Gas Regulation implementation notices, Central Electricity Authority technical standards, customs and trade data for biaxially oriented polypropylene film, and SEC 10-K disclosures from integrated electrical conglomerates. Bottom-up segment sizing triangulated against top-down grid investment forecasts.
Input-output matrices mapped dielectric material throughput to installed capacity across voltage classes, with segmentation modeling spanning product type, application, end user, and technology dimensions throughout the forecast period. CAGRs were derived from regression analysis against renewable interconnection mandates and infrastructure replacement cycles. Industry-specific forecast inputs incorporated FERC reactive power capability requirements and EU greenhouse gas insulation restrictions.
Several conditions sit outside the modeled scope, including unannounced GB standard revisions, abrupt trade policy shifts affecting polypropylene film tariffs, and breakthrough solid-state reactive compensation technologies that could accelerate STATCOM displacement. Forecasts reflect documented assumptions about grid modernization expenditure continuity and dual carbon goal enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
India Electrical Enclosures Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Global Busbar Trunking Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
Busbar Trunking System Market
Electrical Equipment
Global Digital Panel Meter Market