
 Low Voltage Electric Motor Market | 2026-2036
Low Voltage Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Low Voltage Electric Motor Market Intelligence
Modular motor-drive packages is repositioning buyer choice away from standalone hardware toward integrated electromechanical systems. ABB Ltd. leverages its automation portfolio to bundle variable frequency drives with low voltage motors for process industries. Siemens AG anchors European demand through its Simotics platform and extensive service network. WEG S.A. competes aggressively on manufacturing scale from its Brazilian and Mexican facilities.
Low voltage electric motors convert electrical energy into mechanical motion at input voltages typically below 1000 V, with squirrel-cage induction and permanent magnet synchronous configurations dominating industrial installations. These machines power conveyor systems, pumps, compressors, and fans across manufacturing floors and infrastructure sites. AC motors hold the largest installed base due to reliability and minimal maintenance requirements, while servo motors capture premium positioning in robotics and precision positioning applications. The industrial automation application segment commands substantial motor volumes as factories retrofit legacy lines with connected, sensor-equipped units.
Efficiency regulations including the EU Ecodesign Directive, US DOE motor efficiency standards, and China's GB 18613 standard are phasing out IE2 class products and mandating IE3 or higher tiers across most power ranges. Compliance testing by notified bodies under CE marking and third-party certification through UL and CSA shapes market access for multinational suppliers. Stakeholders must track how regional efficiency tier transitions and carbon border adjustment mechanisms affect sourcing strategies and product platform rationalization.
Market Dynamics
IE4 and IE5 efficiency mandates are compressing product lifecycles and forcing manufacturers to redesign core platforms around permanent magnet and synchronous reluctance architectures.
Growth Catalysts
- EU Ecodesign Directive:Minimum energy performance standards are phasing out IE2 motors across the 0.75-375 kW range, compelling fleet replacements in German and Italian process industries.
- HVAC retrofit cycles:Commercial building decarbonization programs in the United States are accelerating demand for electronically commutated motors in chiller and air handling units.
- Industrial automation density:China's robotics installations per 10,000 workers are climbing, pulling precision servo motors into automotive and electronics assembly lines.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings tied to Chinese export quotas are squeezing margins on permanent magnet synchronous motor platforms.
- Copper concentrate supply:Chilean and Peruvian mining disruptions are transmitting volatility into stator winding costs for induction motor producers.
- IE5 certification bottlenecks:Limited accredited test laboratories under IEC 60034-30-1 are extending time-to-market for premium efficiency products.
Strategic Opportunities
- India industrial corridor buildout:Dedicated freight corridors and smart city infrastructure are creating captive demand for low voltage motors in material handling and water treatment.
- Digital twin integration:Sensor-embedded motors with edge analytics are opening predictive maintenance revenue streams in pulp and paper operations.
- US Inflation Reduction Act:Domestic content incentives for clean energy manufacturing are reshoring motor production for wind and solar balance-of-plant equipment.
Industry Challenges
- Magnet motor repair expertise:Permanent magnet rotor demagnetization risks require specialized service capabilities that most independent motor shops lack.
- Legacy drive compatibility:New IE4/IE5 motor electrical characteristics often conflict with installed variable frequency drive parameter sets, forcing costly control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Voltage Electric Motor Market |
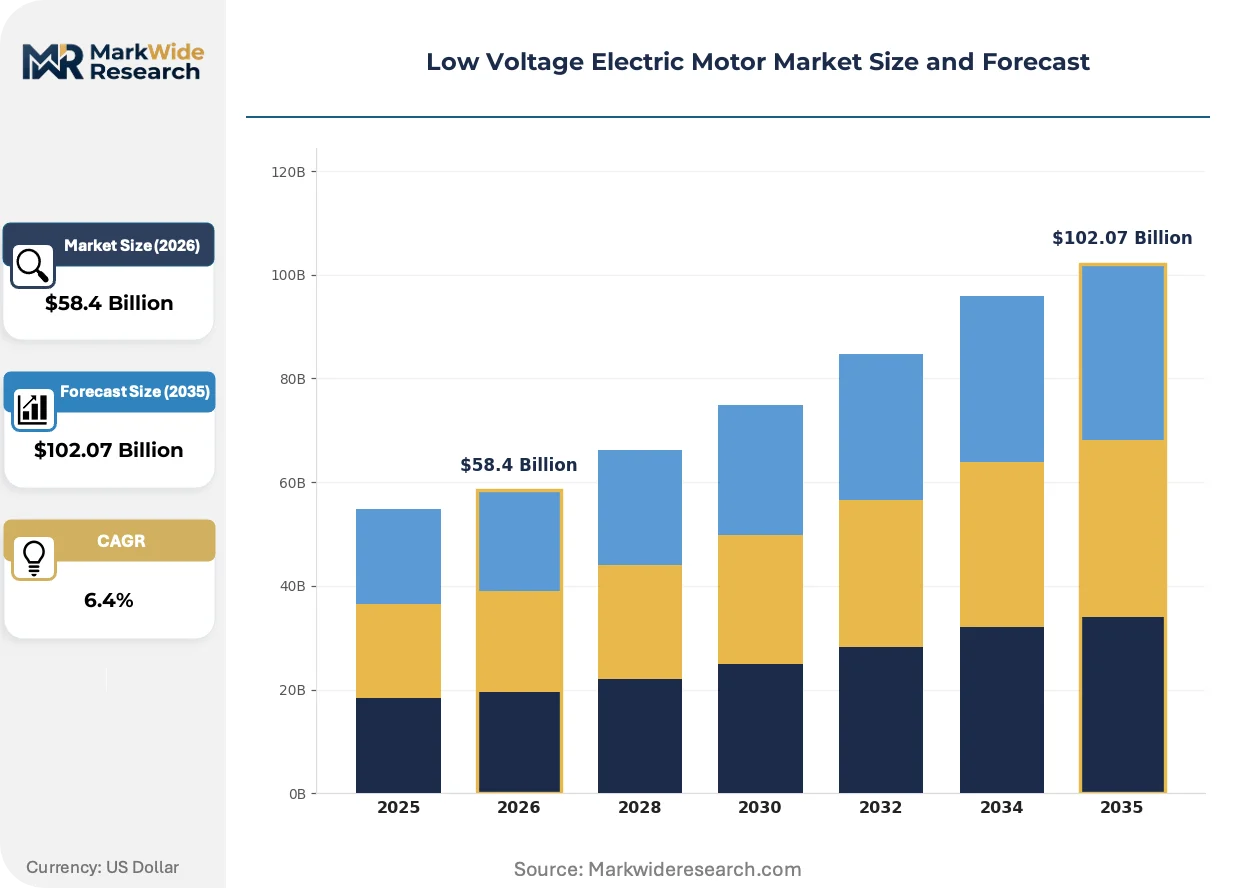
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $102.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motor, DC Motor, Servo Motor, Stepper Motor End User: Manufacturing, HVAC, Automotive, Home Appliances Technology: Brushless, Induction, Synchronous, Asynchronous Application: Industrial Automation, Renewable Energy, Robotics, Water Treatment |
| Companies Covered | Nidec Corporation, Toshiba International Corporation, ABB Ltd., Schneider Electric SE, Rockwell Automation, Siemens AG, Regal Beloit Corporation, Johnson Electric Holdings Limited, WEG S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Voltage Electric Motor Market Strategic Shifts & Innovations
Permanent magnet synchronous motor technology is consolidating its position across premium efficiency tiers while digitalization redefines how motor performance is monetized and maintained.
Synchronous reluctance and permanent magnet assisted synchronous reluctance motor designs are consolidating technical leadership in the IE5 efficiency class. Food and beverage processors with continuous duty cycles are adopting these platforms fastest. The technology is consolidating supplier R&D budgets away from incremental induction motor improvements.
China's GB 18613-2020 standard is accelerating IE3 adoption across domestic manufacturing while tightening test tolerances. Exporters to the Chinese market must now certify through the China Quality Certification Centre. Motor producers are responding by regionalizing product platforms rather than attempting universal compliance.
Condition monitoring subscriptions are displacing traditional break-fix maintenance contracts in heavy process industries. Mining and cement operators are bundling vibration and thermal analytics with motor procurement. This shift is most pronounced in Australian and South African extractive operations where unplanned downtime costs exceed motor replacement value.
Low Voltage Electric Motor Market Segmentation
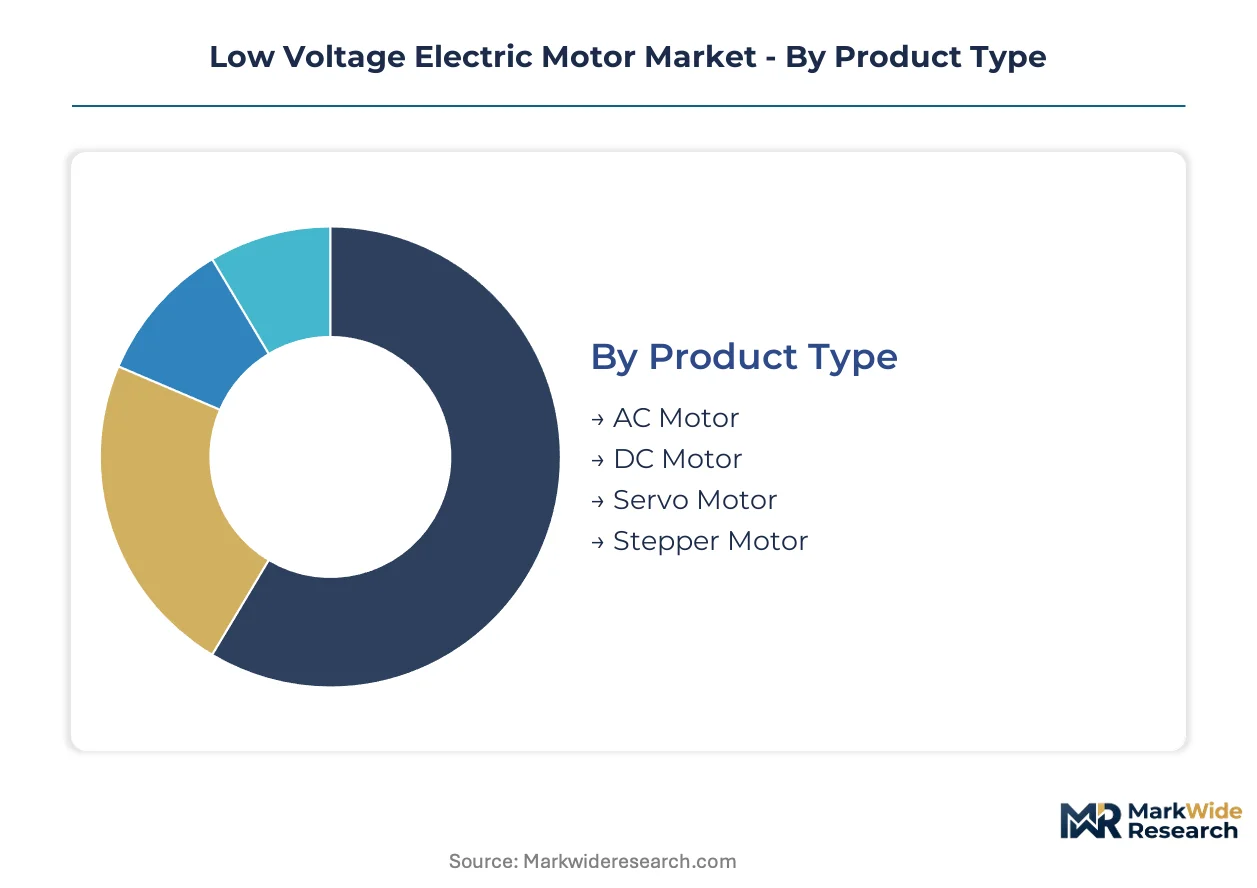
Segmentation reveals how efficiency regulations and application requirements reshape procurement patterns across motor technologies. Understanding these divisions clarifies where IE4 and IE5 upgrade cycles concentrate investment and where legacy equipment persists.
Product Type:
Upgrade cycles vary sharply by motor architecture, with efficiency mandates forcing faster replacement in some categories than others.
- AC Motor:Squirrel-cage induction designs dominate installed base across conveyor systems and pump stations. German and Italian process industries are phasing out IE2 units under EU Ecodesign Directive timelines, pulling replacement volume toward IE3 and IE4 tiers.
- Servo Motor:Permanent magnet synchronous configurations deliver precision positioning for robotics and CNC machinery. China's automotive and electronics assembly lines are absorbing the steepest volume climbs as robotics density per 10,000 workers accelerates.
- DC Motor:Brushed and brushless designs persist in battery-powered mobility and material handling equipment where speed control simplicity matters.
- Stepper Motor:Open-loop positioning systems serve cost-sensitive automation in packaging machinery and 3D printing equipment.
AC motors sit at the top of the volume ranking, with servo motors climbing the fastest.
End User:
Cost tier differentiation separates premium efficiency investments from price-sensitive procurement across customer categories.
- Manufacturing:Factory automation and process lines demand continuous-duty motors with predictive maintenance capability. Food and beverage processors with 24-hour operations are adopting IE5 synchronous reluctance platforms fastest to cut lifetime energy costs.
- HVAC:Commercial building retrofits in the United States are accelerating electronically commutated motor deployment in chillers and air handling units under decarbonization program incentives.
- Automotive:Electric vehicle production lines and battery assembly operations require precision servo systems for welding and component placement.
- Home Appliances:Washing machines and refrigeration compressors prioritize compact induction and brushless DC designs for noise reduction and energy labeling compliance.
Manufacturing commands the largest installed base, though HVAC is expanding most quickly through commercial retrofit mandates.
Technology:
Application requirements dictate technology selection, with efficiency tiers and control precision driving architectural choices.
- Induction:Rugged squirrel-cage designs with minimal maintenance dominate bulk industrial applications. Copper winding cost volatility from Chilean and Peruvian mining disruptions is squeezing margins for producers of these machines.
- Brushless:Permanent magnet and electronically commutated variants eliminate brush wear for extended service intervals. HVAC and appliance sectors are standardizing these for variable-speed operation.
- Synchronous:Permanent magnet and reluctance architectures achieve IE4 and IE5 efficiency ratings. Limited accredited test laboratories under IEC 60034-30-1 are extending certification timelines for these premium products.
- Asynchronous:Standard induction designs without rotor excitation persist in cost-sensitive applications where efficiency regulations have not yet tightened.
Induction technology retains the broadest installed footprint, while synchronous designs are gaining share fastest on efficiency mandates.
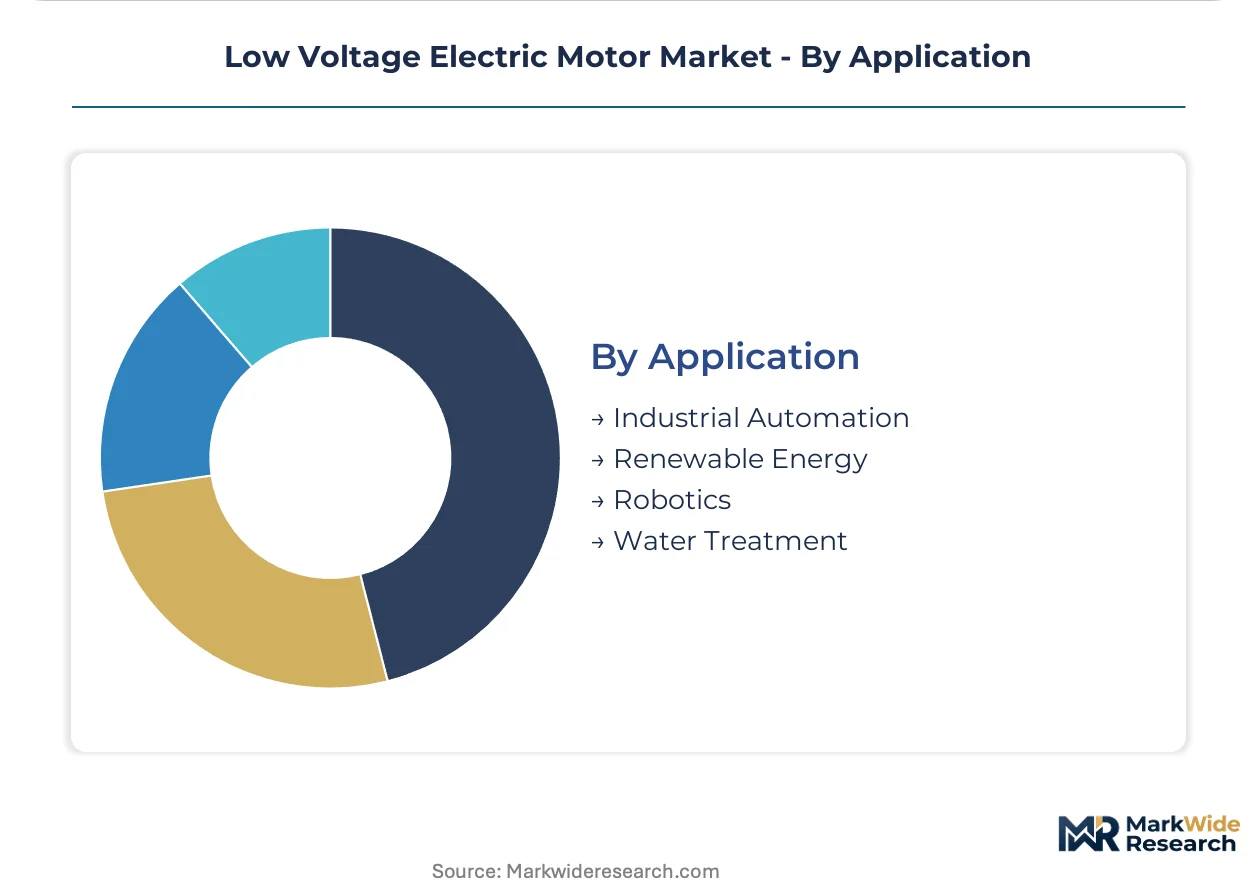
Application:
Supply concentration in motor manufacturing clusters shapes how quickly each application segment accesses next-generation efficiency platforms.
- Industrial Automation:Connected, sensor-equipped motors with edge analytics enable predictive maintenance in pulp and paper operations. Mining and cement operators in Australia and South Africa are bundling condition monitoring subscriptions with procurement.
- Robotics:Precision positioning requirements pull high-dynamic servo motors into automotive assembly and electronics manufacturing. China's installation growth rates per 10,000 workers outpace other geographies.
- Renewable Energy:Wind turbine pitch systems and solar tracking equipment demand reliable low voltage drives. US Inflation Reduction Act domestic content incentives are reshoring production for balance-of-plant equipment.
- Water Treatment:Pump and aeration systems in municipal and industrial facilities require continuous-duty motors with corrosion-resistant enclosures.
Industrial automation represents the largest addressable base, with robotics showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial motor manufacturing in the late nineteenth century, establishing technical standards that still govern efficiency measurement today. The country's engineering heritage created certification frameworks later adopted across Europe and Asia.
Germany
Process industries in the Rhine-Ruhr corridor are replacing IE2 motors under EU Ecodesign Directive deadlines. The Federal Environment Agency enforces MEPS compliance through mandatory efficiency labeling. Stuttgart's manufacturing cluster hosts testing laboratories certifying IE4 and IE5 machines for export markets.
China
Industrial automation upgrades and renewable energy installations are accelerating procurement of premium efficiency motors. GB 18613-2020 mandates IE3 minimums across domestic manufacturing, enforced by the China Quality Certification Centre. Shanghai and Suzhou industrial parks concentrate permanent magnet motor production for robotics and wind turbine applications.
United States
Commercial building decarbonization programs are driving HVAC retrofit demand for electronically commutated motors. The Department of Energy motor efficiency standards phase out sub-IE3 products across the 0.75-375 kW range. Texas and Ohio manufacturing corridors supply motors for oilfield equipment and automotive assembly lines.
India
Dedicated freight corridors and smart city infrastructure are creating captive demand for material handling and water treatment motors. Bureau of Indian Standards efficiency regulations align with IEC frameworks for international market access. Gujarat and Maharashtra industrial zones host assembly operations serving domestic OEMs and Middle East export markets.
Brazil
Mining and agribusiness operations require continuous-duty motors for bulk material handling and irrigation systems. ANEEL efficiency programs promote IE3 adoption in industrial electricity tariffs. São Paulo state manufacturing clusters produce induction motors for Latin American distribution networks.
Low Voltage Electric Motor Market Key Industry Players
Premium-margin players sit above commodity-margin players across efficiency tier specialization and service bundling. The market structures into three concentration bands: diversified electromechanical conglomerates with full automation portfolios, regional scale manufacturers competing on delivery speed, and specialized servo motor engineers serving precision applications. Strategic moves center on platform consolidation around permanent magnet architectures and predictive maintenance service contracts.
Within the diversified conglomerate tier, ABB Ltd., Siemens AG, and WEG S.A. exemplify contrasting geographic anchoring strategies. The Swiss-Swedish entity represents integrated automation bundling, the German engineering group occupies a position anchored in European service density, and the Brazilian S.A. structure exemplifies manufacturing scale from emerging market production bases.
| Leading Market Players |
|---|
| Nidec Corporation |
| Toshiba International Corporation |
| ABB Ltd. |
| Schneider Electric SE |
| Rockwell Automation |
| Siemens AG |
| Regal Beloit Corporation |
| Johnson Electric Holdings Limited |
| WEG S.A. |
| Others |
Cost & Logistics Intelligence
Mandatory IE3 and IE4 efficiency upgrades across German and Italian process industries are forcing motor manufacturers to absorb rare earth magnet cost volatility while maintaining competitive positioning against synchronous reluctance alternatives. Buyers now bundle predictive maintenance subscriptions with hardware procurement, compressing upfront margins while extending revenue capture timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IE5 permanent magnet synchronous motors from IE4 induction platforms and IE3 commodity units. Price differentiation hinges on IEC 60034-30-1 certification tier and after-sales service bundling intensity. Cost compression in the standard tier is intensifying because copper winding expenses from Chilean mining disruptions are transmitting directly into stator production costs. OEM procurement teams in automotive and electronics assembly show the highest price sensitivity, while food and beverage processors with continuous duty cycles prioritize lifetime energy cost over upfront capital outlay.
Supply Chain Analysis
Dual-sourcing requirements mandated by European industrial OEMs are forcing qualification of secondary permanent magnet suppliers outside China's export quota system. Manufacturing concentrates in China, Germany, and Brazil, with Shanghai and Suzhou industrial parks dominating permanent magnet rotor production. Raw material dependencies center on neodymium-dysprosium magnet alloys, copper concentrate from Chilean and Peruvian mines, and electrical steel laminations. Single-source vulnerability in rare earth processing creates supply chain risk exposure during quota enforcement periods. Distribution runs through authorized distributor networks and direct OEM contracts, with service bundling increasingly bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EU Ecodesign Directive's IE2 phase-out deadlines are generating replacement demand that outpaces organic industrial expansion.
For Market Incumbents: To counter synchronous reluctance technology erosion of permanent magnet motor share, ABB and Siemens must accelerate backward integration into rare earth magnet recycling capabilities while expanding IE5 test laboratory accreditation capacity in Stuttgart and Shanghai clusters. Certification investment represents the critical defensive lever against margin compression in premium efficiency tiers. For New Entrants and Emerging Players: Enter via specialized servo motor engineering for India's dedicated freight corridor material handling systems, where Bureau of Indian Standards alignment with IEC frameworks creates accessible certification pathways. White-space concentration appears in predictive maintenance software integration for Brazilian mining operations, with channel partnerships through São Paulo industrial distributors offering the most penetrable go-to-market structure. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap synchronous reluctance motor specialists possessing proprietary rotor design IP and existing IE5 test laboratory relationships. Long-term viability over a multi-year horizon favors acquisition targets with established China Quality Certification Centre accreditation and regionalized product platforms rather than universal compliance attempts. Watch for inflection in US Inflation Reduction Act domestic content incentive disbursement rates for clean energy manufacturing reshoring.| Strategic Initiative | Industry Significance |
|---|---|
| IE5 Test Laboratory Accreditation Expansion | Stuttgart and Shanghai certification capacity directly determines time-to-market for premium efficiency product launches. |
| Rare Earth Magnet Recycling Investment | Backward integration into magnet recovery reduces exposure to Chinese export quota volatility for permanent motor platforms. |
| Predictive Maintenance Subscription Bundling | Australian and South African mining operators now bundle vibration analytics with motor procurement, displacing break-fix contracts. |
| Regionalized Product Platform Development | Separate China GB 18613-2020 compliance streams from EU Ecodesign Directive platforms to avoid over-engineered universal designs. |
| Synchronous Reluctance R&D Consolidation | Food and beverage processor adoption of IE5 reluctance architectures is consolidating supplier R&D budgets away from induction improvements. |
Research Approach
Coverage spans Germany, China, the United States, India, and Brazil, with primary inputs from each market gathered through structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and motor distributor channel managers. Secondary validation drew from IEC 60034 standard documentation, EU Ecodesign Directive regulatory filings, China Quality Certification Centre accreditation records, US Department of Energy efficiency standard publications, and customs trade data on copper concentrate and rare earth magnet flows. Bottom-up motor shipment estimates by efficiency tier and application were triangulated against top-down industrial automation capex projections.
Granularity-level modeling disaggregated volume and value outputs across product type, end user, technology architecture, and application segments throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro industrial production indices. Industry-specific forecast inputs included robotics installation density per 10,000 workers in Chinese automotive assembly and commercial building HVAC retrofit cycle timing under US decarbonization program incentives.
Inputs from regulatory filing databases and industrial OEM procurement systems were available through the study window; gaps in real-time rare earth magnet spot pricing and copper concentrate contract terms introduce uncertainty bands around permanent magnet motor margin projections. Deviation in Chinese export quota enforcement severity or Chilean mining labor disruption frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Global Busbar Trunking Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
High Voltage Insulator Market