
 Copper and Copper Alloy Foil Market | 2026-2036
Copper and Copper Alloy Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Copper and Copper Alloy Foil Market Outlook
Software-defined thickness calibration is shifting how copper foil suppliers contract with buyers. LS Mtron Ltd. leverages in-house rolling mills to sustain premium-grade output for Korean battery makers. Mitsui Mining & Smelting Co. Ltd. anchors Japanese supply through refined electrolytic processes. JX Nippon Mining & Metals Corporation dominates high-purity anode foil for next-generation solid-state designs.
Copper and copper alloy foil denotes cold-rolled or electrolytically deposited sheet metal under 0.15 millimetres thick, alloyed with tin, nickel, or zinc to enhance conductivity, corrosion resistance, or tensile strength for precision electrical transmission. Electrolytic copper foil leads volume due to its dominance in printed circuit board and lithium-ion battery current collector applications, while ultra-thin foil commands the fastest expansion trajectory as cell manufacturers pursue energy density gains. Rolled copper foil retains margin concentration in aerospace and high-frequency RF shielding segments where dimensional tolerances tighten below five micrometres.
The EPA regulates copper processing effluent under the Clean Water Act, compelling US mills to adopt closed-loop electrolyte recovery systems that raise capital thresholds for new entrants. China's MEE enforces dual carbon compliance on smelters, redirecting capacity toward low-carbon electrolytic grades preferred by export-facing battery OEMs. Stakeholders must monitor how REACH and RoHS revisions in Europe restrict certain alloy additives, as compliance costs will reshape supplier qualification timelines and regional sourcing decisions.
Market Dynamics
Ultra-thin electrolytic copper foil specifications below six micrometres are compressing supplier margins while battery cell manufacturers consolidate procurement around certified Korean and Japanese mills.
Growth Catalysts
- Solid-state battery commercialization:Next-generation cell architectures require high-purity anode foil with surface roughness below two micrometres, pulling capacity expansion toward electrolytic-grade specialists.
- China's dual carbon enforcement:MEE emissions audits are redirecting smelter output toward low-carbon electrolytic grades that export-facing battery OEMs now specify in purchase agreements.
- Gumi-Jeonju cluster concentration:LG Energy Solution and Samsung SDI anchor cathode supply chains that consume over half of regional ultra-thin foil output, creating localized demand density.
Market Restraints
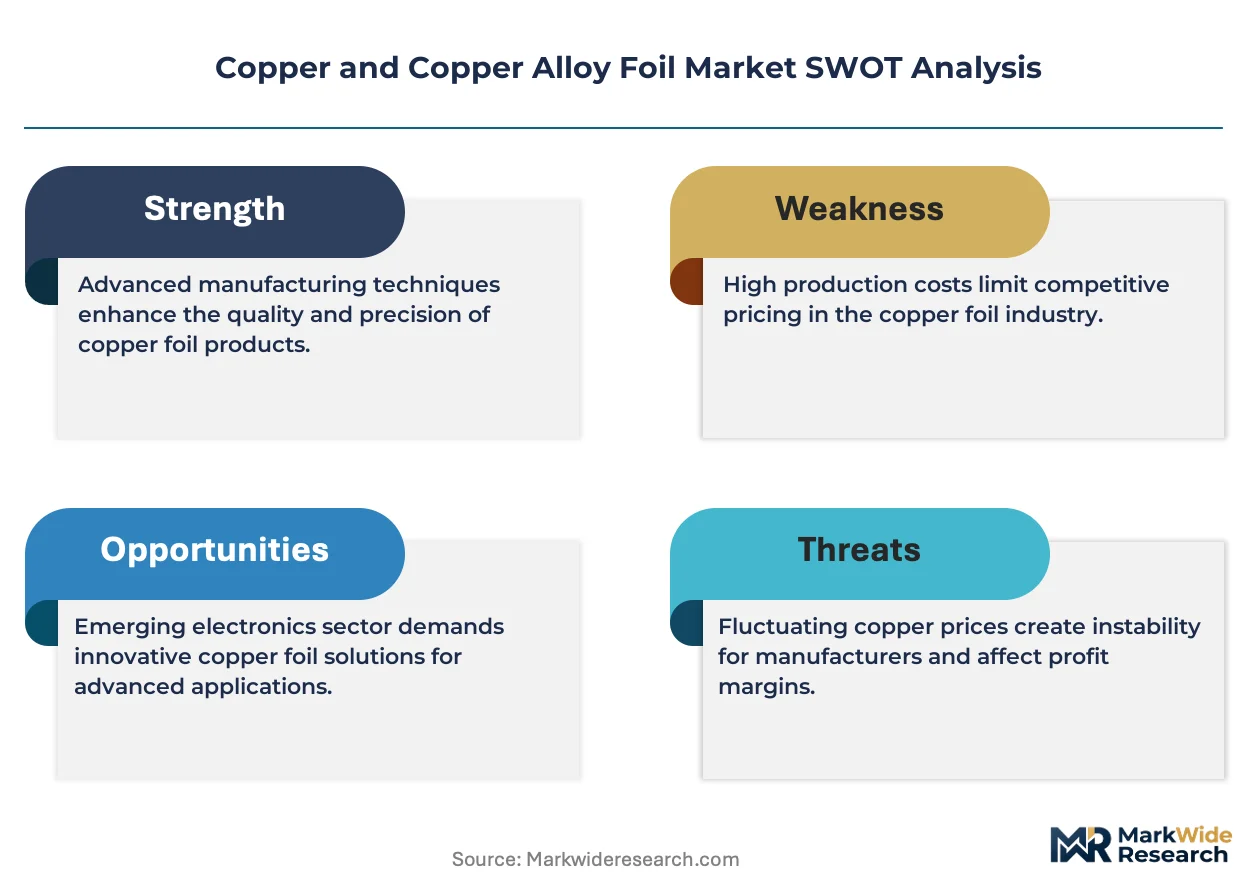
- Copper cathode price volatility:LME price swings above fifteen percent annually compress rolling mill margins and destabilize long-term contract pricing.
- Electrolyte recovery capital intensity:EPA Clean Water Act compliance requires closed-loop systems costing forty million dollars per greenfield site, raising barriers to US capacity expansion.
- Aluminum current collector substitution:Cell manufacturers are testing composite foil laminates that reduce copper mass by sixty percent in prismatic designs.
Strategic Opportunities
- India battery cell localization:PLI scheme incentives for gigafactory construction will create captive demand for electrolytic foil that domestic rolling capacity cannot yet supply.
- RF shielding in satellite constellations:Low-earth orbit hardware requires rolled copper foil with dimensional tolerances below five micrometres for thermal management.
- EU Battery Regulation traceability:Carbon footprint disclosure mandates from 2027 will premiumize low-carbon electrolytic grades in European EV supply chains.
Industry Challenges
- Surface treatment chemistry expertise:Battery-grade foil requires proprietary organic-inorganic coating formulations that few mills have developed in-house.
- Solid-state qualification timelines:OEM validation cycles for next-generation cell designs extend eighteen to twenty-four months, freezing supplier selection decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper and Copper Alloy Foil Market |
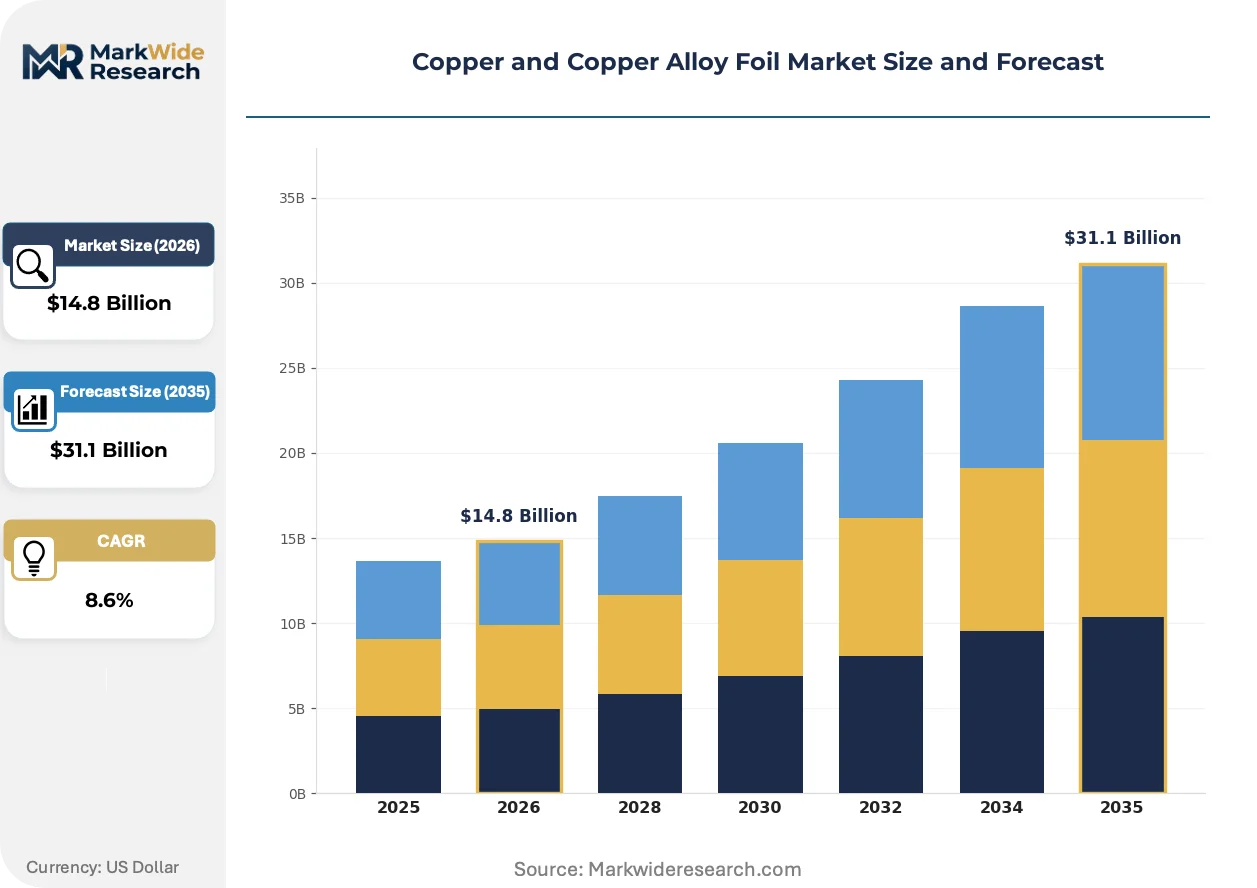
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Copper Foil, Rolled Copper Foil, Bimetallic Foil, Copper Alloy Foil End User: Electrical, Electronics, Automotive, Consumer Goods Thickness: Thin Foil, Medium Foil, Thick Foil, Ultra-Thin Foil Application: Capacitors, Connectors, Heat Sinks, Battery Components |
| Companies Covered | LS Mtron Ltd., Chang Chun Group, Mitsui Mining & Smelting Co. Ltd., Nan Ya Plastics Corporation, Circuit Foil Luxembourg, Furukawa Electric Co. Ltd., ILJIN Materials Co. Ltd., Kingboard Copper Foil Holdings Limited, JX Nippon Mining & Metals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper and Copper Alloy Foil Market Strategic Shifts
Software-defined thickness calibration is rewiring how mills contract with buyers, replacing specification sheets with real-time data feeds that travel with each coil.
Electrolytic deposition with in-situ roughness monitoring is electrifying quality assurance protocols. Battery manufacturers now reject coils lacking digital twin traceability. Korean cathode producers are mandating this capability in 2024 supply agreements, compressing qualification windows for non-compliant mills.
REACH and RoHS revisions in Europe are restricting certain tin-nickel alloy additives used in corrosion-resistant foil. ECHA substance evaluations are forcing reformulation of legacy products. High-frequency RF shielding segments in Germany and France are accelerating certification of alternative alloy systems ahead of 2026 enforcement deadlines.
Long-term offtake contracts with embedded price collars are displacing spot-market purchases for electrolytic grades. Tier-one battery cell manufacturers now lock three-year supply commitments directly with Japanese and Korean mills. This concentration is most visible in South Korea's Gumi industrial zone, where procurement teams have abandoned distributor channels for mill-direct relationships.
Copper and Copper Alloy Foil Market Segmentation
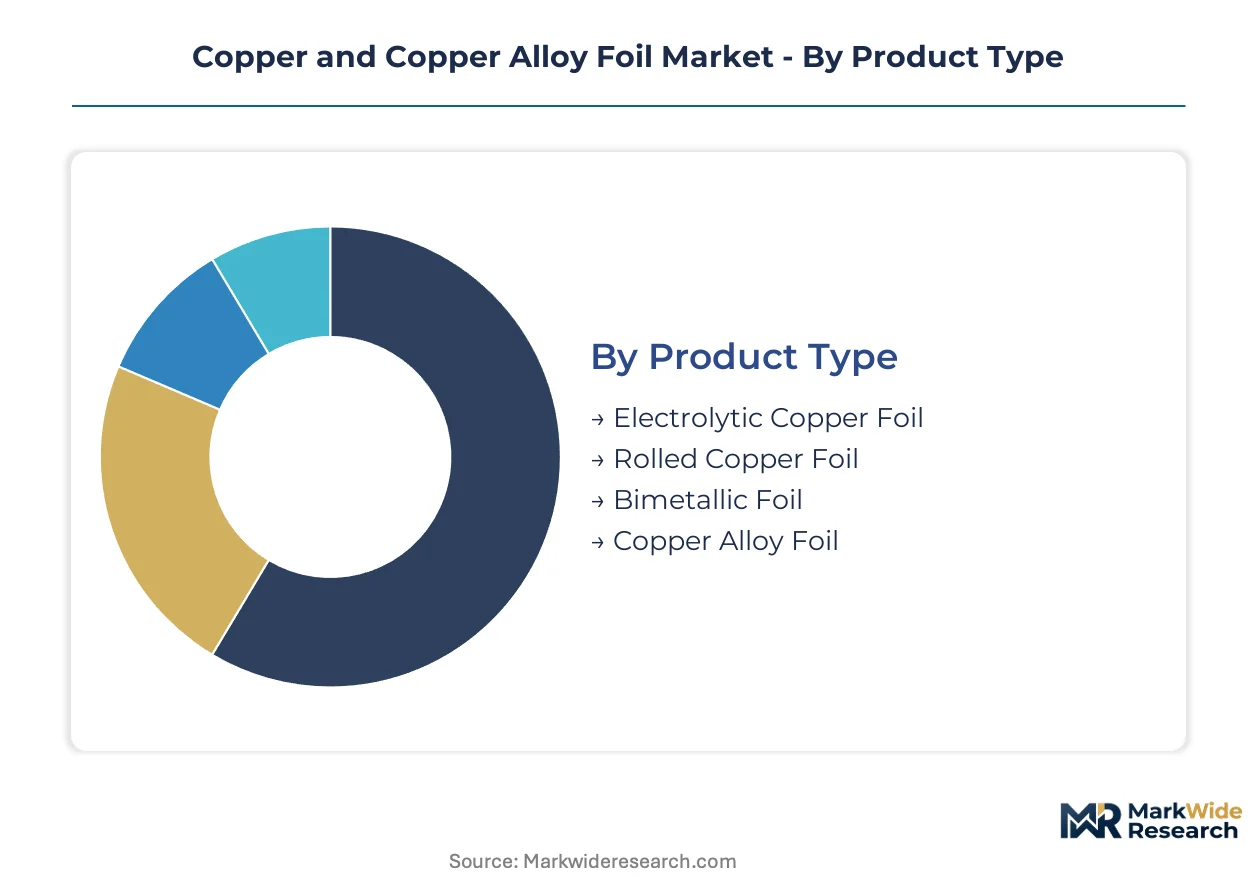
Copper foil procurement decisions hinge on electrochemical performance thresholds that vary sharply across battery chemistry generations and PCB layer densities. Suppliers must align thickness tolerances and surface roughness specifications with the precise thermal and conductivity demands of each end-use vertical.
Product Type:
Buyers prioritize deposition method based on dimensional precision requirements and the cost sensitivity of their downstream application.
- Electrolytic Copper Foil:Electrodeposited onto rotating titanium drums, this grade delivers sub-six-micrometre thicknesses essential for lithium-ion current collectors. Korean battery OEMs in the Gumi cluster now mandate digital twin traceability for every coil, compressing qualification windows for mills lacking real-time roughness monitoring.
- Rolled Copper Foil:Cold-rolled from cast ingots through multi-stand mills, this variant achieves dimensional tolerances below five micrometres critical for aerospace RF shielding and satellite thermal management. Japanese producers anchor supply through proprietary in-house rolling configurations that resist price volatility.
- Bimetallic Foil:Laminated copper-aluminum or copper-steel composites reduce material costs in connectors where conductivity requirements moderate.
- Copper Alloy Foil:Tin, nickel, or zinc additions enhance corrosion resistance for marine electrical applications, though REACH restrictions in Europe are forcing reformulation of legacy tin-nickel systems.
Electrolytic copper foil leads on scale; ultra-thin electrolytic grades gain share fastest as solid-state battery designs advance.
End User:
Volume concentration follows the capital deployment patterns of electrification supply chains, with automotive and electronics commanding divergent specification regimes.
- Electrical:Power transmission and distribution infrastructure consumes medium-gauge foil for transformer windings and busbar laminations, with procurement tied to utility grid investment cycles.
- Electronics:PCB fabricators in Taiwan and South Korea drive demand for standard-thickness electrolytic grades, though HDI board miniaturization is pushing specifications toward thinner deposits.
- Automotive:Cell manufacturers anchor cathode supply chains that absorb over half of regional ultra-thin foil output, with LG Energy Solution and Samsung SDI mandating three-year offtake commitments directly with Japanese and Korean mills.
- Consumer Goods:Smartphone and laptop battery packs require foil with surface roughness calibrated for adhesive bonding to active material layers, a specification niche dominated by electrolytic specialists.
Automotive procurement dominates absolute volume; electronics applications show steepest specification tightening as HDI density increases.
Thickness:
Energy density imperatives in battery design are compressing thickness targets faster than rolling mill and electrolytic deposition equipment can economically achieve.
- Ultra-Thin Foil:Specifications below six micrometres enable higher active material loading in prismatic and cylindrical cells. Korean cathode producers accelerated certification requirements in 2024, locking supply relationships with mills demonstrating sub-two-micrometre surface roughness capability.
- Thin Foil:Six-to-twelve-micrometre grades serve standard lithium-ion designs and high-layer-count PCBs where cost-performance tradeoffs still favor proven deposition economics.
- Medium Foil:Twelve-to-thirty-five-micrometre ranges anchor electrical transformer and industrial motor applications with less aggressive dimensional tolerance requirements.
- Thick Foil:Above thirty-five micrometres, rolled production dominates for busbar and heavy-current connector applications where mechanical strength outweighs conductivity optimization.
Thin foil maintains broadest installed base; ultra-thin grades command premium expansion as cell manufacturers pursue gravimetric energy density gains.
Application:
Functional performance requirements dictate alloy selection and surface treatment chemistry more directly than nominal thickness alone.
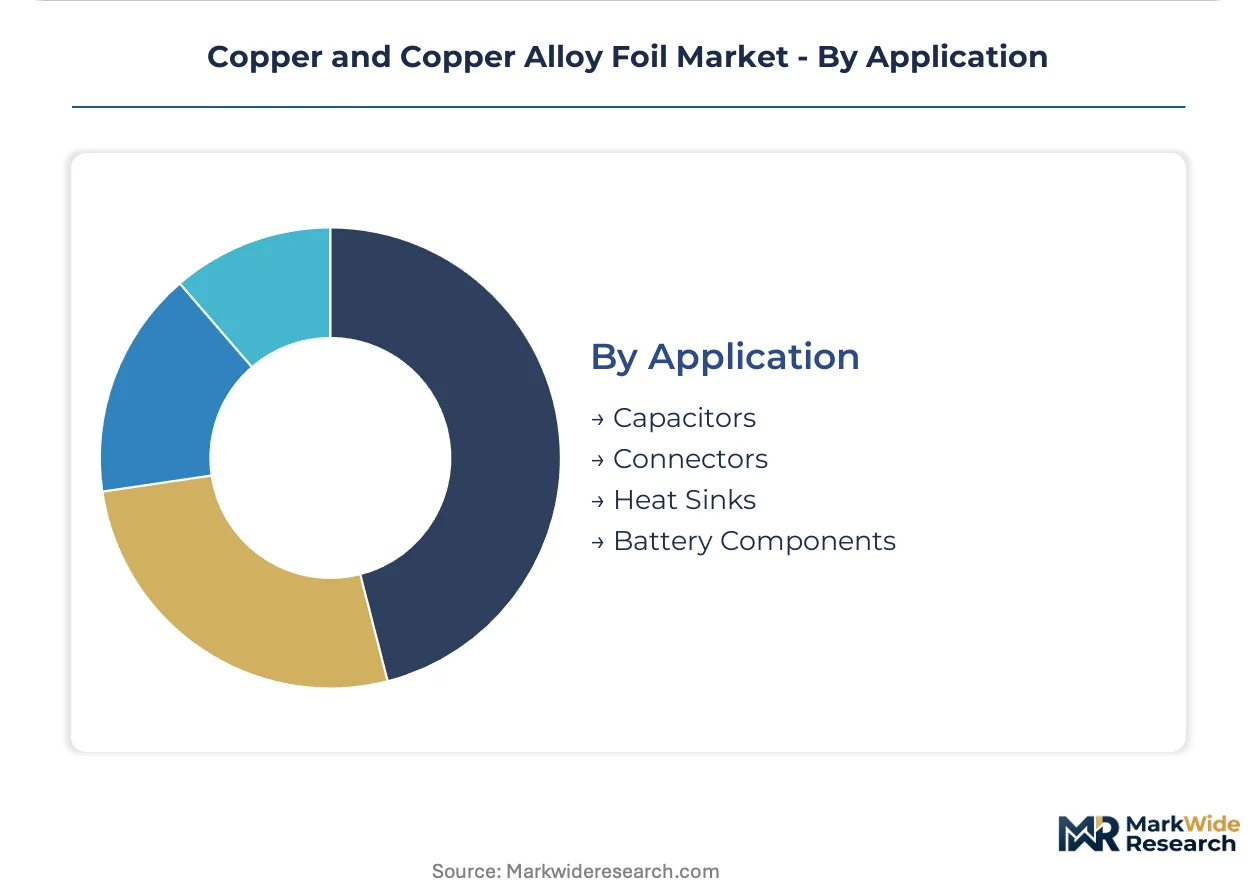
- Battery Components:Current collectors require high-purity anode foil with proprietary organic-inorganic coating formulations that few mills have developed in-house. Solid-state qualification timelines extending eighteen to twenty-four months freeze supplier selection decisions for next-generation cell architectures.
- Capacitors:Etched foil for aluminum electrolytic capacitors demands controlled surface area expansion through electrochemical roughening, a process segment where Japanese producers maintain technical leadership.
- Connectors:Stamp-formed contacts utilize tin-plated or nickel-plated copper alloy foils where corrosion resistance and solderability balance conductivity requirements.
- Heat Sinks:Thermal interface materials leverage copper's thermal conductivity in bonded-fin and vapor chamber assemblies for high-performance computing hardware.
Battery components drive fastest volume growth; capacitor-grade etched foil sustains margin concentration through proprietary process barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed electrolytic capacity while South Korea concentrates the most demanding ultra-thin specifications for battery applications. Japan retains technical leadership in rolled foil for aerospace and RF shielding. India's emerging cell manufacturing base cannot yet satisfy foil demand domestically. Germany anchors European consumption through automotive PCB and industrial transformer demand.
China
MEE emissions audits under dual carbon enforcement redirect smelter output toward low-carbon electrolytic grades that export-facing battery OEMs now specify. NMPA material purity requirements tighten qualification windows for domestic mills. Jiangsu and Zhejiang provinces host the densest concentrations of electrolytic deposition capacity serving both domestic EV cell builders and Taiwan PCB fabricators.
South Korea
LG Energy Solution and Samsung SDI anchor cathode supply chains that consume over half of regional ultra-thin foil output. MFDS traceability requirements for battery materials extend upstream to foil certification. The Gumi and Jeonju industrial clusters concentrate procurement teams that have abandoned distributor channels for mill-direct relationships with Japanese and Korean suppliers.
Japan
METI technology roadmaps prioritize high-purity anode foil development for solid-state battery commercialization. JIS standards for dimensional tolerances below five micrometres protect domestic rolling mill expertise. Tokyo and Osaka metropolitan areas concentrate headquarters functions for electrolytic specialists while Nagoya anchors aerospace RF shielding demand from satellite constellation manufacturers.
India
PLI scheme incentives for gigafactory construction create captive demand for electrolytic foil that domestic rolling capacity cannot yet supply. BIS certification timelines for imported battery materials extend procurement lead times for cell manufacturers. Gujarat and Tamil Nadu states concentrate the first wave of cell assembly investments that will strain regional foil logistics through 2027.
Germany
EU Battery Regulation carbon footprint disclosure mandates from 2027 will premiumize low-carbon electrolytic grades in European EV supply chains. REACH revisions restricting certain tin-nickel alloy additives force reformulation of legacy corrosion-resistant products. Bavaria and Baden-Württemberg host the densest concentrations of automotive PCB fabricators and industrial transformer manufacturers.
Copper and Copper Alloy Foil Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with electrolytic grades consolidating around certified Korean and Japanese mills while rolled foil retains more fragmented regional supply. Three archetypes dominate: integrated mining-to-foil conglomerates with captive cathode supply, independent electrolytic specialists with proprietary surface treatment chemistry, and precision rolling mills serving aerospace and RF shielding niches. Capacity expansion and strategic partnerships represent the dominant competitive moves, as qualification timelines for battery-grade certification freeze supplier selection decisions for eighteen to twenty-four months.
Among Korean fabricators, LS Mtron Ltd. and ILJIN Materials Co. Ltd. exemplify the electrolytic specialist archetype with deep integration into Gumi-Jeonju cluster procurement channels. Japanese conglomerates including Mitsui Mining & Smelting Co. Ltd. and JX Nippon Mining & Metals Corporation occupy positions spanning mining, smelting, and foil finishing that insulate margin structures from LME cathode volatility. Taiwan and Luxembourg-based suppliers such as Nan Ya Plastics Corporation and Circuit Foil Luxembourg sit within the PCB-focused tier where digital twin traceability requirements now separate qualified from non-qualified mills.
| Leading Market Players |
|---|
| LS Mtron Ltd. |
| Chang Chun Group |
| Mitsui Mining & Smelting Co. Ltd. |
| Nan Ya Plastics Corporation |
| Circuit Foil Luxembourg |
| Furukawa Electric Co. Ltd. |
| ILJIN Materials Co. Ltd. |
| Kingboard Copper Foil Holdings Limited |
| JX Nippon Mining & Metals Corporation |
| Others |
Value Chain & Pricing Dynamics
Battery OEM consolidation around sub-six-micrometre specifications is forcing electrolytic mills to absorb surface treatment chemistry costs that legacy pricing models cannot pass through, compressing margins on standard grades while premium-tier contracts with Korean cathode producers widen spreads.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-thickness electrolytic grades as Jiangsu and Zhejiang mills compete for Taiwan PCB fabricator contracts. Three-tier pricing structure across premium, standard, and economy levels separates battery-certified coils with digital twin traceability from industrial transformer grades. Cost compression in ultra-thin specifications is intensifying because Korean cathode producers now mandate sub-two-micrometre surface roughness capability as a qualification threshold. Spot-market buyers in consumer electronics show highest price sensitivity, while automotive cell manufacturers lock three-year offtake commitments that insulate Japanese and Korean mills from volatility.
Supply Chain Analysis
Freight cost differentials between electrolytic deposition capacity in China and rolling mill output in Japan are redirecting procurement flows for aerospace RF shielding applications. Supply concentrates in China, South Korea, and Japan, with raw material draws from Chilean copper cathode and Australian concentrate feeding smelter operations. Closed-loop electrolyte recovery systems required by EPA Clean Water Act compliance create single-source vulnerability for US-bound battery material. Distribution runs through mill-direct relationships that Korean cathode producers in the Gumi-Jeonju cluster have prioritized over distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in surface treatment chemistry capabilities and low-carbon electrolytic grades as EU Battery Regulation carbon footprint disclosure mandates premiumize certified supply.
For Market Incumbents: Deploy proprietary organic-inorganic coating formulation investments to defend against aluminum current collector substitution threats in prismatic cell designs. Backward integration into captive cathode supply insulates Japanese conglomerates from LME price swings above fifteen percent annually. Lock mill-direct relationships with Gumi-Jeonju cluster procurement teams before qualification windows close for solid-state battery certification cycles. For New Entrants and Emerging Players: The eighty-dollar-per-kilogram spread between premium battery-certified foil and standard PCB grades creates entry space for Indian PLI scheme beneficiaries lacking domestic rolling capacity. Target Gujarat and Tamil Nadu gigafactory construction zones where BIS certification timelines extend procurement lead times and strain logistics. Lead with low-carbon electrolytic grades that export-facing OEMs now specify in purchase agreements under China's dual carbon enforcement. For Investors and Strategic Acquirers: Asymmetric upside sits with electrolytic specialists possessing in-house surface roughness monitoring and digital twin traceability capabilities that Korean cathode producers mandated in 2024 supply agreements. Five-to-ten-year viability hinges on solid-state battery commercialization timelines extending eighteen to twenty-four months. Watch for REACH and RoHS revision enforcement deadlines in 2026 as inflection indicators for alloy reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Three-year offtake commitments with LG Energy Solution and Samsung SDI anchor Gumi-Jeonju cluster demand. |
| Backward Integration | In-house rolling mill configurations at LS Mtron Ltd. sustain premium-grade output for Korean battery makers. |
| Green Manufacturing Transition | Low-carbon electrolytic grades redirect smelter output under China's MEE dual carbon enforcement audits. |
| Capacity Expansion | Ultra-thin electrolytic deposition capacity additions target sub-six-micrometre specifications for solid-state designs. |
| Joint Venture | Technology partnerships with Japanese mills transfer surface treatment chemistry expertise for battery-grade certification. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrolytic mill technical directors, cathode procurement leads at Korean battery OEMs, PCB fabricator supply chain managers, and rolling mill operations heads with secondary validation from customs trade data, SEC filings of listed copper producers, LME warehouse stock reports, and MFDS battery material certification databases. Bottom-up capacity modeling and top-down demand triangulation cross-checked segment outputs.
Segment-weighting across the analysis window applied deposition method, end-use vertical, thickness specification, and regional production cluster as primary stratification dimensions. CAGRs derived from electrolytic capacity expansion pipelines, EV cell production forecasts, and PCB layer density trends. Solid-state battery commercialization timelines and REACH alloy restriction enforcement windows served as scenario inputs.
Caveats apply where copper cathode price volatility, aluminum substitution acceleration, or regulatory revision timing could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Vanadium Market
Metals
North America Aluminium Powder Market
Metals
Metal Casting Market
Metals
Wear Steel Plate Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
GCC Metal Forging Market
Metals
Europe Aluminium Cans Market
Metals
TMCP Steel Market
Metals
GCC Aluminium Powder Market
Metals
Seamless Stainless Steel Products Market
Metals
Aluminium Conductors Market
Metals
Magnesium Metal Market
Metals
Shipbuilding Steel Plate Market
Metals
Electrodeposited Copper Foil Market
Metals
Amorphous Metal Cores Market
Metals
Europe Welding Consumables Market