
 Metal Injection Molding (MIM) Parts Market | 2026-2036
Metal Injection Molding (MIM) Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Injection Molding (MIM) Parts Market Analysis
The split between aerospace-grade titanium MIM components and commodity stainless steel fasteners is realigning procurement strategies across tiered supply chains. GKN Powder Metallurgy leverages captive powder production and European automotive certifications to anchor high-volume programs for German OEMs. INDO-MIM competes on cost-optimized stainless steel component runs serving consumer electronics brands across South and East Asian manufacturing hubs.
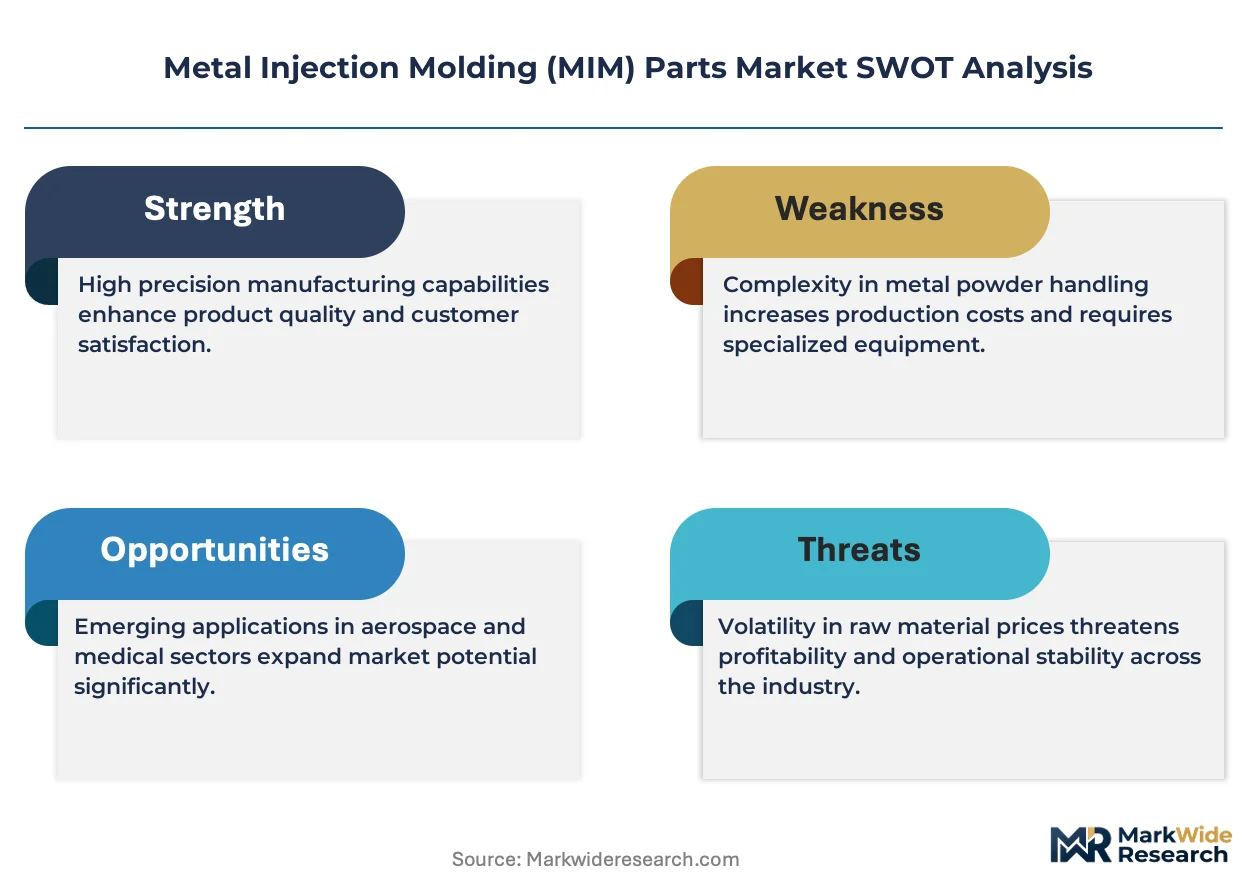
Metal Injection Molding (MIM) Parts are net-shape metal components fabricated from fine metal powders combined with a thermoplastic binder, injected into molds, then debound and sintered to achieve densities exceeding ninety-five percent of wrought material; the process enables complex geometries unattainable through conventional machining or die casting. Stainless steel MIM dominates current volume owing to its balance of corrosion resistance, mechanical strength, and feedstock cost, while titanium MIM occupies the fastest-expanding margin pool as orthopedic and aerospace buyers qualify biocompatible, high-strength-to-weight solutions. Defense applications are maturing into a stable demand pillar driven by ITAR-controlled supply requirements and long program lifecycles for small arms and guidance system components.
FDA quality system regulations and ISO 13485 standards govern biomedical MIM qualification pathways in the United States, while REACH and RoHS frameworks in Europe constrain allowable binder chemistries and surface treatment substances. The EU Green Deal's emissions accounting rules are pressuring sintering furnace operators to document energy intensity and explore hydrogen-fired thermal processing. Stakeholders must monitor evolving dual-use export controls and medical device traceability mandates as these regulatory layers increasingly determine which suppliers retain qualified status in premium tier supply chains.
Market Dynamics
Medical device procurement is tightening qualification timelines for titanium MIM implants while automotive OEMs in Germany consolidate supplier panels around captive powder capabilities, compressing margin pools for independent processors.
Growth Catalysts
- ISO 13485 Certification Mandates:Biomedical buyers in the United States now require validated MIM process documentation for implantable devices, locking in qualified suppliers for multi-year surgical instrument programs.
- Titanium Powder Feedstock Advances:Gas-atomized titanium powder with reduced oxygen content is expanding aerospace component qualification pathways for structural brackets and engine hardware.
- Stuttgart Precision Engineering Cluster:Concentrated automotive tooling expertise around Stuttgart feeds just-in-time MIM supply chains for transmission and fuel system components.
Market Restraints
- Gas-Atomized Powder Cost Volatility:Titanium and superalloy powder prices fluctuate with aerospace demand cycles, squeezing feedstock margins for mid-volume MIM processors.
- Sintering Furnace Concentration:High-temperature vacuum sintering capacity concentrates among German and Japanese equipment operators, creating bottleneck risks for qualified biomedical production.
- CNC Machining Substitution:Five-axis machining centers with automated tool changers compete for complex stainless geometries below 10,000-unit annual volumes.
Strategic Opportunities
- Indian Orthopedic Device Manufacturing:CDSCO streamlined medical device registration is attracting MIM suppliers to establish captive plants near Pune and Chennai surgical instrument clusters.
- Hydrogen-Fired Sintering Retrofit:EU Green Deal emissions accounting rules create first-mover advantage for furnace operators documenting carbon-intensity reductions in thermal processing.
- Additive Manufacturing Convergence:Binder jetting and MIM feedstock formulation overlap is enabling hybrid production models for bridge volumes between prototyping and mass sintering.
Industry Challenges
- Debinding Process Control Expertise:Solvent and thermal debinding parameter optimization requires specialized chemical engineering talent scarce outside established European and East Asian processing hubs.
- ITAR Compliance Infrastructure:Defense contractors face multi-year facility certification timelines to handle controlled technical data for small arms and guidance system MIM components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Injection Molding (MIM) Parts Market |
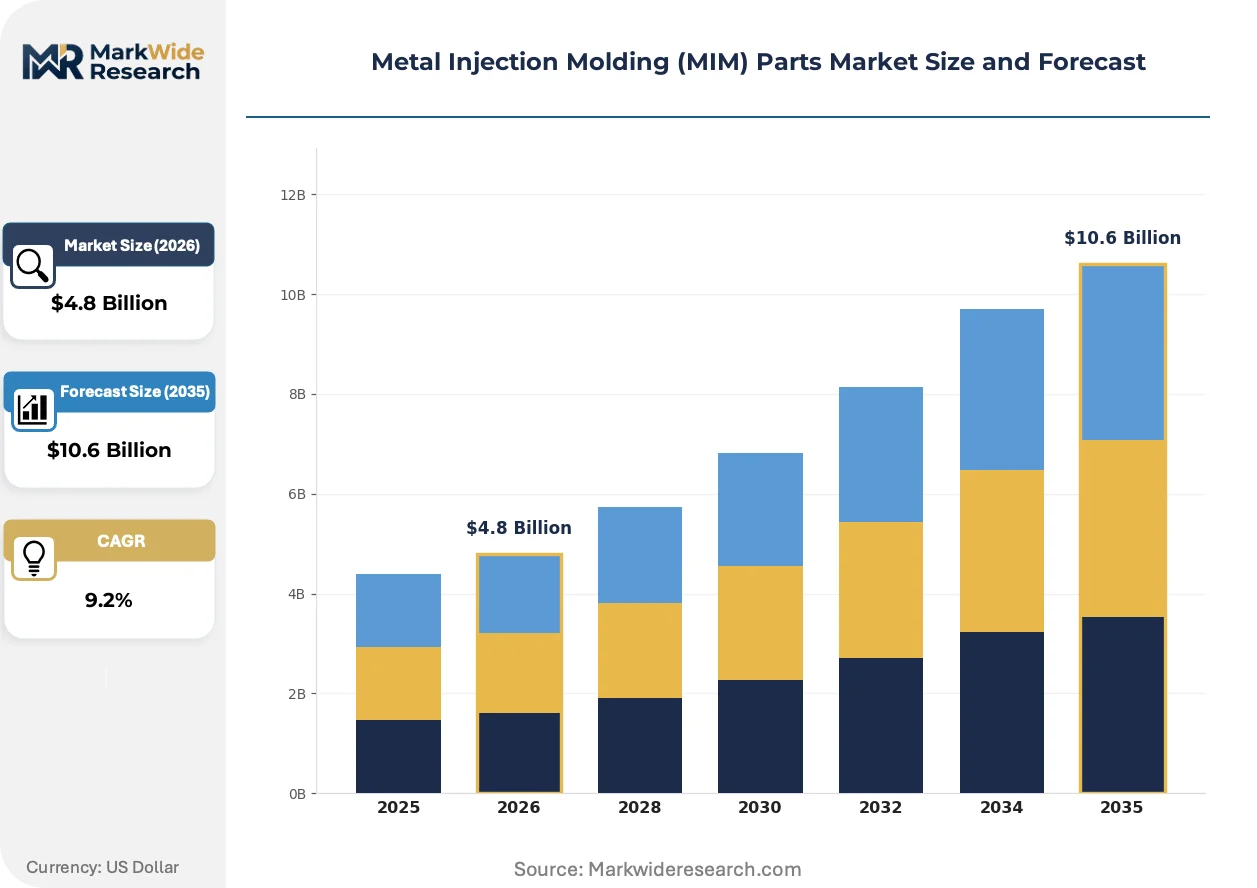
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Components, Tools, Fasteners, Medical Parts Industry Vertical: Automotive, Aerospace, Consumer Electronics, Defense Material: Stainless Steel, Iron, Copper Alloy, Titanium Application: Prototyping, Mass Production, Custom Parts, High Precision |
| Companies Covered | GKN Powder Metallurgy, INDO-MIM, Dynacast, FineMIM, Schunk Group, OptiMIM, ARC Group Worldwide, Smith Metal Products, MPP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Injection Molding (MIM) Parts Market Emerging Trajectories
Process digitization and regulatory traceability requirements are compressing batch-to-batch variation tolerances while opening new application categories for high-performance alloys.
Multi-material injection molding is unifying dissimilar metal combinations into single sintered components, enabling functional gradients for orthopedic implants where porous titanium interfaces transition to dense cobalt-chrome bearing surfaces. German dental implant manufacturers are piloting these systems for patient-matched abutments. The technology is unifying previously separate machining and diffusion bonding steps into one net-shape process, collapsing lead times from weeks to days.
REACH authorization requirements for nickel compounds in binder systems are forcing reformulation of traditional catalytic debinding chemistries across European MIM operations. ECHA substance evaluation timelines are extending new feedstock qualification cycles by 12-18 months. Biomedical suppliers with pre-validated cobalt-free binder portfolios are capturing premium tier contracts from orthopedic OEMs accelerating EU MDR compliance deadlines.
Consolidated supplier scorecards now weight carbon intensity metrics alongside piece price and defect rates in German automotive sourcing decisions. Tier-one transmission manufacturers are disaggregating annual contracts into quarterly releases tied to documented furnace energy consumption. This recalibration is most visible among Stuttgart-area powertrain suppliers where BMW and Porsche procurement teams enforce supplier-specific emissions reduction roadmaps.
Metal Injection Molding (MIM) Parts Market Segmentation
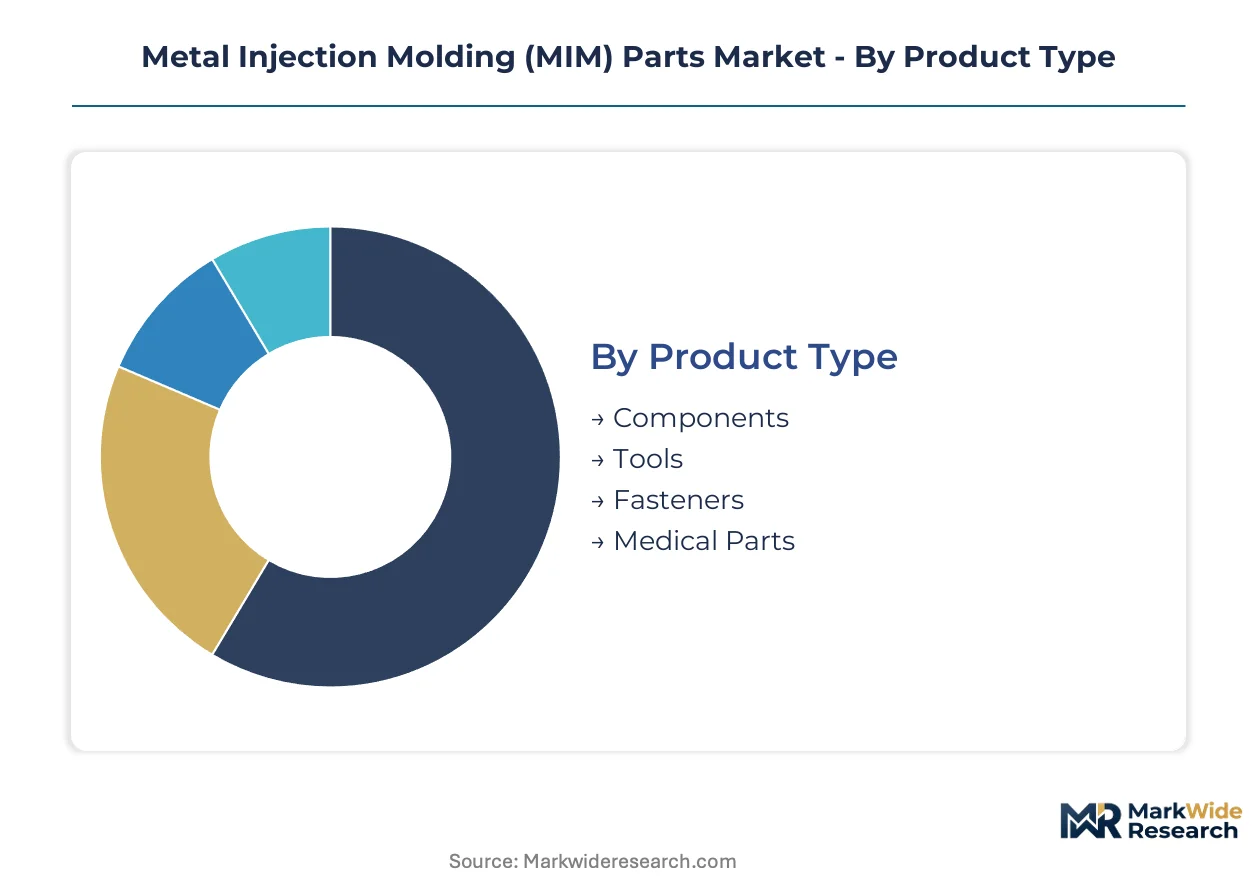
Segmentation in MIM parts reveals how process economics and qualification requirements stratify supply capabilities. Material selection and end-use certification demands create distinct competitive arenas where feedstock control and regulatory compliance determine supplier viability.
Product Type:
Supply concentration clusters around high-volume repeat orders that amortize tooling investments across multi-year automotive and medical programs.
- Components:Complex structural parts with internal features and thin walls achieve net-shape density exceeding ninety-five percent. Transmission gear clusters and fuel system valve bodies in Stuttgart-area automotive supply chains absorb the majority of German MIM furnace capacity.
- Medical Parts:Implantable devices and surgical instruments demand validated process documentation under FDA quality system regulations and ISO 13485. Titanium MIM femoral heads and tibial trays for orthopedic OEMs concentrate procurement among qualified biomedical suppliers with captive cleanroom debinding.
- Tools:Cutting inserts and mold cores leverage tungsten carbide and tool steel feedstocks for wear resistance.
- Fasteners:Small precision screws and threaded inserts compete with cold heading and machining below ten-thousand-unit thresholds.
Components absorb the bulk of installed capacity; medical parts are expanding most quickly.
Industry Vertical:
Cost tier differentiation separates aerospace qualification pathways from commodity consumer electronics procurement.
- Automotive:Powertrain and fuel system parts require IATF 16949 certification and PPAP documentation for German OEM supplier panels. Stuttgart precision engineering clusters feed just-in-time MIM supply chains where BMW and Porsche procurement teams enforce emissions reduction roadmaps.
- Aerospace:Structural brackets and engine hardware demand gas-atomized titanium powder with reduced oxygen content. AS9100 certification and NADCAP special process accreditation create multi-year qualification barriers for new entrants.
- Defense:Small arms and guidance system components operate under ITAR-controlled supply requirements with long program lifecycles.
- Consumer Electronics:Stainless steel hinge mechanisms and connector housings prioritize feedstock cost optimization over mechanical certification.
Automotive commands the deepest supplier integration; aerospace exhibits the steepest expansion trajectory.
Material:
Volume scale separates commodity stainless steel runs from premium titanium qualification programs.
- Stainless Steel:316L and 17-4 PH grades balance corrosion resistance, mechanical strength, and feedstock cost for the majority of current MIM volume. Consumer electronics brands across South and East Asian manufacturing hubs drive procurement concentration.
- Titanium:Ti-6Al-4V ELI grade with biocompatible surface finishes targets orthopedic implants and aerospace structural applications. Gas-atomized powder advances are expanding qualification pathways as oxygen content specifications tighten.
- Iron:Low-alloy steels serve magnetic cores and structural applications where corrosion resistance is secondary.
- Copper Alloy:Thermal and electrical conductivity applications include heat sinks and electrical contacts.
Stainless steel dominates current throughput; titanium is climbing the fastest.
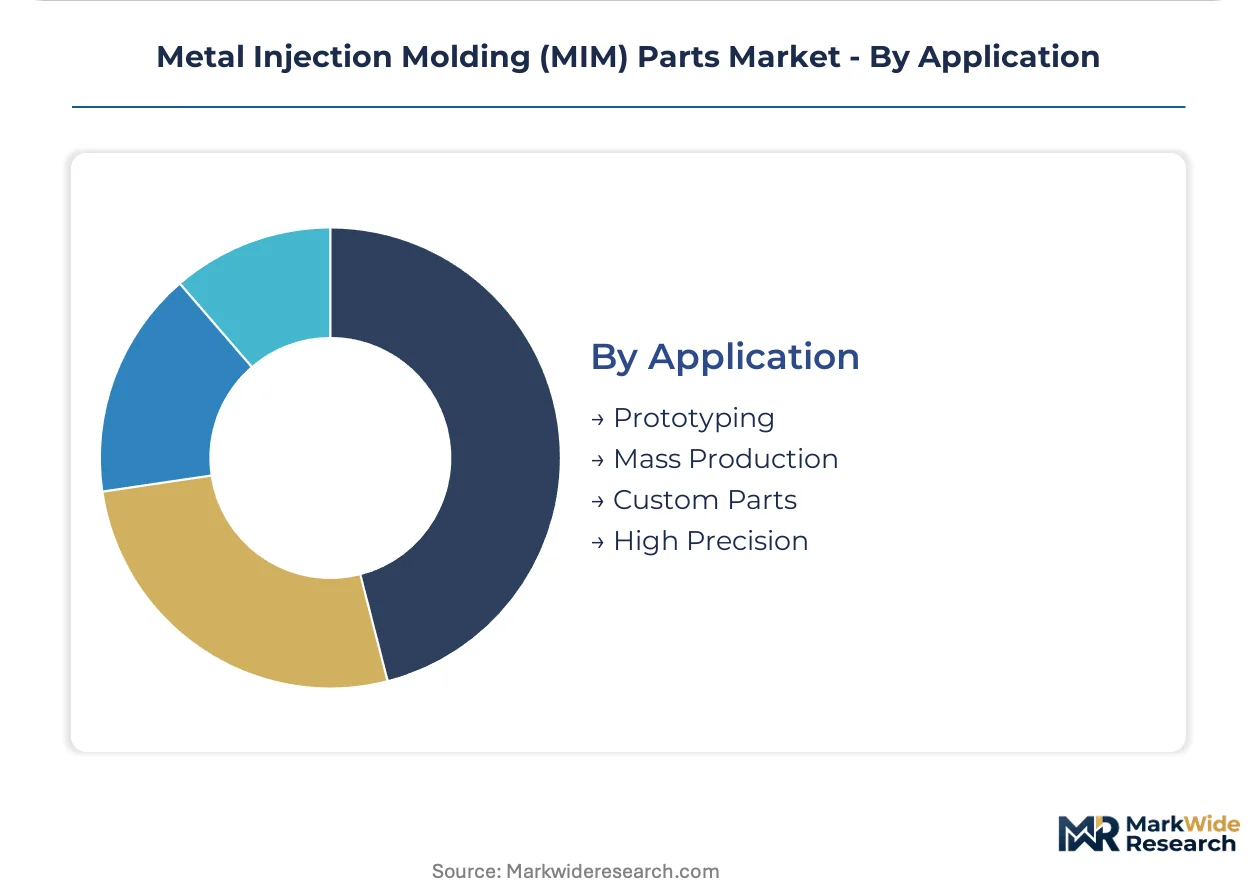
Application:
Customer type stratification distinguishes prototype service bureaus from captive mass production operations.
- Mass Production:Annual volumes exceeding one hundred thousand units justify dedicated tooling and automated debinding lines. German automotive transmission manufacturers disaggregate contracts into quarterly releases tied to documented furnace energy consumption.
- High Precision:Dimensional tolerances below fifty micrometers require specialized sintering furnace control and post-process machining integration. Medical device and aerospace buyers concentrate procurement among suppliers with validated statistical process control.
- Prototyping:Bridge tooling and small batch validation supports design iteration before mass production commitment.
- Custom Parts:Low-volume specialty geometries serve aftermarket and replacement component markets.
Mass production locks in qualified supplier relationships; high precision is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global MIM precision engineering capacity, feeding automotive powertrain supply chains across German OEM networks while medical device clusters concentrate titanium implant qualification expertise in southern Germany and the United States.
United States
Orthopedic OEMs in Warsaw, Indiana and Memphis, Tennessee drive titanium MIM procurement for hip and knee reconstruction systems. FDA quality system regulations and ISO 13485 certification requirements lock qualified suppliers into multi-year surgical instrument programs. Minneapolis-St. Paul hosts defense contractors navigating ITAR compliance for small arms and guidance system components.
Germany
BMW and Porsche procurement teams enforce emissions reduction roadmaps among Stuttgart-area transmission manufacturers, disaggregating annual MIM contracts into quarterly releases tied to documented furnace energy consumption. REACH authorization requirements for nickel compounds in binder systems extend new feedstock qualification cycles by 12-18 months. Baden-Württemberg precision engineering clusters feed just-in-time supply chains for fuel system valve bodies.
China
Consumer electronics brands in Shenzhen and Dongguan manufacturing hubs drive stainless steel MIM procurement for hinge mechanisms and connector housings. MIIT industrial standards and GB certification frameworks govern domestic medical device qualification pathways. Yangtze River Delta powder metallurgy operations compete on cost-optimized feedstock runs serving regional smartphone assembly networks.
India
CDSCO streamlined medical device registration is attracting MIM suppliers to establish captive plants near Pune and Chennai surgical instrument clusters. PLI scheme incentives support domestic orthopedic device manufacturing scale-up. Telangana and Karnataka precision component hubs are integrating MIM capacity into existing aerospace supplier networks serving global OEMs.
Japan
Gas-atomized titanium powder producers in Nagoya and Osaka supply reduced-oxygen-content feedstock expanding aerospace component qualification pathways. METI industrial policy supports high-temperature vacuum sintering capacity concentration among domestic equipment operators. Chubu region automotive suppliers leverage JIS standards compliance to anchor transmission component programs for Toyota and Honda.
Metal Injection Molding (MIM) Parts Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and feedstock control dimensions, with AS9100-accredited aerospace specialists and ISO 13485-validated biomedical suppliers commanding pricing power over stainless steel consumer electronics processors. The vendor base stratifies into three archetypes: captive powder producers with in-house atomization capacity, independent processors reliant on merchant feedstock, and hybrid operators blending MIM with binder jetting additive manufacturing. Consolidation pressure concentrates among mid-volume German automotive suppliers facing quarterly emissions audits, while technology licensing agreements proliferate between established European furnace operators and emerging Asian processors.
Within the captive powder tier, GKN Powder Metallurgy and Schunk Group exemplify European automotive certification anchoring, while INDO-MIM occupies a position representing cost-optimized stainless steel scale operations across South and East Asian manufacturing hubs. FineMIM and OptiMIM sit within the precision medical device specialization vector, reflecting biomedical qualification pathway concentration among qualified suppliers with validated cleanroom debinding infrastructure.
| Leading Market Players |
|---|
| GKN Powder Metallurgy |
| INDO-MIM |
| Dynacast |
| FineMIM |
| Schunk Group |
| OptiMIM |
| ARC Group Worldwide |
| Smith Metal Products |
| MPP |
| Others |
Supply Flow & Price Mechanics
Gas-atomized titanium powder costs cascade through three distinct pricing tiers as feedstock oxygen specifications tighten from consumer electronics grade through aerospace structural to biomedical implant standards. German automotive OEMs now disaggregate annual MIM contracts into quarterly releases tied to documented furnace energy consumption, compressing margin pools for independent processors lacking captive atomization capacity.
Pricing Analysis
Yield-guaranteed throughput contracts anchor value-based pricing for qualified biomedical suppliers, with ISO 13485-certified titanium implant processors commanding premiums over commodity stainless steel fastener runs. Price differentiation rests on certification tier and captive powder control, with AS9100-accredited aerospace specialists extracting premiums while consumer electronics procurement prioritizes feedstock cost optimization. Cost compression in mid-volume stainless steel component runs is intensifying because five-axis CNC machining centers compete for complex geometries below ten-thousand-unit thresholds. Consumer electronics brands in South and East Asian manufacturing hubs exhibit highest price sensitivity; orthopedic OEMs in Warsaw, Indiana and Stuttgart-area powertrain suppliers demonstrate lowest sensitivity due to multi-year qualification lock-ins.
Supply Chain Analysis
Specialized chemical engineering talent for solvent and thermal debinding parameter optimization concentrates in Baden-Württemberg, Nagoya, and the Yangtze River Delta, constraining capacity expansion outside established European and East Asian processing hubs. Geographic supply concentration clusters in Germany, China, and Japan, with gas-atomized titanium powder production anchored in Nagoya and Osaka feeding aerospace qualification pathways. Raw material dependencies center on nickel compound binders facing REACH authorization delays, cobalt-free binder alternatives, and reduced-oxygen-content titanium feedstock. Single-source vulnerability pervades high-temperature vacuum sintering equipment, where German and Japanese furnace operators control qualified biomedical production capacity. Distribution runs through tiered supplier panels consolidated around captive powder capabilities, with independent processors increasingly marginalized in German automotive sourcing decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive atomization capacity and cleanroom debinding infrastructure determine which suppliers retain qualified status in premium tier supply chains. Players are pursuing upstream control over gas-atomized powder production to escape feedstock margin volatility and secure multi-year aerospace and biomedical programs.
For Market Incumbents: Lock in qualified supplier status by retrofitting sintering furnaces for hydrogen-fired thermal processing ahead of EU Green Deal emissions accounting deadlines, and acquire specialized chemical engineering talent pools in Stuttgart and Nagoya before debinding process control expertise scarcity worsens. Binder jetting additive manufacturing convergence threatens traditional MIM bridge volume economics; incumbents must integrate hybrid production models to defend position against technology substitution.
For New Entrants and Emerging Players: Digital-channel direct engagement with Pune and Chennai surgical instrument clusters offers lowest barrier-to-entry, as CDSCO streamlined medical device registration reduces qualification timelines for orthopedic device manufacturing. White-space targets include Indian captive plant establishment near emerging precision component hubs in Telangana and Karnataka, and EU MDR-compliant cobalt-free binder formulation for premium tier orthopedic OEM contracts. Go-to-market positioning should emphasize documented carbon-intensity reductions to capture German automotive quarterly release contracts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-volume German automotive suppliers facing quarterly emissions audits and consolidation pressure, particularly those with existing IATF 16949 certification and PPAP documentation infrastructure. Long-term viability over the next decade hinges on feedstock control and regulatory compliance capabilities rather than scale alone. Acquisition target archetypes include captive powder producers with in-house atomization and qualified biomedical suppliers with validated cleanroom debinding. Watch for ECHA substance evaluation timeline extensions as inflection indicator for cobalt-free binder portfolio premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Fired Sintering Retrofit | EU Green Deal emissions rules create first-mover advantage for documented carbon-intensity reductions in thermal processing. |
| Cobalt-Free Binder Portfolio Development | ECHA REACH authorization delays for nickel compounds extend qualification cycles for pre-validated alternatives. |
| Captive Powder Atomization Capacity | In-house gas-atomized titanium production escapes aerospace demand cycle volatility and secures structural bracket programs. |
| Indian Orthopedic Manufacturing Footprint | CDSCO streamlined registration and PLI scheme incentives attract captive plants near Pune surgical instrument clusters. |
| Hybrid MIM-Binder Jetting Integration | Feedstock formulation overlap enables bridge volume production between prototyping and mass sintering economics. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across MIM process engineers, biomedical regulatory affairs leads, automotive Tier 1 procurement managers, and sintering furnace equipment specialists. Secondary validation drew from FDA quality system regulation documentation, ECHA REACH substance evaluation databases, EU Green Deal emissions accounting disclosures, and German automotive OEM supplier panel records. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Segment-level granularity modeled material grade, end-use certification tier, and geographic production hub across the projection horizon. Titanium MIM biomedical implant qualification pathways and stainless steel automotive powertrain component runs were disaggregated separately. CAGRs derived from installed furnace capacity utilization trends, feedstock price elasticity estimates, and regulatory compliance timeline assumptions. Industry-specific forecast inputs included gas-atomized powder oxygen content specification tightening and ITAR-controlled defense program lifecycle stability.
The model holds under stable regulatory compliance timelines and continued German automotive OEM supplier panel consolidation; deviation in ECHA substance evaluation acceleration or REACH authorization scope expansion would shift qualified supplier concentration. Forecasts reflect assumptions regarding hydrogen-fired sintering retrofit adoption rates and CDSCO registration pathway efficiency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Stretch Spring Wire Market
Metals
North America Iron Casting Market
Metals
Ferrite Market
Metals
Refined Nickel Market
Metals
Global Superconducting Wire Market
Metals
Global Brazing Consumable Market
Metals
Colloidal Metal Particles Market
Metals
GCC Metal Forging Market
Metals
Weathering Steel Market
Metals
Brazing Strips Market
Metals
Stainless Steel Foil Market
Metals
Global Brass Rods Market
Metals
Metallurgical Coal Market
Metals
Steel Casting Market
Metals
Finished Steel Products Market
Metals
Global Hot Rolled Coil Steel Market